



What this article covers
Opher Ganel shows why selling your home and buying a smaller one can raise your housing costs when mortgage rates are high, even after paying off your old loan. Using median-home figures, he makes the case for a better alternative: keep your low fixed-rate mortgage, rent out your current home and rent a smaller one, an approach that in his example cuts net housing costs by $354 a month and can shelter the rental income from tax.
Key Takeaways
Selling to downsize can increase your housing costs when mortgage rates are high
In Opher Ganel’s example, a couple who bought a median-priced $322,600 home at 3.09% would net about $131,400 after selling at $416,100, paying roughly 10% in closing costs and retiring a $243,100 mortgage. Buying a home 25% smaller at today’s rates would still cost them more each year, about $2,000 more if they put all the proceeds down and nearly $4,500 more if they kept $69,000 to invest.
Keeping a low fixed-rate mortgage and renting out your home can cut housing costs
A 3.09% fixed-rate mortgage is valuable when market rates are near 7.6%, so the article suggests leasing out the current home instead of selling it. At rent of about 0.5% of value ($2,080 a month), minus 8% property management and the $1,101 mortgage payment, the owner nets $813 a month toward renting a smaller $1,560-a-month home, paying $354 a month ($4,248 a year) less than before.
Rental deductions can make the rental income tax-free, but being a landlord has real costs
Property management, property taxes, repairs, landlord insurance, maintenance, mortgage interest and depreciation total more than the $24,960 of annual rent in the example, so no tax is owed on that income and excess losses can carry forward. The trade-offs include vacancies, turnover repairs, problem tenants and capital gains tax (including on depreciation claimed) when the house is eventually sold.
What to do if you want to save money by downsizing but can’t afford these insanely high-interest rates?
Three months ago, I wrote a piece about the challenges of buying a home in today’s market.
Beyond the problem with buying a new home, I wrote there: “Clearly, downsizing to bolster your nest egg will be much harder in today’s environment than it was just a year and a half ago.”
But what if I showed you how you can do exactly that in a way that gives you thousands of dollars a year in income?
Would you be interested?
If so, read on.
Why Downsizing Can Raise Your Housing Costs When Mortgage Rates Are High
Let’s assume the following scenario…
Three years ago, you bought a median-priced home, for $322,600. You took out the then-average-rate 30-year-fixed mortgage, with an interest rate of 3.09%. You paid a 20% down payment, resulting in a monthly principal and interest (P&I) of $1101.
Fast forward to today, and your kids have gone off to college, and you decide it makes more financial sense for you and your spouse, now empty nesters, to downsize.
Nothing too extreme. You figure you can be very comfortable in a home that’s 25% smaller. You start doing the math…
Since you’re looking for a home that’s 25% smaller than your current median-sized one, we’ll assume the price point for such a home is 75% of today’s median home price. So, your new home price target is $312,100.
If you sell your current home, you’d get today’s median price of $416,100. Your closing costs would be about 10%, or $41,600. You also need to pay off your mortgage, shaving another $243,100 off your bottom line.
This leaves you with $131,400. You have two choices as shown in the following table.
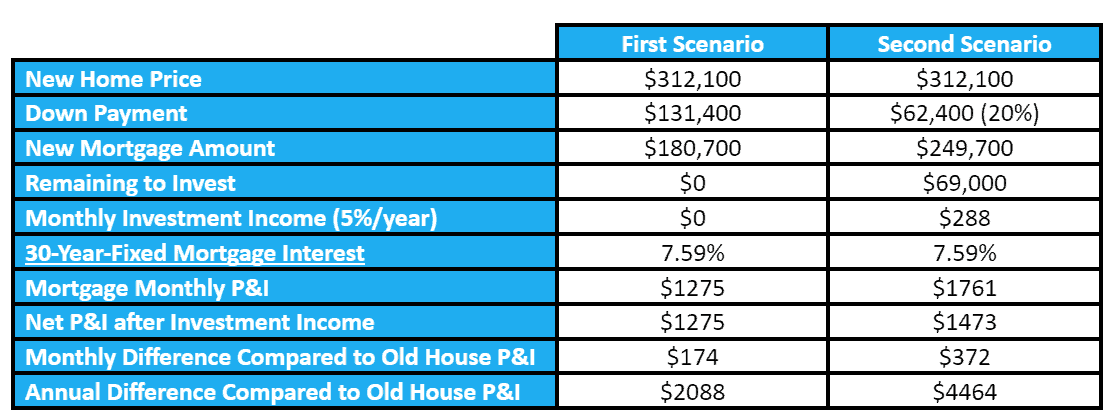
Clearly, in the first scenario, you need to come up with an extra couple of grand a year despite moving to a house that’s 25% smaller and owing a lot less than the $243,100 you paid off.
In the second scenario, where you kept $69k to invest, you need to come up with over double the amount you’re missing in the first case, nearly four and a half grand a year! This, again, is despite living in a smaller house and owing a similar amount to the balance you paid off.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
A Better Way to Downsize: Keep Your Low-Rate Mortgage and Rent Out Your Home
You probably never heard this anywhere before, but as long as you keep making your monthly payments as a fixed-rate mortgage borrower, you have more power than your lender!
If mortgage interest drops, you can refinance and leave your lender. This reduces your monthly payments for the same house. The old lender then has to reinvest in a new loan that brings in less money.
On the other hand, if mortgage interest rates rise, as they have in the past couple of years, your lender is stuck with a loan that pays below-market returns. If the lender wants to sell your loan to a different lender, your payments would stay the same, but your lender would get a fraction of what they invested in your loan.
As a result, your old mortgage, at a fixed rate of 3.09%, offers you value in today’s 7.59% interest rate environment. To take advantage, you need to keep your mortgage, which means you can’t sell your current home.
Instead, lease out your old home based on its current value, and rent a different home that’s 25% smaller, per the downsizing you wanted.
How the Numbers Work: Rent Out Your Home, Rent a Smaller One
Here’s how this could work out (using average and typical figures)…
Though a rule of thumb suggests setting rent at 1% of property value, this is considered aggressive, with 0.5% more likely to match market rates. This agrees with recent numbers since 0.5% of the median home price is $2080, and asking rents are now averaging $2052.
Thus, if you want to rent a home that’s worth about $312,100, your monthly rent should be about $1560.
However, for your own home, you’d get 0.5% of its $416,100 value, or $2080. Since you probably don’t want to manage the property yourself, you’d hire a property management company for, say, 8% of the rental income, or $166, leaving you $1914.
After paying your $1101 P&I, you’d be left with $813 a month to apply toward the rent you pay.
This leaves you paying $747 a month net instead of your $1101 mortgage P&I (since that’s paid by the rent your tenant pays you).
This means you pay $354 a month ($4248 a year) less than what you pay now.
Tax Deductions When You Turn Your Home Into a Rental
Even better, since the house you own now serves as a rental business, you can deduct expenses from your $24,960 annual rental income. For example:
- $1992 property management cost
- $4160 property taxes (assuming 1% of property value)
- $4160 property repairs (assuming 1% of property value)
- $2080 landlord property insurance (assuming 0.5% of property value)
- $2080 maintenance costs (assuming 0.5% of property value)
- $7600 mortgage interest (this will gradually decrease over the years)
- $8272 depreciation (based on a 39-year depreciation schedule)
Since these expenses are higher than your rental income, you pay no taxes on that income, and you can carry the excess losses over to future tax years or apply it against other passive income if you have any. Note that the depreciation isn’t actual money you pay out, so you actually do get some tax-free income.
What Are the Risks of Renting Out Your Home Instead of Selling It?
The above analysis ignores a few important points:
- We neglected the closing costs on the buyer’s side (these are far lower than the seller’s costs).
- Even with a property manager, being a landlord isn’t completely passive.
- From time to time, you may not find renters unless you reduce the rent you charge.
- When a tenant leaves, you’ll need to freshen up and repair your rental property, which costs you money both directly to have the work done and indirectly in lost rental income between tenants.
- Although a good property management company will help you find and vet renters, you may find yourself with a bad renter who pays rent late or not at all and may need to go to the trouble and expense of evicting that renter.
- Ultimately, when you look to sell your old house, it will be an investment property, so you’ll owe taxes on your capital gains (due to any increase in its value and the depreciation you claimed over the years).
The Bottom Line: Should You Sell or Rent Out Your Home to Downsize?
The rapid increase in both property values and mortgage rates has locked many people into their existing homes. As a result, if you want to downsize your home and hope to save money, selling your current house and buying a smaller one will almost certainly increase rather than decrease your costs.
The better solution, if you want to downsize, is to keep your current house but turn it into a rental unit and use the rental income to help pay rent on a smaller house you’ll move to.
This can even reduce your taxes owed on any income you may have from other rental units and/or businesses you own in which you do not materially participate.
However, as listed above, there are several caveats, so do your own due diligence and consider consulting a financial professional before deciding to implement this idea.
Find a Financial Advisor
Frequently Asked Questions
Does downsizing save money when mortgage rates are high?
Not necessarily. In Opher Ganel’s example, a couple selling a median-priced home bought three years earlier at 3.09% and buying one 25% smaller at today’s rates would pay more each year, not less. That holds whether they put all their sale proceeds toward the new home or keep about $69,000 to invest.
Should I sell my house or rent it out if I have a low mortgage rate?
The article argues that a low fixed-rate mortgage is an asset when rates are high, and you lose it if you sell. Renting out your current home and renting a smaller one can let your tenant’s rent cover your mortgage payment while you downsize. In the example, this cut net monthly housing costs from $1,101 to $747.
How much rent can I charge for my house?
A common rule of thumb sets monthly rent at 1% of the property’s value, but the article notes this is considered aggressive and that about 0.5% is more likely to match market rates. At the median home price used in the article, 0.5% works out to $2,080 a month, close to average asking rents at the time.
What tax deductions can I take if I rent out my former home?
Once your home becomes a rental, you can deduct expenses such as property management, property taxes, repairs, landlord insurance, maintenance, mortgage interest and depreciation from the rental income. In the article’s example these exceed the rent, so no tax is owed on the rental income and excess losses can be carried forward or applied against other passive income.
What are the downsides of renting out your home instead of selling?
Being a landlord isn’t fully passive, even with a property manager. You may face vacancies, lower rent to attract tenants, repair costs between tenants, and late-paying tenants or evictions. When you eventually sell, the house is an investment property, so you’ll owe capital gains tax on its appreciation and on the depreciation you claimed.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.