


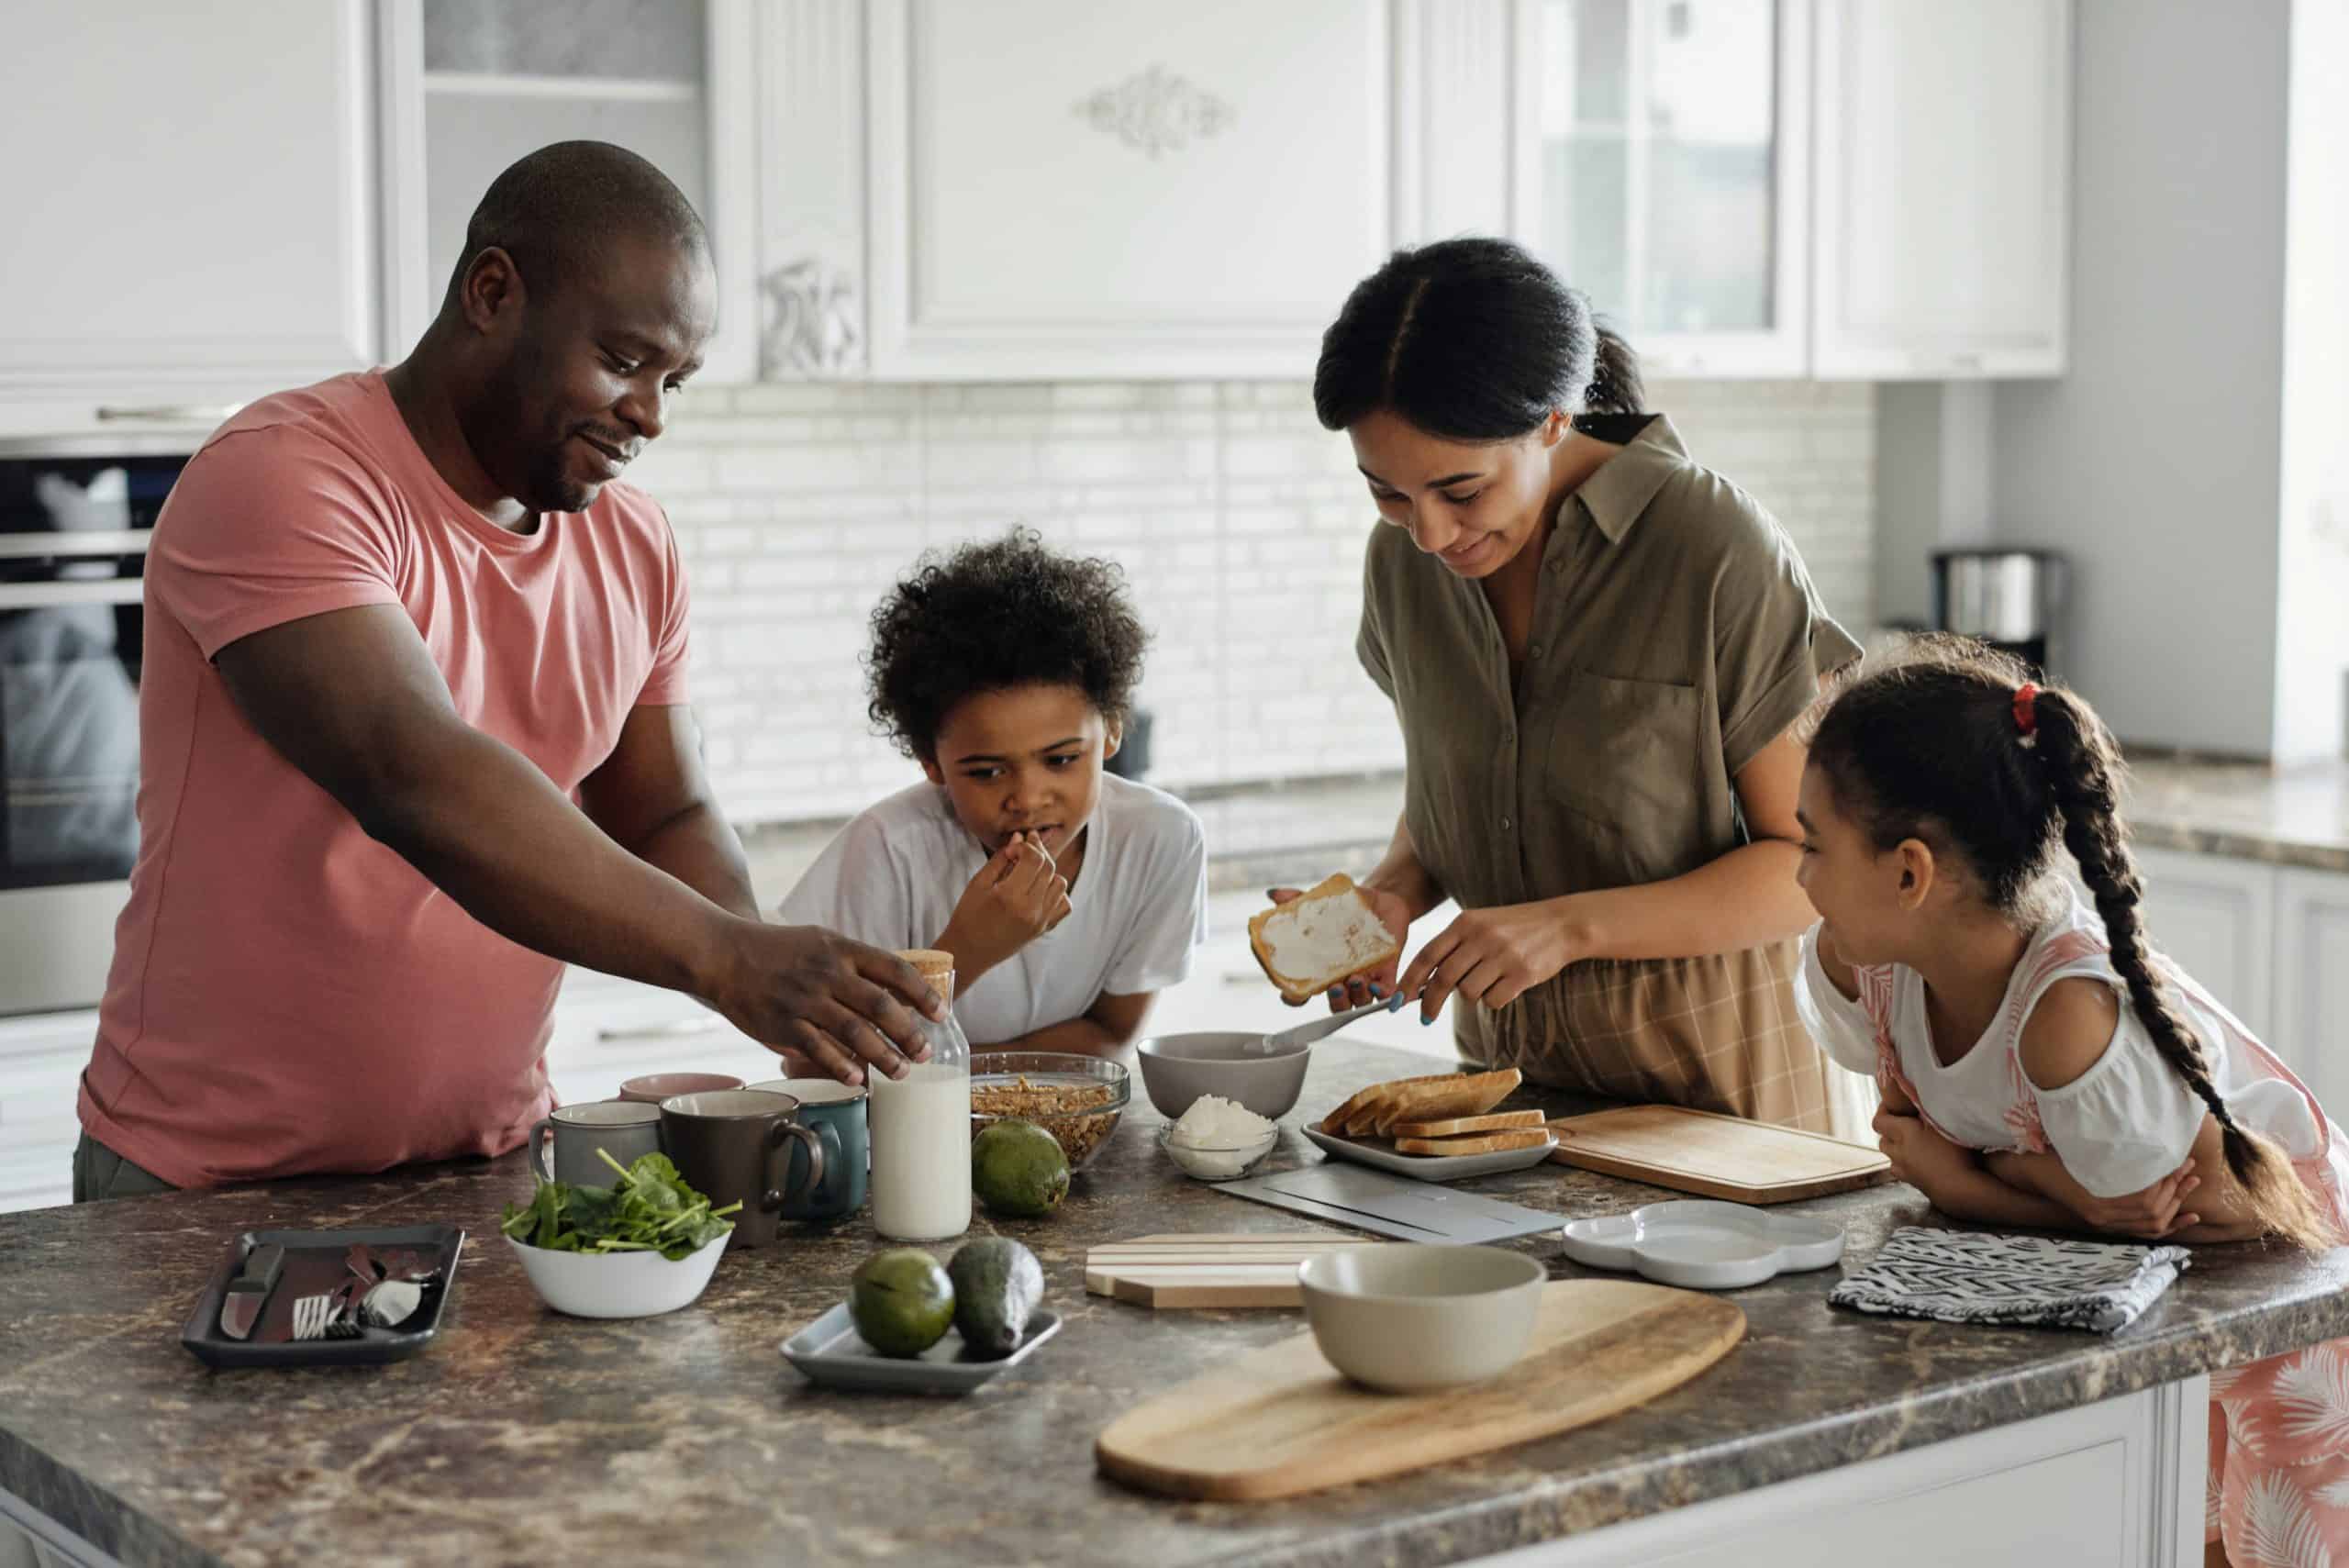

- Starting a family
- Buying a home
- Financial planning
Let’s take a closer look at the top three reasons I find people search for life insurance, and why those are important times to reassess your insurance needs.
Starting a Family
When you have dependents, people who rely on you to earn an income so they can survive, you need to ensure they will always be okay. If anything were to happen to you, life insurance can pay a tax-free benefit to your family. This benefit can be used for all sorts of things like replacing income, paying down debt, putting money towards the future, funeral expenses, and anything else really.
I believe it’s important to put your loved ones in a position where they can succeed, and have every opportunity in the world. If they were to lose a loved one, that is hard enough. If on top of that, they need to worry about how they are going to pay the bills or have to consider selling the house because they can’t afford it, well, that makes things even tougher.
I see people getting life insurance in place to help protect their family and their loved ones. I really hope that none of my clients’ policies ever do have to be paid out, but I know if they do it will go along way for their families.
Buying a Home
Buying a house is a really exciting moment. It can be the start of a new personal journey, and definitely the start of a new financial journey—a mortgage.
For almost everyone, their rent or mortgage is their biggest financial responsibility. Your living expenses take up a lot of your budget. Making sure you have insurance in place to eliminate that debt if you can’t pay it is really important. If not, your spouse could inherit an entire mortgage (where maybe they had to pay for only half of it), or your beneficiary (who may not live with you) could inherit it. I don’t know many people who could just take on an additional mortgage payment just for fun.
When you get a mortgage, your lender will most likely offer you creditor life insurance, but that’s not often your best bet. Creditor life insurance costs the same every month, but only covers your mortgage balance. As you pay off your mortgage, your benefit actually decreases, even though your monthly bill doesn’t.
Financial Planning
When people are in a position that they’re thinking about their future and planning for it, there’s a lot of things we can look at. There’s a lot of parts that come together to complete a plan. Just like making a pizza. Let’s look at a financial plan as a pizza, and let’s say that the insurance aspect of it, is the sauce. Pizza without sauce isn’t great, and pizza made only of sauce, well, that’s just awful.
As we are beginning to build wealth and put ourselves in an advantageous position, it’s good to make sure we have a backup plan. Getting insurance in place helps make sure that we have insurance in the future — there are things that can happen that would make someone uninsurable, and put their wealth at risk. It also allows us to protect our present loved ones, as well as our future loved ones.
Getting insurance to complete a financial plan often happens with young professionals or established professionals with growing families. But it’s always a good thing to keep in mind and review annually. It’s never too soon to have a great insurance plan.
There’s a famous quote in the investing world, that says ‘the best time to start investing is when you’re young, the second-best time is right now’ — and I’d say the same about insurance. Insurance is cheapest when you’re younger, and it’s less complicated. No matter how healthy you are now, that can change, so there’s no better time to reassess then now.
Frequently Asked Questions
Is a life insurance payout taxable to the beneficiary?
In the United States, life insurance proceeds paid to a beneficiary because of the insured person’s death generally are not included in the beneficiary’s gross income and do not have to be reported, according to the IRS. Any interest paid on top of the death benefit, such as when proceeds are held and paid out later, is taxable. Exceptions can apply, for example when a policy was sold or transferred for value, so it is worth reading more about how life insurance benefits are taxed before counting on the full amount.
Do I need life insurance if I don’t have kids?
Life insurance matters most when someone depends on your income, but children are not the only reason to have it. A spouse or partner who would struggle to cover a shared mortgage alone, a co-signer on a loan, or aging parents you support can all be financially exposed if you die. If no one relies on your income and your assets would cover your debts and final expenses, you may need little or no coverage.
What is the difference between mortgage life insurance and term life insurance?
Mortgage (or creditor) life insurance offered by a lender typically pays the lender directly, and the amount it pays shrinks as your mortgage balance falls while the premium usually stays the same. A personal term life policy pays a fixed death benefit to the beneficiaries you choose, and they decide whether to pay off the mortgage or use the money for other needs. Term coverage is also owned by you, so it does not end if you switch lenders or refinance.
How often should I review my life insurance coverage?
A common approach is to review coverage once a year and after any major life event, such as marriage, divorce, the birth or adoption of a child, buying a home, or a large change in income or debt. Each of these changes how much money your family would need if you died. Reviewing early also matters because premiums are generally lower when you are younger and healthier, and a change in health can make new coverage harder or more expensive to get.
About the author
Contributing Writer, Wealthtender
Derek Condon is a Certified Financial Planner and Mortgage Advisor specializing in financial planning, investments, wealth-preserving insurance, mortgages, and others.
Derek helps his clients with a variety of goals. From someone who is just starting their investing journey to a retiree managing their wealth. From a first-time home buyer to someone refinancing to get their very best mortgage. And everywhere in between.