



What this article covers
Opher Ganel uses Morningstar’s Monte Carlo research to show that a retirement portfolio with 30% to 60% in stocks supported the highest safe initial draw, about 3.8%, with a 90% chance of lasting 30 years. Within that range, the choice comes down to whether you want a higher median bequest or a tighter, more predictable range of outcomes, and two financial advisors explain how they set their clients’ allocations.
Key Takeaways
A 30% to 60% stock allocation supported the highest safe initial retirement draw
In Morningstar’s 1,000 simulated 30-year retirements, portfolios with 30% to 60% in stocks supported a 3.8% initial draw with a 90% chance of not running out of money. In the historical data, 75% stocks topped out at a 3.7% draw, while an all-bond-and-cash portfolio managed only 2.3%.
More stocks raise your likely ending balance but widen the range of outcomes
At 60% stocks, the median ending balance after 30 years was more than twice that of a 30% stock portfolio, but the spread across the 900 successful runs was wider. A 30% allocation produced a lower but more predictable ending balance, and a middle path around 45% splits the difference.
Advisors often set retirement allocations by income needs first, then invest the rest in stocks
One advisor starts with enough fixed income to generate the income a client needs and invests the remainder in equities. Another uses a bucket strategy: two years of expenses in cash, five years in bonds and five more in a conservative non-stock allocation, which for a $50,000-a-year need from $1 million works out to 40% stocks.
 Douglas Greenberg
 Michael Mezheritskiy
How much you should invest in stocks in retirement depends on what you prioritize
I’ve been thinking about “retirement” for three decades.
I put the word in quotation marks because I don’t mean to ever retire in the accepted meaning of the word.
When I was 30, an Ameriprise financial planner who wanted to sign me up as a client asked me when I wanted to retire.
My reply was, “Never!”
My preferred term is becoming “work-optional.”
How Much Money Do You Need to Become Work-Optional?
Whether you want to retire to travel and golfing or prefer to keep working, but only with/for people you like, on projects that light you up, and at whatever level you want, regardless of how much or little it pays, it takes money.
A lot of money.
Depending on your preferred lifestyle and where you live, “a lot” could be as little as a (few) hundred thousand dollars or multiple millions of dollars. A common rule of thumb to determine how much you will need is the so-called 4-percent rule.
It’s much easier to get to your goal if you invest your money than if you stick it in savings accounts.
What Counts as Retirement Success? Morningstar’s 90% Test
For what follows, I’ve drawn from a recent Morningstar report.
For their research, Morningstar used 1000 Monte Carlo simulations of possible sequences of returns for various asset classes, including several stock classes (e.g., US large-cap growth, US small-cap value, foreign, etc.), bond classes, and cash.
To call a strategy successful, they required that 900 of the 1000 Monte Carlo runs would maintain a positive balance after 30 years – that’s a 90-percent likelihood of not running out of money.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
How Does Your Stock Allocation Affect Your Safe Initial Withdrawal?
They looked at historical data from 1927 to 1992 for five scenarios.
- 100 percent stocks
- 75 percent stocks
- 50 percent stocks
- 25 percent stocks
- No stocks
The report shows your highest safe initial draw for a 30-year retirement would have been with 75 percent invested in stocks, a 3.7 percent draw.
The worst was with zero equities, a 2.3 percent draw.
Since there were only a few dozen rolling 30-year periods in the historical data, they also looked at their 1000 simulated 30-year runs.
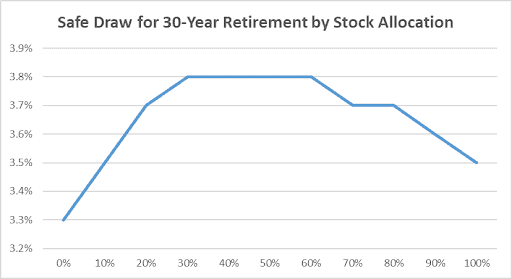
As you can see, you achieve the highest safe initial draw, of 3.8 percent, with a stock allocation between 30 and 60 percent.
But which is best? Should you go high or low?
Should You Hold 30% or 60% in Stocks in Retirement?
Since stocks return more but are more volatile than bonds, let alone cash, if you go to the higher end of that range – 60 percent, your median ending balance will be more than twice as high as what you’d see with a 30 percent stock allocation.
However, the spread between your balance after 30 years (for the 900 successful runs) would be greater for a 60-percent-stock portfolio than for a 30-percent-stock portfolio.
In short, if you opt for a lower stock allocation, your ending balance would be lower on average but would have a tighter spread among those 900 successful runs.
To figure out your best allocation, you need to decide if you want to swing for the figurative fences, go for (again, figurative) singles, or take the middle ground between the two.
- To have a chance at leaving a larger bequest, while risking leaving much less, push your stock allocation up to 60 percent.
- To maximize your chance of leaving a sizeable bequest, knowing it will likely be far lower than the previous option, choose a 30-percent stock allocation.
- To push your median bequest size up without risking as much as with the first option, go for the middle, perhaps q 45 percent allocation for stocks.
How Do Financial Advisors Set a Retiree’s Asset Allocation?
I asked financial advisors how they determine their clients’ asset allocations.
Douglas Greenberg, President, Pacific Northwest Advisory says:
For clients who want to leave an inheritance, our goal is to generate income without spending principal. We start with enough fixed-income assets to generate the income the client needs. The type of assets depends on the client’s willingness to accept risk, either corporate bonds or a portfolio of closed-end funds. We then invest the remainder of the client’s funds in equities.
Michael Mezheritskiy, President of Milestone Asset Management Group has a slightly different approach. He says:
At our practice, we use a bucket strategy to determine the proper asset allocation for our clients. If they need say $50k a year from a $1 million portfolio, we place two years’ worth of expenses, $100k, in cash. Next, we put five years’ worth, $250k, in bonds and five more years’ worth in a conservative non-stock allocation. Finally, we invest the remainder in stocks. This results in 40% in stocks and 60% in bonds and cash. This approach has worked well for us.
The Bottom Line: Trade Off a Bigger Likely Bequest Against Risk
From Morningstar’s research results, we learn that your maximum safe initial draw is highest when you combine stocks with bonds and cash.
The highest maximum safe initial draw in their simulations came out of portfolios with 30 to 60 percent invested in stocks.
Pushing to the 60 percent end increases your median ending balance, but you have a higher chance of ending with a really low final balance.
Pushing to the 30 percent end leaves you with a lower median ending balance, but the spread between the 900 successful simulations is smaller.
Thus, you must choose the level of risk (of leaving a zero or near-zero bequest) you’re willing to accept in return for a higher likely bequest level. The higher you’re willing to fly, the greater the risk, but the farther you’ll likely reach.
Find a Financial Advisor
Frequently Asked Questions
What percentage of stocks should I hold in retirement?
According to the Morningstar research Opher Ganel draws on, portfolios with 30% to 60% in stocks supported the highest safe initial draw, 3.8%, over a 30-year retirement. Where you land in that range depends on how much risk you will accept in exchange for a potentially larger bequest.
Is a 100% bond portfolio safer in retirement?
Not by this measure. In the historical data the article cites, a portfolio with no stocks supported the lowest safe initial draw, 2.3%, compared with 3.7% for a 75% stock portfolio. The research found the highest safe draw comes from combining stocks with bonds and cash.
What does a 90% success rate mean for a retirement withdrawal strategy?
Morningstar called a strategy successful if at least 900 of its 1,000 Monte Carlo simulations still had a positive balance after 30 years. That equals a 90% likelihood of not running out of money.
Should I choose 30% or 60% stocks if I want to leave an inheritance?
A 60% stock allocation gives you a chance at a much larger bequest, with a median ending balance more than twice that of 30% stocks, but a wider range of outcomes. A 30% allocation maximizes your chance of leaving a sizeable bequest, though it will likely be smaller, and about 45% is a middle ground.
How does a bucket strategy determine asset allocation in retirement?
One advisor interviewed places two years of expenses in cash, five years’ worth in bonds and five more years in a conservative non-stock allocation, then invests the rest in stocks. For a client needing $50,000 a year from a $1 million portfolio, that results in 40% stocks and 60% bonds and cash.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.