



What this article covers
Opher Ganel explains how he carries nine no-fee credit cards, pays every balance in full and stacks issuer offers on a single card to earn more than 13% back on groceries, gas and restaurants, despite Dave Ramsey’s warnings about rewards cards. Two financial professionals then share how they turn sign-up bonuses and transferable points into free trips to Hawaii, Japan and Australia.
Key Takeaways
Credit card rewards are free money only if you pay in full and avoid annual fees
Opher Ganel carries only no-fee cards, pays the balances in full every month and has never paid a dime in interest or fees. Because he doesn’t spend more on credit cards than he would otherwise, the rewards are pure upside, which is where he parts ways with Dave Ramsey’s argument that high rates and fees cancel out the freebies.
Stacking issuer offers can push a single no-fee card past 13% rewards
Two renewing offers on one card (a weekly grocery bonus worth $60 a month and an extra 10% on up to $2,000 of spending) sit on top of the card’s regular points. On $1,200 a month that works out to $183.80, or more than 15%, and on $2,000 it is $266.20, or 13.3%, adding up to more than $1,500 a year from that card alone.
Financial advisors play the rewards game with sign-up bonuses and transferable points
One advisor interviewed earned about $1,000 from a card paying 5% for 90 days and took a 10-day Hawaii trip on points, mostly from sign-up bonuses. Another carries 10 to 12 cards, concentrates spending on Chase and AmEx for their transferable points, and turned 320K Chase points into four business-class seats to Australia.
 Jacob T. Rothman
If you follow Dave Ramsey, you know he hates debt (he makes a grudging exception for 15-year fixed mortgages).
He especially despises credit cards.
Here’s a quote from one of the “Ramsey Solutions” blog posts:
“What’s the best kind of credit card? I’ll be honest with you: The best credit card is no credit card. It’s called Capital None, and it’s amazing. But seriously, there isn’t one.”
But how about rewards cards?
“Sure, there are plenty of shiny credit card rewards out there. But you usually have to use your credit card a lot and spend a lot to earn them. And high rewards cards tend to have higher interest rates and higher annual fees. So, by the time you get that free flight to New York, you’ve already handed over more than the cost of a plane ticket to the credit card company. Yeah, those freebies aren’t really free when you do the math.”
Now, let’s contrast hyperbolic rants with reality…
How I Use Credit Cards for Everything Without Paying Interest or Fees
I use credit cards pretty much for anything I can.
I hardly ever use cash or debit cards. That’s for convenience, safety, security, and of course the rewards. And I never pay a dime in interest or fees.
How?
I only carry cards with no annual fees and always pay our balances in full each month.
I have nine cards, but I only use three regularly:
- Citi Double Cash Mastercard is my default card, with unlimited 2% cash rewards on everything.
- Amazon Prime is the card I use for Amazon purchases, with unlimited 5% rewards on Amazon.
- Shop Your Way (SYW) Mastercard is what I pull out at grocery stores, gas stations, and restaurants, with over 13% rewards (see below).
I use three other cards semi-regularly, one for international transactions (it doesn’t charge the typical 3% fee), one for individual rather than joint expenses, and one for Costco (this one pays 4% on gas and EV charging, 3% on restaurants, 2% at Costco, and 1% elsewhere).
If the SYW Mastercard didn’t pay higher rewards, I’d use my Costco card at gas stations and restaurants. On the flip side, if Costco accepted Mastercard rather than just Visa, I’d use my Double Cash card there instead.
But how do I score over 13% with the SYW card? Here’s how…
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
How I Stack Offers to Earn Over 13% Rewards on a Single No-Fee Credit Card
It’s simple, really.
This SYW issuer wants to “train me” to pull out their card as much as possible.
Even though they probably charge merchants 3%, they spend at least 10% above that to entice me to use their card. They probably hope I’ll forget to make a payment or get in over my head.
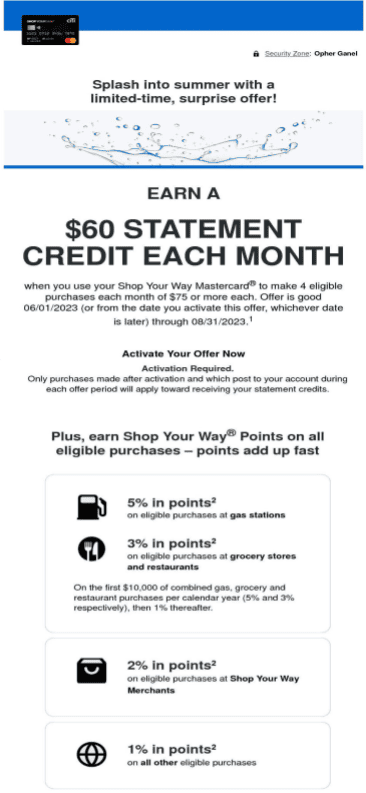
Yeah, good luck with that. In the 30+ years I’ve been in the US, I’ve missed exactly zero payments. Here’s a reward offer they sent me…
And here’s another offer…
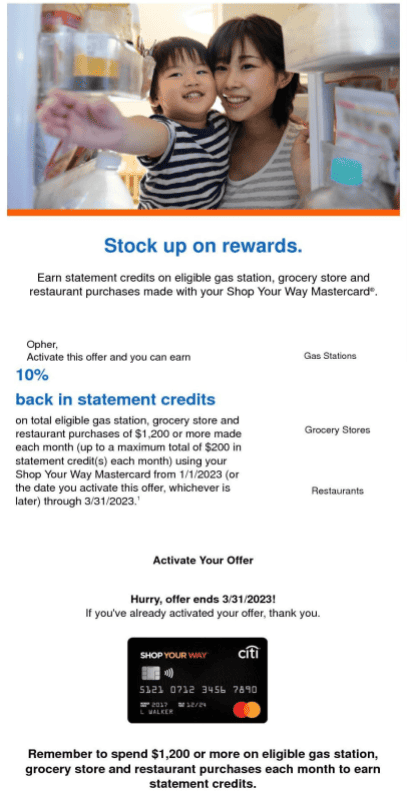
Both offers are time-limited, but they get renewed each time they expire.
Here’s how it works…
The Rewards Math on $1,200 to $2,000 a Month
Say I spend $1,200 a month at grocery stores, gas stations, and restaurants. I’m sure you’re not surprised to hear that we spend more than $75 a week on groceries, so each month we get $60 from the first offer.
Then, we get 10%, or $120, from the second offer, stacked on top of the $60.
Finally, assuming $100 a month is for gas, we get 500 points for that plus another 3300 points for the rest for a total of 3800 points. These points are only worth $0.001 each, so that’s $3.80 more.
Altogether, that’s $183.80 on $1,200 in charges or more than 15%!
Obviously, I keep using the card for those purchases beyond $1,200, usually close to the $2,000 maximum of the 10% offer. So, if I charge $100 for gas and $1,900 for restaurants and groceries, the math changes to $60 + $200 + $6.20 in points = $266.20 or 13.3% in rewards.
Do Financial Advisors Use Credit Card Rewards, Too?
I asked financial pros if they use credit cards to get rewards too, or if they avoid credit cards.
Here’s what a couple of them said…
Jacob T. Rothman, CPA, CFA, CFP®, Portfolio Manager, Rothman Investment Management says:
I love using credit cards for rewards. Here are some examples. I once had a card that paid 5% cash back for the first 90 days, with no limit. It was near year-end, so I used the card for my trip home to see family, Christmas shopping, some purchases I’d been waiting to make, and then my year-end charitable giving. The only problem was that the card had a $2000 limit, so I simply went online and paid it off every week, sometimes twice per week. I earned about $1000 on that card. The World of Hyatt card is a great card for travel points because, while most hotel points are only worth about $0.007, Hyatt points can easily be worth over $.03. For example, a 60,000 point sign-up bonus with a modest minimum spending requirement could cover two nights at the Grand Hyatt Kauai (cash value $981/night). Plus, you can transfer Chase Ultimate Rewards points to Hyatt, making your credit card rewards go even further.
I once took my wife to Hawaii for 10 days with credit card rewards points, mostly accrued with sign-up bonuses. Our points covered our flights, hotels (including five nights at the Waikiki Ritz Carlton!), rental cars, and even a couple of excursions.
Cobin Soelberg, MD, JD, Founder and Principal Advisor, Greeley Wealth Management relates, “Like you, I love playing the credit card rewards game. I just wish I knew about it years before! I got serious around the time the Chase Sapphire Reserve first came out with their 100K-mile bonus. That started the game for me. Now we carry 10-12 cards at any given time. Some we use to get us to Hawaii – thank you Alaska Airlines card. Most of our spend is on Chase and AmEx due to their transferable currency. I grew up skiing in Utah and it’s been a dream for years to ski in Japan. Pre-COVID, I was able to fly my wife and me to Japan and back in business class for 55K miles (again, thanks to our Alaska miles). Japan Air business class is ridiculous! They have a bidet with a heated seat on the plane AND some great ramen.
I’m most excited about an upcoming reward redemption to Australia. I saw nine(!!!) business-class award seats open up in United Polaris from the West Coast to Australia for 80K miles each. I was on call on the Labor and Delivery floor that evening. I hurriedly called my wife to confirm the dates. Then came the stressful part – transferring 320K Chase points to United and praying the seats would still be available. I was about to book and remembered my mother-in-law would be flying from Philadelphia, not Redmond, like the rest of us. I quickly changed the booking and grabbed our three seats from Redmond. Then, I booked the other ticket from Philadelphia to Sydney. The Polaris seats were still there…. I managed to snag four business-class seats to Australia for 320K points total!
The Bottom Line: Are Credit Card Rewards Worth It If You Pay in Full?
Dave Ramsey’s rants notwithstanding, the SYW Mastercard sends me over $1,500 a year in rewards without my paying any fees or interest, while our other cards send us thousands more in their rewards.
And since we don’t spend any more with credit cards than we would have anyway, this is free money that can cover, e.g., a nice annual vacation!
Now, does that sound like a bad deal to you?
Frequently Asked Questions
Are credit card rewards worth it if you pay your balance in full every month?
Opher Ganel argues they are. He uses only no-fee cards, pays every balance in full and never pays interest, so the rewards he earns are effectively free money. The key condition is not spending more with credit cards than you would have anyway.
How can you earn more than 13% rewards from one credit card?
By stacking the issuer’s limited-time offers on top of the card’s regular rewards. In Opher’s example, a weekly grocery offer worth $60 a month plus a 10% bonus on up to $2,000 of monthly spending, together with the card’s points, returned $266.20 on $2,000 of charges, or 13.3%. The offers expire but have been renewed each time.
Why does Dave Ramsey say credit card rewards aren’t worth it?
Ramsey argues that earning rewards usually requires heavy card use and spending, and that high-rewards cards tend to carry higher interest rates and annual fees, so the cost outweighs the freebies. Opher’s response is that the math changes when you carry only no-fee cards and pay in full every month.
How many credit cards should you use to maximize rewards?
Opher has nine cards but uses three regularly: a default card paying 2% on everything, a card paying 5% on Amazon purchases and a card he uses at grocery stores, gas stations and restaurants. He uses three more semi-regularly, including one with no foreign transaction fee for international purchases and one for Costco.
Do financial advisors use credit card rewards?
The financial professionals interviewed do. One earned about $1,000 from a temporary 5% cash-back card and covered a 10-day Hawaii trip with points, mostly from sign-up bonuses. Another carries 10 to 12 cards and uses transferable Chase points to book business-class award seats, including four seats to Australia for 320K points.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.