



What this article covers
Opher Ganel shows how investing $250 a month for a child from birth, raised 2% a year for inflation and held in a tax-efficient index fund in the parent’s name, could grow to over $600,000 by age 30 at a 9.5% assumed return. He walks through the simple steps, what the money could buy in inflation-adjusted terms, and the caveats every parent should weigh first.
Key Takeaways
Investing $250 a month from birth could grow to over $600,000 by your child’s 30th birthday
Assuming a 9.5% annual return and raising the gift 2% a year, the account passes $600,000 by age 30. After adjusting for 2% annual inflation, that is still enough to buy a $340,000 home without a mortgage.
Leaving the money invested until 60 could make your child a multimillionaire
With the same assumed return, the balance could reach about $9.2 million by age 60, or over $2.8 million in today’s dollars. At a 3.5% safe withdrawal rate, that would provide more than $98,000 a year in inflation-adjusted income for life.
Use a taxable account in your own name and a tax-efficient index fund
Opher suggests automating monthly transfers into a diversified, tax-efficient investment such as an S&P 500 ETF, rather than an actively traded mutual fund whose required gain distributions create yearly income taxes. Keeping the account in your name preserves control until your child is ready.
What if I could show you a way you could make your kid wealthy.
For real.
No get-rich-quick schemes. No summer jobs. No complicated financial shenanigans.
All it takes is small gifts.
How Wealthy Can Small Monthly Gifts Make Your Child?
If you’re expecting me to teach you how your kid can become as wealthy as Bezos, Gates, or Buffet, sorry but no.
But how about enough money to buy a house without a mortgage before she’s 30? According to the St. Louis Fed, as of the end of June 2020 that would take $313,200.
How about enough money to be able to retire by 67 with a portfolio throwing off more than the median income in the U.S. ($75,500 as of the fiscal year 2019 according to the U.S. Department of Housing and Urban Development)?
Would that be interesting?
How to Invest Small Monthly Gifts for Your Child, Step by Step
Your kid is born.
Congratulations!
Open a taxable investment account in your own name (so you retain control over it until it’s ready for prime time).
Set up an automatic transfer of $250 per month from your checking account to the new investment account and have it automatically invested in a tax-efficient diversified investment. This could be an exchange-traded fund (ETF) mimicking the S&P 500 or another diversified index.
It’s important to make sure it’s not an actively traded mutual fund, so you don’t have to keep paying income taxes each year as the mutual fund is required to distribute its gains to you.
Each year, increase the monthly gift to account for inflation. If inflation is 2% for example, increase the gift from $250 to $255.
Rinse and repeat until your kid turns 30.
That’s it.
How Much Can $250 a Month Grow to by Age 30 (and 60)?
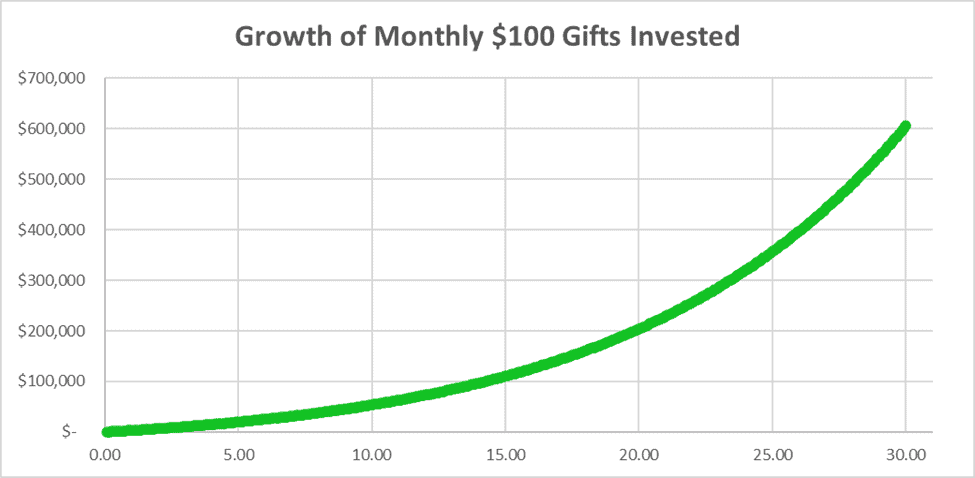
Let’s assume a 9.5% annual return on your investment (depending on how far back you start, the long-term historical return of the U.S. stock market was around 9.5% to $10%).
The figure below shows the growth of your gift balance including returns.
Spectacular, right?
By the time your kid is 30, the account is worth over $600,000!
Not so fast my friend.
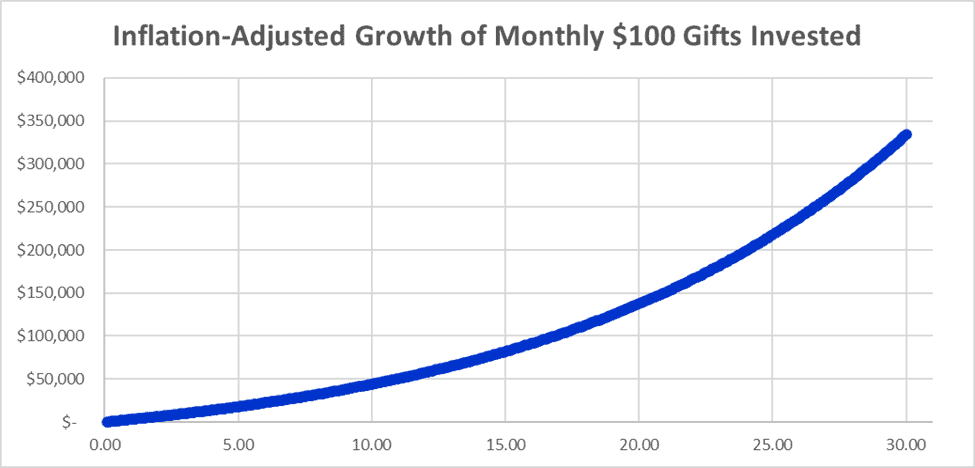
During these 30 years, inflation has been nibbling away at the value of the dollar. The next figure shows your results after adjusting for an assumed 2% annual inflation.
Still pretty impressive, wouldn’t you agree?
Whether your kid would want to do it or not, this would let her buy a $340,000 home with no need for a mortgage!
Alternatively, she could hold off on using the money and set it aside until she turns 60.
By then, with the same assumed annual investment returns, she’d have a cool $9.2 million! Even after inflation, that would be over $2.8 million!
If she stuck with a 3.5% safe withdrawal rate, she’d have over $98k inflation-adjusted dollars to live on for the rest of her life!
How’s that for wealthy?
What Are the Risks and Limits of This Gifting Strategy?
Yes, caveats. Those always have to be acknowledged, right?
Here they are:
- Not everyone can afford to set aside $250 a month for their kid (let alone that much for each of several kids).
- It takes commitment to keep going even when it’s hard to never raid the account for other things and to actually hand it over when it’s time even though the account is in your name so your kid has no legally binding rights to it.
- The stock market may have higher returns than 9.5% a year, but it may also have a lower long-term return. As they say, past results are no guarantee of future ones.
- When it’s time to give the money over, you’ll need to work with financial pros to make sure you don’t have to pay gift tax. This may require transferring the money over the course of several years or using up some of your lifetime gift tax exemption.
The Bottom Line: Small, Regular Gifts Can Add Up to Real Wealth
Even if you can’t afford to gift $250 a month to your kid(s), making regular gifts, even small ones, over the first several decades of their lives can build up into a very significant chunk of money.
As long as you do it smartly, you can maximize the ultimate impact of your gifts, while minimizing taxes.
Frequently Asked Questions
How much should I invest each month to make my child wealthy?
The article’s example uses $250 a month starting at birth, increased each year for inflation (for example, from $250 to $255 at 2% inflation), until the child turns 30. Even if you can’t afford that much, the article argues that regular gifts, even small ones, over the first several decades of a child’s life can build into a significant sum.
How much will $250 a month grow to by age 30?
Assuming a 9.5% annual return, the account would be worth over $600,000 by the time the child is 30. After adjusting for 2% annual inflation, it would still be enough to buy a $340,000 home without a mortgage.
What type of account and investment should I use for gifts to my child?
The article suggests a taxable investment account in your own name, so you keep control until the money is ready to hand over, invested automatically in a tax-efficient diversified fund such as an ETF tracking the S&P 500. It cautions against actively traded mutual funds, whose required gain distributions mean paying income taxes each year.
What are the risks of saving for a child in an account in your own name?
Because the account is in your name, your child has no legally binding right to it, so it takes commitment not to raid it and to actually hand it over. Returns may also be lower than the assumed 9.5% a year, and not every family can afford to set aside $250 a month per child.
Will I owe gift tax when I give the money to my child?
Possibly, which is why the article recommends working with financial professionals when it’s time to transfer the money. Avoiding gift tax may require spreading the transfer over several years or using part of your lifetime gift tax exemption.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.