



What this article covers
Opher Ganel compares inflation-adjusted S&P 500 returns with the purchasing power of cash over rolling periods from 1926 to 2018. Stocks suffered bigger worst-case losses than cash over single years, but by 10-year periods cash fared worse, and over 20 years the worst stock period still gained 22% while cash lost 72%.
Key Takeaways
Over 20-year periods, stocks beat cash even in the worst case
After adjusting for inflation, the worst rolling 20-year period for the S&P 500 between 1926 and 2018 was still a total gain of 22%. The worst 20-year period for holding cash was a 72% loss of purchasing power, and holding cash from 1966 to 1985 cost more than two-thirds of its value.
Stock market losses become rarer as the holding period gets longer
The market lost money in a bit more than a quarter of single years, about 1 in 8 rolling 5-year periods, 1 in 20 rolling 10-year periods and no rolling 20-year periods. Even after inflation, losing periods fell from about a third of single years to none over 20 years.
Cash is safer than stocks only over short time horizons
Worst-case inflation-adjusted losses were about 3x worse for stocks than cash over single years, comparable over 5-year periods, and about 1.7x worse for cash over 10-year periods. Because the dollar lost value in 7 of every 8 years and the average 20-year period erased 52.8% of its purchasing power, Opher Ganel concludes stocks win for horizons longer than a few years.
Common sense will sometimes cost you a lot of money. Comparing inflation-adjusted returns shows when equities were less risky than cash.
Do You Own Any Stocks? Why Fewer Americans Invested After 2008
A Gallup poll shows that following the so-called “Great Recession,” fewer Americans invest in the stock market, dropping on average from 62% in 2001–2008, to 54% in 2009–2017. The decline was greatest among younger Americans, who have the longest time horizon to make up any market losses.
If you owned stock during the “Great Recession,” you may well have concluded that owning stocks is hazardous for your financial health. However, if you look in the long term, nothing could be further from the truth, and if you hold only cash, you may as well burn (much of) your money!
Ben Le Fort published an article about the riskiest things people do with their retirement money. Among his many excellent points, Le Fort states that, “The longer the time horizon the less you need to worry about investment risk and the more you need to worry about opportunity cost.”
Personally, not only do I agree with that sentiment, but I’d go further and say that most people in most situations should seriously consider investing in stocks, even 100% of their portfolios. Of course there are situations when it doesn’t make sense to take on investment risk like that, but IMO those are the exception, not the rule.
Are Stocks Really Hazardous to Your Financial Health?
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
How Often Does the Stock Market Lose Money? What 1926 to 2018 Data Show
Considered by many as the “father of value investing,” Benjamin Graham said, “In the short run, the market is a voting machine but in the long run, it is a weighing machine.” In other words, in the short term, you have to guess which stocks will go up, or at least if the market as a whole will. However, in the long term, the economy tends to grow, so on average the stock market will go up.
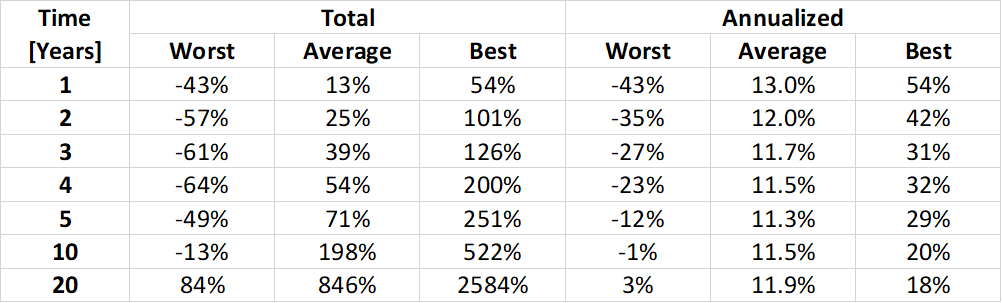
Looking at annual returns of the S&P 500 index (with dividends reinvested) from 1926 to 2018, we see that the market lost money in just a bit more than a quarter of those years. As you increase the time period length, the fraction of losing periods drops to about 1 in 8 for 5 years, 1 in 20 for 10 years, and none at all for rolling 20-year periods.
How Often Do Stocks Lose Money Over 1, 5, 10 and 20 Years?

If you’re planning to spend the money right after the period in question, you’d be justified in considering the maximum loss possible too. In that regard, the worst one-year loss was 43%, and the worst-case total loss increases as you look at longer periods until you start dropping from 4-year periods to 5- and 10-year periods. For 20-year periods, the worst-case total was actually a gain of 84%!
Looking at annualized returns, each time you look at a longer period, the worst case becomes better, and the best case becomes worse. Whereas the difference for a single year is 97% (between 54% gain and 43% loss), for 5-year periods that range drops to 41%. For 20-year periods, the best-to-worst range narrows to 15%.
Why Best- and Worst-Case Stock Returns Converge Over Longer Periods
How Inflation Erodes the Value of Cash Over the Long Term
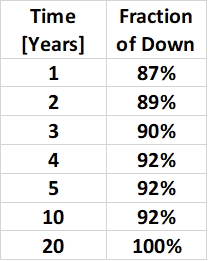
The problem with the above data is that they don’t take into account that over time, the dollar’s purchasing power tends to go down as a result of inflation. From 1926 to 2018, the dollar lost value in 7 out of every 8 years. As you look at longer periods, that fraction goes up to 100% of rolling 20-year periods.
How Often Does Cash Lose Purchasing Power Over Longer Periods?
Especially if you’ve been paying attention to how tame inflation has been recently, you’d be forgiven for thinking inflation isn’t a big concern anymore in absolute terms. However, looking at the long term, it’s still a major factor.
How Much Purchasing Power Does Cash Lose Over 20 Years?
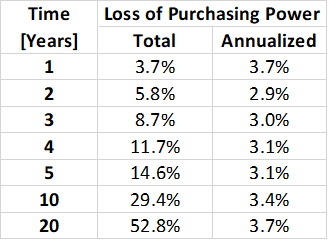
In fact, holding cash would have lost you an annualized average of 3–4% for all holding periods, with total losses growing from 3.7% for the average single year to a whopping 52.8% for the average 20-year period. That means you’d be able to buy less than half as much after holding cash for the average 20-year period! Know what the worst period for cash was like? If you had held cash from 1966 to 1985, you’d have lost more than 2/3 of its value!
Why Even Low Inflation Adds Up Over Long Periods
Are Stocks Riskier Than Cash After Adjusting for Inflation?
To figure out what stock returns really mean for you, you have to adjust returns for inflation. Doing that, we see that the worst one-year loss was 39%, For 20-year periods, the worst-case total was a gain of 22%. For annualized returns, each time you look at a longer period, the worst case and best case also get closer to each other. Whereas the difference for a single year is 101% (between 62% gain and 39% loss), for 5-year periods that range drops to 35%, and for 20-year periods, the range narrows to 12%.
What Was the Worst 20-Year Inflation-Adjusted Return for Stocks?
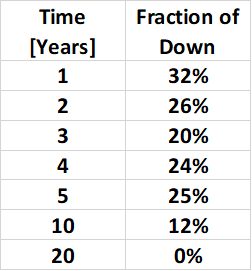
Looking at how frequently the stock market loses purchasing power, we see losses about 1/3 of single years, 1/4 for rolling 5-year periods, 1/8 for 10-year periods, and not a single losing 20-year period.
How Often Do Stocks Lose Purchasing Power After Inflation?
While these results are less inspiring than the pre-inflation returns, we have one last step to take, comparing them to the risk of holding cash.
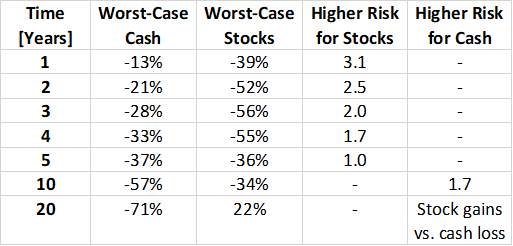
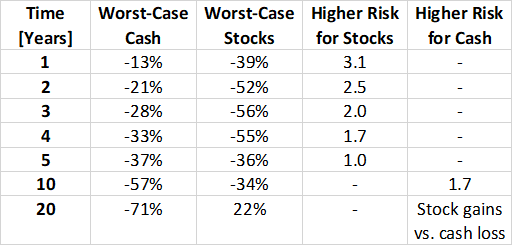
Comparing how bad worst-case inflation-adjusted losses were for stocks vs. cash, we see the loss was about 3x worse for stocks compared to cash for single years, 2.5x worse for 2-year periods, 2x worse for 3-year periods, and 1.7x worse for 4-year periods.
For 5-year periods, the worst-case inflation-adjusted loss was comparable for stocks and cash.
For 10-year periods, cash lost about 1.7x more than stocks in the worst case!
Once you hit 20-year periods, worst-case inflation-adjusted stock market returns were 22% up, compared to 72% down for cash!!!
Stocks vs. Cash: Worst-Case Real Losses Over 10 and 20 Years
The Bottom Line: For Long Time Horizons, Cash Is Riskier Than Stocks
Considering that the upside is far greater for stocks than for cash, it’s clear that for time horizons longer than a few years, investing in stocks is the winner compared to holding cash.
For 5-year periods, the worst-case inflation-adjusted loss was comparable for stocks and cash. For 10-year periods, cash lost about 1.7x more than stocks in the worst case! Once you hit 20-year periods, worst-case inflation-adjusted stock market returns were 22% up, compared to 72% down for cash!!!
Frequently Asked Questions
Is it riskier to hold cash than to invest in stocks?
Over short periods, no: in the worst single year, stocks lost about 3x more than cash after inflation. Over longer periods the picture flips. For 10-year periods cash lost about 1.7x more than stocks in the worst case, and for 20-year periods the worst stock result was a 22% real gain versus a 72% loss for cash.
How often does the stock market lose money over 20 years?
In S&P 500 data from 1926 to 2018 with dividends reinvested, there was no rolling 20-year period with a loss, either before or after adjusting for inflation. Losing periods fell from about a quarter of single years to about 1 in 8 five-year periods and 1 in 20 ten-year periods.
How much does inflation reduce the value of cash over time?
From 1926 to 2018, the dollar lost purchasing power in 7 out of every 8 years and in every rolling 20-year period. Holding cash lost an annualized average of 3 to 4%, which added up to a 52.8% loss for the average 20-year period, meaning you could buy less than half as much.
What was the worst stock market return over a 20-year period?
Even including the Great Depression and the Great Recession, the worst rolling 20-year period for the S&P 500 between 1926 and 2018 was an 84% total gain before inflation and a 22% total gain after inflation.
Should most people invest in stocks?
Opher Ganel argues that most people in most situations should seriously consider investing in stocks, even up to 100% of their portfolios, because over longer time horizons opportunity cost matters more than short-term investment risk. He notes there are exceptions, such as when you plan to spend the money soon, where taking on that risk doesn’t make sense.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.