



What this article covers
Opher Ganel responds to the argument that real estate is the most overrated asset in history, explaining why mortgage leverage and favorable tax treatment can make direct real estate investing worthwhile. He agrees it brings real risks (low diversification, heavy effort, high ongoing costs, tenant regulation and leverage) and shows practical ways to reduce each one, from REITs and property managers to renting out the home you just moved out of. He closes with the situations where you should avoid direct real estate investing altogether.
Key Takeaways
Mortgage leverage is the main reason direct real estate investing can outperform stocks
With 20% down, a mortgage leverages your money 5-fold, so Opher Ganel’s example turns a historical residential return of about 4% a year into roughly 20% on the cash invested. Direct ownership also defers tax on appreciation until you sell, and depreciation creates a deductible expense with no ongoing cash outlay, though it raises your taxable gain at sale.
REITs, other asset classes and property managers reduce the biggest drawbacks of real estate
Owning a single property concentrates risk, so the article suggests holding stocks, bonds and cash alongside it, or using REITs that spread exposure across many properties and markets. A property management company (about 8% of rents, sometimes 6% for higher rents) takes over tenant calls, marketing, vetting and evictions.
A mortgage is more forgiving than buying stocks on margin, but leverage still magnifies losses
At 5x leverage, a forced sale after a 10% price drop wipes out half your investment, and a 20% drop wipes out all of it. Unlike a broker’s margin call, a lender won’t demand more money while you keep making payments, so you can wait out a decline while tenants pay rent.
Real Estate Investing Risks: How to Manage Them and When to Avoid Them
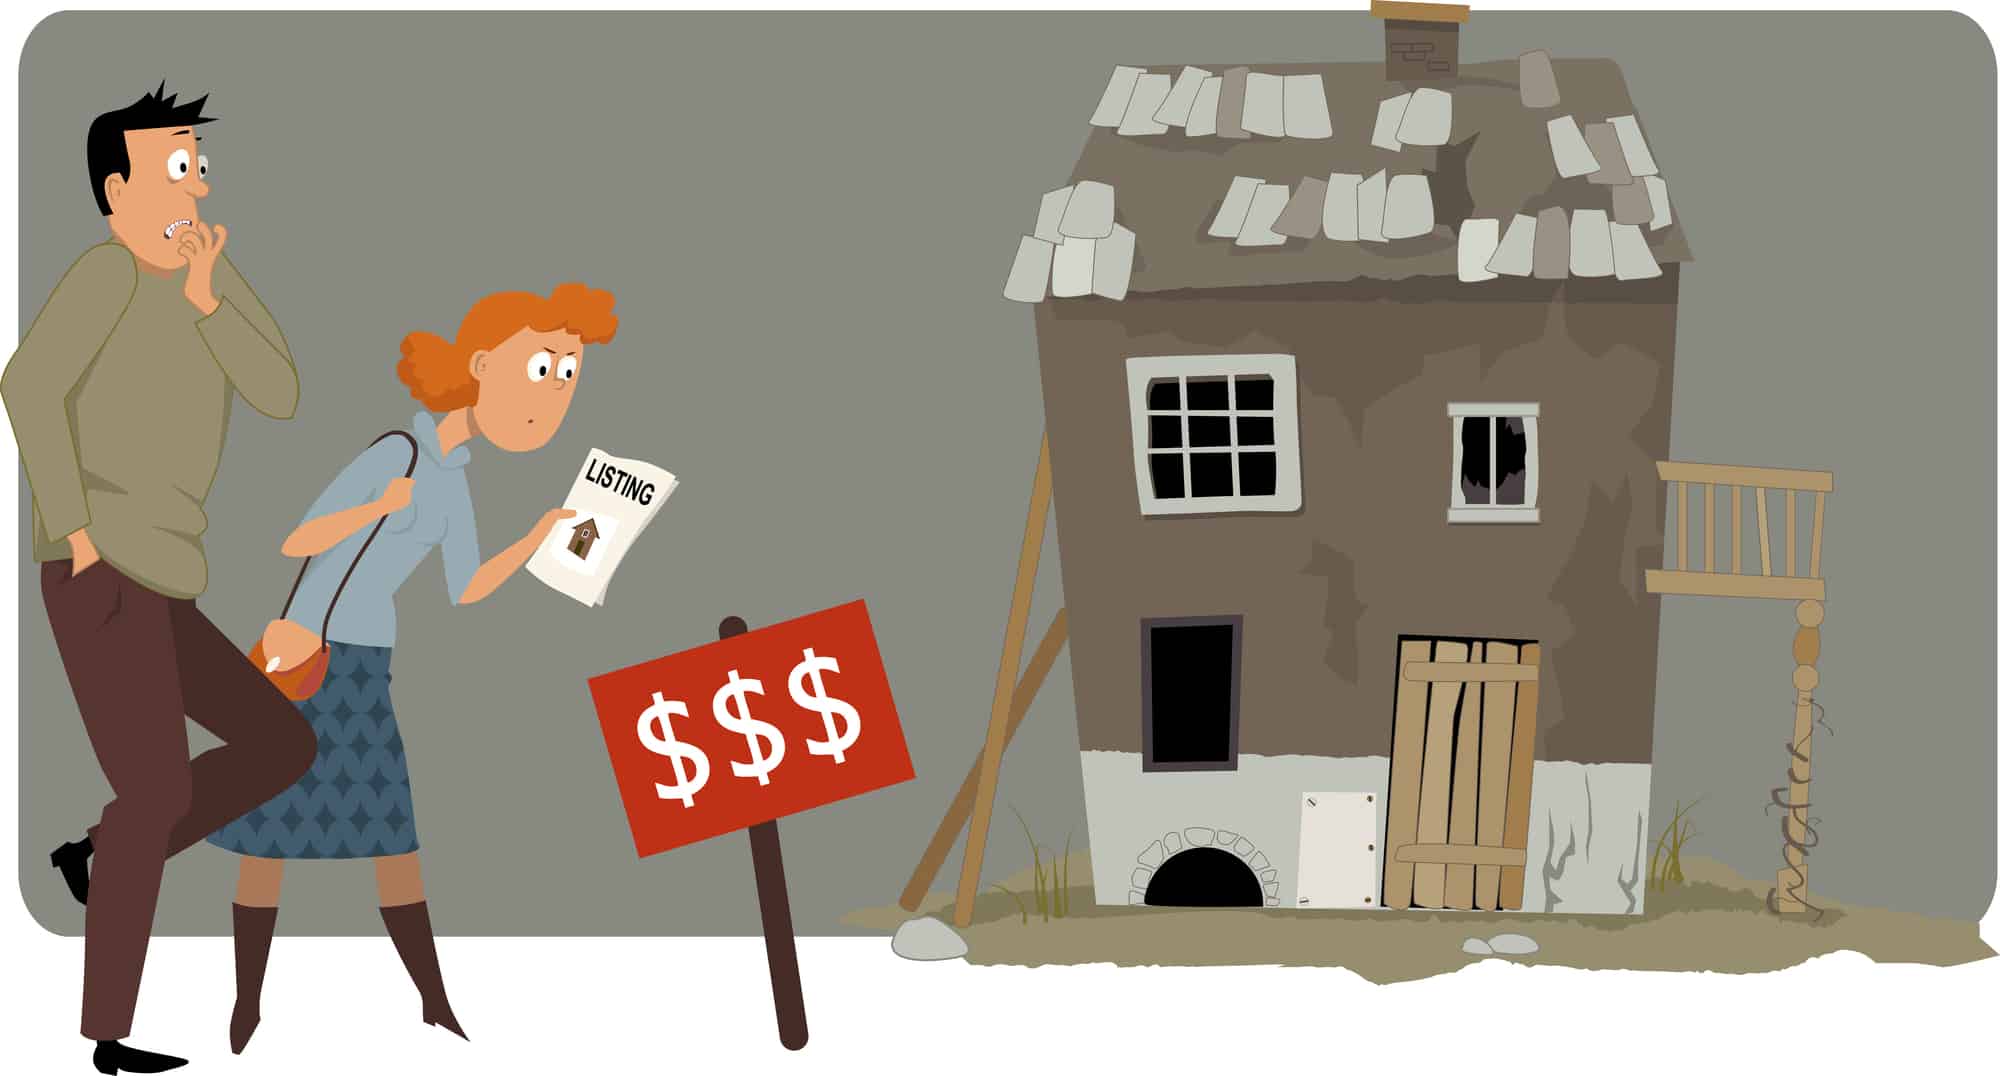
In an excellent primer on the drawbacks of real estate investing, Ben Le Fort makes the case that “real estate is the most overrated asset in history.”
Why Invest in Real Estate? Leverage and Tax Advantages
However, there are good reasons why people swear by real estate investing.
One major reason is that it’s much easier and less expensive to leverage a real estate investment. That’s called a mortgage. If you put down a 20% payment and finance the other 80%, you’ve just leveraged your money 5-fold.
Historically, residential real estate has returned about 4% a year.
Leveraged 5-fold, that becomes a 20% annual return, which is double the historic ~10% annual return on stocks. After accounting for inflation, the leveraged return on real estate is ~17%, which is 2.5x the ~7% real annual return for stocks.
Next, direct real estate investing in more tax-efficient than investing in a mutual fund. The latter is required by law to annually distribute gains to shareholders, with significant tax consequences if held in a taxable account. With a direct investment in real estate, you don’t get taxed on any appreciation in your property’s value until and unless you sell it, likely after years or decades.
In addition, mortgage interest on your rental property should be fully tax deductible as a business expense.
Finally, the US tax code lets you depreciate the value of real estate, typically over 39 years. This is a deductible expense that reduces your taxes without requiring any ongoing cash outlay. Note however that this depreciation increases your ultimate taxable capital gains once you sell.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
Where I Agree: The Real Drawbacks of Real Estate Investing
To be clear, I agree with many of Le Fort’s points, including:
- Risk of Low Diversification: Direct investing in real estate requires a lot of capital, making it hard to diversify (if you’re not already very wealthy);
- Labor-Intensive: Unless you pay someone else to manage the property, it’s a very hands-on investment, requiring a lot of time and effort;
- Ongoing Costs: It’s expensive to buy, and expensive to maintain the investment (mortgage interest, property taxes, insurance, maintenance, marketing for tenants, etc.);
- Regulation Risk: Rentals are highly regulated, so you may be stuck with a bad renter who refuses to pay rent and is hard to evict;
- Leverage Risk: Mortgages are a way to leverage your investment, but they increase your risk if you’re forced to sell when the property value drops near to or even below what you owe on it.
How to Reduce the Risks of Real Estate Investing
How Do You Diversify When You Invest in Real Estate?
While real estate does make it hard to diversify, there are two fairly easy ways of doing so, and doing both reduces your risk more than choosing just one or the other.
- Diversify into other asset classes, so while your real estate investment may be concentrated into a single property in a single market, your other investments, e.g. in stocks, bonds, and cash equivalents reduce the risk of losing everything.
- Instead of direct investment in real estate, you can invest in a Real Estate Investment Trust (REIT) that invests in the sort of real estate you think will perform well over time (e.g., residential, warehouses, office space, etc.). Since REITs invest in many properties and markets, even your real estate exposure will be diversified.
How to Make a Rental Property Less Work
Here too, there are several things you can do to reduce your real-estate-related effort.
- Invest in one or more REITs – the level of effort here is the same as investing in any other financial asset, not much once you’ve identified which REITs to invest in.
- Instead of looking for a new property to buy, consider holding off until you decide to move to a new home, and then convert your existing home to a rental property. This saves you the effort involved in finding a good investment property, finding a buyer’s broker and a mortgage lender, property inspection, closing the deal, setting up a new insurance policy, and rehabbing and/or remodeling before you can rent it out. You also avoid the risk of finding some hidden problems after you close on an investment property, because you’ve already lived there for years and know the property intimately.
- Hire a solid property management company – for residential real estate, this will probably cost you about 8% of rents, but some companies charge as little as 6% if the rent is higher. A property manager helps you avoid middle-of-the-night calls about clogged toilets, driving out to the property to figure out what’s wrong, and finding the right person to fix the problem if you can’t or prefer not to do it yourself. A management company will also take care of marketing your rental, vetting prospective tenants, and evicting the occasional bad renter (which their vetting process should reduce that risk to about the single-percent level.
How to Manage the Ongoing Costs of a Rental Property
The costs involved in owning a rental property directly are certainly much higher and more varied than the costs of owning shares in an index mutual fund. However, owning shares in a REIT avoid those costs.
For direct ownership, you just have to make sure the property is in an area where you can reasonably charge a high enough rent such that your tenants pay all those plus the principal portion of your mortgage payments (which isn’t a cost, but affects your cashflow), and leave enough over that you’re cashflow-positive even when accounting for months when your property is between tenants.
Another tip here is that you can buy a home warranty to help reduce your risk of massive repair costs. In fact, you might be able to put into your lease agreement that the tenant covers half the copay of any repair claim s/he makes. This will make frivolous repair claims less likely.
Here too, there are advantages to renting out a home you just moved out of, rather than buying an investment property. Typically, lenders charge a lower interest rate on mortgages for primary residences, and those rates don’t change if you move out and turn the property into a rental.
How to Handle Regulation Risk and Problem Tenants
This is one risk that’s hard to sidestep (except through investing in REITs).
However, your property manager can give you an estimate of the fraction of renters they’ve experienced problems with over their entire portfolio of properties under management. If that’s about 1%, you can charge a higher rent to offset that level of risk.
Is a Mortgage Less Risky Than Buying Stocks on Margin?
There is no doubt that your risk of losing your investment is much higher when you’re leveraged.
In our example of a 5x leverage, if you’re forced to sell when your asset value drops by just 10%, you just lost half your investment. If you’re forced to sell when it’s down 20%, your entire investment is wiped out. If the asset declines by more than 20% and you’re forced to liquidate, you’d end up owing more than you get for selling the asset.
However, buying stocks on margin (that’s when you borrow money to leverage your stock investment) is far riskier. This is because if and when your investments drop in value, your broker may make that dreaded “margin call” and require you to add money to your investment, and if you can’t or won’t, you’ll be forced to liquidate when prices are low, guaranteeing an outsize loss.
In direct investing in real estate, by comparison, as long as you keep making your mortgage payments, the lender won’t bother you even if the property drops to half its original value. This allows you to wait out the temporary drop in asset value, while being paid by your renters.
Buying a Duplex or Fourplex and Living in One Unit
Above, I mention that your mortgage interest will be lower if rather than buy an investment property, you lease out your own home once you move to a new one.
However, you can get a similarly lower interest rate if you buy a duplex or quad, live in one unit, and rent out the other(s).
Another advantage here is that it makes it easier to keep an eye on your renter(s) because you literally live next door. This makes it much easier to manage the rental yourself, if you prefer to put in more effort rather than pay a property manager.
When Should You Avoid Investing Directly in Real Estate?
All the above may make it seem like a no-brainer that everyone should invest directly in real estate.
That’s hardly the case. Here’s a non-exhaustive list of situations where you should avoid it completely.
- Your credit score is too low to get a good mortgage rate
- You don’t have enough money to properly diversify your investments while putting a large enough down payment (whether on a rental property, on a duplex/quad, or on buying your next home without selling your current home)
- Your local rental market won’t support rents high enough to keep your cashflow positive
- You don’t want the headaches of managing a rental property and can’t afford to hire a management company
- You don’t know how to report your real estate income, expenses, and depreciation on your tax returns, don’t want to put in the time and effort to learn how, and don’t want to pay an accountant to help.
The Bottom Line: Know the Risks Before You Invest in Real Estate
There are solid reasons why investing in real estate is a good idea, but as in all investments, it’s crucial to know what you’re investing in, and accept and mitigate the risks through proper diversification.
The above details the advantages of real estate investing, how to look at the risks and mitigate them, and when you should avoid this sort of investing altogether.
If you’re thinking about getting started with real estate investing, you may want to consider hiring a real estate investment advisor who understands the unique needs that come with owning and managing properties.


Frequently Asked Questions
Is real estate a good investment compared with stocks?
It can be, mainly because of leverage. The article notes that residential real estate has historically returned about 4% a year, but financing 80% of the purchase leverages that return 5-fold on your down payment. That same leverage also magnifies losses if you are forced to sell when prices drop.
What are the main risks of investing in rental property?
The article lists five: low diversification because direct investing takes a lot of capital, a heavy time commitment, high costs to buy and maintain the property, regulation that can leave you stuck with a tenant who won’t pay, and leverage risk if you must sell when the property is worth near or below what you owe.
How can you invest in real estate without managing a property?
Real Estate Investment Trusts (REITs) take about the same effort as any other financial asset and spread your exposure across many properties and markets. If you own a rental directly, a property management company can handle tenant issues, marketing, screening and evictions, typically for about 8% of rents.
Is it smarter to rent out your old home than to buy an investment property?
Often it is easier. Converting your existing home to a rental skips the search, financing, inspection, closing and rehab work, and you already know the property’s condition. The article adds that lenders typically charge lower rates on primary-residence mortgages, and that rate doesn’t change when you move out and rent the home.
When should you avoid investing directly in real estate?
The article recommends avoiding it if your credit score is too low for a good mortgage rate, if you can’t diversify while making a large enough down payment, or if local rents won’t keep your cash flow positive. It also advises against it if you don’t want landlord headaches and can’t afford a manager, or if you won’t learn or pay for help with the tax reporting.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.