Social Security taxation can be as confusing as it is complicated. As one of the oldest and most critical retirement benefits, Social Security definitely deserves your attention. You also don’t want your Social Security to increase your tax bill.

Your Social Security strategy directly affects your taxes. It’s important to understand the when, why, and how of Social Security taxation.

Understanding How Social Security Benefits Are Taxed

Let’s start by saying we don’t necessarily agree with taxing Social Security. However, we can’t do anything about it, so we prefer to focus on what we can control. If you’re really interested in the long history and explanation of why Social Security is taxed, you might find this article from the Social Security Administration interesting.

Regardless, current laws and IRS rules could make a portion of your Social Security taxable. Some states also tax your Social Security income, but many only tax a portion. Missouri generally doesn’t tax Social Security benefits if they’re included in your federal adjusted gross income, and Kansas has an exemption under a certain income level, or only a portion of your Social Security is taxable.

Differences Between Your Taxable Benefits and Your Tax Rate

It’s important to understand the difference between the amount of your taxable Social Security benefits and your individual tax rate. Your taxable Social Security is calculated using the Social Security Benefits Worksheet contained in the “Instructions for Form 1040” from the IRS.

The worksheet combines several of your income sources, adds 50% of your Social Security benefits, and then determines if 0%, 50%, or up to 85% of your benefits are taxed. Once this taxable amount is determined, it’s entered into the calculation for your Adjusted Gross Income (AGI), which is then used to calculate your taxable income.

A Quick Note on the IRS Distinction Between AGI and Taxable Income

Understanding the difference between your AGI and taxable income matters. Your AGI is used to determine your taxable income. Your AGI includes all your income, adjusted for deductions such as business expenses, capital losses, or other allowable deductions.

Your taxable income is your AGI minus any other deductions such as the standard deduction, including the “enhanced” senior deduction (from Schedule 1-A). The graduated income tax rates are then applied to your taxable income.

Discover these 5 opportunities to help lower your taxes! See what the latest tax law changes may mean for you.

Why Up to 85% of Your Benefits May Be Taxable

In short, the taxable portion of your Social Security is derived from the estimated portion of the average employee’s direct contributions to their benefits. In plain language, 15% of your Social Security payments are considered a return of the Social Security (FICA) taxes you’ve paid toward your own benefit.

This came about because the Old-Age and Survivors Insurance Trust Fund (OASDI) was projected to run out of money by 1983. A National Commission on Social Security Reform was formed, and it recommended treating Social Security more like a private pension. The “Greenspan Commission” recommended taxing the portion not funded by direct employee contributions.

Tiered Taxation Thresholds of 50% and 85%

Ultimately, the idea of making 50% of Social Security taxable stuck, but it was modified with thresholds, taxing 85% of Social Security for “higher income” earners. Keep in mind, the thresholds haven’t been indexed for inflation, so the thresholds of $25,000 (single) and $32,000 (married) were vastly different in 1984.

If those amounts had been adjusted for inflation, it might be roughly $82,000 ($81,922.96 based on CPI calculations) and $105,000 ($104,861.39 based on CPI).

When 85% of Your Benefit Becomes Taxable

If your combined income reaches $34,000 (single) or $44,000 (Married Filing Jointly), then up to 85% of your Social Security benefits are taxable. This is all calculated using the Social Security Benefits Worksheet (see the Form 1040 instructions).

When Social Security Benefits Are Not Taxable

If your combined income is less than $25,000 (single) or $32,000 (MFJ), then none of your Social Security retirement benefits are taxed.

How Combined Income Determines What You Owe

To determine how much of your Social Security income is taxed, the IRS calculates your “combined income” on the Social Security benefits worksheet. This isn’t necessarily a technical term, but it’s helpful to know this number differs from your AGI or taxable income.

What Is Included in the Combined Income Calculation?

Your “combined income” for Social Security taxation includes many components of your adjusted gross income, but not the adjustments from Schedule 1 (deductions). It also adds in any tax-exempt interest. Without getting overly complicated, it’s all income, almost none of the deductions, 50% of your Social Security income (possibly all of it), and any tax-free interest.

In other words, it’s looking at all “useable” money at your disposal during the tax year.

Income Thresholds for Single and Married Taxpayers

There are three separate thresholds for Social Security taxation: none (0%), 50% of benefits, or 85% of benefits. If your combined income is less than $32,000 ($25,000 single filers), then none of your Social Security is taxed. If you earn more, the Social Security benefits worksheet uses two separate calculations to determine how much of your Social Security is taxable, between 50% and 85%.

One exception is for married filing separately. If you are filing married filing separately and lived with your spouse at any time in the year (even one day), then 85% of your Social Security is taxable income. Your income threshold becomes $0.

Taxable Social Security vs Taxable Income

A final and particularly important distinction is the difference between taxable Social Security and taxable income. Even if the maximum Social Security becomes taxable, you might not actually pay taxes on it. Your taxable Social Security becomes a part of your AGI.

Then your AGI determines your taxable income. If you have enough credits and deductions, you might not pay any taxes on Social Security at all. If this seems confusing, that’s because it is.

Temporary Reduction from Current Law

In fact, this is the mechanism by which the One Big Beautiful Bill Act (OBBBA) made Social Security “tax-free” for most seniors. The higher standard deduction in concert with the “enhanced” senior deduction makes the taxable portion of Social Security deductible by default. It’s essentially a tax-deduction shell game, but the result is that most seniors will have standard deductions equal to the average Social Security benefits received.

Before the OBBBA, roughly 64% of seniors owed no tax on Social Security. During the OBBBA “enhanced” deduction phase (tax years 2025 through 2028), an estimated 88% of seniors will have exemptions and deductions that exceed taxable Social Security income.
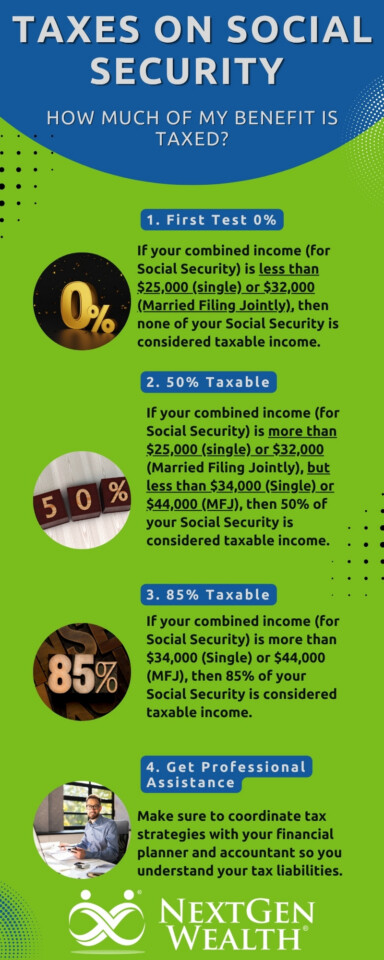
Infographic titled “Taxes on Social Security” explaining the three levels of benefit taxation based on combined income and recommending professional assistance from NextGen Wealth.
Image Credit: NextGen Wealth

Simplified Example of Calculating Taxable Social Security Benefits

Let’s use our good friends Max and Minny Benny as an example. If both are receiving Social Security, taxation of benefits is much more likely. We’ll use the average monthly Social Security payment of $2,071 for 2026, totaling $49,704 as a couple.

Right away, we’re close to the first threshold of $32,000 (using half their Social Security benefits). Max and Minny have to withdraw an additional $3,000 per month to cover their living and travel expenses. This adds $36,000 of income from IRA withdrawals.

This is enough to make 85% of their Social Security taxable. Now they have an AGI of roughly $78,248 from a total of $85,704 of useable income.

Calculating Max and Minny’s Taxable Income

With the standard deduction of $32,200, plus the “normal” additional age 65 standard deduction of $1,650 each, and the new “enhanced” senior deduction from the One Big Beautiful Bill Act of $6,000 each, they have a combined standard deduction of $47,500 for 2026. This significantly reduces their taxable income to $30,748, which is less than their total Social Security benefits alone.

This would translate to roughly $3,194 in total federal taxes (unless they qualify for additional credits or deductions).

Note: This is an extremely simplified version of what goes into your taxes each year. Just completing the Social Security Benefits Worksheet is enough to make your head hurt. We didn’t include common forms of additional income such as interest income, dividends, pension income, or capital gains.

Most people’s tax returns are a tad more complicated. That is why we suggest working with a tax professional to make sure everything is done properly.

Don’t overlook these 5 tax breaks for retirees! Check out these simple moves to consider before you file your taxes.

Other Retirement Income That Can Increase Your Tax Bill

Although Social Security is often a major source of income for retirees, it’s only one part of the equation. Other streams of retirement income can have a much larger impact on your taxes, including increasing your total taxable Social Security.

Pension, 401(k), and Traditional IRA Withdrawals

Income from pensions, employer plans like a 401k or 457, or traditional (tax-deferred) IRA withdrawals can have a major impact. This is especially true if you’re subject to required minimum distributions (RMDs). With RMDs, you don’t have as much control over your income.

Investment Income and Tax-Exempt Interest

We’ve all seen the commercials for various forms of “tax-free” income like municipal bonds. These income sources are added back into the equation for Social Security taxation. This can act as a sort of “phantom tax” on these income-producing assets.

Also, the after-tax yield of things like tax-free bonds is often lower than taxable bonds. Bond prices generally adjust for the allure of “tax-free” or “tax-advantaged” products.

How Roth Withdrawals Can Help Manage Taxable Income

On the other hand, withdrawals from your Roth IRA aren’t included in your AGI or Social Security Benefits Worksheet. This makes Roth accounts immensely helpful in retirement.

Strategies for Reducing Taxes on Social Security

If you start planning now, you may be able to save yourself on taxes (and the resulting headaches). There are more than a few ways to maximize the tax efficiency of your Social Security income.

Coordinate Retirement-Account Withdrawals Before and After Claiming

It can often be beneficial to delay claiming Social Security. This isn’t just because of the additional delayed retirement credits. There’s also more to it than just extracting the most money from Social Security.

Beyond not knowing how long we’ll live, it’s hard to predict how tax laws may change in the future, too. The only true way to “game the system” is by outliving the actuarial tables and drawing a few “extra” years. Statistically speaking, most of us don’t.

It’s better to focus on what we can control first, while trying to influence things like health and longevity.

Consider Roth Conversions Before Required Minimum Distributions

You can often create tax-saving opportunities by coordinating when you stop working and when you start drawing Social Security. If you can wait to draw until full retirement age or later to age 70, you can create an artificial “dip” in income to complete tax-efficient Roth conversions.

You’ll still need to watch for other pitfalls like IRMAA surcharges, but Roth conversions can be extremely helpful. Even if you convert only a portion of your overall balance, you can create flexibility and opportunities to lower your RMDs and tax bill.

Build a Tax-Efficient Retirement Income Plan

Understanding the basics of how Social Security is taxed is essential to building a tax-efficient retirement plan. This can be a real benefit to a safe, secure, and happy retirement. But it all starts with what you truly want.

This seems easy to figure out, but it gets much harder once we start layering in limitations like health, family commitments, and other factors. If you’re married, you add the extra layer of “our” wishes and goals (yours, mine, and ours, right?).

Here are 5 tax questions to ask your financial planner or tax professional. Don’t miss these key considerations during tax season.

How NextGen Wealth Helps with Social Security

Social Security is one of the biggest pieces of American retirement planning. You don’t want to take this irrevocable decision lightly. Make sure you clearly understand the impact on your retirement.

This article was originally published here and is republished on Wealthtender with permission.

About the Author
Headshot of Clint Haynes, CFP®
Clint Haynes, CFP® Helping you build a retirement with pleasure, purpose, and peace of mind.

Clint Haynes, CFP® | NextGen Wealth
Whether you have lived in Marlboro Township for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.

It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Marlboro Township featured on Wealthtender you may want to add to your shortlist.

As you prepare to interview financial advisors in Marlboro Township who may be right for you, get to know local financial advisors featured on Wealthtender.

📍 Map: Financial Advisors with their Primary Office Location in Marlboro Township

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Marlboro Township.

📍Double-click or pinch pins to view more.

Showing

The Benefits of Hiring a Financial Advisor in Marlboro Township

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Marlboro Township, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Do you work for one of the largest employers in Marlboro Township? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Quick Tips For Hiring an Marlboro Township Financial Advisor

Before hiring a financial advisor in Marlboro Township, here are a few quick tips to help you find the best advisor for you.

1. Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2. Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3. Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4. Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.


Frequently Asked Questions & Additional Resources

How do I know if I’m ready to hire a financial advisor?

You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.

But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.

Before I hire a new financial advisor, should I fire my current advisor?

You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.

Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?

After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. 

Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.

I’m a local financial advisor interested in being featured in this guide. How do I get started?

Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.

How Much Does a Financial Advisor Cost?

➡️ How Much Does a Financial Advisor Cost? Read the Article

About the Author
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian

Are you an Arts & Entertainment Professional?

Get expert insights from financial advisors who specialize in helping Arts & Entertainment Professionals navigate the unique financial planning challenges they face.

Looking for a financial advisor who specializes in working with Arts & Entertainment Professionals? You’re in the right place. Below, you’ll find advisors with experience helping Arts & Entertainment Professionals navigate their unique financial planning needs — along with their answers to common questions.

Finding the right financial advisor matters even more when your situation is specialized. For example:

✅ Does your current financial plan take into consideration the financial challenges specific to Arts & Entertainment Professionals?

✅ Are you working with an advisor who understands your circumstances well enough to help you avoid costly mistakes?

Key Takeaways

1

A Reserve Account and Self-Paid ‘Salary’ Can Tame the Feast-or-Famine Income Cycle for Artists

Arts and entertainment professionals often earn a mix of W-2 and 1099 income across unpredictable projects, making cash flow management a core challenge. Routing project income into a reserve account and drawing a steady monthly amount from it restores a sense of financial control. Setting aside taxes on 1099 earnings as they arrive prevents shortfalls when bills come due.

2

Multiple Union Pensions, Annuity Balances, and Health Coverage Rules Make Retirement Planning Unusually Complex for Performing Artists

Many arts professionals hold pension benefits across more than one union, each with its own rules and start dates, alongside annuity fund balances and health coverage tied to continued work. Rather than planning for a hard stop, advisors can map each income source—including Social Security—so clients can phase down gradually without facing a financial cliff. This approach allows established artists to remain selective about projects rather than being forced to accept any available work.

3

An S-Corp or Loan-Out Structure, Union Vesting Milestones, and Mixed Income Streams Signal It’s Time to Hire a Financial Advisor

For artists, financial complexity tends to arrive in recognizable clusters: a significant income jump, a long-running engagement, residuals or royalties layered on top of other earnings, or a first home purchase on 1099 income. These moments benefit from coordinated planning so that each decision reinforces the others rather than creating gaps. Before that complexity appears, a solid budget and emergency fund are often sufficient.

Why Arts & Entertainment Professionals Work with a Specialist Financial Advisor

Careers in film, television, theater, music and dance rarely follow the paycheck-to-paycheck rhythm most financial advice assumes. Income arrives in bursts from projects, residuals and royalties, and the same person may be a W-2 employee on one job and a 1099 contractor on the next, so only part of their earnings has taxes withheld. Some performers work through a loan-out corporation or S-Corp. Many also earn pension credits, annuity fund contributions and health coverage through one or more unions, and health eligibility often depends on how much covered work they booked. A financial advisor who specializes in serving arts and entertainment professionals knows how these pieces fit together and how to build a plan that holds up between jobs.

Money decisions in a creative career are rarely just about numbers. Choosing between a steady role and a passion project, deciding when to slow down, or turning a breakout year into lasting security can carry real emotional weight. These are conversations that may be easier with a trusted financial advisor who understands the creative life and respects the work.

Should You Hire an Arts & Entertainment Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Arts & Entertainment Professionals. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience are the better fit for your unique needs.

💡 In the Q&A below, you’ll gain insights from financial advisors who work with Arts & Entertainment Professionals to help them make smart decisions, reduce their money stress, and feel confident about their financial future.

🙋‍♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.

Q&A: Financial Planning Insights for Arts & Entertainment Professionals

In this section, you’ll gain valuable tips from financial advisors who specialize in working with Arts & Entertainment Professionals.

Financial Advisor Q&A  ·  Arts & Entertainment Professionals

Sylvie Scowcroft, CFP®, Financial Advisor for Arts & Entertainment Professionals at The Financial Grove

Sylvie Scowcroft, CFP®

The Financial Grove  ·  Baltimore, MD  ·  Serves clients nationwide

Financial planning for creatives in film, TV, and theater
Book Intro Call

Hi, I’m Sylvie Scowcroft, Founder and Financial Planner at The Financial Grove.

QWhat is a common financial planning challenge unique to arts and entertainment professionals that you frequently encounter when working with your clients? How do you work with them to overcome this challenge?

For arts and entertainment professionals, one of the primary challenges is the unpredictability of income. Projects and income can vary dramatically from year to year, leading to financial anxiety and the feeling that planning is impossible. Shows close early, pilots don’t get picked up, residuals arrive unpredictably, and jobs end before the next one is booked.

Good planning becomes even more valuable here because there are ways to smooth out your cash flow and put the power back in your hands. One common tactic we use: income from projects goes into a reserve account, and clients pay themselves a steady monthly “salary” from it. Many of my clients are W-2 employees on one job and 1099 contractors on the next, so only part of their income has taxes withheld. We set aside money for taxes on 1099 work as it comes in. You can’t control when the next job comes, but you can control how long your money lasts between jobs.

QFor arts and entertainment professionals who are unsure whether or not they should hire a financial advisor at the current point in their lives, what guidance can you provide to help them make a more informed and educated decision?

For most artists, the right time to hire a financial advisor is when your finances start to get more complicated.

A few moments tend to signal that shift. Your income has jumped and you want to put the extra money to good use. You’ve landed a long-running show that feels more stable than anything you’ve had before. You have assets building up in union funds plus a second type of income, like residuals, royalties, or teaching. You may be ready for an S-Corp or loan-out setup, you’re nearing a union vesting milestone, or you’re considering buying your first home on 1099 income.

In any of these situations, or any time you face a big decision and want to get it right, it helps to have someone looking at the whole picture so each decision works with the others. Before those complications show up, a budget and an emergency fund may be enough to keep you on track.

QHow do the services you offer arts and entertainment professionals distinguish your firm from other advisory firms?

I’ve worked inside the arts as a dancer and as a theater producer, so I understand how different these careers are from almost any other. That experience shapes everything we do at The Financial Grove.

Our clients get an advisor who already understands union pension and annuity systems, the mix of W-2 and 1099 income, and how to plan around income that changes from year to year. Just as important, I understand the emotional side of being a working artist, which doesn’t show up in a spreadsheet but is behind every financial decision.

We focus on mid- to late-career professionals who are established in their field and committed to their craft, even when that means their money will never be perfectly “optimized.” I believe deeply in the value of the arts, and I will never tell a client to get a “real job.”

We’re a fee-only firm with transparent fees, so I’m never selling a product. Artists rarely get the financial education they deserve, and I want my clients to come away more confident about their money, not just better organized.

QFor arts and entertainment professionals approaching retirement age, how do you recommend they prepare to make the transition from living off their working income to relying upon other sources of income?

Most arts and entertainment professionals I work with don’t want to retire in the traditional sense. They fought hard to do the work they do, and they want to keep doing it as long as they can. So instead of planning for a hard stop, we plan for a phase-down. For clients with a traditional job alongside their art, retirement often means finally moving to a full-time creative practice. For clients who earn their living entirely from their art, we build flexibility into the plan so that when they want to slow down, they can afford to be pickier about their projects.

A big part of that is getting crystal clear on how their union benefits fit together. Many of my clients have pensions from more than one union, each with its own rules and start dates, plus annuity fund balances and health coverage that depends on how much they keep working. We map out which income source starts when, including Social Security, so that working less never feels like a financial cliff.

QIs there anything that comes up frequently in your initial meeting with arts and entertainment professionals that surprises you?

Artists are very capable money managers. That isn’t a surprise to me, but it’s often a surprise to them. Anyone who has already navigated years of uneven income and managed to support themselves through all of the uncertainty that comes with life as a freelance artist has a leg up on most people.

They’re also usually better off than they think. Many carry a lot of fear around looking at their money, so they avoid it. Once we look together, we often find money sitting forgotten in union funds, and chances to redirect large checks into a reserve that creates real stability.

What still moves me is how much it means to clients to have a space that’s built for them. Traditional CPAs and investment managers aren’t always sympathetic to the ups and downs of a creative life. We wanted a place where an artist’s work is valued for what it is, not just for what it pays.

Sylvie Scowcroft, CFP®

Considering a financial advisor who specializes in working with Arts & Entertainment Professionals?

Important Disclaimer: Sylvie Scowcroft is the founder of The Financial Grove, a registered investment adviser. These Q&A responses are for educational and informational purposes and do not constitute personalized financial advice. Please consult your own financial professional before making financial decisions.

Are you a financial advisor who specializes in working with Arts & Entertainment Professionals?

✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with Arts & Entertainment Professionals. (Subject to availability and terms.)
✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender

Ask a Financial Advisor Your Questions


Are you ready to enjoy life more with less money stress?

Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.

  • This field is for validation purposes and should be left unchanged.

About the Author

Brian Thorp, Founder and CEO of Wealthtender and Editor-in-Chief

Brian Thorp

Founder & CEO, Wealthtender  ·  Editor-in-Chief

Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.

A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.

Brian and his wife live in Austin, Texas.

Read Brian’s full bio →   ·   Connect on LinkedIn →

A smiling man in a blazer and white collared shirt against a vibrant, multi-colored background.
Ian Karnell, CEO of VastAdvisor | Image Credit: Institute for Innovation Development

[Historically, organic growth processes were rudimentary (e.g., client referrals or email campaigns), but now an expanding focus on “growth intelligence” is quickly becoming the primary value proposition. This is leading to the development of organic growth AI operating systems for wealth management that embed continuous learning, intelligence development, and compliance capabilities, rather than being a tactical marketing platform.

Digital growth intelligence can now power predictable, repeatable, and scalable growth engines that can increase premium firm valuations. This is because potential acquirers can continue firm growth without the founders by using growth intelligence assets that feed a self‑learning model, improve future actions, and form a competitive moat for the firm.

To continue our coverage of the “Organic Growth Crisis in Wealth Management” and learn more about growth intelligence, we spoke with Ian Karnell, CEO of VastAdvisor — an AI-powered organic growth platform and proprietary “agent swarm” designed specifically for RIAs and wealth enterprises. In our discussion, we explored the structural bottlenecks that prevent wealth management firms from executing effective digital campaigns and how AI is collapsing a marketing campaign process that used to take weeks into one that takes minutes.

He argues that marketing often fails due to misalignment between firm narrative and audience intent, and that their AI-Powered Campaign Builder and its nine-step process closes this gap by combining firm identity and Ideal Customer Profile(ICP)‑specific insights to proactively orchestrate campaigns: selecting audiences, defining offers and positioning, choosing channels and ad types, setting budgets, generating assets, and performing inline SEC/FINRA compliance checks via “generative compliance at the architectural level”.

Their centralized growth intelligence layer was designed as a force multiplier for financial firms to help them move from AI pilots to production‑grade enterprise AI, citing data that about 70% of AI initiatives have been shut down or remain stuck in pilot.]

Hortz: What are the primary reasons financial firms have struggled with traditional organic growth processes?

Karnell: The industry built its entire growth motion on three mechanisms, and all three cap out structurally rather than just needing “more effort.”

Referrals do not scale because they are not owned. Referral-based growth is overly reliant on somebody else’s relationship — a single advisor’s or founder’s network — which means it cannot be turned on, cannot be forecasted, and evaporates the moment that person leaves or retires. Industry organic growth nets out to roughly 1% once you strip out market appreciation — an anemic rate for a sector sitting on the largest wealth transfer in history.

Lead brokers rent growth instead of building it. These platforms buy traffic cheaply and resell the same lead to multiple competing advisors simultaneously — the arbitrage math runs roughly $55 -$75 cost per lead resold at $300 – $500 — and critically, they never share the signal intelligence (where the lead originated, how it was qualified) back to the firm. A firm using lead brokers learns nothing and owns nothing; the moment it stops paying, the pipeline stops.

The investor profile has fundamentally changed underneath the old playbook. Roughly $120 trillion is shifting hands to digital-first generations (Gen X through Gen Z) who discover, research, and hire advisors in radically different ways than their parents — spending time on Reddit and social channels rather than reading print financial media, and increasingly asking ChatGPT, Gemini, or Claude instead of Googling. Organic site traffic for the whole industry is heading toward a 50% decline in the next couple of years, even as SEO-driven growth erodes.

The deeper structural failure is misalignment, not volume. Where marketing breaks down is usually not the ad itself — it’s the disconnect between a firm’s generic narrative and the specific intent of the person seeing the ad, and most legacy tools and agencies have no systematic way to close that gap at the pace or cost the channel now demands.

Hortz: How did you design your AI-Powered Campaign Builder into an “organic growth AI operating system” rather than a marketing platform? What is the fundamental difference, and why does that distinction matter for wealth management firms?

Karnell: The design decision was explicit: we positioned VastAdvisor as a governed Al growth operating system — not a marketing platform. Governed means every Al decision made on the platform, through an agent, a sub-agent, or a workflow, is continuously observed and stored so it can be audited, because the SEC requires that level of oversight for any Al used in a market-facing capacity.

The fundamental difference is that a marketing platform executes campaigns; an operating system builds and compounds intelligence.

The approach was not to build a marketing platform, but a growth operating system that enables the wealth management industry — at both the enterprise and RIA level — to start building learning systems that drive organic growth, powered by what we call the Advisor Intelligence Loop, where every signal the platform generates or observes gets pulled in and trains the agents to improve outcomes for the next iteration.

Two architectural choices make this real rather than a marketing claim:

Compliance is built into system architecture, not bolted on as policy. We made a decision to not have compliance at the policy level. We wanted to bring compliance into the system architecture so it auto-checks against SEC and FINRA in line with the same workflows that generate ad assets and target ICPs.

The intelligence layer is the asset; software is not. In a world where everyone has Al and software is commoditized, that is not your competitive moat anymore — your data, and what you do with it, becomes the moat.

This distinction matters for wealth firms because a marketing platform is a rented capability whose value disappears when you stop paying; an operating system is owned infrastructure that compounds — the data, the fine- tuned model, and the audit trail all stay with the firm and keep improving independent of any single vendor relationship or founder.

Hortz: Can you walk us through the steps of what your AI operating system actually does for an advisory firm that wants to launch a campaign?

Karnell:  Before a firm ever builds a campaign, an onboarding agent does the foundational work: it scans the firm’s website, runs a Google search, reviews the Form ADV, and pulls the LinkedIn page to auto—configure firm settings, identify fee structure and service offerings, and surface the firm’s top Ideal Client Profiles (ICPs) — complete with demographic and psychographic insight into pain points, values, and motivators, using core data sources like Pew Research, Meta for Business, and Boston Consulting Group.

Campaign creation itself runs through a structured nine-step wizard (ten steps if starting from an asset or narrative rather than an audience) with three possible starting points — audience-first, asset-first (upload a PDF or webinar URL), or narrative-first (describe the pitch):

Step 1 – Starting point — choose the modality.

Step 2 – Target Niche — select the ICP to target.

Step 3 – Positioning & Offering — the platform takes the firm’s general unique value proposition (UVP) and rewrites it to be specific to the audience being targeted, rather than a one-size-fits-all pitch, and pre-selects which service offerings will most resonate with that ICP.

Step 4 – Campaign Themes — the platform generates several Al campaign themes (typically four to six), each with a resonance score reflecting ICP alignment, market conditions, message clarity, and historical click-through data, plus straw-man headline/body/call-to-action (CTA) copy so you can feel the difference before committing. Some themes incorporate real-time market catalysts — an interest rate shift, a regulatory development, a Medicare IRMAA change — pulled from continuous monitoring of economic and regulatory data.

Step 5 – Campaign Identity — the platform auto-names the campaign, writes a description, adds UTM tracking, and assigns an immutable VastlD that follows the campaign through every platform and reporting view.

Step 6 – Channel Mix — the platform assesses every connected ad platform (Google, Meta, LinkedIn, and others) against the specific ICP — audience size, competitiveness, cost to reach, and historical engagement data — and recommends the optimal channel mix and ad format per channel, explicitly excluding platforms that are not a fit and explaining why.

Step 7 – Budget & Return on AD Spend (ROAS) projections — the Al recommends a daily budget and campaign duration (90 or 180 days) and builds forecasts for leads, meetings, new clients, AUM gained, and revenue, calculated per platform and combined into a spend-weighted total so a firm can build a business case before spending a dollar.

Step 8 – Asset Generation with Inline Compliance — the platform builds all ad assets (images, video, carousel formats) while running real-time compliance checks against SEC, FINRA, and (for Canadian RIAs) federal regulatory considerations.

Step 9 – Review & Launch — a full summary (executive Summary, goals, projected performance, ICP, channel mix, compliance overview) that can be finished and launched, downloaded as a PDF, or submitted for compliance approval.

The whole chain is dynamic, not static – change the selected ICP and the UVP, the insights, offering recommendations, and themes to regenerate for the new audience. Once live, every campaign is trackable from a central “Campaigns” view — status, channels, audience, budget, leads generated, conversion rates, and drill-down into hourly performance trends and audience insights.

Hortz: How exactly do you deploy AI agents into an “agent swarm” that autonomously accomplishes this campaign activity? What are your continuing plans for AI agent usage?

Karnell: The platform runs on an agentic framework — a defined roster of specialized agents, each responsible for one part of the growth workflow, operating under firm-configurable guardrails rather than full autonomy.

Agentic, properly defined, means Al that has agency — the ability to understand a task, infer how to solve a problem, and act autonomously — and no firm on the planet is handing its growth strategy over to fully autonomous Al today, especially in a regulated market. So, rather than claim full autonomy, we built an agentic framework where firms can toggle any agent on or off, set sensitivity thresholds (more or less active), and define activation triggers — for example, the Ad Optimization Agent firing only after 24 hours of performance data or when ROAS drops below a set threshold. Even in “Al Autopilot” mode, additional guardrails require manual approval for things like new campaign launches or budget changes, and firms can cap daily budget authority the Al is allowed to exercise on its own.

Where this is headed: the plan is to keep shipping new specialized agents (a geo targeting agent has been discussed, for instance) and to use performance data from every agent action to continually retrain and tune the underlying models, with the long-term trajectory toward real agentic Al — handing an agent a task with the same trust you would give an employee — once confidence in consistent, predictable agent performance is established. We are building toward where the market is going, not where it is today, while keeping governance rails firmly in place until that confidence is earned.

Hortz: What guardrails are placed around the AI agents and how do marketing and compliance teams maintain visibility and final decisions into what the agents are doing? 

Karnell: Three layers of guardrails operate simultaneously:

Human-in-the-loop by design, not as an afterthought. The application was designed for Al to do the heavy cognitive lift while keeping a human in the loop at every step — a user selects the ICP, approves or edits the Al-generated UVP and positioning, chooses the campaign theme from Al-ranked options, and reviews the final summary before anything launches.

The agentic framework gives firms direct control knobs. Every agent can be toggled on or off individually; sensitivity thresholds control how actively an agent behaves; activation triggers define exactly when an agent is allowed to act (e.g., only after 24 hours of performance data, or only when ROAS drops below a threshold). Even in Al Autopilot mode, firms can require manual approval specifically for campaign launches, new audience creation, or budget changes, and can hard-cap the daily ad spend an agent is permitted to adjust autonomously.

Compliance has its own dedicated workflow and record. Content flows through an approval path (advisor draft, compliance review, launch) configurable by role. The Compliance Review Agent checks every line of Al and human-generated copy against 13 FINRA violation categories (implied guarantees, misleading risk disclosure, exaggerated claims, etc.), flags issues with a severity score, and the compliance officer has a dedicated workspace showing full campaign context, every flagged item, and three resolution paths: accept the Al’s suggested rewrite, accept the risk with a logged justification, or edit manually and resubmit. Every single compliance check and modification a compliance officer makes is captured and stored for seven years.

Everything is logged for regulatory observability. The SEC requires Al telemetry and observability for any Al used in a market-facing capacity — you need to be able to track every Al decision at the agent, sub-agent, and workflow level, time- and date-stamped. Agent IQ captures that full activity log — what happened, what the output was, when it occurred — filterable by date range, campaign, or tenant, and exportable in CSV, JSON, or PDF for regulatory submission.

Hortz: How does the self-learning AI system ensure that faster execution does not lead to faster failures, inappropriate action steps, and detect/correct for drift or degradation in campaign performance over time? 

Karnell:   Speed is deliberately decoupled from unchecked autonomy through the guardrail layer described above — nothing moves faster than the thresholds, triggers, and manual-approval requirements a firm has configured allows, regardless of how fast the underlying model can act.

On the model-quality side, every campaign run, every lead qualified, and every compliance decision made generates a learning signal that feeds back into the fine- tuned models — all of those signals are aimed specifically at mitigating drift, mitigating latency, mitigating cost, and improving predictability over time, which in turn affects click-through rates, cost per lead, cost per acquisition, and audience targeting precision.

VastAdvisor IQ is the dedicated instrumentation layer for this: it surfaces model performance dashboards — quality scores, latency, hallucination rates, predictive accuracy — and lets a firm (or our own data science team) benchmark their fine-tuned model against the cohort median, see how a new model version impacted click-through rate and cost-per-lead, and drill into drift and latency insights, prediction stability, and data quality. Every model version is tracked, so if a model update underperforms, it can be rolled back.

Regulatory-grade compliance is treated the same way. The Regulatory Monitoring Agent runs 24/7 against SEC and FINRA publication sites, and any new guidance automatically retrains or extends the compliance agent so its judgment does not go stale — the same “learning system” logic applied to the compliance domain specifically, so faster execution doesn’t mean compliance falls behind the rules as they change.

Candidly, the honest caveat here is that outcome-level validation — did campaigns that benefited from this learning loop actually outperform over a full market cycle? – is the hardest and slowest layer to prove. It requires enough volume and tenure per firm to be statistically reliable, which is why we are transparent that this compounding benefit is a trajectory we are instrumented to prove out over time, not a static guarantee on day one.

Hortz: How does this growth intelligence provide competitive moat and true differentiators for wealth management firms?

Karnell: The moat argument starts with hard valuation data: firms that had systematized organic growth — repeatable, scalable, predictable, not overly reliant on referrals, lead brokers, or a single rainmaker — saw valuations roughly 200% higher on average than firms still dependent on those older models. That data point, observed while I was building Trulytics (sold to Envestnet), is the founding thesis behind VastAdvisor.

The mechanism behind that premium is ownership versus rental: referral-based growth is opaque and retires when the referral source does; lead-broker growth is rented — the broker never shares the signal intelligence of where a lead came from or how it converted, and you are paying a markup for a lead resold to competitors simultaneously. Systematized, owned growth instead produces something you can actually underwrite – documented/verified credit-for-prior-learning (CPL) the firm controls, audience data that compounds month over month, and a growth system that transfers with the firm rather than with a vendor or a single founder. In a world where everyone has access to Al and software itself is commoditized, your data and what you do with it becomes the moat.

The compounding intelligence layer — the Advisor Intelligence Loop — is what we consider the actual, durable differentiator, not the software shell around it. The more a firm (or, at the enterprise level, a whole advisor network) runs campaigns through the platform, the smarter its targeting, messaging, and compliance judgment get, which is a compounding advantage that’s increasingly difficult for a competitor — or a generic Al tool — to replicate, because they would have to start the learning loop from zero.

For an acquirer specifically, this reframes firm value: growth intelligence is an asset that survives a change of ownership. A buyer is not just acquiring AUM and a client list; they are acquiring a self-improving growth engine, audience and compliance intelligence, and a documented, auditable system that keeps producing a qualified pipeline without being dependent on the departing founder’s personal network.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

A middle-aged man, Bill Hortz, with short dark hair wearing a dark pinstripe suit, white dress shirt, and a maroon tie, posing against a plain gray backdrop. He has a slight smile and is looking directly at the camera.

Bill Hortz

Founder Institute for Innovation Development

Bill Hortz is an independent business consultant and Founder/Dean of the Institute for Innovation Development- a financial services business innovation platform and network. With over 30 years of experience in the financial services industry including expertise in sales/marketing/branding of asset management firms, as well as, creatively restructuring and developing internal/external sales and strategic account departments for 5 major financial firms, including OppenheimerFunds, Neuberger&Berman and Templeton Funds Distributors. His wide ranging experiences have led Bill to a strong belief, passion and advocation for strategic thinking, innovation creation and strategic account management as the nexus of business skills needed to address a business environment challenged by an accelerating rate of change.

Not everyone starts a business planning to sell it. Some of you have no interest in an exit at all, and that’s fine.

But stick with me, because the work that makes a business sellable is the same work that makes it healthier, calmer, and more profitable to run right now. Even if you never sell, you win.

I speak from experience here. I started a marketing agency in college and ran it for about 23 years, first with a couple of partners and later on my own. Eventually another agency acquired it in a strategic buy, and that whole process taught me a lot about what actually drives value in a business.

I’ve also helped other owners get their businesses ready to sell. So what follows is a practical look at what makes a company worth buying, and why those same qualities are worth building regardless of your plans.

Focus on Scaling From the Start

Start small but think big.

If you launch a business assuming it will always be just you, or just you and a helper or two, you’ll make small decisions that get irritating or expensive to unwind later.

Take something as basic as email addresses. If you set yourself up as firstname@yourcompany.com and then hire people using the same pattern, you’ll eventually have two people named Chris and a problem to solve. Firstname.lastname@yourcompany.com scales cleanly from day one.

The same logic applies to software. You can get by early on with cheap tools stitched together, but at some point that patchwork slows you down. Choosing systems that grow with your team saves you a painful migration later.

Policies matter too. Decide early how you handle refunds, payments, and the situations that go wrong before they happen. Writing those rules while you’re small means they’re in place as you grow.

Don’t Obsess Over Funding

A lot of small business owners chase investors or venture capital, waiting for a big payday that rarely arrives.

I’ll be blunt. For most service, product, and even software businesses, outside funding never comes. The stories you read about rapid rounds of investment are the exceptions we celebrate, not the norm.

The sooner you let go of that idea, the sooner you make better decisions built on organic growth. And organic growth is fully in your control.

Funding also brings complexity, obligations, and a whole bunch of people to answer to. You probably don’t want it, and you almost probably don’t need it.

Develop Intellectual Property

Intellectual property gives a buyer something to purchase beyond your client list and revenue.

It can take many forms. Software you build in house, a specialized process refined over years, course material, written content, or a method of serving your market that competitors can’t easily copy.

This isn’t easy for every business, and it may not apply to yours. But when you own something proprietary, the buyer is acquiring that asset along with everything else, and that pushes the value up.

Keep It Simple

I’m a little obsessed with this one, so bear with me.

Many business owners love complexity. It creeps into pricing, product lines, services, delivery, and reporting.

Some of it comes from our own restlessness. Things are working fine, but we have an itch to improve, so we add and tinker until the simple thing becomes complicated.

The biggest culprit is weak boundaries. A client asks for something a little different, you say yes because you want to help, and you build a one-off process just for them. The next client asks for something else, and you accommodate that too.

Before long your three clean service packages have become 21 half-documented variations, and you’re improvising half of them on the fly.

Reporting can suffer the same fate. Metrics are useful, but chasing every possible number can pull you into hours of work and maintaining data that no one ever looks at.

A simple business is easy to run and easy to take over. That makes it more valuable to a buyer, and a lot more pleasant for you in the meantime.

Create Consistent Cash Flow

If I had to name the single factor that most raises the value of a business, it would be consistent cash flow.

Many companies run feast or famine. A big project lands, then the work dries up, then you scramble for the next one. You’re always chasing.

Some industries make this hard to avoid. A real estate agent lives with listings that come and go. But many businesses can build in some form of steady revenue, even project-based ones.

Tax service is a good example. Historically, it was seasonal and project-driven, with cleanup work a few times a year. Now many tax pros put clients on a monthly retainer, which gives the firm predictable income and the client steadier support. Everyone benefits.

Recurring revenue through subscriptions, retainers, or automated monthly billing is one of the most attractive traits a business can have. When it’s not possible, a wide and diverse client base can create a similar steadiness, with new orders always coming in from somewhere.

A reliable marketing system can do the same job. Build the funnels and content that pull in a steady flow of leads, and even a project-based business gains some predictability. It’s hard to build, but it’s valuable when it works.

Keep Clean and Current Financial Statements

Plenty of owners ignore their books entirely. Chaotic bookkeeping, tax returns a couple of years behind, a pile of receipts, and messy records.

A buyer will not want to see that. The first thing they ask for is your financials, and messy books can stall or kill a deal.

One of the best investments any owner can make is hiring an accountant to handle bookkeeping on a regular schedule, quarterly at a minimum, along with your taxes. This results in clean, current statements ready to share whenever someone asks for them.

This pays off even if you never sell. Government aid programs, loans, and lines of credit all rely on solid records. And you get better reporting to see how your business is doing. Good books are simply good practice.

Invest in Your Brand

Your brand can carry real value, and small businesses often overlook it.

This goes beyond what you spend on a logo. Your identity, colors, fonts, and visual style matter, but how consistently you use them matters just as much.

Say you paid a couple thousand dollars for a logo and website and stopped there. That’s fine. Now picture the alternative, where that same identity shows up across every social profile, every printed piece, every shirt your team wears, every video and invoice you send. Each of those touchpoints reinforces who you are.

That consistency strengthens the brand, and a stronger brand strengthens the business. Something as intangible as a brand can add value to what a buyer is willing to pay.

Brand can do a lot for solo owners in particular. If you’re a massage therapist, an appraiser, or a coach, a strong brand starts to lift the business above you as an individual. It becomes an experience clients recognize, which gives you something to hand off later.

Demonstrate Growth

Growth is a green light for any buyer.

If your revenue and profit tick up a little each year, you’re showing exactly what a prospective owner wants to see. A five-year statement that ends higher than it started signals a healthy business, even with a down year or two in the middle.

Steady year-over-year growth is even better. When each year beats the last, especially on profit, the business becomes highly attractive.

So keep expenses in check, but keep investing too. Spend on marketing, on winning new clients, on replacing clunky software with efficient tools that let you do more with less. Push revenue up, but profit is even more important.

Build Systems and Teams That Run Without You

Here’s the harder one. To build a truly valuable business, you have to fire yourself.

When the company runs on its own without you in every operation, its value climbs dramatically. A buyer does not want a business where the owner is stuck in daily operations, because then they either have to keep you around or watch things fall apart when you leave.

If you’re mostly overseeing the business, handling some admin, and letting your team run the day-to-day, you’ve reached the point where your business gets more attractive to a buyer.

This is what helped me sell my marketing agency. I had promoted good people, and a strong team leader was running general operations. I’d stepped out of the daily work, so the handoff was smooth because I wasn’t tangled up in everything.

The buyer was surprised at how easy I was to replace. My ego didn’t love that, but my ability to sell certainly did.

We all like to think we’re irreplaceable. Letting go of that belief is what turns a job into an asset. An asset generates income, through cash flow or a sale, and it does that best when it runs without its owner.

Even a solo business can move in this direction. Bring on a virtual assistant or two for the admin and marketing, keep the high-value knowledge work for yourself, and outsource nearly everything else. You show up for the work only you can do, and the rest runs on its own.

Build It Like You’ll Never Sell

After all this talk of building a business you can sell, there is an important concept to bring balance to the conversation.

Treat your business as though you will never exit. I’ve watched owners get so fixated on a future sale that they stop improving the very things that make a business worth buying. They neglect growth, processes, and their team, and the company loses value while they wait for a payday that may never come.

The way to protect the value of an eventual sale is to run the business like the sale isn’t coming. That keeps you focused on steady improvement.

If you never plan to sell, you keep building anyway, and everything on this list still makes the business stronger and more enjoyable to own. If you do plan to sell and later change your mind, you’re left with a healthy company throwing off good cash flow. Both paths lead to a positive result.

One last thing. Don’t accept the assumption that your kind of business can’t be sold. I’ve seen surprising businesses find buyers, including ones built entirely around a single owner. There’s almost always a way to capture value, whether through a sale or another kind of transition. Don’t give up on the idea that your business can be worth something to someone else someday.

Frequently Asked Questions

Do I need to plan on selling to benefit from this?

No. Every quality that makes a business sellable, from clean books to steady cash flow to a team that runs without you, also makes it healthier and more profitable to own right now. The work pays off either way.

My business is basically just me. Can it still be sold?

Often, yes. Solo businesses built around one person can be harder to sell, but a strong brand, documented processes, and a small support team can create real value that transfers to a new owner. Don’t assume it’s impossible.

What raises the value of a business the most?

Consistent, recurring cash flow and a business that runs without the owner tend to move the needle most. Buyers pay for predictability, and for a business they can step into without depending on you.

How far in advance should I get my financials in order?

Start now. Clean, current financial statements take time to build, and a buyer will ask for several years of history. Regular bookkeeping and timely tax returns should be in place well before you ever consider a sale.

Should I try to raise outside funding to grow faster?

For most small businesses, outside funding never materializes and adds complexity when it does. Focus your energy on organic growth, which you control, rather than waiting on investors.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

Headshot of Michael Reynolds, CFP®, CSRIC®, AIF®, CFT-I™
Michael Reynolds, CFP®, CSRIC®, AIF®, CFT-I™ Progressive Financial Planning & SRI/ESG Investing.

Michael Reynolds, CFP®, CSRIC®, AIF®, CFT-I™ | Elevation Financial

Whether you have lived in Hobart for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.

It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Hobart featured on Wealthtender you may want to add to your shortlist.

As you prepare to interview financial advisors in Hobart who may be right for you, get to know local financial advisors featured on Wealthtender.

📍 Map: Financial Advisors with their Primary Office Location in Hobart

Coming soon.

📍 Additional Advisors Who Serve Clients in Hobart

In addition to the advisors featured above, these advisors can also meet with you in person in Hobart.

The Benefits of Hiring a Financial Advisor in Hobart

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Hobart, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Do you work for one of the largest employers in Hobart? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Quick Tips For Hiring an Hobart Financial Advisor

Before hiring a financial advisor in Hobart, here are a few quick tips to help you find the best advisor for you.

1. Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2. Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3. Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4. Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.

Frequently Asked Questions & Additional Resources

How do I know if I’m ready to hire a financial advisor?

You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.

But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.

Before I hire a new financial advisor, should I fire my current advisor?

You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.

Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?

After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. 

Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.

I’m a local financial advisor interested in being featured in this guide. How do I get started?

Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.

How Much Does a Financial Advisor Cost?

➡️ How Much Does a Financial Advisor Cost? Read the Article

About the Author
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian

Whether you have lived in Glenwood Springs for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.

It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Glenwood Springs featured on Wealthtender you may want to add to your shortlist.

As you prepare to interview financial advisors in Glenwood Springs who may be right for you, get to know local financial advisors featured on Wealthtender.

📍 Map: Financial Advisors with their Primary Office Location in Glenwood Springs

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Glenwood Springs.

📍Double-click or pinch pins to view more.

Showing

The Benefits of Hiring a Financial Advisor in Glenwood Springs

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Glenwood Springs, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Do you work for one of the largest employers in Glenwood Springs? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Quick Tips For Hiring an Glenwood Springs Financial Advisor

Before hiring a financial advisor in Glenwood Springs, here are a few quick tips to help you find the best advisor for you.

1. Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2. Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3. Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4. Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.


Frequently Asked Questions & Additional Resources

How do I know if I’m ready to hire a financial advisor?

You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.

But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.

Before I hire a new financial advisor, should I fire my current advisor?

You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.

Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?

After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. 

Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.

I’m a local financial advisor interested in being featured in this guide. How do I get started?

Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.

How Much Does a Financial Advisor Cost?

➡️ How Much Does a Financial Advisor Cost? Read the Article

About the Author
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian

Sean McCarthy, CFP®, ChFC®, RICP®
Guest contributorSean McCarthy, CFP®, ChFC®, RICP®OnePoint BFG Wealth Partners
View profile

What this article covers

Sean McCarthy, CFP®, of OnePoint BFG Wealth Partners explains what corporate executives should expect from a financial advisor when their pay includes RSUs, PSUs, ESPPs and stock options. He covers multi-year tax projections, managing concentrated company stock within blackout windows and Rule 10b5-1 plans, and the capabilities to look for before you hire an advisor.

Key Takeaways

1

Equity compensation only makes sense in context

Salary, bonuses, vesting schedules, option deadlines, and future grants belong in one connected plan, not a series of separate decisions. A portfolio can look diversified and still carry heavy concentration once you count pending grants, unvested shares, and the fact that your paycheck depends on the same company.

2

A single tax return is the wrong lens for equity decisions

Withholding rarely matches your final bill, so you usually need to project vesting, exercises, and sales across several years. Coordinating charitable gifts, retirement contributions, and estimated payments with a CPA can keep several large taxable events from landing in the same twelve months.

3

Diversification has to work within the rules you actually face

Blackout windows, company policy, and concentration risk shape when and how you can responsibly sell shares. Selling plans need to be built in advance, and a properly structured Rule 10b5-1 plan comes with a cooling-off period before trading can begin.

Most executives don’t struggle with earning equity. They struggle with knowing what to do with it once it’s theirs. A W-2 with RSUs, options, and a bonus structure attached to it doesn’t behave like a normal paycheck, and a financial plan that treats it that way often misses what matters most.

The right advisor relationship connects every piece of your compensation instead of reacting to one vesting date or one exercise decision at a time. That coordination separates a plan that anticipates your next tax year from one that’s constantly catching up.

Disclaimer: This article has been provided for informational purposes only and should not be considered as investment advice or as a recommendation. This material provides general information only. OnePoint BFG does not offer legal or tax advice. Please contact legal counsel or your tax advisor to recommend the application of this general information to any particular situation or prepare an instrument chosen to implement the design discussed herein. Circular 230 notice: To ensure compliance with requirements imposed by the IRS, this notice is to inform you that any tax advice included in this communication, including any attachments, is not intended or written to be used, and cannot be used, for the purpose of avoiding any federal tax penalty or promoting, marketing, or recommending to another party any transaction or matter.

Start With a Complete Picture of Your Compensation

We rarely get an executive’s full financial picture in the first conversation. Salary and bonus are easy to name; unvested awards, option expirations, and deferred compensation often come up as an afterthought, even though they can carry more long-term weight.

A portfolio can look diversified and still carry heavy concentration once you count what’s coming, such as pending grants, unvested shares, and the simple fact that your paycheck depends on the same company. We map compensation next to existing assets before touching a single allocation, because the real exposure is rarely visible in the brokerage account alone.

Know What Each Award Is Actually Doing

RSUs and PSUs: Restricted stock generally creates taxable income at vesting whether or not you sell, and performance-based awards add a layer of uncertainty about the size of that income until results are finalized.

ESPPs: A purchase discount is valuable, but repeated participation can quietly deepen a concentration you’re already trying to manage elsewhere.

ISOs and NSOs: Exercising a nonqualified option generally creates ordinary income right away. Incentive stock options can be more tax-efficient, but exercising and holding them may trigger the alternative minimum tax in the year of exercise.¹

Where we spend the most time isn’t defining these terms, it’s translating them into a specific decision about cash, timing, and how much company stock you’re comfortable holding afterward.

Build a Tax Strategy That Spans Years, Not Returns

Withholding on vesting and bonuses is often a flat rate that has little to do with your actual bracket, which is where the surprise balance due usually comes from. We build multi-year tax projections that place vesting, exercises, sales, and deferred compensation on the same timeline so timing decisions can be tested before money moves, not after.

Charitable gifts, retirement contributions, and estimated payments often create room inside that timeline. Coordinating them with a CPA, rather than treating each as a year-end decision, tends to prevent several large taxable events from landing in the same twelve months by accident.

Manage Concentration Within the Rules You Actually Face

Familiarity can make a large equity position feel safer than it is. We evaluate employer stock with the same discipline we’d apply to any concentrated holding, factoring in that your salary, bonus, and career opportunity are already tied to the same company before counting a single share. We’ve written more about where that exposure tends to hide and how it shapes a broader diversification strategy.

Execution has its own constraints. Blackout windows and internal policy can limit when shares may trade, so selling plans need to be built in advance rather than assembled once a window opens. A properly structured Rule 10b5-1 plan can help, though current rules require a 90-day cooling-off period for directors and officers before trading can begin, and a 30-day period for other insiders.² We walk through how that structure works in more detail in our piece on 10b5-1 selling plans.

What to Look for in an Advisor Who Handles Executive Compensation

Specialized knowledge matters, but process matters just as much. Look for evidence that an advisor can:

  • Work across RSUs, PSUs, ESPPs, ISOs, and NSOs as one cohesive picture, not isolated transactions.
  • Build multi-year projections instead of reacting to a single tax season.
  • Evaluate concentration through a defined framework rather than a general sense of comfort.
  • Understand blackout windows and 10b5-1 structuring well enough to know when compliance review is needed.
  • Coordinate directly with your CPA, estate attorney, and corporate counsel, including estate planning tied to concentrated stock.

Choosing a Financial Advisor for Equity Compensation FAQs

1. How should an advisor help manage RSU vesting?

By mapping each vest, estimating income and withholding ahead of time, and deciding how many shares to keep against your target company-stock allocation.

2. What does coordinated tax strategy actually look like?

Multi-year projections that include salary, bonuses, vesting, exercises, and charitable giving, built and reviewed together with your CPA.

3. Can an advisor help set up a 10b5-1 plan?

An advisor can help define sale objectives, tax reserves, and reinvestment instructions, while securities counsel and your plan administrator handle legal and procedural requirements.

4. How should ISOs and NSOs be compared?

By evaluating exercise costs, expiration dates, potential AMT exposure, and downstream tax implications upon sale, all balanced against your liquidity requirements and willingness to maintain concentrated company stock.

5. Can concentration be reduced without an outsized tax bill?

Often, yes. Staged sales, charitable giving, tax loss harvesting, and coordination with upcoming vesting can spread the tax impact across time rather than absorbing it in one year.

Get Coordinated Guidance for Equity Compensation, Taxes, and Employer Stock Risk

Executive compensation rewards patience more than speed. Awards, tax exposure, and concentration risk all move together, and a plan that treats them separately usually ends up a step behind.

Our team helps organize your equity awards, model exercise and vesting decisions, and build a tax-aware, compliance-conscious plan for selling and reinvesting shares. We coordinate that work with your CPA, estate attorney, and corporate counsel so nothing gets decided in a vacuum.

If your compensation has grown more complex than your current plan accounts for, schedule a complimentary consultation with our team.

Resources

  1. IRS Topic 427: Stock Options
  2. SEC Fact Sheet: Rule 10b5-1 Insider Trading Arrangements

DISCLAIMER

The information contained herein is provided for informational and discussion purposes only. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. It may not be used or relied upon in connection with any offer or sale of securities. The information as set forth herein should not be construed or interpreted as OnePoint BFG’s guarantee of any particular investment outcome or a guarantee of future investment returns or results.

The information provided herein involves the views and judgment of your financial professional, a OnePoint BFG (also referred to as “OnePoint BFG’s Advisors,” “the Advisor” or “its Advisors”). These views regarding the economy, the securities markets, or other specialized areas, like all predictions of future events, cannot be guaranteed to be accurate. The information herein reflects prevailing market conditions and the Advisor’s judgment as of this date, all of which are subject to change without notice.

References herein to OnePoint BFG or OnePoint BFG as a “registered investment adviser” or any reference to being “registered” do not imply a certain level of skill or training.

OnePoint BFG does not offer legal or tax advice. This document is not a substitute for the advice of a qualified attorney or tax professional. You should not take any action based solely on the information provided on this report without seeking legal counsel from a licensed attorney or tax professional in your jurisdiction. No attorney-client relationship is formed by your use of this document.

This communication has been provided for informational purposes only and should not be considered as investment, legal or tax advice or as a recommendation. This material provides general information only. OnePoint BFG does not offer legal or tax advice. Please contact legal counsel or your tax advisor to recommend the application of this general information to any particular situation or prepare an instrument chosen to implement the design discussed herein. Circular 230 notice: To ensure compliance with requirements imposed by the IRS, this notice is to inform you that any tax advice included in this communication, including any attachments, is not intended or written to be used, and cannot be used, for the purpose of avoiding any federal tax penalty or promoting, marketing, or recommending to another party any transaction or matter.

OnePoint BFG Wealth Partners (“OnePoint BFG”) often uses Artificial Intelligence (“AI”) in the generation of reports such as the above. OnePoint BFG and its employees are bound by all applicable Firm policies and procedures when using AI. AI is subject to risks and limitations. OnePoint BFG has established policies and procedures to ensure all AI generated material goes through human review prior to dissemination. For additional information regarding AI, please refer to OnePoint BFG’s ADV 2A.

OP#26-0977

This article reflects the insights and opinions of its author and is not a recommendation or endorsement of their views or services. For informational purposes only, not financial advice. Always consult a financial professional before making any major financial decisions.

About the Author

Headshot of Sean McCarthy, CFP®, ChFC®, RICP®
Sean McCarthy, CFP®, ChFC®, RICP® Financial planning for tech execs, retirees and business owners

Sean McCarthy, CFP®, ChFC®, RICP® | OnePoint BFG Wealth Partners

Whether you have lived in Salina for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.

It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Salina featured on Wealthtender you may want to add to your shortlist.

As you prepare to interview financial advisors in Salina who may be right for you, get to know local financial advisors featured on Wealthtender.

📍 Map: Financial Advisors with their Primary Office Location in Salina

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Salina.

📍Double-click or pinch pins to view more.

Showing

The Benefits of Hiring a Financial Advisor in Salina

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Salina, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Do you work for one of the largest employers in Salina? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Quick Tips For Hiring an Salina Financial Advisor

Before hiring a financial advisor in Salina, here are a few quick tips to help you find the best advisor for you.

1. Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2. Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3. Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4. Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.


Frequently Asked Questions & Additional Resources

How do I know if I’m ready to hire a financial advisor?

You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.

But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.

Before I hire a new financial advisor, should I fire my current advisor?

You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.

Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?

After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. 

Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.

I’m a local financial advisor interested in being featured in this guide. How do I get started?

Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.

How Much Does a Financial Advisor Cost?

➡️ How Much Does a Financial Advisor Cost? Read the Article

About the Author
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian