



What this article covers
Opher Ganel, a consultant who supports NASA technology and flight projects, applies NASA’s risk-management mantra (“test as you fly, fly as you test”) to retirement planning. Financial advisors Kevin Lao and Richard Archer explain the stress tests a retirement plan should survive, including bear markets, prolonged low returns, longevity and long-term care costs, how the pros run them, and what adjustments to consider if your plan comes up short.
Key Takeaways
Stress test your retirement plan the way NASA tests spacecraft: identify risks, assess them, mitigate, repeat
NASA identifies risks, assesses their likelihood and consequences, mitigates what it can, then monitors and reassesses until launch. Opher Ganel argues the same discipline, especially rigorous testing under realistic conditions, is the best way to find weaknesses in a retirement plan before they become problems.
Four core stress tests: bear markets, prolonged low returns, longevity and long-term care
Kevin Lao, CFP®, recommends testing how your plan holds up through another 2007 to 2009 style bear market, years of lower returns, outliving your life expectancy and a long-term care need. Other tests worth running include tax-law changes, high inflation and Social Security changes such as benefit cuts or a later full retirement age.
Advisors use Monte Carlo and historical-return tests, then adjust plans that fall short
Monte Carlo analysis runs a thousand or more randomly generated return sequences, and a plan is commonly called a success at a 90% or higher likelihood of not running out of money. If a plan fails, advisors may suggest Roth IRAs, no-load annuities, long-term care insurance, spending less, saving more or working longer.
 Richard Archer
Take a play out of NASA’s playbook: Stress test your investment portfolio, identify risks, and learn if your retirement plan needs adjustment.
My day “job” as a consultant is supporting NASA technology-development efforts. From time to time, I also support NASA flight projects.
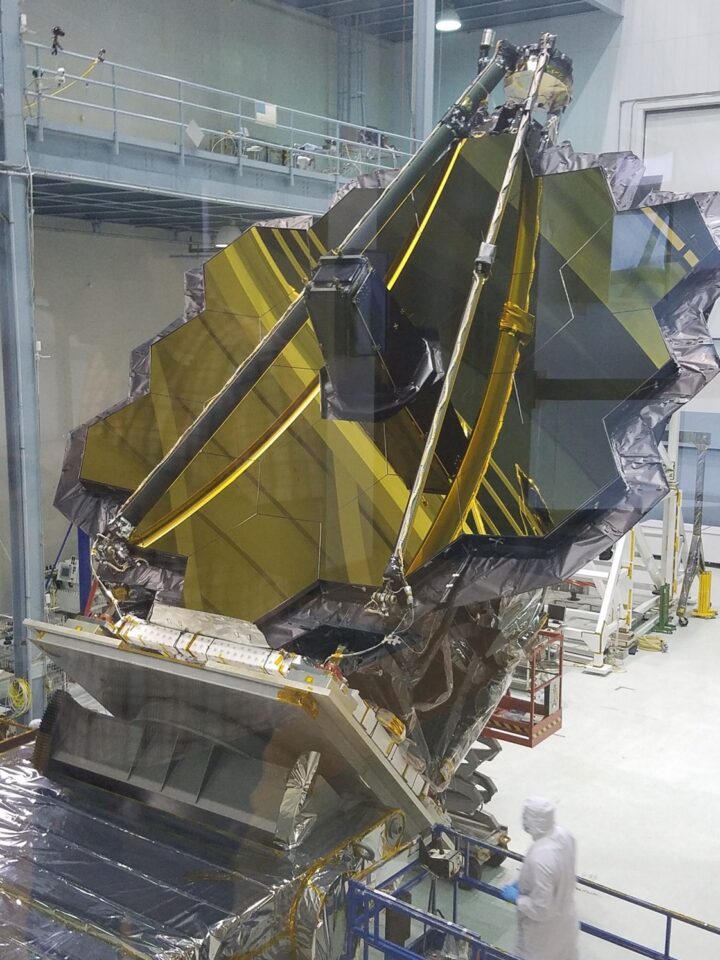
If there’s one thing NASA excels at, it’s developing complex missions and making sure they succeed. Look no further than the recently launched James Webb Space Telescope (JWST) near-perfect launch and commissioning (and no, I had no involvement with Webb other than taking the below picture from a balcony overlooking it – but it’s a cool photo!).
How Does NASA Manage Mission Risk? A Four-Step Process
The first step in risk management and mitigation is to identify the risks you face.
Step two is to assess the likelihood and level of consequences should the risk turn into an actual problem.
Step three is to figure out what you can do about it. This could be to implement mitigation strategies (for example, if the risk is that a critical part may not be available when you need it, you can order it early and/or identify alternative parts and/or develop an alternative design that doesn’t require it).
If you can’t mitigate, you can keep an eye on the risk and see if its likelihood increases or decreases as time progresses. Finally, if the consequence isn’t too dire, you could decide to accept the risk.
Step four is to reassess the likelihood and level of consequence once you’ve mitigated risks you can mitigate.
After that, you just keep an eye on existing risks, retire them when they’re no longer a concern, and add new ones as they come up. Then rinse and repeat until launch.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
What Can NASA’s “Test as You Fly” Approach Teach You About Retirement Planning?
There’s one thing all NASA missions do as a matter of practice to mitigate risk of equipment failures.
Testing.
Project teams test components, subsystems, systems, and entire payloads, stressing them in every way imaginable to make sure that if they’re going to break, they do so early enough that the broken items can be fixed or replaced.
This includes testing them in a vacuum, extreme cold, and heat, vibration, acoustic shock, radiation, etc.
The mantra is, “Test as you fly, fly as you test!”
To the extent humanly possible, you test things as close to how you plan to launch and operate them on orbit and then fly a payload that’s as close as humanly possible to the configuration you tested.
If you want to be as close as humanly possible to certain your retirement plan will work as intended, take a play out of NASA’s playbook – stress testing to see how well your plan addresses retirement-plan risks.
Richard Archer, CDAA, CFA, CFP, MBA, Owner and President, Archer Investment Management, emphasizes:
Stress testing any plan is key to avoiding unexpected failures when something inevitably goes wrong. Once you’re deep into retirement, catching up is challenging if you sustain an economic surprise that threatens your livelihood.
Which Stress Tests Should Your Retirement Plan Pass?
To help ensure your retirement plan succeeds, Kevin Lao, CFP®, Founder and Director of Financial Strategies, Imagine Financial Security, LLC, recommends four stress tests to help you sleep better at night.
- “Bear market risk: How does your retirement goal hold up if you lived through another major recession or bear market, like 2007-2009?”
- “Prolonged low returns: We have been spoiled since 2009 with the longest bull market on record. This could mean a prolonged period of lower growth and lower returns…does your plan succeed or fail?”
- “Longevity risk: What if you or your spouse lives well past your life expectancy? Does the plan succeed or fail?”
- “Long-term care risk: What if you or your spouse had a Long-term care need? How would that impact your financial plan?”
Other tests you could consider include changes to tax laws, high inflation (very timely these days!), Social Security changes (e.g., benefit cuts, means-testing benefits, and/or delayed full-retirement age), etc. Richard Archer adds:
Immediate market drops, longevity, and healthcare.
How Do Financial Advisors Stress-Test a Retirement Plan?
For the first two risks above, bear market(s) and/or prolonged low market returns, the pros run a so-called Monte Carlo test. This procedure, named after a European city that hosts famous gambling casinos, runs a thousand or more randomly generated (plausible but allowed to be far worse than any real historical case) returns for each asset class. Another method is to test your portfolio’s ability to survive actual past market returns for all asset classes you may invest in.
For both procedures, they assess the likelihood that your plan will succeed (i.e., that you won’t run out of money while you’re still alive). Standard practice is to call it a success if there’s at least a 90-percent likelihood you won’t outlive your money.
However, that’s just the beginning.
I asked the pros how they carry out the other stress tests.
Archer replied:
We have sophisticated software that incorporates clients’ entire financial lives into our models and see if their retirements are robust. For each test, we model the impact of up to a 100% increase on clients’ retirement plans. We then review their probability of success vs. running out of money during retirement.
What Can You Do If Your Retirement Plan Fails a Stress Test?
If you have so much money set aside that you’d be fine short of a global financial meltdown, you may not need these pros. If you’re like most of us and have a little (lot) less than that, you probably need at least some help running stress tests since pros have tools you’re not likely to have. Plus, your plan may very well be challenged by some of these tests.
If that happens, Archer would discuss options with you, “We discuss the benefits of Roth IRAs to defend against tax increases, buying no-load annuities, spending less in case Social Security fails, maintaining some equity risk and hard assets like real estate to help protect against inflation, etc.
The pros may also recommend other possible adjustments:
- Buying a so-called Long-Term-Care insurance (LTC) policy
- Increasing income so you can save more
- Reducing expenses so you can save more (and likely need less in retirement)
- Considering a reverse mortgage
- Considering working longer, at least part-time
The Bottom Line: Plan for the Best, Prepare for the Worst
Stress-testing your retirement plan is a crucial step to reduce the risk that life will blindside you and take you down. That means looking at all sorts of really bad possible situations and seeing how they’d impact your retirement plan. Given how difficult it is to amass a large fortune, it may seem like this is an exercise in futility – that there’s no way to fully protect yourself from all these risks.
And you know what? That’s true. You can’t be 100 percent sure to do well under all possible scenarios.
All we can do is the best we can do. Then, we have to trust that if and when something bad happens, we’ll find a way to adapt and overcome. It’s just better to address as many risks as far ahead of time as possible.
And lest all the above makes it sound like you’re doomed, Archer reassures:
These days, it’s easy to predict continued economic doom and gloom. However, historically that’s not been the reality. We always recommend planning for the best and preparing for the worst. We’ll make adjustments together as life throws us curveballs along the way.

Frequently Asked Questions
What does it mean to stress test a retirement plan?
Stress testing means looking at really bad possible situations, such as a major bear market or a long life, and seeing how they would affect your retirement plan. The goal is to find weaknesses early enough to fix them, much as NASA tests spacecraft components under extreme conditions before launch.
What stress tests should a retirement plan pass?
One advisor interviewed recommends four: a major recession or bear market like 2007 to 2009, a prolonged period of low returns, you or your spouse living well past life expectancy, and a long-term care need. The article also suggests testing for tax-law changes, high inflation and Social Security changes.
How does a Monte Carlo simulation test a retirement plan?
A Monte Carlo test runs a thousand or more randomly generated, plausible return scenarios for each asset class, including some far worse than any historical case. It estimates the likelihood that you won’t run out of money while you are still alive, and the article notes a plan is commonly considered successful at a 90% or higher likelihood.
What can you do if your retirement plan fails a stress test?
Options discussed include Roth IRAs to hedge against tax increases, no-load annuities, spending less in case Social Security falls short, and keeping some equity and hard assets like real estate to help protect against inflation. Other adjustments include long-term care insurance, increasing income or reducing expenses to save more, and working longer, at least part-time.
Do I need a financial advisor to stress test my retirement plan?
If you have enough money to be fine short of a global financial meltdown, you may not. Most people, the article notes, will probably need at least some help, since advisors have planning software and tools individuals are unlikely to have, and a plan may well be challenged by some of these tests.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.