



What this article covers
Opher Ganel argues that the best-known emergency fund rules, from Dave Ramsey’s $1,000 to Suze Orman’s 8 to 12 months of income, are either far too small for a real financial emergency or oversized for most people. Instead, he lays out a two-step formula: choose a number of months based on your personal risk factors, then multiply it by only the critical expenses you would still have to pay if your income stopped.
Key Takeaways
Size your emergency fund to your personal risk factors, not a one-size-fits-all rule
Opher Ganel suggests starting at 3 to 6 months if you are low risk on all three factors: financial responsibilities you can’t quickly downsize, income stability and family support. Add 3 months for each factor where you are on the riskier side, so a single person would aim for 6 to 9 months, and a single, self-employed person with little room to cut spending for 12 to 15 months.
Your emergency fund needs to replace critical expenses, not your full income
Housing, utilities, phone, groceries, insurance premiums, medical costs, property taxes, auto costs and debt payments belong in the monthly number. Income taxes, savings and discretionary spending do not, because they fall away or can be cut close to zero when your paycheck stops.
Build a large emergency fund gradually, starting with as little as 1% to 3% of each paycheck
A target that looks out of reach is fine as long as you start. Raise your savings rate a little each year, send at least half of every raise, bonus or cash gift to the fund, and once you reach your target, redirect those contributions to goals like retirement instead of increasing your spending.
Chances are, you know you need to create an emergency fund to help you survive financial emergencies. However, if you research how big or small this fund needs to be, you will find contradictory advice, much of which is flat out wrong or at least incomplete.
The following is how I figure out how much I need to set aside, which should help you figure out your “perfect fit” emergency fund size.
Why Popular Emergency Fund Advice From Financial Gurus Falls Short
Dave Ramsey suggests your emergency fund be $1000. If your kid suddenly needs a cavity filled, your car’s alternator goes out, or something of similar magnitude happens, $1000 should be fine.
However, that’s not a real financial emergency. It’s just life happening.
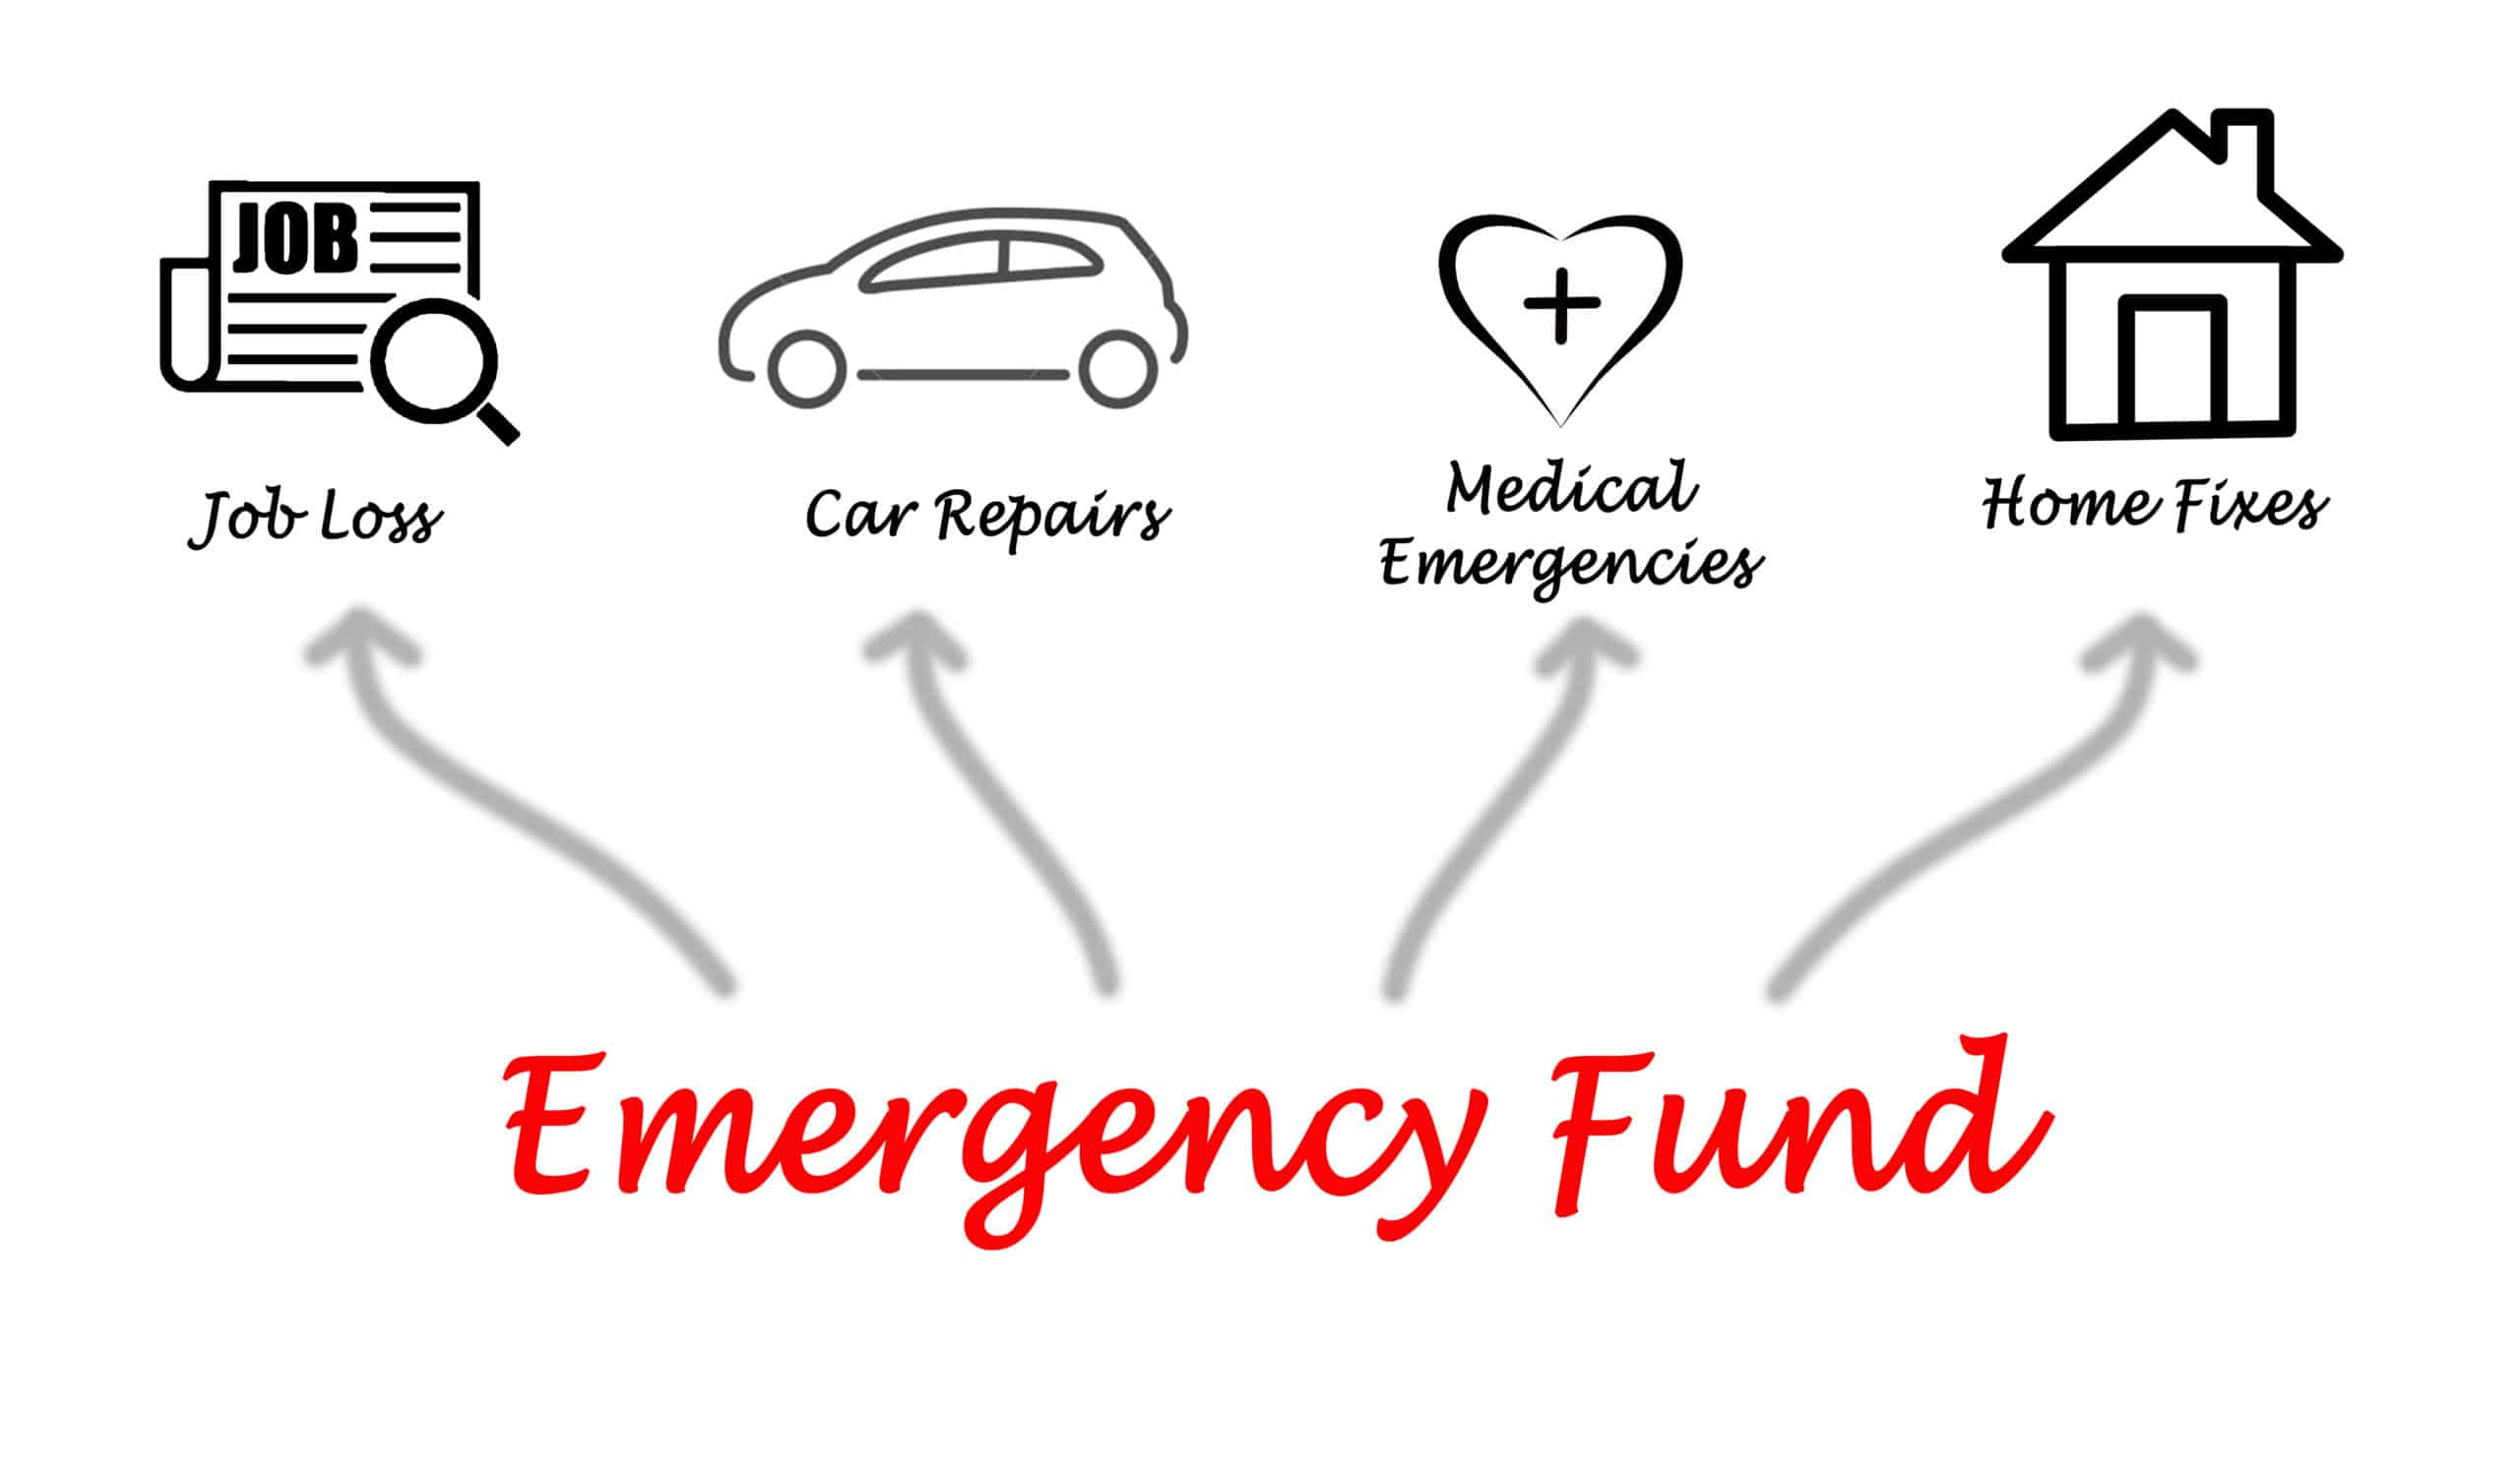
A true financial emergency is if, heaven forbid, you become temporarily disabled due to an accident or severe illness, or you lose your job. In such a situation, $1000 is not even remotely enough to tide you over. If $1000 is all you have saved up, you’ll run out of cash and out of options before the week is out! If you’re really frugal, you may stretch that out to a month.
Then what?
Suze Orman, another well-known ‘financial guru‘, on the other hand, says you need to set aside 8–12 months of your income. While in some cases that’s true, it’s sort of like pulling an XXXL shirt off a store rack and saying that it will be large enough for you. Sure, that shirt will be a perfect fit for some, but it will be grossly over-sized for most.
Orman is right to state things in the number of months, but misses the mark in two important ways. First, by saying that 8–12 months is the right number for everyone, and second by using your income as the measure of what you’ll need to replace.
To get the real number that’s right for you, let’s figure out how many months you need to worry about, and what number of dollars you need to account for in each of those months.
How Many Months of Expenses Should Your Emergency Fund Cover?
As I’m sure you can intuitively understand, if you’re a single parent to several small children, have no family support, and your income isn’t stable, you have a far greater risk of a financial emergency devastating you than if you’re married, have no kids, both you and your spouse have solid jobs with stable employers that pay good salaries, and if push came to shove, your family will help you out.
That’s why nobody should give a set number of months, whether it’s 3, 6, 8, or 12 months, or even a set range like 3–6 or 8–12 months.
We have to accept that any number of months short of the likely remainder of your life will not provide a 100% guarantee that your emergency fund will not run out under any plausible circumstances. If you can create such a giant emergency fund, you can probably already retire, and don’t need my advice (in fact, maybe I could use yours ).
The problem is that almost none of us can create that size fund anytime soon. That’s why you should look at your personal circumstances and decide on a range of months that makes sense given the following factors:
- Do you have to take care of others (young children, elderly parents, etc.) or have other financial responsibilities, or could you significantly downsize in a hurry if you’re hit by an emergency?
- Is your income stable and predictable?
- Do you have a spouse, significant other, or other family or friends who can and would help in an emergency?
If you’re on the low end of the risk spectrum for each of the above factors: i.e. you’re married, both of you have stable incomes, you have strong family support, and don’t have a problem swiftly and significantly cutting expenses, you can probably make do with a 3–6 month emergency fund. For each factor where you’re on the riskier side, add 3 months to your personal number.
For example, if all the above is true for you except that you’re single, 6–9 months would be better for you. If you don’t have too many financial responsibilities that can’t be swiftly downsized, but you’re single and self-employed, 9–12 months would be your better bet. If you’re single, self-employed, and have little flexibility in downsizing, shoot for 12–15 months.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
Which Monthly Expenses Should Your Emergency Fund Cover?
The second critical question is what determines how many dollars you need to set aside for each of these months?
Certainly, if you can replace every dollar you earn, that’s best. However, that may be a much tougher target than you can hit, and importantly, it’s more than you need.
Your real need is to replace only enough income to cover your critical spending. That includes the following:
- Rent or mortgage
- Utilities
- Broadband Internet service (if you’re on a contract and/or you need it to bring in new income)
- Phone
- Groceries and supplies
- Insurance premiums (including homeowner/renter’s, auto, health and dental)
- Medical expenses
- Property taxes (if any)
- Auto expenses (gas, maintenance and repairs, parking, tolls, loan payments if any, etc.)
- Debt payments other than auto and mortgage
- Other expenses you can’t reasonably do away with
You’ll immediately notice that I didn’t include in these three major categories: income taxes, savings, and discretionary expenses. This is because if your income goes away, you don’t have to pay income taxes. You also don’t have any way to set aside money for savings if nothing is coming in. Finally, where you can trim the most — discretionary expenses, you should plan on cutting as close to zero as possible, at least until you’re back on your financial feet.
How to Calculate Your “Perfect Fit” Emergency Fund Target
Now that you’ve calculated how many months you need to worry about, and how many dollars you’ll need to cover per month in an emergency, multiply the two numbers and that’s your “perfect fit” emergency fund size in dollars.
The number you come up with may seem undoable.
That’s ok. You don’t have to get there tomorrow, or even next year. Just get started.
How big should your emergency fund be?
Size it to the bills you would still have to pay if your paycheck stopped, not to your full income. Income taxes, retirement savings and most discretionary spending drop away in an emergency.
How to Build Your Emergency Fund a Little at a Time
Set aside some money from each paycheck, even if it’s only 3%. If you can’t do 3%, start with 1%. Anything can and will help. Then try to increase that rate each year by at least a little bit.
In addition, each time your income increases, whether it’s from an annual bonus, a holiday tip, a big cash gift, or a raise, divert at least half to your emergency fund.
What to Do Once Your Emergency Fund Is Fully Funded
Once you reach your emergency fund target, don’t increase your spending.
Instead, use the money you would have sent to your emergency fund to turbocharge your other savings for goals such as retirement, down-payment for a house, replacing your junker car, college for your kids, paying down credit-card debt, etc.
By doing all this, you help your future self by (a) increasing the resources you have available to you, and (b) preventing your financial obligations from ballooning over time, a.k.a. lifestyle inflation.
Frequently Asked Questions
How much should I have in my emergency fund?
Multiply two numbers: how many months of protection your situation calls for, and how much you need each month to cover critical expenses. The article argues against any fixed number of months for everyone, because risk depends on dependents, income stability and whether family could help in a crisis.
Is $1,000 enough for an emergency fund?
A $1,000 fund can handle everyday surprises like a cavity filling or a failed car alternator. But it falls far short in a true financial emergency, such as a temporary disability or job loss, where it might last a week, or about a month if you’re very frugal.
How many months of expenses should an emergency fund cover?
If you’re low risk on every factor (married, two stable incomes, strong family support and easy-to-cut expenses), 3 to 6 months is probably enough. Add 3 months for each factor where you’re on the riskier side, which can push the target to 9 to 12 or even 12 to 15 months for single, self-employed people with little flexibility to downsize.
What expenses should an emergency fund cover?
Cover critical spending: rent or mortgage, utilities, phone, needed internet service, groceries and supplies, insurance premiums, medical expenses, property taxes, auto expenses, other debt payments and anything else you can’t reasonably do away with. Leave out income taxes, savings and discretionary spending, which you should plan to cut as close to zero as possible during an emergency.
How do I build an emergency fund if the target seems impossible?
Start small and keep going. Save a set share of each paycheck, even 1% to 3%, increase it a little each year, and put at least half of any raise, bonus, tip or cash gift toward the fund. You don’t need to get there tomorrow, or even next year.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.