



What this article covers
Opher Ganel models what the SECURE Act’s end of the stretch IRA means for a middle-class heir: a 45-year-old with a median Maryland household income who inherits a $1 million traditional IRA. Forcing the account to be drained within 10 years instead of over his 39-year life expectancy cuts his inflation-adjusted after-tax income by more than $2.5 million. He then lays out the limited moves available to heirs and the planning steps parents can take now.
Key Takeaways
The SECURE Act replaced the lifetime stretch IRA with a 10-year payout rule for most non-spouse heirs
Before the law, an adult child who inherited an IRA could take only Required Minimum Distributions over his own life expectancy, letting the balance keep growing tax-deferred. For owners who die after December 31, 2019, most non-spouse beneficiaries must empty the account within 10 years, and the article notes the same window applies to inherited Roth accounts.
Losing the stretch IRA can cost a middle-class heir more than $2.5 million over a lifetime
In Opher Ganel’s example, a 45-year-old inheriting $1 million would have received about $3.7 million in inflation-adjusted after-tax income by stretching RMDs over 39 years. Draining the account within 10 years produced only $1.06 million (equal annual draws) to $1.18 million (one lump sum in year 10), a loss of $2.53 million to $2.65 million.
Parents have more ways to soften the SECURE Act than heirs do
Heirs can mainly offset the higher taxable income by maxing out IRAs, 401(k)s, HSAs and, for pass-through business owners, the 20% Qualified Business Income Deduction. Parents can work with a financial planner on Roth conversions, which mean paying tax now so heirs inherit tax-free, and on which beneficiaries the 10-year rule doesn’t apply to, such as a surviving spouse or anyone within 10 years of the owner’s age.
As lawmakers like to do, they tucked into a must-pass bill some last-minute changes to the tax code.
These specific changes will hurt retirement planning even for the middle class.
The so-called “Secure Act” was inserted into a $1.4 trillion spending bill that had to pass to avoid another government shutdown. President Trump signed the bill into law on December 20.
Here’s how the new law is supposed to help you, how it actually hurts you, and what you can do to minimize the damage.
How Was the SECURE Act Supposed to Help Retirement Savers?
The new law makes it easier for small-business owners to provide retirement benefits to part-time employees. It also includes a way for several small businesses to set up a joint retirement plan for their employees, splitting costs between the different businesses.
However, many workers who can already contribute to a 401(k) plan don’t do so, even when employers offer matching contributions. So why would anyone expect this new package to make much of a difference? Especially for part-time employees who likely make too little to be able to set aside much for retirement.
What Was the Stretch IRA, and Why Did It Help the Middle Class Too?
One of the best ways for parents to leave bequests to their children is by leaving unused balances in retirement plans. A child inheriting parents’ retirement plans could maximize lifetime income from these by withdrawing only the Required Minimum Distributions (RMDs). The RMD is intended to limit how long he can put off paying taxes on those balances. However, according to pre-Secure-Act law, a non-spouse beneficiary (e.g., an adult child) could stretch out the draw-down over his lifetime.
Example: A $1 Million Inherited IRA Under the Old Stretch Rules
To see how this works, let’s start with some assumptions:
- A parent dies at age 75, leaving behind $1 million in a traditional IRA.
- The beneficiary is his 45-year-old son whose household income is the median income for MD, and who deducts the standard deduction on his married-filing-jointly tax returns.
- The portfolio earns 9.965% annually (according to data from Yale’s Case and Shiller, this is the annualized return of US stocks from 1926 to 2019).
- Tax brackets for federal, Maryland state, and local income taxes keep up exactly with inflation.
- All amounts adjusted for 2.88% annual inflation (from Case and Shiller data for the above period).
Using data from a Charles Schwab RMD calculator, here’s the inflation-adjusted RMD over the beneficiary’s 39-year life expectancy.

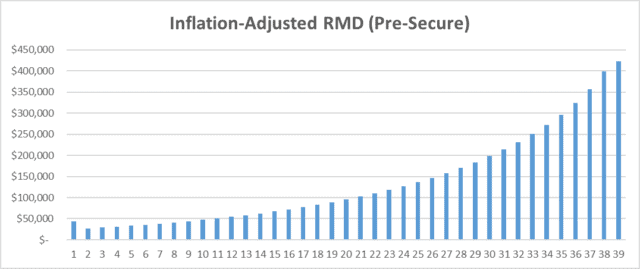
Inflation-adjusted RMD from a hypothetical $1 million IRA inherited by a 45-year-old man from a parent, based on a 9.965%. Data from Charles Schwab RMD calculator.
I started from the $81,868 median household income for Maryland per the Census Bureau. Next, I added each year’s inflation-adjusted RMD. Then, I estimated the excess federal, state, and local income taxes for the RMD amounts each year. Reducing the RMD by these taxes, we find inflation-adjusted after-tax amounts left for the beneficiary as shown below. The total over 39 years is $3.7 million after taxes.

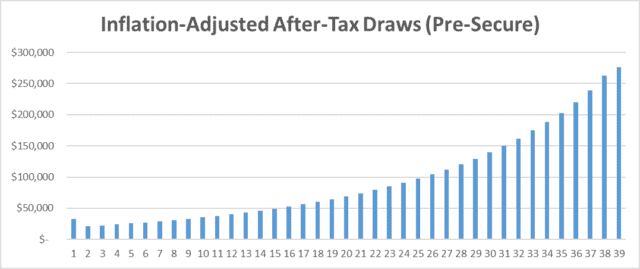
Inflation-adjusted after-tax income from the above RMDs.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
How the SECURE Act’s 10-Year Rule Can Cost an Heir Over $2.5 Million
To help fund the expected costs of the Secure Act, legislators prevented the above “stretch IRA” technique if the parent dies after Dec 31, 2019. Instead, they allow only a 10-year window to draw down the inherited IRA in full. A penalty of 50% is assessed on any amounts left in the IRA after that. The new law does let the beneficiary decide how much to draw each year. The only requirement is that the account be empty after 10 years. Interestingly, the same window and penalty apply to Roth accounts even though contributions to those were made after tax.
To see the impact of the new rules, I redid the above calculations for the same assumptions but drawing down the account within 10 years. I did this both with equal annual draws of $149,338 (inflation adjusted), or drawing nothing for the first 9 years and draining the account in the 10th year by drawing $2,084,471 (inflation-adjusted).
The first strategy results in an extra inflation-adjusted net income of $1.06 million. The second strategy does somewhat better at $1.18 million. Compared to the $3.7 million net inflation-adjusted income of the stretch IRA technique, under the Secure Act you lose $2.65 million if you draw down the account in equal annual amounts, and $2.53 million if you hold off to the last minute!
The Congressional Budget Office estimated in April that this change would bring in an extra $16 billion in new federal income taxes over the next decade.
Guess who’ll pay those extra billions…
What Can Heirs and Parents Do to Reduce the SECURE Act’s Impact?
If you’re the beneficiary in the above scenario, there isn’t much you can do to reduce the impact beyond maximizing whatever tax-deferral options are available to you. These include:
- Maxing out contributions to your own IRAs, 401(k) plans and other employer retirement plan, as well as those of your spouse.
- Maxing out contributions to a Health Savings Account (HSA), assuming your health insurance plan is HSA-compatible.
- If you own a small pass-through business, making sure to take full advantage of the 20% Qualified Business Income Deduction (QBID).
If you’re the parent in our scenario, you should consult with your financial planner to maximize your beneficiaries’ after-tax inheritance.
Some things to consider include:
- The above changes don’t apply to your surviving spouse, minor children, disabled or chronically ill beneficiaries, or anyone within 10 years of your own age.
- Converting your traditional IRAs to Roth IRAs may result in a higher after-tax bequest. This would require you to pay more taxes before you die, but no taxes would be due on the amounts you leave to your beneficiaries. However, as mentioned above, they’d still need to drain those accounts within 10 years of your death.
You Might Also Enjoy:
The Bottom Line: Plan Ahead If You’ll Leave or Inherit a Large IRA
The new Secure Act that was supposed to help you will more than likely hurt you if you’re expecting to inherit a substantial IRA, even if your income isn’t much above the median.
There are a few moves you can make as the parent who plans to leave IRAs to your beneficiaries when you die. There are also (fewer) things you can do if you’re the beneficiary.
Frequently Asked Questions
What was the stretch IRA?
The stretch IRA let a non-spouse beneficiary, such as an adult child, withdraw only the Required Minimum Distributions from an inherited IRA, spreading withdrawals over his own life expectancy. That kept most of the balance growing tax-deferred for decades and maximized lifetime income from the inheritance.
How did the SECURE Act change inherited IRA rules?
For account owners who die after December 31, 2019, the SECURE Act replaced the lifetime stretch with a 10-year window for most non-spouse beneficiaries to empty the inherited account. The article explains that the same window applies to Roth accounts, even though contributions to those were made after tax.
How much can the SECURE Act cost someone who inherits an IRA?
In the article’s example, a 45-year-old with a median Maryland household income who inherits a $1 million traditional IRA would have received about $3.7 million in inflation-adjusted after-tax income under the stretch rules. Under the 10-year rule, he receives $1.06 million to $1.18 million depending on how he times withdrawals, a loss of more than $2.5 million.
Who is exempt from the SECURE Act’s 10-year rule?
According to the article, the 10-year rule doesn’t apply to a surviving spouse, minor children, disabled or chronically ill beneficiaries, or anyone within 10 years of the account owner’s age. These beneficiaries can still use longer payout periods.
What can I do to reduce the tax hit on an inherited IRA?
Opher Ganel suggests that heirs maximize their other tax-deferral options: contributing the maximum to their own and their spouse’s IRAs and 401(k)s, maxing out an HSA if their health plan qualifies, and taking full advantage of the 20% Qualified Business Income Deduction if they own a pass-through business. Parents can consult a financial planner about strategies such as converting traditional IRAs to Roth IRAs.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.