



What this article covers
Opher Ganel explains why high inflation, which quietly erodes cash savings, can work in your favor if you owe money. Using a small car-style loan and a $500,000 30-year mortgage, he shows that inflation barely dents short-term debt but can cut the real cost of a long-term fixed-rate mortgage by about a third. He closes with 4 factors (income, assets, tax bracket and debt) that decide whether inflation is your enemy or your friend.
Key Takeaways
Inflation shrinks the real cost of long-term fixed-rate debt
Because each dollar you owe loses value as prices rise, inflation reduces what your future loan payments are really worth. In Opher Ganel’s example, a $500,000 30-year mortgage at 3% has about $759,000 in total payments, but in inflation-adjusted terms costs about $501,250, saving nearly $258,000 (about $716 a month, over a third of each payment).
Inflation barely helps on small, short-term loans
On a $5,000 loan at 3% over 3 years, the inflation-adjusted total is about $5,013 versus $5,235 in nominal payments. That wipes out almost all of the $235 in interest, but it works out to only about $6 a month, so the benefit is small in absolute terms.
Whether high inflation helps or hurts you depends on 4 factors
Inflation is friendlier if your income keeps up (for example through cost-of-living adjustments), your assets earn more than inflation, your tax bracket is modest and you carry a large, long-term, low fixed-rate mortgage. It is a major problem if you hold big balances in checking, savings or low-coupon bonds, your income is stagnant and you have no fixed-interest debt.
The year was 1955.
My parents were buying their ever first home.
My then-28-year-old mom pushed my then 31-year-old dad into taking on far more debt than he was comfortable with – their mortgage payments ate up half their income!
To say things were tight would be an understatement. My oldest sister tells stories of growing up with the bare necessities only, and sometimes not much of those.
By the time they made their last payment, however, inflation made it equivalent to the cost of a family meal at a neighborhood restaurant.
This story taught me important lessons about inflation and mortgages.
What Happens to Your Savings and Debts When Inflation Soars?
Inflation is what economists call it when prices go up.
There are many inflation measures, such as the well-known Consumer Price Index (CPI), the “chained” CPI, the Producer Price Index (PPI), etc., all of which measure how different prices change over time.
When inflation is high, as it has been in the past year plus, prices increase more rapidly.
If you have money in a bank account earning 0.1% interest and inflation runs 6%, that bank balance lost ~5.9% of its purchasing power. That’s why I suggest you consider if you should maintain large balances in such low-risk, low-return assets, even for an emergency fund.
On the flip side, if you owe money, the value of each dollar you owe also drops.
How Does Inflation Affect Debt? Why Borrowers Can Come Out Ahead
Short-Term Loans: Why Inflation Makes Little Difference
For loans you need to pay off in a handful of years, especially when the balance isn’t very high, the impact of inflation doesn’t usually make a big difference.
For example, if you borrow $5,000 at 3% annual interest for 3 years, your monthly payment is about $145, for a total payment of $5,235. If there’s no inflation, this costs you $235 in total interest over 3 years. If inflation runs at 0.5%/month (~6%/year), the purchasing power of your payments reduces over the 3 years from $145 to $133.
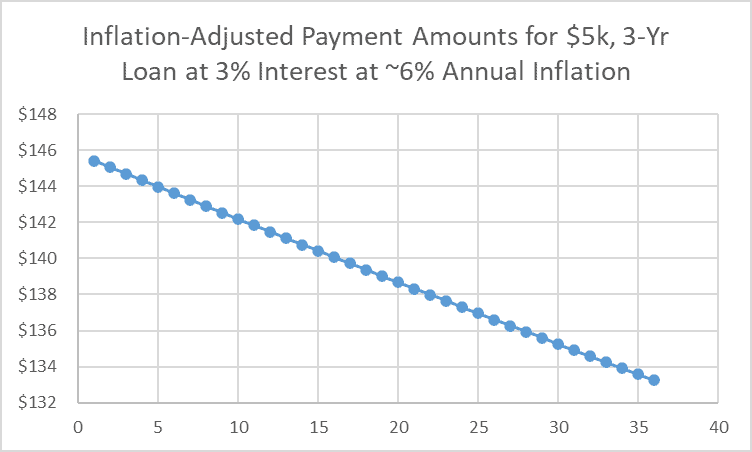
The total paid over the life of the loan, adjusting for inflation, is $5,013. This is good for you as the debtor since it saves you almost all the interest costs. However, in absolute terms, it saves you an average of only $6/month.
Nothing to write home about, right?
Long-Term Mortgages: Why Inflation Makes a Huge Difference
However, say you borrow $500,000 on a 30-year mortgage at 3%, having the value of your owed balance drop by 6% a year makes a huge difference.
Here, your monthly payment is $2,108. Over 30 years, the inflation-adjusted cost of those payments drops from $2108 to only $860! Instead of feeling the full impact of nearly $759k in total payments, adjusting for inflation, it costs you only $501,250!
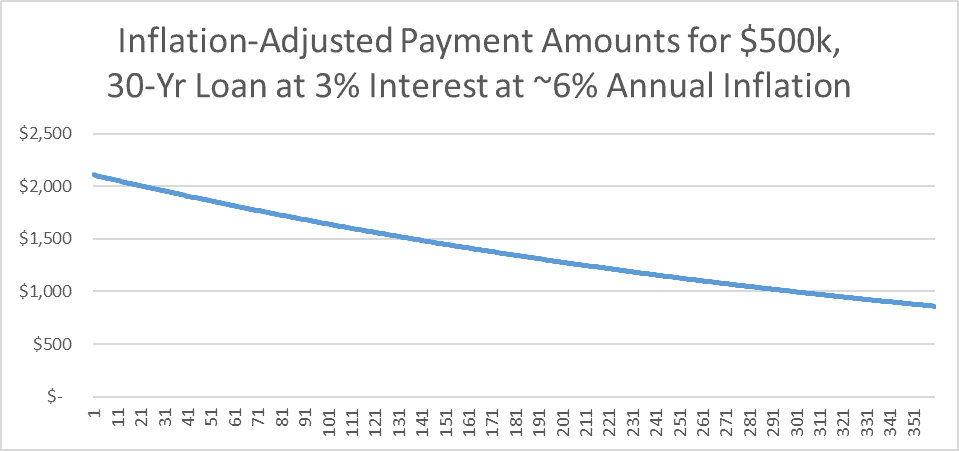
That saves you nearly $258k, or $716/month on average – over a third of your monthly payments!
Enough to make you smile?
Does High Inflation Help or Hurt You? 4 Factors That Decide
There are 4 factors that affect whether high inflation is your enemy or friend:
Does your income keep up with inflation, e.g., through cost-of-living adjustments (COLA)?
- If your income doesn’t keep up, inflation makes it harder to cover your expenses – Enemy!
- If your income goes up enough to keep up (or better yet, exceed) inflation – Friendly!
Do your assets keep up with inflation?
- If you keep a lot of your assets in checking or savings accounts that pay less interest than inflation, your real (inflation-adjusted) net worth is dropping – Enemy!
- If most of your assets have higher (preferably much higher) returns than inflation, especially if pumped up by inflation – Friendly!
Are you in a high tax bracket (federal + state + local)?
- If you’re in a high tax bracket, you pay taxes on “phantom gains” when inflation sucks out much or all of your gains, yet you’re taxed on nominal gains – Enemy!
- If your tax bracket isn’t very high, this is less of a concern – Neither.
Do you have large, long-term, fixed-interest-rate debts?
- If you have a large mortgage with many years until it’s paid off, at interest rates lower than inflation – Best Friend!
- If you have any short-term debt at any interest rate – Friendly!
- If you have no debts on which you pay interest – Neither.
The Bottom Line: Is High Inflation Your Enemy or Your Friend?
The overall impact you suffer or enjoy when inflation soars depends on where you fall on each of the above 4 factors, and how significant each is relative to your financial situation.
For example, if you have few assets but those earn high returns, have a low-interest mortgage, and your income goes up faster than inflation, you should be smiling.
If, on the other hand, you hold significant sums in checking and savings accounts, low-coupon bonds, etc., your income is stagnant in nominal dollars with no COLA, and you don’t have any fixed-interest debt, high inflation is a major problem for you.


Frequently Asked Questions
Does inflation help people who have debt?
It can. When prices rise, the value of each dollar you owe drops, so the real cost of your future payments shrinks. The effect is largest on big, long-term, fixed-rate debts such as a 30-year mortgage at an interest rate below inflation.
How does inflation affect a fixed-rate mortgage?
Your payment stays the same while inflation reduces its purchasing power each year. In the article’s example, a $500,000 30-year mortgage at 3% has a $2,108 monthly payment whose inflation-adjusted value falls to about $860 by the end, saving nearly $258,000 in real terms over the life of the loan.
Is it worth keeping cash in a bank account when inflation is high?
Large balances in low-interest accounts lose purchasing power when inflation outpaces the interest rate. For example, money earning 0.1% while inflation runs 6% loses about 5.9% of its purchasing power in a year, which is why the author suggests reconsidering large low-return balances, even for an emergency fund.
Who is hurt most by high inflation?
People whose income does not keep up with inflation, who hold significant sums in checking, savings accounts or low-coupon bonds, and who have no fixed-interest debt. Those in high tax brackets are also hurt because they pay tax on nominal gains even when inflation erases much of the real gain.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.