



What this article covers
Opher Ganel explains why comparing your 401(k) to the average balance by age can lead you to the wrong conclusion. Using Vanguard’s How America Saves data, he shows that even the average balance for savers 65 and older supports only about $1,000 a month under the 4% rule, that retirement spending varies widely from person to person, and that a 401(k) is just one part of a retirement picture that also includes IRAs, taxable savings, Social Security, annuities and rental income.
Key Takeaways
Beating the average 401(k) balance for your age doesn’t mean you’re on track to retire
Vanguard’s How America Saves 2022 report put the 2021 median balance for participants 65 and older at $87,725 and the average at $279,997. Under the 4% rule, the median supports about $292 a month and the average roughly $1,000 a month, so even twice the average yields only about $2,000 a month.
Your retirement spending, not other people’s balances, determines how much you need
Housing costs, travel, dining and car choices make retirement budgets vary dramatically. Opher Ganel shows how someone with $1 million drawing $100,000 a year (10%) can be in worse shape than someone with $400,000 drawing $20,000 (4%), and Larson Patty of Rothman Investment Management notes that lifestyle expectations differ from person to person.
A 401(k) balance is only one asset in your complete retirement picture
IRAs, taxable portfolios, savings accounts, Social Security benefits, annuities and rental properties all shape how much income you’ll have. The article recommends building a complete financial plan and measuring your balances against what that plan says they should be, a view echoed by Kevin M. Arquette, CFP®, of Wealthpoint Financial Planning.
 Larson Patty
Admit it. You know we all love to read articles like these:
- This Is the Average 401(k) Balance. How Does Yours Compare? (The Fool)
- The Average 401(k) Balance by Age (BankRate)
- The Average 401(k) Balance by Age, Income Level, Gender, and Industry (Business Insider)
- The Average 401(k) Balance by Age (NerdWallet)
- The Average 401(k) Balance by Age — And 18 Ways to Catch Up (Quicken)
They speak to our intense desire to compare our accumulation to those of everyone else.
They speak to the hidden fear that we haven’t saved enough (or, for those who have done well, the hidden glee).
Understandable? Of course!
Human? Sure!
Helpful? Not so much and maybe even dangerous. Here’s why…
Problem 1: Even the Average 401(k) Balance Buys a Modest Retirement
In Vanguard’s 2022 annual How America Saves report, they provide (page 47, figure 55) a table showing 2021 average and median balances in Vanguard defined-contribution plans (e.g., 401(k) plans) by participant demographics, including age groups.
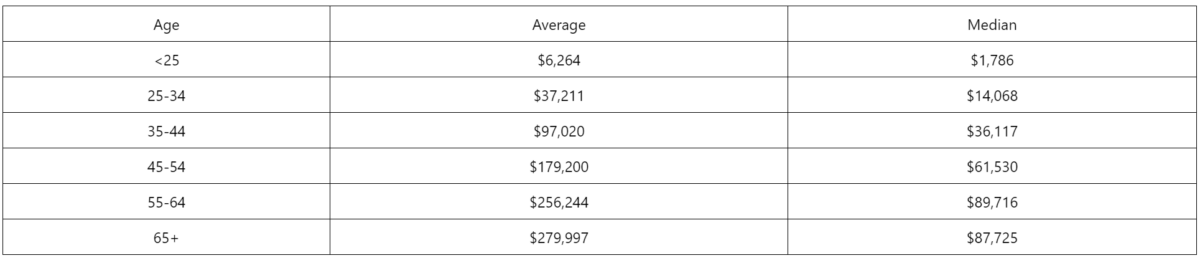
Comparing your 401(k) balance to the median, or even the average 401(k) balance of Americans risks making you feel great even if your balance may be far too low relative to what you’ll need.
For example, if you follow the 4% rule (which isn’t as good as other tools), the median balance for ages 65+, at $87,725, can provide a safe annual withdrawal of just over $3500!
That’s a measly $292 a month!
Even the average, skewed high to $279,997 by outlier 401(k) millionaires, can provide just $12,000 a year, or $1000 a month.
Say you’re in the 65+ age group and have twice as much as the average (over six times as much as the median) for your age group.
You might feel very pleased with yourself.
However, even with this high balance relative to others, you can expect just $24,000 a year or $2000 a month – hardly enough for a luxurious (or even comfortable) retirement.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
Problem 2: Retirement Spending Varies Hugely From Person to Person
Retirement needs and wants vary hugely between people.
As Larson Patty, Financial Planner at Rothman Investment Management says:
Your expenditures in retirement are unique to you – lifestyle expectations vary dramatically from person to person.
If your fixed costs are high, your retirement budget will likely be far higher than your friend whose fixed costs are more modest.
For example, if you retire in San Francisco and still have a mortgage, your housing costs will be dramatically higher than someone living in a small town in a state with less insane real estate prices.
If you love to travel, dine in fancy restaurants, and drive new luxury cars, your budget will similarly be far higher than that of someone who doesn’t care to leave his town, prefers eating at home, and drives a reliable but modest car.
As a result, comparing your 401(k) balance to those of others without also comparing spending levels can give you a very inaccurate picture of your relative situation.
You could have $1 million in your 401(k) but be in far worse financial shape than someone with $400,000 in her 401(k) if you need to draw $100,000 a year (10% of your balance) while she draws just $20,000 (4% of her balance).
Problem 3: Your 401(k) Is Only One Piece of Your Retirement Picture
Your 401(k) balance is just one piece of your retirement-planning puzzle.
More than likely you also have:
- IRA(s)
- Taxable portfolio
- Savings account(s)
If you’re in the older cohort who’ve started Required Minimum Distributions, your 401(k) balance may be dropping fast, with much of that drop going to your taxable portfolio and/or accounts.
Patty agrees:
Focusing on averages can be dangerous. Ultimately the balance of your 401(k) is just one asset in a complex basket of assets unique to you.
Beyond those, you’ll almost certainly receive Social Security retirement benefits that reduce the size nest egg you’ll need to fund your retirement.
You might even have an annuity or two.
If you planned well, you might have one or more rental properties that will keep money flowing in past your last day at work.
Certainly, all other things being equal, having more in your 401(k) is better than having less, but all other things are rarely equal.
The Bottom Line: Compare Your 401(k) to Your Plan, Not to Other People
Articles about 401(k) balances are like the magician who pulls your attention to his right hand while his left pulls a sleight-of-hand trick.
Entertaining, right?
But it pulls your attention away from where it needs to be if you want to see what’s really going on.
While it may be intriguing and even a little fun to compare your 401(k) balance to those of others, the above problems may cause you to draw very misleading conclusions.
If your balance is high relative to the median or even the average, you may mistakenly think you’re in good shape.
If your balance is relatively low, you might conclude you’re in terrible shape even if that’s more pessimistic than warranted.
The best advice is to craft a complete financial plan (with the help of a pro if needed) and look at your complete financial picture relative to your goals and priorities. Let others worry about the irrelevant comparison of their 401(k) balances to everyone else’s. You’ll look at the only relevant metric – your balances relative to what your plan says they should be. As Patty puts it:
Look holistically at your full financial picture. Make a financial plan to balance current consumption with your needs, wants, and wishes for the future.
Kevin M. Arquette, CFP®, Wealth Manager, Managing Partner, Wealthpoint Financial Planning agrees:
Comparing ourselves to others is a common habit, whether it’s about their larger house, their success at work, or their frequent vacations. However, this type of comparison isn’t helpful because it doesn’t consider our unique circumstances. To accurately assess our financial or life situation, we should focus on our personal goals and whether we’ve saved enough to achieve the lifestyle we desire. The financial planning process seeks to answer the question, ‘Am I on track to reach my goals?’ That’s done by analyzing your current financial status and comparing it with your desired financial future.
Find a Financial Advisor
Frequently Asked Questions
What is the average 401(k) balance for people 65 and older?
According to Vanguard’s How America Saves 2022 report cited in the article, the 2021 average balance in Vanguard defined-contribution plans for participants 65 and older was $279,997, and the median was $87,725. The average is skewed high by a relatively small number of 401(k) millionaires, so the median better reflects a typical saver.
Is the average 401(k) balance enough to retire on?
Generally not on its own. Using the 4% rule, the median balance for ages 65 and older supports a withdrawal of just over $3,500 a year (about $292 a month), and the average supports roughly $12,000 a year. The article notes that even twice the average provides only about $2,000 a month, hardly enough for a comfortable retirement.
Why is comparing my 401(k) to the average balance by age misleading?
A balance that looks high relative to others can still be far too low for what you’ll need, and a balance that looks low may be less worrying than it seems. Retirement spending varies widely, and your 401(k) is just one of several assets and income sources, so the comparison leaves out most of what matters.
What should I compare my 401(k) balance to instead?
Compare it to what your own financial plan says it should be. The article recommends building a complete financial plan, with professional help if needed, and looking at your full financial picture relative to your goals and priorities. One advisor interviewed says the planning process answers the question, ‘Am I on track to reach my goals?’
What else besides a 401(k) counts toward retirement readiness?
Most people also have IRAs, taxable investment accounts and savings accounts, and nearly all will receive Social Security retirement benefits that reduce the nest egg they need. Some also have annuities or rental properties that keep income flowing after they stop working.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.