



Do you work at Chevron?
Get expert insights from financial advisors who specialize in helping Chevron employees and executives make the most of their compensation package and benefits.
Looking for a financial advisor who specializes in working with Chevron employees? You’re in the right place. Below, you’ll find advisors who understand Chevron benefits and compensation — along with their answers to common financial questions from Chevron employees and executives.
Whether you recently joined Chevron or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and Chevron benefits can have a lasting impact on your financial future. For example:
✅ Do you know the right moves to get the greatest value from the Chevron benefits available to you?
✅ If you’re thinking about leaving Chevron for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?
Key Takeaways
After-Tax 401(k) Dollars at Chevron Can Become Roth Dollars When You Roll Over
If you contribute after-tax dollars to your Chevron 401(k), those amounts can be separated into a Roth IRA when you roll the plan into an outside IRA. Under current law, Roth IRA investment gains are exempt from federal taxation, making this one of the most tax-efficient moves available at retirement or a job change.
A Spending and Return Forecast Shows When You Can Retire from Chevron
A basic financial plan built from general information — age, income, spending, 401(k) balances, and target retirement date — can forecast whether your savings will last. The advisor below uses that analysis to start the conversation about when you can retire and how much you can spend.
Vet a Financial Advisor on Experience, Credentials, and Fiduciary Duty
Before hiring an advisor, ask how many investment cycles they have managed through, which credentials they hold (such as the CFA or CFP), whether they act as a fiduciary, and how fees are disclosed. Chevron employees with concentrated stock should also ask how the advisor manages concentrated equity holdings.
Why Chevron Employees Work with a Specialist Financial Advisor
Throughout the year, Chevron provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) with an after-tax savings option and, for many employees, a pension plan — along with, for eligible senior employees, deferred compensation and equity awards. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with Chevron who specialize in helping Chevron employees make the most of their income and benefits.
Chevron has moved its headquarters from San Ramon, California, to Houston, Texas, where many of its corporate functions are now based, and it continues to employ thousands of people in the San Francisco Bay Area. Its U.S. operations also include the Permian Basin in West Texas and New Mexico and refineries in Richmond and El Segundo, California, and Pascagoula, Mississippi. Whether you work at one of those sites, another office, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.
Sensitive topics — like the steps you should take before quitting your job at Chevron to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.
Should You Hire a Chevron Specialist or a Local Financial Advisor?
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Chevron employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with Chevron employees is the better fit for your unique needs.
💡 In the Q&A below, you’ll gain insights from financial advisors who work with Chevron employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.
🙋♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.
Q&A: Financial Planning Tips for Chevron Employees & Executives
In this section, you’ll learn how you can make the most of your Chevron employee benefits and gain valuable tips from financial advisors who specialize in working with Chevron employees and executives.
Financial Advisor Q&A · Chevron Employees
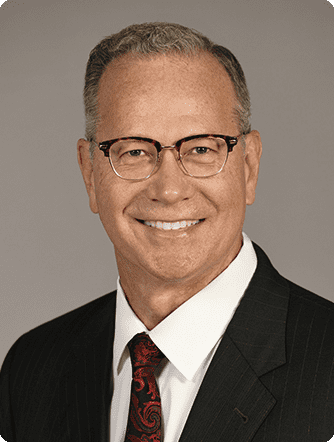
Rob Lloyd, CFA
Lloyds Intrepid Wealth Management · The Woodlands, TX · Serves clients nationwide
30+ yrs Investing Experience Helping People Plan Wisely To Protect Their FamilyRob Lloyd is a financial advisor based in The Woodlands, Texas, who specializes in offering financial planning services to Chevron employees. Rob helps his clients get the most value from their Chevron benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping Chevron employees save for their retirement, how do you help them make the most of their employee benefits?
We start by listening to you describe your current situation. You have had a unique career path and worked hard for your benefits package at Chevron. Our familiarity with the tax code, investment environment, and your situation allow us to suggest steps that will maximize your benefits as you approach a transition or retirement.
For example, did you know that if you contribute after-tax dollars to your 401k plan, those investments can be separated into a Roth IRA when you roll your Chevron 401k into an outside IRA? Roth IRA investment gains are exempt from Federal taxation under the current law making them one of the most tax-efficient types of investment account.
Strategies to maximize your employee benefits differ from person to person. While the 401k and health plan may be well understood, there are nuances to using these tools.
QWhen you first speak with a Chevron employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
The questions we ask at our first meeting are no different what you would hear at a barbeque: What is your role at Chevron? Where are you from initially? What are your hobbies? Tell me about your family.
If you are interested in what a financial planner does, we are happy to explain how we help people: by collecting information on your situation, we forecast your spending and portfolio returns over long periods of time. This analysis uses state-of-the-art techniques and best-practice portfolio construction.
We can build you a basic financial plan without collecting sensitive information like birthdays and account numbers. Of course, we need some general information such as your age, marital status, income levels, spending levels, 401k balances, and anticipated retirement dates. Pulling this information into one report starts a very interesting discussion about when you can retire from Chevron and how much you can spend.
QFor Chevron employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
Financial advisers seem completely unnecessary. After all, with index funds, discount brokers, and free internet news sites, investing and making money should be easy. For those who are financial professionals, this may be true, but even for the pros, investing is never easy.
Most of us use doctors when we are sick, auto mechanics when we have car trouble, lawyers when we have legal problems, or accountants when we have complex tax questions. Even though we recognize these professionals as subject experts, the financial professional is the one expert many try to live without. This can lead to expensive mistakes caused by lost opportunities or outright losses from bad investments.
In contrast, the wealthy almost always have an adviser, or in some cases, two advisers with different firms. For these investors, it is not a question of getting the lowest possible fee but finding a trustworthy person and firm that meets their needs. The adviser is paid to guide the wealthy investor through the myriad choices into something suitable for their unique family situation. A good adviser helps the investor avoid big mistakes by utilizing best practices in planning and portfolio management.
QWhat questions do you recommend Chevron employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
I recommend Chevron employees ask these questions, grouped by category:
1. Experience – what is the age and work experience of the adviser?
· How many total years has the adviser worked in the industry?
· How many investment cycles has the adviser managed through?
· Can the adviser relate to the needs of you, the client?
2. Expertise – Does this investment professional have the right skill set?
· Superior understanding of the characteristics, behavior, and risk of different investments.
· Extensive understanding of retirement planning, the investment process, asset allocation, investment selection, and the practical steps of managing a portfolio.
· Sensitivity to the financial, regulatory, tax, and legal implications of investment decisions.
3. Credentials – what education and certifications does the adviser have that confirm an individual’s knowledge and expertise?
· Education – college and graduate degrees with concentrations in finance, accounting, or economics. Top schools are a plus.
· Professional designations such as the Chartered Financial Analyst (CFA), Certified Financial Planner (CFP) or Certified Investment Management Analyst (CIMA).
4. Financial planning and the investment process
· Is a retirement plan prepared as part of the investment process?
· Does the adviser provide estate and tax education with regard to accounts and general issues?
· Are the advisory and investment fees fully disclosed?
· Is the adviser a fiduciary?
5. Service level – how much contact should you expect with this adviser?
· Number of meetings per year: annual, quarterly, monthly.
· Responsiveness and ability to meet special requests.
· Assistance with managing concentrated equity holdings.
Considering a financial advisor who specializes in working with Chevron Employees?
Are you a financial advisor who specializes in working with employees at Chevron or another large company?
✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at Chevron or another large company. (Subject to availability and terms.)
✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender
Ask a Financial Advisor Your Chevron Benefits & Career Questions
Are you ready to enjoy life more with less money stress?
Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.

About the Author
Brian Thorp
Founder & CEO, Wealthtender · Editor-in-Chief
Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.
A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.
Brian and his wife live in Austin, Texas.