You’ve talked about retirement. You’ve even run some numbers. But somewhere beneath the spreadsheets, there’s a question neither of you has quite asked out loud: Are we actually picturing the same future? In blended families, the answer is often no, not because anyone is being careless, but because each partner brings different obligations and a different sense of what “enough” looks like. Blended family retirement planning starts well before the portfolio. It starts with the expectations each of you carries and where they came from.

Those expectations don’t announce themselves. They show up in assumptions about who owns what assets and what obligations to children or former spouses should take priority. Understanding what each person values, and where that comes from, is where meaningful retirement planning in a blended family begins.

Where Financial Expectations Come From (and Why They Differ in Blended Families)

Every financial decision you make today is connected to something you experienced before. Over time, those experiences become internal rules about what money should do for you. In behavioral finance, these are often referred to as “money scripts”—deeply ingrained beliefs that influence how we save and spend, often without us realizing it. 

In a blended family, aligning your finances requires aligning the beliefs behind them. That’s why expectations around retirement timing, investment risk, and lifestyle can feel so different even when you’re working toward the same future. It’s a dynamic I examine throughout my book, Blended Family Finances: How to Talk About Money, Plan for the Future, and Build a Life You Love. Because understanding where those beliefs come from is the first step toward building a life that you actually want to live.

Even among higher-income couples, asset division, legal costs, and years of financial disruption can leave partners at very different starting points by the time they remarry. U.S. Census data show that adults who have married more than once are significantly less likely to have accumulated substantial retirement savings compared to those who married only once, and the gap persists even when current income is strong. One partner may carry that history internally, shaping how security and fairness feel to them in ways the other may not immediately see. Those differences matter because they shape real decisions.

This is the emotional math of blended family finances—invisible calculations about what feels protective, threatening, or fair. Feelings like guilt toward children, worry of repeating past mistakes, or a desire to protect what you’ve rebuilt can influence your choices. They’re signals worth paying attention to, even when they resist logical solutions, because they can shape everything from how much you save to how you structure your legacy.

Different Starting Points, Different Timelines: Retirement After Remarriage

Our financial history tells a story. In many blended families, perhaps one partner has spent years steadily rebuilding wealth, while the other is still rebuilding after the financial disruption of divorce.

That gap is well documented. According to a Business Insider analysis of U.S. Census Bureau data, the average married retiree has over $100,000 more saved in retirement accounts than a divorced retiree, a difference driven largely by asset division, legal costs, and lost compounding time. Even among couples who remarried, retirement income remained lower than that of those who had married only once.

For higher-income couples, the absolute numbers differ, but the dynamic remains the same. One partner may arrive at the relationship with a well-funded portfolio and a clear retirement timeline. The other might be earning well right now but still carrying the financial weight of starting over after divorce. Those two pictures don’t automatically align, and when they don’t, expectations around retirement timing, lifestyle, and risk tolerance can drift apart.

Those gaps shape how you plan together. How much should you save now? Whose timeline takes priority? How much risk feels comfortable when one partner still feels the urgency to catch up?

These are the kinds of decisions that require coordination across both past and present relationships. And getting them right starts with understanding what each partner is actually bringing to the table.

Clarity Starts with a Conversation

In blended families, many of the biggest financial challenges don’t come from a lack of planning. They stem from assumptions that were never spoken aloud. Over time, those assumptions harden into expectations, and when expectations diverge, even well-resourced couples can find themselves making decisions that pull in different directions.

Bringing those assumptions into the open is where the real planning begins.

One of the most valuable conversations a couple can have isn’t about the numbers—it’s about the experiences that shaped how each person defines security, responsibility, and what ‘enough’ actually means. 

In retirement planning, this is where direction begins. It influences when retirement feels possible, how secure it needs to feel, and how you balance caring for the people who depend on you—past and present—without losing sight of the life you’re building together. 

For example, one partner may feel a responsibility to preserve assets for children from a previous marriage, something shaped by promises made, or lessons learned the hard way. The other may be focused on building a shared future as a couple, assuming that resources will be used more fluidly between present lifestyle and long-term goals.

Neither perspective is wrong. But without a conversation, both can influence decisions:

  • how much risk feels appropriate
  • how aggressively to save
  • how retirement is ultimately structured

And over time, those differences show up in how aligned (or misaligned) the plan feels.

That’s why in our work with blended families, planning doesn’t start with projections alone.

It starts by uncovering: he values each person brings into the relationship, the money stories behind those values, and the vision they’re trying to build together

Because once those pieces are clear, the financial decisions that follow tend to make more sense—not just on paper, but in how they feel to both partners.

Aligning Your Retirement Vision as a Blended Family

You each stepped into this relationship with a story already in progress. Blended family financial planning is the work of bringing those two stories into a coherent shared chapter, one that accounts for where each of you has been while building toward something you can both see clearly.

That work doesn’t have to feel overwhelming. When expectations are surfaced, discussed, and aligned, blended family retirement planning becomes a reflection of the relationships and responsibilities you care about most. 

The question isn’t whether you and your partner see retirement differently. It’s whether you’ve given yourselves the space to say so and to understand why. 

That’s where the planning starts.

And it’s also where having a clear framework can make those conversations more productive.

In my book, I walk through a practical approach for having these conversations, including how to structure them, what to surface first, and how to move from alignment on values to shared direction. It includes a companion workbook so you and your partner can work through the process together.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

Headshot of Brian K. Peterson, CFP®, CPWA®, MBA
Brian K. Peterson, CFP®, CPWA®, MBA Planning Built For Blended Family Life

Brian K. Peterson, CFP®, CPWA®, MBA | Blended Family Financial

What this article covers

Discover financial advisors trusted by residents of Northfield, New Jersey in the only local directory featuring 5-Star Certified Advisor Review™ recipients and Wealthtender Voice of the Client Award™ winners, recognition earned for exceptional client feedback. Compare fiduciary, fee-only advisors, CFP® professionals, and specialists to find the right fit for your unique financial needs.

Financial Advisor Directory for Northfield, New Jersey

📍 Map: Financial Advisors with their Primary Office Location in Northfield

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Northfield.

📍Double-click or pinch pins to view more.

Showing

Key Takeaways

1

You can compare Northfield financial advisors by credentials, specialty and verified client reviews before you contact anyone.

The map shows advisors whose primary office is in Northfield. Profiles include Certified Advisor Reviews™, designations such as the CFP® and the services each advisor offers.

2

Northfield’s ties to Atlantic City’s casinos, AtlantiCare and the FAA Technical Center shape the planning help many residents need.

Many Northfield households earn their income from casino and hospitality jobs, the region’s largest health system or federal aviation research, each with different pay patterns and retirement benefits. Property tax bills above the Atlantic County average and New Jersey’s rules for taxing retirement income also shape plans for residents who want to retire near the shore.

3

Interview more than one advisor and confirm how each one is paid.

Ask about services, fees and whether the advisor acts as a fiduciary, then check their background for free on the SEC’s Investment Adviser Public Disclosure website before you hire.

Financial Planning Considerations for Northfield Residents

Every city has its own financial landscape. Here are a few local factors worth discussing with a Northfield financial advisor.

Casino and hospitality paychecks

Atlantic City’s casinos are about 7 miles east of Northfield, and Borgata, Hard Rock and Ocean Casino Resort each employ more than 3,000 people, making them among Atlantic County’s largest employers. Casino and hospitality pay often includes tips and hours that can change from month to month, so a solid cash reserve, a budget built on base pay and steady contributions to a 401(k) or IRA matter more than usual. Workers moving into management may also need help with bonuses and deferred compensation.

Health care and federal careers

AtlantiCare is Atlantic County’s largest employer, with more than 6,500 workers systemwide, and the FAA William J. Hughes Technical Center has about 4,500 federal employees and contractors on campus. Federal workers face decisions specific to FERS pensions, the Thrift Savings Plan and keeping federal health coverage in retirement. Hospital staff and Stockton University employees often coordinate 403(b) plans and pensions with other savings, especially when both spouses work in different systems.

Property taxes in Northfield

Northfield’s average residential property tax bill was $8,297 in 2025, according to New Jersey Department of the Treasury data, above the Atlantic County average of $7,049 but below the statewide average of $10,340. Older homeowners may qualify for state relief through Stay NJ, ANCHOR and the Senior Freeze. Benefit amounts and income limits change with the state budget, so check the current rules each year before counting on a payment.

How New Jersey taxes retirement income

Many Northfield residents plan to retire near the shore, so New Jersey’s tax rules matter. New Jersey’s top income tax rate is 10.75% for 2026, but Social Security benefits are not taxed. Residents 62 and older with total income of $100,000 or less can exclude up to $100,000 of pension, annuity and IRA income on a joint return ($75,000 single), with a partial exclusion up to $150,000. New Jersey’s estate tax ended in 2018, but its inheritance tax may still apply depending on how heirs are related to the decedent.

The Benefits of Hiring a Financial Advisor in Northfield

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Northfield, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Who are the largest employers in the Northfield area?

These are among the largest employers across Atlantic County, which includes Northfield, Atlantic City and the surrounding communities.

  1. AtlantiCare Health System 6,500+ employees (systemwide)
  2. FAA William J. Hughes Technical Center About 4,500 on campus (federal staff and contractors)
  3. Borgata Hotel Casino & Spa 4,457 employees
  4. Hard Rock Hotel & Casino Atlantic City 3,530 employees
  5. Ocean Casino Resort 3,378 employees
  6. Caesars Atlantic City 2,507 employees
  7. Harrah’s Resort Atlantic City 2,269 employees
  8. Tropicana Atlantic City 1,973 employees
  9. Stockton University About 1,863 employees (estimate)
  10. Resorts Casino Hotel 1,404 employees
  11. Golden Nugget Atlantic City 1,353 employees
  12. Bally’s Atlantic City 1,339 employees

Work for one of these companies or another large employer? Explore our employer Q&As for advice on making the most of your benefits.

Source: Atlantic County Economic Alliance, Atlantic County Development Business Report (May 2026; casino counts are NJ Division of Gaming Enforcement year-end 2024 figures). Counts are countywide; AtlantiCare’s figure is systemwide, and the FAA Technical Center figure includes federal employees and contractors. Stockton’s count is the source’s estimate.

Do you work for one of the largest employers in Northfield? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Types of Financial Advisors You’ll Find on Wealthtender

Thousands of people visit Wealthtender each month to find and compare financial advisors based on their location, education, experience, areas of specialization and online reviews. Wealthtender’s Certified Advisor Reviews™ help consumers make informed hiring decisions with important details about the relationship between reviewers and advisors always displayed to ensure you gain the transparency you deserve when your life savings could be at stake.

On Wealthtender, you can explore a diverse range of financial advisors and wealth management firms that include:

  • Fiduciary advisors committed to acting in clients’ best interests
  • CFP® professionals with advanced financial planning credentials
  • Fee-only advisors compensated solely by clients
  • Advisors for growing families, people nearing retirement, and business owners
  • Specialists across multiple categories (e.g., life stage, occupation, ethnicity, lifestyle, religion)
  • Highly-rated advisors with positive client reviews
  • Firms of varying sizes with advisors who can meet with you in person or online
  • Fee-based advisors who offer access to insurance and alternative investments

How to use this directory: Compare financial advisors in the Northfield area based on what matters most to you. Use the directory to:

  • View advisor profiles to evaluate credentials, services, and areas of specialization
  • Read Certified Advisor Reviews™ to learn what clients value most
  • Identify advisors recognized with Wealthtender Voice of the Client Awards™
  • Contact advisors and schedule free introductory video calls

Wealthtender Voice of the Client Awards™: Top Rated Northfield Financial Advisors

Wealthtender Voice of the Client Awards™ recognize financial advisors and firms that consistently earn exceptional client feedback. Below are Northfield-area advisors and firms that have met the criteria for Highly Rated recognition.

Firm/Advisor Firm City State Voice of the Client Award Website

To qualify for a Highly Rated award, advisors and firms must achieve an average client review rating of 4.75 or higher (on a scale of 1 to 5) based on a minimum number of eligible client reviews published on Wealthtender within a defined timeframe for each particular award (Timeframe for 2025 Award: 1/1/24 – 12/31/25; Timeframe for Subsequent Year Awards: July 1 of the preceding year through December 31 of the Award Year (e.g., Timeframe for 2026 Award 7/1/25 – 12/31/26). Eligible reviews are limited to clients (as of the review submission date) that advisors/firms must self-attest have no material conflicts of interest and received no compensation in exchange for their reviews. ↗️ View full award methodology & FAQs

Although financial advisors and wealth management firms compensate Wealthtender for marketing services (including eligibility to be considered for awards), Wealthtender’s award criteria is objective and not influenced by compensation. Wealthtender Voice of the Client Awards are not a guarantee of future performance or success and client reviews may not be representative of the experience of all past or future clients.

Quick Tips For Hiring a Northfield Financial Advisor

Before hiring a financial advisor in Northfield, here are a few quick tips to help you find the best advisor for you.

1

Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor who specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2

Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3

Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4

Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.

Frequently Asked Questions

What makes a financial advisor “trusted”?
A trusted financial advisor typically earns positive client feedback over time, operates transparently, and clearly explains how they’re compensated. On Wealthtender, trust is reflected through Certified Advisor Reviews™ that combine insights into the client experience and character of advisors with important disclosures about each reviewer to ensure you gain the transparency you deserve when your life savings could be at stake.

Financial advisors and wealth management firms that consistently receive superior client reviews can also qualify for Wealthtender’s Voice of the Client Awards™ designed to recognize America’s most trusted advisors. Learn More About Wealthtender Voice of the Client Awards™
What are Certified Advisor Reviews™?
Certified Advisor Reviews™ from Wealthtender help consumers make smarter hiring decisions when choosing a financial advisor.

Clients and other individuals can submit reviews for financial advisors and wealth management firms that have turned on the reviews feature. Before each review is publicly displayed, financial advisors agree to disclose important information about their relationship with the reviewer to ensure consumers gain the transparency they deserve when their life savings could be at stake. These disclosures also help financial advisors satisfy compliance with industry regulations.

After financial advisors provide the required disclosures, Wealthtender publishes the review with the Certified Advisor Review™ mark. Learn More About Certified Advisor Reviews™
Can I find fiduciary financial advisors on Wealthtender?
Yes, you’ll find hundreds of fiduciary financial advisors on Wealthtender. Fiduciary financial advisors must act in their clients’ best interest. Before hiring an advisor, always ask if they will act in your best interest as a fiduciary.

For example, financial advisors who have earned their Certified Financial Planner (CFP) designation are fiduciaries. To hold themselves out as a CFP, these credential holders must acknowledge they will adhere to the CFP Board’s Code of Ethics and Standards of Conduct and act as a fiduciary when providing financial advice to their clients. Learn More About Fiduciary Financial Advisors
Can I find fee-only financial advisors on Wealthtender?
Yes, you’ll find hundreds of fee-only financial advisors on Wealthtender. Fee-only financial advisors are paid directly by their clients. Since they aren’t compensated based on the products and services they recommend (e.g., commissions), their compensation model helps reduce potential conflicts of interest.

When viewing financial advisor profiles on Wealthtender, look for the Compensation Methods section that shows ways each financial advisor can be paid for their services, including if they offer fee-only financial planning services. Learn More About Fee-Only Financial Advisors
What distinguishes Wealthtender Voice of the Client Awards™ from other advisor recognition programs?
Wealthtender’s Voice of the Client Awards™ recognize financial advisors and wealth management firms that consistently receive superior client reviews. Unlike award programs with ranking factors that favor financial institutions with the most assets and the fastest revenue growth, the Wealthtender Voice of the Client Awards provide both local financial advisors who choose to remain small and large wealth management firms with the opportunity to be recognized on a metric that matters more to consumers – actual client feedback reflecting the quality of their experience. Learn More About Voice of the Client Awards™
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit. But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a Northfield financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Learn how to get featured

Please note: Wealthtender may be compensated by financial advisors featured on our site and within this guide. Learn more about how we operate with integrity to earn your trust.

Watch

How Much Does a Financial Advisor Cost?

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

Are you a New Mexico PERA member?

Get expert insights from financial advisors who specialize in helping New Mexico PERA members make the most of their compensation package and benefits.

Looking for a financial advisor who specializes in working with New Mexico PERA members? You’re in the right place. Below, you’ll find advisors who understand New Mexico PERA benefits and compensation — along with their answers to common financial questions from New Mexico PERA members.

Whether you’re early in your public service career or approaching retirement, making smart decisions about your income and New Mexico PERA benefits can have a lasting impact on your financial future. For example:

✅ Do you know the right moves to get the greatest value from the New Mexico PERA benefits available to you?

✅ If you’re thinking about leaving public service for another job or planning to retire in a few years, are you taking the right steps today to receive all the retirement benefits you’ve earned?

Key Takeaways

1

SmartSave, New Mexico’s 457(b), Is Underused by Many PERA Members

Members can mix pre-tax and Roth contributions, use a special pre-retirement catch-up of up to double the regular limit, and take distributions after separation without the 10% early withdrawal penalty.

2

Think Twice Before Taking a PERA Refund When You Leave

Leaving contributions on deposit preserves service credit if you return to PERA-covered work, while a refund forfeits the future pension and can be costly to buy back.

3

Survivor Elections and Service Credit Purchases Are Decisions You Make Once

These choices, along with the order in which you draw down accounts, have lasting consequences and deserve careful planning within about ten years of retirement.

Why New Mexico PERA Members Work with a Specialist Financial Advisor

New Mexico’s Public Employees Retirement Association provides members with a defined benefit pension, and members can also save in SmartSave, the state’s 457(b) deferred compensation plan, with pre-tax and Roth options — along with retiree health care through the New Mexico Retiree Health Care Authority (NMRHCA). While PERA offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with PERA who specialize in helping members make the most of their retirement benefits.

New Mexico PERA is headquartered in Santa Fe and serves employees and retirees of the state, counties, cities, and other public employers across New Mexico, including police officers, firefighters, and correctional officers. Wherever you work in the state, you may have questions about your retirement benefits better suited for a financial professional who can offer unbiased advice and guidance.

Sensitive topics — like the steps you should take before leaving a PERA-covered job, choosing among pension payout and survivor options, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.

Should You Hire a New Mexico PERA Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving New Mexico PERA members. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with New Mexico PERA members is the better fit for your unique needs.

💡 In the Q&A below, you’ll gain insights from financial advisors who work with New Mexico PERA members to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.

🙋‍♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.

Q&A: Financial Planning Tips for New Mexico PERA Members

In this section, you’ll learn how you can make the most of your New Mexico PERA benefits and gain valuable tips from financial advisors who specialize in working with New Mexico PERA members.

Financial Advisor Q&A  ·  New Mexico PERA Members

Peter Bo Rappmund, EA, CFP®, Financial Advisor for New Mexico PERA Members at Counterpoint

Peter Bo Rappmund, EA, CFP®

Counterpoint  ·  Santa Fe, NM  ·  Serves clients nationwide

Clarity and alignment | Fiduciary financial advisor
Book Intro Call

Peter Bo Rappmund is a financial advisor based in Santa Fe, New Mexico who specializes in offering financial planning services to New Mexico PERA members. Peter helps his clients get the most value from their PERA benefits and compensation package so they can enjoy life and feel confident about their financial future.

QAs a financial advisor with experience helping New Mexico PERA members save for their retirement, how do you help them make the most of their benefits?

When I meet with a New Mexico PERA member, my goal is to help them see their benefits as part of a larger system instead of a mishmash of disconnected pieces. The cornerstone is the PERA defined benefit pension, a 401(a), which is a huge asset most private-sector employees don’t have access to.

I like to get clear on the specifics. We consider the coverage plan, tier, projected pension benefit, and then compare that to the income a client will need in retirement. The gap is usually where SmartSave, New Mexico’s 457(b) deferred compensation plan, comes in. Many members underutilize it, either assuming the pension alone will be sufficient or finding the plan intimidating to navigate. I help think through how much to contribute, the right mix of pre-tax and after-tax (Roth), and how those choices can coordinate with their broader tax picture.

From there we round out the plan. This entails potential service credit purchases that can boost a pension benefit when timed correctly, NMRHCA retiree health care, survivor election decisions (beneficiaries), and how Social Security fits in or, for some PERA roles, how the absence of it shapes the income strategy. We’re not necessarily maximizing a number on a benefits estimate but rather trying to build a safe and sound plan that lets you retire on your terms, with confidence and on the sustainability of your income.

QWhen you first speak with a PERA member, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?

Any PERA member’s situation will be unique enough that a generic intake doesn’t serve them well, so my initial conversation is about gathering the inputs that drive everything else. The first questions are almost always: when were you first hired into PERA-covered employment, and which coverage plan are you in? Or even simpler, do you know how to login to RIO (the online PERA system)? From there we can quickly determine your tier, your contribution rate, your benefit multiplier, and your earliest retirement eligibility. Without those, the advice I’d give would be unreliable.

I also want to know what retirement looks like to them, what they are imagining, and roughly when they want to actually retire, best-case scenario. I look into whether they’ve ever taken a refund, or served in the military (each of which may open the door to a service credit purchase); and how they’re using SmartSave, including the mix of pre-tax and Roth. I also ask about their household and gather information on their spouse or partner, dependents, and the rest of the financial picture. Survivor election decisions can be among the most consequential choices a PERA member makes.

Finally, I want to understand what exists outside of PERA, be it IRAs, prior employer plans, a spouse’s retirement, NMRHCA eligibility, and life and disability coverage. PERA is the anchor, but it’s rarely the whole picture, and the early conversations become less about gathering data than about understanding the person behind it.

QIs there a particular benefit available to PERA members you feel isn’t as well utilized or understood by members as it should be?

I’d point right back to SmartSave (deferred comp), which I touched on earlier. It’s New Mexico’s 457(b) deferred compensation plan, and while most PERA members know it exists, few use it to its full potential. One thing members often don’t realize is the flexibility built into the contribution side. You can save pre-tax (lowering current taxable income), or after-tax (Roth), or mix the two together. For participants whose tax bracket in retirement is likely to look different than it does today, which is most people, that flexibility can make a huge difference.

A second underused feature is the special pre-retirement catch-up. In addition to the standard catch-up available starting at age 50, governmental 457(b) plans like SmartSave allow eligible members to contribute up to double the regular annual limit during the three years before normal retirement age, provided they didn’t fully use their contribution room in earlier years. For someone in the home stretch of their career who’s behind on retirement savings, or who’s recently come into extra cash flow, this is something easy to take advantage of.

Next is access. SmartSave permits plan loans and, in qualifying circumstances, unforeseeable emergency withdrawals, which gives members reassurance that the money they defer isn’t completely locked away. Another one of the underappreciated advantages of a 457(b) is that once a participant separates from service, distributions are not subject to the 10% early withdrawal penalty that applies to most 401(k)’s and 403(b)’s, regardless of age. That distinction matters a great deal for members planning to retire before 59½.

QBeyond PERA member benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?

I almost always have a conversation around health care through New Mexico Retiree Health Care Authority. We’ll talk about eligibility rules, premium subsidies, and how that coverage bridges to Medicare. For many, NMRHCA is one of the most valuable pieces of their public-employee compensation package outside of the pension itself.

Beyond that, I usually have questions on insurance, any additional health savings, and whether long-term care coverage is on their radar. Nothing flashy, but they’re the kind of decisions that quietly shape financial security in retirement.

QFor PERA members thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?

Leaving a PERA-covered job is a major financial decision that deserves more thought than it usually gets. For some, it is similar to leaving a tenured position. Before resigning, it is usually a good idea to maximize what you can put into the system on the way out. For example, deferring as much cash flow allows into the 457(b), especially if you’re in the catch-up window, and confirm what you’ll receive for your final paycheck, sick leave payout, and any annual leave cash-out.

If you aren’t vested, the biggest decision is what to do with your PERA contributions, and in most cases my recommendation is to leave them on deposit with the state. Many New Mexicans who leave one PERA-covered position end up returning to another public sector role in New Mexico, and leaving your contributions with PERA preserves your service credit so you can pick up right where you left off. Taking a refund forfeits the future pension benefit you’ve earned, it basically cashes in on time worked, and if you do return to a PERA-covered job later, the cost to buy that service back can be substantial. A refund can still make sense in some situations, particularly if you’re confident you won’t return to public sector work and have an urgent need for cash, but I want any member to fully understand what they’d be giving up before going that route.

Deferred comp balances can stay in the plan, roll to an IRA, or move to a new employer plan, each with different trade-offs and rules to follow. Update your beneficiary designations after the transition and make sure your new employer’s benefits are configured before separation to avoid a coverage gap.

QFor PERA members approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?

A lot of my clients are surprised when I show them how much money they are spending to work. Also, planning on how money may shift to unforeseen health care costs, or vacation spending in retirement. I’ve even worked with a couple who went on a semi-permanent cruise once they left their state job.

The first step though is requesting a formal benefit estimate from PERA. From there, build a realistic retirement budget and compare it to your projected pension, SmartSave balance, Social Security (if applicable), and any outside savings. The work then shifts to sequencing and timing of withdrawals across those accounts to keep your tax bill manageable in retirement. Before you separate, look at moves like service credit purchases or maximizing SmartSave contributions through things such as vacation/sick-leave payouts.

QFor PERA members who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?

Honestly, doing it yourself for a long time is something to be proud of- many people don’t. A good question to ask is whether the next phase of your life involves decisions that are bigger and more complicated than what you’ve handled before. For New Mexico PERA members, that moment usually arrives somewhere within ten years of retirement, when the choices on the table start to look very different. Survivor benefit decisions, service credit purchase windows, and the order in which you draw down your accounts in retirement are all decisions you generally make once, and the cost of getting them wrong is high.

I’d also think about the tax planning side. If you’re juggling a PERA pension, SmartSave (with both pre-tax and Roth balances), Social Security, IRAs, and possibly a spouse’s accounts, the question stops being “am I saving enough?” and becomes “in what order, and at what rate, do I draw these down to keep my lifetime tax bill as low as possible?” That’s a different kind of math, and a planner who knows your situation can be invaluable.

You also need to know how you actually want to spend your time and energy. Some people enjoy reading retirement research, playing with investing and running their own models, and that’s terrific. But many of my clients tell me the real value of working with an advisor isn’t just the technical work. It’s the freedom to stop carrying the weight of every financial decision themselves, and the confidence that comes from having a second set of trained eyes on a plan they’ve worked their whole career to fund.

QWhat are some of the unique financial planning challenges you commonly see among your clients who are PERA members and how do you help them overcome these obstacles?

The challenges I see most often come back to complexity and irreversibility. PERA’s tier rules vary enough that two members in seemingly similar jobs can have meaningfully different benefit structures. Add deferred comp, Social Security, and any outside accounts to the picture, and the planning lift is suddenly very real. My job is to slow those decisions down, lay out the trade-offs in plain language, and make sure each move fits a coherent long-term plan rather than getting decided in isolation.

QWhat questions do you recommend PERA members ask financial advisors they’re considering hiring to help them decide if they’re a good fit?

Know whether the advisor operates as a fiduciary at all times. A fiduciary is legally and ethically bound to put your interests ahead of their own in every recommendation. Beyond that, look at credentials and specialty. Ask whether the advisor has hands-on experience with PERA members specifically, since the system has its own vocabulary and quirks. Finally, confirm how they’re paid. Fee-only advisors charge solely for advice and don’t earn product commissions.

QIs there anything that comes up frequently in your initial meeting with PERA members that surprises you?

I feel lucky I get to work with such thoughtful and values-driven government employees out here in New Mexico. People who choose public service generally aren’t doing it solely for the money, and that same long-view, mission-oriented mindset shows up in how they approach their lives. They tend to be disciplined savers, and genuinely focused on making good decisions for their families and communities. It makes the work feel less like advising and more like collaborating with people who already know what matters most.

QFor highly compensated PERA members and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

This is another case where we’ll make sure the employee is making full use of SmartSave. The governmental 457(b) is a powerful tool for high earners because it doesn’t have the highly compensated employee testing that limits private-sector 401(k) deferrals, so executives can typically max it out without restriction. The 3-year pre-retirement catch-up is especially valuable here, since it can effectively double the contribution limit during the final years of a career, a window when income tends to peak and the tax benefit of deferral is at its highest. From there, we get into tax-bracket management around the gap between salary income, pension start, and Social Security claiming, which is often where the biggest planning wins live for this group. As a CFP® and an Enrolled Agent (EA), that kind of multi-year tax work is where I tend to spend the most time with clients in this position.

QIs there a particularly memorable experience or a moment you recall with a client who worked at PERA when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?

Prior to starting my own firm, I spent years working exclusively with PERA members and traveling all over the state to meet with New Mexico’s public sector employees. I have too many stories at this point to pick just one, but something that always resonated with me was getting to help people cross the finish line into retirement and then catching up with them on the other side. Public sector employees tend to retire younger than their private-sector counterparts, and more often than not I’d see them taking on a whole new career or life post-government. And I’d see how what we had worked on together was going to help not only them, but their future generations as well.

There’s also a part of myself outside finance that shapes how I approach everything in general. As a working artist, I’ve spent years learning to notice what others miss and to make something coherent out of pieces that don’t always seem to belong together. Planning, at its best, asks for this same instinct.

Considering a financial advisor who specializes in working with New Mexico PERA Members?

Are you a financial advisor who specializes in working with New Mexico PERA members or other public employees?

✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with New Mexico PERA members or other public employees. (Subject to availability and terms.)
✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender

Ask a Financial Advisor Your New Mexico PERA Benefits & Career Questions


Are you ready to enjoy life more with less money stress?

Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.

  • This field is for validation purposes and should be left unchanged.

About the Author

Brian Thorp, Founder and CEO of Wealthtender and Editor-in-Chief

Brian Thorp

Founder & CEO, Wealthtender  ·  Editor-in-Chief

Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.

A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.

Brian and his wife live in Austin, Texas.

Read Brian’s full bio →   ·   Connect on LinkedIn →

Do you work at EOG Resources?

Get expert insights from financial advisors who specialize in helping EOG Resources employees and executives make the most of their compensation package and benefits.

Looking for a financial advisor who specializes in working with EOG Resources employees? You’re in the right place. Below, you’ll find advisors who understand EOG Resources benefits and compensation — along with their answers to common financial questions from EOG Resources employees and executives.

Whether you recently joined EOG Resources or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and EOG Resources benefits can have a lasting impact on your financial future. For example:

✅ Do you know the right moves to get the greatest value from the EOG Resources benefits available to you?

✅ If you’re thinking about leaving EOG Resources for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?

Key Takeaways

1

EOG Performance Units Can Create a Sudden Tax Spike

Performance-based equity payouts depend on company results and can be much higher or lower than expected. Planning ahead for vesting events, and deciding how much to sell and how to allocate the proceeds, keeps a strong year from becoming a tax bomb.

2

Once the EOG 401(k) Is Maxed, the Real Planning Begins

High earners can extend tax-advantaged saving with after-tax 401(k) contributions and Roth conversions (when available), backdoor Roth IRAs, and tax-efficient brokerage accounts. The focus shifts from saving more to saving across the right account types.

3

Net Unrealized Appreciation on EOG Stock Is a One-Time Opportunity When You Leave

If EOG stock is held in the 401(k), the NUA strategy can let appreciation be taxed at long-term capital gains rates. The decision is tied to triggering events such as separation from service, so plan it before you leave.

Why EOG Resources Employees Work with a Specialist Financial Advisor

Throughout the year, EOG Resources provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) with a company match — along with performance-based bonuses and equity compensation such as restricted stock units and performance units. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with EOG Resources who specialize in helping EOG Resources employees make the most of their income and benefits.

EOG Resources is headquartered in downtown Houston, Texas, and operates in major U.S. oil and gas basins, including the Permian Basin in West Texas and New Mexico and the Eagle Ford in South Texas, with division offices in cities such as Midland and San Antonio, Texas, and Denver, Colorado. Whether you work at one of those sites, another office, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.

Sensitive topics — like the steps you should take before quitting your job at EOG Resources to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.

Should You Hire an EOG Resources Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving EOG Resources employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with EOG Resources employees is the better fit for your unique needs.

💡 In the Q&A below, you’ll gain insights from financial advisors who work with EOG Resources employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.

🙋‍♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.

Q&A: Financial Planning Tips for EOG Resources Employees & Executives

In this section, you’ll learn how you can make the most of your EOG Resources employee benefits and gain valuable tips from financial advisors who specialize in working with EOG Resources employees and executives.

Financial Advisor Q&A  ·  EOG Resources Employees

Dr. Preston D. Cherry, CFP®, Financial Advisor for EOG Resources Employees at Concurrent Wealth Management

Dr. Preston D. Cherry, CFP®

Concurrent Wealth Management  ·  Houston, TX  ·  Serves clients nationwide

Houston-Based Flat-Fee Fiduciary Advisor for Gen X & Oil & Gas
Book Intro Call

Dr. Preston Cherry is a financial advisor based in Houston, Texas who specializes in offering financial planning services to EOG Resources employees. Preston helps his clients get the most value from their EOG Resources benefits and compensation package so they can enjoy life and feel confident about their financial future.

QAs a financial advisor with experience helping EOG Resources employees save for their retirement, how do you help them make the most of their employee benefits?

EOG Resources professionals are often in a strong financial position—high salary income, performance-based bonuses, and long-term incentives tied to company results. That creates a powerful wealth-building opportunity, but also introduces a different kind of planning challenge: how to allocate, structure, and tax-optimize that income efficiently. Making the most of EOG benefits is not about maximizing one account. It’s about coordinating cash flow, equity compensation, taxes, and long-term investment strategy so peak earning years translate into lasting flexibility.

When working with EOG professionals, I focus on integrating:

  • 401(k) strategy beyond standard deferrals, including after-tax contributions and Roth conversion opportunities (when available)
  • Employer match optimization and investment exposure within the plan
  • Equity compensation (RSUs and performance-based PSUs) and how vesting impacts taxes and concentration
  • Bonus income planning and marginal tax bracket management
  • Brokerage account strategy to build flexible, tax-efficient capital
  • Backdoor Roth IRA contributions alongside workplace plans
  • Retirement income modeling while income is at its peak

For many high-income EOG professionals, once traditional 401(k) contributions are maxed, the real planning begins, deciding how to allocate income across tax-deferred, tax-free, and taxable accounts. The goal is not just accumulation. It’s building a structure where your income, investments, and future withdrawals work together to support both retirement durability and lifestyle flexibility.

QWhen you first speak with a EOG Resources employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?

With EOG professionals, the starting point is analyzing the benefits summary and, more importantly, understanding how income actually behaves. Compensation often includes variability through bonuses and performance-based equity, which directly affects tax planning and investment strategy.

I focus on questions like:

  • What percentage of your compensation is variable vs fixed?
  • How consistent have your bonuses been across cycles?
  • What is your current savings rate during strong income years?
  • How much of your net worth is tied to EOG or the energy sector?
  • Are you building assets outside of retirement accounts?
  • What does financial independence or optional work look like for you?

EOG professionals typically earn well. The key question is whether that income is being deployed intentionally.

QIs there a particular benefit available to EOG Resources employees you feel isn’t as well utilized or understood by employees as it should be?

One of the most misunderstood areas for EOG professionals is how equity compensation actually behaves, especially performance-based awards. At EOG, equity is often delivered through performance-based incentives (PSUs), which can lead to significant income variability. Unlike RSUs, which vest on a schedule, PSU payouts depend on company performance and can be materially higher or lower than expected.

In strong years, this can result in a sudden increase in taxable income. This is where many high earners experience what they describe as a “tax spike” or “tax bomb.” A large PSU payout may arrive in a single year, pushing income into higher marginal brackets and increasing overall tax liability if not planned for in advance.

EOG professionals navigating equity compensation alongside broader energy sector planning considerations can find additional resources on our Oil & Gas Financial Planning page.

The opportunity is not just in receiving the compensation, but in how it’s managed once it’s received.

That includes:

  • Planning ahead for the tax impact of vesting events
  • Determining how much to sell immediately vs retain
  • Allocating proceeds intentionally across: lifestyle and short-term needs, ongoing financial goals, and long-term investment strategy

When equity vests, the key question is: What role does this money play in your life going forward?

I often guide clients to think in three buckets:

  • Lifestyle + taxes
  • Ongoing goals
  • Long-term capital

Another overlooked opportunity is what happens after traditional retirement contributions are maxed out. Many EOG professionals stop at the 401(k) when additional strategies may be available:

  • After-tax 401(k) contributions with Roth conversion (when supported)
  • Backdoor Roth IRA contributions
  • Brokerage accounts structured for tax efficiency and flexibility

At higher income levels, the focus shifts from saving more to saving across the right account types.

QBeyond EOG Resources employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?

For EOG professionals, one of the most valuable “benefits” is income itself and how it’s used.

Beyond traditional retirement plans, I focus on:

  • Brokerage accounts for flexibility and early access
  • Tax-efficient investing across account types
  • Health Savings Accounts as long-term investment vehicles
  • Insurance and protection planning aligned with income
  • Liquidity planning for career transitions or market cycles

Retirement accounts are important, but they come with restrictions. Brokerage accounts, when used intentionally, partner with retirement accounts to provide flexibility, especially for professionals who may want optionality before traditional retirement age.

QFor EOG Resources employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?

Leaving EOG is more than a career decision—it’s a financial event.

Before making a transition, EOG professionals should evaluate:

  • Bonus timing and eligibility
  • Vesting schedules for RSUs and PSUs
  • Unvested equity that may be forfeited
  • Changes in income structure
  • Retirement plan contributions and match
  • Healthcare differences

One of the most important—and often overlooked—areas involves employer stock inside a retirement plan. If EOG stock is held within a 401(k), there may be a one-time opportunity to use a strategy called Net Unrealized Appreciation (NUA). When structured properly, NUA allows the appreciation on employer stock to be taxed at long-term capital gains rates instead of ordinary income rates. However, this is a one-time decision tied to specific triggering events like separation from service. If missed or executed incorrectly, the opportunity is typically lost.

Timing matters. A difference of a few months can impact:

  • Equity vesting outcomes
  • Tax exposure
  • Retirement strategy

Transitions should be structured in advance, not figured out afterward.

QFor EOG Resources employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?

For EOG professionals, retirement planning often happens later than it should. Not due to lack of resources, but because income has been strong. Planning should include:

  • Converting assets into a structured income strategy
  • Managing tax exposure across account types
  • Reducing concentration in company or sector exposure
  • Coordinating Social Security and withdrawals
  • Maintaining lifestyle flexibility

The shift is from “Can I retire?” to “How do I want to live, and how do I fund that efficiently?”

QFor EOG Resources employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?

The need usually appears when decisions become more complex and more impactful. For EOG professionals, that includes:

  • Managing multiple income streams
  • Coordinating tax strategy
  • Allocating high earnings efficiently
  • Reducing concentration risk
  • Structuring retirement income

The value is not just investment management. It’s confident strategy, coordinated decisions, collaborative guidance, time optimization, and disciplined implementation.

QWhat are some of the unique financial planning challenges you commonly see among your clients who are EOG Resources employees and how do you help them overcome these obstacles?

EOG professionals often face:

  • Income variability tied to performance
  • High earnings that can mask inefficiencies
  • Concentration in the energy sector
  • Underutilization of advanced tax strategies
  • Delayed planning due to strong income

The real risk is unstructured income. Earning well without a clear plan for how it’s allocated, invested, and used over time.

QWhat questions do you recommend EOG Resources employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?

EOG professionals should ask:

  • Are you a fiduciary?
  • How are you compensated?
  • Do you charge a flat fee or a percentage of assets?
  • How do you integrate tax strategy with investing?
  • How do you handle equity compensation?

Fee structure matters. It determines whether advice is aligned, transparent, and built on trust.

QIs there anything that comes up frequently in your initial meeting with EOG Resources employees that surprises you?

What surprises me most is how often high earners feel uncertain despite doing many things right. Another common theme is excess cash accumulation during strong income years, which delays investment decisions. Once structure is introduced, clarity follows quickly.

QFor highly compensated EOG Resources employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

Highly compensated EOG professionals often have:

  • Performance-based compensation
  • Equity awards
  • High tax exposure
  • Access to advanced savings strategies

Planning should focus on:

  • Tax management across years
  • Roth and after-tax strategies
  • Brokerage account construction
  • Equity and sector diversification

The opportunity is meaningful, but it only works when it’s structured with intention and follow-through.

QIs there a particularly memorable experience or a moment you recall with a client who worked at EOG Resources when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?

The most memorable moments working with EOG professionals aren’t just about hitting a number. They’re about defining what “enough” means. Many have high incomes and equity compensation but lack clarity about how it’s all being allocated and coordinated. Once income, investments, and tax strategy are aligned around how they want to live, everything changes. Clarity replaces uncertainty. Confidence replaces hesitation.

Considering a financial advisor who specializes in working with EOG Resources Employees?

Are you a financial advisor who specializes in working with employees at EOG Resources or another large company?

✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at EOG Resources or another large company. (Subject to availability and terms.)
✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender

Ask a Financial Advisor Your EOG Resources Benefits & Career Questions


Are you ready to enjoy life more with less money stress?

Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.

  • This field is for validation purposes and should be left unchanged.

About the Author

Brian Thorp, Founder and CEO of Wealthtender and Editor-in-Chief

Brian Thorp

Founder & CEO, Wealthtender  ·  Editor-in-Chief

Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.

A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.

Brian and his wife live in Austin, Texas.

Read Brian’s full bio →   ·   Connect on LinkedIn →

What this article covers

Your first round of client reviews was a meaningful accomplishment — and it put you ahead of the 90% of advisors who still haven’t asked. But if you’ve been coasting on that initial effort, your review profile may be quietly falling behind, even as your client relationships continue to grow stronger. Reviews age. Prospects notice. Search engines and AI tools weight recency. This guide explains why ongoing review outreach matters more than most advisors realize, why wealth management requires a different cadence than the transactional professions that have been doing this longer, and how to build a sustainable, compliant process — including two ready-to-use email templates and a CRM and AI meeting tool workflow — that keeps fresh reviews flowing in year after year.

Congratulations. You did something the majority of financial advisors still haven’t done: you invited your clients to write reviews. You drafted the email, cleared it with compliance, hit send, and watched your glowing testimonials begin to roll in. That was a meaningful step, and it put you ahead of 90% of advisors still sitting on the sidelines.

But your first round of reviews was just the opening chapter. If you’ve been coasting on that initial effort without a plan for what comes next, your review strategy may be quietly falling behind, even as your client relationships continue to grow stronger every year.

In this article, we’ll explain why ongoing review outreach matters, why wealth management presents a unique set of challenges compared to other professions that have been doing this longer, and how you can build a sustainable, compliant, and client-friendly process for keeping your review profile fresh year after year.

Key Takeaways

1

Asking for reviews once is not enough — ongoing outreach is essential.

A single round of review invitations is a great start, but reviews age over time. Advisors who treat review outreach as a one-time campaign risk their review profile getting stale, reducing SEO/AEO benefits and costing them credibility with prospects who look to recent reviews for social proof.

2

Wealth management requires a different review cadence than transactional professions.

Unlike doctors or lawyers who can tie review requests to discrete appointments or case closings, financial advisors serve clients in an ongoing relationship with no natural finish line. This makes it critical to identify recurring, relationship-driven moments — like annual client meetings or firm anniversaries — to re-invite clients to share their experience compliantly and gracefully.

3

Building review outreach into your CRM and annual meeting process turns it from a chore into a habit.

Advisors who systematize their review outreach — using CRM automation, AI meeting tools, and annual client touchpoints — generate a steady, compliant stream of new reviews without it feeling awkward or burdensome for clients. The key is consistency: a modest but regular flow of fresh reviews is far more valuable than an occasional spike.

Why Financial Advisors Need to Ask Clients for Reviews More Than Once

When you sent your first-round review invitations, you were thinking about a moment. What most advisors don’t anticipate is that reviews, like any content, have a shelf life.

Across any type of business, consumers don’t just count reviews they look to see when they were written. Research in the legal profession has found that recency of reviews is one of the most important factors in how much weight prospective clients assign to them. The same behavioral tendency, albeit to a lesser degree given the long-term nature of advisor/client relationships, could be expected when evaluating financial advisors as well.

Think about it from a prospect’s perspective. You’re considering working with an advisor and you pull up their Wealthtender profile. You see eight glowing reviews, all from three years ago. Compare that to an advisor with five reviews, three of which are from the past six months. Who feels more active, more trusted, more current? Almost always, the latter.

Beyond consumer perception, there is a practical SEO and answer engine optimization (AEO) argument as well. Search engines and AI tools that power recommendation engines give greater weight to businesses with consistent, recent review activity. A profile that continues to earn reviews over time is a profile that continues to earn the greatest visibility.

The conclusion is simple: your first round of reviews built a foundation. But building the structure on top of that foundation requires an ongoing commitment.

Why the Doctor and Lawyer Playbook Doesn’t Fully Apply to Financial Advisors

To understand why ongoing review outreach feels harder for wealth managers than for other professions, it helps to look at how doctors and lawyers handle it because they’ve had much more time to develop their playbooks. While both professions, like financial advisors, survive and thrive based on consumer trust, there are differences worth noting.

A physician’s practice is inherently transactional in cadence. Every appointment is a discrete event and a natural moment of reflection that lends itself to an immediate ask. A patient finishes their visit, feels grateful for the care they received, and receives a follow-up text or email asking them to share their experience. The review request matches the moment.

Law firms face similar dynamics. As one legal marketing guide describes it, review requests work best “within one to two weeks after case closure, when details are fresh and positive emotions are still present.” The end of a legal matter creates a moment of resolution and relief, a natural trigger for asking a client to reflect on their overall experience.

Wealth management is different in a fundamental way: there is no finish line. Your client relationship doesn’t end with a discharged diagnosis or a closed case. It is, by design, an ongoing relationship intended to span years, decades, and in many cases, generations. That’s the beauty of what you do, and it’s also what makes the review ask more complex.

When you invite a longtime client to write a review, they’re not reflecting on a single interaction. They’re reflecting on the entirety of a relationship that may include bull and bear markets, major life transitions, estate planning conversations, and the quiet reassurance of knowing someone is looking out for their financial future. That’s a richer, deeper experience to articulate, and that’s actually a good thing for the quality of reviews you’ll receive. But it means the “timing” question is less obvious than it is for a doctor or a lawyer.

There is an additional wrinkle specific to wealth management: the question of what to do about clients who have already written a review. This creates a real tension. You want to keep your review profile fresh. But you don’t want to create awkward pressure for a client who already came through for you once. And from a compliance standpoint, you remain obligated to avoid cherry-picking which means your approach to ongoing outreach needs to remain systematic and consistent, not targeted at select clients.

How Financial Advisors Should Structure Ongoing Review Outreach

Given these dynamics, how should advisors think about reigniting and sustaining their review efforts over time? The answer lies in shifting from a campaign mindset to a culture mindset.

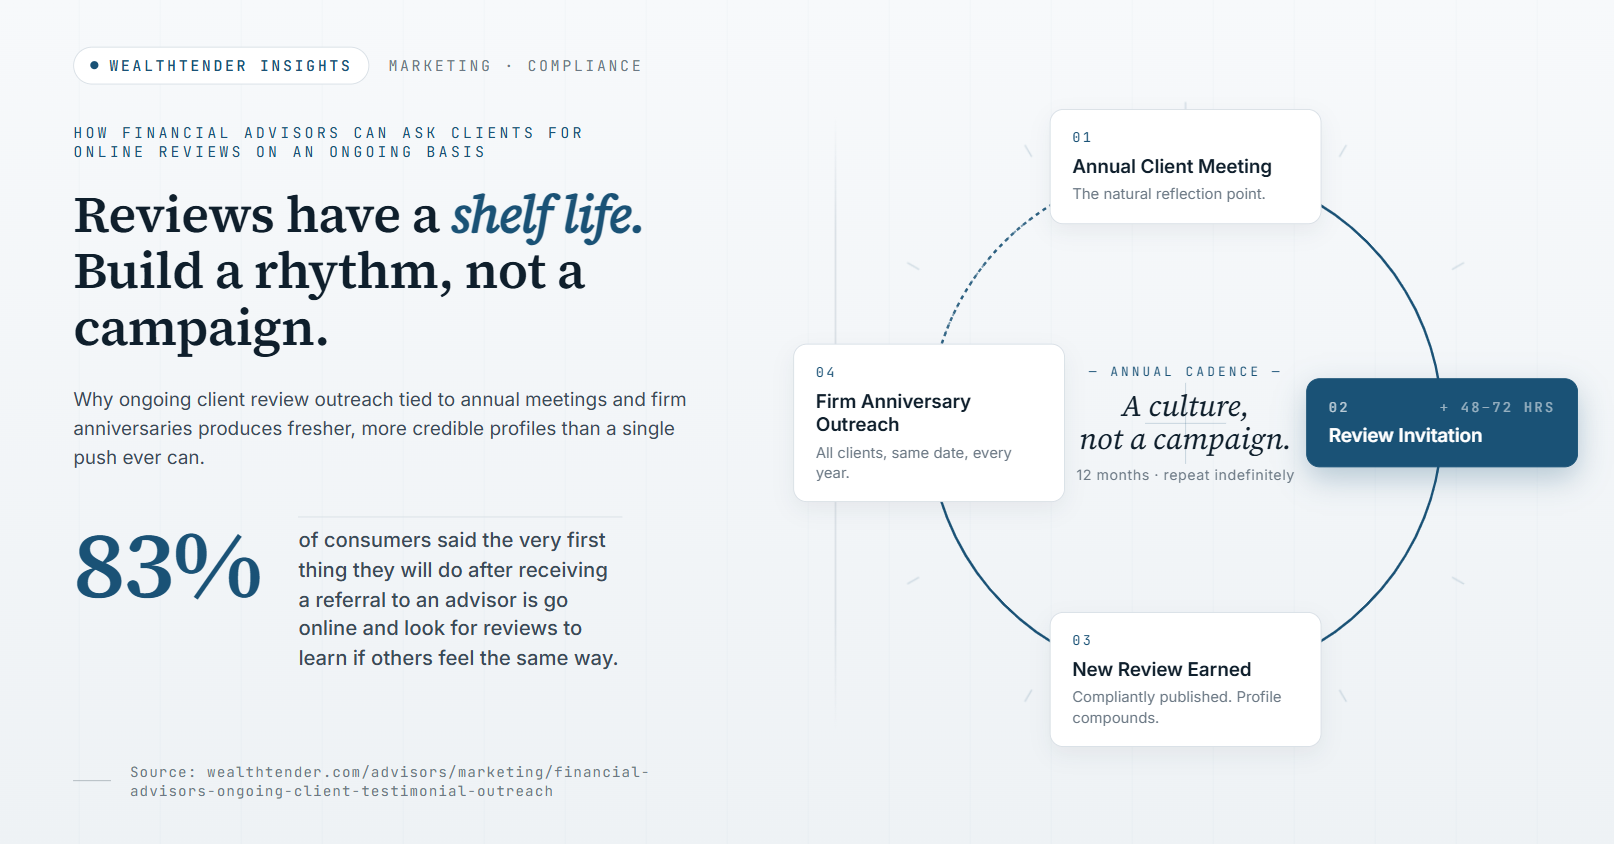
A campaign is something you launch, run, and conclude. A culture is something you embed in your workflows, your team habits, and your client communications. The advisors who will build the most powerful review profiles over the next five years won’t be the ones who do one big annual push. They’ll be the ones who have woven review outreach into the rhythmic fabric of how they serve clients every year.

Independent research shows why a culture beats a campaign. The 2026 Kitces Report on how advisors market their services found that 60% of advisors using review platforms proactively encourage clients to leave reviews, and that doing so appears to increase participation. Even so, among advisors who ask, the median share of clients leaving reviews peaks at about 16%. A steady, repeatable process matters more than any single request. See our breakdown of the 2026 Kitces Report for more on what the research found about reviews.

Here are two primary frameworks to consider:

Strategy 1: Send an Annual Review Invitation to All Clients

One of the most elegant solutions to the “how often do we ask?” question is the annual firm-wide invitation, a message sent to your entire client list on approximately the same date each year (for example, the anniversary of your firm).

This approach has several advantages:

  • It treats all clients equally, which is essential for demonstrating to regulators that you are not cherry-picking reviewers.
  • It establishes a predictable, firm-wide rhythm rather than an ad hoc, person-by-person approach.
  • It frames the ask as an expression of gratitude rather than a request for a favor.

The annual touchpoint also gives you a graceful way to re-invite clients who have already written a review. The message can be framed to acknowledge that some recipients may have already shared their feedback – thanking them for having done so – while gently opening the door for them to update or add to their review if their experience has continued to evolve.

Think about how this might feel to a client: you’re not asking them to repeat themselves or do something they’ve already done. You’re inviting them, if they’re willing, to share how the relationship has grown. That’s a meaningful distinction.

Strategy 2: Ask for a Review Within 48 Hours of Every Annual Client Meeting

The annual client review meeting, already a cornerstone of most advisory practices, is an ideal natural trigger for a review invitation. It’s the one moment each year when a client is most engaged with the breadth of their relationship with you, thinking holistically about their financial picture, their goals, and the progress they’ve made.

That reflective energy is precisely the mindset that produces rich, authentic reviews.

Rather than asking for a review during the meeting itself (which can feel awkward and transactional), the most effective approach is to send a brief, personal follow-up email within a few days of the meeting concluding. The timing is important: the conversation is still fresh, the client is likely in a positive frame of mind, and the ask arrives as a natural extension of the touchpoint rather than an unrelated cold request.

This approach also integrates cleanly into CRM-based workflows, which we’ll discuss in more detail below, making it something your team can execute consistently rather than something that depends on an individual advisor remembering to follow up.

Infographic about ongoing client review outreach for financial advisors. Highlights benefits like higher engagement and new reviews, with flowchart showing steps: Firm Anniversary Outreach, Annual Client Meeting, Review Invitation, and New Review Earned.

Compliant Email Templates for Asking Financial Advisor Clients to Write Reviews

The art of re-inviting clients to write reviews, especially clients who have already done so, is to make the ask feel warm, purposeful, and genuinely optional. Your work ethic and culture of compliance requires that you not pressure clients or selectively target favorable ones. Good judgment requires that you not make anyone feel obligated or uncomfortable.

The language below is designed to honor both of these principles.

Template 1: Annual Client Review Invitation Email (For All Clients, Including Those Who’ve Already Written a Review)

Template 1: Annual Firm-Wide Review Invitation

For All Clients
Subject: A thank-you from [Firm Name] — and a small favor if you’re willing
Hi [First Name], Each year around this time, I take a moment to reflect on what I’m most grateful for in this work, and without question, the trust our clients place in us is at the top of that list. Thank you for being a valued client of [Firm Name]. It’s a privilege to play a role in your financial journey, and I don’t take that lightly. As part of our ongoing commitment to transparency, we periodically invite our clients to share their experience online. These reviews help people who are searching for a financial advisor get a genuine sense of what it’s like to work with us, and they help us continue earning the trust of new clients the same way we earned yours. If you’ve written a review for us in the past, we’re genuinely grateful, and there’s no need to take any additional action unless you’d like to update or add to what you shared. If you haven’t yet written a review, we’d be truly honored if you’d consider it when you have a few minutes. Here’s a link to our profile: [Your Wealthtender Profile “Review Me” Link] It only takes a couple of minutes, and it means a great deal to us and to those who are trying to make an informed decision about their financial future. As always, please don’t hesitate to reach out with anything on your mind. We’re here for you. With gratitude, [Your Name]

Template 2: Post-Annual Meeting Review Request Email

Template 2: Post-Annual Meeting Review Request

After Client Meeting
Subject: Great catching up — one small ask when you have a moment
Hi [First Name], Thank you for the time we spent together this week. I always look forward to our annual conversations. Getting a clear picture of where things stand and thinking through what’s ahead with you is one of the most meaningful parts of this work. I have a small favor to ask, and please know it’s entirely optional. I’d be grateful if you’d consider sharing your experience in a review on our Wealthtender profile. Reviews like yours help people who are looking for a financial advisor understand what working with us is really like, and they make a real difference. Here’s a link to our profile: [Your Wealthtender Profile “Review Me” Link] If you’ve already written a review for us in the past, thank you. There’s no need to do so again unless you’d like to. And if this isn’t the right time, I completely understand. I’m just glad we had the chance to connect. Looking forward to continuing to support you and your family. Please don’t hesitate to reach out if anything comes up before we speak again. [Your Name]

How to Automate Ongoing Client Review Outreach Using Your CRM and AI Meeting Tools

Knowing what to say is only part of the equation. The advisors who succeed at ongoing review outreach are the ones who have removed the burden of remembering to do it. That means building the process into your systems, not your willpower.

Here’s how to make it systematic:

Use Your CRM to Automate Annual Outreach

Most modern CRM platforms used by advisors (including Salesforce, Redtail, and Wealthbox, among others) allow you to set recurring tasks or automated email triggers based on specific dates or relationship milestones. Configure your CRM to flag all active clients for a review outreach campaign once per year, tied to either the anniversary of your first review push or a fixed date meaningful to your firm.

Tag clients who have already submitted a review so you can customize the messaging accordingly, sending one version to first-time recipients and a subtly different, appreciative version to those who have already written one. This segmentation keeps the communication thoughtful without crossing into the territory of cherry-picking, since both messages go out to entire cohorts rather than selectively chosen individuals.

How AI Meeting Tools Like Jump.ai and Zocks Can Automate Your Review Follow-Ups

AI-powered meeting and note-taking tools like Jump.ai, Zocks, and others are transforming how advisors capture and act on client meeting insights. These tools don’t just summarize conversations, they can trigger post-meeting workflows based on what was discussed.

If your firm uses one of these tools, work with your team to configure a workflow that adds a review follow-up task to the advisor’s queue whenever an annual review meeting is logged. The task can include a pre-drafted email template (like Template 2 above) that the advisor can review, lightly personalize if desired, and send with minimal friction.

This approach accomplishes something important: it turns review outreach from something advisors have to remember to do into something the system prompts them to do. That’s the difference between a process and a culture.

Assign Ownership: Who on Your Team Is Responsible for Review Outreach?

Just as healthcare practices train their front-desk staff to request reviews as a natural part of the checkout process, advisory firms benefit from making review outreach a team responsibility rather than a solo advisor task. Designate someone, whether an operations coordinator, a client service associate, or a marketing lead, as the person accountable for ensuring the annual outreach goes out on schedule and that post-meeting follow-ups are sent within a defined window (ideally within 48 to 72 hours of the meeting).

Track it as you would any other business metric. How many review invitations went out this year? What’s the response rate? How many new reviews were added to the profile? Giving the process the same visibility you give other growth metrics ensures it doesn’t slip through the cracks during busy stretches.

Lessons From Doctors and Lawyers on Building a Consistent Review Culture

Doctors and lawyers have had years of practice building review cultures and there are lessons worth borrowing.

The most important one is this: consistency matters more than volume. Legal marketing research consistently finds that a modest but steady flow of reviews is more valuable to online visibility and consumer trust than a large spike followed by a long silence. The same logic applies for financial advisors. Ten thoughtful reviews added across the course of a year do more for your profile than thirty collected in January and nothing thereafter.

The second lesson is about framing the ask around the relationship, not the transaction. Law firms that have cracked the code on ongoing review outreach have learned to invite clients to share how it felt to work with them, the communication, the responsiveness, the sense of being cared for, rather than asking them to narrate specific outcomes or case details. That reframe makes the ask feel less vulnerable and more genuine.

For financial advisors, this is especially resonant. You’re not asking a client to describe their portfolio returns. You’re inviting them to share what it feels like to know that someone is helping them navigate the complexity of their financial life with care and expertise. That’s a story most clients are happy to tell, if you give them an easy, comfortable way to do it.

How Wealthtender Helps Financial Advisors Collect Reviews Compliantly and Consistently

Building an ongoing review culture is only valuable if it’s built on a compliant foundation. That’s where Wealthtender’s platform is purpose-built to support you.

Unlike general consumer review platforms which lack the infrastructure to address the SEC Marketing Rule’s prohibitions and disclosure requirements, Wealthtender’s Certified Advisor Reviews™ are designed from the ground up with regulatory compliance in mind. That means:

  • Required disclosures are built into the review display, ensuring that reviews you promote meet the SEC’s disclosure requirements for testimonials and endorsements.
  • A compliant review collection process helps you demonstrate to regulators that you are inviting reviews broadly and consistently, not cherry-picking favorable clients.
  • A profile that compounds over time, so every new review you collect builds on the ones before it, deepening your profile’s credibility and visibility with consumers, search engines and AI answer engines.

If you’re just getting started with testimonial marketing or want to understand how Wealthtender can support your ongoing strategy, we invite you to explore our Ultimate Advisor Guide to Testimonial Marketing and our SEC Marketing Rule guide to asking for testimonials.

The first round of reviews was your beginning. With the right process in place, the next round, and every one after it, can become one of the most valuable habits you build as a marketer and as a trusted advisor to the clients who count on you.

This article is for informational purposes only. Nothing herein constitutes legal, compliance, or investment advice. Financial advisors should consult with their compliance team and legal counsel before implementing any review outreach strategy.

Want to see how individual advisors and leading wealth management firms are successfully using Wealthtender to grow their business? Visit Wealthtender.com/grow or schedule a demo to learn how you can start converting more prospects into clients with the industry’s first digital marketing platform for AI-optimization and compliant online reviews.
Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

What this article covers

Discover financial advisors trusted by residents of Bellingham, Washington in the only local directory featuring 5-Star Certified Advisor Review™ recipients and Wealthtender Voice of the Client Award™ winners, recognition earned for exceptional client feedback. Compare fiduciary, fee-only advisors, CFP® professionals, and specialists to find the right fit for your unique financial needs.

Financial Advisor Directory for Bellingham, Washington

📍 Map: Financial Advisors with their Primary Office Location in Bellingham

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Bellingham.

📍Double-click or pinch pins to view more.

Showing

Key Takeaways

1

You can compare Bellingham financial advisors by credentials, specialty and verified client reviews before you contact anyone.

The map shows advisors whose primary office is in Bellingham. Profiles include Certified Advisor Reviews™, designations such as the CFP® and the services each advisor offers.

2

Bellingham’s border economy, university and hospital jobs, and river flood risk shape the planning help many residents need.

Local businesses that depend on Canadian shoppers saw sharp declines in border crossings in 2025, and families with Canadian bank accounts may have U.S. reporting duties. Western Washington University and St. Joseph Medical Center employees face retirement plan elections with firm deadlines, and the 2021 Nooksack River flood is a reminder that flood coverage is separate from homeowners insurance.

3

Interview more than one advisor and confirm how each one is paid.

Ask about services, fees and whether the advisor acts as a fiduciary, then check their background for free on the SEC’s Investment Adviser Public Disclosure website before you hire.

Financial Planning Considerations for Bellingham Residents

Every city has its own financial landscape. Here are a few local factors worth discussing with a Bellingham financial advisor.

A border economy tied to Canadian visitors

Whatcom County’s retailers, hotels and gas stations rely heavily on shoppers from British Columbia. The director of Western Washington University’s Border Policy Research Institute told the Bellingham City Council in December 2025 that crossings fell every month after January 2025, typically by 30% to 50%, and that a summer survey found more than half of local businesses had suffered losses. Business owners here may want larger cash reserves and a retirement savings plan that doesn’t depend on one strong season.

Accounts on both sides of the border

Many Bellingham families have work, property or relatives in Canada. If you’re a U.S. person with a financial interest in or signature authority over foreign accounts, such as a Canadian bank account, and their combined value exceeded $10,000 at any time during the year, the IRS says you must file an FBAR (FinCEN Form 114) electronically with FinCEN, separate from your tax return. Cross-border households often benefit from an advisor and tax preparer who handle both countries’ rules.

University and hospital retirement choices

St. Joseph Medical Center and Western Washington University are Whatcom County’s two largest employers. At WWU, faculty choose between TRS Plan 3 and the WWU Retirement Plan, professional staff between PERS Plan 3 and the WWU plan, and classified staff between PERS Plans 2 and 3. Faculty and professional staff have 30 days to decide (classified staff have 90), and WWU says elections can’t be changed while you work there. Faculty and professional staff who don’t choose are enrolled in the WWU plan.

Nooksack River flooding

On November 14, 2021, the Nooksack River flooded Everson, Nooksack and Sumas, with Whatcom County damage estimated at up to $50 million. Standard homeowners policies don’t cover flooding, and FEMA notes a flood policy usually has a 30-day waiting period before it takes effect. FEMA also reports that about a third of National Flood Insurance Program claims from 2013 to 2023 came from outside high-risk flood areas, so it’s worth pricing coverage even if your lender doesn’t require it.

The Benefits of Hiring a Financial Advisor in Bellingham

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Bellingham, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Who are the largest employers in the Bellingham area?

Whatcom County’s largest employers are led by health care, higher education, local government and the Lummi Nation, based on self-reported headcounts countywide.

  1. St. Joseph Medical Center (PeaceHealth) 3,588 employees
  2. Western Washington University 2,486 employees
  3. Bellingham Public Schools 1,714 employees
  4. Lummi Nation 1,698 employees
  5. City of Bellingham 1,073 employees
  6. Whatcom County 959 employees
  7. Whatcom Community College 832 employees
  8. Haggen 715 employees
  9. BP Cherry Point 700 employees
  10. LTI, Inc. 557 employees
  11. Family Care Network 545 employees
  12. Whatcom Educational Credit Union (WECU) 419 employees

Work for one of these companies or another large employer? Explore our employer Q&As for advice on making the most of your benefits.

Source: Western Washington University Center for Economic and Business Research, 2023 Whatcom County Top Employers List (April 2024). Headcounts are as of December 31, 2023, except Lummi Nation, Whatcom Community College, Haggen and BP Cherry Point (2022 data) and LTI, Inc. (2021 data). Figures are self-reported, and not every employer chose to participate.

Do you work for one of the largest employers in Bellingham? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Types of Financial Advisors You’ll Find on Wealthtender

Thousands of people visit Wealthtender each month to find and compare financial advisors based on their location, education, experience, areas of specialization and online reviews. Wealthtender’s Certified Advisor Reviews™ help consumers make informed hiring decisions with important details about the relationship between reviewers and advisors always displayed to ensure you gain the transparency you deserve when your life savings could be at stake.

On Wealthtender, you can explore a diverse range of financial advisors and wealth management firms that include:

  • Fiduciary advisors committed to acting in clients’ best interests
  • CFP® professionals with advanced financial planning credentials
  • Fee-only advisors compensated solely by clients
  • Advisors for growing families, people nearing retirement, and business owners
  • Specialists across multiple categories (e.g., life stage, occupation, ethnicity, lifestyle, religion)
  • Highly-rated advisors with positive client reviews
  • Firms of varying sizes with advisors who can meet with you in person or online
  • Fee-based advisors who offer access to insurance and alternative investments

How to use this directory: Compare financial advisors in the Bellingham area based on what matters most to you. Use the directory to:

  • View advisor profiles to evaluate credentials, services, and areas of specialization
  • Read Certified Advisor Reviews™ to learn what clients value most
  • Identify advisors recognized with Wealthtender Voice of the Client Awards™
  • Contact advisors and schedule free introductory video calls

Wealthtender Voice of the Client Awards™: Top Rated Bellingham Financial Advisors

Wealthtender Voice of the Client Awards™ recognize financial advisors and firms that consistently earn exceptional client feedback. Below are Bellingham-area advisors and firms that have met the criteria for Highly Rated recognition.

Firm/Advisor Firm City State Voice of the Client Award Website

To qualify for a Highly Rated award, advisors and firms must achieve an average client review rating of 4.75 or higher (on a scale of 1 to 5) based on a minimum number of eligible client reviews published on Wealthtender within a defined timeframe for each particular award (Timeframe for 2025 Award: 1/1/24 – 12/31/25; Timeframe for Subsequent Year Awards: July 1 of the preceding year through December 31 of the Award Year (e.g., Timeframe for 2026 Award 7/1/25 – 12/31/26). Eligible reviews are limited to clients (as of the review submission date) that advisors/firms must self-attest have no material conflicts of interest and received no compensation in exchange for their reviews. ↗️ View full award methodology & FAQs

Although financial advisors and wealth management firms compensate Wealthtender for marketing services (including eligibility to be considered for awards), Wealthtender’s award criteria is objective and not influenced by compensation. Wealthtender Voice of the Client Awards are not a guarantee of future performance or success and client reviews may not be representative of the experience of all past or future clients.

Quick Tips For Hiring a Bellingham Financial Advisor

Before hiring a financial advisor in Bellingham, here are a few quick tips to help you find the best advisor for you.

1

Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor who specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2

Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3

Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4

Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.

Frequently Asked Questions

What makes a financial advisor “trusted”?
A trusted financial advisor typically earns positive client feedback over time, operates transparently, and clearly explains how they’re compensated. On Wealthtender, trust is reflected through Certified Advisor Reviews™ that combine insights into the client experience and character of advisors with important disclosures about each reviewer to ensure you gain the transparency you deserve when your life savings could be at stake.

Financial advisors and wealth management firms that consistently receive superior client reviews can also qualify for Wealthtender’s Voice of the Client Awards™ designed to recognize America’s most trusted advisors. Learn More About Wealthtender Voice of the Client Awards™
What are Certified Advisor Reviews™?
Certified Advisor Reviews™ from Wealthtender help consumers make smarter hiring decisions when choosing a financial advisor.

Clients and other individuals can submit reviews for financial advisors and wealth management firms that have turned on the reviews feature. Before each review is publicly displayed, financial advisors agree to disclose important information about their relationship with the reviewer to ensure consumers gain the transparency they deserve when their life savings could be at stake. These disclosures also help financial advisors satisfy compliance with industry regulations.

After financial advisors provide the required disclosures, Wealthtender publishes the review with the Certified Advisor Review™ mark. Learn More About Certified Advisor Reviews™
Can I find fiduciary financial advisors on Wealthtender?
Yes, you’ll find hundreds of fiduciary financial advisors on Wealthtender. Fiduciary financial advisors must act in their clients’ best interest. Before hiring an advisor, always ask if they will act in your best interest as a fiduciary.

For example, financial advisors who have earned their Certified Financial Planner (CFP) designation are fiduciaries. To hold themselves out as a CFP, these credential holders must acknowledge they will adhere to the CFP Board’s Code of Ethics and Standards of Conduct and act as a fiduciary when providing financial advice to their clients. Learn More About Fiduciary Financial Advisors
Can I find fee-only financial advisors on Wealthtender?
Yes, you’ll find hundreds of fee-only financial advisors on Wealthtender. Fee-only financial advisors are paid directly by their clients. Since they aren’t compensated based on the products and services they recommend (e.g., commissions), their compensation model helps reduce potential conflicts of interest.

When viewing financial advisor profiles on Wealthtender, look for the Compensation Methods section that shows ways each financial advisor can be paid for their services, including if they offer fee-only financial planning services. Learn More About Fee-Only Financial Advisors
What distinguishes Wealthtender Voice of the Client Awards™ from other advisor recognition programs?
Wealthtender’s Voice of the Client Awards™ recognize financial advisors and wealth management firms that consistently receive superior client reviews. Unlike award programs with ranking factors that favor financial institutions with the most assets and the fastest revenue growth, the Wealthtender Voice of the Client Awards provide both local financial advisors who choose to remain small and large wealth management firms with the opportunity to be recognized on a metric that matters more to consumers – actual client feedback reflecting the quality of their experience. Learn More About Voice of the Client Awards™
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit. But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a Bellingham financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Learn how to get featured

Please note: Wealthtender may be compensated by financial advisors featured on our site and within this guide. Learn more about how we operate with integrity to earn your trust.

Watch

How Much Does a Financial Advisor Cost?

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

Knowing your net worth in real time isn’t just satisfying; research consistently shows that people who actively track their wealth make better financial decisions, stay on budget more reliably, and build toward financial goals faster. Whether you’re just starting out or managing a complex portfolio across multiple brokerages, the right wealth tracker can be the single tool that brings everything into focus.

Pearson’s Law states: “When performance is measured, performance improves. When performance is measured and reported back, the rate of improvement accelerates.”

So, if you’re working toward a financial goal, tracking your progress will help you achieve it quicker! The hard part is finding an efficient way to do it.

That’s where wealth tracker apps and websites come in to help you know your net worth and achieve your goals. These useful tools aggregate info from your various accounts and allow you to monitor (and manage) everything from your income and expenses to your investments – all from a single dashboard. Making informed financial decisions and hitting those big money goals becomes much easier as a result.

Want to find one that’s right for you? Keep reading to discover 7 of the best wealth trackers available today.

Key Takeaways

1

Tracking your net worth accelerates wealth-building — not just awareness.

Research supports what Pearson’s Law describes: when you measure financial performance and regularly review it, improvement accelerates. Wealth tracker apps automate the aggregation of your accounts into a single dashboard, making consistent monitoring effortless rather than a manual chore.

2

The best wealth tracker depends on what financial visibility you actually need.

Beginners benefit most from budgeting-first tools like YNAB, while those who want a comprehensive view of spending and net worth together will find all-in-one platforms like Monarch Money or Empower ideal. Advanced investors with complex, diverse portfolios may prefer the deeper tracking capabilities of Kubera. Knowing what you need most — budgeting, net worth tracking, investment analytics, or all three — is the right starting point for choosing a tool.

3

Free tools can get you started, but paid options deliver meaningfully more insight.

Several apps on this list offer free tiers — including Empower and PocketSmith — but their most powerful features (investment analytics, multi-account sync, long-range financial projections) typically require a paid plan. Given that most premium wealth trackers cost less than $150/year, the ROI on better financial decisions usually far outweighs the subscription cost.

What Is a Wealth Tracker App and Why Does It Matter?

A wealth tracker app is a digital tool that connects to your financial accounts (e.g., bank accounts, investment portfolios, retirement funds, loans, and more) and aggregates everything into a single, unified dashboard. Instead of logging into five different apps or building a spreadsheet from scratch, you get a real-time snapshot of where you stand financially, including your total assets, liabilities, and net worth.

Net worth is one of the most important numbers in your financial life, yet most people have only a vague sense of what it actually is. Your net worth, the difference between everything you own and everything you owe, is the clearest measure of whether your financial life is moving in the right direction. Wealth tracker apps make that number visible, trackable, and actionable rather than something you calculate once a year (if at all).

Beyond the snapshot, the best wealth tracker apps and websites reveal patterns you’d otherwise miss: spending categories quietly eating into your savings, investment accounts drifting out of alignment with your goals, or retirement projections that suggest you need to course-correct sooner than you thought. Used consistently, these tools don’t just tell you where you are, they help you get to where you want to be.

Stay connected

See more of Wealthtender when you search Google

Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.

1. Betterment

Want to track your wealth and invest at the same time? Try Betterment, the “all-on-one financial dashboard.” The app’s a roboadvisor – a digital financial advisor that manages your investing accounts (Betterment restricts you to investing in exchange-traded funds, or ETFs) depending on your goals and risk tolerance. However, you can also sync your bank accounts to enjoy a birds-eye view of your finances, set goals, and track your saving/investing progress.

There are two service tiers: Digital and Premium. Choose the former if you’re on a budget and investing less than $100k. There’s no minimum to get started, and the annual advisory fee is 0.25%.

2. Empower

Empower (previously called Personal Capital) is another popular and widely-used wealth tracker that comes highly recommended online. Empower is powerful, versatile, and has many impressive free-to-use tools – as well as a paid wealth management service for those who need/want it.

After signing up, you can link your financial accounts (e.g., bank, credit cards, savings, loans, investing, retirement, etc.) to get a real-time look at your net worth. You can then monitor cash flow, set budgets, and leverage many other special tools, including a Savings Planner, Retirement Planner, and Fee Analyzer. The fact you get so much for free is a huge selling point.

Empower
Empower Whatever your financial happiness looks like, let’s help get you there.
Compensation Methods
Fee Based

Empower | Empower

3. Kubera

Self-billed as “the world’s most modern wealth tracker,” Kubera is an advanced portfolio-tracking app that offers a near-limitless number of bank connections and detailed insights on your investments.

It’d be ideal for someone with a large and diverse portfolio – even if it includes international holdings. Kubera tracks all of your assets in one place and shows their current and estimated resale value, making monitoring your net worth over time straightforward.

Take note, though: unlike other wealth trackers with a diverse range of tools, Kubera has a heavy investment focus. Likewise, there’s no free plan. Once the 14-day $1 trial is over, you’ll pay $150 per year.

4. Monarch Money

If Mint’s shutdown left a gap in your financial toolkit, or if you’ve never found a personal finance app that truly brings everything together, Monarch Money may be exactly what you’re looking for. Launched in 2021 and now widely regarded as the leading all-in-one personal finance platform in the post-Mint era, Monarch combines account aggregation, net worth tracking, budgeting, and investment monitoring in a single, polished dashboard.

What sets Monarch apart is its balance of depth and usability. Connect your bank accounts, credit cards, investment portfolios, loans, and retirement accounts, and you get a real-time picture of your complete financial life, not just one slice of it. The budgeting tools are intuitive without being rigid, the net worth tracker updates automatically as balances change, and a collaborative feature makes it particularly well-suited for couples managing finances together.

Monarch is available on both iOS and Android and is priced at $99.99 per year (or $14.99 per month billed monthly). There’s no permanent free tier, but a 30-day free trial gives you time to evaluate it before committing. For anyone who wants a comprehensive, beautifully designed tool that moves beyond basic budgeting into genuine wealth visibility, Monarch Money belongs near the top of your list.

5. PocketSmith

PocketSmith is an easy-to-use personal finance software that helps users with money management, cash flow forecasting, and personal budgeting.

There’s a lot to like, but one highlight is the info it provides on your future financial situation based on your current spending habits and earnings. This glimpse of what’s to come should compel positive financial action in the present.

The fact that PocketSmith offers a free plan is a bonus, although its features are quite limited. If you wish to connect your accounts to a single dashboard (for the most accurate wealth tracking) and enjoy financial projections well into the future, you’ll need to pay for a premium plan.

A person seated in a modern chair, casually dressed in a white shirt and pink pants, scrolling through a smartphone with focused attention.
Image Credit: Depositphotos.

6. Tiller

Calling all spreadsheet fans and aficionados! Tiller could be the best wealth tracker for your needs. Like Microsoft Excel on steroids, this tool syncs to your financial accounts and imports real-time data to robust, highly customizable spreadsheet templates. That means no more manual data entry – unless you choose to edit certain fields or set custom rules!

Among other elements, the basic template offers a net worth tracker and a breakdown of your annual budget. However, many others are available, such as a template for retirement planning and another for debt reduction. Try Tiller for free on a 30-day trial, after which you’ll pay $79 annually.

7. YNAB

Short for “You Need a Budget,” YNAB is a fantastic tool that helps users budget, pay down debt, and manage money more effectively. It’s a great wealth tracker for beginners, with a program that revolves around four basic rules:

  1. Give every dollar a job – be intentional with money, allocating everything you earn to specific expenses based on your financial priorities.
  2. Embrace your true expenses – handle larger but less frequent expenses more easily by breaking them into smaller bills that you save for each month.
  3. Roll with the punches – forget rigid budgets and simply move money from less important budgeting categories when you overspend elsewhere.
  4. Age your money – spend less than you earn, watch your money accumulate, and start buying things today with money you earned in the past.

After a ~30-day free trial, you’ll need to pay for a subscription. This costs $14.99 per month or $98.99 per year. 

Choose From This List of the Best Wealth Trackers to Know Your Net Worth

As Pearson’s Law points out so eloquently, tracking your progress is crucial to moving in the right direction and achieving goals sooner rather than later. That’s why it pays serious dividends – sometimes quite literally – to use a wealth tracker in your bid to budget, save, and invest as effectively as possible!

If you’ve been hunting for the best tracking tool, we hope this list has helped. Whether you’re an advanced investor with a vast and diverse portfolio or someone brand new to the pursuit, there should be a service here to suit your needs.

Author Bio

Danny Newman is a nationally syndicated freelance writer with a focus on travel. MSN feed and Associated Press bylines. Danny is a digital nomad from the UK who’s been traveling full-time since 2018. Learn More About Danny.

Find Financial Advisors on Wealthtender

📍 Click on a pin in the map view below for a preview of financial advisors who can help you reach your money goals and enjoy a comfortable retirement with a personalized plan. Or choose the grid view to search our directory of financial advisors with additional filtering options.

📍Double-click or pinch pins to view more.

Showing

–

Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

Frequently Asked Questions

How do I calculate my net worth?

Add up the value of everything you own, such as cash, investments, retirement accounts, your home and vehicles, then subtract everything you owe, such as mortgages, car loans, student loans and credit card balances. The result is your net worth. Tracking your net worth over time shows whether your overall financial position is improving.

Are net worth tracker apps safe to use?

Reputable apps typically use encryption and connect to your accounts through secure data aggregators, often with read-only access that cannot move money. Still, you are sharing sensitive data, so use strong unique passwords, turn on two-factor authentication and review each app’s privacy policy to see how your data is stored and used.

What happened to Mint, and what can I use instead?

Intuit discontinued the standalone Mint app and moved its users to Credit Karma, which now offers spending and net worth tracking. Former Mint users who want deeper budgeting or investment tracking often switch to tools such as Monarch Money, Empower, YNAB or PocketSmith.

How often should I check my net worth?

For most people, updating net worth monthly or quarterly is enough to spot trends without overreacting to normal market swings. Apps that sync automatically make it easy to check more often, but the long-term direction matters more than any single snapshot.

Danny Newman

About the author

Danny Newman

Contributing Writer, Wealthtender

Danny Newman is a nationally syndicated freelance writer with a focus on travel. MSN feed and Associated Press bylines. Danny is a digital nomad from the UK who’s been traveling full-time since 2018.

He writes about travel tips, planning, adventures, and escaping the rat race on his travel/lifestyle site What’s Danny Doing.

April 20, 2026

If you’ve been watching AI dominate headlines and wondering whether you’re positioned to actually benefit from it, you’re not alone. Most high-income investors have exposure to AI through a handful of large-cap tech stocks. That’s a start, but it’s a narrow slice of one of the most significant economic expansions of our lifetime. The global AI market is on track to grow from roughly $376 billion this year to more than $2.4 trillion by 2034. The opportunity isn’t just in the companies everyone already owns.

Most investors are still playing the same crowded trade. NVIDIA, the dominant force in AI computing, has become the default bet, with Wall Street analysts continuing to raise the ceiling. Consensus estimates project Nvidia’s revenue to jump roughly 48% in fiscal 2027, and some analysts believe the stock could approach double its current price if earnings growth accelerates as expected. The enthusiasm is understandable. North America alone captured nearly one-third of the global AI market in 2025, and this giant sits squarely at its center.

But here’s the question serious investors should be asking: if enthusiasts already own Nvidia, where’s the edge? 

For example, cloud deployment now accounts for more than 71% of the AI market share, growing at a projected rate of 30.7% annually. And the infrastructure powering that cloud buildout is where the real leverage may lie. The AI opportunity goes beyond computing itself. It’s the physical and digital backbone that makes an entire ecosystem operate at scale: data centers, power supply, networking, and cooling. These are the unsexy picks that investors aren’t always talking about at dinner parties, which might be exactly why they’re worth a closer look.

AI Runs on Power, and That’s a Problem

Once you start looking beyond the headlines, one constraint becomes hard to ignore: AI doesn’t just run on innovation; it runs on electricity.

Every query, model, and automation tool relies on data centers working around the clock. And those facilities are power-hungry in ways most people haven’t thought about. A typical AI-focused data center consumes as much electricity as 100,000 households annually, and the largest ones currently under construction are expected to use 20 times that amount. U.S. data centers consumed 183 terawatt-hours of electricity in 2024, more than 4% of the country’s total, and that figure is projected to more than double by 2030.  

According to Bloomberg, a confluence of factors is placing significant strain on power grids worldwide, creating a tangible drag on economic growth. And according to Pew Research, everyday Americans are shouldering the cost in their power bills. In the PJM electricity market, which stretches from Illinois to North Carolina, data centers contributed to an estimated $9.3 billion increase in capacity market pricing.

I’ve been paying attention to this for a while. 

There’s genuine debate about how to solve the energy problem, and some of it gets political fast. But set the politics aside, and the underlying dynamic is straightforward: demand for a critical resource is outpacing the infrastructure supporting it. That gap is where investment opportunities tend to emerge.

What “Investing in the Grid” Actually Means

When I talk about investing in the grid, I’m not talking about chasing a theme or picking the next AI stock. I’m talking about owning the assets that make AI possible. That includes data centers, power generation, transmission infrastructure, and fiber networks. 

These are physical, capital-intensive assets built to support sustained, long-term demand. And the scale of that demand is hard to overstate. 

McKinsey estimates that by 2030, data centers will require $6.7 trillion in cumulative capital investment worldwide to keep pace with AI-driven compute needs, spread across real estate developers, energy providers, semiconductor firms, and cloud operators. Utilities and energy providers alone face an estimated $1.3 trillion in AI-related capital requirements.

If you’ve invested in commercial real estate, this asset class should feel familiar. Data centers are increasingly treated as a specialized form of real estate — physical buildings with long-term leases, mission-critical tenants, and predictable cash flows. A 2025 survey by CBRE found that 95% of major investors worldwide plan to increase their allocations to data centers, with 41% planning to commit $500 million or more in equity, up from 30% the year prior. Vacancy rates in the sector finished 2025 at a historic low of 1% for the second consecutive year, with 92% of capacity currently under construction already pre-committed by tenants.

The appeal is structural. These are long-duration, hard assets — the kind where demand isn’t speculative but is driven by an accelerating, durable tailwind. AI doesn’t run on software alone. It runs on land, steel, power lines, and cooling systems. That’s the investment conversation worth having.

I encourage clients to take a disciplined approach and acknowledge what we don’t know. Researchers at the World Resources Institute point out that modeled projections for data center energy use by 2030 range from 200 to over 1,050 terawatt-hours per year, which is a pretty staggering spread. Some experts have also warned that utilities are being flooded with speculative grid connection requests, which may be distorting load forecasts. 

The investment case for infrastructure isn’t built on assuming the most aggressive projections are right, but on recognizing that even the conservative ones point to a significant and sustained build-out, and that the physical assets required to support it will need to exist regardless.

Why the Real Action Is in Private Markets

These opportunities aren’t readily accessible to everyone. Most of the meaningful investment in AI infrastructure isn’t happening in the public markets, and there’s a structural reason for that.

Large-scale data centers, energy systems, and digital networks require significant capital, long development timelines, and patient ownership. These are conditions private markets are built for, and institutional conviction is growing. 

The World Economic Forum puts the scale of opportunity in sharp focus. Meeting the world’s infrastructure demand will require $106 trillion in investment by 2040, spanning energy, digital, and transportation systems. Private investment plays a critical role, as public funding alone falls well short. 

For high-income investors, access to these markets has improved meaningfully in recent years. But access isn’t the strategy. As I’ve written before, private credit and infrastructure funds can generate steady cash flow even when public markets struggle, and that’s exactly the kind of characteristic that belongs in a long-term, disciplined wealth plan. The trade-offs around liquidity, structure, and complexity are real, and they deserve a direct conversation. That’s always where we start. 

What to Watch Out For

This is where I usually slow things down.

Private infrastructure and similar investments can be a good fit, but they come with real trade-offs. 

Liquidity is one of the biggest. You’re not buying something you can sell tomorrow; you’re committing capital for years, and that needs to align with your broader plan. As I’ve noted in past articles on private investments, these structures often involve lock-up periods and limited access to funds, which can be challenging when flexibility is needed.

Manager selection is just as important. Two funds may both be labeled “infrastructure,” but have very different strategies, risk profiles, and outcomes depending on how they’re built and managed. Not all opportunities are created equal.

I’ve seen investors get pulled in by a compelling theme without fully understanding how the investment works — how returns are generated, what assumptions are being made, and how long capital is tied up. That’s why the focus should always be on fundamentals. If we can’t clearly answer those questions, we don’t move forward.

A Different Way to Think About AI Investing

This isn’t about chasing AI hype or trying to pick the next winner. It’s about understanding where durable, long-term value is being built and whether those opportunities belong in your portfolio. If you’re curious how this type of investment could fit into your broader plan, that’s a conversation worth having.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

Headshot of Sean Gerlin, CFP®, CPWA®, ChFC®, CLU®
Sean Gerlin, CFP®, CPWA®, ChFC®, CLU® Creating Clarity Out Of Complexity

Sean Gerlin, CFP®, CPWA®, ChFC®, CLU® | Envision Wealth Planners

You’ve both managed money successfully before. You’re professionals, homeowners, and financially stable. So why does talking about money together feel so much harder than it should?

In blended families, money isn’t just financial—it’s relational. Each of you brings financial beliefs shaped by different experiences: how you were raised, what your first marriage taught you, what felt safe or risky during the years you were on your own. These beliefs run deep, and they don’t always surface until you’re making decisions together.

The challenge isn’t that one person’s approach is right, and the other’s is wrong. It’s those assumptions about fairness, responsibility, and what money should do that often go unspoken until a decision forces them into the open. When that happens, what looks like a disagreement about numbers is actually a clash of unexamined values.

Traditional financial planning assumes alignment and moves quickly to strategy. But in blended families, that sequence gets it backward. The hard part isn’t the math—it’s the conversations that clarify what you’re building together. When those conversations happen first, the financial decisions become clearer because you’ve defined the direction.

Understanding What Drives Your Financial Choices

In any relationship, you don’t want to lose sight of who you are as an individual. While marriage calls two people to come together as a strong partnership, it also requires honoring each person’s unique experiences, perspectives, and priorities.

Examining your money values helps you do exactly that. It clarifies what drives you financially and reveals the motivations behind both your best decisions and your most challenging ones. Someone who experienced financial instability in their first marriage might prioritize emergency savings above everything else. Another person who managed fine as a single parent might feel more comfortable taking calculated risks or spending on experiences today.

Neither perspective is right or wrong. They’re protective responses to different stories.

But in blended families, those protective instincts can collide in unexpected ways. What feels like financial caution to one spouse can feel like resistance to the other. What looks like generosity might feel like favoritism. Understanding your own values gives you the language to explain what’s driving a decision and helps your spouse see it as protection, not rejection.

When you can name what money means to you, conversations shift from defending positions to understanding each other.

Bringing Your Money Values Into the Open

Once you understand what drives your own financial choices, the next step is harder: sharing those beliefs with your spouse, and creating space to hear theirs.

In blended families, this isn’t a conversation about budgets or account structures. It’s about surfacing the assumptions you’ve both been carrying: what feels fair, what feels threatening, what you’re protecting, and what you’re afraid of repeating from your first marriage.

You’re navigating questions with no easy answers: How do we balance supporting your kids and mine fairly? What happens to assets you brought into the marriage? Should inheritance stay separate or become shared? What feels like protection to you but feels like distrust to me?

There’s emotional math at play—invisible calculations about loyalty, fairness, and what each of you promised yourself you’d never do again. These don’t show up on a spreadsheet, but they shape every financial decision you make together.

Traditional financial planning skips this step. It assumes alignment and moves straight to strategy. But in blended families, when assumptions go unspoken, they don’t disappear. They build consequences that surface years later as conflict or unintended outcomes.

Start by naming what money means to you and what shaped that belief—not what you think you should say, but what’s actually true. Maybe you’re still carrying fear from your first marriage. Maybe you feel protective of your kids in ways that are hard to explain. Your spouse’s perspective will be different, and that’s not a problem to solve immediately. The work here is to understand, not to convince.

Money conversations can get emotional. It’s tempting to label one partner as “bad with money” or overly cautious. But those labels shut down understanding. Don’t assume you know what drives your spouse’s choices without asking. And don’t treat your own perspective as fact while dismissing theirs as opinion.

Where you find common ground, acknowledge it. Where you see differences, don’t ignore them. The danger isn’t disagreeing—it’s leaving assumptions unspoken.

This conversation is how you move from two separate money stories to one shared direction. When you surface what you’re each building toward, the financial decisions become clearer because you’ve defined where you’re going first.

Start Creating Intentional Alignment

You don’t have to agree on every financial detail throughout your marriage. Rather than aim for perfection, build a shared understanding of how your values will be expressed in real life.

For example, you might need to clarify expectations around spending, saving, supporting children, and charitable giving. As a blended family, you may need to think deeper about inheritance planning, financial responsibilities for children from previous relationships, or how household expenses will be shared.

Understand that you won’t be perfectly aligned at every step, and that’s okay. The point is to be more intentional with your decisions and come from a place of understanding. When you know how you both feel about money and what shaped those perspectives, you create a shared sense of direction. That direction becomes your North Star. It won’t eliminate every disagreement, but it gives you a framework for making decisions together.

Knowing what you’re building together helps you measure individual choices against a bigger picture. That’s what alignment actually looks like: not identical opinions on every detail, but clarity about where you’re going and why.

Ready to Go Deeper?

Navigating money conversations in a blended family is complex, but it’s also an opportunity to build deeper understanding and alignment within your marriage.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

Headshot of Brian K. Peterson, CFP®, CPWA®, MBA
Brian K. Peterson, CFP®, CPWA®, MBA Planning Built For Blended Family Life

Brian K. Peterson, CFP®, CPWA®, MBA | Blended Family Financial