I’m not sure why it’s taken me this long to read the New York Times bestseller Million Dollar Weekend. I’m familiar with its author Noah Kagan, founder of major tech brand AppSumo and heavily involved in the launch of image sharing tool Imgur. I’ve read his blog, and listened to him on podcasts, and he gives good business advice, but I guess I let the title put me off. I don’t like crazy claims in book titles and we all know you can’t make a million bucks in a weekend.
Maybe I should have checked the subtitle before writing it off though. The book’s full title is Million Dollar Weekend: The Surprisingly Simple Way to Launch a 7-Figure Business in 48 Hours, which is a (slightly) more realistic aim. You’re not making a million this weekend, you’re coming up with and validating an idea that potentially will. Here’s what resonated with me.
The Fear of Starting and the (Bigger) Fear of Asking
Most of us fear starting something new, and if there’s a bigger fear than starting to sell something it’s the fear of asking for that first sale. It’s why we set up websites, storefronts or sales focused social channels and then don’t immediately start aggressively promoting them, running ads to them, or asking people to buy.
It’s not, of course, the asking that we’re scared of. It’s the answer. We’re scared it will be a no, and it mostly will be. Most sales professionals aim for a very low success rate when cold calling, sometimes a low as 1% — which means you potentially get to hear no 99 times before you get a yes. Good salespeople learn to simply see it as every no getting them a little closer to a yes. Kagan explains that it was his father who taught him:
“Love rejections! Collect them like treasure! Set rejection goals. I shoot for a hundred rejections each week, because if you work that hard to get so many noes, in them you will find a few yeses, too.”
Overcoming the fear of rejection is key to success, in almost anything. As a freelance writer I know this better than most.
Focus on What People Will Actually Buy
We all know we have to solve a real-world problem when we set up a business, and Kagan focuses on how to do that. He advises you address the problems you face yourself and those your potential customers face, but he also suggests a couple of other ways of finding something that will sell.
One tactic is to find something that takes a popular product you love and makes it even better. If you’re thinking about physical products this could be accessories or something that enhances the experience of using it, and it could be something very simple. Someone told me recently the best ‘gadget’ in her kitchen isn’t the dishwasher that makes washing up for a family of five a no-effort endeavor, but the sliding sign a friend bought her that goes on the front of it and lets everyone know whether the dishes are currently ‘dirty’ (yes you can put more in) or ‘clean’ (time to unload if you happen to be passing).
Online entrepreneurs succeed all the time with something that makes an existing product even better. One example is the YouTube channel that focuses on online tutorials to help you get the most out of a product you already own. Think how to level up in a video game, how to create the perfect make-up look, or how to convert your old work van into a cozy camper.
Validate Your Idea
Kagan suggests you do this by getting at least three sales in 48 hours, before you actually launch the business. That’s three actual pre-sales, from people who pay the money up front, not people who say they’ll probably buy if you make it. It sounds hard but in the online world it’s really not.
You run a webinar promoting a course you haven’t made yet and offer a pre-sale price. You post an excerpt of a book you’re writing on your blog and ask for pre-sales from your subscribers. You use an online platform like Kickstarter to see if people will invest cold hard cash in your idea, before the product is made.
I’m going to admit, 48 hours seems like too short a timeline to me. My instinct would be to give it longer, but who am I to contradict Kagan, who apparently sold over 200 subscriptions to Imgur in two days. That alone makes just three sales in 48 hours sound more doable.
If you’re looking to start a million-dollar business (or any profitable business) right now, Million Dollar Weekend is worth a read. Statistically, it’s unlikely you’ll make a million, but if you read carefully and apply thoroughly you’ll get a great sense of whether you’re on the right track to a viable business idea.
About the Author
Karen Banes is a freelance writer specializing in entrepreneurship, parenting and lifestyle. She writes articles, website content, ebooks and the occasional award winning short story. Her work has appeared in a range of publications both online and off, including The Washington Post, Life Info Magazine, Transitions Abroad, Brave New Traveler, Natural Parenting Group, and Copia Magazine.
Learn More About Karen
How a 1031 Exchange Powered Their Move from Landlord to Retiree, Providing More Income and Less Stress
Sometimes it’s hard to quantify the work that I do for clients—measuring outcomes from financial planning can be a tricky thing. Sure, I can track income tax savings or investment portfolio growth, but it can be challenging to measure the change in my clients’ overall quality of life through my financial planning services. To best illustrate the true impact of my services on the lives of my clients, I have decided to share the story of one of my clients as they transitioned to retirement and how we adapted their original plans to position them optimally for retirement.
I have changed a few details to protect the privacy of my clients, who are referenced below. To simplify the discussion, let’s refer to them as the Smiths.
Setting the Stage
The Smiths have been married for many years, working together to build a successful small business and, through savvy investment, had developed an extensive rental property portfolio.
As they approached 65 and turned their focus to retirement, we continued to work on analyzing and updating their financial plan. As business owners, they had effectively managed their tax burden, but also had not accumulated large payouts from Social Security or pensions. Their vision was always that their rental property portfolio would provide retirement security, but the issue was that they had lost motivation to continue managing the rental properties as landlords.
They wanted to retire truly, rather than deal with tenants and maintenance issues. The Smiths had accumulated approximately $1.8MM in Real Estate Assets (16 units), along with $750,000 in Brokerage account investments and another $ 400,000 in IRA accounts. The Smiths needed approximately $9,000 per month to live on in retirement, and Social Security would provide about $3,500 in monthly income (which for one spouse would be delayed until 70). The Smiths were earning about $65K net from their Real Estate after all of their expenses on the rentals were paid. After taking the time to thoroughly understand the Smiths’ unique circumstances and weigh their options, I was able to recommend an effective course of action that would achieve all of their retirement goals. EntryPoint’s solution—the 1031 Exchange Strategy—was designed to help the Smiths truly transition to retirement without landlord responsibilities, obtain at least $65,000 in annual income, and avoid creating a tax situation through the sale of their real estate assets.
The 1031 Exchange Strategy
By utilizing the 1031 Real Estate Exchange strategy, EntryPoint helped the Smiths execute each aspect of their planning situation. A 1031 Exchange allows investors to transition their Real Estate Investments to new holdings without incurring a tax liability. Investors must meet specific guidelines dictated by the IRS to complete the transaction without triggering income tax. In this case, the Smiths had a very low remaining cost basis (about $200K). The rest had been depreciated, meaning that if the Smiths did not complete the exchange correctly, they would have been subject to taxation on $1.6MM either from depreciation recapture or capital gains.
A Closer Look at Taxes
If the Smiths had sold their Real Estate holdings without completing an exchange, their $1.6MM in gains could have triggered almost $400,000 in personal taxes. And the Smiths would have been mostly reinvesting in the Stock Market, where cash yields are around 3%, not nearly high enough to meet their goals. Additionally, considerations would also reveal that the income would be earned on a much lower principal amount than the value of their Real Estate Portfolio. The choice to complete the exchange became easier when considering that the new Real Estate Investments would pay roughly 6% in distributions based on the entire principal, and the Smiths would keep the assets invested without paying taxes.
Reinvestment of the Exchange Proceeds
Through a 1031 Exchange, investors have two main choices: reinvest in personally managed real estate or choose passive real estate investments. Professional operators manage these passive real estate investments in high-quality real estate holdings in some of the best real estate markets in the United States. These passive investments are often institutional-quality properties in high-demand markets, providing diversification, higher-quality tenants, and eliminating landlord headaches. Many times, investors choosing these passive real estate investments will be moving from local real estate environments to upgrade their investment strategy through better opportunities. In this case, the Smiths opted for a passive approach. And as a result of their new portfolio, they state that “We are receiving more income while doing nothing. We wish we had done it sooner.”
Through the reinvestment of their real estate portfolio, the Smiths transitioned from single-family real estate to an infrastructure development fund and medical center in South Carolina, a land bank and retail shopping center in Texas, and a natural gas mineral rights property in Texas. They have achieved greater diversification through better investment holdings, along with increased cash flow, and can now entrust the management of their properties, allowing them to live their best retirement lifestyle. Of course, none of this would have happened if they had not first reached out to me to discuss their options.
If you would like to know more about my Retirement Planning Process and how I help high-net-worth individuals solve complex problems to achieve their best retirement situation. Reach out today to set up a personalized strategy session with me to uncover your next steps. I have helped corporate executives, business owners, and real estate investors, such as the Smiths, transition to retirement. Please get in touch, and I will help you navigate the complexities of your unique circumstances to find an effective solution that achieves your goals.
But only if I can also answer yes to these three questions.
Will This Move Me Closer to My Goals?
I have big goals for the next few years. I want to expand my business, grow my wealth, and simplify my life. And that’s exactly why I say no to a lot of things, because not everything serves those goals. I’m particularly wary of certain things.
Investments that promise big potential but come with very high risks just aren’t for me right now. They might be right for you, of course, depending on your age, life stage, net worth, and appetite for risk. This is why it’s important to have specific goals and see if the opportunities that arise for you support those goals.
New clients are only worth it for me if they are both high paying and offering work that really fires me up. I already have a handful of excellent, reliable clients, alongside a lot of other non-work responsibilities. It’s important that I say no to anything that’s going to make my work life harder, especially if the rates and terms being offered aren’t great.
A new account that offers a bonus just for opening it sounds great, but opening and managing new accounts makes life more complicated at a time when I’m trying to simplify it.
Are the Opportunity Costs Worth It?
There are always opportunity costs when it comes to both money and time. Time spent on a new client is time you could use to pitch other, better-paying, more aligned clients. Money in an investment account could be better invested elsewhere. Even the time used to open a new account could be better used, to either make more money or do something more worthwhile to you personally.
Time is, in many ways, our most important resource alongside money of course. So don’t waste time, and don’t tie up money in ways that make it hard to take advantage of better opportunities that might present themselves.
Will I Do the Opportunity Justice?
Even a great new high-paying client may not be worth taking on if you just don’t have the time or energy right now to do the opportunity justice. As a freelancer, saying no to anything can feel like professional suicide. The feast and famine nature of the work means turning down a lucrative opportunity is always hard. And if it’s a great gig but not that well-paid? The fact that your freelance portfolio is your primary way of impressing future clients means you always want to add to it so you can better showcase your skills.
Taking on any opportunity that you can’t put your all into, however, can do more harm than good. A job not-particularly-well-done doesn’t enhance your reputation. You’re better off waiting until you can give the opportunity the time and attention it deserves, or trusting that another opportunity will come if you miss this one.
Learning to say no to what doesn’t serve you financially is a skill in itself. It’s not always investments and clients. Sometimes it’s an expensive trip or just an extravagant night out. Sometimes it’s a personal commitment that will cost you time and money.
The key to knowing when to say no is often just about having really clear goals. That lets you answer the first question above easily, and can sometimes make the other two irrelevant. So set very clear, specific financial goals, and weight every new opportunity with those in mind.
About the Author
Karen Banes is a freelance writer specializing in entrepreneurship, parenting and lifestyle. She writes articles, website content, ebooks and the occasional award winning short story. Her work has appeared in a range of publications both online and off, including The Washington Post, Life Info Magazine, Transitions Abroad, Brave New Traveler, Natural Parenting Group, and Copia Magazine.
Learn More About Karen
How we spend dictates how much we can save and invest. It all starts with putting a few rules in place. Here are mine.
Big Purchases Are Never Made on Impulse
I never buy anything over $1,000 without deep research. Whether it’s a car, a vacation, a major household appliance or a new investment product. If it’s four figures or more there’s going to be a lot of research carried out and comparisons made before I hit the buy button.
Anything over $100 has a different rule. I wait 24 hours before buying. This avoids impulse spending on smaller but still significant purchases. This mindset becomes second nature over time. One day you’ll notice you’re using it for much smaller purchases too.
Big Expenses Are Kept to a Minimum
The common advice to stop buying coffee shop lattes when you need to save money is problematic for a simple reason. Coffee doesn’t cost that much, not compared to major expenses like housing or childcare. If you can find ways to rearrange your life to halve your housing or childcare costs, you’ll save significantly more than if you halve your coffee costs.
Throughout my life I’ve kept housing costs to less than 20% of my income, often much less. Strategies for this have varied. I’ve lived with family, roommates, and strangers. I’ve worked in return for housing while living abroad. I’ve lived in non-conventional housing. I’ve lived in Spain (where housing costs at the time were a fraction of those in my home country).
Are all these strategies practical for most people? Not really. But it’s worth thinking about what might work for you, even if it’s something drastic like relocation. If you start with your biggest expense, which for most of us is housing, and intentionally look at ways to reduce it to the lowest possible figure, it can make a huge difference over time.
I Don’t Buy Things I Don’t Need
This seems obvious, but most of us aren’t even close to following this rule. Look at your last ten purchases. How many were true needs? When it comes to basic things like clothes I don’t buy anything until I’ve checked my closet to see if I own something very similar. I almost always do.
My biggest tip here is to do a big declutter and actually organise your possessions. It may seem counter intuitive, but when you have less, you’re more aware of what you actually own. You don’t end up buying another version of something that you actually already have stuck in a closet, kitchen cupboard, or junk draw.
I Think of Spending in Terms of Life Energy
This is a concept covered in the book Your Money or Your Life by Joseph R. Dominguez and Vicki Robin. The authors urge readers to see money itself as life energy, given that most of us exchange precious reserves of energy – and hours of time – for the dollars in our paychecks.
How much time and energy does it take for you to earn $500? Thinking like this puts big purchases in a whole new light. Is that new item really worth 10 hours of your time and energy? Or 20, or 100?
This actually works both ways. Some things ‘cost’ several hours and only bring you one hour of low-level enjoyment. They’re probably not worth it. Some things only ‘cost’ an hour of your life but will bring you a lot of joy, sometimes for years to come. They’re the true high-value purchases.
I Design My Environment
My environment isn’t set up for spending. I don’t save payment details for next time when I check out online. I unsubscribe from marketing emails. I don’t scroll endlessly on social sites that are always trying to sell you something, directly or indirectly. I enjoy most of my leisure time in non-retail environments (up a mountain or on a secluded beach when I can).
Your environment has a big impact on your behaviour. Make sure it’s not screaming at you to indulge in unnecessary spending.
I Focus on Creating Much More Than Consuming
I’m a professional writer, a (very) amateur photographer, and a creative in general. I’d make something than buy something. My daily activities are much more focused on creating than consuming.
We’ve become a society where consumption is — for many of us — built into our daily lives in multiple ways. Creating isn’t. We have to seek it out. But when we do, we tend to save money and feel more fulfilled. Creative hobbies are worth cultivating.
These rules help me because they’re specific and strategic. If you’ve set yourself a vague rule like ‘spend less money’ it’s hard to implement because there’s no actual strategy there. Consider these instead.
About the Author
Karen Banes is a freelance writer specializing in entrepreneurship, parenting and lifestyle. She writes articles, website content, ebooks and the occasional award winning short story. Her work has appeared in a range of publications both online and off, including The Washington Post, Life Info Magazine, Transitions Abroad, Brave New Traveler, Natural Parenting Group, and Copia Magazine.
Learn More About Karen
A wealth advisor who specializes in serving construction business owners and individual contractors can help you spend more time building your business with less money stress.
As a construction business owner, you must overcome unique financial planning obstacles in order to achieve near and long-term success. From supplier shortages and missed delivery timetables to weather events that can literally freeze business operations, there’s no shortage of factors that can severely strain your balance sheet.
A wealth advisor who understands these challenges intimately can become a valuable partner committed to helping you succeed.
You’ll likely find dozens of nearby financial professionals well-suited to help you reach your money goals with a personalized plan. But it may be more difficult to find a wealth advisor who specializes in working with construction business owners.
Fortunately, many financial professionals can work with you virtually, so you can meet online no matter where you (or they) live. This means you can choose to hire a specialist who lives hundreds of miles away if you decide their knowledge and experience working with construction business owners is a better fit to help with your unique financial planning needs.
Financial Planning for Construction Business Owners
💡 In the Q&A below, you’ll gain insights from financial professionals who work with construction business owners to help them make smart decisions to enjoy life more today while preparing for a comfortable retirement in the future.
🙋♀️ Do you have questions not answered below? Use the form on this page to submit your questions, and we’ll update this article with answers from the financial professionals and educators in the Wealthtender community. You can also contact the financial professionals featured in this article directly to set up an introductory call or ask your questions by email.
Find a Financial Advisor Who Specializes in Financial Planning for Construction Business Owners
📍 Click on a pin in the map view below for a preview of financial advisors who specialize in financial planning for construction business owners.
💸 Smart Money Insights for Construction Business Owners
This page is organized into sections to help you quickly find the information you need and get answers to your questions:
Q&A with Financial Professionals Specializing in Serving Construction Business Owners
Get Answers to Your Questions About Financial Planning for Construction Business Owners
Browse Related Articles
Q&A: Financial Professionals Specializing in Serving Construction Business Owners
Answers to Construction Business Owner Questions with Jason Berube
Q: What is a common financial planning challenge unique to construction business owners that you frequently encounter when working with your clients? How do you work with them to overcome this challenge?
Jason: One of the most common financial planning challenges my clients face is overpaying in taxes. Because they aren’t working yet with one dedicated person to manage their financial world, they’re often receiving disjointed, reactive advice from various individuals (like tax preparers, accountants, or insurance brokers). With no one to facilitate these conversations and take a proactive approach to planning, clients often end up giving away more of their money to taxes than they need to.
When construction business owners come to me, I make it a priority to evaluate their current tax strategy and identify opportunities to make it more efficient. I look for proactive ways to help them increase their wealth without having to alter their lifestyle.
Q: For construction business owners who are unsure whether or not they should hire a financial professional at the current stage of their business, what guidance can you provide to help them make a more informed and educated decision?
Jason: Construction business owners at any stage of business, whether they’re just getting off the ground or preparing to retire, experience unique financial challenges. No matter where they are in the life cycle of their business, they are managing a balancing act between their personal and business finances.
I take an all-encompassing approach by serving as my clients’ personal CFO. Using my own experience in business and construction, I help them tackle their biggest challenges from cash flow, tax planning, and estate planning to strategically investing back into their business and preparing a robust transition plan.
The more net worth a business owner accumulates, the more complex their financial landscape becomes. Building a healthy foundation now is essential to preserving that wealth over time and making purposeful decisions that align with a client’s long-term goals.
Q: How do the services you offer construction business owners distinguish your services from other financial professionals?
Jason: A huge reason why I work with the people I do is that they often amass a significant amount of wealth, but struggle to navigate the complexities of it. They might be juggling a bunch of disjointed advisors from accountants to estate planning attorneys or even real estate agents. But the problem is, nobody’s there to take the reigns and facilitate clear communication between all parties.
So with that in mind, the services I offer distinguish me from other advisors in two ways. First, I step in and serve as my client’s personal Chief Financial Officer, or CFO. And second, I implement a tax strategy designed to help them increase wealth without sacrificing their lifestyle.
Through my approach to all-encompassing planning, I’m able to help my clients work proactively to grow and preserve their wealth without having to manage the relationships between their full team of financial professionals on their own.
Get to Know Jason Berube, Wealth Coach for Construction Business Owners:
Q: When you first speak with a construction business owner, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
Jason: Anytime I meet with a new construction business owner or contractor, I have them fill out my Discovery Questionnaire. This is a comprehensive document that helps me better understand the fundamentals of their business, such as when it was founded, total revenue, number of employees, and other key data points.
I also include questions about their business’s entity structure, expenses, retirement plan, insurance coverage, history with tax compliance, and other areas of potential concern.
Armed with this information, I’m better prepared to analyze my client’s current financial situation and develop solutions to address their unique needs and goals.
Q: Is there a particularly memorable experience or a moment you recall with a construction business owner client when you first realized they have unique opportunities and circumstances when it comes to their financial planning needs?
Jason: I proudly come from a long line of business owners, and more specifically, construction company business owners. Many of my family members worked hard from the ground up to build successful, family-owned businesses, which I know from experience is no easy feat.
For as long as I can remember, I’ve been able to identify a few areas of specific concern for construction business owner clients.
First and foremost, these business owners need a succession plan that dictates what happens to the business when the owner passes away, becomes unable to work, or retires. They also need an asset protection strategy that keeps their expensive equipment, land, and property protected from legal claims, theft, or damage.
I’ve also seen a need in this particular industry for cash flow management, especially considering how cyclical the nature of business is. With projects often lasting months (even years) and payment often withheld til the end, cash flow can be a big challenge for these business owners. And with cash flow comes tax planning, an area in which I’ve seen too many business owners overpay, simply because no one’s ever been in their corner to help them minimize their tax obligation.
🙋♀️ Have Questions About Financial Planning for Construction Business Owners?
Get answers from the Wealthtender network of financial professionals and educators.
About the Author
Brian Thorp
Founder and CEO, Wealthtender
Brian and his wife live in Texas, enjoying the diversity of Houston and the vibrancy of Austin.
With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.
A dynamic asset allocation investment strategy employed by financial advisors attempts to reduce risks by adjusting portfolio holdings based on timely factors.
When the stock market declines by 1%, 5%, or 20%, should you be concerned if your investment portfolio earmarked for your retirement falls by an equal amount?
The answer will depend upon your investment objectives and tolerance for risk. Unfortunately, for many people who thought their portfolios were diversified and protected from suffering declines just as severe as major stock market pullbacks, the 2008 Financial Crisis and the 2020 COVID Crash proved otherwise.
While no investment strategy with exposure to asset classes like stocks and bonds is immune to losses when prices fall, a dynamic asset allocation approach attempts to reduce the severity of declines in investment portfolios when markets pull back while still achieving the long-term performance returns needed to meet investment objectives.
Suffice it to say that constructing and monitoring dynamic asset allocation portfolios requires considerable education, confidence, and fortitude. If you’re interested in the potential benefits of investing with a dynamic asset allocation approach, you may want to hire a financial advisor who specializes in this area.
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it may be more difficult to find a financial advisor who specializes in building and managing dynamic asset allocation portfolios for their clients.
Fortunately, many financial advisors offer virtual services so you can meet online no matter where you (or they) live. This means you can choose to hire a specialist financial advisor who lives hundreds of miles away if you decide their knowledge and experience managing portfolios using a dynamic asset allocation approach is a better fit to help with your unique financial planning needs.
Financial Advisors Who Specialize in Dynamic Asset Allocation
💡 In the Q&A below, you’ll gain insights from financial advisors who specialize in building portfolios using dynamic asset allocation to help their clients achieve their investment goals with the potential for reduced losses when markets decline.
🙋♀️ Do you have questions not answered below? Use the form on this page to submit your questions, and we’ll update this article with answers from the financial professionals and educators in the Wealthtender community. You can also contact the financial advisors featured in this article directly to set up an introductory call or ask your questions by email.
Find a Financial Advisor Who Specializes in Dynamic Asset Allocation
📍 Click on a pin in the map view below for a preview of financial advisors who specialize in dynamic asset allocation.
Answers to Investing Questions with Todd Stankiewicz, CFP®, ChFC®, CMT®, ABFP®, EA
We asked Harrison, New York-based financial advisor Todd Stankiewicz who specializes in managing dynamic asset allocation portfolios for his clients, to help us learn more about the potential benefits of this approach to portfolio construction.
Q: How does your approach to dynamic asset allocation differ from a traditional buy-and-hold strategy?
Todd: Buy-and-hold sounds disciplined until you are sitting across from a client who just watched half their portfolio disappear. I have been through it. In 2008, the S&P 500 dropped roughly 57% from peak to trough. In early 2020, markets fell over 30% in a matter of weeks. In 2022, both stocks and bonds declined together, leaving traditional “balanced” portfolios with nowhere to hide. That was not merely a drawdown; it was a correlation breakdown. The foundational assumption behind the classic 60/40 portfolio, that bonds provide ballast when stocks fall, failed for the first time in decades. Investors who believed they were balanced had no refuge, facing a fundamentally different kind of risk than a pure equity selloff.
The emotional and financial damage from those drawdowns is real, and for many people it takes years to recover, if they recover at all.
My approach is built around responding to what the market is actually doing, not hoping it will bounce back on schedule. As a Chartered Market Technician, I use price trends, momentum signals, and technical indicators as an early warning system. When the weight of the evidence shifts, we shift. The goal is not to predict the future or time every move perfectly. It is to recognize deteriorating conditions early enough to reduce exposure before a routine pullback turns into a devastating loss. A static portfolio forces you to sit and absorb the full impact. A dynamic approach gives you the ability to act.
Q: Who is the ideal client for a dynamic asset allocation strategy?
Todd: The clients who benefit most from this approach are people who do not have the luxury of waiting it out. At the top of that list is the business owner. Their company is often their largest asset, and it is completely illiquid. The investment portfolio sitting alongside that business is their financial lifeline. If markets drop 40% and they need to make payroll, fund operations, or protect their family’s lifestyle, they cannot afford to wait three to five years for a recovery. Their liquid wealth has to stay intact and accessible.
I also work with pre-retirees in that critical window between 50 and 70 who have spent decades building wealth and are approaching the finish line. A deep drawdown at that stage can delay retirement by years. And for clients already in retirement who are taking regular distributions, the math gets even more unforgiving. Selling into a declining market locks in losses permanently.
That is sequence-of-returns risk, and it is the single biggest threat to a retiree’s long-term financial security.
The threat is not limited to a stock market crash. As 2022 showed, an environment where supposedly safe bond allocations fail at exactly the wrong time can be just as damaging. Dynamic allocation is built to potentially detect not only drawdowns, but also shifts in correlation, when the old defensive playbook stops working. The common thread across all of these clients is straightforward: they need their portfolio to work for them right now, not just eventually.
Q: Does dynamic asset allocation cost more, and how do you think about the value it provides?
Todd: I think the cost question gets framed backwards most of the time. People fixate on the advisory fee, but the real cost in investing is the loss you cannot recover from. If your portfolio drops 50%, you need a 100% gain just to get back to even. That is not a typo. A 100% gain. Depending on where we are in the market cycle, that recovery can take years. After the Dot Com Bubble Burst it took over 10 years for the S&P 500 Index and to reach previous highs. For someone who needs that capital for their business, their retirement, or their family, those years matter enormously.
At SYKON Capital, we operate on a fee-only model. We do not earn commissions or receive compensation for product sales. Standard regulatory trading costs, such as SEC fees, may apply as they do with any brokerage account, but there are no advisor incentives tied to how often we trade or what we recommend. The fee is transparent, and it is aligned with one outcome: growing and protecting your wealth.
The value of dynamic allocation is not just the potential to sidestep the worst of a downturn. It is also the confidence it gives clients to stay invested and engaged with their plan instead of panic-selling at the bottom, which is where the most permanent damage happens. In our experience, that combination of downside awareness and emotional stability is worth far more than the fee.
Q: What role does liquidity play in how you construct dynamic portfolios for your clients?
Todd: At SYKON Capital, liquidity is king. It is the foundation of everything we build. We seek to hold positions in instruments that have traditionally been liquid and trade on public exchanges: stocks, ETFs, and funds that can be bought or sold on any trading day under normal market conditions. We do not generally use alternatives, private placements, or any vehicle with a lock-up period. The reason is simple: if you cannot move, you cannot adapt. And the entire point of dynamic allocation is the ability to adapt when conditions change.
This matters especially for business owners. Their company is already illiquid. It cannot be sold overnight if they need capital. Their investment portfolio should not add another layer of illiquidity on top of that. When a business owner needs to pull funds for an unexpected expense or an opportunity, the portfolio should be ready. The same applies to retirees taking income distributions. If part of your portfolio is locked up in a fund with a multi-year redemption schedule, you lose the flexibility that makes dynamic management effective. We aim to keep our clients in a position where they can act quickly, whether the goal is to reduce risk during a downturn or to access capital when life demands it.
Q: Does dynamic asset allocation mean you are always playing defense?
Todd: That is probably the biggest misconception about this approach, and it is worth clearing up. Dynamic asset allocation is not a strategy built around hiding in cash and waiting for the storm to pass. It is built around following the evidence. And when the evidence says markets are trending higher, the goal is to be fully invested and participating in that upside.
Think about the bull runs following 2009, 2020, and the AI-driven surge of 2023 and 2024. Investors who sat on the sidelines waiting for the next crash missed some of the most powerful rallies in market history. One of the biggest risks in investing is not just being down in a bear market. It is being out of the market during a bull market.
Dynamic allocation, done well, keeps you invested when conditions support it and reduces exposure when they do not.
As a Chartered Market Technician, I use technical signals to read market momentum and trend strength, not just deterioration. When price action and breadth are confirming a healthy uptrend, that is a signal to stay engaged, not to retreat. The daily noise, the recession headlines, the geopolitical fears, the predictions about where the market is headed next week, none of that drives portfolio decisions. The data does. That discipline is what allows clients to tune out the noise and stay invested in strong markets with conviction, rather than second-guessing every move higher.
Dynamic allocation is not about avoiding markets. It is about trying to be in the right position for the environment in front of you.
Get to Know Todd Stankiewicz, Financial Advisor and Dynamic Asset Allocation Specialist:
Answers to Investing Questions with Zack Swad, CFP®, CWS®, BFA™, AWMA®, AAMS®
We asked Santa Rosa, California-based financial advisor Zack Swad who specializes in managing dynamic asset allocation portfolios for his clients, to help us learn more about the potential benefits of this approach to portfolio construction.
Q: When meeting with new clients, how do you describe what dynamic asset allocation is?
Zack: A dynamic asset allocation is an alternative to a strategic allocation, which is typically based on “Modern Portfolio Theory” (MPT). Unlike a strategic allocation, which has a mostly-fixed percentage in each asset class (stocks, bonds, etc.), a dynamic allocation considers certain factors to determine which investments make the most sense at a given time.
Pretend you (and your investment portfolio) are in an airplane, and you have a pilot (the portfolio manager) flying the plane. The pilot can see through the windshield, and he also has an indicator dashboard. The indicator dashboard begins to blink and sends a signal to the pilot, informing him that if he keeps flying in the same direction and at the same speed, he will run into a storm in twenty minutes. What does the pilot do? Of course, he will try to avoid the storm. He will change course, or he may need to slow down or lower the plane.
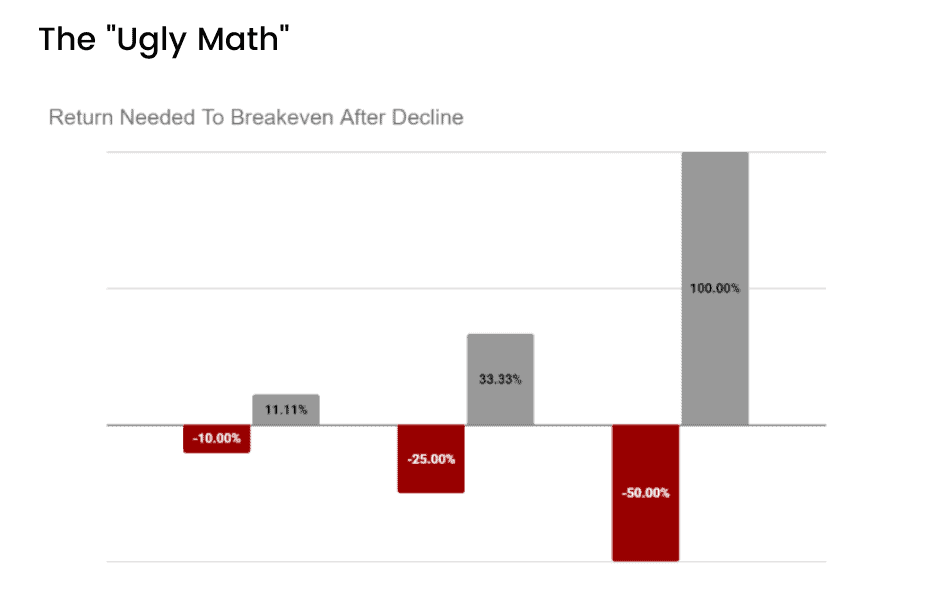
A dynamic asset allocation works similarly. It attempts to avoid catastrophic losses by actively managing the risk in a portfolio. At the same time, because a dynamic allocation typically does a better job of avoiding large losses, it doesn’t need to return as much when the markets are up. As you can see in the “Ugly Math” chart below, the less a portfolio declines, the less return it needs to get back to even and start making new profits.
For example, if you have $1,000,000 and lost 10%, you would have $900,000. To get back to even, you would need to make $100,000 or an 11% return. On the other hand, if you have $1,000,000 and experience a 50% loss (similar to what was seen for “buy-and-hold” stock investors during the 2008 financial crisis), you would then have $500,000. To get back to even, you would need to make $500,000 or double your investment (i.e., 100% return), which can take many years and is tough to bear psychologically.
Different managers use different factors and indicators to determine how to make allocation changes, so it’s important to learn more about their specific processes. You can read more about our process in the “What is an adaptive asset allocation” part of our FAQs section on our website. I’m also happy to provide research papers that I’ve used to inform our investment philosophy and process. Simply email info@swadwealth.com for more information.
Q: How did you first learn about dynamic asset allocation, and what led you to specialize in managing dynamic asset allocation portfolios for your clients?
Zack: I first learned about dynamic asset allocation while I worked as an advisor at Charles Schwab. Charles Schwab had a strategy called “Windhaven” that utilized this approach. Also, one of their partner RIA firms that I worked with had been successful for decades by using an active risk management approach. This inspired me to do more research on the topic, so I began reading countless books and research papers. I found that there were certain factors and indicators that have worked consistently throughout history, providing superior returns with less risk.
Furthermore, as someone who specializes in retirement planning, many of my clients cannot afford a major loss in their portfolio, which could significantly delay their retirement or force them back to work if they are already retired. I believe a dynamic allocation approach does a better job of mitigating that risk for them compared to a strategic allocation.
Get to Know Zack Swad, Financial Advisor and Dynamic Asset Allocation Specialist:
Q: Are there particular market environments where you feel dynamic asset allocation is especially valuable to investors?
Zack: I believe a dynamic allocation is best in any market environment; however, it is especially valuable when interest rates or inflation are rising. Traditional portfolios typically have a fixed percentage of their assets in bonds. Unfortunately, bond performance can be hampered by rising rates and inflation. A dynamic allocation allows an investor to move into areas that may be better suited for the current environment instead of holding all asset classes at all times.
Investors need to be careful when considering making a change to a dynamic allocation during bear markets. It’s important to talk to a financial advisor to see if it is “too late” to reduce the risk in your portfolio and determine if there are any tax considerations.
Q: How does the cost of a dynamic asset allocation portfolio compare with a strategic asset allocation?
Zack: Commissions can be higher with a dynamic asset allocation because there is the potential for more trading. Also, because a dynamic asset allocation requires more research and attention, some advisors may charge more for this investment approach. Lastly, because there is more trading or “turnover,” the strategy can incur more taxes if held in a taxable account. With that being said, based on research, I believe the tax drag of our strategies is outweighed by the risk management and return potential.
Q: How do you work with clients to determine whether their investments will be managed with a dynamic or strategic asset allocation?
Zack: When I first started in the industry over 11 years ago, I believed there was only one way to do things. However, after working with hundreds of real people, I found it wasn’t that simple. People are complex, and companies like Dalbar have proven over and over again that investing and savings behavior is the number one factor on an investor’s portfolio return.
Because of this, I educate and ask my clients questions to help determine their investment philosophy. Then, I will align their portfolio to that philosophy, which I believe will give them the best chance of success. The key to investing is sticking with a well-thought-out strategy, one that you will stick with in good times and bad times. Where most people go wrong is they want to change their strategy or allocation style at the wrong time.
Q: For people interested in learning more about dynamic or adaptive asset allocation, are there online resources you recommend people consider?
Zack: For those interested in learning more about dynamic, tactical, and adaptive asset allocation styles, I recommend checking out the extensive work, research, and white papers produced by Mebane Faber. Meb is the co-founder and Chief Investment Officer of Cambria Investment Management and the author of multiple books on investing.
I would also look into the work done by Gary Antonnaci and his book “Dual Momentum Investing: An Innovative Strategy for Higher Returns with Lower Risk.” Gary has over 40 years of experience as an investment professional, received his MBA from Harvard, and his research on momentum investing was the first place winner in 2013 and the second place winner in 2012 of the Founders Award for Advances in Active Investment Management given annually by the National Association of Active Investment Managers (NAAIM).
Are you a financial advisor who specializes in dynamic asset allocation?
✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience. (Subject to availability and terms.) ✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender ✅ Or request more information by email:
🙋♀️ Have Questions About Dynamic Asset Allocation?
Get answers from the Wealthtender network of financial professionals and educators.
About the Author
Brian Thorp
Founder and CEO, Wealthtender
Brian and his wife live in Texas, enjoying the diversity of Houston and the vibrancy of Austin.
With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.
There’s nothing like a crisp morning, a hot cup of coffee, and a great read. Visualizing what your life in retirement will look like is another relaxing activity—perhaps during a stressful workday!
Combining the two activities can go a long way toward planning for your retirement. There are many publications, podcasts, and videos out there these days to help us figure out our retirement journey. And there are so many topics, aren’t there?
Investments, taxes, Social Security & Medicare, estate planning, and insurance are just some areas on the minds of retirement savers and the financial advisors serving as guides to help their clients enjoy a comfortable retirement.
Here are several popular retirement planning books to help you make smarter financial choices when preparing for your golden years, including books written by financial professionals in the Wealthtender community.
The Bogleheads’ Guide to Retirement Planning (Larimore)
“The Bogleheads” are investors who adhere to the simple yet profound wisdom of John C. Bogle, founder of Vanguard Group. Some of the key tenets of retirement planning, per the Bogleheads, are to keep investment costs low, simplify your financial life, know which account types to maximize first, and insure against the inevitable setbacks along your journey. This book is a great read for beginners looking for a no-nonsense take on how to get started preparing for your life after work.
WEALTHTENDER PROFESSIONAL SHOWCASE
The Summit and Beyond : Your Map to the Retirement You Deserve (Decima)
Brennan Decima, Decima Wealth Consulting
Retirement is a major milestone and a testament to years of preparation and discipline. After the big day, many people are wondering what to do next. I wrote Beyond the Summit to give readers a clear map to not only finding fulfillment in retirement but also the tools they need to fund it financially.
After helping thousands of clients transition into retirement, the ones that consistently thrive share similar patterns and demonstrate the same habits. In this book, I share the stories and lessons learned from clients enjoying their adventure the most. Beyond the Summit is your map to give you confidence on your retirement journey. (View on Amazon)
You can learn about retirement straight from the horse’s mouth, too. Bogle wrote several editions of this classic read before his passing in 2019. Dubbed an investing “Bible” by some, Jack’s words offer everyday folks the keys to getting the most out of investment dollars. The “buy and hold” approach is a time-tested method for building long-term wealth, according to the author.
WEALTHTENDER PROFESSIONAL SHOWCASE
Navigating the Street: A Better Approach to Investing (Davis)
Guy Davis, GCI Investors
“I wrote and published a book on this topic, Navigating the Street: A Better Approach to Investing, and 100% believe every private investor should read it. I’ve been an institutional investor for many, many years, and have seen firsthand so many misleading practices, products, and marketing to individuals.
The investment industry does a terrible job of being open with investors, being fair with them, and providing real solutions. I wrote the book to show investors behind the curtain, and help them understand what’s really happening, and help them understand the products they’re being sold constantly.
People just can’t sift through what’s right and what’s helpful for them when they think about managing their assets. This shouldn’t be the case.”
The New Retirement Savings Time Bomb (Slott)
Diving deeper into the nuances of retirement planning, we can look to one of the world’s foremost experts, Ed Slott, on a complex topic for retail investors and professional advisors alike: tax planning. Understanding the tax code can be a tricky proposition. It seems lawmakers are constantly changing things around. Slott is regarded as among the most knowledgeable financial professionals on the topic of IRAs. This book can help you take control of your financial portfolio, avoid unnecessary taxes, and mitigate risks. You might know Ed from his many appearances on public television and financial networks. He is a frequent contributor to many popular investment publications, as well.
More Than Money (Castelli, Due, Schulte)
The book “More Than Money” emphasizes that money is not the sole key to a fulfilling life. Instead, it shows us how we can use money as a tool to achieve our goals, support our vision, and enhance our enjoyment, as well as prepare for life’s tough challenges.
The authors of this book are true professionals and experts in their financial fields and provide some invaluable insights into financial planning. They have also gone beyond sharing financial advice by donating all the book’s net proceeds to two non-profit organizations dedicated to helping people gain access to financial planning resources.
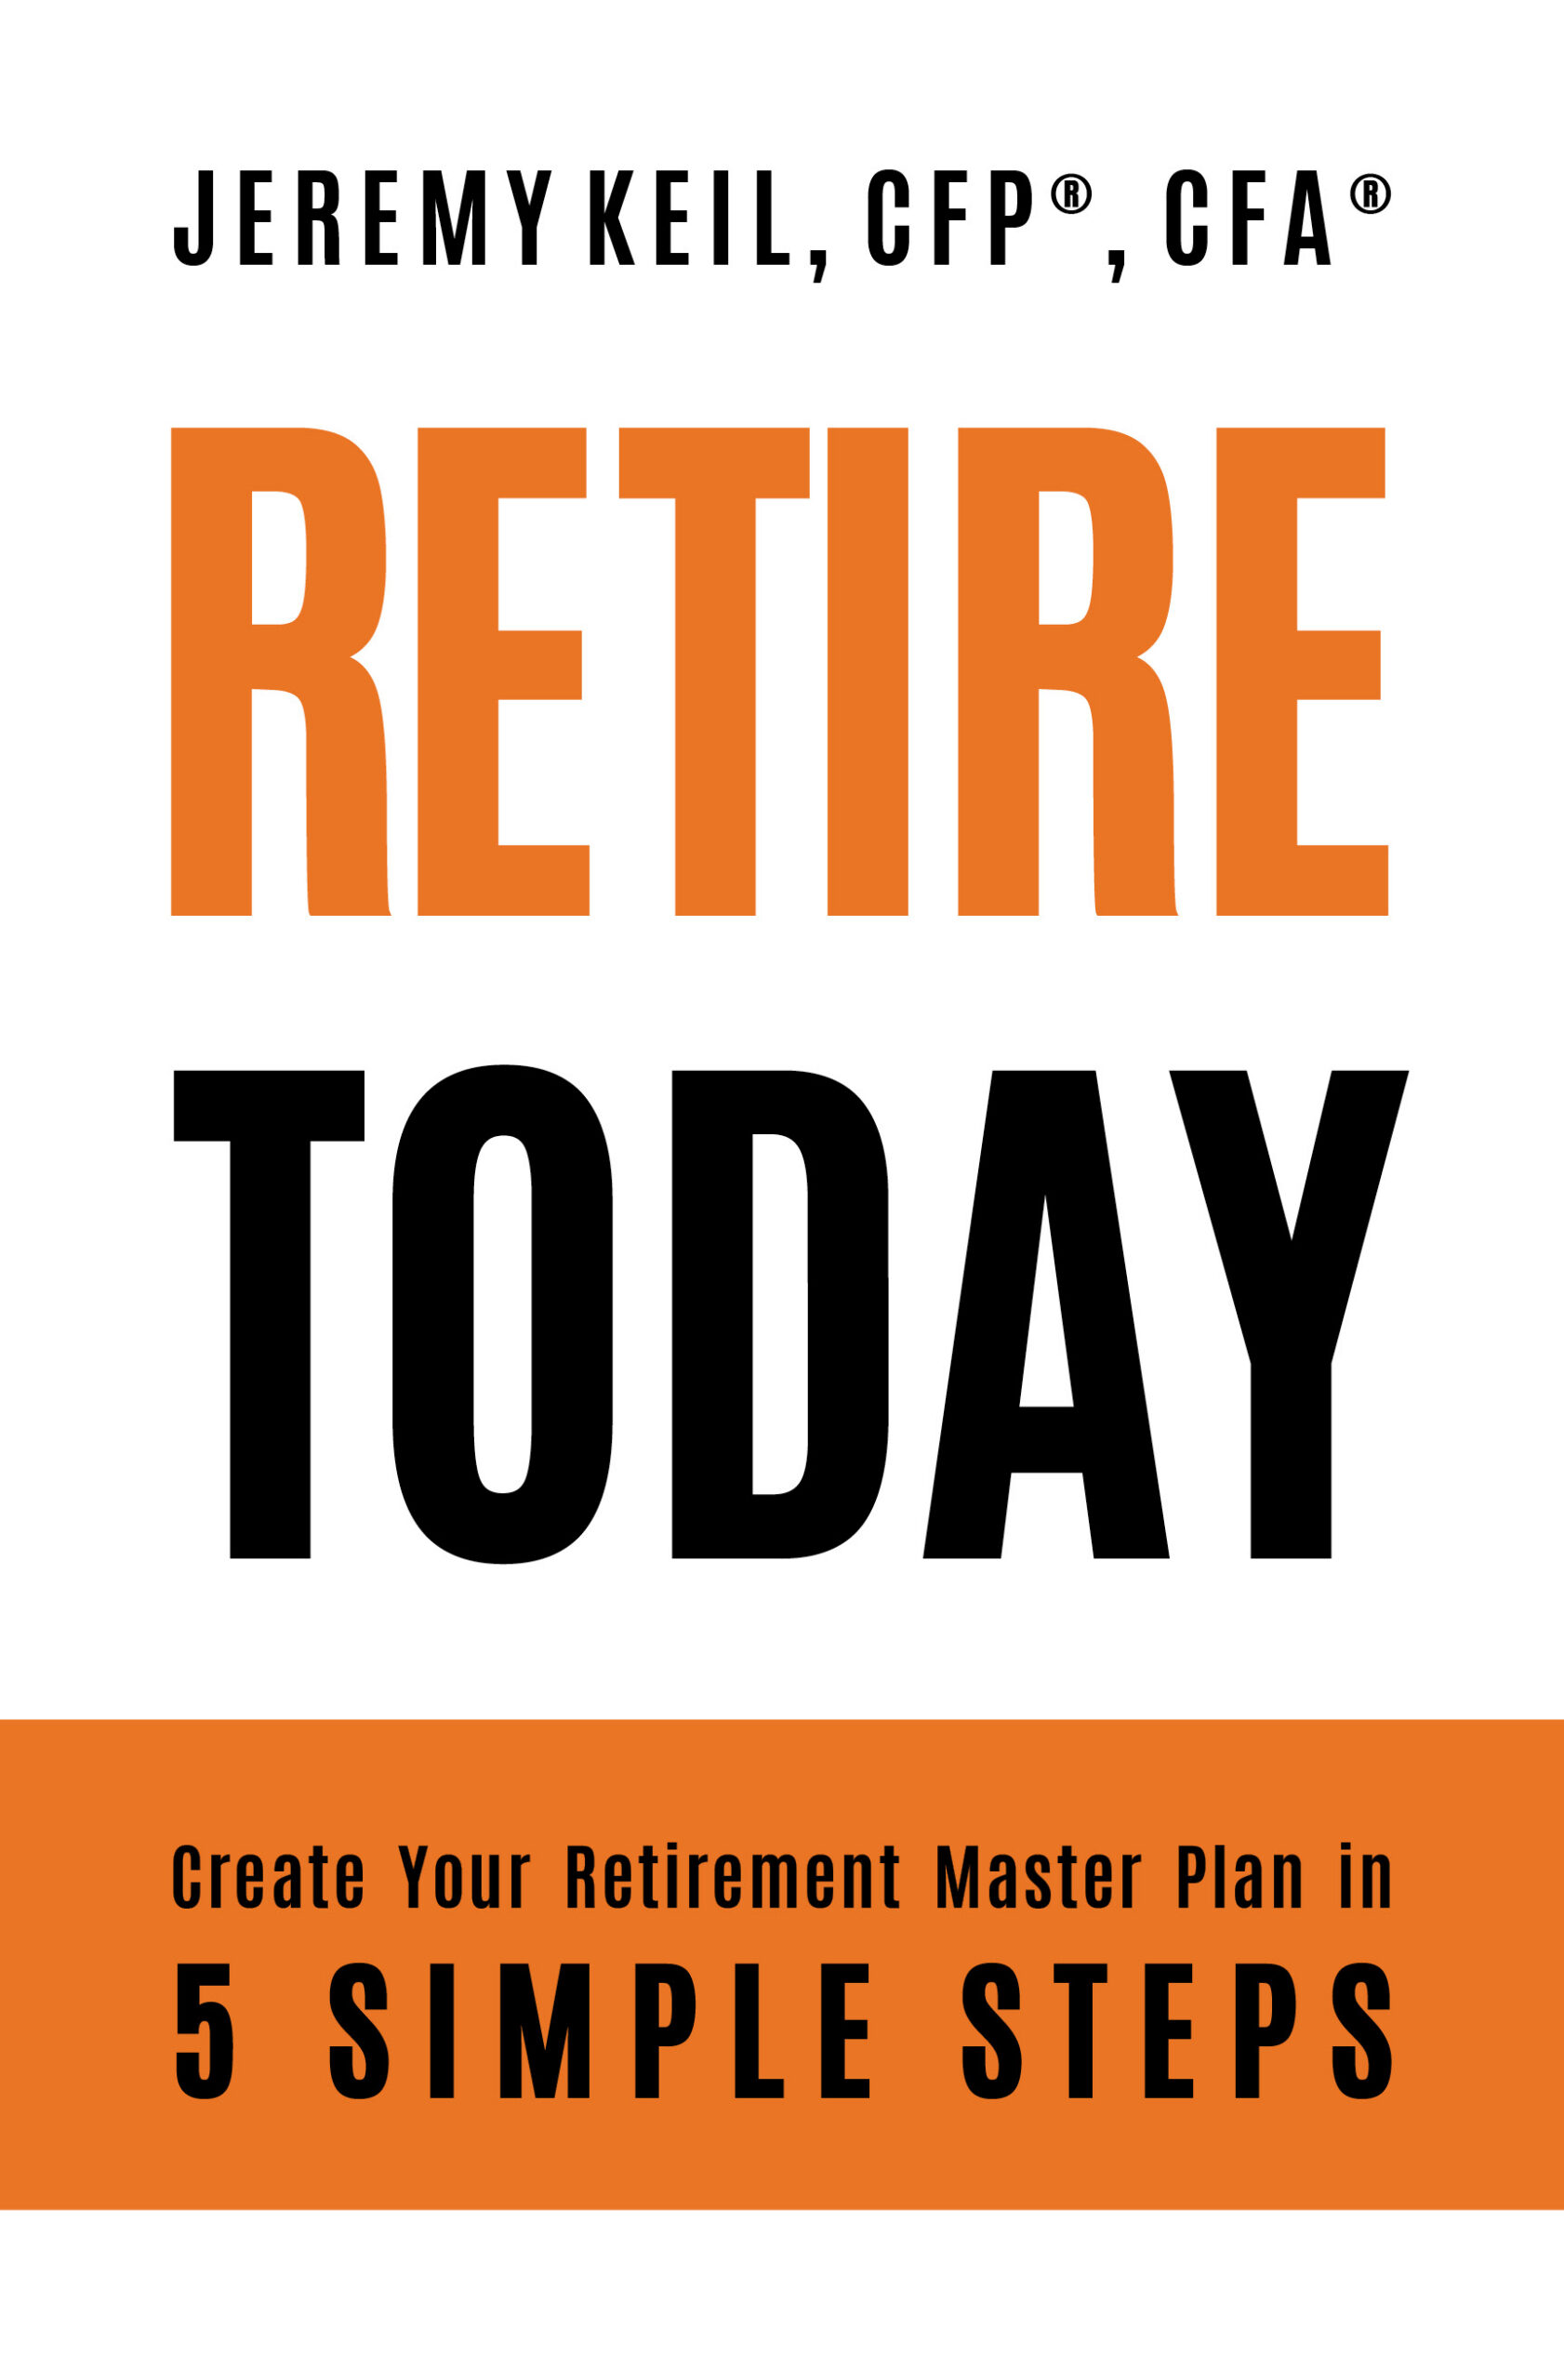
Retire Today: Create Your Retirement Master Plan in 5 Simple Steps (Keil)
Jeremy Keil, Keil Financial Partners
“I wrote Retire Today after seeing how often retirement advice focuses almost entirely on saving and investing, but not on what happens when work ends. In my experience, the real complexity begins when you need to coordinate retirement income, taxes, Social Security, and investments into one cohesive plan.
In this book, I outline a five-step Retirement Master Plan designed to help you think through your retirement income, asset withdrawal, tax strategies, Social Security timing, investment allocation, and legacy decisions. Rather than presenting isolated tactics, I explain how these decisions interact and why you need to coordinate your retirement planning decisions.
Retire Today is written for those within five years of retirement who want structure around important financial decisions. My goal is to present retirement income planning, tax strategy, and long-term planning concepts in straightforward language so readers can approach retirement with greater clarity and confidence.” (View on Amazon)
Wade Pfau is one of the preeminent retirement researchers. As a Professor of Retirement Income, holding a Ph.D. and the CFA Charter, Pfau’s insights into complex areas such as annuities, investments, and insurance are sought by even the savviest financial advisors. In this book, Pfau explains in plain English how people can understand their personal retirement income style. The author then dives into how to strategize Social Security benefits. The alphabet soup that is Medicare is outlined, along with how best to approach finding health coverage in retirement.
Happy Money: The New Science of Smarter Spending (Dunn)
Retirement planning isn’t all about the numbers. An often-overlooked aspect of preparing for the drawdown phase is knowing what kinds of spending habits make you happy. It’s a sad situation when someone saves and saves throughout their working years, but then never figures out what expenditures bring joy. After all, retirement is said to be “funded contentment,” says Brian Portnoy, author of The Geometry of Wealth. Elizabeth Dunn and Dr. Michael Norton, who penned Happy Money, go through the science of spending to optimize pleasure. (View on Amazon)
WEALTHTENDER PROFESSIONAL SHOWCASE
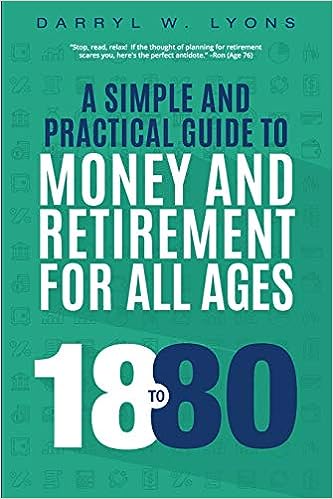
18 to 80: A Simple and Practical Guide to Money and Retirement for All Ages (Lyons)
Darryl Lyons, Pax Financial Group
“I wrote the book 18 to 80 in an effort to fill in the gap that exists in the retirement book space.
In this book, a person can simply open a chapter, find their age, and identify what financial area needs to be addressed in their lives. Because many retirees have kids and parents, they often jump to their kid’s age for financial advice and their parents’ age for financial thoughts.” (View on Amazon)
Among the most prolific and captivating financial writers of our time is unquestionably Morgan Housel. In this 2020 work, he powerfully uses stories to demonstrate tried and true methods of earning, saving, and investing money. You might be surprised at how easy it is to build a solid portfolio through the decades. As the title suggests, human psychology plays a pivotal role in how we behave financially. Equipped with the knowledge Housel provides, you can better understand what true wealth means to you.
Can I Retire? (Piper)
Rounding out our list is a classic by Mike Piper. Without using technical jargon, readers will understand how to use annuities to minimize what might be the biggest fear of retirees: outliving their money. This book also helps retirement savers know how much they will need to fund their future needs. A key question is also addressed: Should you save in a Roth or Traditional IRA? Finally, asset allocation strategies and tax tips can aid even the most seasoned investor. Piper’s CPA background comes through, and your eyes will not be glazed over!
These titles are just a few of so many resources advisors and individual investors can use to learn about both the basics of retirement saving and advanced financial planning strategies. In a world with growing complexity when it comes to investing and planning, it is imperative to stay abreast of the latest rules and trends. At the same time, however, there are classic reads that stand the test of time.
WEALTHTENDER FINANCIAL PROFESSIONAL PICKS
We asked financial professionals in the Wealthtender community to share their favorite books about retirement planning. Here’s what they said.
Stephanie McCulloughDedicated to women on their own who want a true partner in $$ decision-making.
“One of the most practical retirement books I know is written by Emily Guy Birken. All her stuff is great, but The Five Years Before You Retire is especially on-point. Emily guides readers through all the key decisions they need to be thinking about at this crucial financial phase of life, with the important context and educational material to help make informed choices. It’s comprehensive and approachable!”
Beyond picking up a great retirement planning book, hiring a financial advisor can be a smart way to make the transition from your career into your golden years.
📍 Click on a pin in the map view below for a preview of financial advisors who can help you reach your money goals with a personalized plan. Or choose the grid view to search our directory of financial advisors with additional filtering options.
Mike is a freelance writer for financial advisors and investment firms. He’s a CFA® charterholder and Chartered Market Technician®, and has passed the coursework for the Certified Financial Planner program.
Get expert insights from financial advisors who specialize in helping University of Vermont faculty and staff make the most of their compensation package and benefits.
Looking for a financial advisor who specializes in working with University of Vermont faculty & staff? You’re in the right place. Below, you’ll find advisors who understand University of Vermont benefits and compensation — along with their answers to common financial questions from University of Vermont faculty and staff.
Whether you recently joined the University of Vermont or you’ve advanced into a faculty leadership or senior administrative role over a multi-year career, making smart decisions about your income and benefits can have a lasting impact on your financial future. For example:
✅ Do you know the right moves to get the greatest value from the University of Vermont benefits available to you?
✅ If you’re thinking about leaving the University of Vermont for another position or planning to retire in a few years, are you taking the right steps today to receive all the retirement and health benefits you’ve earned?
Key Takeaways
1
Many UVM Employees Don’t Contribute Enough to Get the Full Retirement Match
Missing the match leaves free money on the table. The advisor below also helps employees use both the 403(b) and 457 plans and the Retirement Health Savings Plan.
2
Know the Difference Between an HSA and an FSA — and Don’t Discount Disability Coverage
Confusion between the two accounts affects healthcare, retirement, and taxes, and younger employees often underestimate the likelihood of needing disability insurance.
3
Tuition Benefits and PSLF Can Be Powerful for UVM Employees
Tuition reimbursement can reduce or eliminate college costs, and employees with student loans should plan around Public Service Loan Forgiveness.
Why University of Vermont Faculty & Staff Work with a Specialist Financial Advisor
Throughout the year, the University of Vermont provides its faculty and staff with updates about their benefits, ranging from health insurance to retirement plans like 403(b) and 457 plans and a Retirement Health Savings Plan — along with health savings and flexible spending accounts, disability and life insurance, and tuition benefits. While the university offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with the University of Vermont who specialize in helping University of Vermont faculty and staff make the most of their income and benefits.
The University of Vermont is in Burlington, Vermont, on the shores of Lake Champlain, and is the state’s flagship public research university. Whether you work on campus, at another location, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.
Sensitive topics — like the steps you should take before leaving your job at the University of Vermont for another institution, weighing a buyout or early retirement offer, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.
Should You Hire a University of Vermont Specialist or a Local Financial Advisor?
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving University of Vermont faculty & staff. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with University of Vermont faculty & staff is the better fit for your unique needs.
💡 In the Q&A below, you’ll gain insights from financial advisors who work with University of Vermont faculty & staff to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.
🙋♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.
Q&A: Financial Planning Tips for University of Vermont Faculty & Staff
In this section, you’ll learn how you can make the most of your University of Vermont benefits and gain valuable tips from financial advisors who specialize in working with University of Vermont faculty and staff.
Financial Advisor Q&A · University of Vermont Faculty & Staff
Nev Kraguljevic is a financial advisor based in Shelburne, Vermont, who specializes in offering financial planning services to University of Vermont faculty and staff. Nev helps his clients get the most value from their UVM benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping University of Vermont faculty and staff save for their retirement, how do you help them make the most of their employee benefits?
First, I like to ensure that they are maximizing on the benefits provided by UVM, anywhere from their 403(b) and 457 retirement plans as well as the Retirement Health Savings Plan (RHSP) which helps with health costs during retirement as well as health benefits options while they are employed and looking to leverage the HSA and FSA opportunities. Next, I look for opportunities to ensure employees maximize on other insurances, such as disability and life and for clients who are seeking additional education or have college-bound children, I am a huge fan of the tuition reimbursement and employee discounts. Finally, I always ask my clients if they have student loans, as it impacts our plan and timeline for their PSLF (Public Service Loan Forgiveness).
QWhen you first speak with a University of Vermont employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
I start every client relationship with “getting to know you” meeting. During this 90-minute interaction I like to understand not only their current and future goals, but also their life-time and family relationship with money, their upbringing, their values, the current circumstances, and behavior when it comes to any and all financial decisions. I believe in holistic planning and like to consider their aging parents or other family members, like siblings, children, or anyone else who may become financially dependent on the clients, as I believe all of that impacts how we approach their plan and our collaborative approach to building it.
QIs there a particular benefit available to UVM employees you feel isn’t as well utilized or understood by employees as it should be?
Yes! Three specific pieces come to mind: HSA v. FSA, Disability insurance, and retirement contributions. I find that employees often don’t understand the difference between HSA and FSA and the impact it can have, not only on their healthcare and retirement, but also taxes. I also find, especially with younger employees that they deeply discount disability insurance coverage as an event that they believe has a super-low probability of happening, meanwhile research tells us that the probability is rather high. Finally, the number of employees who don’t even meet the UVM contribution match is really high. I often have to remind folks that this is free money that is readily available to them.
QBeyond the University of Vermont employee benefits for retirement savings, are there other types of benefits offered by the school that you find valuable to discuss with your clients?
Absolutely! First, tuition reimbursement is huge. In the era where a college degree can cost as much as a home, having a benefit where even a portion of that cost can be reduced or even completely removed is tremendous. Second one that I really like is the PSLF track for folks who have student loans. And finally, ability to participate in multiple retirement savings vehicles can give folks a ton of flexibility.
QFor University of Vermont employees thinking about leaving the school to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
Most of the UVM employees when they leave, they go into a different university or college. I have them evaluate not only the new salary, but also benefits that are offered and if they are moving out of state we consider the cost of living in the new area. If they are leaving education or non-profit as a whole, I like to account for the student loans and calculate the impact. And of course, just like any other job, I like to look at the retirement vesting to make sure we account for everything.
QFor University of Vermont employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
This is often challenging, no matter what job or company you are leaving. For some individuals, in addition to income and expenses we talk about the social, purpose, and scheduling impact. For nearly all individuals I have conversations about mental-model change where we shift from accumulation phase to decumulation phase. I find that for many folks this is really hard concept to grasp, which makes perfect sense – you spent your whole life being taught to save and now you have to stop doing that and start taking funds out of it. It can be very weird, uncomfortable, and just plain scarry for many. So we plan and we talk about it and we strategize.
QFor University of Vermont employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
I will be honest to say that I am a little biased here, as I truly believe that everyone can benefit from working with a financial planner. With that being said, here are a few questions to ask yourself:
Do you enjoy dealing with finances, picking holdings and rebalancing your portfolio, keeping up with changes, and continuously learning about money and finance?
Can you have an open and honest conversation with your spouse/partner and other family members about the finances and ensuring everyone is aligned and “rowing” in the same direction?
Are you comfortable spending at least a little bit of time each week or month going through your finances?
Do you know and understand your cash flow (how money comes in and from where and where does it go when it reaches you) and does it support your needs and goals?
Are you maximizing all of the benefits, ensuring proper risk management and insurance coverage, and having a sufficient retirement savings rate?
Have you gone through estate and legacy planning and do you review your documents on regular basis?
Do you understand the financial industry lingo (like difference between stocks and bonds, ETFs and Mutual Funds, expense ratios, load fees, FSA v. HSA…)?
If you have answered yes to all these questions, chances are pretty good you are fine to continue on your own. I do believe (see my self-disclosed bias above) that having a neutral party build and regularly review your financial plan may be a really good idea and beneficial to you.
If, however, you answered most of these questions with no or maybe, I believe you’ll benefit greatly in working with a financial planner, who can not only help you with investment management, but also build other aspects of your financial plan and then work with you to ensure it’s either being followed or ammended, as your situation changes.
If you have answered yes to all questions except for number one (the “enjoy” one), I truly believe you’ll benefit from working with a financial planner well beyond the merely financial perspective.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are University of Vermont employees and how do you help them overcome these obstacles?
Two main challenges come up with UVM employees: academic employment and union vs non-union, staff vs faculty vs executive. And then if we broach into the UVM Health world then we have a whole new set of challenges that play the part. This makes for individualized, unique, and specific planning challenges and opportunities, but all are doable with proper planning.
QWhat questions do you recommend University of Vermont employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
I always tell folks to find individuals who will build their financial plan with them and help them manage and amend it regularly. Second, I remind folks that we all use the same handful of software and set of investments. I truly believe that the real difference is finding someone who gets you, someone who makes you feel seen, heard and safe, and someone that will have your best interest at heart always. Here are a few tips I can offer:
Trust your gut, even if you can’t put your finger on it.
Find someone who will proactively reach out to you with relevant information or update that applies to your life.
Ask hard questions, including hypotheticals.
Pay attention to what questions they ask during the discovery call.
Ask them why and how they chose this career.
QIs there anything that comes up frequently in your initial meeting with University of Vermont employees that surprises you?
All my initial meetings focus on getting to know my clients as people and we rarely even talk about the work. One piece that often comes through from the UVM employees is the commitment to life-long learning and desire to make the world better for the future generations, but that’s not suprising.
QFor highly compensated University of Vermont employees, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?
In short yes, but it all depends on who, where, when… given the multitude of different options it’s really hard to give a quick answer as I believe it’s very much individual impact vs group as a whole.
QIs there a particularly memorable experience or a moment you recall with a client who worked at University of Vermont when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?
I believe that every client has unique opportunities, circumstances and challenges no matter where they work. Partially, it is about the place of employment, but family, age, upbringing, gender, how we process information, etc make a much larger differential in planning needs. What is perhaps unique about public higher education institutions like UVM is the reliance on federal and state funding (in addition to enrollment) and impact on the workforce and the community when those shift.
Considering a financial advisor who specializes in working with University of Vermont Faculty & Staff?
Are you a financial advisor who specializes in working with faculty and staff at the University of Vermont or another college or university?
✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with faculty and staff at the University of Vermont or another college or university. (Subject to availability and terms.) ✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender
Ask a Financial Advisor Your University of Vermont Benefits & Career Questions
Get answers from the Wealthtender network of financial professionals and educators.
Are you ready to enjoy life more with less money stress?
Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.
Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.
A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.
You’re asking the wrong question; ask this instead!
I see it everywhere, and I’m sure you’ve seen it too.
“Delay claiming Social Security to age 70. It’ll grow your guaranteed benefits by 24%!”
If you’re asking, “When should I claim Social Security to get the most money?” delaying is often good advice, and sometimes even excellent advice. But it can lead you into a trap that even smart retirees fall into.
If you ask the wrong question, you may end up making a decision that looks great on the surface, but quietly works against you, given your personal situation.
Morningstar’s Approach: Treat Social Security as Longevity Insurance
Morningstar’s research frames Social Security less as an investment decision and more as insurance against the risk that you’ll live for a long time in retirement.
Into your late 80s, 90s, or beyond.
If that’s what you’re solving for, you want to maximize your guaranteed income by delaying until age 70.
The problem is that, unless you plan to keep working until age 70, your income will be much lower between retirement and age 70. Given that those will be your youngest, healthiest retirement years, you’ll want to spend more then, not less.
Morningstar’s solution is to “bridge” the income gap by drawing more from your nest egg during those years. They analyze three bridge strategies.
A ladder of Treasury Inflation-Protected Securities (TIPS): Withdraw several years’ worth of planned draws from your portfolio and buy TIPS maturing in a year, two years, and three years. This protects you from sequence-of-returns risk by covering your expenses for the first few years of retirement, and ensures the money keeps up with inflation, even if it spikes.
Forgoing inflation adjustment if your portfolio drops: This somewhat reduces how much of your portfolio you may need to sell at lower prices, at the cost of potentially trimming your planned spending. If inflation spikes at the same time, that cut could be large.
Forgoing inflation plus cutting draws by 20%: While this can significantly increase your lifetime spending and remaining balance after 30 years in retirement, it does so by aggressively cutting your spending exactly when you want to spend the most.
All three draw more from your portfolio until age 70 to let you delay claiming Social Security benefits until that age.
This is emotionally appealing for several reasons:
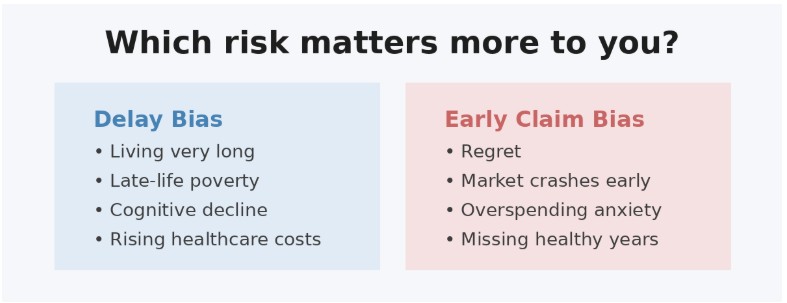
Maximal guaranteed benefits to address fast-rising health expenses, which is especially helpful once financial flexibility declines and cognitive capability may drop.
Reduced dependence on market returns.
Targets one of retirees’ biggest fears – running out of money late in life.
Even if you end up with lower lifetime benefits (if you die before breaking even), you’re buying current confidence for your oldest possible age. That emotional payoff can be more important than optimizing your financial math.
Vanguard’s Approach: Protect Against Regret and Overspending Risk
Vanguard looks at the same decision and highlights a different risk.
Instead of asking, “How do I insure against living a very long time?” Vanguard asks, “What happens if I delay and that turns out to be the wrong bet?”
They don’t say delaying is necessarily a bad choice, but rather that it isn’t optimal for everyone. For example, if you’re wealthy enough (relative to your desired retirement lifestyle) that running out of money isn’t a real concern, and/or you’re not likely to live long enough to break even.
Their suggested approach works to reduce regret and mismatch.
They point out the costs of delaying to age 70:
Drawing down investments faster than comfortable until age 70.
Being forced to constrain spending exactly when you’re healthiest and likely want to spend more, especially if the markets don’t do well during those early years.
Potentially spending less than you could, because you’re uncomfortable seeing your portfolio shrink.
The risk of lower lifetime benefits if you die before breakeven.
The mismatch of higher eventual income in years when most retirees naturally spend less (the so-called “slow-go” and “no-go” years).
If you’re unlikely to live past breakeven, the math of delaying gets flipped.
But even if your personal life expectancy makes you likely to live beyond the breakeven age, if your portfolio throws off far more income than your desired retirement budget, and especially if much of your budget is discretionary (think travel, dining out, gifts, etc.), so you can draw less in market down years, Social Security isn’t your safety net. It’s just one element of a larger financial picture.
As such, early claiming offers multiple benefits:
Reduces the risk of having to sell assets during down years, preserving your portfolio’s longevity.
Supports estate goals.
Offers higher income when you’re healthier and can enjoy spending more.
This approach is emotionally appealing because:
Most people dislike spending more of their assets if they can avoid it.
It reduces the impact of a bad sequence of returns by reducing your dependence on portfolio-based income before age 70.
Many people prefer “a bird in the hand” rather than “two in the bush.”
People want to take advantage of their best health in retirement by spending more when they’re younger.
The emotional punch of this approach doesn’t come from longevity insurance, optimizing your longest-term future at the expense of your present self.
It comes from a feeling of greater control and predictability where you live – in the present.
Reconciling the Differences
At first glance, these conclusions seem to contradict each other. They don’t.
The two finance giants are looking at the same problem, so why do they arrive at such different conclusions?
The answer is that they have different objectives.
Morningstar is concerned with mitigating the so-called longevity risk. That’s the risk that a retiree will survive to a very old age and may run out of money before they die. Vanguard, on the other hand, is trying to mitigate the more immediate risks of regret, stress over spending in early retirement, and a potential mismatch between lifestyle and available income.
Trying to compare their approaches is a classic “apples and oranges” problem. Both are fruits, but different ones, so neither is better nor worse than the other. It’s just a matter of which one you prefer to bite into.
The real mistake is if you try to think of Social Security as an investment to maximize, rather than an insurance to optimize.
The Problem with Considering Social Security as an Investment
Thinking of Social Security as an investment leads you to focus on lifetime benefits and breakeven age. This optimizes for:
The age with the highest probable lifetime payout.
The age you need to exceed to “win” the game.
The internal rate of return.
All are interesting questions, just not the most important ones to consider.
It’s more useful to consider Social Security as insurance against specific retirement-related risks.
These are the real risks you’re insuring against:
Living longer than expected.
Dealing with eventual cognitive decline.
Loss of spending flexibility later in life.
Regret if you end up dying before breakeven.
Your widow(er)’s survivor benefits if you die first and your benefits are higher than hers/his.
Emotional stress over higher spending early in your retirement, leading to a mismatch between your desired lifestyle and what you allow yourself to spend.
Sequence of returns risk, if the market crashes just before retirement or in your early retirement years, in which case not having guaranteed Social Security income hurts your portfolio worse.
Poor health limiting your ability to enjoy spending later in your retirement.
By focusing on risk management over maximizing returns, you realize that you aren’t choosing a claiming age for the eventual financial return. Instead, your choice should be against which risks you want more protection.
If your highest priority is protecting against the first four risks, that tilts the balance toward late claiming. If, on the other hand, you want better protection against the last four risks, early claiming will serve you better.
The decision isn’t a mathematical one that you can solve with a calculator or spreadsheet. It’s a philosophical/emotional one.
It’s about which risks you’re more comfortable with; which potential problems you’re better positioned to deal with financially, and more importantly, from an emotional perspective; and how you want those risks and issues to distribute over the length of your retirement.
The best plan isn’t necessarily the one that offers the better idealized spreadsheet solution; it’s the one you will be comfortable executing. A technically optimal strategy that makes you anxious is not optimal for you.
If you’re more fearful of late-life poverty, you should strongly consider delaying your claim to age 70. If you’re more fearful of missing out on doing things when you’re still healthy enough to enjoy them, an early claim is likely to be a better fit for you.
Both fears are justified.
The problem isn’t that you have them. It’s pretending they don’t apply to you, leading you to ask and answer the wrong question.
What the Pros Say
I asked several financial advisors for their take on Social Security claiming strategies and their experience with clients around this topic. Here’s what they say.
Brett N. Fry, Managing Director at Forteris Wealth Management, relates, “A couple I met with today recently retired and were looking to optimize when to claim Social Security. The numbers came back saying to delay until age 70, but for them, it was a hurdle to know that they would be relying on their portfolio so heavily for the next few years until they got their benefits.
“One of the primary reasons was that they spent their entire lives saving this amount up, and it was hard for them to fathom dipping into the principal to fund their retirement. They were also concerned they would hesitate enjoying life in retirement if they didn’t have some sort of ‘mailbox money’ coming in. Fortunately for them, the numbers for claiming Social Security at their full retirement age, much earlier than 70, also worked, so it was a win-win.”
Claire Pywell, CFP®, of Highline Advisors, reports, “As an advisor, I frequently have open conversations with my clients about their mortality (and feelings about it)! Fear of missing out (FOMO) is a big driver behind the decision to take Social Security earlier than age 70.”
Chris Chen, CFP®, owner of Insight Financial Strategists, agrees and expands, “I find that many people fear not getting a return on their Social Security contributions if they happen to pass away before 70, a form of FOMO.
“It makes sense for most people to delay Social Security to 70. The return you get is difficult to match. It makes a meaningful difference in most financial plans. The best example of when taking social security early makes sense is when people have terminal conditions, so they expect to pass away soon. More generally, people who don’t have enough income or assets to bridge until 70 may need to take social security early.
“My only rule of thumb here is that if you don’t actually need the benefits, you should postpone claiming.
“The biggest regret I see happens when a husband who is a few years older takes the benefit early, and then realizes their wife could have had a higher benefit when he eventually passes away, especially if the wife’s benefit is significantly lower.”
Brady Lochte, Fee-only Financial Advisor & Founder of Axon Capital Management, offers a similar take, “Delaying to 70 is a clear win for clients with longevity in their family, sufficient assets to bridge the gap without portfolio stress, and a need for inflation-protected guaranteed income later in retirement. It doesn’t necessarily make sense if you’re in poor health, need the cash flow now to avoid selling depressed assets, or would deplete retirement accounts so aggressively that you’d face higher RMDs and tax bombs later.
“If you delay claiming and have to bridge, the biggest mistake is using taxable brokerage accounts while leaving 401(k)s untouched, then getting hammered by Required Minimum Distributions (RMDs) later on.
“Fear of missing out on early retirement years drives far more decisions than the math suggests it should. Clients routinely say, ‘I want to enjoy it while I’m healthy,’ even when they have $3 million in assets. It’s emotional, not financial.
“The most common regret I see is claiming early without understanding the permanent haircut to survivor benefits. Widows who lose the higher earner’s benefit because they both claimed early realize too late they optimized for the short term and sacrificed decades of higher income.
“Overall, we find that behavior dominates the math. The math says delay if you can, but clients who are psychologically uncomfortable spending down assets will claim early, no matter what the breakeven analysis shows. They view Social Security as ‘permission’ to retire, not as longevity insurance to optimize.”
Ben Simerly, CFP®, Financial Advisor & Founder of Lakehouse Family Wealth, rounds things out, “If a client is more concerned with maintaining a current account balance than with growth, we encourage them to wait before claiming Social Security. An overly conservative investment portfolio is a common reason why the Social Security amount may grow faster in the government’s hands than in your own accounts.
“Often, clients who are willing to take more risk could do better by taking Social Security earlier and investing the money while they continue to work. Starting Social Security does not mean you need to spend the money. This can also work great for those concerned about future cuts, but still willing to work.
“By and large, the wealthier the client, the more it’s about the math. For clients on the cusp of having enough money to retire, in the $600,000 to $2,000,000 range at retirement in current dollars, we find many clients have already come up with a retirement age in their mind, and likely won’t deviate from it more than a year or two.
“Fear of delaying retirement is the number one driver I’ve seen in making the final decision to begin Social Security or not. For those willing to work part-time or delay retirement, the decision becomes more math-based. But at some point, if you’re burned out from work, the decision becomes about retirement, not math.
“The most common regret we see is when a client or a spouse gets sick, and they regret not retiring sooner. Often, they made the right decision, but the fear of missing out becomes overwhelming. This is why we often encourage clients who are on the fence regarding retirement, due to the math, to work part-time and find a bit of relief from work, but still reduce distributions from their retirement accounts.
“My best advice is, whatever you do, work with someone who can help you do the math. I have yet to see one rule of thumb that consistently works, given how many complex strategies exist surrounding the Social Security decision. Social Security decisions tie into workplace contributions, significant tax planning changes, and more. If I have any rule of thumb, it’s that the first idea folks have often turns out to be the most costly, and doing the math reveals significant gains.”
The Bottom Line: Ignore Slogans, Implement Useful Decision Rules
I wish there were a simple and easy choice that I could recommend, and that I could implement in my own life, now that I’m beyond the earliest claiming age and (mostly) retired!
Unfortunately, it isn’t.
As I often say, personal finance is exactly that – personal.
This applies to Social Security claiming strategies. There’s no universally best claiming age. There’s just the question of which retirement-related risks are your higher priority, which fears take precedence for you.
That’s why both “Always delay claiming to age 70” and “Always claim early” are seductive, but misleadingly incomplete. Following either one blindly replaces a considered, deeply personal insurance decision with a slogan that may not serve you well.
Slogans are catchy and easy to remember.
They’re just not necessarily the best guidance for your personal finances.
Once you accept that Social Security is best understood as insurance against your highest-priority risks, your decision becomes clearer. You stop chasing the highest theoretical payout and design your strategy to help you sleep better at night.
For some, it’s protecting against late-life poverty and loss of independence. For others, it’s mitigating sequence-of-returns risk and matching current income to a desired lifestyle while healthy enough to enjoy it.
Your best bet is to stop obsessing over spreadsheet perfection and optimize for what helps you feel the confidence and emotional stability that lets you execute your financial plans. If that means you want to secure the highest income floor in late retirement, that’s perfectly valid. If it’s enjoying early retirement as much as possible, it’s equally valid.
The trap isn’t in choosing one or the other.
It’s asking the wrong question, solving for the wrong thing, and implementing a slogan rather than what personally helps you most. The right Social Security timing decision isn’t the one that maximizes your benefit check. It’s the one that lets you stop worrying about it.
Now, all I need to do is follow my own advice!
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
About the Author
Opher Ganel, Ph.D.
My career has had many unpredictable twists and turns. A MSc in theoretical physics, PhD in experimental high-energy physics, postdoc in particle detector R&D, research position in experimental cosmic-ray physics (including a couple of visits to Antarctica), a brief stint at a small engineering services company supporting NASA, followed by starting my own small consulting practice supporting NASA projects and programs. Along the way, I started other micro businesses and helped my wife start and grow her own Marriage and Family Therapy practice. Now, I use all these experiences to also offer financial strategy services to help independent professionals achieve their personal and business finance goals. Connect with me on my own site: OpherGanel.com and/or follow my Medium publication: medium.com/financial-strategy/.