Key Takeaways: 

  • Lump-sum and annuity elections have distinct trade-offs. Annuities provide steady income and reduce investment responsibility, but offer less flexibility and no inflation adjustment. Lump sums give you more control, but they also put more market and withdrawal risk on you.
  • Your 401(k) may now need to do more of the heavy lifting. After the freeze, it becomes one of the main sources of future retirement growth. This requires a close review of contributions, matching, catch-up opportunities, and investment choices.
  • Pension decisions should be made as part of a holistic retirement plan. These choices should not be made in isolation from your 401(k), Social Security timing, tax picture, healthcare costs, and other savings or income.

Intermountain’s pension freeze changes the way many employees may need to think about retirement. A benefit that once continued building toward the future now has a defined endpoint, which means other parts of your plan may need to carry more of the load. That shift is not just about the pension itself. It also affects how you need to think about your 401(k), Social Security, personal savings, and the bigger picture of how all your retirement income will eventually come together to support your next chapter.

Step 1: Make Sure You Understand What the Intermountain Pension Means

Intermountain has announced that its pension freeze takes effect on December 31, 2026. Earned benefits are not disappearing. What has already been earned under the pension plan remains protected in trust, and eligible participants may continue to earn additional benefits throughout the year.1

Once the date passes, however, future pension accruals end. At that point, your frozen pension becomes a benefit you’ll need to decide how to take, and you will begin relying fully on the company’s 401(k) program for future employer-sponsored retirement growth.

Lump Sum vs. Annuity: The Main Tradeoffs

From there, one of the biggest decisions is whether to take your benefit as an annuity with steady monthly payments or as a lump sum. The annuity turns the benefit into ongoing pension income, while the lump sum gives you a retirement asset that can be rolled over and managed alongside your other accounts.

The appeal of monthly payments is predictability. The appeal of the lump sum is flexibility. One can help create a dependable income floor, while the other may allow for more control over taxes, investment strategy, withdrawals, inheritance for your heirs and how the money fits into the rest of your plan.

Neither option is automatically better. The right pick comes down to your income needs, your other retirement resources, your comfort with investment risk, and what role you want this benefit to play over time.

Please Note: Intermountain monthly payments are not automatically adjusted for inflation over time, which can reduce real spending power later in retirement. Additionally, once either election is made, and payments or a rollover begin, it is generally irrevocable, which makes thoughtful planning especially important.

Step 2: Review Your Rollover Options Carefully

If you end up making a rollover, it’s important to clearly understand the process before moving any money. A direct rollover is often the most straightforward option because the distribution goes directly to an eligible retirement account. This usually lets the money stay tax deferred and helps you avoid a mandatory withholding upfront.

Rollovers must also be evaluated on their integration with your overall retirement income plan:

  • The receiving account should be chosen based on how it affects your full investment mix and long-term withdrawal plan.
  • Future withdrawals should be reviewed for how they may affect taxable income and Medicare-related costs.
  • Required minimum distributions (RMDs) should be considered now, especially if the rollover adds to tax-deferred balances.
  • The rollover should be evaluated based on the role this money is expected to play in retirement.

Please Note: If the distribution is paid to you instead of going directly to an eligible retirement account, there’s a mandatory withholding of 20% of the taxable amount for federal income taxes. You would then need to complete the rollover within 60 days, and if any taxable portion is not rolled over, those under age 59½ may also owe a 10% early distribution tax unless an exception applies.2

Step 3: Make the Most of Your 401(k)

For many people affected by the freeze, the 401(k) becomes one of the main engines of future growth. That is why this account deserves a more deliberate review now, especially in these core areas:

Contribution Type

Intermountain allows pre-tax and Roth 401(k) contributions. That gives you room to think more intentionally about whether you want to reduce taxable income now, build more tax-free money for later, or use both approaches as part of a broader retirement strategy. 

Annual Limits

Contribution limits shape how much you can actually move into the plan each year. That matters more after a pension freeze because the final working years often become your best chance to increase saving rates, and the catch-up rules available after age 50 and for many workers ages 60 through 63 can make those years especially valuable. 

Employer Contributions

Employer dollars can meaningfully increase your long-term balance, but only if you are positioned to receive them. Make sure you are capturing the full match, understand any additional contributions you may now be eligible for, and review vesting schedules so you know how much of those contributions are truly yours over time.

Investment Mix

With the 401(k) taking on a larger role, your investment choices deserve closer attention. You will need to review your available options and build an allocation based on your time horizon, risk tolerance, and how this account fits alongside your other retirement assets.

Step 4: Review Your Social Security Timing and Other Income Sources

Retirement planning should account for all potential income sources, not just your pension and 401(k). One of the most important is Social Security. 

A few Social Security timing points deserve a close look:3

  • Your full retirement age depends on when you were born. For many current workers, it falls somewhere between age 66 and 67.
  • You can start benefits as early as 62, but starting before full retirement age permanently reduces the monthly amount.
  • Waiting past full retirement age can increase your benefit until age 70, with delayed retirement credits adding 8% for each full year you postpone claiming.
  • For married couples, filing decisions can affect more than one check. Spousal benefits may be available, and timing can change how much a household receives.
  • Medicare timing needs separate attention. If you are not already receiving Social Security, contact the Social Security Administration at least three months before your 65th birthday to enroll and help avoid late penalties.

Understanding Other Retirement Income Sources

Once you account for your Social Security, pension, and 401(k), the next step is understanding how the totality of your income sources will work together. Most retirement plans rely on multiple accounts, and how you withdraw funds significantly impacts your tax burden, financial flexibility, and the longevity of your savings:

Tax-Deferred Accounts

Traditional IRAs and employer-sponsored plans often make up a large share of retirement savings. Withdrawals are taxable and can later be driven by RMDs, which means timing and coordination with other income sources become important.

Roth Accounts

Roth assets can provide flexibility later in retirement since qualified withdrawals are generally tax-free. They can be useful when you want to access funds without increasing taxable income or triggering higher tax brackets.

Taxable Investment Accounts

Brokerage accounts can support early retirement years, help manage income before other benefits begin, and provide flexibility when coordinating withdrawals across different tax treatments.

Cash Reserves

Keeping funds in savings and money market accounts offers a buffer for more immediate needs. These reserves help you avoid selling long-term investments during market dips, which protects and maintains the value of your core retirement assets.

Part-Time Income

Even a modest income stream in the early years of retirement can reduce withdrawal pressure, improve savings outcomes, and create more flexibility around timing decisions.

Step 5: Put Together a Comprehensive Plan for Life After the Freeze

Once you have reviewed the pension decision, the rollover, the 401(k), and Social Security, the next step is seeing how those choices work together. This is where a plan moves beyond separate decisions and starts showing whether it can truly support long-term retirement security.

That broader view helps reveal whether the income plan is efficient, whether risk is concentrated in the wrong places, and whether the strategy still holds up once taxes, timing, healthcare costs, and real spending needs are taken into account.

Model the Main Decisions Together

A helpful plan should compare the decisions that now carry the most weight. That includes modeling monthly pension payments versus a lump sum rollover, testing higher 401(k) contribution rates, capturing the full employer match, and evaluating how a few additional working years may alter the outcome.

When evaluating pension decisions, it’s essential to consider specific risks. Pension payments should be analyzed for inflation risk, as they typically do not have cost-of-living adjustments. Conversely, lump-sum strategies carry sequence of returns risk, where poor early market performance can jeopardize the long-term sustainability of the funds.

A strong comparison should show how these paths perform under pressure. That includes how income is generated, how flexible the plan remains, and how sensitive the strategy is to rises in costs, market performance, and changing spending needs.

Account for Taxes, Healthcare, and Timing

A stronger plan should treat taxes as part of the income strategy from the start. That includes coordinating withdrawals across pre-tax, Roth, and taxable accounts, identifying where partial Roth conversions may reduce future required minimum distributions, and managing income to stay within targeted tax brackets while avoiding medicare costs such as income-related monthly adjustment amount (IRMAA) surcharges.

Similarly, healthcare planning is a critical component of this overall analysis. Those retiring before age 65 will need bridge coverage, which can significantly impact early cash flow. Other important considerations include the strategic use of Health Savings Account (HSA) funds, both before and after age 65, and determining the most effective approach for long-term care needs—whether through insurance, self-funding, or a hybrid strategy.

The key is to take a lifetime view rather than just a year-by-year approach. Proper long-term planning in these areas involves deciding when to recognize income, convert assets, and preserve flexibility so the totals paid across retirement are lower, future RMD pressure is reduced, and health-related costs are kept in check.

Retirement Planning After the Intermountain Pension Freeze FAQs

1. Am I losing what I already earned under the pension?

No. The change affects future accruals, not the pension benefit you have already built. What you have earned remains yours, which makes the planning issue less about loss and more about how to make the most of that benefit going forward.

2. Does a lump sum always make more sense than an annuity?

Not necessarily. The better choice depends on what job you want the pension to do. If you want a stable income floor, an annuity may be more useful. If you want more flexibility over investing, withdrawals, and legacy planning, a lump sum may be worth stronger consideration.

3. What is the biggest rollover mistake people make?

One of the most common mistakes is having the money paid to yourself instead of sending it directly to an eligible account. That can trigger mandatory withholding, create a tight rollover deadline, and increase the risk of otherwise avoidable taxes or penalties.

4. How much should I contribute to my 401(k) now?

That depends on your income, timeline, and the role your 401(k) now needs to play after the pension freeze. At a minimum, many people should make sure they are capturing the full employer match, then evaluate whether higher savings rates and catch-up contributions make sense.

5. Does Peterson Wealth Advisors work with Intermountain employees?

Yes. We are actively helping Intermountain employees navigate this change and get clearer on how the pension freeze affects their retirement planning. That includes helping you think through pension elections, 401(k) strategy, Social Security timing, taxes, and how your overarching financial plan will function across the entirety of your retirement.

We Can Help You Navigate the Intermountain Pension Freeze

The Intermountain pension freeze does not erase what you have earned, but it does raise the stakes on the decisions that come next. The more important question now is how that benefit, along with your 401(k), Social Security, and other assets, will work together to support the retirement you want.

At Peterson Wealth Advisors, we continue to work with Intermountain employees who want clarity on exactly that. Through our Perennial Income Model™, we help clients turn separate accounts and benefits into a coordinated income strategy built around real retirement needs, not rough assumptions.

The freeze deadline is approaching fast. Don’t wait to start planning to bring more clarity to your retirement planning. To learn how we have been helping other Intermountain employees navigate this transition, please schedule a complimentary consultation with our team.

Resources:

1) Intermountain Health Pension Announcement

2) IRS Rollovers

3) Social Security Retirement Benefits

This article reflects the insights and opinions of its author and is not a recommendation or endorsement of their views or services.

About the Author
Headshot of Alex Call, CFP®
Alex Call, CFP® Helping soon-to-be retirees make the transition to and through retirement.

Alex Call, CFP® | Peterson Wealth Advisors
Are you a Physician Assistant?

Get expert insights from a financial advisor who specializes in helping Physician Assistants (also known as Physician Associates) manage student loans, change jobs wisely, and build wealth at every stage of a PA career.

A financial advisor who specializes in working with Physician Assistants can help you navigate student loan strategies, tax planning, and smart investing decisions throughout every stage of your PA career.

Are you a Physician Assistant? Or considering a career as a PA? A financial advisor who understands the distinct financial landscape of Physician Assistants — increasingly referred to as Physician Associates — can help you make smarter money moves at every stage of your career.

Whether you’re fresh out of PA school with significant student debt, weighing a new job offer, or planning your transition into retirement, the financial decisions you make along the way can have a lasting impact. For example:

  • Do you have a clear plan for whether to prioritize paying down student loans or investing more aggressively?
  • Before changing jobs, do you know how your retirement plan vesting schedule and health coverage timeline could affect you?

Key Takeaways

1

Whether to Pay Off Student Loans or Invest Depends on Loan Type, Interest Rate, and Earnings

Many PAs graduate with substantial student debt, and the right balance between paying it down and investing depends on whether loans are federal or private, their interest rates, and projected income. Evaluating these factors together leads to a clearer plan than following a one-size-fits-all rule.

2

PAs Changing Jobs Should Check Vesting Schedules and Health Coverage Before Giving Notice

Leaving shortly before full vesting in an employer retirement plan can mean forfeiting contributions, and knowing when health insurance ends helps avoid a gap in coverage. Reviewing these benefits before resigning can protect meaningful value.

3

Many PAs Feel Embarrassed About Their Finances, but Financial Literacy Isn’t Taught in PA School

Earning a good income doesn’t automatically mean feeling financially organized, and many PAs feel they should already understand topics like backdoor Roth IRAs or refinancing. A specialist advisor can provide guidance without judgment and help PAs build confidence in their decisions.

Why Physician Assistants Work with a Specialist Financial Advisor

Physician Assistants follow a financial path that differs from both physicians and many other healthcare professionals. Significant student debt often arrives alongside a strong starting salary, and decisions about loan repayment, retirement savings, insurance, and taxes all compete for attention early in a career. A financial advisor who specializes in serving PAs understands these tradeoffs and how they change as your career progresses.

PAs also tend to change roles, specialties, and employers more often than many professionals, and each move brings decisions about vesting, benefits, and retirement accounts. An advisor who knows the PA profession can help you evaluate those choices in the context of your long-term plan, from your first job through retirement.

Should You Hire a PA Specialist or a Local Financial Advisor?

You’ll likely find dozens of financial advisors in your hometown well-suited to help you build a personalized plan toward your money goals. But it may be more difficult to find a financial advisor with the specialist knowledge and insights to help you optimize your compensation package, manage the student loan burden that often accompanies PA school, navigate contract negotiations, and make the most of the tax strategies and retirement planning opportunities available to Physician Associates.

Fortunately, many financial advisors now offer virtual services so you can meet online no matter where you practice, whether you’re working in a bustling emergency department in Boston, a family medicine clinic in Phoenix, or a surgical specialty group in Seattle. This means you can choose to hire a financial advisor who lives hundreds of miles away from your clinic or hospital if you believe their knowledge about financial planning for PAs could help you achieve better outcomes with your money.

Whether you’re a newly certified PA-C still paying down loans from your graduate program, a mid-career Physician Associate weighing a move into a higher-paying specialty, or a seasoned PA planning your path to retirement, partnering with an advisor who understands your profession can make a meaningful difference in your long-term financial well-being.

In the Q&A below, you’ll gain insights from financial advisors who work with Physician Assistants to help them make smart decisions to enjoy life more today while preparing for a comfortable retirement in the future.

Do you have questions not answered below? Use the form on this page to submit your questions, and we’ll update this article with answers from the financial professionals and educators in the Wealthtender community. You can also contact the financial advisors featured in this article directly to set up an introductory call or ask your questions by email.

Q&A: Financial Planning Insights for Physician Assistants

In this section, you’ll gain valuable tips from a financial advisor who specializes in working with Physician Assistants (PAs).

Financial Advisor Q&A  ·  Physician Assistants

Caleb Pepperday, CFP®, ChFC®, Financial Advisor for Physician Assistants at Advanced Practice Planning, LLC

Caleb Pepperday, CFP®, ChFC®

Advanced Practice Planning, LLC  ·  Missoula, MT  ·  Serves clients nationwide

Wealth Management for Physician Assistants/Associates | PA-Cs | Fiduciary
Book Intro Call

We asked Caleb Pepperday, a financial advisor based in Missoula, Montana who specializes in serving Physician Assistants nationwide, to answer questions useful to PAs interested in making smart money moves throughout their career and to prepare for a comfortable retirement.

QHow do the services you offer to PAs distinguish your firm from other advisory firms?

Most financial advisory firms are built to serve a broad audience. They work with business owners, retirees, tech workers, physicians, and anyone else who walks through the door. There’s nothing wrong with that, but it means the advice tends to be general. I primarily work with Physician Assistants, their families, and a small number of other advanced practice providers. My wife is a PA. My brother is a physician. My sister-in-law is a nurse practitioner. I live in this world every day, and that shapes how I approach every financial plan I build.

Because I specialize, I already understand the details that a generalist advisor would need you to explain. I know how PA compensation structures work across different specialties and practice settings. I know what a typical PA benefits package looks like, including the gaps most PAs don’t realize they have. I know the career trajectory, the burnout timeline, the student loan burden, and the retirement plan options that come up over and over again. That means we spend less time on background and more time on strategy.

I’m also fee-only, which means I don’t sell insurance products, annuities, or investment products that pay me a commission. You pay me directly for advice, and that’s my only source of income from the relationship. I don’t have sales quotas or product minimums. My job is to give you the best advice I can and help you act on it. that.

QFor PAs thinking about leaving their current employer to accept a job elsewhere, what actions do you suggest they take before resigning and shortly thereafter?

Before you give notice, get your financial house in order on the benefits side. Review your current employer’s vesting schedule for retirement plan contributions. If you’re 80% vested and full vesting happens in four months, it might be worth staying a little longer to lock that in. Check your health insurance coverage and figure out when it ends. Knowing that timeline helps you avoid a gap in coverage, especially if you have a family.

Next, take a hard look at the new offer beyond the base salary. Compare the full picture: retirement plan match, health insurance premiums, disability coverage, CME reimbursement, malpractice insurance, PTO, and any signing bonuses or relocation stipends. I’ve seen PAs take what looked like a raise only to realize the new employer’s benefits were so much worse that they actually came out behind. If you’re not sure how to compare two offers side by side, that’s the kind of planning I help with.

After you’ve made the move, there are a few things to take care of quickly. Review your new benefits elections carefully, especially life and disability insurance, and make sure you’re not leaving coverage gaps. Decide what to do with your old employer’s retirement plan. A job change is one of the most financially significant events in a PA’s career, and taking a few hours to get these details right can save you a lot of headaches later.

QFor PAs approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?

The first thing we do is build a clear picture of what retirement actually costs. Not a guess. An actual month-by-month breakdown of what you spend, what you’ll need to spend, and what changes when you stop working. Some expenses go down in retirement (commuting, work clothes, CME costs, maybe a mortgage, etc.). Others go up (healthcare is the big one, especially if you retire before 65 and need to bridge the gap to Medicare).

Once we know the spending target, we figure out where the income comes from and when. Social Security, retirement accounts, brokerage accounts, pensions (if you have one), rental income, and any other sources all have different tax treatments and timing considerations. The order in which you draw from these accounts matters a lot. Pulling too much from a traditional IRA early in retirement can push you into a higher tax bracket and increase your Medicare premiums. On the other hand, waiting too long can leave you with a massive required minimum distribution problem in your 70s. This is where a withdrawal strategy, mapped out year by year, makes a real difference and can save you serious money on your lifetime tax bill if done properly.

I also encourage PAs who are three to five years out from retirement to start practicing what it’s like to live like a retiree. Try living on your projected retirement budget for a few months while you’re still earning a paycheck. See what areas you struggle with the most. This dry run gives you confidence that the plan works and helps you spot problems while you still have time to fix them.

QIs there anything that comes up frequently in your initial meeting with PAs that surprises you?

One that comes up a lot is embarrassment. PAs often feel ashamed that they make good money but don’t feel financially organized. They’ll say things like, “I should know this already” or “I feel dumb even asking.” That’s not something I take lightly. Financial literacy isn’t taught in PA school. There’s no reason anyone should feel bad about not knowing how a backdoor Roth IRA works or when to refinance their mortgage. My job is to meet people where they are, not judge them for not being financial experts on top of being medical professionals.

I’ll also say this: a lot of PAs come into the first meeting thinking their situation is a mess, and it turns out they’re actually doing better than they think. They’ve been saving in their 401(k) for years, they have some emergency savings, and they’ve been paying down their loans. They’re not starting from zero. They just need someone to look at the full picture and tell them, “Here’s where you are, here’s where you want to be, and here’s how we close that gap.” That moment of clarity is usually a big relief.

QShould PAs prioritize paying off student loans or investing more aggressively?

I’ve answered this question dozens of times. It’s one of the most common questions that I get from PAs. Most PAs I see graduate with somewhere in the ballpark of $80,000 and $150,000 in student debt.

Here’s how I think about it.

Much depends on your loan type (federal versus private), your interest rate, and your projected earnings. Once we evaluate this, we can formulate a plan on whether or not it makes sense to contribute more to your savings, whether that be money you can access prior to retirement or focus more on your retirement savings. That match is free money, and the math on that is hard to beat.Beyond this, we look at things like whether you qualify for Public Service Loan Forgiveness, what your marginal tax rate is, and whether Roth contributions make more sense right now given your income level. These aren’t one-size-fits-all decisions. A PA working at a nonprofit hospital has a very different playbook than one working at a private dermatology practice.

What I typically build for clients is a priority ladder. We figure out the order of operations which may look something like this: emergency fund, employer match, high-interest debt, Roth IRAs, additional loan paydown, taxable investing. The exact order changes based on your situation, but having that structure in place takes the guesswork out of where each paycheck should go. The goal isn’t to choose loans or investing. It’s to do both in the right proportions at the right time.

Caleb Pepperday, CFP®, ChFC®, Financial Advisor for Physician Assistants at Advanced Practice Planning, LLC

Considering a financial advisor who specializes in working with Physician Assistants?

Are you a financial advisor who specializes in serving Physician Assistants?

Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience (subject to availability and terms). Sign up today and join financial advisors attracting their ideal clients on Wealthtender, or request more information by email:

  • This field is for validation purposes and should be left unchanged.
Ask an advisor

Have Questions About Financial Planning for Physician Assistants?

Keep exploring

Find the Right Financial Advisor for You

Browse specialists, compare advisors near you, or find advisors who know your employer’s benefits.

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

[Maximizing after-tax returns by combining superior stock selection with rigorous and active tax management, once only available to UHNW investors,  has become an integrated investment option with growing accessibility to the mass investment market. These tax-managed strategies – not only using loss harvesting – can deliver a customized investment solution with a focus on total return as a source of alpha to construct a portfolio with an optimal balance of risk, return, and cost.

To better understand how tax-managed investment strategies are designed and implemented, we were introduced to Jon Quigley, Chief Investment Officer and John Bright, Senior Portfolio Manager of Great Lakes Advisors Disciplined Equity Tax Managed Strategies. Great Lakes Advisors, LLC is a Chicago-based asset manager founded in 1981 that offers a wide range of client-focused, actively managed equity, fixed-income, and multi-asset strategy solutions. 

We focused our questions specifically on their tax-managed strategy that has actualized the age-old euphemism – “It’s not what you make, it’s what you keep”- into a personalized and widely accessible tax-managed investment solution for a wider swath of investors.]

Hortz: Why did you, as an investment manager, decide to develop tax-managed versions of your portfolios? What experiences and/or research led you to this decision?

Quigley: The Disciplined Equity team has always been driven to build solutions that meet the needs of our clients. Many of our strategies were launched to provide an investment solution for clients who had a specific need that was not met well in the marketplace. Our tax-managed strategies were launched for a large set of clients over 20 years ago. 

Bright: We realized our investment process directly lends itself to be a differentiated solution to a problem that was largely overlooked by many. The way we construct our portfolios gives us a great advantage in custom solutions like Tax Management and ESG. The tax-managed strategies were designed to reduce the tax drag of traditional equity strategies while maintaining the opportunity to outperform on a pre-tax basis.

Hortz: Why might the end of the year not be the best time for tax management?

Quigley: Many advisors and investment managers start looking for unrealized losses near year-end either as a service or at the request of their clients. History shows us that we would miss the lion’s share of harvesting opportunities by following that norm. Historically, November and December experience negative returns only around 20% of the time, while January and February have posted negative returns around 50% of the time over the last 25 years.

Calendar years such as 2012, 2014, 2015, 2016, 2020, and 2025 all experienced stock market losses in the early part of that year that eventually became gains by the time tax harvest season approached. That adds up to missed opportunity costs by only focusing on harvesting a few times per year.

Our approach gives us the ability to harvest losses opportunistically throughout the year, taking advantage whenever market volatility arises.

Hortz: What are some of the major applications for a tax-managed strategy? Who would be best served by a tax-managed investment solution?

Quigley: The best answer is that any taxable equity account should consider a tax-managed solution. However, there are some very compelling use cases. An advisor trying to win business from a prospect with taxable money needs a plan on how to best take over those securities. Our solution shows the client and advisor the plan we would use to transition into a tax-managed strategy without selling the entire portfolio. Having a plan helps the advisor to win over that prospect. 

Many investors have added ETFs over the last several years which are tax-efficient if you buy and hold. They offer little flexibility for investors who need to change investments or make transactions. We can manage ETF’s while adding individual securities to give investors more flexibility and reduce index concentration.

Bright: Additional opportunities are clients with unmanaged portfolios, slowly unwinding concentrated positions, or changing from other investment strategies or broker-dealers.

We also manage these strategies for Corporate taxable plans and Insurance companies that need tax efficiency in their equity allocations.

Hortz: How do you go about adapting an investment strategy to a tax-managed approach? What are the key steps to take to structure and implement that strategy transition?

Bright: Our investment process gives us a great opportunity to include tax management by design. Our focus on portfolio construction, risk, and return opportunities gives us insight across the entire equity market, security by security. Tax Management becomes a natural extension of the process.

We evaluate each position’s contribution to risk and return while understanding the imbedded tax cost.  When rebalancing, we can harvest losses, replacing the “loss” security with a similar position that improves portfolio risk and return opportunities.

Hortz: How did you specifically design your investment and portfolio construction process to attempt to beat benchmarks after taxes?

Quigley: Our process is designed as an institutional-quality strategy that fits into an asset allocation plan, which delivers a risk-controlled portfolio that focuses on stock selection as the main source of risk and return. By not making large market cap, sector, or industry bets, we are able to ensure we add value through stock selection which has been our largest source of relative performance historically.

With the ability to provide outperformance on a pre-tax basis, this allows us not to rely on loss harvesting solely for alpha. In years where loss harvesting is more difficult, this provides us an advantage to prevent portfolio lockup and adds flexibility to generate after-tax returns. 

Hortz: How do you approach the transition management for a client’s portfolio to transfer their assets to a tax-managed account?

Bright: We use our Transition Analysis tool to evaluate each portfolio. Each client comes to us with a unique set of holdings and cost basis. Positions are not sold off because they are not in a “model”.  Each lot, of each position, is evaluated for its risk contribution, return potential, and tax cost. This allows us to build a unique transition plan for each client utilizing a combination of their existing positions while adding positions that improve the risk and return potential.

Additionally, we try to minimize the tax impact at transition. Given our active approach, transitioning a portfolio generally has a lower upfront tax cost than most other strategies available.

Hortz: What technology issues are involved in a tax-managed account? How has tech enabled the ability to scale investment tax management to a larger audience?

Quigley: Technology is at the heart of the tax-managed solution. Coupling a proprietary technology platform with long-standing vendor partners allows us to individually manage each account at scale.  Bringing together risk exposures, individual tax lot information, market information, and return forecasts requires a strong data platform to effectively implement the tax-managed strategies. Improvements in technology across broker-dealers and custodians allow for better trading and accounting strategies with more partners across the marketplace.

Hortz: Any thoughts for advisors and other professional investors on how to explain and deploy these tax-managed vehicles into their clients’ overall portfolio?

Bright: We spent years refining and improving our Transition Analysis report to better serve our advisors and clients. The report shows a snapshot of current holdings and what those look like holistically across risk exposures, sectors, industries, and where the account stands from a tax standpoint.

The proposed portfolio we will generate will intuitively demonstrate the improvements we would make across the portfolio at transition and what the tax cost would be to effect the changes. This report can be used by an advisor with their client to understand how their portfolio would change at transition.

Quigley: We have also developed further support for our financial intermediary partners with our “Unlocking Investment Potential” overview/video and the “Advisor’s Guide to Tax-Managed Investing – An Often Overlooked Yet Growing Opportunity” e-book.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

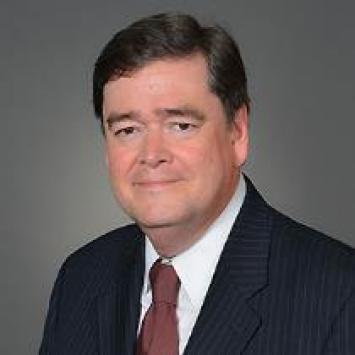
A middle-aged man, Bill Hortz, with short dark hair wearing a dark pinstripe suit, white dress shirt, and a maroon tie, posing against a plain gray backdrop. He has a slight smile and is looking directly at the camera.

Bill Hortz

Founder Institute for Innovation Development

Bill Hortz is an independent business consultant and Founder/Dean of the Institute for Innovation Development- a financial services business innovation platform and network. With over 30 years of experience in the financial services industry including expertise in sales/marketing/branding of asset management firms, as well as, creatively restructuring and developing internal/external sales and strategic account departments for 5 major financial firms, including OppenheimerFunds, Neuberger&Berman and Templeton Funds Distributors. His wide ranging experiences have led Bill to a strong belief, passion and advocation for strategic thinking, innovation creation and strategic account management as the nexus of business skills needed to address a business environment challenged by an accelerating rate of change.

Do you work at Amazon?

Get expert insights from a financial advisor who specializes in helping Amazon employees and executives make the most of their compensation package and benefits.

Looking for a financial advisor who specializes in working with Amazon employees? You’re in the right place. Below, you’ll find an advisor who understands Amazon benefits and compensation — along with his answers to common financial questions from Amazon employees and executives.

Whether you’re a new Amazon employee or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and Amazon benefits can have a lasting impact on your financial future. For example:

  • Do you know the right moves to get the greatest value from the Amazon benefits available to you?
  • If you’re thinking about leaving Amazon for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?

Key Takeaways

1

Amazon’s back-weighted RSU vesting schedule delays most of your equity income to years three and four.

Because only a small share of a new hire’s grant vests early, the advisor featured below recommends budgeting around guaranteed salary in the first two years and building a written plan for the larger vesting events before they arrive. Waiting until shares hit your account usually means reacting to a tax bill instead of managing one.

2

RSUs are withheld at the flat supplemental wage rate, which is often below what highly compensated Amazon employees actually owe.

Restricted stock units are taxed as ordinary income at vest, but default withholding is set at the supplemental rate rather than your marginal bracket. Chris Williams helps clients anticipate future vesting events, understand withholding requirements, and evaluate how those taxable events affect their broader tax picture before the bill arrives.

3

Concentration risk is the planning issue Amazon employees underestimate most.

Long-tenured employees frequently discover that a large share of their net worth sits in a single stock, and that their income is tied to the same company. Chris Williams walks clients through how much Amazon stock they are comfortable holding, when to diversify, and how to coordinate those decisions with taxes and long-term goals.

Why Amazon Employees Work with a Specialist Financial Advisor

Throughout the year, Amazon provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like the 401(k) and equity compensation in the form of restricted stock units. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with Amazon who specialize in helping Amazon employees make the most of their income and benefits.

Whether you work at the Seattle headquarters in South Lake Union, the Puget Sound campus in Bellevue, Washington, HQ2 in Arlington, Virginia, the Operations Center of Excellence in Nashville, another corporate office or tech hub around the country, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.

Sensitive topics — like the steps you should take before quitting your job at Amazon to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.

Should You Hire an Amazon Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Amazon employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with Amazon employees is the better fit for your unique needs.

In the Q&A below, you’ll gain insights from a financial advisor who works with Amazon employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.

Have a question not yet answered? Use the form below to submit it anonymously and watch this article for updates with answers to your questions. You can also reach out to the financial advisor below to set up an introductory call or contact him with your questions by email.

Q&A: Financial Planning Tips for Amazon Employees & Executives

In this section, you’ll learn how you can make the most of your Amazon employee benefits and gain valuable tips from a financial advisor who specializes in working with Amazon employees and executives.

Financial Advisor Q&A  ·  Amazon Employees

Chris Williams, AIF, CRPC, Financial Advisor for Amazon Employees at Capital Fiduciary Advisors

Chris Williams, AIF®, CRPC®

Capital Fiduciary Advisors  ·  Ashburn, VA  ·  Serves clients nationwide

Specializes in Amazon employee financial planning & equity compensation
Book Intro Call

Chris Williams is a financial advisor based in Ashburn, Virginia who specializes in offering financial planning services to Amazon employees. Chris helps his clients get the most value from their Amazon benefits and compensation package so they can enjoy life and feel confident about their financial future.

QAs a financial advisor with experience helping Amazon employees save for their retirement, how do you help them make the most of their employee benefits?

I help Amazon employees maximize their retirement benefits by creating a strategy that coordinates their 401(k), company stock (RSUs), and overall investment portfolio. We review contribution levels to capture the full employer match, evaluate Roth versus pre-tax savings opportunities, and develop a plan for managing equity compensation to reduce unnecessary concentration risk and taxes. I also help clients align their employee benefits with their long-term goals, whether that’s early retirement, buying a home, funding education, or building long-term wealth. My goal is to simplify complex benefits and provide personalized and independent guidance so clients can make informed financial decisions with confidence.

QWhen you first speak with a Amazon employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?

During my initial conversation with an Amazon employee, I focus on understanding both their financial goals and their overall financial picture. I ask about their short- and long-term objectives, such as retirement, buying a home, education funding, or achieving financial independence. We discuss their current retirement savings, equity compensation (including RSUs), cash flow, debt, and investment experience. I also ask about their comfort with investment risk, tax situation, and any upcoming life changes that could impact their financial plan. Understanding how they’re currently using their Amazon benefits helps me identify opportunities to optimize their retirement strategy, manage equity compensation effectively, and create a personalized plan that aligns with their goals and values.

QIs there a particular benefit available to Amazon employees you feel isn’t as well utilized or understood by employees as it should be?

In my experience, one of the most underutilized benefits available to Amazon employees is the opportunity to integrate their employer benefits into a comprehensive financial plan. Many employees take advantage of the 401(k), but fewer maximize the company match or periodically review their investment allocation. Additionally, Amazon employees often accumulate a significant portion of their wealth in restricted stock units (RSUs). While these can be a valuable source of wealth creation, many employees don’t fully understand the risks of concentration or how RSUs affect taxes and long-term planning. Helping employees coordinate their retirement savings, equity compensation, tax strategy, and overall investment portfolio can significantly improve long-term financial outcomes.

I also find that many employees overlook Health Savings Accounts (HSAs), backdoor Roth IRA opportunities (when appropriate), and the importance of planning around RSU vesting events. Education in these areas can add substantial long-term value and help employees make more informed financial decisions

QBeyond Amazon employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients (e.g. stock, education savings, health savings)?

Absolutely. While retirement savings are an important foundation, I believe Amazon’s broader benefits package presents several valuable planning opportunities. Equity compensation, including restricted stock units (RSUs), is often one of the most impactful benefits to discuss because it affects cash flow, taxes, diversification, and long-term investment strategy. Helping employees understand vesting schedules, tax withholding, and concentration risk can have a meaningful impact on their financial outcomes.

I also encourage clients to fully evaluate their Health Savings Account (HSA), when eligible, as it can serve as both a healthcare funding vehicle and a tax-efficient long-term savings tool. Education savings strategies, such as 529 plans, are another important consideration for employees with children, particularly when coordinated with their overall cash flow and retirement goals.

Beyond those benefits, I discuss life and disability insurance, employee stock purchase opportunities (when available), estate planning considerations related to equity compensation, and how all employer benefits fit within a comprehensive financial plan. As a fiduciary, my objective is to help clients maximize the value of their entire compensation package while aligning each benefit with their long-term financial goals, tax situation, and risk tolerance.

QFor Amazon employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?

When an Amazon employee is considering leaving the company, I recommend taking a comprehensive review of their financial situation before submitting their resignation. The timing of a departure can have a significant impact on benefits, equity compensation, taxes, and long-term financial goals.

First, I encourage employees to understand their Amazon Restricted Stock Unit (RSU) position, including upcoming vesting dates, tax implications, and whether it makes sense to hold or diversify their company stock after leaving. Many employees have accumulated significant wealth through Amazon equity, and managing concentration risk is an important part of a prudent financial plan.

I also recommend reviewing their retirement accounts and benefit elections before leaving. This includes understanding their 401(k) options, evaluating whether to leave assets in the plan, roll them over, or consider other strategies, while also being mindful of fees, investment choices, and creditor protections. Employees should also review Health Savings Accounts (HSAs), Flexible Spending Accounts (FSAs), life insurance, disability coverage, and any other benefits that may change after separation.

From a tax planning perspective, employees should consider how their final compensation, RSU vesting, bonuses, and potential equity sales may affect their tax situation. In some cases, coordinating the timing of these decisions with a financial advisor and tax professional can create meaningful opportunities.

Ultimately, the goal is to make the transition intentional rather than reactive. As a fiduciary, I help clients evaluate the full impact of a career change—ensuring their compensation, benefits, investments, and financial plan remain aligned with their long-term goals

QFor Amazon employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?

For Amazon employees approaching retirement, I recommend beginning the transition well before their final day of employment. Moving from a steady paycheck to relying on accumulated assets requires a thoughtful income strategy, not just an investment strategy.

The first step is to create a clear retirement income plan that identifies where future cash flow will come from, including 401(k) assets, taxable investments, Social Security, Amazon equity compensation, pensions (if applicable), and other sources of income. The goal is to determine how these resources work together to support their lifestyle while managing longevity, market, and inflation risks.

I encourage employees to evaluate their Amazon equity position carefully before retirement. Many long-tenured employees have built significant wealth through RSUs, but retirement is also a time when diversification and risk management become increasingly important. Developing a strategy for vested shares, taxes, and portfolio allocation can help protect the wealth they have created.

Tax planning is another critical component. Decisions around Roth conversions, timing of withdrawals, Social Security claiming strategies, required minimum distributions, and the coordination of taxable and tax-deferred accounts can have a significant impact on retirement income and lifetime tax liability.

I also recommend reviewing healthcare coverage, including Medicare planning and the role of Health Savings Accounts (HSAs), as well as updating estate plans, beneficiary designations, and insurance coverage.

Ultimately, the transition into retirement is about shifting from wealth accumulation to wealth management and distribution. As a fiduciary, my role is to help Amazon employees create a personalized retirement roadmap that provides confidence, flexibility, and alignment between their financial resources and the lifestyle they want to maintain.

QFor Amazon employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?

Many Amazon employees are highly capable and have successfully managed their finances on their own, especially during the wealth accumulation phase of their careers. The decision to work with a financial advisor is not necessarily about whether someone can manage their own money—it is about whether professional guidance can help them make better, more informed decisions as their financial situation becomes more complex.

As employees progress in their careers, factors such as RSUs, increased compensation, tax planning, retirement readiness, estate considerations, and balancing multiple financial goals can create challenges that require a more coordinated approach. A financial advisor can help bring those pieces together and ensure decisions made in one area do not negatively impact another.

I recommend employees consider working with an advisor when they find themselves asking questions such as: Am I properly diversified given my Amazon stock exposure? Am I making the most tax-efficient decisions with my equity compensation? Am I on track for retirement? When should I begin taking Social Security? How should I transition from saving to generating income?

A fiduciary advisor should serve as a partner and objective sounding board—helping clients clarify goals, evaluate trade-offs, and create a personalized financial strategy. The value is not simply investment management; it is the ability to coordinate their entire financial picture and provide confidence that their decisions are aligned with their long-term objectives.

Ultimately, the right time to engage an advisor is when financial complexity begins to increase and the cost of making a mistake becomes greater than the cost of receiving professional guidance. A good advisor should complement the work an individual has already done and help them make the most of the wealth they have built.

QWhat are some of the unique financial planning challenges you commonly see among your clients who are Amazon employees and how do you help them overcome these obstacles?

“Amazon employees often have unique financial planning challenges because their compensation structure can be more complex than a traditional salary-based employee. While these benefits create significant opportunities for wealth creation, they also require thoughtful planning to maximize their long-term value.

One of the most common challenges I see is managing concentrated equity exposure. Many Amazon employees accumulate substantial wealth through Restricted Stock Units (RSUs), which can create an unintended concentration in a single company stock. The challenge is balancing the opportunity for continued growth with the importance of diversification, risk management, and aligning their investment strategy with their broader financial goals.

Another challenge is coordinating the different components of their compensation package. Base salary, bonuses, RSU vesting, 401(k) contributions, employee benefits, and taxable investments all have different tax implications and planning considerations. Without a coordinated strategy, employees may miss opportunities to improve tax efficiency or make decisions that do not fully support their long-term objectives.

I also frequently help employees navigate major life transitions, such as career changes, relocation, retirement planning, or preparing for financial independence. These transitions often require decisions around equity compensation, cash flow, benefits, insurance, estate planning, and retirement income strategies.

The way I help clients overcome these challenges is by taking a comprehensive planning approach. Rather than looking at each financial decision in isolation, I help clients understand how their compensation, investments, taxes, and personal goals work together. As a fiduciary, my role is to provide objective guidance, identify potential risks and opportunities, and help clients make informed decisions that are aligned with their long-term financial success

QWhat questions do you recommend Amazon employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?

When evaluating a financial advisor, I believe Amazon employees should look beyond investment performance and focus on whether the advisor can provide comprehensive, objective guidance that aligns with their unique financial circumstances.

Some important questions I recommend asking include:

Are you a fiduciary, and how are you compensated? Employees should understand whether the advisor is legally and professionally committed to acting in their best interest and have a clear understanding of all fees and potential conflicts of interest.

What experience do you have working with employees who have equity compensation, such as RSUs? Amazon employees often have complex compensation packages, and it is important to work with someone who understands how stock awards, vesting schedules, taxes, and diversification decisions impact their overall financial plan.

How do you approach financial planning beyond investment management? A strong advisor should be able to help coordinate retirement planning, tax strategies, insurance, estate planning, cash flow management, and major life transitions—not just select investments.

How will you help me make decisions during important financial events? Employees should understand how the advisor supports decisions such as changing jobs, retiring, selling company stock, managing a large financial windfall, or adjusting their retirement strategy.

Who will I work with, and how often will we communicate? The relationship with an advisor is built on trust and ongoing collaboration. Employees should feel comfortable with the advisor’s communication style, process, and commitment to understanding their goals.

Ultimately, the right advisor should act as a trusted partner who helps bring clarity to complex financial decisions. The value of a fiduciary advisor is not simply managing investments—it is providing objective advice, coordinating the many moving parts of an employee’s financial life, and helping them make informed decisions with confidence.

QIs there anything that comes up frequently in your initial meeting with Amazon employees that surprises you?

One thing that often surprises me in initial meetings with Amazon employees is that many are significantly more financially successful and better positioned than they realize, but they may not have a clear picture of how all the pieces of their financial life fit together.

Many Amazon employees have done an excellent job saving, investing, and building wealth through their compensation package. However, because their financial picture can include salary, bonuses, RSUs, retirement accounts, taxable investments, and other benefits, it is common for them to have questions about whether they are making the most effective decisions across the entire plan.

A frequent area of discussion is concentrated company stock. Employees are often surprised when we look at their overall net worth and identify how much of their financial future may be tied to Amazon equity. While the stock has been an important wealth-building tool, the conversation around diversification, risk management, and tax-efficient decision-making is an important part of protecting and maximizing that wealth.

I also find that many employees are surprised by how much opportunity exists beyond investment management. Questions around tax planning, retirement income strategies, estate planning, charitable giving, and coordinating benefits often become some of the most valuable areas of the conversation.

Ultimately, the biggest surprise is often realizing that financial planning is not just about accumulating wealth—it is about making intentional decisions with the wealth they have built. As a fiduciary, my role is to help Amazon employees gain clarity, identify opportunities, and create a strategy that connects their financial resources with their long-term goals.

QFor highly compensated Amazon employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

For highly compensated Amazon employees and executives, financial planning often becomes more complex because their compensation packages typically include multiple layers of wealth creation and tax considerations. While salary and retirement savings remain important, the most significant planning opportunities often come from coordinating equity compensation, taxes, risk management, and long-term wealth strategies.

One of the most important areas to consider is equity compensation, particularly Restricted Stock Units (RSUs). Executives and long-tenured employees may accumulate substantial Amazon stock, which can create both tremendous opportunity and significant concentration risk. A thoughtful plan should address vesting schedules, diversification strategies, tax implications, and how company equity fits within their broader investment and retirement objectives.

Tax planning is another critical component. Highly compensated employees may face higher marginal tax rates and more complex decisions around charitable giving, Roth conversion strategies when appropriate, tax-efficient investing, and the timing of income recognition. Proactive planning can help improve after-tax outcomes and avoid unnecessary tax surprises.

I also encourage executives to evaluate benefits beyond traditional retirement savings, including Health Savings Accounts (when eligible), deferred compensation opportunities (if available), insurance needs, estate planning strategies, and beneficiary designations. As wealth grows, protecting assets and ensuring efficient wealth transfer become increasingly important.

Another key consideration is aligning their financial plan with their broader life goals. Successful executives often have competing priorities, such as supporting family, funding education, philanthropy, maintaining lifestyle goals, and preparing for eventual retirement or career transitions.

As a fiduciary, my role is to help clients look at the entire financial picture—not just individual benefits or accounts. By coordinating compensation, investments, taxes, estate planning, and risk management, I help Amazon employees and executives make informed decisions designed to preserve and maximize the wealth they have worked hard to create.

QIs there a particularly memorable experience or a moment you recall with a client who worked at Amazon when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?

One experience that stands out was working with an Amazon employee who had been very successful in building wealth through the company’s compensation structure but had never taken the time to step back and evaluate how all the pieces fit together. Like many successful employees, they had done an excellent job saving, investing, and accumulating Amazon stock, but a significant portion of their net worth had become concentrated in company equity.

During our planning process, we reviewed their RSU vesting schedule, investment allocation, tax situation, retirement goals, and overall risk exposure. What became clear was that the employee had created substantial wealth, but the strategy that helped them accumulate that wealth was not necessarily the same strategy that would help them protect and manage it over the long term.

The most valuable part of the engagement was not a single investment decision—it was helping the client understand the connections between their compensation, taxes, investments, and future goals. By creating a more coordinated plan, they gained greater clarity around diversification, financial independence, and how to make intentional decisions with their Amazon equity.

This experience reinforced for me that Amazon employees often have unique financial planning needs because their success is tied to a compensation structure that can be both a tremendous opportunity and a source of complexity. As a fiduciary, my role is to help clients make informed decisions, identify potential risks, and maximize the benefits they have earned while keeping their long-term goals at the center of the plan.

QAmazon’s RSU vesting schedule is famously back-weighted—5% in year one, 15% in year two, then 40% in years three and four—so how should Amazon employees think about cash-flow planning and tax strategy during those early vesting years when income from equity is relatively low?

Amazon’s back-loaded RSU vesting schedule creates a unique planning challenge because employees often experience a gap between their current compensation expectations and the future value of their equity compensation. During the early years, when RSU income is relatively limited, I encourage employees to focus on building a strong financial foundation and planning intentionally for the future increase in compensation.

The first priority is cash-flow management. Employees should avoid making lifestyle decisions based on the future value of unvested RSUs and instead build their budget around guaranteed income. This includes maintaining an appropriate emergency reserve, managing debt strategically, maximizing retirement plan contributions when possible, and creating a savings strategy that allows them to take advantage of future equity compensation without becoming dependent on it.

From a tax perspective, early planning is critical. Employees should understand how RSUs are taxed at vesting, how withholding works, and how future vesting events may impact their overall tax liability. Developing a strategy before larger vesting years arrive can help employees make more informed decisions around estimated taxes, charitable giving, retirement contributions, and diversification.

I also encourage employees to think ahead about what they will do when the larger vesting events occur in years three and four. Having a plan in place before shares vest helps avoid emotional decisions and allows employees to determine how much company stock they are comfortable holding, how much they want to diversify, and how those decisions fit into their broader financial goals.

Another important consideration is using the early years to build financial flexibility. Employees can take advantage of this period to establish good savings habits, optimize their benefits, and create a plan for how future RSU income will be used—whether that means investing, paying down debt, funding education goals, or accelerating progress toward financial independence.

As a fiduciary, my role is to help employees look beyond the vesting schedule itself and understand how their equity compensation fits into their complete financial picture. The goal is not simply to maximize the value of the RSUs, but to help employees use this unique benefit in a way that supports their long-term financial security.

QGiven that Amazon heavily weights total compensation toward RSUs rather than base salary, how do you help Amazon employees evaluate a job offer or promotion where the true value depends so much on future stock performance and vesting milestones?

When Amazon employees evaluate a job offer or promotion, one of the most important considerations is looking beyond the headline compensation number and understanding the true value, risks, and long-term implications of the offer. Because a significant portion of compensation may come through RSUs, employees need to evaluate both the opportunity and the uncertainty that comes with equity-based compensation.

I encourage employees to start by comparing the total compensation package across several dimensions: base salary, bonus potential, RSU grant value, vesting schedule, refresh grants, benefits, and the long-term growth potential of the company. A higher total compensation number does not always translate into a better financial outcome if the compensation is heavily dependent on future stock performance or aggressive vesting assumptions.

For RSUs specifically, I help employees evaluate the difference between guaranteed compensation and variable compensation. We discuss questions such as: How much of my future income is tied to one company’s stock performance? What happens if the stock price declines? How does the vesting schedule impact my cash flow? How much company stock am I comfortable owning as part of my overall net worth?

Tax planning is another important component. Employees should understand how equity compensation will be taxed at vesting, how withholding may impact their actual after-tax compensation, and how future vesting events fit into their broader financial plan. A proactive strategy can help avoid surprises and create a more intentional approach to saving, investing, and diversification.

I also encourage employees to consider the career and financial implications of timing. A promotion or new opportunity may increase compensation, but it may also affect lifestyle decisions, retirement savings, risk exposure, and long-term financial goals. The best decision is not always the offer with the highest projected value—it is the opportunity that aligns with the employee’s overall financial objectives and personal priorities.

As a fiduciary, my role is to help employees objectively evaluate the full picture. By analyzing compensation structure, equity exposure, taxes, benefits, and long-term goals together, I help clients make informed career decisions that support both their professional success and financial well-being.

QHow do you help Amazon employees navigate the vesting schedule and tax implications of their Restricted Stock Units (RSUs), particularly given Amazon’s back-weighted vesting structure that delivers a larger percentage of shares in later years?

Amazon’s RSU compensation structure creates tremendous wealth-building opportunities, but it also requires thoughtful planning because the timing of vesting and the associated tax implications can significantly impact an employee’s financial picture.

I help Amazon employees begin by understanding the mechanics of their RSU grants, including the vesting schedule, the timing of future shares becoming taxable income, and how those vesting events fit into their overall compensation. Because Amazon’s vesting structure is back-weighted, employees need to plan ahead for the larger equity events that occur in later years rather than simply reacting when shares vest.

One of the first areas we address is cash-flow planning. Employees should understand that unvested RSUs are a future opportunity, not current income. I help clients create a plan that balances their current salary with future equity compensation, including saving strategies, emergency reserves, retirement contributions, and lifestyle decisions.

Tax planning is another critical component. RSUs are generally taxed as ordinary income when they vest, based on the fair market value of the shares at that time. I help employees anticipate future vesting events, understand withholding requirements, and evaluate how those taxable events may affect their broader tax situation. This may include coordinating retirement contributions, charitable giving, diversification strategies, and other tax-aware decisions.

As larger portions of RSUs vest in later years, diversification becomes an increasingly important conversation. Many employees are surprised by how quickly company stock can become a significant percentage of their net worth. I help clients evaluate their comfort level with concentration risk and develop a strategy for balancing the opportunity of continued ownership with the importance of protecting the wealth they have accumulated.

Ultimately, the goal is to help employees move from simply receiving RSUs to intentionally managing them as part of a broader financial plan. As a fiduciary, I help Amazon employees make informed decisions around their equity compensation, taxes, investments, and long-term goals so their RSUs can serve as a tool for building financial security.

QHow do you advise Amazon employees on optimizing their total compensation strategy when their pay mix is heavily weighted toward RSUs rather than base salary, especially when stock price volatility can significantly impact their effective annual income?

When Amazon employees have a significant portion of their compensation tied to RSUs, I encourage them to think about total compensation as a strategic planning opportunity rather than simply focusing on the annual compensation number. Equity compensation can be a tremendous wealth-building tool, but it also introduces additional considerations around volatility, taxes, cash flow, and risk management.

The first step is helping employees understand the difference between their expected compensation and their guaranteed compensation. Because RSU value fluctuates with Amazon’s stock price, employees should avoid building their lifestyle around the highest projected value of their equity awards. I help clients create a cash-flow strategy based on their reliable income while treating RSU compensation as an opportunity to build wealth, invest, and achieve long-term goals.

A key part of the planning process is evaluating how much company stock an employee should hold after shares vest. Many employees naturally feel a strong connection to the company that has helped them build wealth, but from a financial planning perspective, it is important to evaluate concentration risk and determine whether their investment exposure aligns with their overall goals, risk tolerance, and financial timeline.

Tax planning is also critical. RSU vesting creates taxable income, and employees need to understand how vesting events, withholding, and future stock sales may affect their tax situation. By planning ahead, employees can make more informed decisions about diversification, retirement contributions, charitable strategies, and other financial priorities.

I also encourage employees to maximize the other components of their compensation package, including retirement benefits, healthcare benefits, and other employer-sponsored programs. A comprehensive strategy looks at the entire package—not just salary and stock—to determine how each piece can work together most effectively.

Ultimately, the goal is to help Amazon employees convert a complex compensation structure into a clear financial strategy. As a fiduciary, my role is to provide objective guidance, help clients manage the opportunities and risks associated with equity compensation, and ensure their compensation decisions support their broader financial goals.

Considering a financial advisor who specializes in working with Amazon Employees?

Ask an advisor

Ask a Financial Advisor Your Amazon Benefits & Career Questions

Keep exploring

Find the Right Financial Advisor for You

Browse specialists, compare advisors near you, or find advisors who know your employer’s benefits.

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

What this article covers

Discover financial advisors trusted by residents of Waco, Texas in the only local directory featuring 5-Star Certified Advisor Review™ recipients and Wealthtender Voice of the Client Award™ winners, recognition earned for exceptional client feedback. Compare fiduciary, fee-only advisors, CFP® professionals, and specialists to find the right fit for your unique financial needs.

Financial Advisor Directory for Waco, Texas

📍 Map: Financial Advisors with their Primary Office Location in Waco

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Waco.

📍Double-click or pinch pins to view more.

Showing

Key Takeaways

1

You can compare Waco financial advisors by credentials, specialty and verified client reviews before you contact anyone.

The map shows advisors whose primary office is in Waco. Profiles include Certified Advisor Reviews™, designations such as the CFP® and the services each advisor offers.

2

Baylor University, health systems and federal and defense jobs shape the planning help many Waco residents need.

Baylor and hospital employees often weigh 403(b) and other workplace plan choices, while federal and defense workers coordinate pensions, the Thrift Savings Plan and company stock. Homeowners should also plan around Texas property taxes and percentage deductibles for hail and wind damage.

3

Interview more than one advisor and confirm how each one is paid.

Ask about services, fees and whether the advisor acts as a fiduciary, then check their background for free on the SEC’s Investment Adviser Public Disclosure website before you hire.

Financial Planning Considerations for Waco Residents

Every city has its own financial landscape. Here are a few local factors worth discussing with a Waco financial advisor.

Baylor and health care careers

Baylor University is Waco’s largest employer with 4,034 employees, followed by Baylor Scott & White Health with 2,711, and Ascension’s local hospital adds another 1,396. Because Baylor is a private university, employees save through the Baylor Retirement Plan, a 403(b), rather than a state pension. Baylor’s discretionary employer contribution has age and one-year service requirements, so it pays to know when you qualify. The 403(b) limit is $24,500 for 2026, and Baylor’s 457(b) deferred compensation plan gives participants who max out their 403(b) a way to save more.

Federal and defense jobs

The Department of Veterans Affairs Regional Office employs 1,395 people in Waco, and L3Harris employs 1,178 at its aircraft work near the TSTC airport, where it moved production of the OA-1K Skyraider II in 2025. Federal employees coordinate a FERS pension with the Thrift Savings Plan, which also allows up to $24,500 for 2026, while defense contractor employees often weigh company stock and pension choices. See our L3Harris employee Q&A.

No state income tax, but property taxes matter

Texas has no personal income tax, so property taxes do much of the work of funding local government and schools. In November 2025, Texas voters raised the school district homestead exemption from $100,000 to $140,000, applying beginning with the 2025 tax year, and raised the extra school exemption for homeowners 65 or older or with a disability from $10,000 to $60,000. Qualifying older homeowners also get a ceiling that freezes school taxes at the amount paid in their first year under the exemption.

Hail, wind and percentage deductibles

Central Texas storms can bring hail and high winds, so check how your home insurance deductible works before you need to file a claim. Some Texas policies set the deductible as a percentage of the home’s insured value. The Texas Department of Insurance gives an example: on a home insured for $150,000, a 5% deductible is $7,500, so a $6,500 hail repair would get nothing from the policy. Keeping cash on hand to cover the deductible helps.

The Benefits of Hiring a Financial Advisor in Waco

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Waco, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Who are the largest employers in the Waco area?

Waco’s largest employers span higher education, health care, schools, retail, local and federal government, and defense. Highlighted companies link to advisor Q&As about their employees.

  1. Baylor University 4,034 employees
  2. Baylor Scott & White Health 2,711 employees
  3. Waco Independent School District 2,373 employees
  4. H-E-B 2,000 employees
  5. City of Waco 1,639 employees
  6. Midway ISD 1,484 employees
  7. Ascension Healthcare 1,396 employees
  8. Department of Veterans Affairs Regional Office 1,395 employees
  9. L3HarrisRead advisor Q&A →1,178 employees
  10. WalmartRead advisor Q&A →1,174 employees

Work for one of these companies or another large employer? Explore our employer Q&As for advice on making the most of your benefits.

Source: City of Waco, Annual Comprehensive Financial Report, Principal Employers (fiscal year 2024). The report compiles counts from the Greater Waco Chamber of Commerce and the Bureau of Labor Statistics.

Do you work for one of the largest employers in Waco? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Types of Financial Advisors You’ll Find on Wealthtender

Thousands of people visit Wealthtender each month to find and compare financial advisors based on their location, education, experience, areas of specialization and online reviews. Wealthtender’s Certified Advisor Reviews™ help consumers make informed hiring decisions with important details about the relationship between reviewers and advisors always displayed to ensure you gain the transparency you deserve when your life savings could be at stake.

On Wealthtender, you can explore a diverse range of financial advisors and wealth management firms that include:

  • Fiduciary advisors committed to acting in clients’ best interests
  • CFP® professionals with advanced financial planning credentials
  • Fee-only advisors compensated solely by clients
  • Advisors for growing families, people nearing retirement, and business owners
  • Specialists across multiple categories (e.g., life stage, occupation, ethnicity, lifestyle, religion)
  • Highly-rated advisors with positive client reviews
  • Firms of varying sizes with advisors who can meet with you in person or online
  • Fee-based advisors who offer access to insurance and alternative investments

How to use this directory: Compare financial advisors in the Waco area based on what matters most to you. Use the directory to:

  • View advisor profiles to evaluate credentials, services, and areas of specialization
  • Read Certified Advisor Reviews™ to learn what clients value most
  • Identify advisors recognized with Wealthtender Voice of the Client Awards™
  • Contact advisors and schedule free introductory video calls

Wealthtender Voice of the Client Awards™: Top Rated Waco Financial Advisors

Wealthtender Voice of the Client Awards™ recognize financial advisors and firms that consistently earn exceptional client feedback. Below are Waco-area advisors and firms that have met the criteria for Highly Rated recognition.

Firm/Advisor Firm City State Voice of the Client Award Website

To qualify for a Highly Rated award, advisors and firms must achieve an average client review rating of 4.75 or higher (on a scale of 1 to 5) based on a minimum number of eligible client reviews published on Wealthtender within a defined timeframe for each particular award (Timeframe for 2025 Award: 1/1/24 – 12/31/25; Timeframe for Subsequent Year Awards: July 1 of the preceding year through December 31 of the Award Year (e.g., Timeframe for 2026 Award 7/1/25 – 12/31/26). Eligible reviews are limited to clients (as of the review submission date) that advisors/firms must self-attest have no material conflicts of interest and received no compensation in exchange for their reviews. ↗️ View full award methodology & FAQs

Although financial advisors and wealth management firms compensate Wealthtender for marketing services (including eligibility to be considered for awards), Wealthtender’s award criteria is objective and not influenced by compensation. Wealthtender Voice of the Client Awards are not a guarantee of future performance or success and client reviews may not be representative of the experience of all past or future clients.

Quick Tips For Hiring a Waco Financial Advisor

Before hiring a financial advisor in Waco, here are a few quick tips to help you find the best advisor for you.

1

Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor who specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2

Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3

Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4

Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.

Frequently Asked Questions

What makes a financial advisor “trusted”?
A trusted financial advisor typically earns positive client feedback over time, operates transparently, and clearly explains how they’re compensated. On Wealthtender, trust is reflected through Certified Advisor Reviews™ that combine insights into the client experience and character of advisors with important disclosures about each reviewer to ensure you gain the transparency you deserve when your life savings could be at stake.

Financial advisors and wealth management firms that consistently receive superior client reviews can also qualify for Wealthtender’s Voice of the Client Awards™ designed to recognize America’s most trusted advisors. Learn More About Wealthtender Voice of the Client Awards™
What are Certified Advisor Reviews™?
Certified Advisor Reviews™ from Wealthtender help consumers make smarter hiring decisions when choosing a financial advisor.

Clients and other individuals can submit reviews for financial advisors and wealth management firms that have turned on the reviews feature. Before each review is publicly displayed, financial advisors agree to disclose important information about their relationship with the reviewer to ensure consumers gain the transparency they deserve when their life savings could be at stake. These disclosures also help financial advisors satisfy compliance with industry regulations.

After financial advisors provide the required disclosures, Wealthtender publishes the review with the Certified Advisor Review™ mark. Learn More About Certified Advisor Reviews™
Can I find fiduciary financial advisors on Wealthtender?
Yes, you’ll find hundreds of fiduciary financial advisors on Wealthtender. Fiduciary financial advisors must act in their clients’ best interest. Before hiring an advisor, always ask if they will act in your best interest as a fiduciary.

For example, financial advisors who have earned their Certified Financial Planner (CFP) designation are fiduciaries. To hold themselves out as a CFP, these credential holders must acknowledge they will adhere to the CFP Board’s Code of Ethics and Standards of Conduct and act as a fiduciary when providing financial advice to their clients. Learn More About Fiduciary Financial Advisors
Can I find fee-only financial advisors on Wealthtender?
Yes, you’ll find hundreds of fee-only financial advisors on Wealthtender. Fee-only financial advisors are paid directly by their clients. Since they aren’t compensated based on the products and services they recommend (e.g., commissions), their compensation model helps reduce potential conflicts of interest.

When viewing financial advisor profiles on Wealthtender, look for the Compensation Methods section that shows ways each financial advisor can be paid for their services, including if they offer fee-only financial planning services. Learn More About Fee-Only Financial Advisors
What distinguishes Wealthtender Voice of the Client Awards™ from other advisor recognition programs?
Wealthtender’s Voice of the Client Awards™ recognize financial advisors and wealth management firms that consistently receive superior client reviews. Unlike award programs with ranking factors that favor financial institutions with the most assets and the fastest revenue growth, the Wealthtender Voice of the Client Awards provide both local financial advisors who choose to remain small and large wealth management firms with the opportunity to be recognized on a metric that matters more to consumers – actual client feedback reflecting the quality of their experience. Learn More About Voice of the Client Awards™
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit. But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a Waco financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Learn how to get featured

Please note: Wealthtender may be compensated by financial advisors featured on our site and within this guide. Learn more about how we operate with integrity to earn your trust.

Watch

How Much Does a Financial Advisor Cost?

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

Finding a financial advisor is easy. But finding the right financial advisor for you? That’s another story.

For most of us, our relationship with a financial advisor will last many years, likely a decade or longer, and could span multiple generations. If you’re preparing to hire a financial advisor, you’ll want to take the decision-making process seriously and spend time researching advisors online to ensure you hire an advisor who’s a perfect fit for you.

You’re not just searching for someone with credentials, you’re looking for someone who understands your specific situation, offers their services at a fair price, specializes in the things that matter most to you, and whose online reviews demonstrate a proven track record of client satisfaction and trust. That’s a lot to ask of a Google search.

Increasingly, Americans are turning to AI tools like ChatGPT, Gemini, Perplexity, and Claude to get a head start on their efforts to find and research advisors, and for good reason. AI tools can help you clarify what you’re looking for, identify the right types of advisors, generate smart interview questions, and research candidates before you ever pick up the phone or book an introductory call on their calendar. But AI tools also have limitations worth knowing when it comes to finding financial advisors, and knowing those limits is just as important as knowing what they can do well. This guide walks you through both.

Key Takeaways – How to Find a Financial Advisor Using AI Tools

1

AI tools are powerful for preparation, but should complement -not replace – verified industry and government resources when choosing an advisor.

ChatGPT, Gemini, Perplexity, and Claude can help you clarify what kind of advisor you need, understand fee structures, and generate smart interview questions, but they can overlook qualified advisors better suited for your unique needs, may favor advisors based on outdated training data, and shouldn’t be relied upon exclusively without checking the underlying source data to confirm accuracy. Use AI to prepare, then verify independently before making contact and aim to speak with three advisors before hiring one.

2

One in four Americans already uses AI tools to start their search for a financial advisor and that number is rising fast.

According to Wealthtender’s 2025 study of 500 affluent U.S. households planning to hire an advisor, 25% said they will use tools like ChatGPT or Gemini to begin their search. Unlike a simple Google search, these consumers are crafting detailed, personalized prompts that describe their specific situation, fundamentally changing how advisor discovery works.

3

Reading verified reviews are a critical step in your advisor search – AI tools often summarize reviews from find-an-advisor directories like Wealthtender which is useful at a glance to understand key themes about the reviews written by clients.

The Wealthtender study found that 83% of people preparing to hire an advisor said reading online reviews was among their most important steps, though AI tools sometimes just display a star rating without important context. Platforms like Wealthtender fill this gap with advisor-verified reviews that AI tools themselves recognize as authoritative sources.

Why More People Are Using AI to Find Financial Advisors

The shift to use AI tools to find and compare financial advisors is happening faster than most people realize. In our 2025 Wealthtender study of 500 U.S. households with incomes above $100,000 with plans to hire a financial advisor in the next few years, 25% of Americans said they will use AI tools like ChatGPT or Gemini to start their search, a number that’s expected to grow quickly.

The appeal is intuitive. Rather than typing a simple query into Google like ‘financial advisor near me’ and scrolling through paid ads and links to advisor websites ranked by distance from your front door, you can have a conversation with an AI tool that prioritizes finding the perfect fit over proximity. You’re not ordering a pizza and wondering how quickly it can get delivered to your house. When choosing a financial advisor, distance may be a factor, but it’s certainly not among the most important factors you need to consider when deciding who to hire.

When typing a prompt into in AI tool, you can describe your situation in detail and ask nuanced questions: What kind of advisor do I need? What professional credentials should I look for? How much should I expect to pay? What questions should I ask in an introductory call? This conversational approach feels more natural and is more likely to narrow your shortlist of advisors to those worth researching further based on what’s truly important to you, versus completing a quiz on a website only to find the shortlist of advisors displayed are those who paid to show up, regardless of any requirements you emphasized as important to you.

What AI Tools Do Well (and Where They Fall Short)

Before diving into the how-to, it’s worth being clear-eyed about what AI tools can and can’t do reliably.

AI tools are typically best at:

  • Helping you clarify what kind of financial help you actually need
  • Explaining the differences between advisor types (fiduciary or not, fee-only vs. commission-based, CFP vs. CPA vs. RIA, etc.)
  • Generating tailored interview questions based on your situation
  • Summarizing what to look for when evaluating an advisor’s credentials and background
  • Helping you understand your own financial situation before your first advisor meeting

AI tools are less reliable for:

  • Recommending specific advisors by name who truly represent the best fit for you – AI tools can surface names, but they may be based on outdated training data or false assumptions about what matters most for your unique circumstances
  • Verifying credentials, disciplinary history, or current registration status – AI tools may report findings, but before hiring an advisor, always check the official source
  • Providing verified client reviews – You’ll often see client reviews summarized in AI tools citing sources like Wealthtender, but it’s worth viewing the underlying Wealthtender profile to read all reviews and accompanying disclosres
  • Keeping up with advisors who have recently joined a firm, retired, or changed their specialization

The bottom line: use AI as a research and preparation tool, not as your final word on which advisor to trust with your financial future. Here’s exactly how to do that.

Step 1: How to Determine What Type of Financial Advisor You Need

Most people start their advisor search without a clear sense of what they’re actually looking for. AI tools are genuinely excellent at helping you get more specific.

Open ChatGPT, Gemini, Perplexity, or Claude and try a prompt like this:

“I’m [age] years old with [brief description of your life and financial situation (e.g., location, income range, employer name, savings, major goals, family/marital status)]. I’m thinking about hiring a financial advisor for the first time. What kind of advisor should I be looking for, and what credentials or designations are most relevant to my situation?”

Your AI tool of choice will likely walk you through key distinctions worth knowing: between fiduciary and non-fiduciary advisors, fee-only versus commission-based compensation models, and designations like CFP (Certified Financial Planner), CFA, CPA, or CDFA, etc. depending on your needs.

This conversation alone can save you hours of research and help you avoid the costly mistake of hiring the wrong type of advisor for your situation.

Step 2: Define What to Look for in a Financial Advisor

Once you understand what kind of advisor you need, use AI to get even more specific about the criteria for your shortlist.

Try a prompt like this one:

“I’m looking for a fee-only financial advisor who specializes in helping teachers and educators plan for retirement. I’ve worked for the University of [your employer] for 17 years, have a [name of retirement plan] and a 403(b). I’d prefer an advisor in [your city or state], or one who works with clients virtually, if they specialize in areas important to me, understand my circumstances, and have positive client reviews. What specific things should I be looking for, and what questions should I prioritize asking?”

A good AI response will give you a prioritized list of what to look for: specialization, fee structure, minimum asset requirements, fiduciary status, meeting format, plus a set of interview questions tailored to your situation. Save this. You’ll use it throughout your search.


Step 3: Use AI to Search for Financial Advisors (Then Verify)

This is where the process gets more nuanced. You can ask AI tools to suggest advisors, and you may get useful names back. But treat those suggestions as a starting point, not a definitive list.

AI tools may pull from indexed web content, which means advisors with a strong online presence, particularly those listed on reputable directories with verified reviews are more likely to surface. Advisors who are newer, less active online, or who rely entirely on referrals may not appear at all, regardless of how skilled they are. AI tools may also pull from outdated training data – the information may still be accurate and useful, but reinforces the importance of going to the underlying sources for independent verifcation.

A prompt worth trying:

“Can you suggest financial advisors in [city/region] who specialize in [your situation, e.g., equity compensation, divorce planning, small business owners]? I’m looking for fiduciary advisors with positive reviews on platforms like Wealthtender where clients consistently express their satisfaction and trust. Please provide a link to any sources cited in your response so I can easily dive deeper and independently verify if they meet my qualification criteria.”

Then take those names, plus any referrals you’ve received from friends, family, or other professionals, and verify them independently as we discuss further in the next step.

Step 4: Research and Compare Financial Advisors Using Verified Reviews

As your shortlist starts to shape up, this is when independently verified information matters most, and where a resource like Wealthtender proves its value.

Wealthtender is one of the few places online where you can:

  • Find advisors near you with profiles that include their specializations, credentials, compensation methods, meeting options, and who they serve best (search local advisors here)
  • Find specialist advisors – Whether you need someone who works with physicians, military families, LGBTQ+ clients, divorcees, or business owners, Wealthtender’s specialist directories make it easy (browse by specialty)
  • Read authentic client reviews – This matters more than it might seem. The 2025 Wealthtender study referenced earlier found that 83% of people preparing to hire an advisor said reading online reviews was a priority. Wealthtender is one of the only platforms where reviews are verified by advisors with important disclosures required by the Securities and Exchange Commission (SEC) to ensure you know if reviews were written by clients, whether or not they were compensated for sharing their feedback, and if any conflicts of interest exist. If you come across a negative review, here’s how to tell whether it matters.

This last point deserves emphasis. If you’ve received a referral to a specific advisor, or an AI tool surfaced a name that looks promising, Wealthtender is a smart place to look them up. Even if an advisor didn’t come to your attention through Wealthtender, you’ may still be able you’ll still want to read their reviews and compare them against others who specialize in the same area to make a more informed hiring decision.

Step 5: Use AI to Prepare for Your Introductory Calls

Once you have a shortlist of two or three advisors, use AI again, this time to prepare for your introductory conversations. Ideally, your prompt should be a continuation of your earlier conversation with AI, so the AI tool can take all of the cumulative information gathered thus far into consideration in its next response.

Try a prompt like:

“I have an introductory call with a financial advisor who specializes in [their specialty]. They charge a flat annual fee. I want to make sure I’m hiring someone who’s truly the right fit. Taking this into consideration and incorporating everything relevant in our conversation thus far, what are the 10 most important questions I should ask, and what answers should raise red flags?”

The AI-generated answer will typically include questions about fiduciary status, how they’re compensated, how they communicate with clients, how they handle conflicts of interest, do they have client reviews you can read on a platform like Wealthtender (and if not, why not), and what their investment philosophy looks like. Armed with these questions, you’ll walk into your call far more prepared than most people in their initial conversation, and you’ll start off in a much stronger position to evaluate who’s genuinely the right fit.

Step 6: Contact Financial Advisors on Your Shortlist

When you’re ready to reach out, most advisors make it easy to get in touch and offer a free introductory call or meeting. For example, advisors with profiles on Wealthtender typically include options for you to:

  • Send a contact request via a “Contact Me” button that puts an email in their inbox
  • Book an introductory call directly if the advisor offers online scheduling
  • Visit the advisor’s website to learn more before reaching out

Don’t limit yourself to contacting only one advisor. The Wealthtender study cited above found that 97% of people planning to hire an advisor intend to contact and interview multiple advisors before making a decision. An introductory call is typically free, low-pressure, and gives both you and the advisor a chance to assess fit. If an advisor pressures you into making a decision on the spot or discouraging you from speaking with other advisors, that’s a red flag and you shouldn’t feel afraid to simply end the conversation and move on.

Which AI Tool Works Best for Finding a Financial Advisor?

AI tools are rapidly evolving, so the best AI tool to assist in your search for a financial advisor today, may in fact be another tool tomorrow. Regardless, you have several solid options popular among consumers, and each offers slightly different strengths for this use case:

ChatGPT (OpenAI) is popular for its conversational style and handles nuanced, multi-part questions well. It may be best for clarification and preparation steps, helping you define what you need and generating interview questions. The paid version (ChatGPT Plus) includes web browsing, making it better for surfacing more current advisor information versus free versions that may cite outdated information from its training database.

Gemini (Google) integrates with Google Search results, which can make it more current than some alternatives when surfacing advisors with a strong online presence. Useful when you want search-grounded responses. Even a traditional Google search is likely to now display an AI overview, so expect Gemini/Google to maintain its dominance in search in the coming years.

Perplexity is citation-forward by design which can be useful when researching financial advisors as it typically shows you the sources behind its answers, making it easier to evaluate the quality of information you’re getting. Worth using specifically when you want to see exactly where the AI is pulling its suggestions from.

Claude (Anthropic) excels at handling long, complex documents and nuanced prompts. If you want to paste in an advisor’s bio, ADV disclosure, or investment philosophy statement and ask for a plain-language summary or a red-flag analysis, Claude handles that particularly well.

For finding and researching financial advisors, no single tool is a complete solution. The best approach is likely to use one or two for clarification and question generation, then moves to a purpose-built discovery and research platform like Wealthtender to compare advisors, read client reviews with useful disclosures, and contact advisors.

AI Tool Best Use in Your Advisor Search Key Limitation
ChatGPT Clarifying what type of advisor you need; generating tailored interview questions; explaining fee structures and credential types May surface advisor names based on outdated training data; cannot verify registration or review authenticity
Google Gemini Finding advisors with a current, active online presence; search-grounded responses tied to recent web content Quality depends on what’s indexed; still cannot confirm credentials, client reviews, or regulatory status
Perplexity Source-cited research that lets you evaluate where information is coming from before trusting it Source authority varies; cannot access verified advisor review platforms or regulatory databases directly
Claude Analyzing long documents — paste an advisor’s ADV disclosure, bio, or investment philosophy for a plain-language summary and red-flag check Less effective at surfacing specific local advisors by name; no access to live regulatory databases
For verified profiles, credentials, and real client reviews: visit Wealthtender.com →

How to Verify a Financial Advisor’s Credentials Before You Hire

AI tools can act as powerful research assistants, but they can get things wrong, especially about specific people and firms. They may surface an advisor’s name without knowing the advisor retired last year, changed firms, or has a recent regulatory issue on record. They may occasionally misstate credentials or specializations.

Before scheduling any introductory call with an advisor you found through an AI recommendation, take a few minutes to:

This extra layer of due diligence takes less than 15 minutes and is worthwhile when hiring a professional who you may work with for the foreseeable future.

Bottom Line: How to Use AI to Find the Right Financial Advisor

AI tools are genuinely changing how people find financial advisors, and for the better, when used thoughtfully. They can help you get clear on what you need, ask better questions, and research smarter. But they work best as a starting point, not a final answer.

The most effective approach combines the personalization and speed of AI with the reliability of purpose-built and trusted platforms. Use AI to prepare. Use Wealthtender to research, compare, and connect. And use regulatory databases like BrokerCheck and SEC IAPD to ensure advisors are properly licensed and their disciplinary records are clean.

—

Data in this article references the Wealthtender 2025 Study of $100K+ Households Seeking Financial Advice, a survey of 500 U.S. adults with household incomes over $100,000 conducted in July 2025.

Are You Ready to Hire a Financial Advisor?

You’ll find a growing number of financial advisors featured on Wealthtender. You can search based on the areas of specialization most important to you and where they’re located, or browse our financial advisor directory for more search options to find advisors who may be a good fit for you.

Find Your Next Financial Advisor on Wealthtender

📍 Click on a pin in the map view below for a preview of financial advisors who can help you reach your money goals with a personalized plan. Or choose the grid view to search our directory of financial advisors with additional filtering options.

📍Double-click or pinch pins to view more.

Showing

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

Do you work at OpenAI?

Get expert insights from a financial advisor who specializes in helping OpenAI employees and executives make the most of their compensation package and benefits.

Looking for a financial advisor who specializes in working with OpenAI employees? You’re in the right place. Below, you’ll meet an advisor who understands OpenAI benefits and compensation — along with his answers to common financial questions from OpenAI employees and executives.

Whether you recently joined OpenAI or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and OpenAI benefits can have a lasting impact on your financial future. For example:

  • Do you know the right moves to get the greatest value from the OpenAI benefits available to you?
  • If you’re thinking about leaving OpenAI for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?

Key Takeaways

1

OpenAI Pays Most Equity as PPUs (Profit Participation Units), Not Traditional Stock

OpenAI’s primary equity instrument is the Profit Participation Unit, which grants a share of the company’s future profits rather than actual shares, vests over four years, and becomes liquid mainly through periodic tender offers. Some newer employees may also hold RSUs or options, so the first step is understanding exactly what type of equity you have.

2

Concentrated OpenAI Equity Is the Biggest Risk Many Employees Overlook

Because OpenAI equity values have climbed quickly, that equity can make up an outsized share of an employee’s net worth. Advisors suggest dividing your vested equity value by your total investable assets, and building a diversification plan if that figure climbs above roughly 20%.

3

OpenAI Has Confidentially Filed for an IPO, Raising the Stakes on Liquidity Planning

OpenAI confidentially submitted a draft IPO registration with the SEC in 2026, though the company has said timing is undecided and a public listing could still be a while away. A clear plan covers how concentrated you are, how much equity to sell at liquidity events such as tender offers or an eventual IPO, and how to manage the resulting tax bill.

Why OpenAI Employees Work with a Specialist Financial Advisor

Throughout the year, OpenAI provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k), along with equity compensation. Unlike most public companies, OpenAI has historically granted equity as Profit Participation Units (PPUs) — a share of the company’s future profits that vests over several years and becomes liquid mainly through periodic tender offers — though some employees may also hold restricted stock units (RSUs) or stock options. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with OpenAI who specialize in helping OpenAI employees make the most of their income and benefits.

Whether you work at OpenAI’s San Francisco headquarters in the Mission Bay area, a growing office elsewhere in the Bay Area or another city, an international office, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.

Sensitive topics — like the steps you should take before quitting your job at OpenAI to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.

Should You Hire an OpenAI Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving OpenAI employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with OpenAI employees is the better fit for your unique needs.

In the Q&A below, you’ll gain insights from a financial advisor who works with OpenAI employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.

Have a question not yet answered? Use the form below to submit it anonymously and watch this article for updates with answers to your questions. You can also reach out to Tom below to set up an introductory call or contact him with your questions by email.

Q&A: Financial Planning Tips for OpenAI Employees & Executives

In this section, you’ll learn how you can make the most of your OpenAI employee benefits and gain valuable tips from a financial advisor who specializes in working with OpenAI employees and executives.

Financial Advisor Q&A  ·  OpenAI Employees

Tom Lo, CFP®, MBA, Financial Advisor for OpenAI Employees at Vested Financial Planning

Tom Lo, CFP®, MBA

Vested Financial Planning  ·  San Carlos, CA  ·  Serves clients nationwide

Financial planning for tech professionals with equity · Fee-only fiduciary
Book Intro Call

Tom Lo is a financial advisor based in San Carlos, California who specializes in offering financial planning services to OpenAI employees. Tom helps clients get the most value from their OpenAI benefits and compensation package so they can enjoy life and feel confident about their financial future.

QAs a financial advisor with experience helping OpenAI employees save for their retirement, how do you help them make the most of their employee benefits?

For OpenAI employees who want to get to financial independence, I help you make the most of your employee equity including PPUs and RSUs. I help you diversify risk, minimize taxes, and make the most of your OpenAI equity so you can achieve financial independence.

QWhen you first speak with an OpenAI employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?

What are your big life goals? When do you want to get to financial independence? What financial goals do you have for yourself and your partner e.g., buy house? What financial goals do you have for your children e.g. pay for college? What financial goals do you have for your lifestyle e.g., travel? What vested and unvested OpenAI equity do you have?

QIs there a particular benefit available to OpenAI employees you feel isn’t as well utilized or understood by employees as it should be?

OpenAI employees don’t understand your OpenAI equity including PPUs and RSUs as well as it should be because this is by far your most important employee benefit. I can help you understand how to diversify risk, minimize taxes, and use your OpenAI equity to reach your goals including financial independence.

QBeyond OpenAI employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients (e.g. stock, education savings, health savings)?

I find it valuable to discuss your OpenAI equity including PPUs and RSUs to help you so you can diversify risk, minimize taxes, and maximize the value to achieve your other financial goals.

QFor OpenAI employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?

For OpenAI employees thinking about leaving OpenAI, I can help you negotiate your compensation package with your new employer by quantifying the financial value of your OpenAI equity that you’re leaving on the table. I can help you understand the details of your vesting schedule including timing so you can maximize the vesting of your PPUs and RSUs.

QFor OpenAI employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?

I help OpenAI employees approaching financial independence understand how you can use your OpenAI equity and other assets to generate enough income to support your financial independence and with what type of lifestyle.

QFor OpenAI employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?

For OpenAI employees who don’t have the time, energy, interest, or expertise to understand how to diversify risk, minimize taxes, and maximize value of your OpenAI equity including PPUs and RSUs, you should consider working with a financial planner that specializes in working with tech professionals with equity. If a financial planner can help you get 10% more value out of your OpenAI equity that you would on your own, how much would that be worth?

QWhat are some of the unique financial planning challenges you commonly see among your clients who are OpenAI employees and how do you help them overcome these obstacles?

The primary financial planning challenge among OpenAI employees is helping you understand how you can diversify risk, minimize taxes, and maximize the value of your OpenAI equity including PPUs and RSUs so that you can achieve your goals. I help you overcome these obstacles by helping you identify your goals and using selling and tax strategies to maximize the value of your OpenAI equity to help you reach your goals.

QWhat questions do you recommend OpenAI employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?

What percentage and number of your clients are tech professionals with equity? How many clients in total do you work with? Are you fee-only which means the client is the only one who pays the advisor? Are you a fiduciary which means the advisor is legally obligated to work in the clients’ best interest? Are you independent which means the advisor isn’t connected to bank or broker? Do you have the Certified Financial Planner (CFP) designation which is the highest standard for financial planners?

QIs there anything that comes up frequently in your initial meeting with OpenAI employees that surprises you?

OpenAI employees not understanding the importance of the concept of concentrated stock, holding too much of a single company stock, is what surprises me. OpenAI employees are typically taking a ton of risk because OpenAI equity makes up too much of your investable assets. The risk is that something happens to OpenAI and most of your net worth vanishes.

QFor highly compensated OpenAI employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

The primary benefit to take into consideration when preparing your financial plan for highly compensated OpenAI employees and executives is your OpenAI equity including PPUs and RSUs. I want to help you diversify risk, minimize taxes, and maximize value of your equity. For executives and select employees, I want to be aware if you are subject to corporate insider rules and if so, I would look at using a 10b5-1 plan when selling OpenAI equity.

QIs there a particularly memorable experience or a moment you recall with a client who worked at OpenAI when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?

I met with a client who joined OpenAI and we reviewed his PPUs. Within a year of joining which is a relatively short time, the value of his OpenAI PPUs had increased many multiples. The skyrocketing value helped me realize that OpenAI employees have a unique opportunity to use your OpenAI equity to reach your goals likely faster than any tech employees in history.

QGiven OpenAI’s rapid growth and potential future IPO considerations, how do you help employees navigate the complexities of pre-IPO equity compensation and liquidity planning?

I help OpenAI employees navigate the complexities of pre-IPO equity compensation and liquidity planning by walking you through a simple framework that I’ve developed after taking tech professionals through dozens of IPOs. I start by helping you determine your concentration in OpenAI PPUs and RSUs, decide how much in OpenAI PPUs and RSUs to sell, and learn how to minimize taxes when you sell your OpenAI PPUs and RSUs. These are the key steps to take before your OpenAI IPO.

QWith OpenAI’s mission-driven culture around AI safety and the unique pressures of working at the forefront of artificial intelligence, what specific financial wellness strategies do you recommend for managing both the opportunities and uncertainties that come with being at such an innovative company?

I help you identify your goals so you can understand how you can use your OpenAI PPUs and RSUs to reach those goals. By keeping you focused on your goals, I find that this helps OpenAI employees manage both the opportunities and uncertainties that come with working at such an innovative company.

QOpenAI employees often hold equity in a company whose stock isn’t publicly traded — how do you help them think through the considerations and risks of concentrated private-company equity?

I start by helping you determine your concentration in OpenAI PPUs and RSUs so you can understand how much risk you’re taking by calculating how much your OpenAI equity makes up your net worth. Then I help you develop a plan to diversify your risk through tender offers or an IPO and minimize taxes when you do that.

QWhat should OpenAI employees do first since OpenAI filed for an IPO?

OpenAI employees should first calculate how concentrated you are in your OpenAI equity. Take the value of your total vested OpenAI equity and divide by the total value of your investable assets including savings, investments, retirement, and 401ks to get your concentration. If you are more than 20% concentrated in OpenAI, you need to figure out a plan for your OpenAI equity because it makes up lots of your net worth.

Considering a financial advisor who specializes in working with OpenAI employees?

The information contained within this article is provided for informational purposes only and is not intended to substitute for obtaining accounting, tax, or financial advice from a professional. Information provided in this article is not all inclusive and such information should not be relied upon as being all inclusive. In no way should this information be construed or interpreted to be advice for your specific situation. Before making any financial decision you should consider all factors and consult with a professional. This article provides general information only, and is not intended to provide personal investment advice and it does not take into account the specific investment objectives, financial situation and the particular needs of any specific person. In addition, investments in the stock market are subject to fluctuation, and that the price or value of any securities and investments may rise or fall and you may lose part or all of your investment. In addition, any information relating to the tax status of financial instruments discussed in this article is not intended to provide tax advice or to be used by anyone to provide tax advice. You are urged to seek tax advice based on your particular circumstances from an independent tax professional.

Ask an advisor

Ask a Financial Advisor Your OpenAI Benefits & Career Questions

Keep exploring

Find the Right Financial Advisor for You

Browse specialists, compare advisors near you, or find advisors who know your employer’s benefits.

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

You’ve outearned your parents. Probably your grandparents, too. But here’s the uncomfortable truth: the skills that build wealth aren’t the same ones that preserve it across generations. There’s an old saying that captures this perfectly — “shirtsleeves to shirtsleeves in three generations.” First generation builds it. The second generation enjoys it. By the time that wealth passes through the third generation, however, it’s vanished, and the cycle starts over.

Preserving the wealth you’ve worked so hard to build takes real work, and most importantly, clear communication across generations. What many don’t realize is that legacy planning doesn’t stop at the financial and tax considerations. It needs to include your family members’ real feelings and actions as well.

If you haven’t thought seriously about what happens to your wealth, both tax-wise and legacy-wise, you may be leaving more on the table than you think. 

Why the Wealth Preservation Mindset Doesn’t Come Naturally to High Earners

You’ve already proven you can build wealth. You’re naturally wired to accumulate — a diligent saver, a prudent investor, a hard worker.

But the preservation mindset is different, and it might not come as naturally as wealth accumulation. In fact, high earners tend to put off thinking about preserving wealth beyond their lifetimes until they’re confronted with an unexpected life event. A health scare or the loss of someone close has a way of making these questions impossible to ignore.

The Estate Tax Problem Most High Earners Don’t See Coming

The larger the estate, the greater the potential tax exposure. Your wealth transfer strategy will require a different level of tax planning than most people ever need to think about.

The federal estate tax imposes a tax (up to 40%) on the portion of your estate that exceeds the exemption limit. In 2026, that limit is set to $15 million per individual, or $30 million per married couple. It’s adjusted annually for inflation and is subject to changes in federal tax law, meaning future exemption limits aren’t guaranteed. [1] 

While the exemption limit protects the majority of taxpayers from federal estate tax, it may not be enough for high-earners who’ve accumulated significant wealth. When unplanned for, the estate tax can reduce how much of your wealth goes to your children, sending more of your wealth to the IRS than you intended.

The right planning now can protect significantly more of your estate from wealth transfer taxes. You and your family may want to consider tax-focused strategies for protecting and transferring wealth, including:

  • Establishing an irrevocable trust
  • Gifting during your lifetime (being mindful of the annual gift tax exclusion)
  • Charitable giving strategies (Donor-Advised Funds, charitable remainder trusts, etc.)

Generational Wealth Is About More Than the Money 

Beyond the financial assets, think about what you really want to pass down to your family. What personal values have served you well during your lifetime? What financial lessons do you wish you had known sooner? If you own a business, what can you do to instill an entrepreneurial spirit in your children?

Only so much of your legacy plan can live on paper. Every piece of financial knowledge, wisdom, and encouragement you can give your family now is a gift that keeps giving well after you’ve passed. You’ve accumulated more than wealth; you’ve accumulated experience, perspective, and hard-won lessons your family can’t get anywhere else. Share those experiences now, while you have the time and space to do it thoughtfully.

You have a vision of how you want your estate handled and what a meaningful legacy will look like. Don’t assume your children already know. Be specific and clear about how you see your hard work supporting your family for generations to come. Give them the opportunity to ask questions, and encourage open, honest communication.

The Hardest Conversation in Generational Wealth Planning Is Also the Most Important

It’s hard to think of your kids as financial stakeholders, no matter how old they get. Even as they grow and start their own families, it can be hard to see them as the responsible adults they’ve become.

Having candid conversations about your money might not come naturally. Many parents struggle to open up to their kids about wealth. Most people find it easier than they expected once the conversation actually starts.

Your estate plan doesn’t live in isolation from your family. It’s a critical component of your financial world, and it will deeply affect your children when you’re not there to lead the way. Without those conversations, your estate plan has to speak for itself, and that’s a lot to ask of a document. Nobody likes to face their own immortality head-on, but difficult conversations today will greatly ease the stress your family feels later on.

Turning Generational Wealth Goals Into a Real Plan

Review your tax strategy with a professional to understand exactly what your estate could owe after your passing. For high earners, the numbers can be significant, and knowing where you stand is the first step toward taking action.

If you haven’t looked at your estate documents recently, now is a good time. Life changes and estate plans that made sense five years ago may no longer reflect your current situation.

And finally, start having money conversations with your family. If that feels uncomfortable, a financial advisor can facilitate those discussions and help everyone get on the same page.

Building a wealth transfer plan is only half the battle, but it often gets the most attention. The other half — making sure your family understands it, is prepared for it, and knows what you expect of them — is just as important.

If you’re ready to take a closer look at your estate and legacy plans, we’d love to help. At Envision Wealth Planners, we work with high-income families and successful business owners to build generational wealth and legacy plans that go beyond the numbers, including the family conversations that make those plans actually work. Reach out to schedule a call today.

Sources:

  1. https://www.irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill

This article was originally published here and is republished on Wealthtender with permission.

Headshot of Sean Gerlin, CFP®, CPWA®, ChFC®, CLU®
Sean Gerlin, CFP®, CPWA®, ChFC®, CLU® Creating Clarity Out Of Complexity

Sean Gerlin, CFP®, CPWA®, ChFC®, CLU® | Envision Wealth Planners

Do you work at SpaceX?

Get expert insights from a financial advisor who specializes in helping SpaceX employees and executives make the most of their compensation package and benefits.

Looking for a financial advisor who specializes in working with SpaceX employees? You’re in the right place. Below, you’ll find an advisor who understands SpaceX benefits and compensation, along with answers to common financial questions from SpaceX employees and executives.

Whether you’re a new SpaceX employee or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and SpaceX benefits can have a lasting impact on your financial future. For example:

  • Do you know the right moves to get the greatest value from the SpaceX benefits available to you?
  • If you’re thinking about leaving SpaceX for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?

Key Takeaways

1

SpaceX Employees’ Biggest Financial Risk Is Concentration in Company Stock

Years of equity grants and belief in the mission can leave a large share of an employee’s net worth in a single stock. Specialist advisors recommend setting diversification targets in advance and reducing concentration gradually, in a tax-aware way that respects trading windows, rather than making all-or-nothing decisions.

2

Tax Planning Should Come Before Every SpaceX Equity Decision, Not After

Option exercises, RSU vesting, AMT exposure and withholding shortfalls can combine into an unexpectedly large tax bill, and a low cost basis makes selling shares costly. Advisors model multi-year scenarios alongside a CPA so exercises and sales happen deliberately, with cash set aside for the taxes they trigger.

3

Review Vesting Dates and Exercise Deadlines Before Leaving SpaceX

Unvested equity may be forfeited when you resign, and the window to exercise stock options after leaving is often just 90 days. Map what’s vested, what you’d leave behind and which grants are worth exercising before giving notice, then plan your health coverage and 401(k) rollover so nothing falls through the gaps.

Why SpaceX Employees Work with a Specialist Financial Advisor

Throughout the year, SpaceX provides its employees and executives with updates about their benefits, ranging from health insurance and health savings plans to retirement plans like a 401(k), deferred compensation, and equity compensation such as stock options, RSUs, and an employee stock purchase plan. Now that SpaceX is a publicly traded company, that equity comes with a new set of decisions — post-IPO lockup periods, a concentrated position in a stock you can eventually sell on the open market, and the tax consequences of when and how you do it. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with SpaceX who specialize in helping SpaceX employees make the most of their income and benefits.

Whether you work in the Starbase, Texas headquarters, the Bastrop office near Austin, the facility in Hawthorne, California, another office location around the country, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.

Sensitive topics — like the steps you should take before quitting your job at SpaceX to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.

Should You Hire a SpaceX Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving SpaceX employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with SpaceX employees is the better fit for your unique needs.

In the Q&A below, you’ll gain insights from a financial advisor who works with SpaceX employees to help them make smart decisions, navigate the move from a private company to the public markets, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.

Have a question not yet answered? Use the form below to submit your question. You can also contact the financial advisor below directly to set up an introductory call or contact them with your questions.

Q&A: Financial Planning Tips for SpaceX Employees & Executives

In this section, you’ll learn how you can make the most of your SpaceX employee benefits and gain valuable tips from a financial advisor who specializes in working with SpaceX employees and executives.

Financial Advisor Q&A  ·  SpaceX Employees

Ajay Vadukul, CFP®, EA — Financial Advisor for SpaceX Employees at Endeavor Advisors

Ajay Vadukul, CFP®, EA

Endeavor Advisors  ·  Torrance, CA  ·  Serves clients nationwide

Specializes in SpaceX equity compensation, tax planning & retirement
Book Intro Call

Ajay Vadukul is a financial advisor based in Torrance, California who specializes in offering financial planning services to SpaceX employees. Ajay helps his clients get the most value from their SpaceX benefits and compensation package so they can enjoy life and feel confident about their financial future.

QAs a financial advisor with experience helping SpaceX employees save for their retirement, how do you help them make the most of their employee benefits?

SpaceX employees have access to a strong benefits package, but the real value comes from coordinating those benefits with the rest of their financial life. I help clients look at their 401(k), equity compensation, ESPP, and cash savings as one connected system rather than separate accounts. We start by clarifying their goals, then build a plan that uses each benefit in the most tax-efficient and goal-aligned way. For a lot of SpaceX employees, the biggest opportunity is simply making sure their equity and retirement decisions are working together instead of in isolation.

QWhen you first speak with a SpaceX employee, what questions do you like to ask to better understand their unique circumstances?

I start with their goals before anything else: what they want their money to do for them, what timeline they have in mind, and what would make them feel financially secure. From there I ask about their full compensation picture, including salary, bonus, equity grants, and how much of their net worth is tied to company stock. I also want to understand their risk tolerance, their family situation, and whether they expect any major life changes. Those answers shape everything we do next.

QIs there a particular benefit available to SpaceX employees you feel isn’t as well utilized or understood as it should be?

The Health Savings Account is one of the most underused benefits I see. A lot of employees treat it as a simple medical spending account, when it can actually be one of the most tax-advantaged retirement tools available. If you can pay current medical costs out of pocket and let the HSA grow and stay invested, you get a triple tax benefit that very few other accounts offer. It’s a small piece of the benefits package that can quietly become a meaningful part of a long-term plan.

QBeyond retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?

Beyond the retirement accounts, I think the equity compensation and the insurance benefits deserve the most attention. Equity is often where the largest dollars are, so how it’s handled has an outsized effect on someone’s long-term outcome. On the protection side, group life and disability coverage are worth reviewing, because they may not be enough on their own for someone whose family depends on their income. I like to make sure the foundation is solid before we optimize the rest.

QFor SpaceX employees thinking about leaving the company, what actions do you recommend they take before resigning and shortly thereafter?

Before resigning, I encourage employees to map out their equity carefully: what’s vested, what’s unvested, what they may forfeit, and any deadlines they’ll face for exercising options after they leave. Those post-termination windows can be short, and missing one can be expensive. I also recommend reviewing health coverage so there’s no gap, and deciding what to do with the 401(k) ahead of time. Making these decisions calmly before you give notice is far better than scrambling afterward.

QFor SpaceX employees approaching retirement age, how do you recommend they prepare to transition from living off their salary to relying on other sources of income?

The biggest mental shift in retirement is going from saving to spending, and it’s worth preparing for that several years in advance. I help clients build a clear picture of their expenses, then design an income strategy that draws from the right accounts in the right order to manage taxes. We also look at Social Security timing, healthcare costs, and how much risk the portfolio should carry once a paycheck is no longer coming in. The goal is a plan that gives them the confidence to actually enjoy retirement.

QFor SpaceX employees who have managed their finances on their own, what would you suggest they consider to help them decide if they should begin working with a financial advisor?

Plenty of SpaceX employees are smart enough to manage their own finances, so the real question is whether their situation has become complex enough that a second set of eyes adds value. Once there’s meaningful equity compensation, concentrated stock, multiple goals, and real tax complexity, the stakes of each decision go up. That’s usually the point where professional guidance pays for itself. I also think there’s value in having someone objective to talk to, because it’s hard to be fully rational about your own money.

QWhat are some of the unique financial planning challenges you commonly see among SpaceX employees, and how do you help them overcome these obstacles?

The most common challenge is concentration: a large share of net worth tied up in a single company’s stock. That creates real risk, but it’s also emotionally hard to address because the stock has often been very good to them. I help clients work through a thoughtful diversification plan that respects both the tax consequences and their belief in the company, rather than an all-or-nothing decision. The second challenge is tax complexity around equity, which we manage with proactive planning instead of reacting at filing time.

QWhat questions do you recommend SpaceX employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?

I’d ask whether the advisor is a fiduciary, how they’re compensated, and whether they have real experience with equity compensation and concentrated stock positions. Those questions cut through a lot quickly. I’d also ask what their planning process actually looks like and what you can expect in the first year, so you know whether you’re getting comprehensive planning or just investment management. Finally, pay attention to whether they listen well, because the relationship only works if you feel understood.

QIs there anything that comes up frequently in your initial meeting with SpaceX employees that surprises you?

What surprises me most is how many highly accomplished employees still feel uncertain about whether they’re on track. They’ve done a great job earning and saving, but they haven’t had time to step back and see the whole picture, so there’s often an underlying anxiety. Once we lay everything out and put a plan around it, that stress tends to ease quickly. People are usually in a better position than they realized; they just needed it organized and confirmed.

QFor highly compensated SpaceX employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

For higher earners, the planning opportunities and the constraints both get bigger. Trading restrictions and blackout periods can make it harder to diversify on your own timeline, so the planning has to be more deliberate and further ahead. There are also years where bonuses, vesting, and other income can stack up and push someone into a much higher tax bracket. For those clients, building a multi-year tax strategy rather than planning one year at a time can make a substantial difference.

QHow should SpaceX employees think about their equity compensation, which may represent a significant portion of their net worth, especially through the transition from a private company to the public markets?

Equity is often the single biggest financial component for a SpaceX employee, so it deserves the most careful thought. The first step is simply understanding what you hold: the type of equity, the vesting schedule, the cost basis, and the tax treatment of each piece. Many people have a rough sense of the value but not the details that actually drive the decisions.

Here’s what makes this such a pivotal moment: that whole pre-IPO world has come to an end. Now that SpaceX has gone public, the problem flips. The constraint is no longer “I can’t sell”; it’s “I can sell, so how much, and when, and what does it cost me in taxes?” That’s a very different planning conversation, and it’s one a lot of employees haven’t had to have before.

My advice is to decide on a framework in advance: how much concentration you’re comfortable holding, how quickly you want to diversify, and which goals the proceeds should fund. A clear plan made calmly is far better than reacting to every move in the stock price.

QHow do you help SpaceX employees manage the tax impact of their equity compensation?

Taxes are where good planning earns its keep with equity compensation. Depending on the type of equity and the timing of decisions, the difference between a thoughtful approach and a reactive one can be very large. I work with clients to project their income across multiple years, model the tax consequences of exercising or selling, and coordinate closely with their CPA so there are no surprises. The goal is to make tax-aware decisions on purpose, rather than discovering the bill after the fact.

QHow important is diversification for SpaceX employees, especially now that the company is public after years of limited liquidity?

Diversification is one of the most important and most emotionally difficult topics for SpaceX employees, and SpaceX’s move to the public markets has made it especially urgent. When a large portion of your net worth sits in one stock, a single company’s fortunes can determine your financial future, and that’s a lot of risk to carry even when you believe in the mission.

At the same time, I don’t believe in diversifying blindly or all at once. Taxes, conviction, and personal circumstances all matter, so the right answer is usually a gradual, planned reduction in concentration rather than a single dramatic move.

Now here’s what changes everything: SpaceX is now public. Once the stock is trading, employees finally have the ability to act on a diversification plan that may have been impossible before. The key is to decide in advance what you want that plan to look like, so you’re executing a strategy rather than guessing.

I help clients set targets for how much concentration they’re comfortable with and then move toward those targets in a tax-aware, unemotional way over time.

QWhat role does cash flow and emergency planning play for SpaceX employees with significant equity compensation?

Even when someone has substantial equity, I think a healthy cash reserve and steady cash flow are essential. Equity can be volatile and sometimes hard to access at the moment you need it, so cash is what keeps you from being forced to sell at a bad time. I encourage clients to keep an emergency fund that reflects their real expenses and to fund near-term goals from cash rather than counting on the stock. That stability is what lets you be patient and strategic with the equity instead of dependent on it.

QWhat’s the most important piece of advice you’d give a SpaceX employee who wants to make the most of their financial opportunity?

Have a plan before you need one. The employees who do best aren’t necessarily the ones who pick the perfect moment to sell or make a brilliant tax move; they’re the ones who decided in advance what they wanted their money to accomplish and then stuck to that plan. Get clear on your goals, understand what you actually own, and make deliberate decisions instead of reacting to headlines or stock prices. If you do that consistently, you give yourself the best chance to turn a great opportunity into lasting financial security.

Ask an advisor

Ask a Financial Advisor Your SpaceX Benefits & Career Questions

Keep exploring

Find the Right Financial Advisor for You

Browse specialists, compare advisors near you, or find advisors who know your employer’s benefits.

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.