Do you work at Boston Scientific?

Get expert insights from financial advisors who specialize in helping Boston Scientific employees and executives make the most of their compensation package and benefits.

Looking for a financial advisor who specializes in working with Boston Scientific employees? You’re in the right place. Below, you’ll find advisors who understand Boston Scientific benefits and compensation — along with their answers to common financial questions from Boston Scientific employees and executives.

Whether you recently joined Boston Scientific or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and Boston Scientific benefits can have a lasting impact on your financial future. For example:

✅ Do you know the right moves to get the greatest value from the Boston Scientific benefits available to you?

✅ If you’re thinking about leaving Boston Scientific for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?

Key Takeaways

1

Contribute 6% to Capture Boston Scientific’s Full, Immediately Vested 401(k) Match

Many employees stay at the default auto-enrollment rate and never raise it, leaving match dollars behind every paycheck. Boston Scientific’s match vests immediately, so every matched dollar is yours from the day it is deposited.

2

Boston Scientific’s ESPP, HSA, and Individual Disability Plan Are Easy to Overlook

The ESPP’s discount with a six-month look-back, the company HSA contribution, and portable individual disability coverage at a group discount for higher earners can all add real value. The disability plan is especially worth securing during open enrollment, since the coverage stays with you if you leave.

3

Add Up Every Share of BSX Stock Before Planning Retirement or a Departure

ESPP shares, RSUs, and the 401(k) Company Stock Fund can together leave long-tenured employees with far more concentration than they realize. Timing a departure around vest and purchase dates, and considering net unrealized appreciation for 401(k) stock, can preserve significant value.

Why Boston Scientific Employees Work with a Specialist Financial Advisor

Throughout the year, Boston Scientific provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) with an immediately vested company match and, for eligible senior employees, deferred compensation plans — along with an employee stock purchase plan and equity awards such as restricted stock units, performance share units, and stock options. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with Boston Scientific who specialize in helping Boston Scientific employees make the most of their income and benefits.

Boston Scientific is headquartered in Marlborough, Massachusetts, and its other major U.S. sites include Arden Hills, Maple Grove, and Plymouth, Minnesota; Quincy, Massachusetts; and Valencia, California. Whether you work at one of those sites, another office, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.

Sensitive topics — like the steps you should take before quitting your job at Boston Scientific to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.

Should You Hire a Boston Scientific Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Boston Scientific employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with Boston Scientific employees is the better fit for your unique needs.

💡 In the Q&A below, you’ll gain insights from financial advisors who work with Boston Scientific employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.

🙋‍♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.

Q&A: Financial Planning Tips for Boston Scientific Employees & Executives

In this section, you’ll learn how you can make the most of your Boston Scientific employee benefits and gain valuable tips from financial advisors who specialize in working with Boston Scientific employees and executives.

Financial Advisor Q&A  ·  Boston Scientific Employees
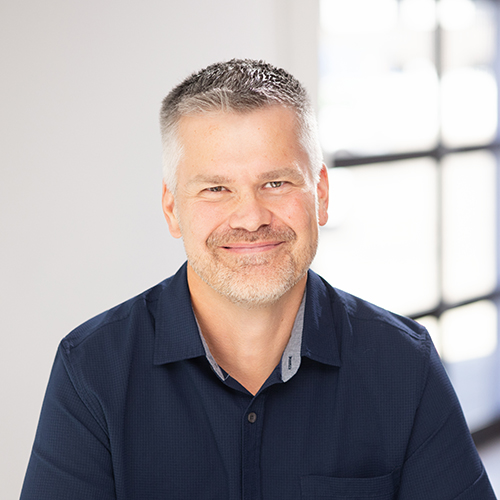
Matthew Nelson, CFP® AIF® ECA, Financial Advisor for Boston Scientific Employees at Perspective 6 Wealth Advisors

Matthew Nelson, CFP® AIF® ECA

Perspective 6 Wealth Advisors  ·  Minneapolis, MN  ·  Serves clients nationwide

Specialized Financial Planning for MedTech Professionals
Book Intro Call

Matthew Nelson is a financial advisor based in Minneapolis, Minnesota who specializes in offering financial planning services to Boston Scientific employees. Matthew helps his clients get the most value from their Boston Scientific benefits and compensation package so they can enjoy life and feel confident about their financial future.

QAs a financial advisor with experience helping Boston Scientific employees save for their retirement, how do you help them make the most of their employee benefits?

Boston Scientific’s 401(k) match structure is one of the first things I walk new clients through, because it’s both more generous and more nuanced than most employees realize. BSC matches 200% on the first 2% you contribute and 50% on the next 4%.  That means to reach the full company contribution of 6% of your pay you need to contribute 6% of your pay. That’s meaningful free money, so be careful not to unknowingly leaving match dollars behind every paycheck by contributing 3% or 4%.

What makes this match especially compelling is that it’s immediately and permanently vested from the day it hits your account. There is no cliff or graded schedule unlike many large employers who use multi-year vesting as a retention tool. Whether you’ve been at Boston Scientific for 18 months or 18 years, every dollar of employer match already belongs to you. That’s a genuine differentiator worth understanding from day one.

Once the 401(k) is optimized, I turn to the ESPP. Boston Scientific’s plan allows employees to contribute 1%–10% of eligible compensation and purchase company stock at 85% of the lower of the stock price at the beginning or end of the six-month offering period. That lookback feature is significant—it means you’re guaranteed a 15% discount at minimum, and in a rising market the effective discount can be considerably larger. I treat proceeds from the ESPP as a systematic funding source: sell the shares at purchase, capture the gain, and redirect the proceeds toward the 401(k), a taxable brokerage account, or other financial goals.

After the 401(k) and ESPP are working efficiently, we build out the broader picture. That means establishing an emergency reserve—I typically recommend two years of accessible savings or investments for clients with significant equity compensation, since a market downturn and a job disruption can happen simultaneously. Beyond that, excess cash flow goes toward maxing out retirement contributions, which also reduces taxable income.

For employees whose income puts them near or above the Roth IRA threshold, pre-tax 401(k) contributions can reduce adjusted gross income enough to open up Roth eligibility. For higher earners above the limit, a backdoor Roth strategy often makes sense. The goal in all of this is to build a tax-diversified retirement picture, not just a large pre-tax balance that creates complications later.

QWhen you first speak with a Boston Scientific employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?

Every first conversation is really about building a complete picture before I say anything prescriptive. Boston Scientific employees often come to me with a specific trigger like a large RSU vest, how to optimize their 401k plan, or a job offer from another company.  Often the immediate question is rarely the most important one, so I want to understand the full context before we zoom in on any one decision.

Some of my favorite questions to open with:

  • What specifically prompted you to reach out now.  Was there a triggering event, or has this been on your mind for a while?
  • What does financial independence look like for you, and when do you want to get there?
  • Do you see yourself staying at Boston Scientific for the long term, or is a move to another company or a start-up on your radar?
  • How are you currently handling your equity compensation like RSUs, PSUs, ESPP shares? Do you have a sell strategy, or are shares accumulating without a plan?
  • Is tax planning something you actively think about, or has it mostly been reactive and you deal with surprises at tax time?
  • Are there goals outside of retirement that matter to you for family, giving, a business, a second career?
  • Does anything keep you up at night financially?

That last question often produces the most useful answer. Anxiety about a concentrated BSX stock position, uncertainty about what happens to unvested equity if there’s a layoff, and concern about whether they’re saving enough are the real starting points for a meaningful planning conversation. Everyone’s situation is different, and these questions help me understand not just the goals but the motivations behind them.

QIs there a particular benefit available to Boston Scientific employees you feel isn’t as well utilized or understood by employees as it should be?

The ESPP is the most obvious one. Boston Scientific’s plan offers a 15% discount with a six-month lookback which is a structure that generates an immediate, relatively low-risk return simply by participating. Yet I regularly meet employees who aren’t enrolled, or who are contributing well below the 10% maximum. The most common reason I hear is that it feels complicated, or they’re nervous about accumulating more company stock. Both are solvable by selling the shares immediately on the purchase date and diversify the proceeds rather than holding them.

The HSA is another one that’s consistently underutilized as a long-term tool. Boston Scientific contributes $500 per year for individual coverage and $1,000 for family coverage into employees’ HSAs.  That’s before you add your own pre-tax contributions. The triple tax advantage is well known in financial planning circles but rarely internalized by employees.  Contributions are pre-tax, growth is tax-free, and withdrawals for qualified medical expenses are tax-free. What most people miss is the long-term power of letting the HSA compound while paying current medical costs out of pocket. The accumulated balance can then be used in retirement for Medicare premiums, long-term care, and other expenses tax-free. After age 65, any withdrawal for non-medical purposes is simply taxed as ordinary income, making it functionally equivalent to a traditional IRA.

But the benefit I find most genuinely overlooked, especially by employees who have been with BSC for several years, is the Individual Disability Income Insurance Plan. Boston Scientific offers eligible employees earning $100,000 or more the ability to purchase individual disability coverage through Guardian at a 25% discount off standard market rates, using unisex pricing. That unisex rate is particularly valuable for women, who typically pay significantly more for individual disability policies on the open market. What makes this benefit especially worth paying attention to is portability.  If you leave Boston Scientific for any reason, the coverage stays with you at the same premium, with no conversion requirements and no new underwriting. That kind of guaranteed-issue access at a group discount is very difficult to replicate once you’re no longer with an employer offering it.

QBeyond Boston Scientific employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?

Absolutely. The HSA is one I come back to often. Boston Scientific contributes $500 annually for individual coverage and $1,000 for family coverage to employees enrolled in the UMR Consumer HDHP. My advice is always the same, treat the HSA as a long-term investment vehicle, not a medical spending account. Pay smaller out-of-pocket costs directly when you can, leave the HSA invested, and let it compound. In retirement, those funds can cover Medicare premiums, long-term care, and healthcare costs that aren’t covered by Medicare—all tax-free. The account is yours permanently, even if you leave Boston Scientific.

The Short-Term Disability program is a benefit I find genuinely underappreciated, and Boston Scientific’s version stands out in the MedTech space. It’s fully company-funded, and the salary continuation schedule is tied to tenure. Employees with 10 or more years of service receive 100% of base pay for the full 26-week STD period. Even employees in their first two years receive 2 weeks at full pay followed by 24 weeks at 75% of base pay. Most employers offer a flat 60% benefit from day one.  BSC’s structure is meaningfully stronger, particularly for tenured employees, and it’s worth factoring into total compensation comparisons when evaluating outside offers.

Long-Term Disability is another important area. Boston Scientific’s LTD pays 60% of monthly earnings up to $15,000 per month after a 180-day elimination period, with the full premium company-funded. For higher earners, there may still be a meaningful gap between the LTD cap and actual income needs. That’s where the supplemental Individual Disability Income Insurance Plan comes in.  They offer additional coverage at a 25% group discount, with unisex pricing and full portability if you leave.

Beyond insurance, I spend significant time on equity compensation planning like RSUs, PSUs, and stock options. Many employees don’t have a clear strategy for when to sell vested shares, how to reduce concentrated BSX stock exposure, or how to manage the tax consequences of equity events. Getting this right has one of the highest financial impacts of anything we do together.

QFor Boston Scientific employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?

The first thing I tell anyone considering a departure from Boston Scientific is: don’t give notice until we’ve mapped every dollar that’s about to vest. The difference between leaving on a Friday versus the following Monday can sometimes be tens of thousands of dollars in RSUs or ESPP proceeds. Employees may time a resignation based on a new employer’s start date without realizing they were a few weeks away from a significant grant vesting. That’s an avoidable and painful mistake.

Something that surprises many departing employees is Boston Scientific’s 401(k) employer match is immediately 100% vested from the day it’s contributed to your account. No cliff, no graded schedule on the match itself. Whether you’ve been at BSC for eight months or eight years, every dollar of matching contributions in your Vanguard account is already yours and goes with you. Many employees assume there’s a vesting wait because at a number of BSC’s MedTech competitors there is. That’s one less thing to worry about when timing your exit.

The one 401(k) vesting item worth checking before you leave is whether you’ve received any discretionary profit-sharing contributions, which follow a separate 5-year graded schedule at 20% per year. These are distinct from the regular match and made at Boston Scientific’s discretion.  Not all employees receive them, but if you have, your Vanguard account will show your exact vested percentage. Worth a quick check before you set a departure date.

Beyond equity and the 401(k), I encourage employees to think carefully about total compensation when weighing an outside offer, not just base salary. Boston Scientific’s STD program pays 100% of base salary for up to 26 weeks for tenured employees, fully company-funded. Most employers can’t match that. If a new offer looks close on paper, it may look less competitive once you account for the benefits package you’re walking away from.

One more item that rarely gets discussed: if you’ve enrolled in Boston Scientific’s Individual Disability Income Insurance Plan, know that this policy is fully portable. You keep it when you leave—same rate, no conversion, no new underwriting. That matters especially if you’re moving to a smaller company or start-up without group disability coverage.

Finally, plan your healthcare bridge before you hand in your notice. Medical coverage ends at termination, and COBRA premiums can be a significant monthly expense. Know your options such as marketplace plans, a spouse’s plan, or COBRA, and have the transition mapped before your last day.

QFor Boston Scientific employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?

Retirement planning for Boston Scientific employees has a few specific wrinkles that don’t apply to everyone. By the time many BSC employees reach their late 50s, they’ve accumulated a meaningful amount of company stock through RSUs that vested over the years, ESPP shares, and contributions to the 401(k)’s Company Stock Fund. The plan has no cap on how much you can hold in company stock, which means concentration risk can grow for years. The single most important pre-retirement move for many of my BSC clients is developing a systematic, tax-efficient plan to diversify away from BSX before they stop working.

Beyond that, the transition from accumulation to distribution requires a clear income map. I ask clients to identify every reliable income stream they’ll have in retirement such as Social Security, pensions, or rental income.  Then calculate the gap that savings and investments need to fill. We model out different Social Security claiming ages, because the difference between claiming at 62 versus 67 versus 70 can be substantial over a 25-year retirement. For most BSC employees with significant assets, delaying Social Security and drawing from taxable accounts first is often the stronger path.

Withdrawal sequencing matters enormously for lifetime tax efficiency. Generally, taxable brokerage accounts first, then tax-deferred accounts like the 401(k), with Roth assets held as long as possible. The years between retirement and the age Required Minimum Distributions kick in are often a window to execute Roth conversions at lower tax rates. Many BSC employees retire with very large pre-tax 401(k) balances from years of contributions and a generous match, and converting some of that to Roth in the early retirement years can significantly reduce lifetime tax burden.

I also encourage clients to set aside four to six years of living expenses in lower-risk assets as they approach retirement. This creates a buffer that allows the equity portion of the portfolio to stay invested through market volatility without forcing sales at the wrong time. It’s a simple framework, but it does a lot to reduce the anxiety that comes with shifting from a paycheck to portfolio withdrawals.

QFor Boston Scientific employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?

There are a handful of inflection points specific to Boston Scientific where the complexity of the benefits package tends to outpace what a generalist or self-directed approach can comfortably handle. If any of the following apply to you, it’s worth a conversation with a specialist.

Ask yourself:

  • Do you have a written strategy for your ESPP shares.  Do you know the difference between a qualifying and disqualifying disposition, and are you timing your sales intentionally?
  • Do you know the total value of BSX stock you hold across your ESPP account, RSU grants, and the 401(k) Company Stock Fund combined? Many employees are more concentrated than they realize.
  • Are you contributing at least 6% to your 401(k) to capture the full, company match?
  • Is your HSA being invested and grown as a long-term retirement asset, or are you spending it down on current medical costs?
  • Have you enrolled in the Individual Disability Income Insurance Plan during an open enrollment window while guaranteed-issue access is available, and do you understand the portability provisions?
  • Do you have a proactive tax estimate built around your RSU vesting schedule, or will you find out what you owe in April?
  • Do you have an estate plan, a current beneficiary review, and a clear plan for what happens to unvested equity if something unexpected happens to you?

Boston Scientific’s compensation package is genuinely complex.  The interplay between the 401(k) match structure, ESPP lookback feature, RSU vesting, deferred compensation plans, and disability benefits creates planning opportunities that are easy to miss and mistakes that are easy to make. The employees I work with who have managed their finances independently are often smart, capable people who simply haven’t had the bandwidth to go deep on all of it. That’s exactly what a specialist is for.

QWhat are some of the unique financial planning challenges you commonly see among your clients who are Boston Scientific employees and how do you help them overcome these obstacles?

The most consistent challenge I see is stock concentration that has crept up over the years without the employee fully recognizing it. Boston Scientific’s 401(k) plan has no limit on how much participants can allocate to the Company Stock Fund, and when you layer ESPP shares and RSU grants on top of that, it’s common for a long-tenured employee to have 50% or more of their investable assets in a single stock. Most clients are surprised when we add it all up. We address this with a systematic, tax-aware diversification plan by spreading sales across multiple tax years, using specific identification on ESPP shares to optimize tax treatment, and coordinating with RSU vesting dates to avoid bunching income unnecessarily.

Equity tax surprises are another very common issue. RSU vesting is a taxable event where shares are treated as ordinary income at the time of vesting, regardless of whether you sell them. If supplemental withholding isn’t calibrated correctly, employees can end up with a large, unexpected tax bill in April. ESPP shares add another layer.  The tax treatment differs depending on whether you hold shares long enough to qualify for preferential long-term capital gains rates, or sell sooner and trigger a disqualifying disposition. Without planning, employees often make the wrong decision from a tax standpoint simply because they didn’t know the rules.

Pre-tax 401(k) accumulation is a third challenge, a good problem to have, but a real one. Boston Scientific’s immediate match vesting, combined with strong employer contributions and years of employee deferrals, means many long-tenured employees arrive in retirement with very large pre-tax balances. Those balances come with future Required Minimum Distributions that can push retirees into higher tax brackets than they expected. We address this proactively through Roth conversions during lower-income years and tax bracket management strategies that spread the burden more efficiently over time.

Finally, disability income gaps for higher earners are a challenge I encounter regularly. Boston Scientific’s base LTD covers 60% of monthly earnings up to $15,000—but for a director or senior engineer earning $250,000 or more, that coverage replaces a much smaller fraction of actual income. The supplemental Individual Disability Income Insurance Plan available through BSC is the right tool to close that gap, but it requires action during open enrollment. I try to get this on every client’s radar early, because access to guaranteed-issue coverage at a group discount disappears once you leave the company or miss an enrollment window.

QWhat questions do you recommend Boston Scientific employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?

Finding the right financial advisor is about more than credentials or a good first impression. I recommend employees ask some pointed questions, such as:

  • Do you have specific experience with Boston Scientific’s benefit plans such as the 401(k) match structure and immediate vesting, the ESPP lookback feature, RSU and PSU programs, and deferred compensation plans like the CAP and NRPS?
  • How do you coordinate 401(k) planning with equity compensation and outside investments?
  • Do you have special training in equity compensation planning, such as the Equity Compensation Associate (ECA) designation?
  • Can you handle financial planning beyond investments such as taxes, estate planning, charitable giving?
  • Are you a fiduciary, and does your firm act as an Independent Registered Investment Advisor?
  • What is your fee structure?  Do I pay separately for financial planning and investment management, or is it an all-inclusive package?

QIs there anything that comes up frequently in your initial meeting with Boston Scientific employees that surprises you?

Yes—and it tends to cluster around the same themes. The most common surprise is how many employees are enrolled at the default 2% 401(k) contribution rate and have never increased it. The auto-enrollment feature means many people are contributing far less than they intend to—and far less than the 6% needed to capture Boston Scientific’s full, immediately-vested match. That’s usually the first thing we fix.

The second common surprise is equity tax exposure that hasn’t been planned for. An RSU vest or large ESPP purchase can generate significant ordinary income in a single calendar year, and many employees have no idea how much additional tax they’ll owe until they sit down with their accountant. We model this out in advance and adjust estimated payments or withholding elections so there are no April surprises.

A third one that genuinely catches people off guard is a survivor benefit most employees don’t know exists. If a Boston Scientific employee passes away while covered, eligible family members receive six months of COBRA continuation coverage at no cost to them. That’s a meaningful benefit that most employees—and honestly most financial advisors—aren’t aware of. It doesn’t change daily financial decisions, but it’s exactly the kind of detail that matters enormously to a family during a very difficult time.

And almost universally, when we aggregate total BSX stock exposure across the ESPP account, unvested RSUs, and the 401(k) Company Stock Fund, the concentration number is higher than the client expected. Showing someone exactly how much of their net worth is riding on a single stock is often the moment the planning relationship really clicks into place.

QFor highly compensated Boston Scientific employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

Higher-income employees and executives at Boston Scientific have unique opportunities that require specialized attention. The Capital Accumulation Plan (CAP) and the Non-Qualified Retirement Plan Supplement (NRPS) are two standout examples. These plans allow eligible employees to defer compensation on a pre-tax basis above IRS 401(k) contribution limits, creating significant savings opportunities. However, planning the withdrawal timing carefully is critical.  Distributions are taxed as ordinary income and can compound with other retirement income in ways that push retirees into higher brackets than anticipated. We look at payout election strategies to spread distributions in a tax-efficient way.

Company stock concentration is a magnified concern at the executive level. Vice presidents and directors often accumulate large BSX positions through RSUs, PSUs, and years of ESPP participation on top of whatever is in the 401(k). Diversifying strategically in coordination with the company’s trading window requirements and any Rule 10b5-1 plan considerations is essential to reducing portfolio risk as they approach retirement.

For executives earning above the LTD benefit cap, disability income planning takes on added importance. The base LTD covers 60% of earnings up to $15,000 per month, but for a vice president or director earning $300,000 or more, that leaves a very significant income gap. The supplemental Individual Disability Income Insurance Plan available through Boston Scientific is an important tool here: executives can secure substantial additional coverage at a 25% group discount, with guaranteed-issue access during open enrollment and full portability if they leave.

We also focus heavily on tax planning around equity compensation such as estimating and managing payments upfront, exploring Net Unrealized Appreciation (NUA) strategies for company stock held inside the 401(k), and considering charitable vehicles like Donor-Advised Funds to offset income in high-earning years. The complexity scales with income and net worth, but so do the opportunities.

QIs there a particularly memorable experience or a moment you recall with a client who worked at Boston Scientific when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?

One case that stands out involved a senior engineer who had been with Boston Scientific for over 15 years and was planning to leave for a start-up opportunity. Over that time, they had accumulated a significant amount of company stock across their ESPP account, the 401(k) Company Stock Fund, and unvested RSUs. When they first came to me, the immediate question was simply: “when should I give notice?”

But when we looked at the full picture (vesting schedules, ESPP offering period timelines, RSU grant dates, and the tax implications of all of it) the real opportunity became clear. By pressing pause and timing the departure strategically around an upcoming RSU vest and ESPP purchase date, we were able to capture a meaningful amount of additional compensation that would have been forfeited with a hasty exit. 

At the same time, we developed a Net Unrealized Appreciation (NUA) strategy for the company stock inside the 401(k), which allowed the client to pay long-term capital gains rates on the appreciated portion of the stock rather than ordinary income rates.  This saved a substantial amount in taxes. We also coordinated the ESPP qualifying disposition holding periods to maximize the tax treatment on those shares.

One final detail that mattered: this client had enrolled in the Individual Disability Income Insurance Plan years earlier and hadn’t thought about it in the context of leaving the company. We made sure they understood the policy was fully portable and they kept it at the same rate with no interruption in coverage.  This was especially meaningful given they were moving to a start-up with no group disability coverage at all.

That experience was a clear reminder of how much value a specialist in Boston Scientific’s specific plans can bring. The intersection of equity compensation, tax strategy, benefit timing, and insurance planning is complex.  When you understand the intricate details, the opportunities are significant. With the right guidance, Boston Scientific employees can put themselves in a strong position for financial independence, whether they’re staying at the company or ready to make their next move.

Considering a financial advisor who specializes in working with Boston Scientific Employees?

Are you a financial advisor who specializes in working with employees at Boston Scientific or another large company?

✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at Boston Scientific or another large company. (Subject to availability and terms.)
✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender

Ask a Financial Advisor Your Boston Scientific Benefits & Career Questions


Are you ready to enjoy life more with less money stress?

Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.
  • This field is for validation purposes and should be left unchanged.

About the Author

Brian Thorp, Founder and CEO of Wealthtender and Editor-in-Chief

Brian Thorp

Founder & CEO, Wealthtender  ·  Editor-in-Chief

Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.

A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.

Brian and his wife live in Austin, Texas.
Read Brian’s full bio →   ·   Connect on LinkedIn →

[Professional investors are awash in Exchange-Traded Funds, with over 5,000 U.S. listed ETFs and more than 14,000 listed globally. This momentum is not a temporary surge, but rather a clear reflection of a structural shift in investment product creation and adoption. ETF launches continue to accelerate, driven by investor demand for transparency, tax efficiency, low fees, and precise exposures. Both established asset management firms and new industry entrants are embracing ETFs across broad beta, thematic, active, and alternative strategies.

Adding to this continuing momentum are regulatory changes that now allow mutual funds to convert into ETFs without creating separate products. This legislation enables large fund families to expand into ETF offerings more efficiently, driving faster adoption, increased competition, and continued innovation, while also improving fee structures and tax efficiency for investors.

To better understand this expansive and ever-growing ETF ecosystem, we spoke with Trammel Robinson, Director, Head of ETF Issuer Relations and Jim Gregory, Senior Director, Head of Business Development at ETF Global – a leading independent provider of enterprise-grade ETF reference data and analytics, and host of the semiannual ETP Forum dedicated exclusively to the global Exchange-Traded Products ecosystem. ETF Global’s next ETP Forum will take place in New York City on June 2, 2026. Attendance is complimentary for ETF Investors such as Wealth Managers, Financial Advisors, Financial Consultants, Investment Consultants, Financial Planners, Family Offices, Endowments, Foundations, Pensions and other professional investor profiles.

At the core of the ETF Global value proposition is timely, comprehensive, precise, and well-structured data designed to power a broad spectrum of ETF investment activities ranging from Portfolio and Risk Management to ETF Research and Selection. The firm delivers T+1 institutional-grade data to hundreds of asset managers, asset owners, financial intermediaries, and investment platforms.

As a specialist data provider, we asked how ETF Global developed its data capabilities into their ETF Global Data Helix which is a centralized data hub to support institutional and financial professionals in navigating the rapidly expanding universe of ETF vehicles. The continued growth of the ETF universe has introduced greater complexity across research, due diligence, risk management, trading, and portfolio construction, heightening the need for advanced analytics, robust data tools, and a deeper understanding of how ETF data can be applied across the investment lifecycle.]

Hortz: How do ETF datasets differentiate among competitors, and why is the level of detail crucial for investment research and institutional users? What specific advantages does a higher level of granularity provide to different clients?

Robinson: ETF Global differentiates through the depth, precision, and structure of its ETF reference data, sourced directly from issuers and normalized into a consistent, research-ready format. While many providers offer surface-level ETF data, ETF Global delivers full look-through transparency into underlying holdings, daily fund flows, ETF classifications, and product structures.

This level of granularity is critical because ETFs are no longer simple beta exposure tools. They represent complex vehicles with embedded exposures, derivatives, and evolving strategies. Institutional, enterprise, and even individual users require precise, timely data to properly evaluate risk, product attributes, liquidity, and correlations.

For quantitative firms, this granularity – along with ETFG’s extensive historical data – enables more accurate modeling, factor analysis, and signal generation. For portfolio managers, it improves security selection, peer comparison, and exposure management. For wealth platforms, it supports better product due diligence and portfolio construction. Ultimately, comprehensive granular data reduces blind spots and enables more informed, confident decision-making.

Hortz: Can you briefly discuss the comprehensive nature of your ETF Data Helix capabilities and the major use cases where ETF data can help firms across their entire operation? 

Gregory: The ETF Global Data Helix is a centralized, companywide data hub designed to provide a comprehensive data panel that maps ETF data across the full investment lifecycle. It enables firms to integrate ETF intelligence across their enterprise and multiple functional areas rather than treating it as a siloed dataset.

Key use cases include:

Research and Analysis – Supports deep ETF screening, peer comparison, factor analysis, and macro attribution.

Portfolio Management – Enables precise exposure management, portfolio construction, and rebalancing decisions using underlying holdings and fund flows.

Trading and Capital Markets – Provides insight into liquidity, spreads, primary market activity, and execution efficiency.

Risk Management – Allows firms to monitor concentration risk, stress scenarios, and hidden exposures within ETF structures.

Distribution and Sales – Equips sales teams with differentiated insights to position products and engage clients more effectively.

Responsible Investment – Supports ESG analysis through transparency into underlying holdings and classifications.

Client Reporting and Advisory – Enhances reporting with deeper insights into exposures, performance drivers, and portfolio composition. 

By connecting these functions, the ETFG Data Helix allows firms to operationalize ETF data across the full enterprise.

Hortz: Can you walk us through the tools and applications that you are developing to help clients understand all the different ways ETF reference data can be utilized? Why is this important?

Robinson: ETF data is highly valuable, but often underutilized due to its volume and complexity. To address this, ETF Global has developed applications and curated datasets, including the Data Helix, to clearly map how ETF data flows across an organization.

These applications simplify complex datasets into intuitive, functional use cases that resonate with different stakeholders – from researchers to sales teams. The broader campaign focuses on education, helping our institutional clients understand not just what data is available, but how it can be applied in practical workflows.

This is important because many firms already have access to ETF data but are not fully leveraging it. By improving understanding and accessibility, ETF Global helps clients unlock additional value from their data investments to drive better outcomes.

Hortz: Let’s dig into some of these use cases more deeply. How can professional investors utilize ETF data when building and managing their own ETF products, investment strategies, and what reconnaissance capabilities does it provide? 

Gregory: For asset managers, ETF data has become essential throughout the product lifecycle. During product development, it supports competitive analysis, market gap identification, and product positioning. Managers can analyze peer products, underlying exposures, daily fund flows, and fee structures to refine their strategy.

Post-launch, ETF data enables ongoing monitoring of performance, flows, liquidity, and holdings as well as compliance with regulations such as SEC Rule 6c-11. The ETF Global Data Helix provides reconnaissance capabilities by offering a full view of the competitive landscape, helping managers identify trends, costs, threats, and opportunities.

For Asset Owners such as family offices, endowments, foundations, and asset managers, ETF data serves as a flexible toolkit for building customized strategies. It allows them to deconstruct ETFs into their underlying exposures, identify inefficiencies, and construct portfolios that align with specific mandates, risk tolerances, and macro views.

Hortz: How do RIA platforms and wealth management firms leverage ETF data from your Helix data platform? What role can ETF data play in fueling recommendation engines and portfolio personalization for wealth management firms?

Gregory: RIA platforms and wealth managers use ETF data to build, refine, and scale ETF model portfolios and strategies for clients. Granular holdings data allows for precise allocation decisions, overlap analysis, and diversification.

ETF data also plays a central role in powering recommendation engines. By integrating flows, performance, exposures, and classifications, firms can generate more tailored investment recommendations based on client objectives, risk profiles, and market conditions.

This enables a more dynamic portfolio approach, moving beyond generic models to more targeted, client-specific solutions, while maintaining scalability across large platforms.

Hortz: How can ETF data be embedded into existing platforms, workflows, and advisory tooling to enhance decision-making processes? 

Robinson: ETF data can be embedded directly into front, middle, and back-office systems to enhance decision-making in real time.

For example, within capital markets, it supports analysis of primary market activity and liquidity conditions. In trading, it informs spread management and execution strategies. In portfolio management, it improves exposure tracking and rebalancing decisions. In risk functions, it enables stress testing and monitoring of hidden exposures. Across the enterprise, it strengthens data governance by providing a consistent, high-quality reference dataset.

By integrating ETF data into existing workflows, firms can move from static and product-level analysis to continuous, data-driven decision-making at both the ETF and underlying constituent levels.

Hortz: How is ETF data being integrated into AI-driven next-best-action platforms, tax exposure analysis and optimization, and sales and distribution automation tools?

Robinson: ETF data is increasingly being used as a foundational input for AI-driven platforms. In next-best-action systems, it helps identify investment opportunities based on flows, trends, and portfolio gaps.

In tax optimization, ETF data enables analysis of embedded gains, turnover, and tax efficiency, allowing advisors to make more informed decisions around rebalancing and product selection.

For sales and distribution, ETF data powers automation tools that identify relevant prospects, tailor messaging, and surface insights that improve engagement with clients.

As AI adoption grows, high-quality ETF data becomes even more critical, as the accuracy of outputs depends directly on the quality of inputs. AI is only as good as the data on which it is trained. 

Hortz: How are fintech companies and digital platforms incorporating ETF reference data to enhance their service offerings?

Gregory: Fintech platforms are integrating ETF data to deliver more sophisticated analytics, screening tools, and portfolio construction capabilities to end users.

This includes enhanced ETF comparison tools, real-time exposure analysis, and personalized investment recommendations. By embedding ETF data into user interfaces, fintech firms can provide institutional-grade insights in a more accessible format.

This elevates the user experience and allows platforms to differentiate through data-driven capabilities.

Hortz: What are the key data requirements for firms engaged in ETF back-office operations and fund administration?

Gregory: Back office and fund administration functions require highly accurate, standardized, and timely ETF data.

This includes holdings data for reconciliation, corporate actions, fund flows, and classification data for reporting and compliance. Consistency and reliability are critical, as errors can impact NAV calculations, regulatory filings, and client reporting.

ETF Global’s structured datasets help ensure that operational teams have a single source of truth to support these functions efficiently.

Hortz: How do you work with firms to help them determine what the most strategic use cases are for them in using ETF data?

Gregory: ETF Global works closely with clients to understand their business model, workflows, and strategic priorities. Rather than taking a one-size-fits-all approach, the focus is on identifying where ETF data can have the greatest impact across the organization.

This involves mapping data capabilities to specific use cases, aligning with functional teams, and helping clients operationalize the data within their existing systems.

The goal is not just to provide data, but to empower clients to fully leverage it to drive measurable outcomes across research, investment, and business functions.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

A middle-aged man, Bill Hortz, with short dark hair wearing a dark pinstripe suit, white dress shirt, and a maroon tie, posing against a plain gray backdrop. He has a slight smile and is looking directly at the camera.

Bill Hortz

Founder Institute for Innovation Development

Bill Hortz is an independent business consultant and Founder/Dean of the Institute for Innovation Development- a financial services business innovation platform and network. With over 30 years of experience in the financial services industry including expertise in sales/marketing/branding of asset management firms, as well as, creatively restructuring and developing internal/external sales and strategic account departments for 5 major financial firms, including OppenheimerFunds, Neuberger&Berman and Templeton Funds Distributors. His wide ranging experiences have led Bill to a strong belief, passion and advocation for strategic thinking, innovation creation and strategic account management as the nexus of business skills needed to address a business environment challenged by an accelerating rate of change.

The patterns in ultra-high-net-worth portfolios are more consistent than most people expect, and recent research puts real data behind what we already see in practice. CEG Insights surveyed 350 ultra-high-net-worth investors, defined as those with a net worth of $25 million or more (not including a primary residence), covering their assets, risk tolerance, investment attitudes, and behaviors. 

These investors are disciplined, diversified, and intentional. What’s worth unpacking is how they execute on those principles and what their approach looks like in practice. Much of it maps directly to conversations I have with clients every day.

What the Data Actually Show

According to the CEG Insights survey, investable assets make up nearly three-quarters of ultra-high-net-worth portfolios. That alone tells you something about where these investors believe wealth is built and maintained. The approach is intentional and diversified, not built on concentration or speculation.

Equities play a central role. These investors are comfortable with market movement in exchange for long-term growth potential. But they are not relying solely on stocks. Nearly a quarter of their investable assets are held in alternatives, meaning assets outside of traditional stocks and bonds, such as private equity, hedge funds, and real assets like commodities. That allocation reflects a deliberate effort to broaden sources of return and reduce reliance on public markets.

Fixed income, which includes bonds and similar investments, represents another notable slice, providing stability and income across different market conditions. Liquidity is part of the plan as well. Cash and liquid assets stay in the mix, creating flexibility for both unexpected needs and new opportunities.

Even real estate plays a supporting role. Primary residences account for a small fraction of total assets. For these investors, a home is a lifestyle decision, not a primary engine of wealth creation.

The Diversification Thread

The wealthiest investors didn’t build or preserve wealth by betting on a single outcome. The thread running through their portfolios is diversification, applied with intention. That same approach informs how I advise clients to think about portfolio construction today.

For years, investments like private equity, private credit, and real assets were largely reserved for institutions and the ultra-wealthy, but access has expanded. Recent Department of Labor guidance has opened the door for certain private investments to be included in qualified retirement plans. More high-income investors now have access to tools that were previously out of reach.

The idea here is to build on what already works. Private investments can offer exposure to companies and sectors not available through public exchanges and may help reduce the impact of market volatility over time. 

Large pension funds and university endowments have used alternatives this way for decades, and the results are well-documented. A National Association of College and University Business Officers (NACUBO) endowment study tracks how institutional portfolios use alternatives to improve long-term outcomes. The Cambridge Associates Private Equity Index reports show private equity has historically outperformed public equity benchmarks over longer time horizons. Individual investors are now gaining access to a similar toolkit.

That said, fit matters. Private investments typically involve longer time horizons, reduced liquidity, and more complexity. The goal is thoughtful integration, not novelty. A well-diversified portfolio has more building blocks available today than it did even a few years ago. The opportunity is in using them deliberately.

The Mindset Behind the Portfolio

Beyond the allocations, the mindset is just as consistent. According to the CEG Insights data, more than three-quarters of ultra-high-net-worth investors find greater satisfaction in saving and investing than in spending. Most want to stay actively involved in day-to-day portfolio decisions, and they don’t treat growth and preservation as competing priorities. They pursue both.

That balance shows up in the data. The Capgemini World Wealth Report 2025 found that high-net-worth investors are actively rebalancing their portfolios, combining preservation strategies with growth-oriented positions. Alternative investments, including private equity, continue to hold a meaningful allocation. Preservation and growth are managed together, deliberately.

The clients I work with tend to share these instincts: disciplined, engaged, and intentional about where their money goes and why.

The question worth sitting with is whether your portfolio actually reflects those instincts. Over time, allocations drift, priorities evolve, and structures that once made sense can fall out of alignment with current goals. Checking that alignment, not just the returns, is often where the real progress happens.

Your Plan, Revisited

The ultra-wealthy don’t rely on a secret. They build a plan, stick with it, and revisit it as life and markets evolve. If you’ve built serious wealth, you’re already doing the hard part. The principles here aren’t out of reach. They’re likely already part of how you think and operate. 

But does your portfolio represent that thinking today? 

If there’s a gap between your goals and how your assets are currently structured, now is a great time to take a closer look. 

This article was originally published here and is republished on Wealthtender with permission.

About the Author

Headshot of Sean Gerlin, CFP®, CPWA®, ChFC®, CLU®
Sean Gerlin, CFP®, CPWA®, ChFC®, CLU® Creating Clarity Out Of Complexity

Sean Gerlin, CFP®, CPWA®, ChFC®, CLU® | Envision Wealth Planners

It’s easy to get excited about everything “out there” and forget all the local resources at your disposal. Retirees often have more programs and services available than they might realize. Not every benefit will apply to your situation, but it’s a good idea to know what’s available.

If nothing else, having a good handle on the resources in your local area might help someone else you know in need. It’s important to stay informed about resources for a successful retirement.

Why Local Benefits Matter More Than You Think

Community programs can dwindle and die because of underutilization. Unfortunately, many programs aren’t used due to a common misconception of services being intended for “someone else.” If you qualify for a beneficial program or service, you need to explore it.

Also, by using a benefit or service, you can help others who might benefit from it. There’s nothing better than first-hand experience to help you guide someone else. Regardless, don’t let these benefits go unused!

Reducing Fixed Expenses in Retirement

When it comes to reaching our financial goals, retirement or otherwise, you really only have three main levers: spend less, make more, or adjust your goals. If you’re able to take advantage of programs and services, you can help reduce your expenses. This can be especially helpful for retirees on a fixed income.

Increasing Your “Spendable” Income Without Taking More Risk

At the end of the day, only the money you get to spend matters. If you’re able to take advantage of local tax breaks or incentives, you can increase your “spendable” money. This keeps more money in your nest egg without adding risk.

Many Benefits Go Unused

By some estimates, seniors miss out on billions of dollars of unused federal aid each year. Not everyone qualifies for these programs, but it’s worth taking a look. There are many programs looking to help.

Property Tax Relief Programs

Once you cross the threshold into retirement, taxes often become one of your major expenses alongside healthcare. Even if you paid your mortgage off, you often can’t escape property taxes. Luckily, there are some programs to help alleviate some of your property tax burden.

We can’t speak for all states, but in Missouri and Kansas, where most of our clients live, programs operate very differently. You’ll need to check with your local county, city, and state government offices to find out if they offer tax relief programs. We’ll touch on Missouri and Kansas briefly so you can see what we mean.

Missouri Property Tax Credit and Freeze Programs

For Missouri property tax freeze programs, each county decides whether to participate and how to administer it. With 114 different counties in Missouri, it’s impossible to keep track of them all. Be sure to check with the local county assessor’s and collector’s offices to learn more.

Kansas Homestead and Refund Programs

On the West side of the Missouri River, Kansas operates its property tax freeze programs much differently. There are three separate programs: the Homestead Refund Program, the Safe Senior (SAFESR) Program, and the Senior or Disabled Veteran (SVR) Program. The eligibility criteria for the property tax freeze programs are somewhat restrictive, so you’ll need to check to see if you’re eligible for them.

Additionally, each county can keep overall tax collections the same each year (revenue-neutral), but many don’t.

Why This Matters for Long-Term Planning

The recent explosion in real estate prices since 2020 has caused many seniors’ property taxes to increase significantly. Over time, these higher evaluations can lead to ever higher property taxes for the same home. All while your income may stay the same or even decrease relative to inflation.

Healthcare and Prescription Cost Assistance

Healthcare is one of the most important issues retirees face, if not the single most important issue. Your access and ability to pay for quality healthcare are huge quality-of-life concerns. Be on the lookout for assistance through federal and local government programs.

Medicare Savings Programs

Although the income limits are quite low, seniors who need assistance paying for Medicare can get assistance. You’ll have to check with your state office to see if you qualify.

It’s a good idea to know about these programs even if you’re not eligible. Even if it’s not helpful to you, it may be useful to friends and family who need some assistance.

Prescription Drug Assistance

Most states offer some type of medication assistance program. These are often called State Pharmaceutical Assistance Programs (SPAPs). You can look for your state’s prescription drug programs and discount card programs here.

These often have eligibility requirements, but they vary by program.

Local Clinics and Community Health Resources

Don’t forget to check for other organizations and nonprofits in your local city and county. There are too many resources to list here, but you never know what’s available until you check.

Utility and Everyday Cost Savings

Some programs are specific to certain age groups, disabilities, or other specific qualifying needs.

Utility Assistance Programs

There are several utility assistance programs available to low-income households or senior citizens. Many local electric cooperatives and/or utility companies will have information on their website. A good place to start looking is the local United Way or the nearest Salvation Army.

Transportation and Senior Discounts

If getting to and from the doctor’s office or grocery store becomes difficult, you may be in luck. There are generally several resources available to you. Search for local transportation resources available to you.

Veteran-Specific Benefits

If you or your spouse served in the military, you might be eligible for many services, programs, and discounts. It’s always a good idea to check the National Resource Directory for benefits you may qualify for.

Local Veteran Service Organizations

If you’re not connected with a local Veteran Service Organization (VSO), it’s a good idea to check for what’s available in your area. You can search the Veterans Affairs website to check for accredited VSOs in your area. Even in rural areas, large organizations like The American Legion and Veterans of Foreign Wars typically have a post close by.

You should be aware of scams. Veterans are never required to pay to apply for or access VA benefits.

Property Tax and Housing Benefits for Veterans

Many states offer an array of tax benefits for military members and veterans. Many of these are specific to the veteran’s VA disability rating, so filing a claim for a service-connected disability should be the first step.

Why Coordination Matters

For veterans, you may need to create a “roadmap” to benefits because many benefits might qualify you for additional benefits. For instance, having a documented service-connected disability may qualify you for additional benefits. Also, you may be eligible for multiple versions of similar benefits.

If you’re not careful, you might end up with a confusing array of benefits which serve similar needs.

Start with Federal, State, and County Resources

Many local benefits depend on funding or eligibility from federal or state benefits. For instance, some prescription programs only apply if you’re already enrolled in Medicare. In other cases, SNAP eligibility might automatically qualify you for other community resources.

However, most local community organizations will help point you in the right direction.

Work with a Financial Planner or Counselor

Just because you’re in a good financial position doesn’t mean you don’t qualify for local resources. It also doesn’t mean you don’t “deserve” help either. If you qualify for a benefit, we’d encourage you to apply.

Most of the time, a financial planner or counselor in the area will have a newsletter or blog with local resource information. Even if you don’t work with them directly, these folks can be a great resource for up-to-date information and insights.

Review Annually

We recommend checking for new benefits and programs each year. It’s common for programs to be shut down or defunded, consolidated, or modified over the years. It never hurts to spend a few minutes checking for new programs.

Bringing It All Together

At the end of the day, knowing your local resources can help you build a more efficient retirement plan. More than likely, your tax dollars fund many of the programs we talked about either directly or indirectly. You may as well get some use from them if you’re eligible.

Stay informed about your local community resources and get the most out of your retirement!

This article reflects the insights and opinions of its author and is not a recommendation or endorsement of their views or services.

About the Author

Headshot of Clint Haynes, CFP®
Clint Haynes, CFP® Helping you build a retirement with pleasure, purpose, and peace of mind.

Clint Haynes, CFP® | NextGen Wealth

Until last year, my wife and I were paying three mortgages. One on our old house, which we kept as a residential rental. Another for an office suite we both use and partially lease to others. The third for our current home.

When we’d had enough of being residential landlords, we sold the rental property, leaving us with two active mortgages. Then I reached a personal and professional decision point: should I mostly retire, or keep running my consulting business full-time?

I chose retirement.

If you were advising me then, you might have asked, “But what about the mortgages? Are you planning to pay them off?” That would have been a fair question. For many people, being debt-free feels like a requirement for retiring responsibly.

In our case, the math didn’t force the issue. We could pay off the mortgage without draining our savings, but both loans carry low fixed rates, so the payments are manageable.

Still, we’ve long planned to downsize. As empty nesters who live close to our kids, we love our home, but it’s more house than we need. But now, things aren’t so simple.

Even if we move to a home costing half as much as our current home and put 20% down, the new mortgage payment would be higher than our current one because today’s rates are so much higher. Downsizing would still reduce our cash-flow needs by lowering utilities, property taxes, maintenance costs, and insurance premiums, so it’ll likely be the right decision in the short to medium term.

But then, we’d face a familiar dilemma: should we buy the next place in cash, or take out a new mortgage and invest the difference? This isn’t a simple “pay it off or don’t” decision.

Even financial advisors don’t all agree. Some say retirees should do everything they can to enter retirement debt-free and stay that way. Others argue that tying up so much net worth in home equity reduces your retirement income and flexibility.

The real issue isn’t whether a mortgage is good or bad, even in retirement. It’s whether you’re evaluating the right factors so you can make the decision that’s right for you.

Key Takeaways

1

Paying off your mortgage before retirement isn’t always the safer choice.

Eliminating a mortgage reduces fixed expenses and provides peace of mind, but it also converts liquid, income-generating assets into illiquid home equity. For retirees with low-rate mortgages or limited portfolio size, paying off the loan can actually increase financial risk by reducing flexibility exactly when you need it most.

2

The mortgage payoff decision must be evaluated as part of your full retirement plan — not in isolation.

Key factors include your mortgage interest rate, the tax consequences of liquidating assets to pay it off, how much of your fixed expenses are covered by guaranteed income sources, and how much liquidity you’ll retain afterward. A large IRA withdrawal to clear a mortgage, for example, can trigger bracket creep, IRMAA surcharges, and a permanently smaller tax-deferred base.

3

A third option — partial paydown with a dedicated mortgage reserve — often beats paying off or keeping the loan outright.

Recasting the mortgage after a partial paydown, or setting aside short-duration Treasuries or a laddered CD portfolio to cover remaining payments, can capture most of the psychological benefit of debt elimination while avoiding a one-time tax event and preserving liquidity. Most retirees don’t realize this middle path exists until a financial advisor models it alongside the two obvious alternatives.

Why the “Pay Off Your Mortgage Before Retiring” Rule Can Backfire

For many people, the idea of keeping a mortgage into retirement feels not just suboptimal, but outright wrong, maybe even irresponsible.

Blame decades of conventional advice that said the only way to retire responsibly is to pay off your mortgage and any other debt you may have. 

That doesn’t mean this view has no merit. If you do this:

  • Your retirement expenses are lower, making your lifestyle easier to sustain.
  • No lender can come in and take away your home for missing a few payments.
  • As a result, there’s the very real emotional comfort of owning your home outright.

That’s why it feels so obvious that if you can pay off your mortgage before you retire, you should absolutely do that.

However, this approach treats your mortgage as a standalone problem you need to solve, rather than as one piece of your larger financial puzzle.

And that’s the pitfall.

Because once you choose to accept that you must pay off your mortgage before retiring, it can dramatically delay your retirement age, just because you haven’t yet “checked that box.” 

This, even if your overall financial picture can support it, 

The result is that you aren’t optimizing for the life you want to live in retirement. Instead, you’re optimizing for following conventional wisdom that may not be wise for you.

Why Financial Advisors Disagree on Paying Off Your Mortgage in Retirement

Some advisors argue passionately that paying off your mortgage as early as possible, especially if you’re about to retire, or already in retirement, is one of the best moves you can make.

Others make just as strong a case for keeping that mortgage in place, especially if the interest rate is fixed and low.

Both sides’ reasoning is valid, for certain people, in certain circumstances.

A perfect example of why it’s called personal finance.

Advisors who favor paying off your mortgage focus on the resulting simplicity and certainty. It eliminates a high fixed cost from your monthly budget, reducing the retirement income you need. This is especially important during a market crash, when your portfolio is down, and you want to avoid, or at least minimize, selling shares.

Seen from that perspective, retiring your mortgage reduces risk and increases stability.

The advisors who argue the opposite focus on flexibility and opportunity.

If you pay off your mortgage, you’re tying up a large chunk of your investable capital in an illiquid asset that provides no income – home equity. This is often described as a “phantom return” equal to the interest rate of the loan you’re paying off.

As Chris Chen, CFP, Wealth Strategist, Insight Financial Strategists, says, “The decision isn’t as straightforward as having cash hanging around in your checking account. For example, you may have held your 30-year mortgage for, say, 20 years. At that point, most of your payment goes toward paying off the principal, essentially moving money from your checking account into your home equity. Very little goes to interest. Suppose you have to take an IRA distribution to pay off the mortgage. Does that distribution interfere with your other goals, such as Roth conversions? Does the distribution make you jump a tax bracket, resulting in a higher tax bill? There is no way to know until you run the scenario.”

Jeffrey J. Smith, Founder & Managing Partner, Owl Private Wealth Advisors, expands, “Paying off your mortgage for most is a financial goal that has been worked for multiple decades. Up until 2020, many soon-to-be retirees likely had a mortgage rate of 5%+, but now we see that same demographic of soon-to-be or recent retirees locked in at historically low rates sub 4%, these historically low rates have made the decision a bit murkier. 

“For many, the decision to pay off or not to pay off the mortgage is part math and part emotion. If they have excess savings in non-qualified accounts, it likely makes sense to pay off the mortgage with those funds simply for the sleep-well factor. 

“If overfunded with qualified retirement savings, it becomes more complicated. Paying off the mortgage with those funds will have implications not only for your current tax year but also for 2 years later, with the potential for higher Medicare Income-Related Monthly Adjustment Amount (IRMAA) premiums, given the 2-year look-back. As stated above, this is a personal decision that can only be made after a careful discussion with the client and their advisor on what is best for their personal financial goals.”

Peter Bo Rappmund, Principal at Counterpoint, agrees, “I lean toward paying off the loan when the math is close and the mortgage creates real friction in a client’s retirement plan. The clearest ‘yes’ cases I see are when a client has a higher-rate mortgage (6% or higher) that they took out in the last few years, the payoff doesn’t require liquidating assets that would trigger a meaningful tax event, and after the payoff, they still have 12–24 months of liquid reserves plus comfortable headroom in their portfolio to cover essential expenses. I’m also more inclined to recommend a payoff when a client takes the standard deduction anyway, that, post-Tax Cuts and Jobs Act (TCJA), is most retirees, because they’re getting no tax benefit from the interest, so the mortgage rate is effectively the after-tax rate. 

“Behavior matters too. For clients who genuinely sleep better without the debt and who aren’t going to redeploy their freed-up cash flow into something riskier, the psychological return is real and worth pricing in.”

Especially today, when so many mortgages are fixed at historically low rates, like our 30-year fixed 3% loan. That’s a very low return compared to what that capital could likely earn if invested for retirement income.

According to DQYDJ.com, the median net worth for Americans in their late 60s is $394k. That’s not very high relative to what’s needed for a comfortable retirement. Worse, however, is that two-thirds of that net worth is tied up in home equity, leaving just $132k to generate income to supplement Social Security retirement benefits.

Anything that ties up a large fraction of your net worth in home equity makes it that much harder to have a reasonable retirement income.

Seen from this perspective, a mortgage isn’t just a liability. It’s a tool for maintaining liquidity, increasing retirement income, and increasing your margin of safety.

That’s why the argument isn’t really about whether keeping a mortgage is good or bad.

It’s about what risk you’re trying to reduce or remove, and which risk you’re more comfortable living with.

Do you prefer predictability and stability, risking a lower standard of living, or would you rather optimize for higher income along with potentially better long-term outcomes?

Neither is universally better.

Each solves for different objectives, which is what makes this a matter for careful, personalized assessment.

How Paying Off Your Mortgage Affects Your Entire Retirement Plan

From the above, it should be clear that framing this as a “mortgage = good/bad” decision is what leads to confusion and disagreement.

Because paying off your mortgage isn’t a simple decision with pros and cons that are independent of the rest of your financial picture.

It’s just one part of your overall finances, along with your income, investments, and spending, and how large or small, and how flexible or fixed, they are.

It’s more useful to shift the question from “Should I pay off my mortgage before or early in retirement?” to “How does paying my mortgage off before retirement (or in early retirement) affect my overall financial safety?”

Once you change your perspective like that, whether to keep the mortgage or pay it off stops being a standalone decision and becomes an integral part of your overall financial plan.

Paying off your mortgage:

  • Reduces your fixed expenses.
  • Lowers the retirement income you need to generate.
  • Per research by David M. Blanchett, PhD, CFA, CFP®, reducing the fixed fraction of your retirement budget lets you increase your safe withdrawal rate (SWR) by ~7% (Blanchett, Head of Retirement Research at Morningstar Investment Management, found that reducing your fixed expense fraction from 75% to 25%, with certain reasonable assumptions, increases SWR from 4.1% to 4.4%).

However, paying off the mortgage also:

  • Reduces your investable assets.
  • Reduces your retirement income.
  • Reduces liquidity and flexibility to respond to unexpected expenses and/or unexpected opportunities, should your circumstances change.

Obviously, keeping your mortgage does the opposite.

  • Keeps fixed expenses higher.
  • Requires higher retirement income.
  • Reduces SWR.
  • Keeps investable assets higher.
  • Increases retirement income.
  • And maximizes liquidity and flexibility.

That’s the trade-off most people miss.

They focus solely on the mortgage decision and miss its implications for flexibility, adaptability, and safety in retirement. And, in retirement, adaptability and safety are every bit as important as optimization, if not more so.

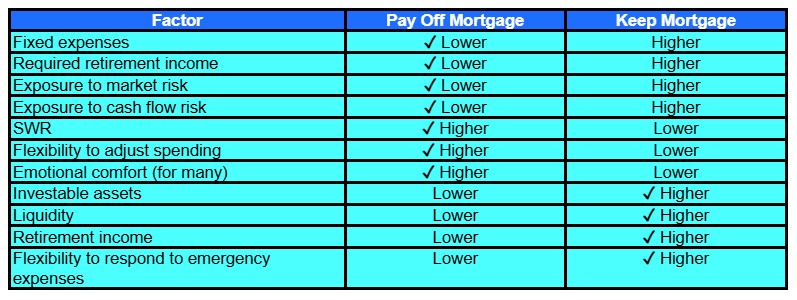
Table 1 shows the factors affecting your decision and how each influences it. In each line, the check mark indicates the preferred outcome.

A comparison table lists factors for "Pay Off Mortgage" vs "Keep Mortgage," showing differences in expenses, risk, flexibility, comfort, investable assets, and retirement income, with check marks and "Higher" or "Lower" under each option.
Table 1. These key trade-offs affect your decision about whether to pay off your mortgage or keep it in retirement.

Why Fixed Expenses Matter More Than Most People Realize

While you’re working, fixed expenses can be a very good thing.

A fixed-rate mortgage means your principal and interest payment never increases during the life of the loan. No landlord raising rents, and no variable-rate loan letting the lender increase your interest rate when the market turns against you.

Predictable and stable.

As long as your income stays stable, you have little to worry about. And if something unexpected happens, you can, e.g., work longer hours, start a side gig, and/or cut expenses elsewhere.

In retirement, your earnings stop. 

Instead, you depend on Social Security, pensions, if any, annuities, if any, and withdrawals from your portfolio.

The first three are predictable, but small to non-existent for most people.

The main source for a comfortable retirement is the last, portfolio-based, assuming you saved enough. Unfortunately, the markets are anything but predictable. 

On average, stocks return about 10% a year. But they could gain 50% one year and drop 40% the next.

That’s why flexibility and margin of safety matter even more in retirement.

Fixed expenses like a mortgage, that can’t easily be reduced, make you less flexible. 

If markets decline or expenses spike, especially early in your retirement, you have lower discretionary spending, reducing the area where it’s usually the easiest to trim costs when needed.

If you need to cover higher expenses and/or have to sell more shares at depressed prices during a bear market to make ends meet, your risk of running out of money increases.

On the flip side, if more of your spending is discretionary, you have more levers to pull to respond to a market crash and/or an expense spike. You can temporarily reduce travel, delay replacing the car, scale back gift-giving, etc., all without disrupting your core lifestyle for long.

On the other hand, even with somewhat higher fixed expenses, a significantly larger portfolio increases your baseline retirement income, which gives you a greater margin of safety, either by allowing you to increase your discretionary spending even more (so a larger fraction of your budget is discretionary) or by drawing a smaller percentage of your portfolio value each year.

Why Downsizing Doesn’t Eliminate the Mortgage Trade-off in Retirement

Downsizing seems like an attractive option for many retirees facing cash-flow limitations.

You sell an expensive home that’s larger than you need, and buy a smaller, less expensive one. This lets you eliminate your mortgage or at least replace it with a smaller loan.

Ideally, that smaller loan means lower monthly payments.

Except when it doesn’t, like in our case.

As mentioned above, our current mortgage rate is so much lower than the current market rates that we could move to a home that costs half as much as our current one, take a new mortgage with 20% down, which would significantly reduce our mortgage balance, and end up with a higher monthly payment than what we’re paying now.

At the same time, downsizing will reduce other costs:

  • A smaller home is easier to manage and cheaper to maintain.
  • It also tends to reduce utility expenses.
  • A less expensive home usually means lower property taxes.
  • It’s also typically less expensive to insure.

All of these reduce monthly cash flow needs, which is an important goal in retirement.

So, we’re still likely going to downsize, at which point we’ll come up against a similar trade-off. What do we do with the equity we unlock from our current home when we sell it?

Do we use most of it to buy a less expensive home outright, with no mortgage, or do we use a small portion of that equity to put down just 20% for a new loan?

This decision goes back to the trade-offs we described above, for eliminating your mortgage before retirement or keeping it in place.

The former would dramatically reduce our cash flow needs and fixed expenses. Still, it would also cost us the opportunity to increase our investable assets and the greater margin of safety that higher retirement income provides.

The latter would reduce our cash flow needs and fixed expenses, but nowhere near as much, because we’d still have the large mortgage payment. However, it would significantly increase our portfolio size, and, along with that, our retirement income and the resulting margin of safety.

Downsizing changes the specifics, but it doesn’t eliminate the trade-offs and the decision.

A Better Framework for Deciding Whether to Pay Off Your Mortgage in Retirement

As we said before, there isn’t a single, universally correct answer that tells you to eliminate your mortgage before retirement (and stay debt-free thereafter), or not.

But that doesn’t mean you have to guess.

You just need better questions and a better decision framework.

Rather than considering the mortgage payoff question in a vacuum, you need to evaluate the multiple impacts on your overall financial situation.

  • With the mortgage vs. without it, how much of your budget is fixed and non-negotiable, and how much is discretionary? The higher your fixed expenses, the more income you need in retirement, regardless of your portfolio’s performance in any given year. This puts more pressure on your investments and makes it harder to adapt when needed.
  • Next, how much of your fixed expenses are covered by predictable sources like Social Security retirement benefits (which also get adjusted up for inflation), pensions, and annuities? The higher the portion of fixed expenses that you can cover from predictable income, the less you need to take from your portfolio, which is especially important when, not if, the market crashes. This gives you more flexibility in managing your investments.
  • Now, look at liquidity. How much of your net worth is tied up in your home equity, which is illiquid and doesn’t generate income that lets you cover unexpected (or even planned-for) expenses? Paying off the mortgage (and not taking out a new one) increases the part of your net worth that’s tied up and non-productive like that. Keeping your mortgage (or taking out a new one when downsizing) does the opposite.
  • Beyond the numbers, it’s time to look at the emotional aspect. When the market crashes, how comfortable will you be with having to continue making fixed mortgage payments? Or would eliminating that mortgage make it easier to stick with your financial plan? Your answers to this point are at least as important as the results of the above three calculations.
  • Finally, consider your margin of safety. Is your portfolio large enough to comfortably support your lifestyle, even when things don’t go exactly as planned? Or are you so close to the edge that you need to do something to increase your margin, e.g., by increasing your productive investments?

Putting all these factors together is how you can make a holistic decision that accounts for the multiple ways that eliminating or keeping the mortgage will affect your retirement in the long term.

After all, that’s the critical goal here.

Not to become debt-free at all costs, and not to maximize returns at all costs.

But to build a plan that offers you a combination of stability, flexibility, margin of safety, and long-term sustainability that you’re most comfortable with and lets you stick with the plan.

Rappmund offers a comprehensive, balanced look at when to pay off vs. when not to. “I lean toward paying off the loan when the math is close, and the mortgage creates real friction in a client’s retirement plan. The clearest ‘yes’ cases I see are when a client has a higher-rate mortgage (6% or higher) that they took out in the last few years, the payoff doesn’t require liquidating assets that would trigger a meaningful tax event, and after the payoff, they still have 12–24 months of liquid reserves plus comfortable headroom in their portfolio to cover essential expenses. I’m also more inclined to recommend a payoff when a client takes the standard deduction anyway, that, post-Tax Cuts and Jobs Act (TCJA), is most retirees, because they’re getting no tax benefit from the interest, so the mortgage rate is effectively the after-tax rate. 

“Behavior matters too. For clients who genuinely sleep better without the debt and who aren’t going to redeploy their freed-up cash flow into something riskier, the psychological return is real and worth pricing in. 

“I push back hard when paying off the mortgage would require a large taxable distribution from a traditional IRA or 401(k), or a concentrated capital gains realization. Especially if it pushes the client into a higher marginal bracket, triggers IRMAA surcharges, or causes more of their Social Security benefit to become taxable. 

“I also advise against it when the mortgage is a legacy (3% or lower) loan; that’s an inflation hedge and a negative-real-rate liability you generally don’t want to retire early. And I won’t sign off on a payoff that leaves a client house-rich/cash-poor, because home equity is the least useful asset in a downturn. You can’t eat it, and a Home Equity Line of Credit (HELOC) can be frozen by the bank at exactly the time you need it most.”

But even when the math seems clear, mistakes are common. Rappmund shares several common mistakes people make: “The single most common mistake I see is comparing the mortgage rate to a hoped-for portfolio return without adjusting for risk, taxes, or sequencing. A client says, ‘My mortgage is 4%, and my portfolio earns 8%, so it’s obvious.’ That comparison is wrong on two fronts: paying off the mortgage is a guaranteed, after-tax return equal to the mortgage rate, while the 8% is a pre-tax, risk-bearing expected return that includes years like 2008. The right comparison is the mortgage rate vs. the after-tax yield on a similar-duration, low-risk bond. On that basis, the decision is much closer than people think. 

“The second mistake is solving for net worth instead of cash flow. Retirement is often fundamentally a cash-flow problem, not a balance-sheet problem. Two clients with identical net worth can have radically different retirement experiences depending on how much of their monthly expenses are fixed and inflexible. 

“And the third, which I see all the time, is making this decision in isolation, separate from the tax plan. Pulling $300k out of an IRA in a single year to clear a mortgage can cost a client tens of thousands in avoidable taxes and Medicare premium increases, and it permanently shrinks the tax-deferred base that was going to compound for the next 20 years.” 

So how should you actually evaluate the trade-offs? Rappmund describes how he helps clients with this, “I help clients weigh the tradeoff between reducing fixed expenses and preserving liquidity and investment income in retirement by separating the question from the math and asking what role this decision plays in the plan. We map out essential expenses (housing, food, healthcare, insurance) vs. discretionary, and we look at what’s already covered by guaranteed income (Social Security, pensions, and annuities). 

“If the mortgage payment is the difference between essentials being covered by guaranteed income and not, that’s a strong argument for retiring the debt; you’re effectively buying yourself a higher floor and reducing sequence-of-returns risk in the early retirement years, which is when portfolio damage is most permanent. 

“From there, we run the actual numbers in the financial plan, modeling paying it off, keeping it, and a third path. And I almost always show a third option, because most clients don’t realize it exists. That path is something like recasting the mortgage after a partial paydown or carving out a dedicated mortgage reserve in short-duration Treasuries or a laddered CD portfolio that earns close to the mortgage rate and gives the client the option to extinguish the loan later if rates or circumstances change. 

“That tends to be the right answer surprisingly often, as it captures most of the psychological benefit and avoids a one-time tax event. The frame I leave clients with is that liquidity is itself a form of insurance, and in retirement, it’s one of the cheaper kinds you can own. 

“Paying off the mortgage converts a flexible asset (cash and securities) into an illiquid one (home equity), and that conversion is irreversible without taking on new debt at whatever rates happen to exist when you need it. So, the question isn’t really ‘should I pay it off?’ Rather, it’s ‘what’s the right amount of fixed-expense reduction I can buy without giving up more flexibility than I can afford to lose?’” 

The Uncomfortable Truth About Entering Retirement Debt-Free

For many retirees or near-retirees, believing the conventional wisdom that “you must enter retirement debt-free” is worse than outdated.

If accepting that paying off your mortgage is a go/no-go gate for entering retirement forces you to:

  • Delay retirement for years.
  • Tie up too high a fraction of your capital in home equity that generates zero income.
  • Reduce your liquidity to the point where you have no good options when something unexpected happens.

Then, following this “rule” can increase your risk and possibly cause you far more financial harm than good.

It’s counterintuitive. Eliminating your mortgage feels like it should reduce your risk, but in some situations, it can leave you more exposed rather than less.

It removes a fixed obligation, simplifies your finances, and reduces the retirement income you need. But it does so while reducing your retirement income, increasing the risk that you’ll need to sell assets when they’re depressed, and leaving you with less liquidity and flexibility.

Over a decades-long retirement, in many situations, those risks may be the ones you’re less comfortable carrying. 

That’s why there isn’t a universally correct answer to the question of eliminating your mortgage before retiring. It’s because the “enter retirement debt-free” rule, like any other financial rule, is designed to offer a simple shortcut for making decisions.

But your situation isn’t simple.

It’s multi-faceted and different than anyone else’s.

A complexity that simple “rules” can’t capture.

The Bottom Line: Should You Pay Off Your Mortgage Before Retiring?

As frustrating as it may be, I can’t give you an answer on whether you should wait until you’ve paid off your mortgage before entering retirement, or even whether taking out a new mortgage in retirement when downsizing makes sense.

That’s because my answer is just that – mine.

You need your answer.

And that answer depends on many factors:

  • How large is your nest egg?
  • How high a retirement income do you need to be comfortable?
  • How will paying off your mortgage affect those two answers?
  • What risks are you comfortable carrying, and which ones do you need to avoid?
  • Which decision gives you the best chance of sustaining your desired lifestyle in retirement over the long haul?
  • Can you, emotionally, stick with a plan that keeps a mortgage into retirement?

For many people, these factors result in a preference for paying off their mortgage.

For many others, they’ll point to keeping the mortgage in place for as long as possible.

Both approaches are right, given the right circumstances. And both are wrong given the wrong situation.

Your bottom line must be based on a clear understanding that the mortgage payoff decision must be made as part of a comprehensive assessment of your personal situation, goals, and risk preferences.

Because to have a good retirement, your decisions can’t be based on box-checking.

They need to be made as part of a comprehensive plan that you can live with and stick to, through good markets and bad, because you will live through both.

As Dr. Steven Crane, Founder of Financial Legacy Builders, says, “I’d only strongly recommend paying off a mortgage if the payment is creating stress or the person needs simplicity to sleep at night. Beyond that, the math doesn’t always support it. I actually push back on people who rush to pay it off just because it ‘feels safe.’ In a lot of cases, they’re trading liquidity and flexibility for a psychological win. 

“The biggest mistake is treating the mortgage like the enemy instead of looking at the full picture. I’ve seen retirees drain a large chunk of their savings to wipe out a low-interest mortgage, only to put themselves in a tighter position long term. They feel better emotionally, but financially, they’ve boxed themselves in. I frame it as control vs. comfort. Paying off the mortgage gives you comfort, no payments, and a clean slate. Keeping the mortgage often gives you more control, more liquidity, and more flexibility if something changes. Most people default to comfort without realizing what they’re giving up. Debt isn’t the problem in retirement. Poor planning is. A mortgage can be managed. Running out of options can’t.”

A practical way to start is this: picture both scenarios.

One where your mortgage is gone, but your portfolio is smaller, and one where your mortgage remains, but your portfolio is larger and more flexible.

Which scenario gives you more confidence that you can handle whatever comes next?

Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

Opher Ganel

About the Author

Opher Ganel, Ph.D.

My career has had many unpredictable twists and turns. A MSc in theoretical physics, PhD in experimental high-energy physics, postdoc in particle detector R&D, research position in experimental cosmic-ray physics (including a couple of visits to Antarctica), a brief stint at a small engineering services company supporting NASA, followed by starting my own small consulting practice supporting NASA projects and programs. Along the way, I started other micro businesses and helped my wife start and grow her own Marriage and Family Therapy practice. Now, I use all these experiences to also offer financial strategy services to help independent professionals achieve their personal and business finance goals. Connect with me on my own site: OpherGanel.com and/or follow my Medium publication: medium.com/financial-strategy/.


Learn More About Opher

If you have kids under 18, you’ve probably looked up college savings numbers.

According to T. Rowe Price (TRP), for example, the full cost of attendance for a four-year degree is $103k at a public university for in-state students and $183k for out-of-state students. At a private non-profit school, that cost grows to $244k.

TRP expects parents to save up enough to pay about half of that, considering likely grants, scholarships, loans, and income from current employment during school years.

If you’re anything like my family was while our kids were growing up, it can seem like an impossible task, especially given all the competing priorities, like putting food on the table, keeping a roof over your head, and hopefully saving at least some money for retirement.

Key Takeaways

1

College savings benchmarks measure a hypothetical family, not yours.

Benchmarks from firms like T. Rowe Price assume you started saving at birth, contributed consistently, and knew years in advance which type of school your child would attend. Most families don’t fit that profile. Being behind on paper reflects those mismatched assumptions — not a verdict on whether your child can afford college.

2

Deciding how much you’re willing to pay matters more than how much you’ve saved.

Defining your funding commitment — whether that’s full cost of attendance, in-state tuition only, a fixed dollar amount, or a percentage of total cost — drives every other decision: school choice, loan strategy, scholarship goals, and how realistic your path forward actually is. Two families with identical savings balances can reach completely different outcomes based on this one conversation.

3

Retirement savings should take priority over college savings when you can’t fully fund both.

Your child has decades of options — loans, scholarships, work-study, and school choice — to fund their education. You have far fewer levers to fund retirement, and every year you delay makes the challenge steeper. Financial advisors consistently remind clients that not becoming a financial burden to your children later in life is itself one of the most meaningful things you can do for them.

When our kids were growing up, we never managed to save a single dollar toward their college costs, let alone meet TRP’s benchmarks, shown in Table 1.

Table showing college costs by age and school type: at ages 5, 10, 15, 18, percentages of full cost are listed, with corresponding costs for in-state public, out-of-state public, and private non-profit schools.
Table 1. Guidelines for the amounts to be saved by children’s age and school type, per TRP (based on covering ~50% of total costs).

In practical terms, that means being expected to have tens of thousands saved well before high school. Those are big numbers, especially if you’re starting late.

Say you have a 15-year-old who has her heart set on attending a private university. Do you already have $91k in her college fund?

If you’re not on track with these guidelines, the gap can feel increasingly uncomfortable. You may be asking yourself, “Are we behind?”

And if the answer is yes, you may be thinking, “Are we failing our daughter?”

That’s a feeling I know well from firsthand experience. 

Since we didn’t have a college fund, we had to figure out ways to cover those costs as we went, using current income, with trade-offs and uncertainty as our constant companions. 

When our son was accepted to our state university’s flagship campus, the University of Maryland, College Park (UMCP), and to a prestigious private school he preferred, we sat him down to discuss what each choice would mean. 

We could cover the full costs of a degree at UMCP without taking out loans, but the private school would have left him with many tens of thousands of dollars in student-loan debt by graduation, even considering their offer to reduce his tuition by 50%.

Conversations like this, and the decisions they led to, shaped how we paid for our kids’ degrees, how they approached school and work, and, ultimately, their careers.

All this forced us to face something that benchmarks and guidelines don’t usually address. Those numbers were never intended to be treated as a scorecard.

They’re a useful planning tool, based on specific assumptions, defined savings goals, and the ability to contribute consistently from birth to college graduation. If you’re anything like we were, your life simply doesn’t look like that.

Some families start late.

Some can’t save consistently, or at all.

Even if you saved from your kid’s birth, they may start out willing to attend their state school, only to decide later that they really want to attend a highly selective, super expensive private school. And when that happens, say when they’re 15, even in the unlikely case that you were “on track” up to that point, you’re suddenly less than halfway to where you’re “supposed” to be.

And yet, many of those families still find a way to make it work.

Not by hitting all the benchmarks on time, but by making informed decisions about what they’ll pay for, what they won’t, and how they expect their children to support the process.

Unless you’re uber-wealthy, you can’t avoid all trade-offs. But you can and should make smart choices about the trade-offs you face.

What that looks like is what we’ll cover below.

What College Savings Benchmarks Actually Measure And What They Don’t

The biggest pitfall of benchmarks like TRP’s is if you believe they’re something they’re not, which may then lead you to despair or make unsustainable decisions.

First, what they aren’t.

They’re not requirements, predictions, or guarantees.

They’re just intended to give you a sanity check. And even that’s limited, because they’re trying to give you a plausible path to successfully funding your kid’s college career, without knowing anything about your situation.

  • How old is your child?
  • What’s the full cost of attendance at the college your child will attend, and how will that cost change by the time your child graduates?
  • How many college years will your child need to graduate (4 is the minimum, not a maximum or even the median*)?
  • How many other children do you have, for whom you need to save in parallel?
  • How much, if anything, do you already have saved up for their college expenses?
  • How much can you afford to put into their college fund, and how consistently?
  • How will you invest that college fund, and what returns will you achieve?

* According to the National Center for Education Statistics (NCES), “In 2020, the overall 6-year graduation rate for first-time, full-time undergraduate students who began seeking a bachelor’s degree at 4-year degree-granting institutions in fall 2014 was 64 percent.” This means that more than one in three students took longer than 6 years to graduate! The median time to graduate was 52 months, and only 44.1% graduated in 4 years.

So, not knowing any of those things, they make assumptions:

  • You have one child (or the following is true for each of your children).
  • You started saving from your child’s birth and contribute a consistent amount each month.
  • You aim to cover 50% of the full cost from your college fund.
  • Your college fund is invested and will compound at a “reasonable” long-term rate.
  • You know the cost level of your child’s college (between the three levels they show).

With all these hypotheticals in place, they generate a plausible trajectory that helps you see if you’re ahead, on track, or behind.

But there’s a problem.

You live in the real world, not in their hypothetical “typical” scenario.

  • You may have started saving later than ideal.
  • You face competing priorities and may have had months (or years) when you couldn’t contribute as much, or at all, to the college fund.
  • College costs are unlikely to stay the same over the 20+ years from when your kid is born until they graduate from college.
  • You may think you’ll send your kid to your state’s school, but they may choose to go to a far more expensive private school.

As Cole Williams, Founder, Vessel Financial Planning, says, “Benchmarks are hard to trust because the true out-of-pocket cost varies so much from family to family. There are too many variables on the front end to know whether you’re ahead or behind.”

Using the benchmarks as gospel is like playing on a tilted playing field with moving goalposts.

Stressful and not very helpful.

TRP recognizes this and provides a secondary set of benchmarks for parents who can’t save as much as their main model assumes, starting from their child’s birth. This secondary model assumes lower contributions early on, with contributions increasing gradually, as seen in Table 2.

A table shows estimated college costs by age and school type: At age 5, in-state public costs $8k, out-of-state public $14k, and private non-profit $18k. Costs rise with age and vary by school type.
Table 2. Guidelines for the amounts to be saved by children’s age and school type, per TRP’s “Ramp up” model (based on covering ~50% of total costs).

This seems much more practical because many families face higher expenses in the early years, especially for childcare, and their earnings are usually lower than in later years. As these factors reverse, it becomes easier to allocate money for college savings.

This shows that TRP realized their benchmarks need flexibility, though even this “ramp-up strategy” doesn’t necessarily account for your specific situation and how it will evolve over 20+ years.

As you can tell, these benchmarks should be viewed as one reference point, not a judgment or verdict on how successful you are.

They help answer the question: If everything went according to the specific assumptions of these benchmarks, where should I be at this point?

They don’t answer any of these questions:

  • Am I doing this right?
  • Have I already failed?
  • Will my child end up unable to go to college because I haven’t saved enough?

They also don’t tell you what to do next, given your specific situation, which is really the only thing that would make a difference.

Things like:

  • Discuss school choice with your kid and make clear what you can and likely cannot afford.
  • Adjust your aim to a smaller portion of the full cost of a degree, with grants, scholarships, and loans covering the remainder.
  • Have your kid work part-time through college to help pay tuition.

Two families can have identical college-fund balances for kids at the same age but have completely different likelihoods of success, depending on how they address potential shortfalls.

That’s why financial advisors tend to treat such benchmarks as a starting point rather than a plan. They use them to surface potential gaps, then shift to defining realistic goals, prioritizing competing needs and goals, and proposing ways of making the plan work by increasing income, decreasing spending, or a combination of the two.

As Joe Stabile, founder of Coast Financial, explains, “Most families I speak with would like to fund their kid’s college 100% if they could, but also understand it may not be realistic. I’ve found that the best way to give them confidence in their decision is to show them different scenarios on what it would take to fund different levels of college tuition. For example, showing them the monthly savings required to fund 100%, 75%, 50%, and 25% of projected college tuition at different tuition rates. Once they see these numbers and we have a conversation about their family values, they feel much more confident in their approach.”

This kind of scenario planning helps make trade-offs concrete and easier to evaluate.

In other words, benchmarks can tell you how close you are to a plausible trajectory, but don’t tell you what to do about it.

That’s our next focus.

The College Planning Decision That Matters More Than Your Savings Balance

Since benchmarks don’t tell you what to do next, what does?

The answer is both simpler and more uncomfortable than you might expect.

You need to decide how much you’re actually willing and able to pay toward your child’s college.

As Mike Hunsberger, ChFC®, CFP®, CCFC, Owner, Next Mission Financial Planning, puts it, “I find that most families are behind in saving for college and don’t understand what they’re likely to be expected to pay at different schools. While saving for college is important, choosing the best school you can actually afford has far more impact.” 

That single decision drives everything else:

  • What type of school can your child realistically attend, cost-wise?
  • Will they need to take out student loans, and if so, how large?
  • Will they need to bring in scholarships and grants?
  • Will they need to work during college to help cover costs?
  • How much “catching up” do you have to do?

Without such clarity, you risk defaulting to “We should cover the full cost of attendance at whatever school she chooses.”

Steve Witter, CFP®, CSLP®, Founder of Student Loan Steve, warns, “The biggest mistake I see with parents is telling their kid that ‘if you get into your dream college, we will figure it out.’ With the new student loan borrowing limits and the loss of parents’ ability to repay Parent Plus loans based on income, it’s more important than ever to have a college budget and stick to it.”

Hunsberger agrees, “The most dangerous words in college planning are ‘If you get in, we’ll figure it out.’ Families need a plan and a budget for college. You don’t shop for Ferraris if all you can afford is a Honda. College shouldn’t be any different.”

Doing that could cause you to:

  • Stretch beyond what you can sustain.
  • Underfund your retirement nest egg.
  • Suffer long-term financial stress that lasts long after your kid graduates.

This is why a good financial advisor won’t ask, “How far behind are you?”

Instead, your advisor is more likely to ask, “What role do you want to play in paying for your child’s college?”

Your answer could be, “All costs related to getting the degree at whatever college he chooses.” And if you can afford that, without shortchanging your other priorities, your advisor will work that into your plan.

However, you could instead say, “Full cost of attendance for 4 years at the in-state tuition level,” or a fixed dollar amount, or a set percentage of total cost.

There’s no universally right answer here.

There’s just an answer that’s right for you, your situation, and your priorities.

Williams explains, “School choice still matters, but it’s not as clean as ‘public = affordable, private = expensive.’ There are exceptions on both sides. What matters more is getting clear early on whose shoulders the funding will fall. Are the parents and student willing to take on loans? Is the student prepared to do the work required to get merit-based aid, such as scholarships or grants? How much? These answers matter a lot.”

He then addresses what often happens when there are several children, “I commonly see spouses who aren’t aligned on what college funding should look like, especially with multiple kids, when ‘being fair’ becomes the goal. Fairness is our instinct as parents, but life doesn’t sit still. One spouse loses a job, or bonuses dry up, or, on the flip side, income increases. The financial picture that existed when your oldest started school often looks different by the time your youngest gets there.”

Should You Prioritize College Savings or Retirement Savings?

Except for the wealthiest among us, we all face financial trade-offs.

The biggest such trade-off regarding funding college is how it interacts, not to say interferes, with saving and investing for retirement.

Hunsberger shares how he illustrates this to clients, “I like to frame the savings choice between college and retirement in terms of how much longer the parents will need to work if they decide that funding college is the priority. If their after-tax income is $120,000 and they have 2 kids that they expect will cost $240,000 to get through undergrad, I make sure they’re willing to work for an additional 2 years.”

Williams agrees, “Every family is different, but my general coaching is to put your own oxygen mask on before helping others with theirs. Some parents commit to covering every dollar of their kid’s education without realizing that choice might require them to work three more years before they can retire comfortably. I want them to see that tradeoff clearly before they share any funding expectations with their students.”

I’m sure you’ve heard the common saying, “You can borrow for college, but not for retirement.”

And while it’s not completely accurate, since you can take out a reverse mortgage to help fund retirement, it is directionally true, since those options tend to be expensive, reduce flexibility, and leave you with a smaller cushion later in retirement.

Student loans, on the other hand, are a $1.8 trillion (and growing) industry that includes both federal and private options.

This doesn’t mean that student loans are appropriate in all cases, nor that students don’t often over-extend themselves and then struggle with years or decades of debt repayment.

But it is a broader and more readily available resource.

Peter Bo Rappmund, Principal at Counterpoint, explains, “Regarding how to balance college savings with retirement savings, especially when you can’t fully fund both, the priority is clear: retirement comes first. You put on your oxygen mask, then help your kids. Your child has decades of options to pay for college, including loans, scholarships, part-time work, and school choice. You have far fewer options to fund retirement, and they all diminish the longer you wait. I remind clients that a loving and thoughtful thing you can do for your kids is not to become their financial burden in 20 years. So, we protect retirement at the level we need to commit to, then direct what’s left toward college, and we have an honest conversation with the child about what that means for school choice.”

A Real-World Example: Starting College With $0 Saved

In our situation with my two older kids, this wasn’t a theoretical trade-off.

We barely managed to put something away for retirement. We certainly couldn’t save anything for their college expenses, so we had to figure out what we could and would do.

Their mother and I, seeing our trajectory early on, told them both, from when they were tweens, that we would cover their full cost of attendance for 4 years at UMCP in-state levels.

If they wanted to attend a more expensive school and/or if they took longer than 4 years, it would be up to them to cover the difference. This could be from grants and scholarships, or student loans.

That was the context of our later conversation with our son, which led him to decline his acceptance to the private school he initially preferred and to attend UMCP. 

While this wasn’t an easy conversation to have, it was clear.

And it was that clarity that led him to make that choice, because he understood that (a) managers at the private school had a higher regard for UMCP graduates in his field than their own, all other things being equal; (b) it would be far better for him financially to avoid the crushing student debt he’d incur; and (c) his career outcome was unlikely to be affected by school choice in the long term, based on research that shows long-term earnings are often similar regardless of school selectivity.

As a result, he graduated in 4 years with a degree in his chosen field from a highly regarded school and went on to a successful career, all from a starting point of $0 in college savings when he started school.

Rappmund says such conversations are critical, “The biggest mistake I see parents make when trying to fund their child’s college education is when they avoid the conversation. Parents will save diligently for 18 years and then never sit their kid down to say, ‘Here’s what we can pay for, here’s what we can’t, and here’s what we expect you to bring or compromise on.’ That straightforwardness and clarity are worth more than another $20,000 in the 529 plan. The mistake isn’t so much that too little was saved. It’s hoping the numbers will perfectly work themselves out by the finish line.”

This illustrates the limitations of college savings benchmarks.

They focus only on the savings balance and the child’s age. Understandably, they can’t account for the things you can do to address any “paper shortfalls.” Things like setting expectations and deciding what trade-offs you’re willing to make.

Two families can have identical college-fund balances, be equally behind (or on track) on paper, and end up with vastly different ultimate outcomes. Had we encouraged our son to go to the private school, his results would likely have been far worse.

In other words, while how much you’ve saved matters, the decisions you make about funding, school choice, and trade-offs matter far more.

That’s what ultimately determines whether a family ends up with a workable outcome or one that creates long-term financial stress.

As Rappmund puts it, “Benchmarks can be a good sanity check, but shouldn’t be a scorecard. The savings balance tells me where a family stands on a hypothetical track. It tells me almost nothing about whether they’ll reach a good outcome, though. The decisions matter far more. I’ve seen families who were ‘behind’ on paper end up just fine because they had those conversations early. And I’ve seen families who were ‘on track’ get into real trouble because they never did.”

The most important takeaway here isn’t that you shouldn’t try to set aside money for your kids’ college education.

It’s that your goal can’t be to avoid every trade-off; it should be to make the trade-off choices that are right for you and your family.

Articulate and share with your kids what you’re willing and able to pay towards their college expenses. Once you do that, even if you’re far behind on paper, your path forward becomes much clearer.

What to Do If You’re Behind on College Savings

If you made it this far and still feel behind, you’re not alone.

But remember, what matters most isn’t where you are relative to benchmarks based on “typical” assumptions.

It’s what you’ll do next.

TRP acknowledges this and offers more nuanced guidance based on your child’s age.

  • If your kid is young, they suggest trying to redirect money spent on childcare to college savings. The point isn’t to fix everything immediately by magically making up any savings shortfall, but to concentrate on changing the trajectory.
  • If your kid is about halfway to college age, they suggest asking family and friends to make college-funding contributions as holiday and birthday gifts, and using income increases, and budget cutting to increase college savings. Here, the point is to make serious changes that make it at least plausible that you’ll hit your goal. 
  • When there’s little or no time left, their guidance is to try to get scholarships, student loans, and paid internships or part-time work while in school. At this point, you’re in the situation we were in. It’s too late to save for college, but you still have options for getting to a good outcome, especially if your kid is willing to attend your state school. 

In our case, we did what we needed to do:

  • Set clear boundaries.
  • Made trade-offs explicit for our kids.
  • Set expectations that they’d work while in school and contribute some of their earnings toward their college expenses.

We also took (legal) advantage of our state’s 529 plan rules.

In Maryland, contributions to a 529 plan may qualify for a state income tax deduction, even if the funds are used shortly after you contribute. Thus, when we needed to make a tuition payment, we first put the money into a 529 plan, then withdrew it the next day and sent it to the school.

We couldn’t benefit from the tax-free growth of investing over time in such plans, but we did get the state income tax deduction for the 529 contributions, which helped make those college expenses somewhat more affordable.

The details of 529 plan rules vary by state, so you may or may not be able to do something similar. But the broader point stands. Even late in the process, there are probably ways you can improve your situation.

The Bottom Line on College Savings Benchmarks

Benchmarks are useful tools. But they’re not a guilty verdict when you’re behind on paper.

Instead of stressing over how far behind you may be, focus on what you can still control.

  • Evaluate and adjust your strategy and the trade-offs you’re willing to accept.
  • Decide what you’re willing and able to pay.
  • Make adjustments where you can.

What you’ve saved so far gives you options you wouldn’t have otherwise. But it doesn’t determine your outcome.

The most important factors in determining your results are the trade-offs you choose and the actions you take from this point forward.

Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

Opher Ganel

About the Author

Opher Ganel, Ph.D.

My career has had many unpredictable twists and turns. A MSc in theoretical physics, PhD in experimental high-energy physics, postdoc in particle detector R&D, research position in experimental cosmic-ray physics (including a couple of visits to Antarctica), a brief stint at a small engineering services company supporting NASA, followed by starting my own small consulting practice supporting NASA projects and programs. Along the way, I started other micro businesses and helped my wife start and grow her own Marriage and Family Therapy practice. Now, I use all these experiences to also offer financial strategy services to help independent professionals achieve their personal and business finance goals. Connect with me on my own site: OpherGanel.com and/or follow my Medium publication: medium.com/financial-strategy/.


Learn More About Opher

It seems like a tempting offer; lower fees are certainly a benefit, as costs impact total return for investors. However, an early investor discount isn’t the only factor to consider (nor is it the most important) when deciding if a private equity opportunity is right for your portfolio. 

Before locking up a portion of your money into a new opportunity, you should know how the investment works, where it fits into your broader plan, and whether the manager is reputable. Two concepts can help you cut through the noise: the J-Curve, which explains why early returns often look discouraging, and fee discounts, which fund managers use to offset that early sting. Understanding how they connect, and what neither one tells you, can help you make a more informed decision.

What Is the J-Curve?

Many private equity funds begin with an investment period where capital is called from the investor (commonly referred to as drawdown funds). During this period, the fund is looking for feasible investments and collecting capital from investors on an as-needed basis. Once they’ve identified and acquired businesses, the capital is deployed, acquisitions completed, and the businesses are infused with funds to help increase profitability. 

When the initial acquisition takes place, no value has yet been gained on the investment, meaning returns are nonexistent—possibly even negative.

The acquired companies begin to improve operations and gain value. During this time, investors may be paying management fees or other operating expenses. With no meaningful exits yet (or no companies sold), gains likely haven’t been realized either. The combination shows a slow start for the fund on paper. If you were to plot the path on a chart, it would resemble the letter “J” (hence the name).

As portfolio companies grow, improve, and eventually get sold or recapitalized, returns may start trending upward at a steeper rate. 

While an initial downturn in value might surprise new investors, the J-curve is a relatively normal part of how private equity performance typically moves.

So, Why Do Fund Managers Offer Fee Discounts?

Remember, it’s likely that once investors have joined the fund, they’ll see the value of their investment initially drop before (ideally) rising over time. Fund managers recognize that this initial downward dip can feel painful for investors. Many offer reduced management fees as a way to soften the blow and reward early participation. 

Lower fees may modestly improve net returns over time and can help reduce some of the drag that often appears during a fund’s earlier stages.

However, a fee discount does not improve the quality of the underlying investments or determine whether a management team is reputable. It also won’t accelerate when portfolio companies are ready to be sold, nor will it reduce risk.

While it may be an effective way to reward those willing to commit capital early in the fundraising process, it should not be a primary reason to invest.

Deciding if Participation Makes Sense

When I evaluate a private equity opportunity with a client, there are a few specific questions I like to start with.

Who is the fund manager?

It’s important to review a fund manager’s track record, paying close attention to how they performed through different market environments. Remember, you’re trusting these managers with your capital. The quality of the team managing the fund is paramount to the success of the investment.

What is the strategy, and does it make sense for you? 

Some funds focus on buying mature businesses. Others target growth companies, distressed opportunities, or niche sectors. The strategy should align with your goals, risk tolerance, and broader portfolio design.

Are you comfortable with the time horizon? 

Private equity is typically a long-term commitment, often with a 5- to 10-year lifecycle. Your capital will likely be tied up for an extended period, with limited opportunities for liquidity along the way. Investors need to be comfortable planning around that reality.

How does it fit within everything else you own? 

While everyone’s asset mix is unique, a private equity allocation will likely need to complement a larger investment strategy, not dominate it. 

That is why I often tell clients, you are not investing because of a fee break. You are investing in a manager, a process, and a long-term strategy.

Selecting the Right Opportunity for Your Portfolio

If you’re already thinking about private equity, it’s certainly worth considering the benefit of lower fees for getting in early. Costs matter, and all else equal, paying less in management fees is better than paying more. 

This article was originally published here and is republished on Wealthtender with permission.

About the Author

Headshot of Sean Gerlin, CFP®, CPWA®, ChFC®, CLU®
Sean Gerlin, CFP®, CPWA®, ChFC®, CLU® Creating Clarity Out Of Complexity

Sean Gerlin, CFP®, CPWA®, ChFC®, CLU® | Envision Wealth Planners

You’ve talked about retirement. You’ve even run some numbers. But somewhere beneath the spreadsheets, there’s a question neither of you has quite asked out loud: Are we actually picturing the same future? In blended families, the answer is often no, not because anyone is being careless, but because each partner brings different obligations and a different sense of what “enough” looks like. Blended family retirement planning starts well before the portfolio. It starts with the expectations each of you carries and where they came from.

Those expectations don’t announce themselves. They show up in assumptions about who owns what assets and what obligations to children or former spouses should take priority. Understanding what each person values, and where that comes from, is where meaningful retirement planning in a blended family begins.

Where Financial Expectations Come From (and Why They Differ in Blended Families)

Every financial decision you make today is connected to something you experienced before. Over time, those experiences become internal rules about what money should do for you. In behavioral finance, these are often referred to as “money scripts”—deeply ingrained beliefs that influence how we save and spend, often without us realizing it. 

In a blended family, aligning your finances requires aligning the beliefs behind them. That’s why expectations around retirement timing, investment risk, and lifestyle can feel so different even when you’re working toward the same future. It’s a dynamic I examine throughout my book, Blended Family Finances: How to Talk About Money, Plan for the Future, and Build a Life You Love. Because understanding where those beliefs come from is the first step toward building a life that you actually want to live.

Even among higher-income couples, asset division, legal costs, and years of financial disruption can leave partners at very different starting points by the time they remarry. U.S. Census data show that adults who have married more than once are significantly less likely to have accumulated substantial retirement savings compared to those who married only once, and the gap persists even when current income is strong. One partner may carry that history internally, shaping how security and fairness feel to them in ways the other may not immediately see. Those differences matter because they shape real decisions.

This is the emotional math of blended family finances—invisible calculations about what feels protective, threatening, or fair. Feelings like guilt toward children, worry of repeating past mistakes, or a desire to protect what you’ve rebuilt can influence your choices. They’re signals worth paying attention to, even when they resist logical solutions, because they can shape everything from how much you save to how you structure your legacy.

Different Starting Points, Different Timelines: Retirement After Remarriage

Our financial history tells a story. In many blended families, perhaps one partner has spent years steadily rebuilding wealth, while the other is still rebuilding after the financial disruption of divorce.

That gap is well documented. According to a Business Insider analysis of U.S. Census Bureau data, the average married retiree has over $100,000 more saved in retirement accounts than a divorced retiree, a difference driven largely by asset division, legal costs, and lost compounding time. Even among couples who remarried, retirement income remained lower than that of those who had married only once.

For higher-income couples, the absolute numbers differ, but the dynamic remains the same. One partner may arrive at the relationship with a well-funded portfolio and a clear retirement timeline. The other might be earning well right now but still carrying the financial weight of starting over after divorce. Those two pictures don’t automatically align, and when they don’t, expectations around retirement timing, lifestyle, and risk tolerance can drift apart.

Those gaps shape how you plan together. How much should you save now? Whose timeline takes priority? How much risk feels comfortable when one partner still feels the urgency to catch up?

These are the kinds of decisions that require coordination across both past and present relationships. And getting them right starts with understanding what each partner is actually bringing to the table.

Clarity Starts with a Conversation

In blended families, many of the biggest financial challenges don’t come from a lack of planning. They stem from assumptions that were never spoken aloud. Over time, those assumptions harden into expectations, and when expectations diverge, even well-resourced couples can find themselves making decisions that pull in different directions.

Bringing those assumptions into the open is where the real planning begins.

One of the most valuable conversations a couple can have isn’t about the numbers—it’s about the experiences that shaped how each person defines security, responsibility, and what ‘enough’ actually means. 

In retirement planning, this is where direction begins. It influences when retirement feels possible, how secure it needs to feel, and how you balance caring for the people who depend on you—past and present—without losing sight of the life you’re building together. 

For example, one partner may feel a responsibility to preserve assets for children from a previous marriage, something shaped by promises made, or lessons learned the hard way. The other may be focused on building a shared future as a couple, assuming that resources will be used more fluidly between present lifestyle and long-term goals.

Neither perspective is wrong. But without a conversation, both can influence decisions:

  • how much risk feels appropriate
  • how aggressively to save
  • how retirement is ultimately structured

And over time, those differences show up in how aligned (or misaligned) the plan feels.

That’s why in our work with blended families, planning doesn’t start with projections alone.

It starts by uncovering: he values each person brings into the relationship, the money stories behind those values, and the vision they’re trying to build together

Because once those pieces are clear, the financial decisions that follow tend to make more sense—not just on paper, but in how they feel to both partners.

Aligning Your Retirement Vision as a Blended Family

You each stepped into this relationship with a story already in progress. Blended family financial planning is the work of bringing those two stories into a coherent shared chapter, one that accounts for where each of you has been while building toward something you can both see clearly.

That work doesn’t have to feel overwhelming. When expectations are surfaced, discussed, and aligned, blended family retirement planning becomes a reflection of the relationships and responsibilities you care about most. 

The question isn’t whether you and your partner see retirement differently. It’s whether you’ve given yourselves the space to say so and to understand why. 

That’s where the planning starts.

And it’s also where having a clear framework can make those conversations more productive.

In my book, I walk through a practical approach for having these conversations, including how to structure them, what to surface first, and how to move from alignment on values to shared direction. It includes a companion workbook so you and your partner can work through the process together.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

Headshot of Brian K. Peterson, CFP®, CPWA®, MBA
Brian K. Peterson, CFP®, CPWA®, MBA Planning Built For Blended Family Life

Brian K. Peterson, CFP®, CPWA®, MBA | Blended Family Financial

Whether you have lived in Northfield for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.

It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Northfield featured on Wealthtender you may want to add to your shortlist.

As you prepare to interview financial advisors in Northfield who may be right for you, get to know local financial advisors featured on Wealthtender.

📍 Map: Financial Advisors with their Primary Office Location in Northfield

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Northfield.

📍Double-click or pinch pins to view more.

Showing

The Benefits of Hiring a Financial Advisor in Northfield

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Northfield, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Do you work for one of the largest employers in Northfield? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Quick Tips For Hiring an Northfield Financial Advisor

Before hiring a financial advisor in Northfield, here are a few quick tips to help you find the best advisor for you.

1. Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2. Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3. Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4. Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.


Frequently Asked Questions & Additional Resources

How do I know if I’m ready to hire a financial advisor?

You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.

But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.

Before I hire a new financial advisor, should I fire my current advisor?

You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.

Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?

After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. 

Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.

I’m a local financial advisor interested in being featured in this guide. How do I get started?

Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.

How Much Does a Financial Advisor Cost?

➡️ How Much Does a Financial Advisor Cost? Read the Article

About the Author
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian