Do you work at NVIDIA?

Get expert insights from financial advisors who specialize in helping NVIDIA employees and executives make the most of their compensation package and benefits.

Looking for a financial advisor who specializes in working with NVIDIA employees? You’re in the right place. Below, you’ll find advisors who understand NVIDIA benefits and compensation — along with their answers to common financial questions from NVIDIA employees and executives.

Whether you recently joined NVIDIA or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and NVIDIA benefits can have a lasting impact on your financial future. For example:

✅ Do you know the right moves to get the greatest value from the NVIDIA benefits available to you?

✅ If you’re thinking about leaving NVIDIA for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?

Key Takeaways

1

NVIDIA’s ESPP Look-Back Makes It One of the Company’s Most Valuable Benefits

The advisors below describe NVIDIA’s employee stock purchase plan as unusually attractive because the discount applies to the lower of the price at the start or end of a long offering period. They pair it with a plan for vesting RSUs so the purchases support cash flow without deepening concentration risk.

2

Concentration in NVIDIA Stock Is the Challenge Advisors See Most Often

Equity grants and strong share-price growth can leave a disproportionate share of an employee’s net worth — and their paycheck — tied to one company. The advisors below help clients diversify in a way that feels rational rather than disloyal, while planning ahead for the taxes that selling triggers.

3

After-Tax 401(k) Contributions Help High-Earning NVIDIA Employees Save Enough

After-tax 401(k) contributions and in-plan conversions of pre- and after-tax savings are among the most underused tools available to NVIDIA employees. For high earners, the advisors below note that the extra room can be the difference between falling short and reaching a savings rate of 15% to 20% of salary.

Why NVIDIA Employees Work with a Specialist Financial Advisor

Throughout the year, NVIDIA provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) — along with equity compensation such as restricted stock units and an employee stock purchase plan. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with NVIDIA who specialize in helping NVIDIA employees make the most of their income and benefits.

NVIDIA’s headquarters is in Santa Clara, California, and Austin, Texas, is one of its largest U.S. sites, with engineering teams in hubs such as Durham, North Carolina, Westford, Massachusetts, Seattle, and Beaverton, Oregon. Whether you work at one of those sites, another office location around the country, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.

Sensitive topics — like the steps you should take before quitting your job at NVIDIA to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.

Should You Hire an NVIDIA Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving NVIDIA employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with NVIDIA employees is the better fit for your unique needs.

💡 In the Q&A below, you’ll gain insights from financial advisors who work with NVIDIA employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.

🙋‍♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.

Q&A: Financial Planning Tips for NVIDIA Employees & Executives

In this section, you’ll learn how you can make the most of your NVIDIA employee benefits and gain valuable tips from financial advisors who specialize in working with NVIDIA employees and executives.

Financial Advisor Q&A  ·  NVIDIA Employees
Emily Rassam, CFP®, CRPS, AIFA, NSSA, CDAA, Financial Advisor for NVIDIA Employees at Archer Investment Management

Emily Rassam, CFP®, CRPS, AIFA, NSSA, CDAA

Archer Investment Management  ·  Charlotte, NC  ·  Serves clients nationwide
Book Intro Call
Richard J. Archer, CDAA, CFA, CFP®, MBA, Financial Advisor for NVIDIA Employees at Archer Investment Management

Richard J. Archer, CDAA, CFA, CFP®, MBA

Archer Investment Management  ·  Austin, TX  ·  Serves clients nationwide

Book Intro Call
Specializes in NVIDIA employee financial planning & equity compensation

With a focus on serving professionals in the technology industry, the financial advisors at Archer Investment Management help their clients get the most value from their benefits and compensation package so they can enjoy life and feel confident about their financial future. Based in Charlotte, North Carolina, and Austin, Texas, respectively, Emily Rassam and Richard Archer specialize in offering financial planning services to NVIDIA employees.

QAs a financial advisor with experience helping NVIDIA employees save for their retirement, how do you help them make the most of their employee benefits?

Emily: At Archer Investment Management, we specialize in working with mid-career technology professionals. We have several NVIDIA employees as clients and are familiar with the company’s employee benefit plans, retirement plans, equity compensation packages, and ancillary benefits. More importantly, we are acutely aware of the financial planning needs of technology professionals and how their Nvidia benefits fit into an overall financial plan, including long-term planning, goal setting, tax planning, and estate planning. We start by building a financial personality profile and risk tolerance assessment to understand your relationship with money and your comfort level with risk.

QWhen you first speak with an NVIDIA employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?

Richard: Our detailed onboarding process includes conversations about your life goals, how your finances play a role in maximizing happiness, and what it means to be intentional with money. We gather information about your benefits and compensation package, spending plan, short-term and long-term goals, taxes, estate plans, and insurance. This detailed planning process allows us to build a comprehensive picture of your financial life and how each piece of the puzzle fits together. You cannot make recommendations without examining the whole picture.

QIs there a particular benefit available to NVIDIA employees you feel isn’t as well utilized or understood by employees as it should be?

Richard: I see two areas that are underutilized and often deserve more attention. (1) The opportunity to make after-tax 401(k) contributions. (2) The ability to perform an in-plan conversion of your pre- and after-tax savings. Employees tend to focus on contributing to their pre-tax or Roth 401(k) without realizing the power of additional savings via after-tax 401(k) contributions.

QBeyond NVIDIA employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients (e.g., stock, education savings, health savings)?

Emily: NVIDIA offers an Employee Stock Purchase Plan (ESPP) within which they can receive a 15% discount on NVIDIA stock. You can contribute up to 15% of your salary. The offering price is set on the first trading day after your enrollment month, and it remains the ‘look-back’ price for up to 24 months. There are four purchase periods within that 24-month period. and the 15% discount is applied to the lower of the price at the beginning or end of the offering period. NVIDIA also contributes up to $3,000 annually to your Health Savings Account (HSA).

QFor NVIDIA employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?

Emily: Your matched 401(k) dollars are 100% vested from day one. However, you may have received employee stock options or restricted stock units (RSUs) that are unvested. Look carefully at the dates on your grants and vesting schedules to determine when each grant vests; this may impact your timing to leave NVIDIA – you don’t want to leave any money on the table! You have 90 days after departing the company to exercise your stock options. Work with an advisor to determine which grants to exercise and the best way to fund this purchase.

QFor NVIDIA employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?

Richard: Our detailed retirement planning process includes:   

  • A spending strategy tailored to your income goals
  • Social Security timing recommendations
  • Coordination of health care benefits
  • Discussion around how your spending will change throughout retirement
  • Stress-testing your retirement projection with many what-if scenarios
  • Timing your exit to maximize any unvested incentive stock options (ISOs), non-qualified stock options (NSOs), or RSUs

QFor NVIDIA employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?

Emily: There are many online tools and calculators. Where we find NVIDIA employees get stuck is understanding how to prioritize goals and seeing the big picture. We help NVIDIA employees organize their financial lives and provide accountability for reaching goals. Understanding whether you should use surplus dollars to pay down debt, save towards a short-term goal, or work towards a long-term aspiration (such as retirement or college education savings) can be challenging. For Nvidia employees planning with a spouse or partner, an advisor helps facilitate difficult conversations and moves the ball forward in your planning process.

QWhat are some of the unique financial planning challenges you commonly see among your clients who are NVIDIA employees, and how do you help them overcome these obstacles?

Richard: One common obstacle we find is knowing when to diversify away from the concentration risk of holding a high percentage of your net worth in one company’s shares. Many of our NVIDIA employee clients struggle with selling positions; it requires coaching, recognizing natural human biases, an evaluation of the risks, and careful diversification away from an outsized position.

QWhat questions do you recommend NVIDIA employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?

Richard: If you were granted ISOs or RSUs, be sure to work with an advisor who understands how to incorporate those into your overall picture. Seek an advisor who can model the alternative minimum tax (AMT), understands the rules around qualifying and disqualifying dispositions, and knows how and when to diversify away from sizeable single stock positions, if appropriate.

QIs there anything that comes up frequently in your initial meeting with NVIDIA employees that surprises you?

Richard: Employees do not always understand the full realm of benefits – both big and small – available to them. Be sure to carefully review the benefits available to you! For some employees, this may be the first time they have received an equity compensation package, and they often need our guidance to fully understand the type of grant they received and potential tax implications. We enjoy helping people with strategies to ensure they fully benefit from their entire compensation package.

QFor highly compensated NVIDIA employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

Emily: For highly compensated employees, we advise you contribute the maximum to your 401(k) with after-tax dollars. Without that additional contribution, it will be hard to save the recommended amount of 15% to 20% of your salary.

QIs there a particularly memorable experience or a moment you recall with a client who worked at NVIDIA when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?

Emily: One of our clients did not have the opportunity to contribute to an ESPP at a previous employer. We helped him understand the benefits of purchasing company stock at a 15% discount and encouraged him to contribute the maximum amount. We also showed him how to use vesting RSU shares as cash flow to offset money set aside for the ESPP purchase if needed. NVIDIA’s ESPP has a particularly attractive feature in that the stock price at the beginning of the offering period is part of the look-back for 24 months.

Financial Advisor Q&A  ·  NVIDIA Employees
Richard Siminou, MBA, Financial Advisor for NVIDIA Employees at Siminou Wealth Management

Richard Siminou, MBA

Siminou Wealth Management  ·  Long Island, NY  ·  Serves clients nationwide

Financial Advisor for Business Owners, Entrepreneurs & Pre-Retirees in New York
Book Intro Call

Richard Siminou is a financial advisor based in Long Island, New York who specializes in offering financial planning services to Nvidia employees. Richard helps his clients get the most value from their Nvidia benefits and compensation package so they can enjoy life and feel confident about their financial future.

QAs a financial advisor with experience helping Nvidia employees save for their retirement, how do you help them make the most of their employee benefits?

Employees at large companies are often in a fortunate position — the benefits packages tend to be genuinely strong — but that also means there are a lot of moving parts to coordinate, and the stakes are high.

The first thing I do is make sure no one is leaving free money on the table. That means capturing the full 401(k) match before anything else. From there, we look at whether pre-tax or Roth contributions make more sense given where they are in their career and what their income looks like today versus in retirement.

For employees who receive equity compensation — RSUs, stock options, or an ESPP — that’s often where the bigger conversation happens. Equity can be a tremendous wealth-building tool, but it also creates real risks: concentration in a single stock and a tax bill that catches people off guard at vesting. I help clients build a thoughtful diversification strategy so they’re not overexposed to any one position, and we plan proactively for the tax implications so nothing comes as a surprise.

For employees on a high-deductible health plan, I also make sure they’re maximizing their HSA — not just as a healthcare fund, but as a long-term investment vehicle. Most people don’t realize it’s one of the most tax-efficient accounts available.

What I enjoy most about working with employees of large companies is that they’re often sharp, motivated, and have real wealth-building potential through their benefits alone. My job is to bring all the pieces together — the 401(k), the equity, the HSA, the taxable accounts — into one coordinated strategy so that every dollar is working as efficiently as possible.

QWhen you first speak with a Nvidia employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?

The first conversation is really about listening more than talking. My goal is to understand not just where someone stands financially, but where they want to go — and what’s standing in the way.

I usually start with some foundational questions: Where are you in your career, and how are you thinking about the next five to ten years? Are you planning to stay with this employer long-term, or is there a possibility of a transition down the road? Those answers shape almost everything else.

From there I get into the specifics of their benefits. Are they capturing the full employer match on their 401(k)? How are they invested inside the plan, and does that still make sense given their timeline? If they receive equity compensation — RSUs, stock options, an ESPP — I want to understand how much of their net worth is tied to a single company’s stock, because concentration risk is one of the most common and underappreciated issues I see.

I also ask about taxes. Not in a technical way at first, but questions like: Did anything surprise you on your tax return last year? Are you feeling like you’re paying more than you should? That opens up a conversation about whether we can do better through smarter use of pre-tax accounts, HSAs, or deferred compensation if it’s available.

And then I ask the question that often matters most: What does financial security actually look like for you? The answer is different for everyone. For some people it’s retiring early. For others it’s funding their kids’ education without derailing their own retirement. For executives it might be building enough outside their employer that they have real optionality. Understanding that goal — that specific vision — is what drives everything else we do together.

QIs there a particular benefit available to Nvidia employees you feel isn’t as well utilized or understood by employees as it should be?

Without question — the HSA, or Health Savings Account. It’s the most underutilized financial tool I see across the board, and it’s a shame because the tax advantages are extraordinary.

Most people treat the HSA like a flexible spending account — they contribute a little, pay their medical bills out of it, and move on. What they’re missing is that the HSA is actually a triple tax-advantaged account: contributions go in pre-tax, the money grows tax-free, and withdrawals for qualified medical expenses are tax-free. No other account does all three.

What I encourage clients to do, if their cash flow allows, is pay current medical expenses out of pocket and let the HSA grow invested for the long term. After age 65, you can withdraw the money for any reason — not just medical — and it essentially functions like a traditional IRA. But if you do use it for healthcare costs in retirement, which most people will have plenty of, it’s completely tax-free. That’s a powerful combination.

The other benefit I’d mention is deferred compensation, for those who have access to it. Non-qualified deferred compensation plans are available at many large employers for higher-earning employees, and they can be a meaningful way to reduce current taxable income and build wealth outside of the standard retirement account limits. But they come with real complexity and risk that needs to be understood before participating — which is exactly where having an advisor in your corner makes a difference.

QBeyond Nvidia employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?

Absolutely — and this is actually one of my favorite conversations to have, because most employees are sitting on benefits they’ve never fully explored.

Equity compensation is usually the first place I look. Whether it’s RSUs, stock options, or an Employee Stock Purchase Plan, these can represent a significant portion of someone’s total compensation — and they come with real decisions attached. When do you sell? How much do you hold? What’s the tax impact? I see a lot of employees either ignore these questions entirely or make emotional decisions about their company stock rather than strategic ones. Getting this right can make a meaningful difference in long-term wealth building.

Education savings is another area worth a dedicated conversation, particularly for employees with young children. A 529 plan isn’t an employer benefit in the traditional sense, but many large employers offer payroll deduction into 529 accounts, which makes the habit easy to build. More importantly, it’s a conversation that often gets delayed until it’s too late to let compounding do its work.

Life insurance and disability coverage are benefits people tend to click through during open enrollment without really thinking about. Group coverage through an employer is a great starting point, but it’s rarely sufficient on its own — especially for higher earners — and it doesn’t travel with you if you leave the company. I like to make sure clients understand what they actually have and where the gaps are.

Finally, I always ask about any financial wellness programs or legal services the employer offers. These are frequently overlooked and can provide real value, particularly around estate planning basics like wills and healthcare directives — documents that everyone needs but most people put off indefinitely.

The common thread across all of these is that benefits only create value if you actually understand and use them. My job is to make sure nothing valuable falls through the cracks.

QFor Nvidia employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?

A job transition is one of those moments where the financial decisions you make in a short window can have a lasting impact — for better or worse. I always encourage clients to slow down and think through a few key areas before they hand in their notice.

The first thing I look at is vesting schedules. Whether it’s a 401(k) employer match, RSUs, or stock options, leaving before a vesting date can mean walking away from meaningful compensation. Sometimes it’s worth negotiating a start date with the new employer to capture a vesting event that’s just weeks away. That’s a conversation most people don’t think to have.

Equity is the other big pre-resignation consideration. If you hold vested stock options, there’s typically a limited window — often 90 days — to exercise them after you leave. Missing that deadline means forfeiting them entirely. RSUs that haven’t vested yet are generally gone when you walk out the door, so understanding exactly what you’re leaving on the table is critical before making any final decision.

On the benefits side, I encourage clients to take stock of their health insurance situation before their last day. COBRA is always an option but can be expensive, so knowing how quickly the new employer’s coverage kicks in helps avoid any gaps.

For the 401(k), there’s no need to rush a decision, but shortly after leaving I’d recommend rolling it over to an IRA or the new employer’s plan rather than leaving it scattered across former employers. It’s easier to manage, typically opens up more investment options, and keeps your financial picture clean and consolidated.

And finally — the offer letter itself. Before signing, I always encourage clients to look at the full compensation picture at the new employer, not just the base salary. How does the equity package compare? What’s the 401(k) match? Is there a vesting cliff? Understanding the complete package helps make sure the move actually makes financial sense from day one.

QFor Nvidia employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?

The transition from a steady paycheck to drawing down from multiple income sources is one of the most significant financial shifts a person will ever make — and in my experience, the people who navigate it most successfully are the ones who start planning it seriously three to five years out, not three to five months out.

The first thing I work through with clients approaching retirement is what I call the income gap analysis. We add up all the guaranteed income sources they’ll have — Social Security, any pension, annuity income if applicable — and compare that to what they actually need to live comfortably. Whatever’s left is what the portfolio needs to cover, and that shapes everything from asset allocation to withdrawal strategy.

Social Security timing is one of the highest-impact decisions in this phase and one of the most misunderstood. Claiming early can make sense in certain situations, but for many people delaying — even by a few years — results in a meaningfully higher monthly benefit for the rest of their life. We model this out carefully based on health, other income sources, and whether there’s a spouse involved.

Healthcare is another area that deserves serious attention, particularly for anyone looking to retire before Medicare eligibility at 65. Bridging that gap can be expensive, and it needs to be factored into the retirement budget explicitly rather than treated as an afterthought.

On the portfolio side, I work with clients to gradually shift their thinking from accumulation to distribution — which is a fundamentally different challenge. It’s not just about how much you’ve saved, it’s about sequencing withdrawals intelligently across taxable accounts, tax-deferred accounts like IRAs and 401(k)s, and tax-free accounts like Roth IRAs to minimize the tax drag over time. Getting that order of operations right can add real longevity to a portfolio.

And then there’s the psychological side, which doesn’t get talked about enough. After decades of saving and accumulating, actually spending that money can feel deeply uncomfortable for a lot of people. Part of my job in this phase is helping clients feel confident and grounded in their plan — so they can enjoy retirement rather than worry their way through it.

QFor Nvidia employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?

I have a lot of respect for people who have taken ownership of their finances and done the work on their own. That discipline and engagement is actually a great foundation for a productive relationship with an advisor. The question I’d encourage them to ask isn’t “have I done okay so far?” — because the answer is probably yes — but rather “is doing this alone still the right approach given where I am and where I’m headed?”

The complexity argument is the most straightforward one. Early in a career, personal finance is relatively simple — contribute to the 401(k), build an emergency fund, avoid bad debt. But as income grows, equity compensation enters the picture, taxable accounts accumulate, families expand, and retirement starts moving from a distant concept to an actual horizon, the number of interconnected decisions multiplies quickly. At that point, the cost of a suboptimal decision — whether it’s a tax mistake, a poorly timed equity sale, or a Social Security claiming error — can far exceed the cost of professional guidance.

I’d also ask: how much time are you actually spending on this, and is that the best use of your time? Many of the people I work with are high achievers who are extremely capable of managing their own finances. But capability and bandwidth are two different things. If financial decisions are getting made reactively — or worse, getting deferred — because life is busy, that’s worth examining honestly.

Another honest question is around blind spots. We all have them. A good advisor isn’t just a technician — they’re a thinking partner who can challenge assumptions, stress test a plan, and flag things you might not know to look for. Most people don’t know what they don’t know until something goes wrong, and by then the cost of finding out can be significant.

And finally, I’d suggest looking at a few key moments as natural triggers for seeking a second opinion: a job change, an inheritance, a major equity vesting event, a divorce, or the death of a spouse. Any one of those situations involves enough complexity and enough at stake that having an experienced guide in your corner is genuinely valuable — not just reassuring.

The goal of a first conversation with an advisor shouldn’t be to hand everything over. It should be to get an honest assessment of where you stand, what you might be missing, and whether there’s enough value on the table to make the relationship worthwhile. A good advisor will tell you the truth either way.

QWhat are some of the unique financial planning challenges you commonly see among your clients who are Nvidia employees and how do you help them overcome these obstacles?

Working with employees of large companies over the years, a few patterns come up consistently — and they’re worth naming because recognizing them is half the battle.

The first is what I’d call benefits paralysis. Large employers offer generous and often complex benefits packages, and the sheer number of decisions — 401(k) elections, health plan choices, equity grants, deferred compensation options, life insurance levels — can be genuinely overwhelming. The path of least resistance is to set something up during onboarding and never revisit it. I see people years into their careers still invested in the default target-date fund they selected on day one, with life insurance coverage that made sense when they were single but is now completely inadequate for a family. My job is to bring structure and intentionality to decisions that otherwise get made by default.

Concentration risk is another challenge I encounter constantly. When someone has worked at the same company for a long time and received equity compensation along the way, it’s very common for a disproportionate share of their net worth to be tied up in a single stock — their employer’s. There’s often an emotional attachment to that stock, a sense that loyalty or conviction should translate into holding. But from a pure risk management standpoint, having your income and your investment portfolio both dependent on the same company’s fortunes is a vulnerability. I help clients think through diversification in a way that feels rational rather than disloyal.

Lifestyle creep is a quieter challenge but a very real one, particularly among high earners at large companies. As compensation grows — base salary increases, bonuses, equity — spending tends to grow with it, sometimes faster. I work with clients to make sure that as their income rises, their savings rate and investment contributions are rising proportionally, not just their expenses. Building real wealth is about the gap between what you earn and what you spend, not the absolute level of either.

Tax complexity is something a lot of employees underestimate until it bites them. Between equity vesting events, bonus income, potential deferred compensation, and investment accounts, the tax picture for a high-earning employee at a large company can get complicated quickly. I work closely with clients — and coordinate with their CPAs where appropriate — to make sure we’re being proactive rather than reactive when it comes to tax planning.

And finally, there’s the challenge of integration — or the lack of it. Most people manage different pieces of their financial life in isolation. The 401(k) is one conversation, the equity compensation is another, the mortgage is another, the insurance is another. Nobody is looking at the whole picture at once. That’s precisely what I do. Bringing everything together into a single, coherent strategy is where the real value of financial planning lives.

QWhat questions do you recommend Nvidia employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?

This is a question I genuinely love, because I think everyone should approach hiring a financial advisor the way they’d approach any other important professional relationship — with real curiosity and a willingness to ask direct questions. The right advisor will welcome the scrutiny. Here’s what I’d encourage people to ask:

How are you compensated? This is the most important question on the list and the one people are most reluctant to ask. Understanding whether an advisor is fee-only, fee-based, or commission-based tells you a great deal about where their incentives lie. There’s no single right answer, but you deserve a clear and honest explanation — not a vague or defensive one.

Are you a fiduciary, and in what capacity? A fiduciary is legally required to act in your best interest. Some advisors are fiduciaries all the time, some only in certain contexts, and some not at all. Knowing where your advisor stands on this — and when — matters enormously.

What is your experience working with clients in situations like mine? If you receive equity compensation, have significant assets in a company retirement plan, or are navigating a specific life transition, you want an advisor who has real familiarity with those circumstances — not someone who will be learning on your time.

What does your typical client look like? This helps you understand whether you’ll be a priority or an afterthought. An advisor whose practice is built around clients at a very different income or asset level may not be the best fit, regardless of how capable they are.

How often will we meet, and what does ongoing service look like? A financial plan isn’t a document — it’s a living relationship. You want to understand upfront how proactive the advisor will be, how accessible they are between scheduled meetings, and what you can expect when your circumstances change.

Who else is on your team, and who will I actually be working with day to day? At larger firms especially, the person you meet with initially isn’t always the person managing your relationship. It’s worth understanding the structure before you commit.

And finally — can you explain a time you told a client something they didn’t want to hear? A good advisor isn’t just a validator. They push back when it matters, flag risks you might be overlooking, and prioritize your long-term interests over your short-term comfort. How an advisor answers this question tells you a lot about their character and their willingness to have honest conversations.

The goal of these questions isn’t to trip anyone up — it’s to find someone you can trust completely with one of the most important areas of your life. The right advisor will answer every one of them directly and without hesitation.

QIs there anything that comes up frequently in your initial meeting with Nvidia employees that surprises you?

Honestly, yes — and the same few things come up more often than you’d expect, even among people who are financially engaged and working at sophisticated organizations.

The one that surprises me most consistently is how many people don’t know what they actually own inside their 401(k). They know they’re contributing, they have a general sense of the balance, but when I ask what they’re invested in and why, there’s often a long pause. A lot of people are in whatever default option they selected years ago and have never revisited it. For something that may ultimately be one of their largest assets, that level of inattention is striking — though I understand how it happens. Life gets busy, the account is out of sight, and as long as the balance is going up it’s easy to assume everything is fine.

Another thing that comes up frequently is a genuine surprise at how much equity compensation they’ve accumulated — and how concentrated that makes them. People receive grants periodically, the stock does well, and before long a significant portion of their net worth is tied to a single company. When I show someone that number visually, as a percentage of their total picture, it often lands differently than they expected.

I’m also consistently surprised by how many people have never looked carefully at their insurance coverage — life, disability, long-term care. They enrolled in whatever the employer offered during onboarding, accepted the default amounts, and haven’t thought about it since. For someone whose income and family situation have changed substantially over the years, that coverage is often badly misaligned with their actual needs.

And then there’s estate planning. I would say the majority of people I meet for the first time — across all income levels — either have no will at all or have one that’s badly out of date. People know they need it, they intend to get to it, and somehow it never rises to the top of the list. It’s one of the first things I encourage clients to address, because it’s not just a financial document — it’s how you take care of the people you love when you’re no longer able to do it yourself.

What ties all of these together is that they’re not failures of intelligence or effort — they’re failures of attention and integration. People are busy, the financial system is complex, and without someone periodically looking at the whole picture, important things quietly fall through the cracks. That’s exactly the gap a good advisor fills.

QFor highly compensated Nvidia employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

Absolutely — and this is an area where the complexity increases significantly and the cost of not having a coordinated plan can be substantial. Highly compensated employees and executives often have access to a layer of benefits that goes well beyond what’s available to the broader workforce, and each one comes with its own set of decisions, tax implications, and risks.

Nonqualified deferred compensation plans are one of the most powerful tools available to executives, and also one of the most misunderstood. The ability to defer a significant portion of income — sometimes hundreds of thousands of dollars — into a future tax year can be enormously valuable for someone in a high bracket today who expects to be in a lower bracket in retirement. But these plans are fundamentally different from a 401(k). The deferred amounts are technically still a liability of the employer, meaning they’re at risk if the company runs into financial trouble. The distribution elections are also largely irrevocable once made. Getting the strategy right from the beginning matters enormously.

Executive equity compensation tends to be more complex than standard RSU grants. Stock options — particularly incentive stock options, or ISOs — come with specific tax treatment that requires careful planning around exercise timing, alternative minimum tax exposure, and holding periods. The difference between a well-timed and a poorly timed exercise can be measured in tens of thousands of dollars or more.

Supplemental executive retirement plans, sometimes called SERPs, are another benefit worth understanding thoroughly. These are employer-funded retirement arrangements designed to provide additional income beyond what qualified plans like the 401(k) allow, and the terms vary widely from company to company.

Executive life insurance arrangements — things like split-dollar policies or executive bonus plans — also come up frequently at this level and require a careful look to make sure they’re structured in a way that actually serves the executive’s interests and integrates properly with their overall estate plan.

And speaking of estate planning — at the executive level this conversation becomes significantly more involved. We’re often talking about wealth transfer strategies, trust structures, charitable giving vehicles, and in some cases business succession considerations. The financial plan and the estate plan need to be built together, not treated as separate exercises.

What I find most important with highly compensated clients is that all of these pieces — the deferred comp, the equity, the insurance, the estate plan, the investment portfolio — are looked at holistically and updated regularly as circumstances change. The opportunities at this level are genuinely significant, but so are the consequences of getting it wrong.

QIs there a particularly memorable experience or a moment you recall with a client who worked at Nvidia when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?

There’s one that comes to mind that I think illustrates the point really well — and it’s a situation I’ve seen play out in different variations more times than I can count.

I met with a client who had been with a large employer for about twelve years. She was sharp, successful, and by any measure financially responsible. She had been contributing to her 401(k) consistently, had no significant debt, and felt like she had a reasonable handle on her finances. She came to me not because something was wrong, but because her compensation had grown considerably and she wanted a second set of eyes.

When we sat down and actually mapped out her complete financial picture, a few things became immediately clear. First, she had accumulated a substantial amount of vested company stock through RSU grants over the years — far more than she had mentally accounted for — and it represented nearly half of her investable net worth. She had always thought of her portfolio and her equity compensation as two separate things. They weren’t. They were deeply connected, and the concentration risk was significant.

Second, she had been eligible for her company’s nonqualified deferred compensation plan for three years and had never enrolled. Nobody had ever walked her through how it worked or why it might be worth considering. Given her tax bracket, that was a meaningful missed opportunity — not catastrophic, but real.

And third, her estate plan consisted of a will she had drafted before she was married, before she had children, and before her net worth had grown to its current level. It was essentially obsolete.

None of these were failures on her part. She had done a lot of things right. But they were a perfect illustration of what happens when the pieces of a financial life are managed in isolation rather than as a whole. The moment I laid it all out on one page — the portfolio, the equity, the deferred comp eligibility, the estate plan gap — I could see the shift in her expression. It wasn’t alarm, it was clarity. She finally saw her complete financial picture for the first time.

That’s the moment I find most meaningful in this work. Not when something has gone wrong, but when someone who has been doing well realizes they could be doing significantly better — and that the path to get there is clearer than they thought.

Considering a financial advisor who specializes in working with NVIDIA Employees?

Are you a financial advisor who specializes in working with employees at NVIDIA or another large company?

✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at NVIDIA or another large company. (Subject to availability and terms.)
✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender

Ask a Financial Advisor Your NVIDIA Benefits & Career Questions


Are you ready to enjoy life more with less money stress?

Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.
  • This field is for validation purposes and should be left unchanged.

About the Author

Brian Thorp, Founder and CEO of Wealthtender and Editor-in-Chief

Brian Thorp

Founder & CEO, Wealthtender  ·  Editor-in-Chief

Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.

A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.

Brian and his wife live in Austin, Texas.

Read Brian’s full bio →   ·   Connect on LinkedIn →

Do you work at Southern California Edison?

Get expert insights from financial advisors who specialize in helping Southern California Edison employees and executives make the most of their compensation package and benefits.

Looking for a financial advisor who specializes in working with Southern California Edison employees? You’re in the right place. Below, you’ll find advisors who understand Southern California Edison benefits and compensation — along with their answers to common financial questions from Southern California Edison employees and executives.

Whether you recently joined Southern California Edison or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and Southern California Edison benefits can have a lasting impact on your financial future. For example:

✅ Do you know the right moves to get the greatest value from the Southern California Edison benefits available to you?

✅ If you’re thinking about leaving Southern California Edison for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?

Key Takeaways

1

Southern California Edison’s Pension Election Is a One-Time, Irrevocable Decision

Payout options, survivor elections, and their trade-offs can make a substantial difference over time. Model each option’s impact on lifetime income, taxes, and your spouse before you elect, rather than defaulting to the highest payment.

2

Working One to Three More Years at SCE Can Meaningfully Raise Your Pension

Before resigning, request a current pension estimate and compare it with projections for staying a little longer, especially near key milestones in the benefit formula. Review your 401(k), deferred compensation, and healthcare benefits before you leave, too.

3

SCE Deferred Compensation Offers Tax Benefits but Carries Employer Risk

Deferring income in peak earning years can lower taxes, but poorly structured distributions can create large taxable income later. Because deferred comp assets depend on the company’s financial strength, integrate them carefully with your pension, 401(k), and wider portfolio.

Why Southern California Edison Employees Work with a Specialist Financial Advisor

Throughout the year, Southern California Edison provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) with a company match and a pension plan and, for executives, deferred compensation — along with retiree medical benefits for many long-tenured employees. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with Southern California Edison who specialize in helping Southern California Edison employees make the most of their income and benefits.

Southern California Edison, a subsidiary of Edison International, is headquartered in Rosemead, California, in the San Gabriel Valley east of Los Angeles, and serves customers across a 50,000-square-mile area of central, coastal, and Southern California. Whether you work at one of those sites, another office, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.

Sensitive topics — like the steps you should take before quitting your job at Southern California Edison to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.

Should You Hire a Southern California Edison Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Southern California Edison employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with Southern California Edison employees is the better fit for your unique needs.

💡 In the Q&A below, you’ll gain insights from financial advisors who work with Southern California Edison employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.

🙋‍♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.

Q&A: Financial Planning Tips for Southern California Edison Employees & Executives

In this section, you’ll learn how you can make the most of your Southern California Edison employee benefits and gain valuable tips from financial advisors who specialize in working with Southern California Edison employees and executives.

Financial Advisor Q&A  ·  Southern California Edison Employees

James Selu, CFP®, CEPA®, CBDA, Financial Advisor for Southern California Edison Employees at Palm Coast Wealth Management

James Selu, CFP®, CEPA®, CBDA

Palm Coast Wealth Management  ·  Westlake Village, CA  ·  Serves clients nationwide

Maximize Your Financial Potential
Book Intro Call

James Selu is a financial advisor based in Westlake Village, California who specializes in offering financial planning services to Southern California Edison employees. James helps his clients get the most value from their Southern California Edison benefits and compensation package so they can enjoy life and feel confident about their financial future.

QAs a financial advisor with experience helping Southern California Edison employees save for their retirement, how do you help them make the most of their employee benefits?

I’ve worked closely with employees from Southern California Edison, and one of the biggest opportunities I see is helping them fully capitalize on a benefits package that’s stronger than most—especially when it’s coordinated properly. That includes maximizing the 401(k) match and catch-up contributions, but more importantly, aligning those savings with your pension and overall retirement income plan. The goal isn’t just to participate in the benefits—it’s to make sure each piece is working together in the most efficient way possible.

Where I spend a significant amount of time with clients is around the pension decision. This is one of the most important financial choices you’ll make, and it’s also one of the few that is truly irrevocable—you typically only get one opportunity to elect your option, and once it’s set, there’s no going back. We walk through all of the available payout options, survivor elections, and trade-offs in detail, and then model how each choice impacts your long-term income, taxes, and your spouse or family. It’s not just about picking the highest payment—it’s about choosing the option that best supports your overall financial plan.

Beyond that, I help clients build a clear withdrawal and tax strategy across their 401(k), pension income, Social Security, and brokerage accounts so that everything works together efficiently over time. If you’re looking for guidance on how to make the most of your benefits and want to be confident you’re making the right decisions—especially around your pension—I’d be glad to help you think through your options.

QWhen you first speak with a Southern California Edison employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?

When I first speak with someone from Southern California Edison, my goal is to quickly understand how all the moving pieces of their financial life fit together especially their benefits, which tend to be more complex than most. I usually start with a few key areas: where they are in their career or retirement timeline, what their expected pension looks like (including any estimates they’ve received), how they’re currently using their 401(k), and what other assets they’ve built outside of the company plan. Just as important, I want to understand their goals—what retirement actually looks like for them and any concerns they have, whether that’s market risk, taxes, or making sure a spouse or their family is protected.

QIs there a particular benefit available to Southern California Edison employees you feel isn’t as well utilized or understood by employees as it should be?

One of the most valuable and often misunderstood benefits for employees at Southern California Edison is the company pension. Many employees know it’s there, but don’t fully realize how significant the decision is when it comes time to elect their payout option. This is typically a one-time, irrevocable choice, with multiple options that impact not only your lifetime income, but also how (or if) that income continues to a spouse. The difference between options can be substantial over time, especially when factoring in taxes, life expectancy, and overall portfolio strategy. Taking the time to fully understand and model each option—rather than defaulting to what seems simplest can make a meaningful difference in long-term financial security.

QBeyond Southern California Edison employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?

Beyond the core retirement benefits, there are a couple of areas at Southern California Edison that I find especially valuable to spend time on with clients—primarily the 401(k) and retiree medical benefits, because both can have a meaningful impact on long-term outcomes if handled correctly.

With the 401(k), it’s not just about contributing and getting the match—it’s about optimizing it. I help clients evaluate whether pre-tax or Roth contributions make more sense based on their current income and future tax expectations, ensure they’re taking full advantage of catch-up contributions, and align their investment allocation with how their pension already provides a fixed-income base. When coordinated properly, the 401(k) becomes a powerful complement to the pension rather than just a standalone account.

For more tenured employees, retiree medical benefits are another major planning opportunity that’s often overlooked. Understanding what coverage continues into retirement, how it bridges to Medicare, and what costs to expect can significantly impact when someone retires and how much income they need. I work with clients to factor these benefits into their broader plan so there are no surprises especially around healthcare, which is one of the largest and most uncertain expenses in retirement.

QFor Southern California Edison employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?

For employees at Southern California Edison who are considering leaving for another opportunity, the most important step before making any decision is to fully understand the impact on their pension. In many cases, the pension is one of the most valuable benefits they have, and leaving even a few years early can significantly reduce the lifetime income it provides. I strongly encourage employees to request a current pension estimate and, ideally, compare it to projections if they were to stay an additional 1–3 years. It’s not uncommon to see a meaningful increase in monthly income just by extending employment slightly, especially as you approach key milestones in the benefit formula.

Beyond the pension, it’s also important to review your 401(k), any deferred compensation, and healthcare benefits before resigning. Understanding what you’re giving up and how it fits into your overall plan helps ensure you’re making a fully informed decision, not just a career-driven one. I often walk clients through a side-by-side comparison so they can clearly see the trade-offs, including how replacing that pension income would impact their long-term financial picture.

QFor Southern California Edison employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?

For employees at Southern California Edison approaching retirement, the transition from a steady paycheck to drawing from multiple income sources is one of the most important financial shifts you’ll make. The best way to prepare is to work with a financial planner who can walk you through each step helping you clearly understand your options and how all the pieces fit together. This includes evaluating your pension election, coordinating withdrawals from your 401(k), deciding when to take Social Security, and building a plan that replaces your paycheck in a reliable and tax-efficient way.

A good plan doesn’t just focus on income it prepares you for the decisions behind that income. That means understanding how different choices impact your spouse, your taxes over time, healthcare costs, and how your investments are structured once you’re no longer contributing. Having a clear, well-thought-out strategy in place before you retire allows you to move forward with confidence, knowing you’ve explored your options and are making informed decisions every step of the way.

QFor Southern California Edison employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?

For employees at Southern California Edison who have managed things on their own, I’d say the most important thing to consider is the growing complexity of the decisions in front of you especially around your pension, 401(k), taxes, and retirement income. Many of these decisions are interconnected, and some—like your pension election are permanent. Even if you’ve done a great job saving and investing, having a second set of experienced eyes can help you avoid costly mistakes and identify opportunities you may not have considered.

In my view, there’s no “perfect” time to start today is always the right time. The right advice can have a lasting impact, whether you’re years away from retirement or right on the doorstep. It’s not about giving up control it’s about gaining clarity, confidence, and a well-thought-out strategy so you can make informed decisions and fully understand your options moving forward.

QWhat are some of the unique financial planning challenges you commonly see among your clients who are Southern California Edison employees and how do you help them overcome these obstacles?

One of the most common challenges I see with employees at Southern California Edison is navigating the pension decision, because it’s both highly valuable and permanently binding. Many employees underestimate how impactful this one choice can be not just on their lifetime income, but on their spouse’s security, tax situation, and overall retirement strategy. Since the election is irrevocable, the risk isn’t just making a “suboptimal” choice it’s locking in a decision that can’t be corrected later. I help clients work through this by carefully modeling each option, walking through the trade-offs in plain terms, and aligning the decision with their broader financial plan so they can move forward with confidence knowing they got it right.

QWhat questions do you recommend Southern California Edison employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?

When evaluating a financial advisor, especially as an employee of Southern California Edison, it’s important to ask questions that help you understand whether they are truly acting in your best interest and have the experience to guide you through complex decisions like your pension. Here are some key questions I recommend:

  • Are you a fiduciary at all times, and will you put that in writing?
  • How are you compensated—fee-only, commission-based, or a combination?
  • What are all the fees I will pay, both directly and indirectly?
  • Do you have any conflicts of interest I should be aware of?
  • What services are included in our relationship (investment management, tax planning, retirement planning, etc.)?
  • How do you help clients make pension decisions, and have you worked with others in situations similar to mine?
  • Can you walk me through your process for building a retirement income plan?
  • How do you coordinate tax strategies with investment and withdrawal decisions?
  • What does ongoing communication look like how often will we meet and review my plan?
  • What credentials, experience, or background do you have that are relevant to my situation?
  • How do you tailor advice for someone with my level of assets and stage of life?
  • Can you provide an example of how you’ve helped a client avoid a costly mistake or improve their outcome?

These questions help you understand not just what an advisor does, but how they think, how they’re incentivized, and whether their experience aligns with the decisions you’re facing.

QIs there anything that comes up frequently in your initial meeting with Southern California Edison employees that surprises you?

One thing that consistently stands out to me when meeting employees from Southern California Edison is the strong work ethic and genuine pride they take in what they do. They tend to be thoughtful, responsible, and focused on doing the right thing for their families. It’s always a positive experience working with individuals who have been so consistent and disciplined in building their financial lives.

QFor highly compensated Southern California Edison employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

For highly compensated employees and executives at Southern California Edison, deferred compensation plans are one of the most important and often misunderstood benefits to get right. These plans can be a powerful tax planning tool, allowing you to defer income during your highest earning years and potentially recognize it later when you’re in a lower tax bracket. However, the elections you make when to defer, how much, and how distributions are structured are critical, as the wrong setup can lead to large, concentrated taxable income in future years.

At the same time, deferred comp comes with a unique risk that many overlook: those assets are not held in your name and are subject to the financial strength of the company. In other words, it’s not the same as a 401(k) there is employer risk involved. Because of this, the planning becomes a balance between tax efficiency and risk management. I work with clients to structure their elections thoughtfully, diversify their overall exposure, and ensure deferred comp is integrated properly alongside their pension, 401(k), and broader financial plan so it enhances not complicates their long-term strategy.

QIs there a particularly memorable experience or a moment you recall with a client who worked at Southern California Edison when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?

One moment that really stands out to me was working with an employee from Southern California Edison who came in assuming they needed to work several more years or weren’t sure they could retire at all. After walking through their full picture the pension, 401(k), and overall benefits it became clear they were already in a position to retire comfortably. You could see the shift immediately, from uncertainty to relief, as they realized how strong their benefits really were and how well they had been taken care of.

Those are some of the most rewarding conversations, helping someone see that they can confidently step into the next chapter of life. I often tell clients retirement is the longest vacation they’ll ever take and being able to help them get there sooner than expected, with clarity and confidence, is a pretty special part of what I get to do.

Considering a financial advisor who specializes in working with Southern California Edison Employees?

Are you a financial advisor who specializes in working with employees at Southern California Edison or another large company?

✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at Southern California Edison or another large company. (Subject to availability and terms.)
✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender

Ask a Financial Advisor Your Southern California Edison Benefits & Career Questions


Are you ready to enjoy life more with less money stress?

Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.
  • This field is for validation purposes and should be left unchanged.

About the Author

Brian Thorp, Founder and CEO of Wealthtender and Editor-in-Chief

Brian Thorp

Founder & CEO, Wealthtender  ·  Editor-in-Chief

Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.

A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.

Brian and his wife live in Austin, Texas.

Read Brian’s full bio →   ·   Connect on LinkedIn →

If you’re asking whether hiring a financial advisor is worth it, you’re probably closer to the decision than you think.

I came late to this question. I took the DIY (Do It Yourself) route for decades. It worked.

I reached “work optional” status and, three months ago, mostly retired.

Then, as a sanity check, I hired a financial advisor to review my plan.

And that’s when it hit me: Did I miss out on a lot by not working with a financial advisor earlier?

Key Takeaways – Are Financial Advisors Truly Worth It?

1

The real cost of DIY isn’t the fee you pay — it’s the value you may be leaving behind.

Most DIY investors compare an advisor’s 1% AUM fee against the near-zero cost of managing their own portfolio. But that framing misses the less visible costs: suboptimal tax decisions, behavioral mistakes during market downturns, missed planning opportunities, and the compounding impact of small inefficiencies over decades.

2

Research shows advisor value goes well beyond investment returns.

According to Vanguard, working with a financial advisor can add an estimated 3% to annual returns — but clients report the most meaningful benefits come from peace of mind, better decision-making, and time saved. In fact, 76% of advised clients reported saving a median of more than 100 hours per year managing their finances.

3

The right question isn’t “do I need an advisor?” — it’s “would I do better with one?”

DIY investing can be a smart, legitimate approach — especially if your finances are straightforward and you’re disciplined. But for those approaching major financial events, managing growing complexity, or simply wanting to optimize rather than settle for “good enough,” a skilled advisor can deliver value that compounds just as powerfully as the returns they help protect.

Why DIY Investing Isn’t Enough on Its Own

Anyone can invest. That’s the easy part now.

With a few clicks, you can:

  • Open a brokerage account.
  • Invest in low-cost index Exchange-Traded Funds (ETFs).
  • Build broad diversification at minimal cost.
  • Automate contributions. 
  • Rebalance periodically.
  • Let time do the heavy lifting.

So, it’s a fair question.

If it’s simple enough to do with a few clicks every few months, is paying for a financial advisor’s help worth the cost?

Understandably, most people look at the prevalent 1% of assets under management (AUM) annual fee and think it sounds like a lot, especially compared to what feels like a near-zero-cost DIY approach.

And sometimes it is.

But framing it like that misses a more interesting and important question: What might it cost you to keep going without an advisor?

Because it isn’t simply 1% of, e.g., a $1 million portfolio, i.e., $10k a year vs. no cost for DIY.

It’s that 1% vs. several less obvious costs:

  • Missing opportunities to improve returns or reduce risk.
  • Making costly behavioral mistakes, like panic-selling at the worst time.
  • Leaving tax savings and planning opportunities untapped.
  • Making suboptimal decisions because you’re operating without coordinated expertise.

This is where I am now. Sure, I’ve been very successful by almost any metric. But how much more successful might I have been had I hired a great advisor 10 or even 15 years ago?

Not because what I did was wrong, but because it may not have been optimal.

Should You Hire a Financial Advisor? Here’s a Quick Answer

At the most basic level, here’s who’d be more likely to benefit by working with a financial advisor and who wouldn’t.

You’d be more likely to benefit from professional advice if:

  • Your financial life is becoming more complicated.
  • You’re not completely confident you’re optimizing what you’ve built.
  • You’d rather not spend the time managing every detail yourself.
  • You want a second set of eyes to help you avoid mistakes.
  • You want more than “fine.” You want “optimal.”

DIY may be your better bet if:

  • Your finances are relatively simple.
  • You follow a disciplined, low-cost approach.
  • You’re comfortable making and sticking to long-term decisions.
  • You prefer to go with “simple, inexpensive, and fine” over “optimal.”
  • You enjoy managing your money and staying on top of it.

Most people who consider hiring an advisor find themselves somewhere in between.

If that’s you, ask yourself which sounds closer to your situation. And keep in mind that your answer may very well change over time.

That’s why, in this article, instead of considering if you need an advisor, we’ll dig into whether working with an advisor could help you do better, not just financially, but in how you use your time and make decisions.

What Does Research Say About the Value of a Financial Advisor?

The headline number is eye-popping.

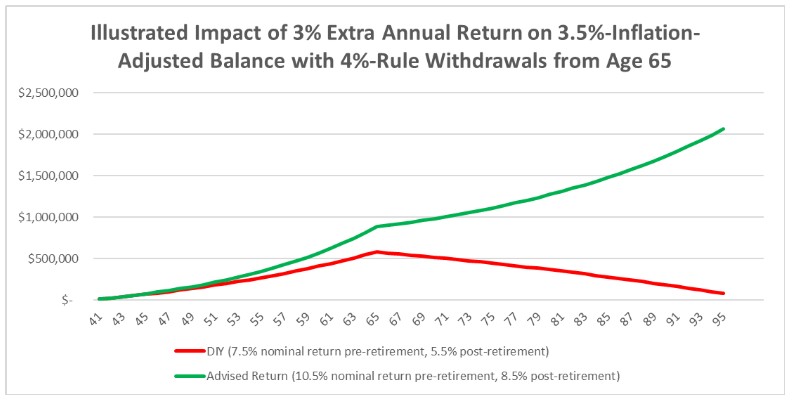
According to Vanguard, advisors add an estimated 3% to their clients’ annual returns. Figure 1 uses that 3% number to illustrate the possible impact of such an excess return over an investment lifetime, with the DIYer reaching the end of Year 30 of retirement with an $81k inflation-adjusted balance and the advised investor reaching a $2.1 million inflation-adjusted balance at that point (an example scenario, not a guaranteed result).

Line graph showing the impact of a 3% extra annual return on a retirement balance from age 65. The advised return line rises steeply, while the DIY return line grows slowly, illustrating the difference over time with 4% withdrawals.
Figure 1. Illustration of how 3% extra return can impact retirement account balances over an investment lifetime, including a 25-year accumulation phase and a 30-year retirement. Assumptions are: 3.5% annual inflation, 4.5% annual income increase, 15% annual savings, 7.5% annual DIY returns before retirement, 5.5% post-retirement return, and 3% higher annual return with a financial advisor in both pre- and post-retirement.

It’s important to note that the above number, as widely quoted as it is, is an estimate. Your actual results will be affected by, e.g., how well you respond to behavioral coaching, asset allocation advice, and cost-control recommendations.

A survey of Vanguard advisor clients reports that said clients attribute one-third of their three-year returns to their advisors’ help. Note that although this is client perception, not a measured increase in returns, it does highlight how those clients view the financial value of the advice they received.

But research suggests that the value of advice comes less from outperforming markets and more from improving behavior, tax efficiency, and decision-making.

A recent Vanguard paper, The emotional and time value of advice, says the focus “often overlooks other important benefits that investors gain from paid professional financial advice, such as peace of mind and the time they save by delegating their financial lives to an advisor,” and offers the following more complete list of benefits:

  • “Portfolio: Maximizing risk-adjusted after-tax wealth.
  • “Emotional: Providing financial peace of mind. 
  • “Financial: Maximizing the ability to achieve life objectives.
  • “Time: Reducing time spent thinking about and dealing with financial matters.”

Vanguard’s research found that 86% of advised clients reported experiencing the above emotional benefit (88% of clients advised by a human), and 76% reported experiencing the above time benefit, reporting a median annual time saving of over 100 hours thinking about and dealing with their finances (78% of clients advised by a human).

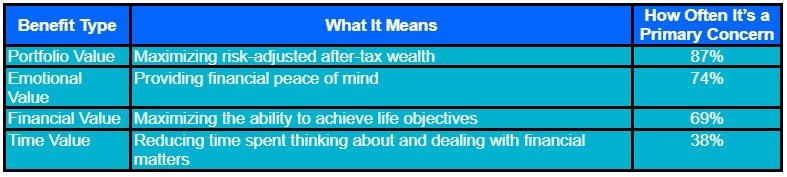
When asked for their primary reasons for seeking out advice, Vanguard found the following (Table 1):

  • Portfolio value: 87%.
  • Emotional value: 74%. 
  • Financial value: 69%.
  • Time value: 38%.

Thus, it’s clear that the emotional and time benefits were experienced even by clients for whom these weren’t the primary motivation for seeking advice.

A table shows four benefit types—Portfolio Value (87%), Emotional Value (74%), Financial Value (69%), and Time Value (38%)—with definitions and the percentage each is a primary financial concern.
Table 1. Benefits of financial advice and how often they’re considered of primary concern by advisory clients.

Another Vanguard paper, Assessing the value of advice, found that clients who rated their advisory service most highly ascribed 45% of the value they received to the emotional value of the service.

In plain English, this means a good advisor offers far more value to clients, including helping you make better decisions, reducing your financial stress, saving you time, and improving coordination across the full breadth of your financial picture.

This doesn’t mean that every advisor will be a good fit for you (or a good advisor, period), nor that you personally need an advisor.

What it does mean is that when considering whether or not you’d benefit from hiring a good advisor, you need to think more broadly than simply about improving your investment returns.

What Most DIY Investors Get Wrong About Financial Advice

The value of financial advice is not primarily about investment selection. It’s about improving decisions, coordinating complex financial choices, and reducing costly mistakes over time. 

Research can, and does, tell you what value a good advisor can provide, and how widely that’s valued by clients.

What it misses is how and why a good advisor can provide that benefit in ways that exceed what DIY investors achieve.

And that’s why most people underestimate the difference.

Having helped clients as a coach in the past, I came across an interesting saying, “You can’t read the label if you’re inside the jar.”

Whether a coach or an advisor, that’s a big part of how and why you can help people who are already knowledgeable. It’s the outside perspective, unclouded by an emotional attachment to the result.

Said more plainly:

  • You often don’t know what you don’t know, so you can’t see your own blind spots. This is why a second set of eyes is crucial, especially when making important decisions. As Ben Simerly, Financial Advisor and Founder of Lakehouse Family Wealth, says, “Anyone can save some money and pick a fund. Whether or not an account is being managed to a far better outcome is a matter of time, learning, expertise, and knowing what you don’t know.”
  • When the results affect your future well-being and that of your loved ones, it’s hard to stay objective and unemotional. That makes it hard to stay the course during tough times.

This is why even experts don’t go it alone, often hiring other experts to help them with their own finances.

Simerly speaks to this, “As the maxim goes, ‘For he who will be his own Counsellour, shall be sure to have a Fool for his Client.’ This is true for lawyers, as it’s often understood, but is more broadly true when seen as giving oneself counsel in general. In reality, even professionals are blind to a wide array of areas, including their own biases, failures, and limits of their genuine expertise. The best doctors have their own doctors. The best lawyers have their own lawyers. And the best advisors have their own advisors.

“Even the best Olympic runners, possibly the most ‘solo’ sport ever, never try to be their own running coach, too. Even I, as a pro, still learn new things every day. So, how is an amateur supposed to keep up with that learning curve? Beyond that, how many DIYers have been on hundreds of calls with 401(k) companies and/or read hundreds of investment prospectuses that include advisor-only details without being an advisor? What’s given to the general public is different than what’s offered behind the licensure wall.”

Even ignoring the above (which you shouldn’t), there’s an even bigger difference.

As a DIYer, you can keep researching, learning, and implementing what you learn. However, you’re working with a sample of one – your own situation. And any statistician will tell you that a small sample, especially a sample of one, makes for poor predictive value.

A good advisor, however, brings to the table:

  • Experience and learning from multiple client situations.
  • Coordination across taxes, investments, retirement planning, and estate planning, using input from teams of specialists and professional-grade software tools that you, as a DIYer, can’t easily match, no matter how smart or knowledgeable you are.

Good Enough vs. Optimal: What Financial Advice Can Actually Do for You

If you’ve reached a seven-figure net worth, you’ve already proven you can do well on your own.

You’ve met, and in a very real sense, exceeded “the standard.”

You’re unlikely to make a catastrophic mistake.

However, you probably do make lots of less-than-optimal decisions (or fail to make optimal ones). As a result, you’re probably:

  • Paying somewhat higher taxes than the minimum you must legally pay.
  • Making retirement income withdrawals from different account types in a somewhat less-than-optimal order.
  • Allocating your investments in a way that will likely result in a somewhat lower long-term, risk-adjusted return, and making some fear- and/or greed-driven decisions.

None of these has a large enough impact to be immediately noticeable, and some years it may not even show up much, if at all. 

However, combined and running over years and decades, they will likely have a material impact on your financial and emotional results. 

The challenge is that you won’t see it happening while it’s happening.

This is why assessing the value of hiring a good financial advisor vs. DIY is so hard. The short-term impacts don’t jump right out at you. The massive impact only shows up after years, when you’ve already left a great deal of value on the table without noticing.

That’s why the core question isn’t if you can do this yourself.

You can. You’ve proven that already.

The core question is whether hiring a good advisor would let you do even better, with less stress and a smaller time commitment (Table 2).

A table compares DIY reality and the impact of a good advisor across five value sources: behavior, taxes, blind spots, coordination, and time/cognitive load, highlighting the benefits of a good advisor in each area.
Table 2. Where advisor value typically shows up vs. DIY.

That last entry in Table 2 is especially underappreciated by most DIYers.

You don’t have infinite time, so the time you spend managing your family’s finances comes at the expense of time you have available for other priorities, such as spending time with your family, on your wellness, and on your career.

Will you get a better financial, physical, and emotional return on time invested in managing your finances, or delegating that to an advisor and spending the freed-up time with your spouse and family, staying fit and healthy, and developing your career?

So, how much time are you willing to dedicate to your finances at the expense of those other priorities?

Plus, as an individual, you can’t compete with the time spent by teams of professionals who each spend dozens of hours each week working on multiple clients’ financial lives and learning from that and from continuing education training.

Having said all that, Simerly cautions that not all those who list themselves as “financial advisors” are experts in managing clients’ overall finances. “So many ‘financial advisors’ are forced to list themselves as ‘financial service professionals,’ but are actually insurance agents by profession. They don’t have years of experience managing wealth and investments, tax planning expertise, or working with a team that is 30 years their senior. As a result, they deliver advice that is as simplistic and scripted as the firm behind them can possibly make it. At that level of service, it’s no wonder hiring an advisor is questioned. The outcome may not be much different than doing it yourself.”

When Hiring a Financial Advisor Is Worth It

Here are things that are typically true for those who’d get the most benefit from hiring an advisor.

  • Your financial life is becoming more complicated.
  • You’re making decisions with long-term consequences (retirement timing, Social Security claiming timing, withdrawal strategy, tax strategy, estate planning, etc.).
  • You’re looking for optimal results rather than “good enough.” 
  • You find yourself second-guessing important decisions.
  • You’d rather focus your time on other priorities, such as family, wellness, and career.

When Managing Your Own Finances Is the Right Call

Here are things typically true for those who can likely stay DIYers without losing too much.

  • Your financial situation is relatively straightforward.
  • You follow a disciplined, low-cost investment strategy and can stick with it through market crashes.
  • You’re comfortable making and sticking to long-term decisions and don’t keep second-guessing yourself and stressing over things.
  • You’re willing and able to invest enough time to stay informed.
  • You’re fine with a “good enough” outcome.

That last point is especially important because if that describes how you feel, DIY is most likely good enough for you, and paying for advice isn’t crucial.

The Real Cost of Not Hiring a Financial Advisor

By contrasting these two lists, you can see that the core question isn’t whether or not you can stick with DIY.

It’s the tradeoff between the things you’re trying to optimize for. If you’re looking for a combination of the following, a good financial advisor can be of great value.

  • Optimal financial outcome.
  • Reduced time and emotional and cognitive load.
  • Greatest simplicity and acceptable cost.

The real tradeoff isn’t cost vs. no cost. It’s visible fees vs. less visible inefficiencies. And those inefficiencies compound over time.

How to Decide If You Need a Financial Advisor: A 3-Question Framework

If you’re still on the fence about hiring a financial advisor, use this simple approach. Ask yourself:

  • Am I confident that my decisions are good enough for my goals, even during market crashes, and comfortable taking responsibility for the outcome?
  • Would my outcome benefit from a review by a second, expert, objective set of eyes?
  • Can I (and do I want to) spend the necessary time on educating myself and otherwise managing our finances, or would I rather delegate it so that I can focus on my other life priorities (family, wellness, career, etc.)?

Your answer to these three questions will tell you more than any theoretical headline number or example outcome graph ever could.

So far, we’ve looked at what research says. Now let’s look at what this actually looks like in real life.

Common Financial Mistakes Advisors Help Clients Avoid

I asked several professional financial advisors to share the biggest mistakes they’ve seen clients make, or helped clients avoid. Here’s what they shared.

Kevin Newbert, Financial Advisor of Ausperity Private Wealth, shares five such mistakes:

  • “Selling equity too late or too concentrated: executives who held too long because they believed in the company and watched a $3M position erode to $800k. We build systematic diversification tied to tax efficiency, not emotion. 
  • “Entering a business sale without pre-sale planning: one of the most expensive mistakes I see. Qualified Small Business Stock (QSBS), 83(b) elections, charitable structures, installment arrangements, trust planning… these only work before the deal closes. A client who came to us after the Letter of Intent (LOI) had already eliminated most of their options. 
  • “Underestimating the tax hit on a liquidity event: a business owner expected to net $6M on an $8M sale. Proper pre-close structuring could have saved over $700K. The plan wasn’t in place. Most of it was avoidable. 
  • “Spending drift after a liquidity event: clients moving from high W2 or K-1 income to living off a lump sum often overspend during the first few years. We build a capital sufficiency model early so there’s a clear, defensible number rather than a guess. 
  • “Leaving rollover equity unanalyzed: Private-Equity-backed founders often accept rollover terms without stress-testing the concentration risk or understanding how it fits the broader plan. We model it before they sign.”

The takeaway here is that many of the most expensive mistakes happen before major financial events, when planning opportunities still exist.

Cole Williams, CFP®, CIMA®, BFA™, Founder of Vessel Financial Planning, shares two somewhat counterintuitive instances:

  • “A common mistake I help clients avoid isn’t reckless spending, but the opposite. Many of the people I work with save well and started early, but they’re overdoing it in retirement accounts while putting on hold real goals such as family vacations, a home purchase, a car, and the kids’ education.” 
  • “One client came to me focused on the numbers. But early in our work together, she and her husband each completed a values exercise independently. Meaningful work, community, and diversity showed up in her top five. Her then-current job didn’t align with any of those, and she suspected it. She left. From a planning standpoint, I recommended temporarily reducing her husband’s 401(k) contributions to improve their cash flow and redirect savings into non-qualified accounts. That gave her a full year of runway to be selective. She passed on roles that offered competitive salaries but not the influence or impact she was looking for. When she landed the right job, she described it as beyond organizational leadership. It made a meaningful difference, and she was excited to wake up in the morning. You can’t show that in a portfolio report, but it’s what the planning work is there to do.”

Here, the takeaway is that a good advisor can help clients achieve better life outcomes that they value highly.

Dr. Steven Crane, Founder of Financial Legacy Builders, says:

  • “Some of the biggest mistakes I’ve helped people avoid are actually pretty simple. Cashing out retirement accounts too early, taking on unnecessary debt, or making major financial decisions without understanding the long-term consequences. I’ve seen people unknowingly cost themselves six figures over time just from a few poorly timed moves. In those cases, the value of advice isn’t theoretical; it’s immediate.”

Takeaway: When you’re wealthy, it’s easy to make mistakes that can cost six-figure sums. A good advisor helps you recognize the pitfalls and avoid them.

Uziel Gomez, CFP®, founder of Primeros Financial, shares:

  • “Clients have come to me with their emergency fund sitting in a savings account that wasn’t earning any interest. That money could have been working for them in a high-yield savings account or a CD.
  • “I also work with many recent graduates whose income has recently increased. With that shift, some were under-withholding without realizing it, which could lead to an unexpected tax bill when they file their taxes.”

The takeaway here is that many people can make mistakes that are simple and easy to fix, but only if they’re aware of them.

Simerly says:

  • “I’ve never worked a case where someone handling their finances for themselves hadn’t missed significant savings, increased returns, or pitfalls. Not once. And that includes my time as a newbie when I knew less than the proverbial doorknob. A second set of eyes can be worth the world.”

What Financial Advisors Say Is the Greatest Value They Provide

Next, I asked the advisors what they see as the greatest value they bring, and who would not benefit from it.

Newbert says, “My practice is built around one idea: income alone is not a financial plan. The clients I work with, from private-equity-backed founders navigating a liquidity event, to business owners approaching an exit, to equity-compensated executives in tech, healthcare, and consumer packaged goods, have built real wealth through hard work. But complexity scales with success, and most of them make high-stakes financial decisions without a coordinated strategy. 

“What I bring is integration. Tax planning, equity comp strategy, investment architecture, and long-term cash flow modeling, working together, not in silos. I act as a personal CFO, helping clients answer the two questions that matter most at this level: ‘what can I actually spend?’ and ‘how do I make this last?’ 

“This provides the most benefit for clients who built their wealth through ownership, equity, or entrepreneurship, and are ready to stop winging it. Usually, they have $250K+ in income, with real complexity on the horizon: an equity award, a business exit, a liquidity event, or concentrated risk they haven’t addressed. They’re engaged, they care about family and legacy, and they understand that every dollar of planning at this level has measurable ROI. For the right client, the return on advice is often 10–50× the fee.

“On the other hand, the value isn’t compelling if you have a simple balance sheet, stable W-2 income, and no major financial decisions in sight.”

Williams offers, “The value I bring clients starts with something most financial conversations skip: what actually matters to them. Clients tell me they feel heard for the first time when talking about money. That often translates into allowing them to spend on experiences and comforts that align with their values right now, not just someday. 

“Clients get the most out of working with me when they’re honest about what they want, including with each other. Many work in medicine or hospitality, where thinking about themselves can feel uncomfortable. But when they’re willing to look at that honestly, the results are real: mortgages paid off ahead of schedule, vacation homes that stop feeling like pipe dreams, retirements entered into confidently, and kids graduating without crippling debt. These outcomes make for more meaningful conversations than anything on a performance report. 

“I’m also honest with clients who aren’t ready to make changes. Working with me won’t have the same return on investment for them, and I tell them that directly.”

Dan O’Rourke, Director of Multifamily Office Solutions, Strathmore Capital Advisors, says, “For wealthy investors, good advice is often less about generating more return and more about preventing expensive, avoidable mistakes. Many self-directed investors do a great job building wealth, but the transition from accumulation to turning assets into reliable, after-tax income is where advice often becomes most valuable. Things like taxes, withdrawal strategy, asset location, estate planning, and behavior during volatile markets can matter more than picking the next great investment.”

Crane agrees, “The biggest value I bring isn’t picking better investments. It’s helping people make better decisions. Most financial damage doesn’t come from markets; it comes from behavior. I’ve had clients who were ready to pull out of the market during downturns, make emotional decisions with large sums of money, or completely mismanage taxes. Stopping one bad decision can be worth far more than any fee they’ll ever pay. 

“The people who get the most value from an advisor are the ones who want clarity and accountability. They don’t need someone to impress them; they need someone to help them stay on track and make consistently smart decisions. 

“The people who get the least value are usually those who are already disciplined, keep things simple, and don’t overreact. They can do just fine on their own. Where I think the industry gets it wrong is how fees are structured. A portfolio doesn’t suddenly become five times more complex just because it’s five times larger. At some point, people should be asking whether they’re paying for real advice or just paying more because they have more.”

Jakub Kubrak, CEO and Founder of Kubrak Wealth Advisors, has a slightly different take on fees. He says, “Fees are only an issue in the absence of value, and during volatility is where advisors bring the most value. A good advisor will bring good market interpretation and discipline to help clients reach their goals. Most investors fail at reaching their goals because they aren’t good at staying disciplined or interpreting markets.”

Gomez says, “Having someone clients can turn to as a sounding board to talk through opportunities and potential risks can make a big difference. It also helps to have someone who can provide accountability, explain how the financial system works, and build their confidence along the way. With step-by-step guidance, the process can feel clearer, more manageable, and empowering. 

“The clients I’ve seen make progress are usually the ones who are open to change and stay engaged in the process. I can walk through what may be in their best interest, but whether things get implemented often comes down to where they are in their readiness. I’ve worked with people who are dealing with debt and patterns of overspending, and many are aware that their current approach may not move things forward. At the same time, making the tradeoffs needed to shift those habits can feel difficult. That tension tends to be part of the process, and movement often starts once they feel more ready to take those steps.”

Key Findings: Is a Financial Advisor Worth It?

Across both research and real-world examples, a clear pattern emerges:

  • The biggest value of advice often comes from making the right decisions, not picking the best investments. 
  • Major financial events can give rise to costly mistakes, especially for the wealthy.
  • Small inefficiencies can compound into high, long-term costs. 
  • And much of this is hard to detect without an outside perspective, and most of the difference is hard to see while it’s happening.

Which brings us back to the key question: Would you do better with help?

Bottom Line: Is Hiring a Financial Advisor Worth the Cost?

So, are financial advisors truly worth hiring?

I can’t give you a definitive answer that’s true for you.

It depends, but not (just) on whether or not you can invest for yourself. Because if you’re at a 7-figure net worth, you probably can.

And many do, and it works out well enough for them.

Most investors don’t fail because they lack knowledge. They fall short because they miss small opportunities to optimize over long periods of time.

What it really depends on is whether you think you’d do better with professional help.

  • Have a better risk-adjusted return.
  • Make better decisions and lose less sleep over them.
  • Avoid mistakes that will compound to your detriment over time.
  • Spend more time on other priorities, such as family, wellness, and career.
  • Feel more confident and less anxious, especially during market turmoil.

For some, the answer will still be no, and that’s ok.

If your finances are simple, you’re disciplined and confident, and you’re ok with a “good enough” outcome, DIY can be your best bet.

But for others, and even for those DIYers at a later date, the answer may be that the value of a good advisor, in terms of finances, portfolio, emotion, and time, would be more than worth the cost.

Especially if you want an optimal, rather than “good enough,” outcome.

In my case, I didn’t hire an advisor because I failed, or because I couldn’t stay the DIY course.

I hired one because I wanted to make sure there wasn’t any “gotcha” that I didn’t know that I didn’t know. I wanted a professional, objective, second opinion.

Finally, I wanted to see if I could go from “good enough” to “optimal.”

Because ultimately, the question isn’t just ‘Is it worth the fee?’

It’s also “What’s the potential cost of missing something without knowing it?”

That last cost can often turn out to be higher than any of us expect.

Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

Opher Ganel

About the Author

Opher Ganel, Ph.D.

My career has had many unpredictable twists and turns. A MSc in theoretical physics, PhD in experimental high-energy physics, postdoc in particle detector R&D, research position in experimental cosmic-ray physics (including a couple of visits to Antarctica), a brief stint at a small engineering services company supporting NASA, followed by starting my own small consulting practice supporting NASA projects and programs. Along the way, I started other micro businesses and helped my wife start and grow her own Marriage and Family Therapy practice. Now, I use all these experiences to also offer financial strategy services to help independent professionals achieve their personal and business finance goals. Connect with me on my own site: OpherGanel.com and/or follow my Medium publication: medium.com/financial-strategy/.


Learn More About Opher

Annuities are often sold as “tax-advantaged,” but what do taxes actually look like when you’re in retirement? It’s important to understand the “wait now, pay later” nature of tax-deferred growth and annuity taxation. Retirement isn’t the time to get caught off guard by tax surprises.

The name of the game is keeping more of your retirement check and not overpaying Uncle Sam. The first step in maximizing your tax strategy is understanding what you have and how your investments are taxed. This is an essential part of a comprehensive financial plan to make the most of your retirement savings.

The “Where” Matters: Qualified vs. Non-Qualified Annuities

The first step to understanding how an annuity is taxed is deciphering what type of annuity you’re talking about. In other words, what tax “bucket” is your money in? Annuities are classified into two main categories for tax purposes: qualified and non-qualified.

Qualified Annuities (The Pre-Tax Bucket)

The term “qualified” simply means the annuity was funded with pre-tax dollars (such as an IRA or 401(k)). The catch? The money you pull out is taxed as ordinary income.

These annuities are either purchased inside your employer plan or funded with a rollover from a qualified (pre-tax) plan. In these instances, the IRS typically counts your cost basis (the amount you paid for the asset) as zero.

Non-Qualified Annuities (The After-Tax Bucket)

A non-qualified annuity is purchased with after-tax money. In other words, these are funded with money outside a qualified plan. In most cases, only the earnings are taxed when you withdraw them.

There are some overly complicated rules on exactly how to calculate the taxable portion of a non-qualified annuity. We’ll go over this in more depth below.

Ordinary Income vs. Capital Gains

Remember, annuity gains are taxed at your regular income rate, not the lower capital gains rate. This can be confusing because exclusion ratios and other annuity tax considerations depend on several distinct factors.

Bottom line, annuities don’t function like a regular investment asset. These are often extraordinarily complex, with sometimes circular language in the contracts themselves. Even seasoned professionals have difficulty decoding the legalese and the interplay among various riders and if/then rules.

How much do you really know about taxes? Take the tax literacy quiz to find out if you know the basics in less than 2 min.

Annuity Withdrawal Rules and Strategies

For a non-qualified annuity, there are specific rules based on how and when you choose to receive your money. In other words, a single lump-sum distribution or one-off withdrawal changes how the IRS views it. The “normal” way to receive annuity payouts is through regular, usually monthly, payments.

The Exclusion Ratio

If you “annuitize” and start receiving monthly distributions, each payment from the annuity is part return of principal (tax-free) and part earnings (taxed). This spreads the tax bill over your (theoretical) lifetime or the specific contract length. For a qualified annuity, your cost basis is generally considered $0 for tax purposes.

The IRS uses one of two established methods to determine how much of your annuity payment is taxable: The General Rule or the Simplified Method.

The General Rule

For most annuities, you’ll follow what’s called the general rule. In short, you’ll spread out the cost of the annuity over a certain period. This is based on your age and the chart in the Form 1040 instructions.

The specifics can be complex, but we’ll outline the “basic” process for calculating your exclusion ratio.

Step 1: Determine Net Cost

The first step is to determine your net cost in the annuity contract. This is based on your payments into the annuity contract adjusted for your age (life expectancy), any unpaid loans, or other special circumstances.

Step 2: Calculate Your Expected Return

Next, you’ll calculate the money you’re expected to receive from the annuity. This is what the IRS calls your expected return. Calculate the expected return using the normal monthly payment amount and the total number of payments.

This is also adjusted for your age and/or life expectancy. If you have a variable annuity, your actual returns may differ significantly. A fixed annuity will vary as well (check the contract for crediting rate calculations).

Step 3: Determine the Exclusion Ratio

Divide your net cost from step one by the expected return from step two. Round this number to the “nearest three decimal places,” which is the IRS’s confusing way of saying nearest tenth. If your exclusion ratio is 0.5174257425742574 (calculated using the IRS example), your actual percentage is 51.7%.

Step 4: Apply to First Regular Payment

Next, you’ll apply the exclusion ratio to your first regular periodic payment. For example, if your exclusion ratio is 40%, and your first payment of the year is $500, then $200 is a tax-free return of cost. Multiply that by 12, and your annual exclusion amount is $2,400.

Keep in mind, this is a simplified version of the general rule. There are other exceptions for the death of an annuitant and other factors. Your personal situation and annuity will be different.

Exceptions to the General Rule

If your annuity started after July 1, 1986, and before November 19, 1996, you could have chosen the Simplified Method or the General Rule. However, you can’t change your election. We’ll very briefly cover the simplified method.

Infographic explaining the annuity exclusion ratio, with four steps: determine net cost, expected return, calculate exclusion ratio, and apply it to first payment. Includes graphics and "NextGen Wealth" logo at the bottom.
Image Credit: NextGen Wealth

The Simplified Method

The simplified method is covered in IRS Publication 575. This is the method used for qualified annuities. There are still exceptions, and some non-qualified annuities might use the simplified method to determine exclusion amounts.

In short, the simplified method divides your total cost by the estimated number of payments listed at the bottom of the simplified method worksheet. The number of payments is determined using your age.

The last section of the simplified method form tracks your total recovered costs from the annuity.

Try your best at these 7 Questions to put your tax knowledge to the test! Will you get the questions about taxes right?

More Information on General Rule versus the Simplified Method

Refer to IRS Publication 939 for more information on whether your annuity is subject to the general rule or simplified method. It’s 85 pages of sleep-inducing specifics on annuity taxation.

Interestingly enough, you can actually pay to have the IRS calculate your exclusion ratio. The fee is $1,000 as of today. In return, you’d receive a “letter ruling” from the IRS explaining your exclusion ratio. The fact the IRS has this process should be a sign of how complicated annuity taxation can be.

This is why coordinating with your accountant can be so valuable. We highly recommend engaging a competent tax professional to ensure your taxes are prepared correctly.

Single Distributions and the “Earnings First” Rule

For random withdrawals, called “nonperiodic distributions” by the IRS, the IRS assumes you’re taking your gains out first. It’s “Last-In, First-Out,” meaning you pay taxes upfront before you get to your tax-free principal.

Also, the IRS doesn’t deduct your assumed cost (basis) for surrender charges. The surrender charges are all on you to cover. Regardless, it’s generally best to follow the contract rather than take distributions at random, though there are some exceptions for hardship.

The “Survivor” Rule

Another rule to keep in mind is how annuity taxation applies if you outlive your life expectancy. It eventually becomes 100% taxable. This is because your tax exclusion is limited to the total cost you paid for the annuity.

Once you’ve received the cost back, you can’t claim an exclusion. Everything you receive after your maximum exclusion is fully taxable as income.

Avoiding IRS Penalties

In addition to the other complex annuity taxation rules, you still need to be mindful of specific ages and dates. Just like other retirement accounts, there are rules for when you can withdraw funds penalty-free.

The 59½ Line in the Sand

Like other qualified accounts, withdrawals from qualified annuities before age 59½ are subject to the 10% early withdrawal penalty. If you need to withdraw funds for early retirement, you may want to explore alternative early retirement options.

There are several exceptions to the 10% early withdrawal tax as well.

Required Minimum Distributions (RMDs)

Similar to other traditional retirement accounts, annuities are subject to required minimum distributions. However, there are rules (and exceptions) for your required beginning date as well. Your required beginning date is usually age 73 or the year you retire.

Furthermore, SECURE 2.0 enhanced the ability to count certain annuity payments as a portion of your RMDs. If you have an annuity within a qualified account, such as an IRA, your annuity payments count toward the total RMD for the account it’s held in. Before SECURE 2.0, the RMD would have to be taken from other investments inside the account.

In theory, your calculated payments for your annuity will meet your RMD because they’re both based on life expectancy. It’s always best to check so you don’t get hit with the 25% excise tax for failing to take your RMD.

On the other hand, non-qualified annuities aren’t subject to RMDs.

Rules for 1035 Exchanges and Annuities

In some cases, it might be a good idea to swap an old annuity for a new one without triggering a massive tax bill. You can use a 1035 exchange to switch to a different annuity. However, you must be careful not to trigger surrender charges, lose your mortality credits, or lose out on unique features you may need.

How an Annuity Affects Your Heirs

As with everything else, annuities have unique rules when the owner passes away. The type of annuity is important as well. In general, you’ll apply annuity taxation as if you were the original owner of the annuity.

Annuities don’t get the same “step-up in basis” as stocks or a home. It can be messy to close an estate which has an annuity.

Spousal Continuity

For joint-life annuities, the surviving spouse will continue to receive payments based on the contract terms. In some cases, their payments may be reduced, so ensure you understand what’s specified in the contract. There are additional rules for applying the exclusion ratio in this case.

Can you ace this basic tax literacy quiz? See what you know & don’t know (& why it matters).

The Tax Bill for Non-Spouse Beneficiaries

The rules vary slightly depending on whether the original owner/annuitant had started receiving payments. In general, there is still a “return of basis” for the original cost of the contract.

If the annuity owner had started payments, the estate can deduct the portion of the estate tax attributable to the annuity. If the annuity payments had not begun, the death benefit would be treated as income, but the estate could still claim an estate tax deduction.

Annuities vs. Life Insurance

Although annuities are insurance products, they are taxed differently from the death benefits paid under a life insurance contract. Annuities are “tax-deferred,” but death benefit payments from life insurance are generally “tax-free” for the designated beneficiary.

Making Taxes Part of Your Retirement Strategy

As the saying goes, don’t let the tax “tail” wag the investment “dog,” but we don’t need to pay extra to the IRS either. Trust us, they’ll take what they’re owed. Don’t let taxes catch you by surprise.

Furthermore, make sure you understand the potential ongoing tax headaches you get with an annuity. It can get messy quickly, and the IRS doesn’t always care whether you understand everything before assessing a penalty.

Have a Plan

If you don’t already have a clear, written financial plan, you need one. Whether you think you have a complex situation or not, there’s a ton of value in having a game plan. This is especially important if you’re considering a complex financial product like an annuity.

This article was originally published here and is republished on Wealthtender with permission.

Headshot of Clint Haynes, CFP®
Clint Haynes, CFP® Helping you build a retirement with pleasure, purpose, and peace of mind.

Clint Haynes, CFP® | NextGen Wealth

Whether you have lived in Missoula for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.

It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Missoula featured on Wealthtender you may want to add to your shortlist.

As you prepare to interview financial advisors in Missoula who may be right for you, get to know local financial advisors featured on Wealthtender.

📍 Map: Financial Advisors with their Primary Office Location in Missoula

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Missoula.

📍Double-click or pinch pins to view more.

Showing

The Benefits of Hiring a Financial Advisor in Missoula

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Missoula, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Do you work for one of the largest employers in Missoula? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Quick Tips For Hiring an Missoula Financial Advisor

Before hiring a financial advisor in Missoula, here are a few quick tips to help you find the best advisor for you.

1. Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2. Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3. Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4. Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.


Frequently Asked Questions & Additional Resources

How do I know if I’m ready to hire a financial advisor?

You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.

But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.

Before I hire a new financial advisor, should I fire my current advisor?

You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.

Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?

After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. 

Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.

I’m a local financial advisor interested in being featured in this guide. How do I get started?

Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.

How Much Does a Financial Advisor Cost?

➡️ How Much Does a Financial Advisor Cost? Read the Article

About the Author
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian

Do you work at Dimensional Fund Advisors?

Get expert insights from financial advisors who specialize in helping Dimensional Fund Advisors employees and executives make the most of their compensation package and benefits.

Looking for a financial advisor who specializes in working with Dimensional Fund Advisors employees? You’re in the right place. Below, you’ll find advisors who understand Dimensional Fund Advisors benefits and compensation — along with their answers to common financial questions from Dimensional Fund Advisors employees and executives.

Whether you recently joined Dimensional Fund Advisors or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and Dimensional Fund Advisors benefits can have a lasting impact on your financial future. For example:

✅ Do you know the right moves to get the greatest value from the Dimensional Fund Advisors benefits available to you?

✅ If you’re thinking about leaving Dimensional Fund Advisors for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?

Key Takeaways

1

Contribute at Least 6% to Capture Dimensional’s 401(k) Match

Dimensional adds a meaningful match, and whether to contribute pre-tax or Roth can change year to year with cash flow and your household tax bracket.

2

Dimensional’s HSA Contribution Makes the High-Deductible Plan Worth a Close Look

As of 2026, Dimensional contributes $1,500 for individuals and $3,000 for families. Treating the HSA as a tax-free retirement account and investing it systematically can multiply the benefit.

3

Vested LTIP Phantom Units Stay Behind When You Leave Dimensional

Senior employees forfeit vested phantom units in the Long-term Incentive Plan if they leave, so use their value in negotiations with a new employer. Large bonuses also often need estimated tax payments.

Why Dimensional Fund Advisors Employees Work with a Specialist Financial Advisor

Throughout the year, Dimensional provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) with a match and a mega backdoor Roth option — along with an HSA contribution and, for senior employees, a Long-term Incentive Plan. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with Dimensional who specialize in helping Dimensional employees make the most of their income and benefits.

Dimensional Fund Advisors is headquartered in Austin, Texas, and has U.S. offices in Charlotte, North Carolina, and Santa Monica, California, along with offices around the world. Whether you work at one of those sites, another office, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.

Sensitive topics — like the steps you should take before quitting your job at Dimensional Fund Advisors to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.

Should You Hire a Dimensional Fund Advisors Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Dimensional Fund Advisors employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with Dimensional Fund Advisors employees is the better fit for your unique needs.

💡 In the Q&A below, you’ll gain insights from financial advisors who work with Dimensional Fund Advisors employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.

🙋‍♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.

Q&A: Financial Planning Tips for Dimensional Fund Advisors Employees & Executives

In this section, you’ll learn how you can make the most of your Dimensional Fund Advisors employee benefits and gain valuable tips from financial advisors who specialize in working with Dimensional Fund Advisors employees and executives.

Financial Advisor Q&A  ·  Dimensional Fund Advisors Employees

Kelly Klingaman, CFP®, RLP®, Financial Advisor for Dimensional Fund Advisors Employees at Kelly Klingaman Financial Planning

Kelly Klingaman, CFP®, RLP®

Kelly Klingaman Financial Planning  ·  Austin, TX  ·  Serves clients nationwide

Financial Planning for Professional Women & Their Families
Book Intro Call

Kelly Klingaman is a financial advisor based in Austin, Texas who specializes in offering financial planning services to employees of Dimensional Fund Advisors. Kelly helps her clients get the most value from their Dimensional benefits and compensation package so they can enjoy life and feel confident about their financial future.

QWhen you first speak with a Dimensional employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?

During our initial consultation, I’ll ask about your current financial situation and what specific events or topics have prompted you to reach out. I also want to explore your values and vision for living a great life. Why is money important to you? What is essential to living a great life? If we decide to work together, your “why” gives us a lens to look through when making future financial decisions.

QAre there a particular benefits available to Dimensional employees you feel aren’t as well utilized or understood by employees as they should be?

Dimensional provides a nice amount of free cash into your 401k as a match, so it’s important you’re contributing at least 6% of your salary to this retirement account. There’s a lot of confusion around whether to make pre-tax contributions or Roth contributions to your 401k, and this is highly dependent on other factors like your cash flow needs and your household marginal tax bracket. The truth is, there isn’t one static choice to make here – it could shift each year! I talk through these tradeoffs with each of my Dimensional employee clients on an annual basis to make sure they’re selecting the option that makes the most sense for short and long-term wants and needs.

Dimensional also offers two different medical plans, one being their HSA Health Plan, and I find that you might struggle to understand whether or not this high-deductible plan with a Health Savings Account is a sensible choice for your family. As of 2026, Dimensional gives a sizable amount of free cash into your Health Savings Account: $1500 for individuals and $3000 for families. I’ll help you understand the power of treating your HSA as a tax-free retirement account, and we create a system for investing the cash systematically and “paying yourself back” in the future for current medical expenses.

QBeyond Dimensional employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?

In recent years, Dimensional has added a four-week sabbatical every 10 years, and there is an enhancement to the Long-term Incentive Plan for senior level employees where they’ll give a 50% match on top of elective bonus contributions. There is also a new Key Contributor Program for top-performing employees who are not eligible for the LTIP yet. In this program, you can earn discretionary Key Contributor Awards (KCAs) at a minimum of $10,000 that pay out over three years.

QFor Dimensional employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?

For senior level Dimensional employees who have a good amount of vested Phantom Units in their Long-term Incentive Plan (LTIP), they need to understand that they would lose this financial benefit entirely if they leave the company – these shares don’t go with them. It’s important to understand the vested value and use that amount in negotiations with any potential new employer as part of their overall compensation package.

QFor Dimensional employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?

Dimensional employees have the unique advantage of working inside a company with strong ties to the independent financial advisor community, and the firm fosters a deep respect for the value of financial advice. Despite these ties, employees often feel like they’re supposed to know exactly how to DIY the management of their own personal finances because they work for a financial firm.

As Dimensional employees reach upper-level roles (Managers, Regional Directors, Vice Presidents), this is a good time to consider working with a professional. Maybe you lack the accountability and guidance to focus on your financial health amidst the demands of a successful career and busy home life. Or perhaps you’ve built a great foundation for wealth and you’re making a competitive salary, but what are you missing and how do you prioritize your financial to-do list?

There is also a big consideration for hiring an independent, unbiased professional to guide you and your spouse through all the household financial decisions, big and small. Perhaps you want to feel connected with your partner when it comes to money, especially around aligning how you use your financial resources to live your ideal lives.

QWhat are some of the unique financial planning challenges you commonly see among your clients who are Dimensional employees and how do you help them overcome these obstacles?

One of the unique challenges for Dimensional employees, especially those of you at a Regional Director or Vice President level, is the fact that a big portion of your total compensation comes in a semi-annual or annual bonus. This can be hard to manage in terms of balancing your cash flow across the entire year, plus you likely will get hit with unexpected tax consequences. These could be underpayment penalties and/or an unexpected large tax bill come April 15th because this supplemental income is taxed at a flat 22% tax rate. Oftentimes, your household tax bracket is much higher, so you end up owing additional tax money to the IRS. Realistically, it might even be necessary to make an estimated tax payment to avoid an underpayment penalty. Most W-2 employees have never made an estimated tax payment before, so the whole ordeal is confusing and complicated to manage.

QFor highly compensated Dimensional employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

For senior level Dimensional employees making $250K+ in total compensation, a percentage of your bonus is deferred into the Long-term Incentive Plan (LTIP) to purchase Phantom Units. Generally, the more you earn while working at Dimensional, the more your compensation is tied to the growth of the firm. It’s important from a financial planning perspective to manage this potential concentration risk where your human capital and a growing portion of your financial capital are both tied to the performance of the firm.

I also don’t see many highly compensated Dimensional employees taking advantage of their recent Mega-Backdoor Roth option inside the 401k plan. There are also many tradeoffs to consider with financial planning strategy to decide whether or not it makes sense to add more to the Roth/retirement bucket or to use extra cash flow in other ways.

Considering a financial advisor who specializes in working with Dimensional Fund Advisors Employees?

Are you a financial advisor who specializes in working with employees at Dimensional Fund Advisors or another large company?

✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at Dimensional Fund Advisors or another large company. (Subject to availability and terms.)
✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender

Ask a Financial Advisor Your Dimensional Fund Advisors Benefits & Career Questions


Are you ready to enjoy life more with less money stress?

Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.
  • This field is for validation purposes and should be left unchanged.

About the Author

Brian Thorp, Founder and CEO of Wealthtender and Editor-in-Chief

Brian Thorp

Founder & CEO, Wealthtender  ·  Editor-in-Chief

Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.

A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.

Brian and his wife live in Austin, Texas.
Read Brian’s full bio →   ·   Connect on LinkedIn →

Managing money as a couple is one of the most important things you can do for your relationship and your financial future. Yet most couples rarely sit down together to actually talk about it in a structured way. Life gets busy, conversations get avoided, and before long, financial stress starts to quietly build beneath the surface.

That’s where the money date comes in.

A money date is a scheduled, intentional time you set aside with your partner to review your finances together. It doesn’t have to be long or complicated. In fact, the simpler you keep it, the more likely you are to actually do it. Once a month is a good rhythm for most couples, though some prefer every two weeks, especially when working toward a specific goal.

Couples who regularly discuss money report higher relationship satisfaction and better financial health. This is why regular money dates can be so valuable for your relationship.

The goal isn’t to audit each other or assign blame. It’s to stay connected to your shared financial picture so you can make decisions together, reduce surprises, and work toward the things that actually matter to you as a team.

Here’s a checklist you can work through together at every money date.

Your Monthly Money Date Checklist

Review Last Month’s Spending Together

Start by pulling up your spending from the past month. This could be your budgeting app, a spreadsheet, your bank account, or your credit card statements. The format doesn’t matter as much as actually looking at the numbers together.

The point here isn’t to critique every purchase. It’s to get an honest picture of where your money went. Did spending align with what you both value? Were there any surprises? Did any categories run higher than expected?

This is also a good time to notice patterns. If dining out keeps coming in over budget, that’s useful information. Maybe the budget needs to be adjusted, or maybe it’s a signal to be more intentional. Either way, you’re making that decision together instead of one person silently stewing about it.

Keep this part of the conversation neutral and curious, not accusatory. You’re reviewing data, not assigning fault.

Check Progress on Shared Savings Goals

Whether you’re saving for a vacation, a home down payment, a new car, or an emergency fund, your money date is the time to check in on how those goals are progressing.

Pull up the balance in whatever account you’re using for each goal. Compare it to where you expected to be by now. If you’re on track, great. If you’ve fallen behind, you can talk about why and decide if you want to adjust your contribution or your timeline.

Having a visual tracker for savings goals can make this part of the conversation more motivating. Watching a number grow, even slowly, reinforces that your efforts are adding up.

If you don’t have shared savings goals yet, this is also a good time to start defining them. What are the two or three things you’re both most excited to save toward in the next year? Getting specific about goals makes it much easier to stay committed to them.

Identify Upcoming Big Expenses for Next Month

Take a few minutes to think through what’s coming up financially in the next 30 days. Are there any irregular or larger-than-usual expenses on the horizon?

This might include things like:

  • A car registration or annual insurance premium
  • A birthday or anniversary gift
  • Planned home maintenance or a repair
  • A school event or activity fee
  • Travel or a hotel for a trip you’ve already booked

Flagging these ahead of time helps you plan for them rather than getting caught off guard. It also gives you a chance to decide together how you’ll cover them, whether that’s from a sinking fund, from discretionary spending, or by temporarily cutting back somewhere else.

This step alone can eliminate a significant amount of financial stress. Most financial surprises aren’t truly surprises. They’re just expenses that weren’t planned for in advance.

Discuss One Financial Win Each Person Had Since the Last Date

This one might feel a little uncomfortable at first, especially if you’re not used to celebrating financial progress. But it matters.

Each person shares one thing they feel good about financially from the past month. It doesn’t have to be dramatic. Maybe you resisted an impulse purchase, automated a savings transfer, increased your 401(k) contribution, negotiated a lower rate on a subscription, or finally called to dispute a charge you’d been putting off.

Acknowledging progress, even small progress, builds positive momentum. It also helps reinforce that both people in the relationship are making an effort, which strengthens trust and keeps the financial conversation from feeling like it’s only about problems.

This part of the money date sets a constructive tone and reminds you both that you’re on the same team.

Confirm All Bills Are Paid or Scheduled

This is the unsexy but important housekeeping portion of the money date.

Go through your regular monthly bills and confirm that everything is either paid or scheduled. This includes utilities, rent or mortgage, subscriptions, loan payments, insurance premiums, and anything else that hits your accounts regularly.

If you have bills set to autopay, verify that the payment amounts look right and that there’s enough in the account to cover them. Autopay is convenient, but it can also lead to surprises if a rate changes or a payment processes at an unexpected time.

This step only takes a few minutes, but catching a missed payment or an unexpected charge during your money date is a lot less stressful than catching it after a late fee or an overdraft.

Review Debt Payoff Progress

If you’re currently paying down debt, whether that’s credit cards, student loans, a car loan, or anything else, your money date is a good time to check in on where things stand.

Look at the current balances and compare them to last month. Are they going down? Is the payoff strategy still the one you both agreed on? Are there any opportunities to accelerate payoff, like applying a bonus, a tax refund, or some extra cash flow toward a balance?

Watching debt balances decrease can be genuinely motivating, and celebrating that progress together makes the effort feel worth it.

If debt isn’t currently part of your picture, you can skip this step or use the time to talk about your strategy for staying debt-free going forward.

This is arguably the most important item on the list, and the one most couples skip.

Financial stress rarely announces itself clearly. More often, it shows up as irritability, avoidance, or tension that seems unrelated to money but usually isn’t. Giving each person a direct, low-pressure opportunity to name what’s worrying them can prevent a lot of that from building up.

The question is simple: Is there anything money-related causing you stress right now?

Maybe one person is anxious about job security. Maybe there’s a financial decision coming up that feels overwhelming. Maybe someone has been avoiding opening a certain account because they’re afraid of what they’ll see. Whatever it is, this question creates a safe opening to bring it into the conversation instead of carrying it alone.

You don’t have to solve everything in the money date. Sometimes just naming a concern out loud to your partner is enough to take the edge off it. And sometimes, it opens a conversation that leads to a plan.

A Few Tips for Making Your Money Date Work

You don’t need to make this elaborate. Some couples do their money date over brunch on a Sunday morning. Others do it over dinner on a weeknight. Some keep it to 20 minutes, others go longer. The format is flexible.

What matters is that it’s consistent and intentional. Put it on the calendar like any other commitment. Protect the time. And agree in advance to keep the conversation constructive.

If you and your partner are just getting started with money dates, it’s okay if the first few feel a little awkward. That’s normal. Financial conversations can carry a lot of emotional weight, especially if you’ve had conflict around money in the past. The structure of a checklist actually helps here because it gives you something concrete to focus on instead of letting the conversation drift into old patterns.

Over time, the money date becomes something most couples genuinely appreciate. It removes the guesswork from your finances, reduces conflict, and helps you feel like a real team when it comes to building the life you want together.

Financial stress in relationships often comes not from lack of money but from lack of communication. The money date is a practical way to change that.

By setting aside a small amount of time each month to review your spending, track your goals, look ahead, celebrate progress, and check in emotionally, you build the kind of financial partnership that makes everything else easier.

You don’t have to be perfect at it. You just have to show up.

Frequently Asked Questions About Money Dates

How long should a money date actually take?

For most couples, 15 to 30 minutes is a reasonable target. If you’re just starting out, your first few sessions might run longer as you set up systems and get comfortable with the format. Once you’ve established a rhythm and your finances are organized, many couples find they can get through the checklist in 10 to 15 minutes. The goal isn’t to spend hours on it. It’s to be consistent.

What if one partner is more interested in finances than the other?

This is extremely common. One person in most relationships tends to be the “money person,” and the other is less engaged. The money date helps bridge that gap because it creates a regular, low-stakes opportunity for the less financially engaged partner to stay informed without having to manage everything day to day.

Keep the conversation accessible. Avoid jargon. And remember that engagement usually grows over time once the less interested partner starts to see the value in staying connected to the financial picture.

Should we combine our finances before starting money dates?

Not necessarily. Money dates work for couples with fully combined finances, partially combined finances, and even those who keep things mostly separate. The checklist can be adapted to whatever structure works for your relationship. The point is to have visibility and open communication around money, not to force a particular financial structure.

That said, if you’re not sure what approach to take with your accounts, a money date is actually a great time to have that conversation.

What if our money date turns into an argument?

It happens, especially in the beginning. Money is emotional, and old tensions can surface when you start talking about it openly. A few things that help: agree on ground rules before you start, such as no blame and no bringing up past mistakes. Stick to the checklist so the conversation stays focused on information rather than grievances. And if things get heated, it’s okay to pause and come back to it later.

The goal is progress, not perfection. If financial conflict is a recurring and serious issue in your relationship, working with a couples therapist or a financial therapist can be genuinely helpful.

Do we need a budgeting app or special software to do this?

No. A shared spreadsheet, a notes app, or even paper works fine. What matters is that you both have access to the same information during your money date. If you don’t already have a system for tracking spending, a money date is a good time to decide together what tool you want to use going forward. But don’t let the lack of a perfect system stop you from starting. You can always refine your tools as you go.

How do we handle it if one partner earns significantly more than the other?

Income differences can create subtle power imbalances in financial conversations if you’re not careful. The key is to approach the money date as a conversation between equals regardless of who earns what. Both people’s perspectives, concerns, and goals deserve equal weight. If income disparity is creating real tension around spending, saving, or decision-making authority, that’s worth addressing directly, either in your money dates or with the help of a financial advisor or therapist who can help you build a structure that feels fair to both of you.

What if we have very different financial personalities?

One person might be a natural saver, while the other tends to spend more freely. One might be comfortable with financial risk while the other prefers security. These differences are common and don’t have to be a problem. In fact, they can balance each other out.

The money date creates a regular space to acknowledge those differences, understand where the other person is coming from, and find a middle ground that works for both of you. The structure of the checklist helps keep the conversation grounded in shared goals rather than personal habits.

When is a good time to start doing money dates?

Now. There’s no financial milestone you need to hit first. You don’t need to be debt-free, fully employed, or have a certain amount saved. Money dates are useful at every stage of a financial journey, whether you’re just starting out, actively building wealth, or navigating a financial challenge.

The earlier you establish the habit, the more natural it becomes. And if you’ve been together for years without ever having a structured financial conversation, it’s still not too late. Starting now is always better than waiting for the perfect moment.

This article was originally published here and is republished on Wealthtender with permission.

Headshot of Michael Reynolds, CFP®, CSRIC®, AIF®, CFT-I™
Michael Reynolds, CFP®, CSRIC®, AIF®, CFT-I™ Progressive Financial Planning & SRI/ESG Investing.

Michael Reynolds, CFP®, CSRIC®, AIF®, CFT-I™ | Elevation Financial

Find financial advisors in Biloxi, Mississippi ready to help with your financial planning needs so you can enjoy life more with less money stress.

Whether you have lived in Biloxi for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.

It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Biloxi featured on Wealthtender you may want to add to your shortlist.

As you prepare to interview financial advisors in Biloxi who may be right for you, get to know local financial advisors featured on Wealthtender.

📍 Map: Financial Advisors with their Primary Office Location in Biloxi

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Biloxi.

📍Double-click or pinch pins to view more.

Showing

The Benefits of Hiring a Financial Advisor in Biloxi

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Biloxi, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Do you work for one of the largest employers in Biloxi? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Quick Tips For Hiring an Biloxi Financial Advisor

Before hiring a financial advisor in Biloxi, here are a few quick tips to help you find the best advisor for you.

1. Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2. Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3. Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4. Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.


Frequently Asked Questions & Additional Resources

How do I know if I’m ready to hire a financial advisor?

You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.

But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.

Before I hire a new financial advisor, should I fire my current advisor?

You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.

Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?

After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. 

Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.

I’m a local financial advisor interested in being featured in this guide. How do I get started?

Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.

How Much Does a Financial Advisor Cost?

➡️ How Much Does a Financial Advisor Cost? Read the Article

About the Author
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian
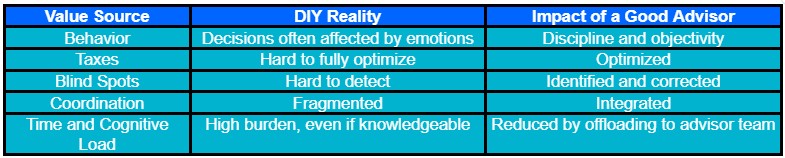
I’ve been a Marylander for almost 30 years. Although I’ve lived on three continents (four, if you count a couple of months in Antarctica), in three countries, and in two US states, I’ve lived here longer than anywhere else.

There’s a lot to love about Maryland. Just look at the photo below, taken not far from my home, and you’ll start to see why:

A calm lake reflects autumn trees with orange and yellow leaves, houses, and a cloudy sky at sunset. The scene is peaceful and serene, with still water mirroring the landscape.
Maryland autumn, 2022. Photo by the author.

However, the tax burden isn’t one of the things I love about my home state.

According to the Tax Foundation, Maryland has the 11th-highest per-capita tax burden in the country, about 13% above the U.S. average (based on 2022 data).

As Ben Simerly, CFP®, Financial Advisor and Founder of Lakehouse Family Wealth and former Marylander, says, “Maryland has literally become famous for unique and destructive taxes. To my knowledge, it’s the first state or territory, or in some cases one of the few, to tax the rain, provide more than a dozen forms of property taxes, and even tax money at the state level both at the time of death and inheritance. 

“For some, living in Maryland isn’t optional. Many federal workers and military personnel and their families are required to live and work in the region. If this is you, make the best of the situation. You may not get hazard pay like you would in earlier days of government service in the region, but with some help from pros, you can lessen the ill effects on your finances. 

“Here are our top areas of tax concern in Maryland. First, Maryland has its own particularly vindictive capital gains tax, despite gains already being taxed under several other state and federal codes. 

“It applies an extra 2% capital gains tax mainly on households with federal Adjusted Gross Income (AGI) above $350,000. Even if your household doesn’t normally make over $350,000, your AGI could get ‘bumped’ over $350k due to, e.g., receiving a large bonus; selling a house that appreciated too much; moving financial assets between account types that causes a taxable event; owning shares in mutual funds that distribute significant capital gains, dividends, and interest; etc. These can all trigger a ‘capital gains’ trap, which happens far more easily than you might think. 

“Second is additional death and estate taxes. Maryland levies a 10% tax on inheritance to the beneficiary, even if the money was taxed at the benefactor’s death. That’s right, it taxes the money yet again. And that’s after the also unique state inheritance tax of between 8% and 16% on estates with a gross value of $5 million. 

“There are look-back clauses too, meaning you can’t simply move to avoid the tax; you have to move long enough before death or inheritance to avoid the tax. States like Maryland, New York, and California will follow you around the world to collect taxes from you and take you to court or send agents if it goes that far. 

“My retirement planning work with Maryland clients over the years shows that most could retire 10 years sooner and have dramatically higher retirement income outside of Maryland, largely due to the benefits of rollovers occurring outside of the state.

“So, for Maryland residents, we often plan out income for even young families the way you normally only would for someone approaching Medicare age or already retired. We do everything we can to keep income under certain thresholds and then get the resident out of Maryland as soon as humanly possible.”

If I had to, I’d bet a nickel (assuming I can still find one in these digital times) that many Marylanders overpay their taxes. Not because they’re careless, but because they start thinking about it too late.

If you’re a higher-income Maryland resident, that can mean paying several thousand dollars in higher taxes per year than you’re legally required to. And once that money is gone, you don’t get it back.

By the time you’re filing your tax return, your tax liability is already set. At that point, your income is already set, your deductions and credits have already been earned (or not), and most opportunities to reduce your tax bill are behind you.

At that point, it’s mostly a question of how well you (or your tax software) identify the deductions and credits you’re eligible for.

That’s why if you want to reduce your Maryland taxes, filing better is a secondary priority. Your top priority should be to focus on better tax planning and strategy.

Three Types of Tax-Reducing Moves for Maryland Residents

There are only three legal ways to pay lower income tax.

  1. Lower your taxable income, ideally without reducing your standard of living (e.g., by using more and larger deductions).
  2. Take advantage of all tax credits for which you qualify.
  3. Make smarter timing and structural decisions.

Many taxpayers focus on the first, but still miss some opportunities, take partial advantage of the second, and almost entirely miss the third.

That’s why, even if they do everything perfectly at tax-filing time, they end up paying more than they could have.

The following are 10 tips for reducing your Maryland state and local income taxes. Some are straightforward. Others require a bit of planning. Most are easier to implement before the tax year is over.

You don’t have to use all 10, but the more you miss, the more of your hard-earned money you’ll leave on the table.

Lower Your Taxable Income

If you ask most people, this is what they’ll identify as a good way to reduce their taxes.

It’s natural. It’s the most straightforward way to reduce taxes.

But there’s a catch.

There’s using this lever, and then there’s USING it.

The former means contributing whatever you feel you can to your traditional retirement plans, using the standard deduction, and letting things flow as they will over the years.

This leaves lots of opportunities on the table, unused.

The latter requires being more proactive and committed.

Here are the top three examples.

1. Maximize Pre-Tax Retirement Contributions

If you can’t afford to maximize your retirement contributions without counting on the tax deduction, and especially if you’re already in a high tax bracket, this may be your best bet.

Not only does it reduce your federal taxable income, but it also reduces your taxable income for Maryland state and local taxes.

Table 1 shows some examples of how much you can lower your 2026 income taxes (federal, state, and local) by contributing an extra $10k to your traditional 401(k) account if you file “married filing jointly” and live in, e.g., Howard County, Maryland.

A table showing tax savings for different taxable incomes: $45,000 saves $1,995; $90,000 saves $2,995; $180,000 saves $3,233; $360,000 saves $4,395. Columns detail federal, Maryland, and Howard County savings.
Table 1. Example 2026 tax savings (federal, state, and local) for a married couple living in Howard County, Maryland, by increasing traditional 401(k) contributions by $10k.

Clearly, the majority of the tax savings come from the federal portion, but the state and local tax reduction can go as high as $980, or 0.98% (for residents of Dorchester County with a Maryland taxable income above $1.2 million).

If you’re one of those who don’t max their retirement contributions, this is the simplest and most powerful place to start, but only if you make the contributions before the end of the tax year!

And unlike many strategies, this one is (almost) entirely within your control.

2. Use Maryland’s 529 Deduction as Much as Possible

Maryland has a relatively generous deduction for people who set aside money for their dependents’ (or their own) education.

You can deduct contributions to Maryland 529 plans, up to $2500 per contributor, per beneficiary, per year.

That means that, if you’re married and have two kids, you could potentially deduct up to $20k a year ($5k from you and your spouse per beneficiary, for each of your kids, plus for the two of you).

What’s more, you can carry over excess contributions for up to 10 years.

That means that if you, e.g., open a plan for your child when she’s born, and contribute $5k a year from you and your spouse until your daughter goes to college, then contribute $20k in her freshman year and another $50k during her senior year, all of those contributions can ultimately be deducted.

That’s $160k-worth of deductible contributions spread over 32 years.

Even if you can’t afford to set aside money until your kid goes to college, but you do pay $70k in tuition and other eligible educational expenses during his college career, you can deduct those over the four years of college, plus the following decade.

And the most incredible thing about this deduction, in my opinion, is that you can contribute to the plan, then take the money out the very next day to pay the tuition bill, and it’s still deductible!

And lest we forget, if your kid doesn’t go to college or has such large scholarships that there’s a large balance left over, you can change beneficiaries, or you can use a SECURE 2.0 provision to convert up to $35k of the remaining balance into a Roth IRA for the beneficiary.

Few deductions offer this much flexibility with this much impact.

3. Don’t Blindly Use the Standard Deduction

Despite the significant increase in the federal standard deduction over the past several years, if you own a home with a large mortgage, make significant charitable donations, and perhaps have high medical expenses, itemizing can still reduce your taxable income by more than the standard deduction would.

And the larger your federal deduction, the lower your taxable income for Maryland state and local taxes.

The above three tips are the most visible lever and the one that most people focus on.

But if you stop there, you’re likely missing more powerful opportunities.

Take Full Advantage of Tax Credits

Tax deductions are great. They reduce your taxable income, which reduces your taxes.

But there’s something even better. 

Tax Credits.

For every $1 of tax deductions, your Maryland state and local taxes drop by about $0.08. But for every $1 of Maryland tax credits, your Maryland state and local taxes drop by a full $1!

If deductions are about trimming around the edges, credits are where meaningful reductions often happen.

The only problem is that, while more valuable from a tax reduction perspective, credits are far more tightly targeted.

Maryland offers quite a few such tax credits. The problem is that most middle-to-high earners assume credits don’t apply to them and never take the time to verify that assumption.

Here are a few credits worth checking carefully.

4. Child and Dependent Care Tax Credit

Even if your adjusted gross income is in the 6 figures, Maryland offers a substantial tax credit for child and dependent care expenses. 

The Maryland credit amount is figured as a percentage of the federal Child and Dependent Care Credit (CDCC), which can be 20% – 32% of qualified expenses up to $3000 for a single dependent or $6000 for two or more dependents.

That percentage depends on your filing status and your federal AGI. Table 2 shows some examples for couples who file jointly, have two dependents, and paid $6k or more in qualified care expenses.

Table comparing Federal and Maryland CDCC tax credits for different AGIs: $45,000, $90,000, $180,000, and $300,000. Columns show credit percentages, amounts, and total tax savings for each income level.
Table 2. Example 2026 tax savings (federal, state, and local) for a married couple living in Maryland, claiming the CDCC for $6k or more in qualified expenses for two kids.

5. Senior Tax Credit

Maryland offers a tax credit for seniors, even if their federal AGI is up to $150k if married filing jointly or up to $100k if single.

The credit takes up to $1750 off your Maryland tax bill if both spouses are 65 before the end of the tax year. If it’s a single taxpayer, or a couple where only one is 65 by the end of the tax year, the senior tax credit is $1000.

6. First-Time Homebuyer Subtraction

If you and your spouse (if any) are Maryland residents, haven’t owned or purchased a home in the past seven years, and contributed money to a first-time home buyer savings account, you can subtract from your taxes the lower of $5000 or the amount you contributed in the tax year, plus earnings from the account for the tax year.

You can do this for up to 10 years.

The earnings subtracted cannot exceed $50k over the 10 years.

There are caveats.

First, by the end of 15 years from when you open the account, you must use the account balance toward a down payment and/or eligible closing costs for buying a home in Maryland. Any amount not so used counts as taxable income in the following year.

Second, amounts withdrawn from the account for purposes other than eligible first-time home buying expenses count as taxable income for the tax year of the withdrawal and are also subject to a 10% penalty. Three exceptions are rollovers, bankruptcy, and administrative costs charged by the financial institution for the savings account.

Some other possible credits to investigate include:

  • Student Loan Debt Relief Tax Credit
  • Maryland Earned Income Credit
  • Credit for Taxes Paid to Another State
  • Long-term Care Insurance Credit
  • Independent Living Tax Credit
  • Oyster Aquaculture Credit
  • Historic Revitalization Credit
  • Conservation Easements Credit, and many more.

As mentioned above, don’t simply assume that you make too much to qualify. That just increases your risk of leaving easy money on the table, paying higher taxes than you owe.

Also, you may qualify for certain income-limited credits you wouldn’t normally qualify for in years when your income is lower than usual. This could be due to, e.g.:

  • Being unemployed or underemployed for part of the year (or, hopefully not, all of it).
  • Living off withdrawals from a Roth account, taxable portfolio, and/or savings accounts.
  • Living off untaxable proceeds from the sale of a home or other property.

 There’s no doubt that tax credits can be a powerful tool in reducing your Maryland state and local income tax.

But even these aren’t necessarily your biggest tax-cutting opportunity.

That will often result from planning and making optimal timing and strategic decisions.

Strategic Decisions and Timing – Where Planning Shines

As helpful as tax deductions may be, and as powerful as tax credits are, there’s someplace else where the biggest savings often are, and where many people leave the most money on the table.

Some because they prefer not to make the changes that would reduce their state and local taxes by the largest amount, but many others just don’t make the right moves in time.

This is the only category where decisions made months or even years earlier can completely change your tax outcome.

Simerly says, “While most of the available tax credits or deductions for Maryland are automatically asked about or applied by tax software and or accountants, some areas require more advanced planning.”

7. Time Income and Deductions Proactively

You don’t want the tax tail to wag your income dog, but the progressive nature of our tax system lets you reduce your long-term total taxes by avoiding spikes in taxable income that would push you into higher tax brackets.

This is true for federal taxes, but also for Maryland state and local taxes.

For example, if you have an especially high income in a specific year, you can:

  • Ask to defer at least part of your bonus (if any) to the following tax year.
  • Avoid realizing capital gains that year, holding off on selling appreciated assets until the following year.
  • Harvest tax losses by selling assets whose current value is lower than your basis in them.
  • Bunch charitable contributions into that year from the previous and/or next year.

The crucial thing is to be intentional and make the necessary decisions proactively, when you still have the flexibility to make them.

8. Coordinate Federal and State/Local Tax Decisions Intelligently

A Roth conversion is a plausible long-term tax-reduction and estate-planning strategy.

However, it’s important to consider your short-term taxes, including your Maryland state and local income taxes.

If you’ve decided on a Roth conversion, carry it out during years when you’re in a lower tax bracket.

Similarly, if you’re retired, you may benefit from drawing more out of your tax-deferred retirement accounts in years when your taxable income is otherwise lower than typical.

9. Where You Live Matters

Your Maryland state and local income tax could vary by up to 13% simply because you live in one jurisdiction vs. another.

For example, the local income taxes in Worcester County and Talbott County are relatively low, at 2.25% and 2.40%, respectively. Local tax in Dorchester County is the highest, at 3.30%. 

All other counties fall between those extremes, with Anne Arundel and Frederic Counties charging progressive taxes, per taxable income.

In this age of remote work, all other things being equal, you could shave over 1/8 of your Maryland state and local tax by moving from a high-local-tax-rate county to the lowest one.

Crucially, if for some reason the Comptroller of Maryland can’t identify your county of residence, you will be taxed at the highest local tax rate, of 3.30%. So if you live in a county that charges a lower rate, make sure you identify it correctly on your state tax return.

10. Treat Tax Planning as a Year-Round Process

Most people only think about how they can reduce their taxes when it’s mostly too late.

At tax filing.

By then, your income is already earned, your decisions are already implemented, and your tax-reduction opportunities are mostly gone.

If you want to minimize your state and local taxes, you need to do more than file better. You need to plan, decide, and execute earlier.

This means you need to:

  • Review your situation before year-end (preferably far before that point).
  • Identify opportunities.
  • Make adjustments while they can still affect your taxes.

Dr. Steven Crane, Founder of Financial Legacy Builders, shares, “In my experience, the biggest state tax wins usually come from decisions around income timing and where income shows up. Maryland has relatively high state and local taxes, so things like Roth conversions, retirement withdrawals, and even where assets are held can make a noticeable difference. I’ve worked with clients who didn’t realize that simply shifting how and when they recognize income could save them thousands over time. 

“One of the biggest mistakes I see is people treating state taxes as an afterthought. They focus on federal planning but ignore how state and local taxes stack on top of that. Another common issue is not coordinating decisions; someone might take a large distribution, sell assets, or exercise stock options without realizing the full state tax impact until it’s too late.”

The Bottom Line for Maryland Residents

If you’re a Maryland resident, especially one paying relatively high state and local income taxes, your biggest-impact tax-reduction strategy isn’t to find a single large tax break you somehow missed all these years.

It’s to identify and take advantage of all the deductions you’re legally allowed to take, claim all the tax credits you’re eligible for, and most crucially, make proactive choices before the end of the tax year, when they can still reduce your taxes.

The goal isn’t to find one big tax break. It’s to avoid small inefficiencies that add up over time.

Crane agrees, “The biggest thing I wish people understood is that tax planning isn’t something you do in April. By then, most of the decisions are already locked in. The real opportunities happen during the year, when you still have flexibility to control income, deductions, and timing. At the end of the day, reducing state taxes isn’t about finding one big trick. It’s about being intentional with how your financial life is structured and making small decisions that add up over time.”

You may already be implementing some of the above tips.

But it’s a good bet that you’re missing one or more and overpaying your taxes, year after year, as a result.

To reduce your Maryland state and local taxes as much as legally possible, identify the tips you’re missing and implement them as soon as possible.

The earlier you start, the more options you’ll have.

And the more options you identify and take advantage of, the more control you’ll have over how much of your money you’ll get to keep.

If you consider yourself financially disciplined, this is one area where that discipline can pay off directly. Because when it comes to taxes, the difference between ‘good enough’ and ‘well planned’ can mean thousands of dollars a year back in your pocket.

Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

Opher Ganel

About the Author

Opher Ganel, Ph.D.

My career has had many unpredictable twists and turns. A MSc in theoretical physics, PhD in experimental high-energy physics, postdoc in particle detector R&D, research position in experimental cosmic-ray physics (including a couple of visits to Antarctica), a brief stint at a small engineering services company supporting NASA, followed by starting my own small consulting practice supporting NASA projects and programs. Along the way, I started other micro businesses and helped my wife start and grow her own Marriage and Family Therapy practice. Now, I use all these experiences to also offer financial strategy services to help independent professionals achieve their personal and business finance goals. Connect with me on my own site: OpherGanel.com and/or follow my Medium publication: medium.com/financial-strategy/.


Learn More About Opher