
What this article covers
Find financial advisors in Creve Coeur, Missouri ready to help with your financial planning needs so you can enjoy life more with less money stress.
Financial Advisor Directory for Creve Coeur, Missouri
📍 Map: Financial Advisors with their Primary Office Location in Creve Coeur
Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Creve Coeur.
📍Double-click or pinch pins to view more.
Explore nearby city guides
Keep exploring
Key Takeaways
You can compare Creve Coeur financial advisors by credentials, specialty and verified client reviews before you contact anyone.
The map shows advisors whose primary office is in Creve Coeur. Profiles include Certified Advisor Reviews™, designations such as the CFP® and the services each advisor offers.
Creve Coeur’s Bayer campus, ag-science research and hospitals shape the planning help many residents need.
Employees of Bayer and the area’s plant-science organizations often need help with corporate benefits and job changes, and Missouri now lets individuals subtract 100% of capital gains from state income. Mercy Hospital St. Louis and Barnes-Jewish West County bring health care professionals with their own retirement and insurance questions.
Interview more than one advisor and confirm how each one is paid.
Ask about services, fees and whether the advisor acts as a fiduciary, then check their background for free on the SEC’s Investment Adviser Public Disclosure website before you hire.
Financial Planning Considerations for Creve Coeur Residents
Every city has its own financial landscape. Here are a few local factors worth discussing with a Creve Coeur financial advisor.
Bayer and the ag-science corridor
Creve Coeur was Monsanto’s home until Bayer acquired it in 2018, and Bayer’s crop science operations remain in the area along with the Donald Danforth Plant Science Center and the 39 North AgTech Innovation District. In 2024, Bayer announced more than $100 million in investments at its Creve Coeur and Chesterfield campuses while exploring the sale of part of the Creve Coeur campus. Employees going through reorganizations often need help with severance, 401(k) rollovers and health coverage.
Missouri’s capital gains subtraction
A 2025 Missouri law lets individuals subtract 100% of the capital gains reported on their federal return from Missouri income, according to the Missouri Department of Revenue. Capital losses don’t qualify, and trusts and estates can’t claim it. For residents with company stock, a concentrated portfolio or appreciated real estate, this changes the after-tax math on selling, though federal capital gains tax still applies.
Hospital and medical careers
Mercy Hospital St. Louis and Barnes-Jewish West County Hospital are both in Creve Coeur, and Mercy employs 15,342 people in the St. Louis County area. Doctors, nurses and other clinicians often balance student loans, disability insurance and more than one retirement plan. For 2026, 403(b) plans allow up to $24,500 in employee contributions, plus higher catch-up amounts at 50 and older and a larger catch-up for ages 60 to 63. For 2027, the IRS raised the limit to $25,500.
The Benefits of Hiring a Financial Advisor in Creve Coeur
Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.
As a resident living in Creve Coeur, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.
Who are the largest employers in the Creve Coeur area?
These are the ten largest employers in the St. Louis County area, as reported in the St. Louis County Library District’s 2024 financial report. Highlighted companies link to advisor Q&As about their employees.
- Washington University in St. Louis 21,278 employees
- Boeing Defense, Space & SecurityRead advisor Q&A →16,681 employees
- SSM Health 15,631 employees
- Mercy 15,342 employees
- Schnuck Markets 8,496 employees
- Archdiocese of St. Louis 7,000 employees
- Charter Communications 6,230 employees
- Special School District of St. Louis County 5,903 employees
- Edward Jones 5,446 employees
- Enterprise Mobility 5,000 employees
Work for one of these companies or another large employer? Explore our employer Q&As for advice on making the most of your benefits.
Source: St. Louis County Library District, 2024 Annual Comprehensive Financial Report (Principal Employers, citing the St. Louis Business Journal) (2025). Counts are for the St. Louis County area, not Creve Coeur alone, and come from the St. Louis Business Journal as cited in the library district’s report. BJC HealthCare does not appear in this table.
Do you work for one of the largest employers in Creve Coeur? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.
When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.
Types of Financial Advisors You’ll Find on Wealthtender
Thousands of people visit Wealthtender each month to find and compare financial advisors based on their location, education, experience, areas of specialization and online reviews. Wealthtender’s Certified Advisor Reviews™ help consumers make informed hiring decisions with important details about the relationship between reviewers and advisors always displayed to ensure you gain the transparency you deserve when your life savings could be at stake.
On Wealthtender, you can explore a diverse range of financial advisors and wealth management firms that include:
- Fiduciary advisors committed to acting in clients’ best interests
- CFP® professionals with advanced financial planning credentials
- Fee-only advisors compensated solely by clients
- Advisors for growing families, people nearing retirement, and business owners
- Specialists across multiple categories (e.g., life stage, occupation, ethnicity, lifestyle, religion)
- Highly-rated advisors with positive client reviews
- Firms of varying sizes with advisors who can meet with you in person or online
- Fee-based advisors who offer access to insurance and alternative investments
How to use this directory: Compare financial advisors in the Creve Coeur area based on what matters most to you. Use the directory to:
- View advisor profiles to evaluate credentials, services, and areas of specialization
- Read Certified Advisor Reviews™ to learn what clients value most
- Identify advisors recognized with Wealthtender Voice of the Client Awards™
- Contact advisors and schedule free introductory video calls
Wealthtender Voice of the Client Awards™: Top Rated Creve Coeur Financial Advisors
Wealthtender Voice of the Client Awards™ recognize financial advisors and firms that consistently earn exceptional client feedback. Below are Creve Coeur-area advisors and firms that have met the criteria for Highly Rated recognition.
| Firm/Advisor | Firm | City | State | Voice of the Client Award | Website |
|---|
To qualify for a Highly Rated award, advisors and firms must achieve an average client review rating of 4.75 or higher (on a scale of 1 to 5) based on a minimum number of eligible client reviews published on Wealthtender within a defined timeframe for each particular award (Timeframe for 2025 Award: 1/1/24 – 12/31/25; Timeframe for Subsequent Year Awards: July 1 of the preceding year through December 31 of the Award Year (e.g., Timeframe for 2026 Award 7/1/25 – 12/31/26). Eligible reviews are limited to clients (as of the review submission date) that advisors/firms must self-attest have no material conflicts of interest and received no compensation in exchange for their reviews. ↗️ View full award methodology & FAQs
Although financial advisors and wealth management firms compensate Wealthtender for marketing services (including eligibility to be considered for awards), Wealthtender’s award criteria is objective and not influenced by compensation. Wealthtender Voice of the Client Awards are not a guarantee of future performance or success and client reviews may not be representative of the experience of all past or future clients.
Quick Tips For Hiring a Creve Coeur Financial Advisor
Before hiring a financial advisor in Creve Coeur, here are a few quick tips to help you find the best advisor for you.
Decide Which Services You Need
Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.
Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:
- Budgeting and money management
- Debt management
- Insurance planning
- Retirement planning
- Other investment planning
- Inheritance planning
- Estate planning
- Tax planning
As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor who specializes in those areas.
Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.
Consider Your Budget and Payment Preferences
Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.
If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.
Interview Multiple Financial Advisors
Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:
- What services do you provide?
- What are all the ways you get paid? (fee transparency)
- What is your investment strategy?
- How do you measure investment performance?
- How do we communicate about my plan?
Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.
Review Financial Advisor Credentials
Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website.
You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.
As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.
For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.
Frequently Asked Questions
Financial advisors and wealth management firms that consistently receive superior client reviews can also qualify for Wealthtender’s Voice of the Client Awards™ designed to recognize America’s most trusted advisors. Learn More About Wealthtender Voice of the Client Awards™
Clients and other individuals can submit reviews for financial advisors and wealth management firms that have turned on the reviews feature. Before each review is publicly displayed, financial advisors agree to disclose important information about their relationship with the reviewer to ensure consumers gain the transparency they deserve when their life savings could be at stake. These disclosures also help financial advisors satisfy compliance with industry regulations.
After financial advisors provide the required disclosures, Wealthtender publishes the review with the Certified Advisor Review™ mark. Learn More About Certified Advisor Reviews™
For example, financial advisors who have earned their Certified Financial Planner (CFP) designation are fiduciaries. To hold themselves out as a CFP, these credential holders must acknowledge they will adhere to the CFP Board’s Code of Ethics and Standards of Conduct and act as a fiduciary when providing financial advice to their clients. Learn More About Fiduciary Financial Advisors
When viewing financial advisor profiles on Wealthtender, look for the Compensation Methods section that shows ways each financial advisor can be paid for their services, including if they offer fee-only financial planning services. Learn More About Fee-Only Financial Advisors
Please note: Wealthtender may be compensated by financial advisors featured on our site and within this guide. Learn more about how we operate with integrity to earn your trust.
How Much Does a Financial Advisor Cost?
About the author
Founder & CEO and Editor-in-Chief, Wealthtender
Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.
Brian and his wife live in Austin, Texas.
What this article covers
Discover financial advisors trusted by St. Louis residents in the only local directory featuring 5-Star Certified Advisor Review ™ recipients and Wealthtender Voice of the Client Award™ winners, recognition earned for exceptional client feedback. Compare fiduciary, fee-only advisors, CFP® professionals, and specialists to find the right fit for your unique financial needs.
Financial Advisor Directory for St. Louis, Missouri
📍 Map: Financial Advisors with their Primary Office Location in St. Louis
Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in St. Louis.
📍Double-click or pinch pins to view more.
📍 Additional Advisors Who Serve Clients in St. Louis
In addition to the advisors featured above, these advisors can also meet with you in person in St. Louis.
Key Takeaways
You can compare St. Louis financial advisors by credentials, specialty and verified client reviews before you contact anyone.
The map shows advisors whose primary office is in St. Louis, and the section below it lists advisors who also serve St. Louis clients in person or virtually. Profiles include Certified Advisor Reviews™, designations such as the CFP® and the services each advisor offers.
St. Louis’s earnings tax, academic medicine and large corporate employers shape the planning help many residents need.
City residents and people who work in the city pay a 1% earnings tax that voters renewed in April 2026. Washington University, the region’s health systems and companies like Boeing and Edward Jones bring retirement plan and equity pay decisions, and the May 2025 EF3 tornado is a reminder to review home insurance.
Interview more than one advisor and confirm how each one is paid.
Ask about services, fees and whether the advisor acts as a fiduciary, then check their background for free on the SEC’s Investment Adviser Public Disclosure website before you hire.
Financial Planning Considerations for St. Louis Residents
Every city has its own financial landscape. Here are a few local factors worth discussing with a St. Louis financial advisor.
The city’s 1% earnings tax
The City of St. Louis charges a 1% earnings tax on residents, wherever their employer is located, and on people who work for businesses located or performing work in the city, wherever they live. In April 2026, city voters renewed the tax for another five years with 84.7% support. If you’re choosing between living in the city or the county, or between an office downtown and one in Clayton or West County, the earnings tax belongs in the math.
Academic medicine and research careers
Washington University in St. Louis is the area’s largest employer in the St. Louis Business Journal figures, with 21,278 employees, and SSM Health and Mercy each employ more than 15,000. Physicians, researchers and hospital staff often face student loan repayment choices, disability insurance gaps and multiple retirement accounts. For 2026, 403(b) and governmental 457(b) plans each allow up to $24,500 in employee contributions, with higher catch-up limits for those 50 and older. For 2027, the IRS raised the limit to $25,500.
Boeing, Edward Jones and corporate pay
Boeing Defense, Space & Security employs 16,681 people in the area, and Edward Jones and Enterprise Mobility each employ about 5,000 or more. Corporate employees often have a 401(k) match, bonuses and sometimes stock awards or deferred compensation, which raises questions about tax timing and how much of your wealth depends on one employer. Our Boeing Q&A covers these choices for Boeing employees.
Tornado risk and home insurance
On May 16, 2025, an EF3 tornado with estimated peak winds of 152 mph touched down in Richmond Heights and tracked about 23 miles through north St. Louis to Edwardsville, Illinois, damaging or destroying thousands of buildings, according to the National Weather Service. It’s worth checking your deductibles, replacement-cost coverage and emergency savings. Most standard homeowners policies don’t cover flood damage, and FEMA notes flood insurance typically takes 30 days to become active.
The Benefits of Hiring a Financial Advisor in St. Louis
Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.
As a resident living in St. Louis, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.
Who are the largest employers in the St. Louis area?
These are the ten largest employers in the St. Louis County area, as reported in the St. Louis County Library District’s 2024 financial report. Highlighted companies link to advisor Q&As about their employees.
- Washington University in St. Louis 21,278 employees
- Boeing Defense, Space & SecurityRead advisor Q&A →16,681 employees
- SSM Health 15,631 employees
- Mercy 15,342 employees
- Schnuck Markets 8,496 employees
- Archdiocese of St. Louis 7,000 employees
- Charter Communications 6,230 employees
- Special School District of St. Louis County 5,903 employees
- Edward Jones 5,446 employees
- Enterprise Mobility 5,000 employees
Work for one of these companies or another large employer? Explore our employer Q&As for advice on making the most of your benefits.
Source: St. Louis County Library District, 2024 Annual Comprehensive Financial Report (Principal Employers, citing the St. Louis Business Journal) (2025). Counts are for the St. Louis County area, not the city alone, and come from the St. Louis Business Journal as cited in the library district’s report. BJC HealthCare does not appear in this table.
Do you work for one of the largest employers in St. Louis? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.
When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.
Types of Financial Advisors You’ll Find on Wealthtender
Thousands of people visit Wealthtender each month to find and compare financial advisors based on their location, education, experience, areas of specialization and online reviews. Wealthtender’s Certified Advisor Reviews™ help consumers make informed hiring decisions with important details about the relationship between reviewers and advisors always displayed to ensure you gain the transparency you deserve when your life savings could be at stake.
On Wealthtender, you can explore a diverse range of financial advisors and wealth management firms that include:
- Fiduciary advisors committed to acting in clients’ best interests
- CFP® professionals with advanced financial planning credentials
- Fee-only advisors compensated solely by clients
- Advisors for growing families, people nearing retirement, and business owners
- Specialists across multiple categories (e.g., life stage, occupation, ethnicity, lifestyle, religion)
- Highly-rated advisors with positive client reviews
- Firms of varying sizes with advisors who can meet with you in person or online
- Fee-based advisors who offer access to insurance and alternative investments
How to use this directory: Compare financial advisors in the St. Louis area based on what matters most to you. Use the directory to:
- View advisor profiles to evaluate credentials, services, and areas of specialization
- Read Certified Advisor Reviews™ to learn what clients value most
- Identify advisors recognized with Wealthtender Voice of the Client Awards™
- Contact advisors and schedule free introductory video calls
Wealthtender Voice of the Client Awards™: Top Rated St. Louis Financial Advisors
Wealthtender Voice of the Client Awards™ recognize financial advisors and firms that consistently earn exceptional client feedback. Below are St. Louis-area advisors and firms that have met the criteria for Highly Rated recognition.
| Firm/Advisor | Firm | City | State | Voice of the Client Award | Website |
|---|---|---|---|---|---|
| Joe Petry, PhD, CFP®, EA, CRPC® | Mayfair Financial | Kirkwood | Missouri | 2025 Highly Rated Advisor | Website |
To qualify for a Highly Rated award, advisors and firms must achieve an average client review rating of 4.75 or higher (on a scale of 1 to 5) based on a minimum number of eligible client reviews published on Wealthtender within a defined timeframe for each particular award (Timeframe for 2025 Award: 1/1/24 – 12/31/25; Timeframe for Subsequent Year Awards: July 1 of the preceding year through December 31 of the Award Year (e.g., Timeframe for 2026 Award 7/1/25 – 12/31/26). Eligible reviews are limited to clients (as of the review submission date) that advisors/firms must self-attest have no material conflicts of interest and received no compensation in exchange for their reviews. ↗️ View full award methodology & FAQs
Although financial advisors and wealth management firms compensate Wealthtender for marketing services (including eligibility to be considered for awards), Wealthtender’s award criteria is objective and not influenced by compensation. Wealthtender Voice of the Client Awards are not a guarantee of future performance or success and client reviews may not be representative of the experience of all past or future clients.
Quick Tips For Hiring a St. Louis Financial Advisor
Before hiring a financial advisor in St. Louis, here are a few quick tips to help you find the best advisor for you.
Decide Which Services You Need
Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.
Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:
- Budgeting and money management
- Debt management
- Insurance planning
- Retirement planning
- Other investment planning
- Inheritance planning
- Estate planning
- Tax planning
As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor who specializes in those areas.
Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.
Consider Your Budget and Payment Preferences
Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.
If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.
Interview Multiple Financial Advisors
Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:
- What services do you provide?
- What are all the ways you get paid? (fee transparency)
- What is your investment strategy?
- How do you measure investment performance?
- How do we communicate about my plan?
Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.
Review Financial Advisor Credentials
Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website.
You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.
As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.
For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.
Frequently Asked Questions
Financial advisors and wealth management firms that consistently receive superior client reviews can also qualify for Wealthtender’s Voice of the Client Awards™ designed to recognize America’s most trusted advisors. Learn More About Wealthtender Voice of the Client Awards™
Clients and other individuals can submit reviews for financial advisors and wealth management firms that have turned on the reviews feature. Before each review is publicly displayed, financial advisors agree to disclose important information about their relationship with the reviewer to ensure consumers gain the transparency they deserve when their life savings could be at stake. These disclosures also help financial advisors satisfy compliance with industry regulations.
After financial advisors provide the required disclosures, Wealthtender publishes the review with the Certified Advisor Review™ mark. Learn More About Certified Advisor Reviews™
For example, financial advisors who have earned their Certified Financial Planner (CFP) designation are fiduciaries. To hold themselves out as a CFP, these credential holders must acknowledge they will adhere to the CFP Board’s Code of Ethics and Standards of Conduct and act as a fiduciary when providing financial advice to their clients. Learn More About Fiduciary Financial Advisors
When viewing financial advisor profiles on Wealthtender, look for the Compensation Methods section that shows ways each financial advisor can be paid for their services, including if they offer fee-only financial planning services. Learn More About Fee-Only Financial Advisors
Please note: Wealthtender may be compensated by financial advisors featured on our site and within this guide. Learn more about how we operate with integrity to earn your trust.
How Much Does a Financial Advisor Cost?
About the author
Founder & CEO and Editor-in-Chief, Wealthtender
Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.
Brian and his wife live in Austin, Texas.
Do you work at Tesla?
Get expert insights from financial advisors who specialize in helping Tesla employees and executives make the most of their compensation package and benefits.
Looking for a financial advisor who specializes in working with Tesla employees? You’re in the right place. Below, you’ll find advisors who understand Tesla benefits and compensation — along with their answers to common financial questions from Tesla employees and executives.
Whether you recently joined Tesla or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and Tesla benefits can have a lasting impact on your financial future. For example:
- Do you know the right moves to get the greatest value from the Tesla benefits available to you?
- If you’re thinking about leaving Tesla for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?
Key Takeaways
Tesla Stock Sales Need a Plan Built Around Trading Windows
Tesla employees generally have to sell shares during open trading windows or through a 10b5-1 selling plan, so diversifying takes structure rather than a one-time decision. The advisors below describe tax-aware selling plans, and note that Tesla employees’ mixed feelings about the stock can make the diversification conversation easier than at many companies.
Tesla Stock Options Require Careful Alternative Minimum Tax Planning
Exercising incentive stock options and holding the shares can trigger the alternative minimum tax. The advisors below describe modeling multi-year exercise strategies, using vested RSU shares to fund exercises, and revisiting the hold decision before year-end, when a disqualifying disposition can still undo an exercise that no longer makes sense.
Before Leaving Tesla, Check Unvested Equity, Option Deadlines, and Health Coverage
Unvested equity is forfeited when you leave, and vested options typically must be exercised within a short window after departure. Health coverage ends at month-end, so a gap before a new job starts matters, and 401(k) and HSA contribution limits carry across employers in the same calendar year.
Why Tesla Employees Work with a Specialist Financial Advisor
Throughout the year, Tesla provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) and, for some highly compensated employees, a deferred compensation plan — along with equity compensation such as restricted stock units, stock options, and an employee stock purchase plan. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with Tesla who specialize in helping Tesla employees make the most of their income and benefits.
Tesla moved its headquarters to Gigafactory Texas in Austin in 2021, and its largest U.S. workforces are spread across the Austin gigafactory, the Fremont, California, vehicle factory, Gigafactory Nevada near Reno, and engineering teams in Palo Alto, with additional operations in places such as Lathrop, California, and Buffalo, New York. Whether you work on a factory floor, in a service center or corporate office, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.
Sensitive topics — like the steps you should take before quitting your job at Tesla to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.
Should You Hire a Tesla Specialist or a Local Financial Advisor?
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Tesla employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with Tesla employees is the better fit for your unique needs.
In the Q&A below, you’ll gain insights from financial advisors who work with Tesla employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.
Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.
Q&A: Financial Planning Tips for Tesla Employees & Executives
In this section, you’ll learn how you can make the most of your Tesla employee benefits and gain valuable tips from financial advisors who specialize in working with Tesla employees and executives.
Jump to a Financial Advisor for Tesla Employees
Financial Advisor Q&A · Tesla Employees
Emily Rassam, CFP®, CRPS, AIFA, NSSA, CDAA
Archer Investment Management · Charlotte, NC · Serves clients nationwide
Richard J. Archer, CDAA, CFA, CFP®, MBA
Archer Investment Management · Austin, TX · Serves clients nationwide
With a focus on serving professionals in the technology industry, the financial advisors at Archer Investment Management help their clients get the most value from their benefits and compensation package so they can enjoy life and feel confident about their financial future. Based in Charlotte, North Carolina, and Austin, Texas, respectively, Emily Rassam and Richard Archer specialize in offering financial planning services to Tesla employees.
QAs a financial advisor with experience helping TESLA employees save for retirement, how do you help them make the most of their employee benefits?
Emily: At Archer Investment Management, we specialize in working with mid-career technology professionals. We have several TESLA employees as clients and are familiar with the company’s employee benefit plans, retirement plans, equity compensation packages, and ancillary benefits.
More importantly, we are acutely aware of the financial planning needs of technology professionals and how their TESLA benefits fit into an overall financial plan, including long-term planning, goal setting, tax planning, and estate planning. We start by building a financial personality profile and risk tolerance assessment to understand your relationship with money and your comfort level with risk.
QWhen you first speak with a TESLA employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
Richard: Our detailed onboarding process includes conversations about your life goals, how your finances play a role in maximizing happiness, and what it means to be intentional with money. We gather information about your benefits and compensation package, spending plan, short-term and long-term goals, taxes, estate plans, and insurance.
This detailed planning process allows us to build a comprehensive picture of your financial life and how each piece of the puzzle fits together. You cannot make recommendations without examining the whole picture.
QIs there a particular benefit available to TESLA Technologies employees you feel isn’t as well utilized or understood by employees as it should be?
Richard: Many of the TESLA health care plans are high-deductible health care plans (HDHPs) that allow you to save in a Health Savings Account (H.S.A.). An H.S.A. is a very powerful savings vehicle that can be triple-tax-free and allows you to build long-term savings for future health care costs.
In 2023, a single individual can save up to $3,850 in an H.S.A. and a married couple can save $7,750. For TESLA employees over age 50, you may save an additional $1,000 as a catch-up contribution. [Editor’s note: These are 2023 figures. For 2026, the H.S.A. limits are $4,400 for self-only coverage and $8,750 for family coverage, and the $1,000 catch-up applies at age 55 or older.] Once your H.S.A. reaches a minimum balance threshold, you can then invest the assets in a brokerage account. This is an underutilized benefit we regularly advise our TESLA clients to maximize and build over time. It’s often advantageous to avoid tapping your H.S.A. for health care costs so that you can allow the H.S.A investment account to compound over time; If you have the means, paying out-of-pocket for health care expenses can be a savvy tax move.
QBeyond the TESLA employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients (e.g., stock, education savings, health savings)?
Emily: Virtually all employees are eligible to join the employee stock purchase plan (ESPP) through E*TRADE. So long as you are scheduled to work for more than 5 months for TESLA, are employed at the beginning and end of the offer period, and work 20 hours or more per week, you may join the plan at the start of the next offer period.
This plan allows you to purchase TESLA stock at a discount and build additional wealth beyond the 401(k) plan by saving up to 15% of your pay into the ESPP plan. Each year, the offer period typically opens on August 1st for the September 1 – February 28 purchase period and you may make elections throughout the month of February for the purchase period of March 1 – August 31. As mentioned earlier, you can also invest your H.S.A. money like you would a retirement account.
QFor TESLA employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
Emily: Your matched 401(k) dollars vest at 25% each year over four years. If you have not yet met four years of service, you may want to review the employer dollars you are leaving on the table. You may have received employee stock options or restricted stock units (RSUs) that are unvested. Look carefully at the dates on your grants and vesting schedules to determine when each RSU grant vests; this may impact your timing to leave TESLA. You have 90 days after departing the company to exercise your stock options. Work with an advisor to determine which grants to exercise and the best way to fund this purchase.
QFor TESLA employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
Richard: Our detailed retirement planning process includes:
· A spending strategy tailored to your income goals
· Social Security timing recommendations
· Coordination of health care benefits
· Discussion around how your spending will change throughout retirement
· Stress-testing your retirement projection with many what-if scenarios
· Timing your exit to maximize any unvested incentive stock options (ISOs), non-qualified stock options (NSOs), or RSUs
QFor TESLA employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
Emily: There are many online tools and calculators. Where we find TESLA employees get stuck is understanding how to prioritize goals and seeing the big picture. We help TESLA employees organize their financial lives and provide accountability for reaching goals.
Understanding whether you should use surplus dollars to pay down debt, save towards a short-term goal, or work towards a long-term aspiration (such as retirement or college education savings) can be challenging. For TESLA employees planning with a spouse or partner, an advisor helps facilitate difficult conversations and moves the ball forward in your planning process.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are TESLA employees and how do you help them overcome these obstacles?
Richard: One common obstacle we find is knowing when to diversify away from the concentration risk of holding a high percentage of your net worth in one company’s shares. Many of our TESLA employee clients struggle with selling positions; it requires coaching, recognizing natural human biases, an evaluation of the risks, and careful diversification away from an outsized position.
QWhat questions do you recommend TESLA employees ask financial advisors they’re considering hiring to help them decide if the relationship would be a good fit?
Richard: If you were granted ISOs or RSUs, be sure to work with an advisor who understands how to incorporate those into your overall picture. Seek an advisor who can model the alternative minimum tax (AMT), understands the rules around qualifying and disqualifying dispositions, and knows how and when to diversify away from sizeable single stock positions, if appropriate.
QIs there anything that comes up frequently in your initial meeting with TESLA employees that surprises you?
Richard: We enjoy finding opportunities to help TESLA employees maximize their ESPP plans, H.S.A. plans, and understand their non-traditional benefits such as tuition reimbursement, legal services, vision insurance refunds, fitness benefits, and generous life insurance benefits.
QFor highly compensated TESLA employees and executives, are there any special benefits you believe are important to take into consideration when preparing their financial plan?
Emily: Highly compensated employees at TESLA are more likely to have been awarded stock options and/or RSUs. It’s important to evaluate your equity compensation as part of your overall offer for employment and understand how they fit into your multi-year financial plan.
QIs there a particularly memorable experience or a moment you recall with a client who worked at TESLA when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?
Emily: In recent meetings with a TESLA employee, we modeled multiple stock option exercise strategies to reduce lifetime AMT. In some cases, it makes sense to exercise options slowly over many years. In this case, it made the most sense to exercise all vested options within three years. We determined which vested RSU shares we could sell to help fund the cost of exercising those shares.
Considering a financial advisor who specializes in working with Tesla Employees?
Financial Advisor Q&A · Tesla Employees

Ryan Goldenhar, CFA®, CFP®
Wealth With Options · San Diego, CA · Serves clients nationwide
Portfolio manager, financial planner and trusted partner to wealthy familiesRyan Goldenhar is a financial advisor based in San Diego, California who specializes in offering financial planning services to Tesla employees. Ryan helps his clients get the most value from their Tesla benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping Tesla employees save for their retirement, how do you help them make the most of their employee benefits?
Tesla has some great benefits and we make sure that you are taking advantage of all that they offer. This includes helping you with your equity compensation (ISOs, NSOs, RSUs, ESPP), retirement accounts, health insurance and family benefits within their overall corporate benefits package.
QWhen you first speak with a Tesla employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
Tesla is a publicly traded company which means you either need to sell during open windows or a 10b5-1 selling plan with E-Trade/Morgan Stanley. We help you to strategize around the best way to diversify with the lowest possible taxes based on your unique situation and goals.
This leads to questions such as:
- What are your goals in life?
- How long do you hope to stay with Tesla?
- How would you like your wealth to support your family and legacy?
- How well do you feel you understand your equity compensation?
- Do you have an idea of how much in taxes you will owe with your total compensation package?
QIs there a particular benefit available to Tesla employees you feel isn’t as well utilized or understood by employees as it should be?
Incentive Stock Options (ISOs) are still occasionally issued by Tesla and if you have them, they can be confusing since they do have tax benefits but you have to be careful around generating Alternative Minimum Tax (AMT) if you exercise-and-hold shares via an ISO exercise. We help clients navigate this issue with a structured plan of potentially exercising them early in a calendar year and then revisiting the buy-and-hold decision during the last trading window of the calendar year before AMT might become due on the phantom benefit value from exercising the following April. If the decision to buy-and-hold TSLA shares from an ISO exercise no longer makes economic sense during the last trading window of the year, we help clients explore what’s called a “disqualifying disposition” which works like a “mulligan” in golf…it’s a do over.
QBeyond Tesla employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?
Tesla has a nice legal benefit that can allow you to create an estate plan for little to no cost. Many employees might not know about this benefit but it’s one we encourage our clients to use since we focus on much more than just investments. We help review our clients’ corporate benefits, estate plans, tax returns, insurance (property & casualty term life, etc.), college savings plans, debt management and review job offers as they explore moving to a new employer.
QFor Tesla employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
If you’re thinking of leaving Tesla, you should consider the financial impact of losing your UNVESTED equity which will be forfeited when you leave. In addition, you may have a short window to exercise and remaining vested options when you leave and need to factor this economic decision into all of the other financial choices that come with leaving Tesla to join a new company. Another consideration is health insurance. Health insurance will end at month-end of your employment. Knowing you have another job starting in a few weeks vs. a few days may leave you open to a medical emergency if coverage is not continuous. Finally, 401(k) employee contributions and HSA contributions are a zero sum game across employers. If you contribute the maximum to the Tesla 401(k) and then move to a new employer, you might need to wait until the next year to start contributing to the new 401(k) to make sure you don’t overcontribute to a 401(k) plan for the calendar year and then need to fix it later to avoid a tax penalty.
QFor Tesla employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
Many of our tech professional clients look to make work optional around age 50 to age 55. Because they’re not 59 1/2 yet which would allow them to pull funds penalty free from an IRA or 401(k), we need to assess the level of outside retirement account assets to support the client’s lifestyle and to budget potentially higher costs for medical insurance until they reach age 65 to qualify for lower cost Medicare coverage.
We work with our clients to understand COBRA and health exchange options years in advance, so we have a good year of emergency savings ready for the first big moment of this next phase in life. Then, it’s really about seeing how you can lean into your values and passions while keeping the finances in mind. Some of our clients go on to create their own startups or decide on consulting or volunteer work, etc. For our clients, we’ve discovered that a traditional ‘retirement’ to lounge by the pool with a Mai Tai isn’t of interest. They want “financial freedom” to explore new and different life adventures that may require cash needs to get going. We make sure we understand what will be going out the door by helping our clients imagine what their new lives will look like. Then we work to structure their portfolio cash flow so they can see how they are doing spending-wise compared to what we planned for.
QFor Tesla employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
An advisor can help with short-term decision-making such as equity compensation decisions, tax planning guidance, etc. and also with bigger-picture thinking (i.e. creating a framework so you can see the direction all your hard work is taking you, and make sure your money behaviors are aligning with your life goals). A client is often already doing many of the right things, moving in a positive direction and the value of working with an advisor/coach is to serve as an execution and accountability partner to allow the client to achieve more than they can do on their own.
Our planning process helps to put things in a broader framework to allow our clients to confidently make decisions that are proactive and intentional while we serve as a sounding board for the client about ideas they’re not sure about.
We encourage DIY investors to consider the cost of NOT getting a second opinion. Investment management is one thing, but retirement planning has incredible nuance to it that many people overlook such as:
- How will my investments be taxed? Can I minimize my lifetime taxation? Am I taking too much (or not enough) risk in the markets?
- What is my plan to turn my assets into income? What are the tax implications of doing that?
- Am I going to run out of money? How should I deal with Inflation?
- What about long-term care?
- Are my beneficiary designations up to date? Do I understand what’s going to happen to my assets when I pass?
- Do I need life insurance? Do I have enough or too much? Should I keep these old policies?
There are a number of different areas that a Certified Financial Planner (CFP) can provide incredible value to a recent retiree, even if they choose to continue to manage their own investments.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are Tesla employees and how do you help them overcome these obstacles?
A good, high-paying job in tech can feel a bit like golden handcuffs sometimes and it can be hard to imagine walking away. But, if you want to prepare for an exit or a shift to a different industry, we can create a pathway to ease the transition. In a role with equity compensation, a challenge can be to define how much to rely on that compensation in the plan. It’s variable and can be hard to quantify, but can be significant. So, having a firm structure based on a client’s comfort with the exposure and how it’s treated in the plan is important.
QWhat questions do you recommend Tesla employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
How does the advisor think about and approach decisions to complicated financial choices? We’ve found that sometimes the best choice for a particular client isn’t the one with the highest possible economic value because “sleep at night” and emotional factors might be more important than the biggest number on a spreadsheet. Your advisor should be able to clearly articulate how they arrived at their recommendations in a way that you can understand in plain English with no salesy finance gibberish. They should understand that trust must be earned over time and isn’t going to be granted immediately. Beyond these philosophical points, you should ask if the advisor is a fiduciary legally required to put your economic interests before his or her own? Will the advisor be providing comprehensive financial planning or just investment management? What will you pay in fees? Are there any hidden fees in the products the advisor is recommending?
QIs there anything that comes up frequently in your initial meeting with Tesla employees that surprises you?
Maybe not surprising in the current political climate, but Tesla employees can feel conflicted in their feelings about their company stock. Most employees of other companies where we have clients LOVE their company stock…it’s their favorite investment. With Tesla, some love it and some not so much. I suppose it makes it easier to discuss diversifying Tesla than it is at other clients’ companies.
QFor highly compensated Tesla employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?
For highly compensated employees at Tesla, we encourage them to look at and explore the potential benefits of a deferred compensation plan if they get invited to participate in the following calendar year. It’s a good tool to defer income taxes but comes with some tradeoffs that we help our clients explore before participating.
QIs there a particularly memorable experience or a moment you recall with a client who worked at Tesla when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?
We have found that many Tesla company employees that are single when they join are more interested in getting married if their significant other doesn’t also have a high amount of compensation. In these situations where our Tesla client makes a high income and their significant other does not, filing their tax returns as “married filing jointly” instead of as a single taxpayer might be just enough of an economic benefit nudge to get clients to say “I do.”
Considering a financial advisor who specializes in working with Tesla Employees?
Are you a financial advisor who specializes in working with employees at Tesla or another large company?
Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at Tesla or another large company. (Subject to availability and terms.) Sign up today and join financial advisors attracting their ideal clients on Wealthtender.
Ask a Financial Advisor Your Tesla Benefits & Career Questions
About the author
Founder & CEO and Editor-in-Chief, Wealthtender
Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.
Brian and his wife live in Austin, Texas.
Do you work at Johns Hopkins University?
Get expert insights from financial advisors who specialize in helping Johns Hopkins University faculty and staff make the most of their compensation package and benefits.
Looking for a financial advisor who specializes in working with Johns Hopkins University employees? You’re in the right place. Below, you’ll find advisors who understand Johns Hopkins University benefits and compensation — along with their answers to common financial questions from Johns Hopkins University faculty and staff.
Whether you recently joined Johns Hopkins University or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and Johns Hopkins University benefits can have a lasting impact on your financial future. For example:
- Do you know the right moves to get the greatest value from the Johns Hopkins University benefits available to you?
- If you’re thinking about leaving Johns Hopkins University for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?
Key Takeaways
Johns Hopkins University Provides Institutional 403(b) Contributions Regardless of Employee Participation
JHU contributes a percentage of eligible employees’ salaries directly into their retirement accounts even if employees make no personal contributions. Many employees don’t fully understand this benefit exists or haven’t reviewed how these institutional contributions are invested within TIAA or Fidelity platforms.
JHU’s Tuition Remission Benefit Can Be Worth Hundreds of Thousands for Families with College-Bound Children
The university offers tuition assistance for dependent children at JHU and through exchange programs at other participating institutions. This benefit fundamentally changes college funding strategies but requires planning around eligibility rules and interaction with federal financial aid.
Career Transitions from JHU Require Careful Timing Around Vesting Schedules and Benefit Conversions
Employees should audit vesting status across all benefit categories before resigning, as leaving before vesting milestones can mean forfeiting institutional contributions. Time-sensitive decisions include COBRA health coverage elections within 60 days and life insurance conversion options.
Why Johns Hopkins University Employees Work with a Specialist Financial Advisor
Throughout the year, Johns Hopkins University provides its faculty and staff with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 403(b), pension options, and other faculty and staff benefits. While the institution offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with Johns Hopkins University who specialize in helping Johns Hopkins University employees make the most of their income and benefits.
Whether you work at one of Johns Hopkins University’s offices, from a regional hub, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.
Sensitive topics — like the steps you should take before quitting your job at Johns Hopkins University to work elsewhere, protecting yourself in advance of a layoff or workforce reduction, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.
Should You Hire a Johns Hopkins University Specialist or a Local Financial Advisor?
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Johns Hopkins University employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with Johns Hopkins University employees is the better fit for your unique needs.
In the Q&A below, you’ll gain insights from financial advisors who work with Johns Hopkins University employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.
Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.
Q&A: Financial Planning Tips for Johns Hopkins University Faculty & Staff
In this section, you’ll learn how you can make the most of your Johns Hopkins University employee benefits and gain valuable tips from financial advisors who specialize in working with Johns Hopkins University faculty and staff.
Financial Advisor Q&A · Johns Hopkins University Employees
Jeff Judge, CFP®, AEP®, ChFC®, CLU®
Chesapeake Financial Planners · Maryland · Serves clients nationwide
Specializes in financial planning for Johns Hopkins University employeesJeff Judge is a financial advisor based in Maryland who specializes in offering financial planning services to Johns Hopkins University employees. Jeff helps clients get the most value from their Johns Hopkins University benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping Johns Hopkins University employees save for their retirement, how do you help them make the most of their employee benefits?
Johns Hopkins University offers one of the most comprehensive benefit packages of any employer in the Baltimore region, and helping employees fully leverage those benefits is one of the most rewarding parts of my work. Most JHU employees are enrolled in the university’s 403(b) retirement plan, administered through TIAA and Fidelity Investments, but simply being enrolled is not the same as having a strategy. I work with clients to evaluate their current contribution rate against JHU’s institutional contribution (the university contributes a percentage of salary to eligible employees’ retirement accounts regardless of whether the employee contributes anything themselves), their investment allocations within TIAA and Fidelity, and whether they’re making the most of the Supplemental Retirement Annuity (SRA) for additional voluntary savings. You can read more about our comprehensive planning approach at chesapeakefp.com.
Beyond the retirement plan itself, JHU’s benefits ecosystem includes meaningful health savings account options, tuition remission for employees and dependents, and life and disability coverage. I approach each JHU client’s situation holistically, looking at how each benefit layer interacts with their overall financial plan. A younger faculty member might prioritize maximizing the SRA and using tuition benefits for their children, while a senior researcher approaching retirement might focus on transitioning from salary-based cash flow to systematic withdrawals. The goal is always to make sure nothing is left on the table. JHU’s official benefits documentation lives at hr.jhu.edu/benefits.
I also stay current on changes JHU makes to its plan offerings, because investment lineups, matching structures, and plan rules can change and employees often don’t receive clear guidance on how those changes affect their strategy. Part of my value is serving as a translator between the complexity of a large institutional benefits package and the real-life financial decisions my clients need to make. For JHU employees who want to understand their full range of retirement savings options, the IRS publishes a helpful overview of 403(b) plans at irs.gov/retirement-plans.
QWhen you first speak with a Johns Hopkins University employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
The first conversation I have with a Johns Hopkins University employee is less about products or portfolios and more about context. I start by asking about their role at JHU, because there is a meaningful difference between the financial planning needs of a tenured faculty member, a postdoctoral researcher, a clinical staff member at Johns Hopkins Medicine, and an administrative professional. Each of these categories comes with different compensation structures, benefit eligibility, and career trajectory considerations. I also ask how long they have been at JHU, because benefit eligibility often vests over time and longevity affects decisions around legacy benefits, TIAA accumulations, and retiree health coverage.
I ask about family situation, including whether they have dependents who might benefit from JHU’s tuition remission program, which is one of the most financially significant but commonly underutilized benefits the university offers. I ask whether they have ever worked through their plan elections with any guidance, because in my experience, many JHU employees made initial enrollment decisions years ago and have not revisited them since. I also ask about income outside of JHU — a spouse’s employment, consulting arrangements, rental property — because JHU benefits have to fit into a complete household financial picture, not exist in isolation. Our initial consultation process is described at chesapeakefp.com.
Finally, I ask about goals in concrete terms: not just “retire comfortably” but what retirement age they are targeting, what lifestyle they envision, and whether they have obligations like parent support, education funding, or charitable giving that belong in the plan. This intake process has been refined over years of working with employees across the Baltimore metro area, and it produces a financial plan specific to a JHU employee’s actual life rather than a generic template.
QIs there a particular benefit available to Johns Hopkins University employees you feel isn’t as well utilized or understood by employees as it should be?
Without question, the benefit I see most consistently underutilized by Johns Hopkins University employees is the university’s institutional contribution to the 403(b) retirement plan. JHU contributes a significant percentage of an eligible employee’s salary directly into their retirement account, and this contribution occurs regardless of whether the employee contributes anything themselves. Many employees I speak with either do not fully understand this benefit exists, do not know how to find their current accumulation within TIAA or Fidelity, or have not reviewed the investment allocation those institutional contributions are going into in years. This is essentially free retirement savings growing in a default investment option that may or may not align with the employee’s actual risk tolerance or timeline. Full details on JHU’s retirement plan structure are at hr.jhu.edu/benefits.
The second most underutilized benefit I encounter is tuition remission for dependent children. JHU’s tuition benefit is extraordinary compared to what most employers offer, and through various tuition exchange programs, eligible children can receive assistance at participating institutions across the country as well. For employees with college-bound children, this benefit can be worth tens or even hundreds of thousands of dollars over time, but it requires planning around eligibility rules, interaction with federal financial aid, and how it factors into an overall college funding strategy.
The Supplemental Retirement Annuity is the third area I would flag. Many JHU employees are contributing at the minimum level without asking whether they could or should be contributing more. For mid-career employees especially, the SRA contribution space represents meaningful tax-advantaged savings capacity that often goes unused simply because no one has walked them through the math. The IRS publishes current 403(b) contribution limits, including catch-up provisions for employees age 50 and older, at irs.gov/retirement-plans.
QBeyond Johns Hopkins University employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients (e.g. stock, education savings, health savings)?
Johns Hopkins University’s non-retirement benefits are genuinely some of the strongest in the Baltimore region, and I make a point to discuss them in depth with every JHU client. Health savings accounts are a significant focus. JHU offers high-deductible health plan options that pair with an HSA, and many employees choose a traditional PPO plan by default without running the numbers on whether an HDHP and HSA combination might actually serve them better, both for current healthcare costs and long-term tax-free growth. A well-funded HSA used as a long-term investment vehicle rather than just a spending account is one of the most tax-efficient tools available, and JHU’s plan eligibility makes this possible for many employees. Current HSA contribution limits are published at irs.gov/publications.
Tuition remission is a benefit I return to frequently because the financial magnitude of it is rarely fully internalized. JHU offers tuition assistance for employees taking courses at the university, which is relevant for employees pursuing graduate degrees or professional development. But the dependent education benefit, which can provide tuition assistance for eligible children at JHU and through exchange programs at other participating institutions, is where the real financial planning conversation begins. For families with children ten or more years from college, the existence of this benefit fundamentally changes how aggressively to fund a 529 plan. Employees can review JHU’s tuition benefit details at hr.jhu.edu/benefits.
Life insurance and disability coverage are the benefits I find most likely to be accepted at face value without any analysis. JHU provides basic life and long-term disability coverage to eligible employees, but the group benefit structures do not always align with what a particular employee actually needs given their income, debts, dependents, and existing personal coverage. I review these alongside any individually owned policies my clients have to identify gaps or redundancies. For JHU employees who have the option of supplemental disability coverage, the decision of whether to elect it and at what level is worth a careful look. Our approach to comprehensive benefit planning for employees of major institutions is at chesapeakefp.com/services.
QFor Johns Hopkins University employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
Leaving Johns Hopkins University is a significant financial transition, and the preparation that happens in the months before a resignation can have a lasting impact. The first step I recommend is a thorough audit of vesting status across all benefit categories, including retirement plan contributions and any employer contribution matching, because leaving before a vesting milestone can mean forfeiting real money. JHU’s institutional 403(b) contributions vest according to a schedule, and employees should know exactly where they stand before finalizing the timing of their departure. I also recommend reviewing retiree health benefit eligibility rules, because some long-tenured JHU employees have access to retiree health coverage that may be forfeited if they leave before reaching a qualifying threshold.
For the retirement plan itself, JHU employees who leave have several options: leaving the balance in the TIAA or Fidelity accounts associated with the JHU plan (which may be permissible depending on balance size and plan rules), rolling the balance into an IRA for continued tax-deferred growth, or rolling it into a new employer’s plan. Cashing out should be avoided given the immediate tax liability and potential 10% early withdrawal penalty. A direct rollover is the preferred approach because it avoids mandatory 20% withholding. The IRS has a useful overview of rollover rules and direct transfer procedures at irs.gov/retirement-plans/plan-participant-employee/rollovers-of-retirement-plan-and-ira-distributions.
Shortly after leaving, I would prioritize a review of all benefits that have time-sensitive conversion or continuation windows. Health insurance through COBRA must be elected within 60 days of losing coverage. Life insurance policies through JHU may have portability or conversion options that expire quickly. FSA balances often have tight run-out periods. Employees who leave late in the calendar year should also think carefully about tax implications, because the timing of a final paycheck, accrued vacation payout, and any signing bonus from a new employer can create unexpected tax exposure in that tax year. I walk JHU clients through all of this in what I call a career transition planning session, which you can learn more about at chesapeakefp.com.
QFor Johns Hopkins University employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
The retirement income transition is one of the most psychologically and financially significant shifts a person makes, and for Johns Hopkins University employees, the planning typically starts five to ten years before the target date. The first priority is building a clear picture of what income will look like from day one of retirement. For most JHU employees, that means understanding their TIAA and Fidelity account balances, projecting what those balances can sustainably provide, determining their Social Security benefit at various claiming ages, and identifying any other income sources like a spouse’s retirement account, rental income, or part-time consulting. TIAA in particular offers annuity income options that can provide guaranteed lifetime income, and evaluating whether and how much to annuitize is a major planning decision that belongs in a formal retirement income plan. Our retirement planning process is outlined at chesapeakefp.com/services.
Social Security timing is a conversation I have with almost every pre-retirement JHU client. Claiming at 62, at full retirement age, and at 70 can result in meaningfully different monthly benefits, and the right choice depends on health, other income sources, marital status, and longevity assumptions. The Social Security Administration’s benefits estimator at ssa.gov/benefits/retirement/estimator.html is a useful starting point, but the optimization is more nuanced than the tool conveys. For married JHU employees especially, coordinating claiming strategies between spouses can add significant lifetime value to the household’s total Social Security benefit.
I also focus on expense and cash flow planning, because most people underestimate healthcare costs in the years between leaving work and Medicare eligibility at 65. JHU employees who retire before 65 need a clear plan for bridging health insurance coverage through COBRA, marketplace plans, or a spouse’s employer plan. A complete retirement income plan accounts for taxes on 403(b) distributions, required minimum distributions starting at age 73 under current law, and inflation over what could be a 20-to-30-year retirement. Getting these variables right at the outset makes a substantial difference in long-term financial security.
QFor Johns Hopkins University employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
Self-directed financial management works well for some people, and I genuinely respect that many Johns Hopkins University employees are highly educated and capable of handling their own finances. The honest question is not whether working with an advisor is universally necessary — it is whether the complexity of your specific situation has reached a point where outside expertise creates more value than it costs. A few honest self-assessments are worth doing. Can you clearly state your projected retirement income, accounting for your JHU 403(b) balance, Social Security, and any other sources? Do you have a written strategy for when to claim Social Security? Are your investment allocations within TIAA and Fidelity actually aligned with your risk tolerance and timeline, or are they where they were when you first enrolled?
JHU’s benefits package is genuinely complex. Between the 403(b), the SRA, tuition remission, HSA options, insurance elections, and any legacy benefit components, there are a lot of moving parts. Complexity tends to increase at predictable life stages: approaching retirement, receiving an inheritance, going through a divorce, having a child, or experiencing a significant income change. These are the moments when even financially literate people benefit from a second opinion. The CFP Board provides guidance on how to evaluate an advisor and what credentials to look for at cfp.net/find-a-cfp-professional, and SEC resources for evaluating investment advisors are at investor.gov.
I would also suggest that any JHU employee on the fence ask themselves what a mistake in this area would actually cost. Getting investment allocation wrong, claiming Social Security at the wrong time, or missing a benefit election window are not small errors — they can have permanent and compounding financial consequences. The cost of a comprehensive financial plan from a fee-based, fiduciary advisor is typically a fraction of the value created by avoiding one significant mistake. Our fee structure and planning process are described at chesapeakefp.com, and I am always happy to have an initial conversation with no obligation attached.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are Johns Hopkins University employees and how do you help them overcome these obstacles?
One of the most common challenges I see among Johns Hopkins University employees is what I would call the complexity gap: the disconnect between having strong benefits on paper and having any real strategy for using them. JHU’s benefit package is comprehensive, but it is administered across multiple providers including TIAA, Fidelity, and various insurance carriers, accessed through separate portals, with different vesting schedules and rules. Many employees have never seen a consolidated view of what they have. I address this by building a complete financial inventory at the start of our relationship, pulling together every account, benefit, and policy so the client can see the full picture in one place for the first time. More about how we approach this process is at chesapeakefp.com/services.
Income complexity is another recurring theme. JHU employs a large number of researchers, faculty, and clinical professionals whose compensation includes components beyond base salary: grants, consulting arrangements, summer salary for academic-year faculty, clinical revenue sharing at Johns Hopkins Medicine, and in some cases equity from spinout companies or licensing activity. Each income stream has different tax treatment and different implications for retirement savings capacity. A faculty member who earns consulting income can potentially open a SEP-IRA or solo 401(k) on top of their JHU 403(b), significantly expanding tax-advantaged savings. Identifying and acting on these opportunities is a meaningful part of the work I do with JHU clients.
A third challenge is the intersection of academic career trajectories and financial planning timelines. JHU employs many people who spent their twenties and early thirties in graduate programs and postdoctoral positions with limited income and no retirement savings. By the time they reach a tenured or permanent position with meaningful salary and strong benefits, they may be a decade behind peers in other industries who began saving in their mid-twenties. I help these clients build an accelerated savings strategy using the full range of available tools, including maximizing both the SRA and any outside savings capacity, structuring investments for appropriate growth given their compressed timeline, and setting realistic retirement expectations grounded in what the numbers actually support.
QWhat questions do you recommend Johns Hopkins University employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
The first question I would encourage any JHU employee to ask a prospective advisor is whether they have specific experience working with university employees or 403(b) plan participants. Working with a university’s 403(b) is meaningfully different from working with a corporate 401(k), and an advisor who primarily serves corporate clients may not have deep familiarity with TIAA’s annuity products, the nuances of academic compensation structures, or the specific benefit architecture JHU offers. Follow-up questions should include how the advisor is compensated (fee-only, fee-based, or commission-based) and whether they are a fiduciary who is legally required to act in the client’s best interest at all times. The SEC’s Investor.gov at investor.gov has helpful guidance on evaluating financial advisors, and FINRA’s BrokerCheck at brokercheck.finra.org allows you to verify credentials and review any disciplinary history.
Second, ask how they approach financial planning as distinct from investment management. Some advisors are primarily portfolio managers who treat financial planning as secondary. For a JHU employee trying to maximize a complex benefits package, optimize multiple savings vehicles, plan a retirement income strategy, and coordinate insurance coverage, investment management alone is not enough. The advisor should be able to describe a comprehensive planning process that covers retirement income, tax strategy, insurance, estate planning, and benefits optimization. Ask to see a sample financial plan, and ask how often the plan is reviewed and updated as your circumstances change.
Third, ask specifically how the advisor would approach your JHU benefits. A prepared, knowledgeable advisor should be able to speak fluently about the 403(b) plan structure, TIAA and Fidelity investment options, the institutional contribution, and the SRA. They should ask you pointed questions about your benefit elections and offer specific observations about whether your current setup appears optimized. If the advisor seems unfamiliar with JHU’s plan structure or suggests it is something to revisit later, that is a meaningful signal. The CFP Board’s advisor search tool at cfp.net/find-a-cfp-professional lets you find and verify credentialed planners in your area.
QIs there anything that comes up frequently in your initial meeting with Johns Hopkins University employees that surprises you?
The thing that surprises me most consistently is how rarely JHU employees have had a substantive conversation about money with anyone. Johns Hopkins employs some of the most accomplished people in the country — researchers, physicians, engineers, attorneys — and many of them have never sat down with a financial advisor, never reviewed their investment allocation with any real intention, and have only a vague sense of what their retirement accounts actually contain. There appears to be a pattern in highly educated professional environments where financial literacy is assumed but never explicitly developed, and where admitting uncertainty about personal finance feels inconsistent with professional identity. The result is that people manage something critically important on the basis of enrollment decisions made years or even decades ago.
The second thing that surprises me is how many JHU employees have never looked at their TIAA account in any meaningful way. TIAA is the primary retirement platform for higher education institutions, and it operates differently from the mutual-fund-based platforms most people are more familiar with. TIAA’s annuity products, including the TIAA Traditional, have guaranteed return components that function unlike anything else in a 403(b). Many JHU employees have significant balances in TIAA products they do not fully understand, and some do not know that certain TIAA products have restricted liquidity, meaning they cannot be moved freely without following a specific payout schedule. TIAA’s own educational resource center at tiaa.org is a useful starting point, and I walk new clients through these products as a foundational step.
A third recurring pattern is dual-income households where both spouses work at major institutions — Johns Hopkins University, Johns Hopkins Medicine, other universities, federal agencies, or large nonprofits — and have never coordinated their benefits or retirement savings across the household. Two sets of institutional contributions, two retirement accounts at different providers, two sets of insurance elections, and potentially two Social Security benefit strategies being managed completely independently of each other. The coordination opportunity in those situations is often the single highest-value conversation I have with a new client.
QFor highly compensated Johns Hopkins University employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?
Highly compensated Johns Hopkins University employees and executives face a distinct set of planning challenges and opportunities that go beyond standard benefit optimization. The most immediately relevant consideration is the IRS annual addition limit for 403(b) contributions, which for 2025 is $70,000 total including both employee and employer contributions for those under age 50, with additional catch-up provisions for older participants under SECURE 2.0. [Editor’s note: The limit is $72,000 for 2026, and the IRS raised it to $75,000 for 2027.] Once 403(b) contributions are maximized, the question becomes where to direct additional savings. Some JHU employees may have access to a 457(b) non-qualified deferred compensation plan, which is an important tool at this income level because it carries an entirely separate contribution limit and allows for significant tax deferral on income that would otherwise be taxed in the current year. The IRS overview of 457(b) plans is at irs.gov/retirement-plans/irc-457b-deferred-compensation-plans.
Highly compensated JHU employees should also be aware of how their income level interacts with other planning opportunities. At higher income levels, traditional IRA deductibility phases out, Roth IRA direct contributions phase out (though backdoor Roth strategies remain available for many), and certain tax credits become unavailable. Tax-efficient asset location, meaning the deliberate decision of which types of investments belong in tax-advantaged accounts versus taxable accounts, becomes increasingly valuable as income rises. For faculty or researchers with consulting income or intellectual property licensing revenue, there may be additional self-employment savings capacity through a SEP-IRA or solo 401(k) running parallel to the JHU 403(b), and identifying that capacity is a significant planning opportunity. Our approach to high-income financial planning is at chesapeakefp.com/services.
At the executive level, compensation may include components requiring specific financial planning treatment: deferred compensation arrangements, supplemental retirement plans, or in some cases equity interests in spinout companies connected to university research. These situations often carry significant complexity around timing of income recognition, tax exposure, and concentration risk. I also focus on insurance adequacy for high-income JHU professionals, because the standard group life and disability coverage JHU provides is calculated on compensation formulas that may be structurally insufficient for someone with a large income, significant financial obligations, and dependents who have built a lifestyle around that income level. Individually owned coverage often needs to fill material gaps.
QIs there a particularly memorable experience or a moment you recall with a client who worked at Johns Hopkins University when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?
There was a client I worked with who had been a senior researcher at Johns Hopkins for over twenty years. When we first sat down together, she walked me through her financial life with the kind of systematic precision you would expect from someone who had spent decades in scientific research. She had her salary information, her account statements, her insurance policies — everything organized and ready. But when I asked her what she expected her monthly income to look like in retirement, she paused in a way I will never forget and said, “I assumed I would figure that out when I got there.” Here was someone with a distinguished research career, significant retirement savings built up over twenty years of disciplined contributions, and access to one of the best university benefit packages in the country — and she had never had anyone help her connect those pieces into an actual income strategy.
What made her situation particularly compelling was the combination of a substantial TIAA accumulation she had never fully analyzed, a Social Security benefit being shaped in real time by choices she was still making, tuition remission benefits for two college-bound children that had never been factored into her savings rate, and consulting income from a private sector advisory role that had never been captured in any retirement savings vehicle. There were four or five significant financial planning opportunities in her picture that had simply never been acted on because no one had ever mapped them out together in one place. That experience crystallized for me why JHU employees in particular — who are often incredibly capable and organized in their professional domains — benefit so much from having a financial planning partner. More on how we approach these discovery conversations is at chesapeakefp.com.
The moment I return to most often is not when we finalized her plan. It was when we finished the initial inventory session and I showed her the projected monthly income from her existing accounts alongside her Social Security benefit at her target retirement age. She had assumed she was behind. She was not. She had quietly built a strong foundation over twenty years of consistent saving, and the work ahead was optimization and coordination, not rescue. That is actually a common story among long-tenured JHU employees: more has been accumulated than they realize, and the planning work is about making sure it is structured to serve them well in retirement.
Considering a financial advisor who specializes in working with Johns Hopkins University employees?
Are you a financial advisor who specializes in working with employees at Johns Hopkins University or another large company?
Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at Johns Hopkins University or another large company. (Subject to availability and terms.) Sign up today and join financial advisors attracting their ideal clients on Wealthtender.
Ask a Financial Advisor Your Johns Hopkins University Benefits & Career Questions
About the author
Founder & CEO and Editor-in-Chief, Wealthtender
Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.
Brian and his wife live in Austin, Texas.
Do you work at Raytheon Technologies (RTX)?
Get expert insights from financial advisors who specialize in helping Raytheon Technologies (RTX) employees and executives make the most of their compensation package and benefits.
Looking for a financial advisor who specializes in working with Raytheon Technologies employees? You’re in the right place. Below, you’ll find advisors who understand RTX benefits and compensation — along with their answers to common financial questions from Raytheon Technologies employees and executives.
Whether you recently joined Raytheon Technologies or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and RTX benefits can have a lasting impact on your financial future. For example:
- Do you know the right moves to get the greatest value from the Raytheon Technologies benefits available to you?
- If you’re thinking about leaving Raytheon Technologies for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?
Key Takeaways
RTX Pension Benefits Were Restructured Around the 2020 Merger, and a Lump Sum Moves With Interest Rates
Longer-tenured Raytheon and United Technologies employees may hold pension benefits split across a frozen formula and a newer cash balance formula, each calling for a different strategy. The advisors below explain that a lump-sum figure is calculated from IRS segment rates published monthly, so the quarter you retire in can change that number materially — independent of anything about your own situation.
The Mega Backdoor Roth Is the Most Commonly Missed Opportunity in the RTX Savings Plan
After-tax contributions converted to Roth inside the plan are not something every employer’s 401(k) permits. Multiple advisors below describe experienced, well-informed savers who had never heard of it — and years of eligibility that cannot be recovered once they have passed.
Concentration Risk Compounds When Company Stock Sits Inside the 401(k)
RTX shares held in the retirement plan can carry a low cost basis and a potential net unrealized appreciation opportunity at retirement, while simultaneously representing a concentrated bet alongside career income and equity grants. The advisors below treat the tax benefit and the concentration as one decision rather than two.
Why Raytheon Technologies Employees Work with a Specialist Financial Advisor
Throughout the year, Raytheon Technologies provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to the RTX Savings Plan and deferred compensation, along with equity compensation such as restricted stock units, performance share units, stock appreciation rights, and an employee stock purchase plan. Longer-tenured employees may also hold pension benefits that were restructured around the 2020 merger of Raytheon Company and United Technologies. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with RTX who specialize in helping Raytheon Technologies employees make the most of their income and benefits.
RTX runs its corporate headquarters in Arlington, Virginia, and each of its three businesses keeps a headquarters of its own: Raytheon in Arlington, Collins Aerospace in Charlotte, North Carolina, and Pratt & Whitney in East Hartford, Connecticut. Most employees, though, work at engineering, program, and manufacturing sites well away from those four addresses. Whether you work at a business headquarters, at a program site elsewhere in the country, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.
Sensitive topics — like the steps you should take before quitting your job at Raytheon Technologies to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.
Should You Hire a Raytheon Technologies Specialist or a Local Financial Advisor?
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Raytheon Technologies employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with RTX employees is the better fit for your unique needs.
In the Q&A below, you’ll gain insights from financial advisors who work with Raytheon Technologies employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.
Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.
Q&A: Financial Planning Tips for Raytheon Technologies Employees & Executives
In this section, you’ll learn how you can make the most of your Raytheon Technologies employee benefits and gain valuable tips from financial advisors who specialize in working with RTX employees and executives.
Jump to a Financial Advisor for Raytheon Technologies Employees
Financial Advisor Q&A · Raytheon Technologies Employees
Allen Mueller, CFA, CFP®
7 Saturdays Financial · Dallas, TX · Serves clients nationwide
We help lifelong savers retire and spend with confidenceAllen Mueller is a financial advisor based in Richardson, Texas, who specializes in offering financial planning services to Raytheon Technologies (RTX) employees. Allen helps his clients get the most value from their Raytheon Technologies benefits and compensation package so they can enjoy life and feel confident about their financial future.
QIs there a particular benefit available to Raytheon Technologies employees you feel isn’t as well utilized or understood by employees as it should be?
A huge benefit to Raytheon employees is the RAYSIP retirement plan which allows pre-tax, Roth, or after-tax contributions. In 2022, a high saver who wants to maximize their tax-advantaged accounts can contribute $20,500 to their pre-tax 401(k) ($27,000 if over age 50). On top of that, they can contribute about $40,000 to the after-tax 401(k) and convert that amount to Roth with an in-service conversion. This strategy, also known as the “Mega Backdoor Roth”, is popular among those who are above the income threshold to contribute to a Roth IRA. [Editor’s note: For 2026, the pre-tax limit is $24,500 ($32,500 at 50 or older) and the total cap is $72,000; for 2027, the IRS raised them to $25,500 ($34,000) and $75,000.]
QBeyond Raytheon Technologies employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?
Raytheon healthcare plans are typically HSA eligible which means maximum account contributions of $3,650 for individuals or $7,300 for families (2022 values). [Editor’s note: For 2026, HSA limits are $4,400 for individuals and $8,750 for families, rising to $4,500 and $9,000 in 2027.] The HSA is a fantastic way to lower taxable income at contribution, the money can be invested to grow tax-free, and withdrawals are tax-free if used for eligible medical expenses. Bonus points – the contributions to an HSA get to dodge Social Security and Medicare taxes if funded through payroll contributions. Building up a massive HSA balance can be an effective way to pay for Medicare premiums in retirement or self-insure for long-term care (LTC).
Another fantastic benefit is the group legal plan – a very cost-effective way to get estate planning documents like wills and trusts drafted for about $240. Normally, these documents cost several thousand dollars. Employees can choose the plan during open enrollment, pay for a year of the service, get documents created, and decline coverage during the next year’s open enrollment.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are Raytheon Technologies employees, and how do you help them overcome these obstacles?
A common challenge among Raytheon employees, particularly those who are entering retirement, is the large tax-deferred balances in their 401(k) plans. If not mitigated, Required Minimum Distributions (RMDs) can cause a massive tax bill after age 72.
It’s important for retirees to work with a competent financial planner and develop a strategy to get ahead of RMDs during lower-income years. Typically implemented in the “tax planning window” between retirement and age 72, tools can include Roth conversions, delaying Social Security, and withdrawing from taxable accounts.
QWhat questions do you recommend Raytheon Technologies employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
Questions to ask a potential advisor include:
- Do you act as a fiduciary (in my best interest) at all times?
- How are you compensated? Do you sell any products?
- How much (in dollars) can I expect to pay now and in the future?
- Do you require me to move my assets, or can you provide advice only without investment management?
- Do you focus solely on investments, or do you also advise on other important areas like tax planning, estate, retirement, debt/cash flow management, and insurance?
- What is your investment philosophy?
- What professional credentials do you hold?
Considering a financial advisor who specializes in working with Raytheon Technologies Employees?
Financial Advisor Q&A · Raytheon Technologies Employees
Jeffrey Davis, AAMS®
ONE Advisory Partners · Santa Barbara, CA · Serves clients nationwide
Wealth Strategies for Successful, Busy ProfessionalsJeffrey Davis is a financial advisor based in Santa Barbara, California who specializes in offering financial planning services to Raytheon employees. Jeffrey helps his clients get the most value from their Raytheon benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping Raytheon employees save for their retirement, how do you help them make the most of their employee benefits?
When working with Raytheon employees, I start by helping them understand the full scope of their benefits package—because maximizing retirement readiness begins with leveraging what’s already available. I focus on strategies that integrate the Raytheon savings plan (such as the RTX 401(k) with potential employer match), as well as supplemental benefits like the Employee Stock Purchase Plan, all within a broader financial plan.
We explore contribution limits, Roth versus traditional deferrals, and tax-efficient withdrawal strategies to enhance long-term growth potential. I also guide clients through decisions around pension options and deferred compensation, ensuring they align with their broader retirement goals and cash flow needs. Ultimately, I tailor each strategy to the individual’s career stage and life priorities, bringing clarity to complex choices and helping them confidently move toward financial independence.
QWhen you first speak with a Raytheon employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
When I first meet with a Raytheon employee, my goal is to understand both their financial picture and what truly matters to them—because a great plan is built around purpose, not just numbers.
I typically start with questions like:
- What areyour short-term and long-term goals—both personally and financially?
- How confident do you feel about your current retirement strategy?
- Are you aware of all the benefits available to you through Raytheon, and are you using them to their full advantage?
- Do you have other financial priorities right now, like college savings, buying a home, or reducing taxes?
I also want to understand any life transitions on the horizon—whether it’s a career change, relocation, or family event—so we can anticipate and plan proactively.
These conversations often uncover opportunities to optimize their current benefit elections, adjust savings strategies, or build in tax-efficient planning. Ultimately, it’s about crafting a plan that’s aligned with their values, evolves with their life, and gives them peace of mind.
QIs there a particular benefit available to Raytheon employees you feel isn’t as well utilized or understood by employees as it should be?
One particularly powerful but underutilized benefit available to Raytheon employees in 2025 is the ability to implement a backdoor Roth strategy through the RTX 401(k) Plan (RAYSIP).
Raytheon allows employees to make after-tax contributions beyond the standard pre-tax and Roth limits—up to the 2025 total contribution cap of $70,000 (or $81,250 for ages 60–63 with catch-ups). These after-tax dollars can then be converted to Roth within the plan, creating a significant opportunity for long-term, tax-free retirement growth. Despite its potential, many employees overlook this option due to its complexity or lack of awareness. [Editor’s note: For 2026, the total cap is $72,000 ($83,250 at ages 60 to 63); for 2027, it rises to $75,000 ($86,750).]
Another valuable and often overlooked benefit is the MetLife Group Legal Plan, still available in 2025. For a modest monthly payroll deduction (typically $16–$20/month), Raytheon employees can access estate planning services like wills, trusts, and powers of attorney at no additional cost. It also covers a wide range of personal legal matters—without deductibles or copays when using in-network attorneys.
Both benefits can make a meaningful difference when incorporated into a thoughtful, comprehensive financial strategy. Helping employees understand and confidently navigate these opportunities is a key part of the work I do.
QBeyond Raytheon employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?
Absolutely—beyond retirement savings, Raytheon offers several benefits that can significantly enhance a client’s financial well-being when integrated into a broader plan.
One standout is the Employee Stock Purchase Plan (ESPP), which allows employees to purchase RTX stock at a 15% discount through payroll deductions. This can be a powerful tool for long-term wealth accumulation, especially when paired with a disciplined diversification strategy.
Raytheon’s Employee Scholar Program is another exceptional benefit. It provides 100% reimbursement for tuition, books, and fees for approved degree programs—with no cap on the number of degrees. For clients looking to advance their careers or pivot professionally, this is a tremendous value.
The Health Savings Account (HSA), available with Raytheon’s high-deductible health plans, is also worth highlighting. Contributions are triple tax-advantaged, and Raytheon contributes to the account as well. For clients who can afford to pay current medical expenses out of pocket, the HSA becomes a stealth retirement account for future healthcare costs.
Lastly, the MetLife Group Legal Plan continues to be a cost-effective way for employees to access estate planning services like wills and trusts—services that are often overlooked but critically important.
These benefits often go underutilized simply because they’re not well understood. I help clients evaluate which ones align with their goals—whether that’s reducing taxes, funding education, or protecting their family’s future.
QFor Raytheon employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
For Raytheon employees nearing retirement, the transition from a steady paycheck to drawing income from various sources requires careful planning and coordination. I guide clients through a multi-step process that helps them feel confident and in control of this next chapter.
We start by mapping out all available income streams—401(k), pension (lump sum or annuity), Social Security, brokerage accounts, and any deferred compensation. From there, we build a tax-efficient withdrawal strategy that balances income needs with long-term sustainability.
One key opportunity is to take advantage of the ‘income valley’—the window between retirement and the start of required minimum distributions (RMDs). During this period, we often implement Roth conversions, harvest capital gains at favorable rates, or draw down taxable assets to manage future tax brackets.
We also evaluate healthcare coverage, including retiree medical benefits and Medicare timing, and ensure estate planning documents are up to date.
Ultimately, it’s about replacing the predictability of a paycheck with a well-structured income plan that aligns with their lifestyle, values, and legacy goals. I help clients make this shift with clarity and confidence—so they can focus on enjoying the freedom they’ve worked so hard to earn.
QFor Raytheon employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
For Raytheon employees who’ve done a great job managing their finances independently, the decision to work with a financial advisor often comes down to complexity and confidence. As they near retirement or experience major life transitions, the stakes get higher—and so does the value of having a second set of eyes.
I encourage them to consider a few key questions:
- Are you confident in your retirement income strategy—including how and when to draw from your 401(k), pension, and Social Security?
- Have you evaluated the tax impact of your decisions, including Roth conversions, RMDs, and capital gains?
- Do you have a plan for healthcare costs, estate planning, and legacy goals?
- Are you making the most of Raytheon’s more advanced benefits—like deferred compensation, the backdoor Roth strategy, or the ESPP?
QWhat are some of the unique financial planning challenges you commonly see among your clients who are Raytheon employees and how do you help them overcome these obstacles?
Raytheon employees often encounter unique planning challenges that stem from the structure of their compensation, evolving retirement benefits, and the tax implications of various elections. One common issue is navigating the transition from legacy pension plans to cash balance plans following the merger with United Technologies. Many employees are unsure how to weigh lump sum versus annuity options, or how these fit into their broader retirement income strategy.
Another challenge is the underutilization—or mismanagement—of advanced savings opportunities like after-tax 401(k) contributions and in-plan Roth conversions. While Raytheon offers the ability to implement a backdoor Roth strategy, many employees either miss the conversion step or don’t understand the tax implications, which can lead to missed opportunities or unintended tax bills.
Deferred compensation planning is also a key area of concern, especially for higher-level employees. Elections must be made well in advance and are irrevocable, so aligning those decisions with future cash flow needs and tax brackets is critical.
Finally, equity compensation—such as RSUs and ESPP participation—can create concentrated stock risk and unexpected tax consequences if not managed proactively.
I help clients overcome these challenges by building integrated plans that coordinate all these moving parts. We model different scenarios, optimize tax strategies, and ensure that each decision—from pension elections to stock diversification—is aligned with their long-term goals. The goal is to bring clarity to complexity and help them make confident, informed choices.
QWhat questions do you recommend Raytheon employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
I always encourage Raytheon employees to ask prospective financial advisors questions that go beyond investment performance. The goal is to find someone who understands the nuances of Raytheon’s benefits and can provide truly personalized guidance. Here are a few key questions to consider:
- Do you have experience working with Raytheon employees or are you familiar with the RTX Savings Plan, pension options, and deferred compensation?
- Do you act as a fiduciary at all times—and can you explain what that means in practice?
- How are you compensated? Are there any commissions or product sales involved?
- Can you help me with more than just investments—like tax planning, estate strategies, and benefit elections?
- What is your process for building a retirement income plan that includes my 401(k), pension, Social Security, and other assets?
- How do you stay up to date on changes to Raytheon’s benefits and the broader financial landscape?
- What kind of ongoing support and communication can I expect from you?
These questions help uncover whether an advisor is not only technically competent but also aligned with your values, communication style, and long-term goals. It’s about finding a partner—not just a portfolio manager.
QIs there anything that comes up frequently in your initial meeting with Raytheon employees that surprises you?
One thing that frequently comes up—and surprises both me and the Raytheon employees I meet with—is just how underutilized and complex their benefits package can be, especially for those who’ve spent years with the company.
Many are unaware of advanced planning opportunities like after-tax 401(k) contributions and in-plan Roth conversions (a backdoor Roth strategy), or they haven’t evaluated deferred compensation elections, which require early, irrevocable decisions that can significantly impact future cash flow and taxes.
Pension decisions are another common challenge—particularly for employees navigating the transition from legacy defined benefit plans to cash balance formats after the Raytheon–UTC merger. Choosing between lump sum and annuity options often comes with uncertainty and wide-ranging financial implications.
It’s also surprising how many employees have accumulated substantial retirement savings but haven’t yet mapped out a coordinated withdrawal strategy—one that aligns income sources like 401(k), pension, and Social Security while managing taxes across retirement.
Lastly, I often discover that clients are paying into the MetLife Legal Plan but haven’t taken advantage of the included estate planning services such as wills, trusts, and powers of attorney.
These realizations can be eye-opening—and they reinforce how valuable it is to work with someone who can integrate all these moving parts into a cohesive, personalized strategy.
QFor highly compensated Raytheon employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?
For highly compensated Raytheon employees and executives, there are several specialized benefits that warrant close attention when building a comprehensive financial plan.
One of the most impactful is the RTX Compensation Deferral Plan, which allows eligible employees to defer salary, bonuses, and other compensation beyond IRS limits. This can be a powerful tool for managing taxable income and aligning cash flow with future retirement needs. Timing and structure are critical, as elections must be made in advance and are irrevocable.
Executives may also receive Performance Share Units (PSUs), Restricted Stock Units (RSUs), and Stock Appreciation Rights (SARs) through Raytheon’s Long-Term Incentive Plans. These awards come with vesting schedules, tax implications, and concentration risk—especially when combined with 401(k) holdings and ESPP participation. I help clients evaluate when to exercise, diversify, or hold based on their broader portfolio and tax strategy.
Additionally, Raytheon offers a Lifetime Income Strategy (LIS) within the 401(k) plan, which provides guaranteed income options. While this can be attractive for some, it may limit flexibility and preclude strategies like Net Unrealized Appreciation (NUA), so it’s important to assess fit on a case-by-case basis.
Finally, executives should consider supplemental disability insurance and legal benefits that go beyond standard offerings, especially given income levels that exceed base policy caps.
These benefits can be incredibly valuable—but only when integrated thoughtfully into a broader plan that considers taxes, timing, and long-term goals.
QIs there a particularly memorable experience or a moment you recall with a client who worked at Raytheon when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?
One particularly memorable experience was working with a long-tenured Raytheon engineer who was approaching retirement and had accumulated a significant balance across multiple benefit plans—including a legacy pension, after-tax 401(k) contributions, deferred compensation, and unexercised stock options.
What stood out was how unaware he was of the tax implications tied to each of these accounts. For example, he hadn’t yet initiated in-plan Roth conversions on his after-tax 401(k) contributions, which meant he was missing out on a powerful backdoor Roth opportunity. He also hadn’t considered how his deferred compensation payouts would overlap with required minimum distributions, potentially pushing him into a much higher tax bracket.
Through our planning process, we were able to model different income scenarios, optimize the timing of his pension election, and implement a multi-year Roth conversion strategy during his lower-income retirement window. We also helped him diversify out of concentrated RTX stock positions and take advantage of the MetLife Legal Plan to update his estate documents.
That experience reinforced how uniquely complex—and potentially rewarding—Raytheon’s benefits can be when integrated thoughtfully. It also highlighted the value of proactive planning, especially for employees who’ve done a great job accumulating assets but haven’t yet mapped out how to turn them into a sustainable, tax-efficient retirement income.
Considering a financial advisor who specializes in working with Raytheon Technologies Employees?
Financial Advisor Q&A · Raytheon Technologies Employees
Joseph Boughan, CFP®
Parkmount Financial Partners · Scituate, MA · Serves clients nationwide
Fee-only, fiduciary financial planning for busy professionals and familiesJoseph Boughan is a financial advisor based in Scituate, MA who specializes in offering financial planning services to Raytheon Technologies employees. Joseph helps clients get the most value from their RTX benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping Raytheon Technologies employees save for their retirement, how do you help them make the most of their employee benefits?
Over the years I’ve worked with a lot of employees at Raytheon Technologies. It all starts with having critical knowledge of the benefits that are available to Raytheon employees. There are a couple that seem to be more useful and more valuable for a lot of people. For example the HSA plan: depending on your situation you might choose the silver or gold. Both plans let you contribute to an HSA, which is one of the only accounts that’s pre-tax going in, grows tax-free, and comes out tax-free for qualified expenses — a real triple benefit most people don’t get anywhere else. Being able to understand where that’s valuable in the client’s life, either for the near term or long term, and possibly helping them to set up a systematic investment plan for their HSA is valuable.
There are also other tools available to everyone, like the backdoor or mega backdoor Roth. It is an interesting financial long-term opportunity for investing and tax efficiency for retirement. This can be a great tool for people looking to retire maybe a little bit earlier and save a little bit more than the average person for their retirement.
Separately there is a series of healthcare benefits for retirees available to Raytheon employees. Knowing about those and maximizing those is pretty key. For employees that have been with Raytheon for a while, there may be some employees that have different retirement packages, which might include pensions. Understanding how those pensions interact with the other pieces of their retirement portfolio (so they can know when they might be able to retire and how much they need to be saving to be on track to retire when they’d like to) is very significant. It is a very significant piece of their overall financial situation and not factoring that in improperly can lead to maybe retiring a lot later than you needed to or possibly missing other opportunities (whether that be from a tax or investment standpoint) that could be valuable to you.
Lastly is the 401(k) investments. There are also a lot of 401(k) investments. There are actually what I would consider poor investments in the 401(k) that are available and really strong, low-cost, valuable investment opportunities. Getting the right mix is important because it could be a very big piece of their portfolio. That’s on top of the RTX Savings Plan’s own moving parts — the tiered company match, the age-based Company Retirement Contribution that shows up whether you contribute or not, and for longer-tenured employees, company stock sitting inside the plan that can come with real tax planning opportunities like NUA at retirement. Making sure that some discipline is applied to how that’s invested can really make a long-term difference and make sure nothing is missed out on in terms of potential there.
Those are some of the most common ones. There are also separate benefits for executives. For example executives may have some opportunity to decide whether or not they want to contribute or receive stock appreciation rights or stock shares. Helping to navigate the different risk, investment, and financial planning implications of those can be really valuable. For employees that are highly compensated, navigating the deferred compensation and how that might be useful versus what is heavily dependent on the lifecycle of where the employee is relative to their goals, their retirement, and their financial path in life is valuable.
QWhen you first speak with a Raytheon Technologies employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
Honestly when it comes to Raytheon employees, I know there are very unique aspects to their career that they are navigating. It’s about just understanding what’s important to them in terms of what is the money for? For most people, obviously, it’s going to be retirement. There may be very unique other aspects of their life and lifestyle. Those will help us understand what is going to be the shape of their plan: when they’ll need that money and how much risk they’re comfortable taking in order to achieve their long-term goals. What is the trajectory of their career or their family and how is that going to influence this plan?
Understanding these is the most fundamental component to building the financial plan. Before we can even determine which opportunities financially out there (in terms of investments, employee benefits, or tax planning techniques) may be most relevant, we have to first determine who we’re talking to. Then we can back into what’s going to help them along their path the best way possible.
QIs there a particular benefit available to Raytheon Technologies employees you feel isn’t as well utilized or understood by employees as it should be?
I think the mega backdoor Roth is one that is underutilized. Oftentimes I will run into employees that have saved so much over their lifetime and they never even knew about it even though they knew a lot about investing and taxes in general. If they didn’t take advantage of that over the number of years, that could be a huge missed opportunity. It’s not something every employer’s 401(k) even allows, but Raytheon’s does, which is exactly why it’s worth flagging early. Depending on how many years someone’s been eligible and how much they’d otherwise be saving into a taxable brokerage account instead, the tax savings can add up to a meaningful amount over a career. Not to say that there’s not a place for a brokerage account, because I think both make sense, but that’s one of the big ones.
I think, separately, another benefit that Raytheon employees could be using more than they do is the legal plan available through the benefits. More often than not when I’m first speaking to someone, they do not have the appropriate estate planning in place. The legal benefits available when you sign up for your employee benefits can cover that, right? That’s just an opportunity.
A lot of people even sign up for this with the intention to do it and then forget to do it. Obviously it’s an emotionally challenging topic to confront: the potential for death. Getting a will in place is something that almost everyone needs to do and so really making it more of a priority is the key here. When you’re paying for it you have an incentive. Otherwise that’s just wasted money. Might as well go ahead and get your value for what you’re putting aside for that.
QBeyond Raytheon Technologies employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients (e.g. stock, education savings, health savings)?
The health savings account is great. A lot of people do know about that so it’s not necessarily totally unheard of. There are two different types of Plans that qualify for HSA.
I typically say that for families or people that are married with kids, or if they’re single and they have more health concerns, probably the gold HSA plans are the strongest option (because they keep the deductible relatively low while still qualifying as a technically high-deductible plan).
They allow you to contribute to your HSA and also get that employer HSA contribution to that account, which is good.
If you’re single or you’re married with no kids that are on your health plan and you’re both in good health, you might do the silver plan to just keep your premiums really low. That also, I think, can be good for some people.
In some situations you might want to do the other plans and forgo the HSA. I know some people are just not comfortable with a higher-deductible plan and prefer to have a lower deductible. Even if the costs and economics work the same, it’s just psychologically easier for them to stomach just paying a flat rate and not having too many surprises, even if the flat rate is a lot higher.
Also for people planning for retirement, you can’t contribute to an HSA if you’re on Medicare. Those are other things to be aware of. That’s another reason why you might shift to a lower-deductible plan and not contribute to that.
For executives there’s a couple of things. There’s a whole different set of things, like possibly using stock appreciation rights as opposed to stock grants, as an opportunity for some people to at least consider different risks and rewards.
Of course tuition reimbursements are also a great opportunity for anyone really looking to progress their career to have the company contribute to your growth and development by taking different certificate programs and stuff like that that you can qualify for.
QFor Raytheon Technologies employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
For Raytheon employees thinking about leaving the company and accepting a job elsewhere, the important thing is just understanding your cash flows.
When you do change jobs you might be contributing to a 401(k) from your previous employer. If it’s mid-year you might have a brand-new 401(k). Making sure you don’t overcontribute is a key piece of how that is going to all shape up because if you overcontribute you could be subject to penalties. No one’s going to be keeping track of your 401(k) contributions for the year from your previous employer so you have to be responsible for that.
Separately there may be duplications in taxes that you might face if you’ve already exceeded the Social Security tax limit. You may be paying twice into that system so you may get a larger refund. Just being aware of that.
When you do sign up for a new employer, if you’ve been at your current employer for a while, you have to remember to set up your tax withholding correctly. If you’ve got family (or I suppose that works) or something special about your taxes, you may need to set up a specialized withholding schedule in order to not get surprised with taxes at your new job.
Consider if you’re receiving some sort of severance package from Raytheon. What to do with that? How are you going to be receiving that and what are the implications from a tax standpoint and a cash management standpoint? You don’t want that money just sitting in your checking account if it’s not something you need immediately. If you have another job lined up you might consider what the best use of that capital is, which could be a variety of different things, putting that into the context of your long-term plans.
Lastly and maybe most importantly, determining what the change is going to be in your household income, what you contribute to your retirement savings, and how that all fits into a broader financial plan for your most important life objectives is the main consideration you need to make.
QFor Raytheon Technologies employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
When they’re approaching retirement age you really need to start factoring in:
– How much you’re going to need to have saved and invested
– How your investments need to be positioned
– What to do about your tax planning
These are the big three pieces and most importantly how much you need to have saved and invested, depending on your career. If you spent a lot of time at Raytheon, people who have been there for 20+ years probably have a pension. That means that’s going to be a big part of their overall retirement strategy. That’s just income that’s coming in on top of Social Security, which means the gap for the income that they’ll probably need to fill with sustainable portfolio withdrawals is a lot smaller, meaning their portfolio might need to be smaller.
One thing that catches people off guard: if you’re deciding between the lump sum and the monthly annuity, the lump sum isn’t a fixed number sitting there waiting for you — it’s calculated off IRS segment rates that get published monthly and move with the bond market. When those rates go up, the lump sum value goes down, and vice versa, so the specific quarter you retire in can swing that number by a meaningful amount, completely separate from anything about your own situation. It’s also worth knowing that RTX has been actively moving pension risk off its own books — they transferred a chunk of retiree obligations to Prudential in an annuity buyout that closed at the end of 2025 — so this is a plan sponsor that’s clearly thinking about de-risking, which is one more reason to have a real analysis done rather than defaulting to whichever option sounds simpler.
For those types of people, thinking about rules of thumb that they might need and that they read on the internet about how much people need to save for retirement might be completely different. It’s important to take an assessment of all your different resources, including income sources for you and investments for you and for your spouse, or any other pieces of your situation that may need to be factored in separately. If they determine what they need to have saved and invested, they might find that they have a couple years to go in order to get to a good place. There can be different adjustments that can help a client along that path. That’s where the investment and planning, from a tax standpoint or healthcare standpoint, come in.
On the healthcare side, if you’re retiring before 65, you’re bridging to Medicare somehow — COBRA, a retiree medical option if it’s available to you, or the marketplace — and that gap needs its own line item in the plan rather than an afterthought. On the tax side, the years between when you stop working and when Social Security and required distributions kick in are often the best window you’ll ever get for Roth conversions, since your income is naturally lower before those other sources turn on. Coordinating that with the pension election and when you start drawing from the portfolio is where a lot of the real value gets added.
Determining what the game plan is from here, just based on what you’re currently doing and where you need to be, what the right set of tools is that you should be using, and what the trade-offs of using them are, a financial planner can help them do that. If they have a really in-depth level of personal investment knowledge, healthcare planning knowledge, or tax planning knowledge, they can probably do a lot of things on their own. It might still help to work with a financial planner to streamline that process or add any pieces of expertise that they may need as they’re trying to make critical life decisions with the big retirement on the horizon.
QFor Raytheon Technologies employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
Yeah obviously it costs something to work with an advisor, right?
They need to be comfortable with the value that they’re going to get out of that. I would think it’s hard to oftentimes just translate a service into something that’s really tangible although a lot of it can be measured.
Think about the following common reasons people choose to work with an advisor:
- Are they looking for the financial optimization of getting additional expertise and analysis of their situation?
- Are they trying to make decisions and finding it difficult?
- Are they facing change that is challenging to navigate without a clear financial plan?
- Are they looking for help with retirement?
- Are they just looking to get more time back on their schedule?
There’s also just the value of having someone in your corner who understands and has a lot of knowledge about you and the broader options and possibilities you face. They can help you with those decisions using their planning, judgment, and expertise layered on top of you.
The question becomes, “can the person you choose be empathetic, and capable of really putting themselves in your shoes?”
Part of it is going to be just understanding the landscape of options that they face. One of the big pieces that they really need to watch out for is all the different models of financial services.
It’s critical to understand the difference between a fee-based advisor who may be double dipping in terms of how they’re getting compensated (from commissions and products that they’re selling, but also from fees from the client) and a fee only advisor. This double-dipping has the potential to introduce additional conflicts of interest to an advisory relationship. It may bias the advisor to putting a compensation schedule ahead of what may be truly in the client’s interests. That doesn’t always mean actually recommending a bad product but it just may steer the discussion away from what the client might need the most help with (such as areas that don’t offer commissions, like tax planning or helping with Medicare planning decisions).
It’s not to say that that’s always going to completely ruin the ability to have a productive advisory relationship but there are other options that people need to be aware of. Using a fee-only advisor would be one way to help reduce the conflicts of interest. Once someone’s already decided to work with an advisor, going fee-only just means fewer conflicts sitting between you and the advice — which makes for a more collaborative relationship, since the advisor isn’t weighing what to recommend against what pays them best.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are Raytheon Technologies employees and how do you help them overcome these obstacles?
I think the big challenges are:
- Understanding what to do about taxes. If you’ve got a significant pension and significant retirement savings, determining what the best tax planning strategy is going to be is going to be big. That gets more complicated for anyone whose pension is split across a frozen final-average-earnings formula and a newer cash balance formula, since each piece can call for a different strategy.
- Right alongside that is a retirement spending problem. Understanding, after years of saving and investments, how much they can spend is, oftentimes for people that have been frugal their whole life and are really good savers, one of the most difficult challenges. Trying to rewire their saver brain into a retirement spender brain can be helped by having a financial planner to help you understand what is realistically safe, using probabilities, history, and math. That can be really helpful in making that shift and that change when you are in retirement and also knowing when you are ready to retire can be a big shift. It can be scary going from a paycheck and all that career success and recognition to then being able to have your freedom but also having to rely on your portfolio and using a system. What a financial planner can provide can help you have a lot of confidence in the income machine that you guys build together, based on your portfolio and all your different resources and tools.
- For people mid-career, just maximizing their company benefits, maximizing their savings opportunities and investment opportunities to set themselves up and their families up for their most cherished life objectives. Saving time in doing that and helping clients just really understand thoroughly what opportunities are available and which ones are uniquely suited to them (so they can really make the most of their efforts and their career and have that translate well into their financial world)
QWhat questions do you recommend Raytheon Technologies employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
They’re going to want to ask:
- Have they worked with Raytheon employees before?
- How do they get paid? Do they have compensation from third parties or do they only get paid by clients?
- What are the fees based on? Is it based on hours worked or something else? I guess it’s under management.
- What’s the process for choosing to work with an advisor and identifying if there’s a mutual fit?
- Is there consultation involved?
- Are there any education materials that you provide to help understand what they’ll get and what a typical client experience might look like (whether that be a sample plan, videos, or something along those lines)? To help the potential client evaluate if the client does have the expertise and merit that might closely align with what their needs are.
- What are the credentials and licenses of the advisor? Are they CFP?
QIs there anything that comes up frequently in your initial meeting with Raytheon Technologies employees that surprises you?
Oftentimes something that surprises me in my first meeting with Raytheon employees is that they’re just not fully aware of what options they have with financial advisors or planners.
A lot of them have been doing things on their own, working really hard, saving into their 401(k), and doing a great job financially but not fully understanding the scope of the options they have. They do not understand how things might be able to be configured with their finances and how all their cash is going into different places that might be more beneficial for their scenario.
I will say that I’m a little biased because I am a financial planner but frequently I do find there are opportunities to provide some adjustments or tweaks to help people get in more alignment with where they’re at.
Separately it’s worth saying not all financial advisors or financial planners are going to be high quality. There are a lot of insurance salespeople that kind of brand themselves as financial advisors. That’s an additional thing that I oftentimes encounter when someone believes that they’re working with a financial advisor but they’re really just putting money into an insurance policy. They really haven’t taken the time to reevaluate things from an objective financial standpoint because their financial advisor, who they believe they’re getting objective input from, is really an insurance sales representative or works for an insurance company.
QFor highly compensated Raytheon Technologies employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?
Yeah this is one area where I really specialize in helping people. I’ve worked with some really high-level executives. Sometimes there’s significant stock compensation that applies. Executives may have the option to elect a portion of their stock compensation to be received as stock appreciation rights, which is a high-leverage option for them to potentially experience significant upside with business. However there’s a lot of risk associated with that so each person’s going to have a unique situation where it may or may not make sense for them.
Separately there’s a deferred compensation plan for employees with over $360,000 (will adjust higher in years after 2026; it is $375,000 for 2027) in includable compensation that allows employees to contribute extra to the deferred compensation plan and not miss a full company match on their retirement contributions (just because the IRS has an includible compensation limit). That is pretty much a no-brainer for a lot of people to at least do the excess compensation contribution to the deferred compensation plan so they don’t miss out on any matching contributions on their salary from a percentage standpoint.
The extra use of the deferred compensation plan or other more advanced benefits can be pretty tricky to determine. It really depends on where you’re at in terms of your career, how close you are to retirement, what your goals and objectives are, and how much extra cash you may need in the short term for your personal objectives (whether you have a kid going to college, plan to buy a second home, or have other aspirations to renovate part of your house). All of these things might require a lot of additional cash and so how much you use some of these benefits should really fit into the broader profile of your financial plan and goals.
QIs there a particularly memorable experience or a moment you recall with a client who worked at Raytheon Technologies when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?
One of my clients is an executive at Raytheon and as he’s been getting closer to retirement, we have been able to use the deferred compensation plan more precisely with the rest of his goals and in the broader tax planning strategy.
He also is a charitably inclined individual so we were able to come up with a pretty unique financial strategy that includes:
- bunching his charitable contributions in one year with a donor-advised fund
- alternating that with years that he’s contributing to the deferred compensation plan, with specific distribution years aligned to his retirement goals
As a highly compensated individual this is great because he’s able to use his tax deduction opportunities a little bit more precisely than he would have probably come up with on his own. This is not because he is not smart enough, but because he has a family and kids, and everyone knows how hard they work you when you get to the higher levels at the company.
Altogether, we believe it’s going to help him to save a significant amount of taxes because a lot of this is going to come out when he is in retirement and is in a much lower tax bracket.
QRaytheon Technologies has gone through significant corporate changes, including the 2020 merger of Raytheon Company and United Technologies and the subsequent spin-offs of Carrier and Otis — how should employees think about managing equity, pension, and benefits that may have shifted or been restructured across those events?
Well, it really depends on where you were before 2020. If you were a Raytheon employee prior to 2020 and you have some legacy benefits for hires pre-2007, Your pension moved from a defined benefit plan to a cash balance plan during the merger.
Separately for United Technologies employees that were part of the merger in 2020, if they were hired before 2010, they may have a pension plan that got phased out in the merger as well.
One thing that people should really be thinking about is what the impact is on their retirement plan of that change. It means they’re going to be getting less salary replacement from that because the defined benefit plan is not going to continue and the cash balance plan is a little bit less lucrative. That might mean that if they haven’t really updated their plan in a long time, they may need to review what their target savings need to be, considering all of their income sources and what the projected cash balance plan will contribute to their retirement.
Another big piece of planning for employees post merger, especially if they’ve been there for a number of years, is employer stock in the 401(k). Depending on how long you’ve had that stock, that stock may have gone through a couple of changes and may have a low basis. This may introduce an opportunity for NUA, or net unrealized appreciation. This is an important tax planning tool that may apply when you do retire, it applies to employer stock in the 401(k), it would allow for really favorable tax treatment on that if the procedure is done properly when making those changes.
However it’s important to note that carrying a significant amount of employer stock in your 401(k) could be a big trap as well. I would advise evaluating it in the context of a broader financial plan and determining what exactly the tax benefits would be. I would determine if management of that position, in light of the tax benefits, may still be a better proactive move for your retirement plan.
While some benefits may be phasing out or coming in, oftentimes what might seem small can really be a significant factor in your long-term plan. It may even introduce new opportunities for you to contribute more, get a better match on your retirement plan.
QGiven that Raytheon Technologies operates heavily in the defense sector with many employees holding security clearances and working on classified programs, are there any unique financial planning considerations — such as limitations on outside employment or specific career-transition challenges — that advisors should be prepared to address?
There is oftentimes a really great translation of skills and experience across different defense industry companies. The big thing would just be from a location standpoint: defense contractors employees are oftentimes limited to being on site at least a few days a week. Some employees are exempt, but we’ve seen, over the past couple years, return-to-office mandates for Raytheon employees become stronger and the key is factoring this location requirement into the broader financial plan. If someone’s planning to step back and maybe have a second act in early retirement, if it’s going to be in the defense contracting industry, that may still be location-dependent. That, in turn, does materialize in different state tax considerations and a variety of other pieces: cost of living, real estate costs, what to do with existing homes, and so forth.
Additionally, I have seen some people come frequently from the military into Raytheon. That’s an extremely common thing. Combining previous government or military benefits with the Raytheon retirement package is a type of planning that requires a little bit more advanced knowledge of some of those pensions or VA benefits. Those can be extremely valuable in a financial plan and a retirement plan but if overlooked can be costly.
QHow do you help Raytheon Technologies employees evaluate the trade-offs between the company’s defined benefit pension plan and other retirement savings options like the 401(k), and what strategies do you recommend for maximizing long-term retirement income?
Yeah I really would think that the company’s defined benefit pension plan is a great benefit that puts you ahead of most other employees savings for the future in today’s workforce, and also embeds a conservative income stream into your overall financial plan separate from social security. However, for most Raytheon employees, it’s not going to fully replace the need to save into 401(k) because the benefits started to phase out in 2020 — with most people’s actual accruals frozen by the end of 2022 — and so oftentimes there’s going to be a gap.
The key is just understanding what your goals are in terms of your ideal lifestyle and then backing into what’s going to be the best set of tools and contributions that’s going to achieve your objectives. The savings gap you need to cover in your 401(k) may be very small if your lifestyle objectives are modest, but it could be larger if you were in the pension for a shorter period of time, and have greater lifestyle aspirations.
The rule of thumb thinking around how much you need to save in the 401(k) is where a lot of people get tripped up. Knowing your math and numbers is a unique and personal things, and getting it right can give you confidence in your financial plan, and help become more free of just chasing what every one else is doing when that may not be right for you.
QHow do you advise Raytheon Technologies employees and executives on managing company stock and equity compensation within the context of their overall portfolio, particularly given the concentration risk that can come with working in the defense and aerospace sector?
For Raytheon employees that are receiving stock and equity compensation, the stock has done exceptionally well over the years and understanding the concentration risk can be challenging when all they can remember is positive performance.
I think one key is reminding them exactly how much upside they still have to participate in the stock with unvested shares and determining whether people are a little bit more driven to capture the potential rewards of that concentration. Reminding them that maybe the best way to do that might not be with stock share grants. Maybe it might be holding positions in a 401(k), which can benefit from advanced tax treatment like NUA, and managing the current positions that become vested as cash.
However it’s not a one-size-fits-all type strategy. Understanding the importance of diversification, I think, to some degree or another, is going to be essential to any well-grounded financial strategy. There are a lot of considerations. If someone is already completely funded in their plan or on track to be funded, maybe they have a higher risk tolerance and more ability to take risk (because it might not threaten their future and their goals as much as it would someone who really is behind on their retirement plan and is trying to catch up by having all company stock in their portfolio).
Tax considerations can be a part of the picture too for employees that we meet. Sometimes they have had positions that they just haven’t got around to selling and doing that thoughtfully. From a tax standpoint that introduces the possibility to discuss a lot of other solutions: maybe more elegant tools to diversify that tax position or maybe it’s just diversifying that tax position over a number of tax years (depending on where their income brackets are falling and a variety of other things).
But the key is that, while the stock’s done well and hopefully it continues to do well, we don’t know what the future holds. And at the core it’s just that, as opposed to you making a deal, right? You are choosing to not get killed by one thing happening and in exchange you’re not going to make a killing with one thing going well, right? A lot of the employees at Enron or Polaroid had no idea what was going on. With a very complicated organization there can be risks that you just don’t really have knowledge of or can’t really foresee.
QHow should employees think about the guaranteed income options in their 401(k)?
Personally I don’t think the guaranteed income options are super strong. They carry high fees and while that does come with the benefit of having some guaranteed income, in general for most people, I do think it’s best to have a broader investment strategy and think about obtaining guaranteed income in other ways. I’ve also written a blog about that here. https://www.parkmountfinancial.com/post/rtx_401k_income_strategy
Considering a financial advisor who specializes in working with Raytheon Technologies Employees?
The foregoing content reflects the opinions of Parkmount Financial Partners LLC and is subject to change at any time without notice. Content provided herein is for informational purposes only and should not be used or construed as investment advice or a recommendation regarding the purchase or sale of any security, or the implementation of any strategy or strategies. There is no guarantee that the statements, opinions or forecasts provided herein will prove to be correct. Past performance may not be indicative of future results. Securities investing involves risk, including the potential for loss of principal. There is no assurance that any investment plan or strategy will be successful or that markets will act as they have in the past.
Parkmount Financial is a Registered Investment Advisor doing business only in the states where it is registered and exempt from registration. Full Advisory Disclosures can be found here: https://adviserinfo.sec.gov/firm/brochure/323902
Are you a financial advisor who specializes in working with employees at Raytheon Technologies or another large company?
Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at Raytheon Technologies or another large company. (Subject to availability and terms.) Sign up today and join financial advisors attracting their ideal clients on Wealthtender.
Ask a Financial Advisor Your Raytheon Technologies Benefits & Career Questions
About the author
Founder & CEO and Editor-in-Chief, Wealthtender
Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.
Brian and his wife live in Austin, Texas.
Do you work at Apple?
Get expert insights from financial advisors who specialize in helping Apple employees and executives make the most of their compensation package and benefits.
Looking for a financial advisor who specializes in working with Apple employees? You’re in the right place. Below, you’ll find advisors who understand Apple benefits and compensation — along with their answers to common financial questions from Apple employees and executives.
Whether you recently joined Apple or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and Apple benefits can have a lasting impact on your financial future. For example:
- Do you know the right moves to get the greatest value from the Apple benefits available to you?
- If you’re thinking about leaving Apple for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?
Key Takeaways
Apple’s After-Tax 401(k) Option Is Its Most Overlooked Wealth-Building Benefit
The advisors below single out Apple’s after-tax 401(k) contributions and the ability to convert them to Roth dollars — often called a “mega backdoor” Roth — as the benefit employees know least about. Used well, it lets employees save far beyond the standard contribution limits for long-term, tax-free growth.
Concentration in Apple Stock Calls for a Structured Selling Plan
Decades of strong share-price performance leave many Apple employees with an outsized share of their net worth in one company. The advisors below describe structured, tax-aware selling plans — and coaching through the very human reluctance to sell — as the way to bring that exposure back in line with personal goals.
Check Your Vesting Calendar and Payout Schedules Before Leaving Apple
Unvested restricted stock units are typically forfeited when you resign, and leaving weeks before a major vest can leave thousands on the table. Review your RSU vesting dates, ESPP purchase windows, and any deferred compensation payouts first, and plan any stock option exercises within the post-departure window.
Why Apple Employees Work with a Specialist Financial Advisor
Throughout the year, Apple provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) and, for senior leaders, a deferred compensation plan — along with equity compensation such as restricted stock units and an employee stock purchase plan. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with Apple who specialize in helping Apple employees make the most of their income and benefits.
Apple’s headquarters is Apple Park in Cupertino, California, and Austin, Texas, is home to the company’s largest U.S. campus outside California, with thousands more employees in engineering and operations hubs such as San Diego, Culver City, and Seattle. Whether you work at one of those sites, another corporate office, one of Apple’s retail stores across the country, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.
Sensitive topics — like the steps you should take before quitting your job at Apple to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.
Should You Hire an Apple Specialist or a Local Financial Advisor?
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Apple employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with Apple employees is the better fit for your unique needs.
In the Q&A below, you’ll gain insights from financial advisors who work with Apple employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.
Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.
Q&A: Financial Planning Tips for Apple Employees & Executives
In this section, you’ll learn how you can make the most of your Apple employee benefits and gain valuable tips from financial advisors who specialize in working with Apple employees and executives.
Jump to a Financial Advisor for Apple Employees
Financial Advisor Q&A · Apple Employees
Emily Rassam, CFP®, CRPS, AIFA, NSSA, CDAA
Archer Investment Management · Charlotte, NC · Serves clients nationwide
Richard J. Archer, CDAA, CFA, CFP®, MBA
Archer Investment Management · Austin, TX · Serves clients nationwide
With a focus on serving professionals in the technology industry, the financial advisors at Archer Investment Management help their clients get the most value from their benefits and compensation package so they can enjoy life and feel confident about their financial future. Based in Charlotte, North Carolina, and Austin, Texas, respectively, Emily Rassam and Richard Archer specialize in offering financial planning services to Apple employees.
QAs a financial advisor experienced in helping Apple employees save for retirement, how do you help them make the most of their employee benefits?
Emily: At Archer Investment Management, we specialize in working with mid-career technology professionals. We have several Apple employees as clients and are familiar with the company’s employee benefit plans, retirement plans, equity compensation packages, and ancillary benefits.
More importantly, we are acutely aware of the financial planning needs of technology professionals and how their Apple benefits fit into an overall financial plan, including long-term planning, goal setting, tax planning, and estate planning. We start by building a financial personality profile and risk tolerance assessment to understand your relationship with money and your comfort level with risk.
QWhen you first speak with an Apple employee, what questions do you ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
Richard: Our detailed onboarding process includes conversations about your life goals, how your finances play a role in maximizing happiness, and what it means to be intentional with money. We gather information about your benefits and compensation package, spending plan, short-term and long-term goals, taxes, estate plans, and insurance.
This detailed planning process allows us to build a comprehensive picture of your financial life and how each piece of the puzzle fits together. You cannot make recommendations without examining the whole picture.
QIs there a particular benefit available to Apple employees you feel isn’t as well utilized or understood by employees as it should be?
Emily: Beyond the IRS 401(k) contribution limit of $20,500 plus $6,500 of catch-up contributions (as of calendar year 2022), Apple allows employees to contribute after-tax dollars between 1% and 20% of pay. These after-tax dollars can then convert to Roth dollars as a “mega backdoor” Roth contribution. [Editor’s note: These are 2022 figures. For 2026, the limit is $24,500 plus an $8,000 catch-up; for 2027, the IRS raised them to $25,500 and $8,500.]
Few employees know about this option for mega retirement savings and how it can help you build significant wealth over time. Additionally, the Apple plan allows you to utilize a self-directed brokerage window (PCRA) through Charles Schwab. As a registered investment advisor on the Schwab platform, we can seamlessly manage these assets and incorporate them into the overall asset allocation for each Apple employee.
QBeyond Apple employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients (e.g., stock purchase plan, education savings, health savings account)?
Richard: Apple has a very generous matching program for charitable contributions. For every dollar donated, Apple matches it one-for-one. Additionally, if you volunteer your time to a qualifying organization, Apple will contribute $25 for every hour you volunteer. Whether you donate your time or treasure, Apple matches your contributions up to $10,000.
In addition to a tuition reimbursement program, Apple provides its own personal and professional development programs through Apple University. Classes range from software skills to personal finance seminars and tools.
QFor Apple employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
Emily: Your matched 401(k) dollars are 100% vested from day one. However, you may have received employee stock options or restricted stock units (RSUs) that are unvested. Look carefully at the dates on your grants and vesting schedules to determine when each RSU grant vests; this may impact your timing to leave Apple – you don’t want to leave any money on the table!
You have 90 days after departing the company to exercise your stock options. Work with an advisor to determine which grants to exercise and the best way to fund this purchase.
QFor Apple employees approaching retirement age, how do you recommend they prepare to transition from living off their salary to relying upon other sources of income?
Emily: Our detailed retirement planning process includes:
- A spending strategy tailored to your income goals
- Social Security timing recommendations
- Coordination of health care benefits
- Discussion around how your spending will change throughout retirement
- Stress-testing your retirement projection with many what-if scenarios
- Timing your exit to maximize any unvested incentive stock options (ISOs), non-qualified stock options (NSOs), or RSUs
QFor Apple employees who have managed their finances on their own to this point, what would you suggest they consider to help decide if they should begin working with a financial advisor at this stage in their lives?
Richard: There are many online tools and calculators. Where we find Apple employees get stuck is understanding how to prioritize goals and seeing the big picture.
We help Apple employees organize their financial lives and provide accountability for reaching goals. Understanding whether you should use surplus dollars to pay down debt, save towards a short-term goal, or work towards a long-term aspiration (such as retirement or college education savings) can be challenging.
For Apple employees planning with a spouse or partner, an advisor can help facilitate difficult conversations and move the ball forward on your planning process.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are Apple employees, and how do you help them overcome these obstacles?
Emily: Apple stock has seen decades of incredible performance. One common obstacle we find is knowing when to diversify away from the concentration risk of holding a high percentage of your net worth in one company’s shares.
Many of our Apple employee clients struggle with selling positions; it requires coaching, recognizing natural human biases, an evaluation of the risks, and careful diversification away from an outsized position.
QWhat questions do you recommend Apple employees ask financial advisors they’re considering hiring to help them decide if the relationship would be a good fit?
Richard: If you were granted employee stock options, RSUs, or participate in the employee stock purchase plan, be sure to work with an advisor who understands how to incorporate those into your overall picture. Seek an advisor who can model the alternative minimum tax (AMT), understands the rules around qualifying and disqualifying dispositions, and knows how and when to diversify away from sizeable single stock positions, if appropriate.
QIs there anything that surprises you frequently in your initial meeting with Apple employees?
Emily: Considering we work with many female-led households, we are pleased to see Apple’s commitment to closing the wage gap and paying women the same as men in similar roles. Apple’s family-friendly benefits include fertility treatments, paid leave for all types of new parents, and a gradual return-to-work program. They provide free guidance to help find childcare and eldercare and include paid time away to care for ill family members.
QFor highly compensated Apple employees and executives, are there any unique benefits you believe are essential to consider when preparing their financial plan?
Richard: Most benefits are available to all employees, regardless of pay level. Apple uniquely offers stock grants to all workers. Highly compensated employees should know that Apple’s compensation packages are not based on your personal salary history; they have pre-determined ranges for each position based on fair market value. This practice allows for a potentially generous increase in salary when joining Apple.
QIs there a particular experience or moment you recall with a client who worked at Apple when you realized they have unique opportunities and circumstances regarding their financial planning needs?
Emily: One unique and detailed plan we worked on involved an Apple employee married to another Fortune 500 technology firm worker. We spent many hours building various stock options into their plans and a strategy to diversify away from the concentration risk of holding two large technology single-stock positions. Our team also coordinated their two strong benefits packages to optimize coverage.
Considering a financial advisor who specializes in working with Apple Employees?
Financial Advisor Q&A · Apple Employees
Christian Ortez, AIF®, CEPA®, CPFA®
Saxe Capital · Roseville, CA · Serves clients nationwide
Strategic Wealth Advisory for High-Performing Entrepreneurs and Business OwnersChristian Ortez is a financial advisor based in the Sacramento area who specializes in offering financial planning services to Apple employees throughout Silicon Valley and nationwide. Christian helps his clients get the most value from their Apple benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping Apple employees save for their retirement, how do you help them make the most of their employee benefits?
When I sit down with someone from Apple, the first thing we do is take a big-picture look at how all their benefits fit together — not just their 401(k). The goal being to make sure every moving part of their compensation plan is working in sync. Apple’s 401(k) match is one of the better structures out there — up to 6% with immediate vesting — so I make sure clients are capturing every dollar of that first if it’s appropriate for their unique circumstances. From there, we look at the after-tax contribution option and in-plan Roth conversions, which can be a huge opportunity for higher earners to build long-term, tax-free wealth. Once that foundation is set, we connect it to their RSUs, ESPP, and any deferred comp so that everything complements each other instead of competing for attention.
QWhen you first speak with a Apple employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
I usually start with life, not spreadsheets. What are they working toward? What’s changing in their world — buying a home, starting a family, planning early retirement, or maybe feeling the weight of too much Apple stock? Those personal goals set the tone for every financial decision we make.
QIs there a particular benefit available to Apple employees you feel isn’t as well utilized or understood by employees as it should be?
Absolutely — the after-tax 401(k) contribution option and the ability to convert it to a Roth inside the plan. Most people have never heard of it, but it’s one of the most powerful tools Apple offers for long-term tax-free growth. It’s essentially a way to save far beyond the normal IRS limits if you structure it right. The other underused benefit is the Deferred Compensation Plan for senior leadership. It’s not just a tax deferral tool — it’s a way to control when income hits your tax return, which can make a major difference in managing tax bracket creep.
QBeyond Apple employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?
Definitely. The Employee Stock Purchase Plan (ESPP) is an easy win if it’s managed well. Buying Apple stock at a 15% discount on the lower of two prices every six months is potentially a built-in return, with the obvious caveat that Apple’s share price continues to rise. The challenge is deciding how much to hold versus sell, and when — which we map out based on tax exposure and diversification goals. Apple’s health and wellness programs also deserve more attention. Things like fertility coverage, parental leave, mental-health access, and fitness reimbursements all impact real financial decisions. And for those based at the Silicon Valley campus, where the Bay Area cost of living is steep, the overall benefits package carries even greater value.
QFor Apple employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
Before you resign, pause and review your vesting calendar and ESPP purchase windows. I’ve seen people leave just weeks before a major vest and leave thousands on the table. It’s also smart to check your Deferred Compensation and RSU payout schedules so you don’t accidentally trigger big tax events in the same year.
QFor Apple employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
We start by mapping out cash flow in retirement — what’s coming in, what’s going out, and when. For many Apple employees, that means coordinating deferred comp payouts, RSU liquidations, and 401(k) distributions so income replaces their paycheck seamlessly and tax-efficiently.
It’s also about timing. We look at which accounts to draw from first, when to turn on Social Security, and how to balance Roth versus traditional withdrawals.
QFor Apple employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
Many Apple employees are natural DIY planners, especially our engineer clients— they’re smart, detail-oriented, and used to solving complex problems. But once stock-based comp, deferred income, and multiple tax layers enter the mix, the decisions start to compound. An advisor adds value not by taking control away, but by helping you connect the dots. Taxes, timing, diversification, estate strategy — all those pieces need to move together. If you find yourself reacting to things instead of planning ahead, that’s usually the signal it’s time for professional coordination.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are Apple employees and how do you help them overcome these obstacles?
The biggest one is stock concentration — too much wealth tied up in Apple shares. It’s a great problem to have, but it’s still a risk. We design structured selling plans that spread out sales, manage taxes, and keep exposure aligned with their goals. Another challenge is tax timing — especially when RSUs, ESPP shares, and deferred comp all hit in the same year. My job is to help smooth that income out so they don’t get blindsided by a large tax bill or miss opportunities for deductions and charitable strategies.
QWhat questions do you recommend Apple employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
Ask real questions — not surface ones. Try:
• “How do you plan around RSUs, ESPP, and deferred comp in the same year?”
• “What’s your approach to coordinating taxes and investments, not just managing one or the other?”
• “What kind of clients do you usually work with — and how often do you meet with them?”
You’ll know quickly if someone truly understands Apple’s ecosystem. The right advisor should already be talking about tax brackets, liquidity timing, and diversification before you even bring it up.
QFor highly compensated Apple employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?
Yes — the Deferred Compensation Plan is a major one. It lets senior leaders decide when to recognize income, which can be incredibly useful for managing taxes around retirement or a big liquidity event. But it’s only valuable if it’s coordinated with RSU vesting, option exercises, and other income sources. We also pay close attention to RSUs, PSUs, and NQOs — each has its own tax treatment and timing nuances. The planning process isn’t about reacting to grants; it’s about designing an intentional strategy that balances cash flow, taxes, and long-term goals.
Considering a financial advisor who specializes in working with Apple Employees?
Are you a financial advisor who specializes in working with employees at Apple or another large company?
Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at Apple or another large company. (Subject to availability and terms.) Sign up today and join financial advisors attracting their ideal clients on Wealthtender.
Ask a Financial Advisor Your Apple Benefits & Career Questions
About the author
Founder & CEO and Editor-in-Chief, Wealthtender
Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.
Brian and his wife live in Austin, Texas.
Traditional, Roth, HSA, or taxable account – which maximizes after-tax income and legacy?
What this article covers
Mostly retired with most of his nest egg in tax-deferred accounts, Opher Ganel asks whether he made a mistake and compares traditional, Roth, HSA and taxable accounts on after-tax income, flexibility, contribution and withdrawal rules, RMDs and what heirs keep. His answer: HSAs win for healthcare dollars, Roth accounts for legacy and RMD control, traditional accounts when today’s tax rate is higher than tomorrow’s, and taxable accounts for flexibility. Three financial advisors explain why tax diversification across all of them is the real winner.
Key Takeaways
No single retirement account wins: traditional, Roth, HSA and taxable accounts each win on different criteria
HSAs win for healthcare dollars thanks to their triple tax benefit, Roth accounts win for legacy and RMD control, traditional accounts win when your current tax rate is higher than your expected retirement rate, and taxable accounts win for flexibility. Which one wins for you depends on whether your priority is after-tax income, RMD risk, flexibility or heirs.
Roth accounts are best to leave to non-spouse heirs, and an inherited HSA is worst
Non-spouse heirs generally must empty inherited traditional accounts within 10 years and pay ordinary income tax on the withdrawals, so $1 million taxed at a total 33% rate is worth about $670,000, while $1 million in a Roth stays $1 million. A non-spouse heir is taxed on an inherited HSA’s full value in a single year, while taxable accounts get a step-up in basis.
Tax diversification across pre-tax, Roth and taxable accounts gives retirees control over their tax bracket
The advisors interviewed warn against tax concentration: retirees with multimillion-dollar balances entirely in pre-tax IRAs face large RMDs, higher taxes on Social Security and IRMAA surcharges. They also call the taxable brokerage account an underrated bridge for retiring before 59½, and Opher plans to fill the 12% federal bracket with Roth conversions in low-income years.
 Alex Bridges
 Anthony Ferraiolo
 Ben Simerly
Now that I’m mostly retired and have most of our nest egg in traditional tax-deferred accounts, I find myself wondering if I made a mistake.
With Required Minimum Distributions (RMDs) looming, will those decades of tax deferral come back to haunt me?
We did maximize our Health Savings Account (HSA), but should I have put less into tax-deferred accounts and more into Roth or taxable instead?
Let’s compare four account types so you can decide which one really wins for you.
What Does It Mean for a Retirement Account to Win? 5 Criteria
For pre-retirees, here are the criteria I find most important:
- Flexibility before retirement (e.g., convertibility)
- After-tax retirement income
- Maximum amount allowed to be invested, including income limits (if any)
- Limitations on penalty-free and/or tax-free withdrawals
- Tax treatment for spousal and non-spousal heirs
As we’ll see below, every account is a trade between tax timing, flexibility, and legacy efficiency. Thus, different account types “win” in different circumstances and by different criteria.
How Traditional, Roth, HSA and Taxable Accounts Are Taxed
Here’s a quick reference guide for the tax characteristics of the different account types.
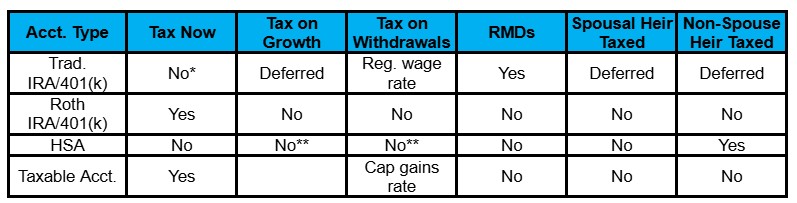
Next, let’s dig a little deeper into each account type.
Traditional IRAs and 401(k)s: Deduct Now, Pay Taxes and Take RMDs Later
Both of these are tax-deferred retirement accounts. The IRA is an individual plan available to anyone with earned income, while the 401(k), along with its cousins, the 403(b) and 457 plans, are employer plans to the benefit of employees.
Since the 403(b) and 457 are limited to employees of state and local governments, religious organizations, public schools, and non-profit organizations, we’ll ignore them here.
2026 Annual Contribution Limits
- IRAs: $7,500, plus $1,100 catch-up for people age 50 and older (unchanged for 2027).
- 401(k) plans: $24,500 elective salary deferral, plus $8,000 catch-up for employees over age 50. Employers are allowed, but not required to, match employee contributions. However, the overall contribution may not exceed the lower of 100% of the employee’s compensation or $72,000 ($80,000 if over age 50 and $83,250 if aged 60-63). For 2027, the IRS raised these limits to a $25,500 deferral, an $8,500 catch-up and a $75,000 overall cap.
- Note that these limits are shared with the Roth versions of the same account types.
Income Limits to Contribute
None.
2026 Deductibility Limits
- For IRAs, there is a complex set of deductibility limits, depending on your filing status and whether or not you and/or your spouse have access to an employer retirement plan. For example, if married and filing jointly, and you have access to an employer plan, you can fully deduct up to a Modified Adjusted Gross Income (MAGI) of $129,000 in 2026 ($133,000 in 2027). For MAGI above $149,000 ($153,000 in 2027), none of your contributions are tax-deductible. For MAGI between the two numbers, you can deduct a prorated fraction of the contribution. If neither you nor your spouse (if married) can access an employer plan, the deductibility of your contributions isn’t subject to income limits.
- There are no deductibility limits for employee contributions to 401(k) plans (up to the contribution limit). Employer contributions are deductible to the employer, up to 25% of employee compensation.
Withdrawal Rules
- Taxed as ordinary income in the year of the withdrawal.
- With limited exceptions, withdrawals before age 59½ are subject to a 10% penalty in addition to taxes.
- RMDs apply (if not already subject to RMDs, RMDs begin at age 73 for those who turn 73 before 2033; those who turn 73 in 2033 or later will be subject to RMDs from age 75).
Rules for Heirs
Inheritance rules are different for spouses and non-spouse heirs.
- Spouses:
- If the original account holder had already started RMDs, their widow(er) can (a) keep the account as an inherited account and delay their distributions until the original account holder would have turned 72; (b) take distributions based on their own life expectancy; or (c) follow the 10-year rule, wherein they must drain the account within 10 years of the original account holder’s death. Alternatively, the widow(er) can roll the account over into their own IRA.
- If RMDs had not been started, the widow(er) can keep the account as an inherited account and take distributions based on their own life expectancy, or roll it over into their own IRA.
- Non-spousal heirs:
- If an “eligible designated beneficiary” (for non-spouse, this is a minor child of the original account holder, disabled or chronically ill, or someone who is no more than 10 years younger than the original account holder), can (a) take distributions over the longer of their own life expectancy or the original account holder’s remaining life expectancy, or (b) follow the 10-year rule.
- If not an eligible designated beneficiary, must follow the 10-year rule.
Pros for Pre-Retirees
Get tax deductions during peak earning years.
Cons for Pre-Retirees
- RMDs apply.
- Withdrawals get stacked as taxable income on top of wage income and realized short-term capital gains, all subject to the high rates of taxes on regular wages. This may push you high enough to be subject to Medicare Income-Related Monthly Adjustment Amount (IRMAA).
- Non-spousal heirs must drain the account within 10 years and pay regular wage tax rates on the resulting withdrawals.
Roth IRAs and Roth 401(k)s: Pay Taxes Now, Withdraw Tax-Free Later
These are similar to the traditional accounts mentioned above, but instead of getting a tax deduction now and paying taxes later, you contribute after-tax dollars, and withdrawals are tax-free (once the account has been open for five years).
2026 Annual Contribution Limits
- IRAs: Share limit with traditional IRAs.
- 401(k) plans: Share limits with traditional 401(k) plans.
Income Limits to Contribute
- Complex income limits for Roth IRAs – for example, if married and filing jointly, MAGI up to $242,000 in 2026 ($250,000 in 2027) allows Roth contributions. MAGI above $252,000 ($260,000 in 2027) disallows it. MAGI between those allows a prorated reduction in contribution limits.
- Can convert from traditional to Roth. Note that the IRS uses a pro-rata rule for the total balance of after-tax vs. pre-tax balances across all IRAs when calculating what part of the conversion is not taxable.
- Can make “back-door” contributions by making an after-tax contribution to a traditional IRA, then converting to a Roth. The pro-rata rule applies here too.
- None for 401(k).
Deductibility Limits
Not deductible.
Withdrawal Rules
- Tax-free withdrawals.
- Withdrawal of contributions is allowed, but you cannot later reverse it.
- With limited exceptions, withdrawals of earnings before age 59½ and/or before the account is five years old are subject to a 10% penalty.
- RMDs don’t apply.
Rules for Heirs
Generally, the same rules as for non-Roth accounts, except that withdrawals are tax-free, However, withdrawals of earnings from accounts that are less than five years old may be subject to income tax. Since the 10-year rule doesn’t require withdrawals in any specific year, the heir can hold off on withdrawals until the Roth account is five years old, and thus avoid such taxation.
Note that heirs’ RMDs from an inherited Roth account are separate from RMDs from Roth accounts not inherited from the same person.
For qualified employer plans, such as a 401(k), there are further rules.
Free calculator
Roth Conversion Tax Calculator
See what converting traditional savings to a Roth would cost in federal tax this year and how much room you have before the next bracket.
Pros for Pre-Retirees
- Tax-free retirement income.
- Heirs receive tax-free.
- If tax rates are lower now than later, can pay lower tax now to avoid higher tax later.
- No RMD
Cons for Pre-Retirees
- No current tax deduction, potentially at a high tax bracket.
- Higher taxes now may mean current cash flow doesn’t allow maxing the contribution limits.
- Conversions cause a taxable income spike, possibly causing IRMAA.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
HSAs: A Triple Tax Advantage With a Catch for Heirs
These are intended to provide a way to cover qualified healthcare expenses with pre-tax dollars. These accounts enjoy a triple tax benefit:
- Tax deduction for contributions.
- Tax-free growth.
- Tax-free withdrawals (for qualified health-related expenses).
As a result, these can be used as a long-term way to maximize healthcare dollars for retirement.
2026 Annual Contribution Limits
Assuming you have an HSA-compliant high-deductible health plan (HDHP), you can contribute up to $4,400 for an individual or $8,750 for a couple or family.
Income Limits to Contribute
None.
Deductibility Limits
Fully deductible (assuming HSA-compliant health plan).
Withdrawal Rules
- Tax-free withdrawals for qualified health-related expenses.
- After age 65, can use like a traditional IRA for non-health expenses.
- RMDs don’t apply.
Rules for Heirs
- Spouses: inherit as HSA.
- Non-spousal heirs: taxed for full market value in the year of inheritance. This means, for example, an inherited $200,000 HSA could add $200,000 of taxable income to your child in a single year, potentially pushing them up into an extremely high tax bracket.
Pros for Pre-Retirees
- Current tax deduction.
- Tax-free way to fund healthcare expenses in retirement.
- No RMD
Cons for Pre-Retirees
- Must be enrolled in HDHP.
- Penalties apply for withdrawals not used to cover eligible health-related expenses before age 65.
- Worst tax setup for non-spousal heirs.
Taxable Brokerage Accounts: Maximum Flexibility and a Step-Up in Basis
This is the least tax-efficient for you, but more tax-efficient for your heirs than a traditional retirement account, and especially compared to an HSA.
Annual Contribution Limits
None.
Income Limits to Contribute
None.
Deductibility Limits
Not deductible.
Withdrawal Rules
None.
Rules for Heirs
Heirs enjoy a step-up in basis, which means no taxes are ever due on gains that were unrealized as of the death of the original account owner.
Pros for Pre-Retirees
- When used for retirement income, (long-term) realized capital gains are taxed at the preferred long-term capital gains rates (0%, 15%, or 20%, depending on your taxable income).
- Greatest flexibility.
- Heirs receive with step-up basis.
- No RMD
Cons for Pre-Retirees
- No current tax deduction, potentially at a high tax bracket.
- Dividends and interest are taxed in the current year.
- Mutual funds distribute capital gains annually, increasing current-year taxes.
Traditional vs. Roth vs. HSA vs. Taxable: Side-by-Side Comparison
Here’s a quick summary of the four account types with their pros and cons.
My Personal Math: Comparing After-Tax Results When Cash Flow Is Limited
Numbers clarify trade-offs better than theory. Here’s how the math worked in our case.
Whenever I had an HDHP, I maxed out our HSA contributions.
Beyond that, I maxed out our traditional, tax-deferred contributions to the best of our ability, given our cash flow each year.
Let’s see how that math works when your contribution is limited by cash flow. Say you can set aside $3,350 a year and pay a total marginal tax rate of 30%. That translates to contributing $5000 into your HSA or traditional retirement account and getting a tax deduction worth $1,500, or putting $3,500 into a Roth or into your taxable account.
- Putting $5,000 in an HSA: Fits within your after-tax cash flow, grows tax-free, and allows tax-free withdrawals for qualified health expenses. Assuming 7% real (inflation-adjusted) return, you’ll have about $10,000 in 10 years, all of which is accessible for use.
- Putting $5,000 into a traditional retirement account: Fits within your after-tax cash flow, grows tax-deferred, and allows penalty-free withdrawals after age 59½ (some exceptions allow earlier penalty-free withdrawals). Assuming 7% real (inflation-adjusted) return, you’ll have about $10,000 in 10 years, but if you’re still paying 30% marginal tax rate, only $7,000 is accessible for use.
- Putting $3,500 into a Roth account: Fits within your after-tax cash flow, grows tax-free, and allows tax-free withdrawals once the account is at least five years old and you’re 59½ (contributions can be withdrawn earlier). Assuming 7% real (inflation-adjusted) return, you’ll also have about $7,000 in 10 years, all of which is accessible for use.
- Putting $3,500 into a taxable account: Fits within your after-tax cash flow, dividends and interest are taxed annually, and capital gains are taxed when realized. Realized long-term capital gains are taxed at preferred rates (0%, 15%, or 20%, depending on your taxable income). Assuming 7% real (inflation-adjusted) return, you’ll have less than $7,000 in 10 years (if you had to pay annual income taxes from dividends and interest income), and the accessible amount is even lower due to taxes on realized capital gains.
Had we not been limited by cash flow, maxing out Roth contributions would have provided more retirement income than traditional retirement accounts. Had we made the contributions to a traditional account and used the tax benefit to fund a taxable investment, the difference would shrink, but not disappear.
From the perspective of eventual heirs, we need to drain our HSA before touching our Roth accounts, and preferably before draining our tax-deferred accounts. Once the HSA is drained, we should drain as much as possible of our tax-deferred accounts before draining our taxable portfolio.
However, I don’t plan to let the bequest tail wag the retirement-income/tax dog. Accordingly, we will use our HSA in years when our taxable income is higher, and when we have little taxable income, we’ll “fill” the 12% federal tax bracket by converting a portion of our tax-deferred balance into a Roth account.
Which Account Type Wins for Your Priorities?
Pre-retirees need to balance their priorities and risks. These include:
- Current marginal tax rate (federal, state, and local).
- Expected marginal tax rate in retirement, especially once RMDs hit.
- IRMAA risk, especially once RMDs start growing.
- Estate goals.
- Current liquidity needs.
Your winning option depends on your priorities and which risks most concern you.
If your top priority is maximizing after-tax retirement income, your winning strategy is maximizing HSA contributions, if you’re eligible, up to the point where your balance is more than you’re likely to spend on qualified healthcare expenses during your lifetime.
Next, if your tax rate in retirement is likely to be equal to or higher than your current rate, Roth accounts win. If not, traditional retirement accounts are better.
If your top priority is managing RMD risk and/or funding healthcare costs, HSAs are once again your top winner, followed by Roth accounts and a taxable portfolio.
For the greatest flexibility, a taxable portfolio is your best bet.
If your priority is ensuring your heirs get the biggest benefit, Roth accounts are the clear winners, followed by traditional retirement accounts.
In short, If all else is equal and used optimally:
- HSA wins for healthcare dollars.
- Roth wins for legacy (e.g., $1 million inherited by non-spouse taxed at a total 33% rate in a traditional IRA is worth $670k vs. $1 million in a Roth is worth $1 million) and RMD control.
- Traditional wins if current tax rate > retirement tax rate.
- Taxable wins for flexibility.
How Financial Advisors Approach Tax Diversification Across Account Types
I asked several financial advisors for how they advise their clients, and the biggest mistakes they see people making when saving for retirement. Here’s what they had to say.
Alex Bridges, CFP®, ChFC®, RICP®, Wealth Advisor, Tiverton Wealth, says:
Because every financial plan is as unique as a fingerprint, account selection is never a generic exercise; it requires balancing current tax liabilities with future flexibility. I frame this decision for clients through the lens of Tax Diversification.
For young professionals just starting, we aggressively favor the Roth side of the equation, Roth IRAs, Roth 401(k)s, and Roth 403(b)s. In lower early-career tax brackets, the upfront tax deduction of a traditional account is less valuable, whereas decades of tax-free compounding growth are incredibly powerful. However, as clients enter their peak earning years, the strategy shifts. We start balancing the need for immediate tax relief via pre-tax deferrals with the necessity of future tax flexibility.
For our small-business-owner clients, this often involves layering bespoke retirement plans, like pairing a Safe Harbor 401(k) with a Cash Balance Plan, to maximize their personal tax deductions while simultaneously structuring beneficial retention incentives for their employees. Ultimately, my goal is to ensure a client never reaches retirement with all their eggs in one tax basket.
We aim to build a ‘three bucket’ strategy: tax-deferred via traditional 401(k)/IRA, tax-free via Roth accounts, and after-tax in taxable brokerage accounts. A perfect real-world example of this synergy is an employee who contributes their own money to a Roth 401(k), receives their employer’s matching funds in a pre-tax bucket, and systematically funds a taxable brokerage account on the side. This triangulation gives us ultimate control over their tax destiny in retirement.
The single most pervasive mistake I see is tax concentration, which is arriving at retirement with entirely one type of tax asset. I often work with highly successful professionals, such as retired attorneys, who accumulated massive wealth. Often, they own their homes outright and have multi-million-dollar balances sitting entirely in pre-tax IRAs.
On paper, they are wealthy, but functionally, they are trapped, because every single dollar they withdraw is taxed as ordinary income, so they have zero control over their retirement tax bracket. This lack of tax diversification can trigger a ‘tax torpedo,’ exposing them to massive RMDs, higher taxes on their Social Security benefits, and steep Medicare IRMAA surcharges.
Conversely, while many advisors preach that ‘all Roth is perfect,’ overconcentration in Roth accounts presents its own set of challenges, particularly for early retirees. If you want to retire at 50, having 100% of your assets tied up in pre-tax or Roth accounts usually means navigating restrictive IRS rules and potential 10% penalties to access earnings before age 59½.
This leads to what I consider the most underrated retirement vehicle: the after-tax taxable brokerage account. There is a lot of noise in the industry dismissing taxable accounts for retirement savings, but I view them as the ultimate ‘bridge account.’
If you have a healthy after-tax portfolio, you can retire at whatever age you choose. There are no age restrictions, no early withdrawal penalties, and the funds are subject to highly favorable long-term capital gains tax rates rather than ordinary income rates. Failing to build this after-tax bridge is the biggest missed opportunity for anyone dreaming of financial independence before age 60.
Anthony Ferraiolo, CFP®, Partner Advisor at AdvicePeriod, agrees and expands:
As pointed out above, the best account type is really a combination of many. It’s not uncommon for clients to tell me they wish they had more money in their Roth IRAs or HSAs, but Roth IRAs debuted in 1998 and HSAs in 2003. I tell them that if all their money was in Roth accounts, they probably would have missed some tax-arbitrage opportunities during their working years.
However, I think HSAs provide some good mental accounting benefits in addition to their tax benefits. It’s a lot easier to stomach a $5K dental bill in retirement when you have a tax-free bucket to tap.
During all these conversations, I often feel that the plain old regular taxable account gets the least love but is one of the most flexible tools for your accumulation and retirement years. There are really only two cons to the taxable account: no tax benefit, and taxes on interest and dividends along the way.
However, the latter is an overblown concern, and there is a minor tax benefit that may come into place. I say the latter is overblown because with a proper account structure, with the inclusion of municipal bonds or municipal bond funds, most of your bond allocation’s income can be tax-exempt, so there’s little to no carrying cost for bonds. This is important because in most people’s retirement, if they retire before they can claim Social Security benefits, they may tap their taxable portfolio’s bonds for more stable distributions.
Next, you have tax-efficient ETFs. Nowadays, you can even find low-to-no-dividend ETFs for your favorite indices or prioritize growth stocks or US stocks, which could have lower yields than their international counterparts. These accounts have the most flexibility, no contribution limits, age limits, penalties, etc., so when ‘life happens’ you don’t need to worry about the tax hit too.
The hidden tax benefit is twofold when you invest cash during a high-yield environment vs. keeping it in a high-yield savings account, you can reduce the tax hit from your assets.
Similarly, if you need $50k from your portfolio, you may only need to pay capital gains on a fraction of that amount, and in some cases, that can be at the 0% tax bracket. It always depends, but I don’t think the regular taxable account gets enough credit for its Swiss-Army-Knife-like character.
The biggest challenge with the taxable account is that it doesn’t, by default, have automations connected to your paycheck, like your 401(k) or HSA, which means it takes intention to build up this account. So, while the tax benefits are attractive compared to the other accounts, the regular taxable account remains a bit underrated in my view.
Ben Simerly, CFP®, Founder and Financial Advisor of Lakehouse Family Wealth, rounds out the conversation:
First, adding to the 401(k) discussion above, there are technically annual compensation limits to 401k accounts, including pre-tax dollars. This does not factually change the outcome because of the contribution limits themselves, but I have seen it impact those with unique plan contribution percentage rules and higher incomes.
Also, since these conversations often affect families looking into trusts, you should note that the above-mentioned rules can be significantly affected by the use of trusts, both for the owner of the assets, and those inheriting them.
Account type questions are some of the most common ones we receive. There are two sets of answers. The first is technical: what fits the client according to the math? The second set of answers addresses the emotional aspect. What helps the client feel most comfortable?
More often than not, it’s the client’s comfort level with a given path that helps find the answer that’s best for them. From a math perspective, the biggest mistake we see is looking at the account-type choice based on current tax return savings. Choosing a pre-tax 401(k), for example, may reduce current taxable income. But what’s the effect of choosing a pre-tax 401(k) vs. a Roth or after-tax 401k sub-account on lifetime taxation and lifetime income from investments?
Often, a significant decrease in current taxes can create a significant decrease in retirement income. The other major factor on the math side is legacy. If an account type being considered will be primarily used for legacy to children or non-profit donations, it can completely change the math of the situation.
From the emotional perspective, the number one question is this: would you rather pay taxes later when you are unsure of your ability to work or make up the difference? Or would you rather pay the taxes now while you’re able to work, likely have more control over your life and ability to work, and a choice over your investments?
Once someone nears retirement, choices decrease. Once someone retires, they decrease further. Whether it’s from IRMAA bracket considerations, RMDs, or a potential future disability, we may not always have the same choices in the future that we have now.
More often than not, our clients choose to focus on Roth, or after-tax, contributions to pay more of the taxes now while they have more control. We love the benefits of Roth accounts and the after-tax growth. Especially with the length of modern retirements. But taxation relative to ability to work decides more cases than any other single factor we’ve encountered.
The Bottom Line: Tax Diversification Beats Any Single Account Type
So, did I make a mistake that will come back to haunt me?
Tentatively, my answer is that I didn’t.
True, having such a concentrated bet on tax-deferred accounts does reduce our flexibility in any specific year. For example, anytime we have an especially high spend in retirement, we’ll need to account for the higher taxes we’ll be hit with.
However, while I didn’t dig in deeply enough ahead of time to make the most informed choices, overall, I don’t regret what we did because it ended up allowing us to make the most of what our cash flow allowed us to set aside.
More generally, what I learned is that there is no perfect account type. There is only a tax structure that fits your stage of life, and managing your tax brackets over time. And the earlier you understand the trade-offs, the fewer regrets you’ll suffer.
However, always keep in mind that the US tax code changes often, sometimes dramatically, and all the above assumes things will mostly stay as they currently are. But that’s the best we can do without a functioning crystal ball.
In the end, the real winner isn’t one account type, but rather tax diversification across the account types that fit your priorities.
Frequently Asked Questions
Is a Roth or traditional retirement account better for pre-retirees?
If your tax rate in retirement is likely to be equal to or higher than your current rate, Roth accounts win; if not, traditional accounts are better. When cash flow limits what you can save, the gap narrows: in the article’s example, $5,000 in a traditional account and $3,500 in a Roth both leave about $7,000 of spendable money after 10 years at a 30% tax rate and 7% real return. One advisor interviewed said most of his clients choose Roth contributions to pay taxes while they still have more control over their ability to work.
Should you max out your HSA before other retirement accounts?
If your top priority is maximizing after-tax retirement income and you’re eligible, the article suggests maximizing HSA contributions first, up to the point where your balance exceeds what you’re likely to spend on qualified healthcare in your lifetime. HSAs offer a tax deduction, tax-free growth and tax-free withdrawals for qualified health expenses, and after age 65 they can be used like a traditional IRA for other expenses. The trade-off is that they are the worst account to leave to non-spouse heirs.
Which retirement account is best to leave to your heirs?
Roth accounts are the clear winner for heirs because withdrawals are tax-free, followed by traditional retirement accounts, which non-spouse heirs generally must drain within 10 years and pay ordinary income tax on. Taxable accounts benefit from a step-up in basis, so unrealized gains at death are never taxed. An HSA inherited by a non-spouse is taxed at its full value in the year of inheritance, which can push the heir into a very high bracket.
Why are taxable brokerage accounts useful for retirement?
Taxable accounts have no contribution limits, age restrictions or early withdrawal penalties, and long-term capital gains are taxed at preferred rates of 0%, 15% or 20%. Advisors interviewed call them an underrated bridge for anyone hoping to retire before 59½. One noted that municipal bonds and low-dividend, tax-efficient ETFs can keep the annual tax drag low.
What is tax diversification in retirement planning?
Tax diversification means holding savings in three buckets: tax-deferred (traditional 401(k) or IRA), tax-free (Roth) and after-tax (taxable brokerage). Advisors interviewed say the most common mistake is tax concentration, arriving at retirement with nearly everything in one type of account, which leaves little control over your tax bracket and can expose you to large RMDs, higher taxes on Social Security and IRMAA surcharges.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.
Many employees see a pay raise as an excuse to immediately upgrade their lifestyle. The extra money soon disappears, because for many of us when we have more, we spend more. The raise goes on everyday spending, or perhaps a big upgrade like a new car (along with a new, bigger-than-ever monthly car payment).
What this means is that more money simply becomes more stuff, rather than more financial stability and security. The raise gets absorbed by lifestyle inflation, rather than actually improving your finances.
If your aim is financial security and wealth building, you need to treat raises a little differently. Here are three strategies to consider.
Invest
The best thing to do with a raise is pretend you didn’t get it. Don’t spend it. Don’t plan to spend it. Don’t even save it (at least not in to a traditional savings account). Invest it.
For many this is hard to do. You want to reward yourself for that raise with something tangible. But if you can tweak your mindset and learn to see a growing investment account as something tangible, future you will thank you. Take the raise, invest it, and allow your spending to stay exactly the same.
There are exceptions of course. If you have high interest debt or no emergency fund whatsoever, then the extra money should go to this first, but the principle remains the same. You’re still not using the raise on stuff. You’re using it to buy more financial security.
Splurge, but with a Delay
Some people choose to enjoy their new income increase, but with a delay. This is the concept of living ‘one raise behind’. At the beginning of your career, you invest your first big raise, and with the next one you upgrade to the lifestyle someone on your previous salary might have.
There are no hard and fast rules for how to do this. We all need some flexibility with our finances, but embracing the general concept means you are always living within your means, rather than living at the edge of comfort, waiting for the next raise.
Whereas those who invest every raise will continue to live a simple lifestyle long-term, those living one raise behind will allow for lifestyle inflation, just at a slower rate, delaying gratification and building wealth slowly.
If you can let four or five raises go entirely into building wealth, you’ll see big growth and eventually financial freedom. If you live one raise behind, you buy yourself a financial cushion and less day-to-day stress.
Sometimes, of course, the choice isn’t yours. Changes in lifestyle mean changes in expenses that can eat up new raises whether you like it or not. Some people manage to invest every raise easily until they have children for example. Then things get expensive. So if you’re currently childfree but planning to have a family in the future, all the more reason to invest those raises now.
Upgrade, but Strategically
You can really tell when some people get a raise. New car. New phone. New designer handbag. Luxury vacation pics on Instagram. But did they really need (or even want) all those upgrades, all at once?
If you really feel the need to, you can of course spend at least part of your raise on life upgrades, but why not do it strategically? Your best strategy is probably to upgrade just one or two areas that will make a huge difference to your life, regardless of whether they’re the areas other people would upgrade. And — this one is important — even if nobody else will know what you upgraded.
I’m talking things like a new gym membership, a regular housekeeper, a better health insurance policy, or maybe even a weekly massage. Something that will have a big impact on your health, wellbeing, or time use in a way that matters to you, even if you can’t flaunt it in front of the neighbours or post it online.
The strategic upgrade is basically something that significantly improves your life, but doesn’t necessarily impress anyone else.
However you use your next raise, give it the thought and planning that future you deserves. Resist the reflex to immediately turn it into stuff. Let the gap between your income and your lifestyle grow bigger, while your investments and financial freedom do too. Try and avoid the all too common trap of being financially constrained even on a high income, constantly one raise away from truly feeling secure.
Frequently Asked Questions
What is lifestyle inflation?
Lifestyle inflation, sometimes called lifestyle creep, happens when your spending rises every time your income does. A raise gets absorbed by a nicer car, a bigger home or more frequent dining out, so your savings rate stays the same or even falls. Keeping your spending steady when your pay increases is one of the simplest ways to build wealth faster.
Should I use a raise to pay off debt or invest it?
Paying down high-interest debt such as credit card balances usually comes first, because the interest you avoid is often higher than what investments can reliably earn. Building an emergency fund is also a priority before investing heavily. Once those are in place, directing a raise toward long-term investments helps your money grow.
How can I invest my raise automatically?
One of the easiest ways is to raise the percentage you contribute to your workplace retirement plan as soon as your new pay starts, so you never get used to the extra money in your paycheck. Make sure you contribute at least enough to receive any employer match. For 2026, the IRS limit on employee contributions is $24,500 for 401(k) plans and $7,500 for IRAs, before any catch-up contributions for those 50 and older. For 2027, the IRS raised the 401(k) limit to $25,500, while the IRA limit stays at $7,500.
What does ‘living one raise behind’ mean?
Living one raise behind means you invest your next raise in full and only let your lifestyle catch up when the following raise arrives. This keeps a permanent gap between what you earn and what you spend, which can be directed toward savings and investments. It allows gradual lifestyle upgrades while still building a financial cushion.

About the author
Contributing Writer, Wealthtender
Karen Banes is a freelance writer specializing in entrepreneurship, parenting and lifestyle. She writes articles, website content, ebooks and the occasional award winning short story. Her work has appeared in a range of publications both online and off, including The Washington Post, Life Info Magazine, Transitions Abroad, Brave New Traveler, Natural Parenting Group, and Copia Magazine.
Karen provides copy editing and proofreading services, as well as content creation services, at her website KarenBanes.com.
It’s not always easy to tell when Gen X are in trouble. We were the generation raised to sort out our own problems, or brush them under the rug. On the whole we’re stoic, cynical, and have a tendency to pride ourselves on not starting or fueling drama. So it’s not surprising that many of us are quietly drowning, financially speaking.
Born between 1965 and 1980, Gen X are now in later midlife, often juggling mortgages, other debts, and kids’ ever-rising college costs, while trying to save for retirement too, which is perhaps why The Economist suggests that Gen X is the real loser generation.
It doesn’t help that many of us are now cutting back on work to provide care to ageing parents. To top it off Gen X were the ones who raised Gen Z, known for often relying on the Bank of Mom and Dad. And — perhaps as a backlash to their own haphazard and somewhat feral childhood and adolescence — Gen X as a group seem to want to support their kids as much as they possibly can.
So if you’re Gen X and quietly drowning, it’s time to look at some fixes and see if things can be improved. Here are a few things to consider.
Address Retirement Planning
While there are no doubt plenty of exceptions, Gen X as a whole hasn’t saved enough for retirement. Addressing that should probably be priority number one for most, and it may mean making some hard decisions, like putting retirement savings ahead of paying for college education.
Before you have a meltdown at the thought of it, talk to your kids, if they’re not yet college age. Many young adults are reacting to the extreme levels of student debt they see others dealing with, and opting for more practical community college courses or other options. They may even be happy to have some pressure taken off.
Then it’s time to really assess all your retirement savings — and goals — and put a plan in place. You may have more options than you think, especially if you’re hurtling towards an empty nest with lots of equity in your home. Downsizing is an obvious option, as is renting out part of your property, or all of it if you want to relocate in retirement, perhaps somewhere to somewhere with a lower cost of living.
Kerry Hannon, coauthor of the book Retirement Bites: A Gen X Guide to Securing Your Financial Future stresses that Gen X still have options when it comes to retirement. Speaking in an interview with Kiplinger, she points out:
As they become empty nesters, Gen Xers will have more opportunity to become super savers and take advantage of things like the catch-up contributions that people 50 and older can make to their retirement accounts.
So you have options. Just act on them now rather than later.
Deal with That Debt
I often give people the advice that they need to “deal with debt”, because it’s not always helpful to say “eliminate debt” or simply “pay debt off”. Gen X now carry some of the highest and most crushing debt, compared to other age groups, and that can’t be paid off quickly and easily.
Dealing with debt simply means assessing exactly what you owe and making a plan to pay it down. That alone makes many people feel much more in control of their finances, and is always worth doing.
Most of Gen X still have a mortgage, but they also carry a lot of high-interest credit card debt, which should be a first priority. Paying down high-interest debt puts you back in charge of your income. It’s worth considering consolidation loans, re-financing packages, and moving credit and charge card debt on to 0% cards, with a plan to pay them off before any more interest kicks in.
More drastic measures are worth considering too. Like the property downsizing mentioned above. For some it may be the only way they’ll fully clear their mortgage, especially if they’ve re-financed multiple times. As always, it’s worth talking to a professional (or several) at this point. Perhaps a credit counsellor to really make the best plan to repay current debts, and a retirement planner for other options you might have missed.
Be Realistic About Inheritance
Gen Xers do have one potential advantage. They’re often the kids of older generations who lived through simpler (and much more affordable) times. Their parents bought homes when they came at a very reasonable cost, and existed in a stable job market where re-financing wasn’t as needed as it often is now.
According to a report from Wealth-X an upcoming generational wealth Transfer will see 1.2 million individuals worth $5 million or more passing on a total of over $31 trillion to their inheritors, by 2033.
While this will only apply to the minority, there are plenty of ordinary middle-class families handing over houses they once bought for five-figure sums and are now worth closer to seven figures. And some of Gen X are relying on that inheritance for their retirement savings.
That’s all fine, but life is unpredictable. Not all parents are going to be able or willing to hand that money to their kids. Elder care is hugely expensive, and many have no real plan for it other than to use their current capital (including home equity). Meaning your parents care in their old age can wipe out the inheritance you were expecting.
Depending on where in the world you live, taxes can also take a chunk, and big families will be splitting that windfall many ways. Inheritance, for most, is probably best looked at as a bonus, not a retirement plan.
Accept Your Own Mortality
A report from Western & Southern Financial Group found that around half of American adults don’t have any kind of life insurance, and about a quarter of those only have a group life policy from their employer which, depending on their circumstances, may not be adequate for their needs. The numbers of Gen Xers with some kind of life cover in place stands at around 55%.
No-one wants to address the worst case scenario, but it’s worth looking into whether life insurance is a good investment for you and your family. While you’re at it, now is as good a time as any to create or review your entire estate plan. That includes drafting or updating your will, getting Power of Attorney in place, and updating beneficiaries on things like insurance policies and pension pots.
Don’t forget to consider digital estate planning too. And ensure that paperwork is in order so beneficiaries can actually find it and act on it. Putting your affairs in order makes you feel better and saves a lot of unnecessary stress for your family, should the worst happen.
Frequently Asked Questions
What years were Gen X born?
Pew Research Center defines Generation X as people born from 1965 through 1980. In 2026 that places Gen X roughly between their mid-40s and early 60s, a stage when retirement saving, debt payoff, and support for children and aging parents often compete for the same dollars.
How much can people over 50 contribute to a 401(k) and IRA in 2026?
For 2026, the 401(k) employee contribution limit is $24,500, and workers 50 and older can add an $8,000 catch-up contribution, for a total of $32,500. Workers aged 60 to 63 get a higher catch-up limit of $11,250 instead. The IRA limit is $7,500, plus a $1,100 catch-up contribution for those 50 and older. For 2027, the IRS raised the 401(k) limits to $25,500, $8,500 and $11,750, while the IRA limits stay the same.
Should I save for retirement or for my kids’ college first?
Many planners suggest putting retirement first, because students have options like scholarships, lower-cost schools, and loans, while there are no loans for retirement. Talking openly with your children about costs and alternatives such as community college can ease the pressure. A financial advisor can help you weigh the trade-offs for your family’s situation.
Is life insurance through work enough?
Employer group coverage is a useful benefit, but the amount is often modest and the coverage may end or need to be converted if you leave the job. LIMRA’s 2026 Insurance Barometer Study found that only about 52 percent of U.S. adults have any life insurance. If others depend on your income, it is worth checking whether your total coverage would replace that income and pay off major debts.
About the author
Contributing Writer, Wealthtender
Karen Banes is a freelance writer specializing in entrepreneurship, parenting and lifestyle. She writes articles, website content, ebooks and the occasional award winning short story. Her work has appeared in a range of publications both online and off, including The Washington Post, Life Info Magazine, Transitions Abroad, Brave New Traveler, Natural Parenting Group, and Copia Magazine.
Karen provides copy editing and proofreading services, as well as content creation services, at her website KarenBanes.com.