



What this article covers
Opher Ganel shows why a typical single retiree living on Social Security and median savings could fall more than 30% short of a comfortable budget, then lays out seven ways to lower the risk of running out of money, from saving your raises and switching to the guardrails approach to delaying Social Security to age 70. He also compares single-premium annuity income with a stock and bond portfolio, and five financial advisors weigh in on where annuities help and where they fall short.
Key Takeaways
A median earner relying on Social Security and median savings faces a retirement shortfall of 30% or more
Opher Ganel’s example assumes a single retiree with a $50k pre-retirement income, a Social Security benefit of about $24k a year and a $90k portfolio drawn at 4%. That covers well under the $40k (80% of pre-retirement income) that financial professionals suggest, a gap he calls a 30%+ haircut beyond the expected 20% drop in spending.
Saving raises, the guardrails approach and a flexible budget can substantially lower the risk of running out of money
Allocating at least half of each raise or bonus to retirement can push a savings rate toward 30% or more without cutting spending. The guardrails approach allows an initial draw of 5% rather than 4%, and research cited in the article shows moving from a nearly all-fixed to a nearly all-flexible budget can more than triple a safe draw.
Single-premium annuities pay more income up front, but most payments are not adjusted for inflation
In the article’s $100k comparison, an immediate annuity paid $7.7k in inflation-adjusted Year-1 income vs. $5.0k from a 5% portfolio draw, but after a 30-year deferment the portfolio won, $15.7k vs. $11.3k. Advisors interviewed cautioned that inflation can halve a standard annuity’s real benefit over 20 years and pointed to fees, limited liquidity and alternatives such as a bond or CD ladder.
 Michael Hunsberger
 Chris Chen
If you’re like most people, you’ve at least given some thought to whether you’ll be able to retire and how to try and get from where you are now to retirement.
If you’re like most people, you’re also unlikely to retire comfortably.
Why Most People Risk a Less Comfortable Retirement Than They Hoped
Let’s start with Social Security.
For simplicity, let’s assume you’ll be single when you retire. US News & World Report quotes US Census data showing over 31% of men and 55% of women aged 65 or older are single, so it’s almost likely as not to be the case.
According to DQYDJ, the median income of 67-year-olds is $50k, so let’s assume that’s what you’ll make before retirement.
Using the Social Security Administration (SSA) formula, your retirement benefit at full retirement age would be about $24k a year (and we’ll ignore the pesky 20% drop in benefits likely to happen around 2034).
However, you’ll have at least some money set aside by retirement age, right?
Sure, but how much?
Also, according to DQYDJ, the median net worth (excluding home equity) for people in their early 60s is $90k. Using the “4% rule,” you’ll be able to safely draw $3.6k in your first year of retirement from such a portfolio.
Adding that to your estimated Social Security retirement benefit, you’d need to live on about $28k/yr.
Financial professionals estimate your retirement spending should be 80% of your pre-retirement budget (since you won’t need to save for retirement, your taxes will be lower, and you won’t need to cover work-related costs like commuting), so you’d like to live on $40k (80% of your current $50k income).
But you’ll only have $27k a year.
That’s more than a 30% additional “haircut” to your budget beyond the expected 20% decrease.
Ouch!
How Can You Lower the Risk of Running Out of Money in Retirement?
You can do any of the following 7 simple (though not necessarily easy) things to reduce your retirement risks:
1. Increase Your Income So You Can Save More for Retirement
This can be through learning new skills to increase your salary potential, taking on a second job, and/or starting a side hustle. If you can increase your income, your savings amounts will go up even if you don’t change your savings rate.
That leads us to the next idea…
2. Increase Your Savings Rate by Saving Your Raises
Ramit Sethi of “I Will Teach You to Be Rich” fame suggests setting aside at least 10% of your income to (short-term) savings and 20% to (long-term) investments.
This has the dual benefit of increasing how much you retire on, while also reducing your standard of living so retirement is less expensive.
Can’t fathom the idea of getting to a 30% savings rate?
If you follow my advice, you’ll be able to do it without feeling any expense-cutting pain!
Just allocate at least half (I prefer 2/3) of each salary increase and/or bonus toward retirement. Over time, this could increase your savings rate, potentially to 50% or more, with zero pain.
3. Replace the Static 4% Rule with the Dynamic Guardrails Approach
Using the guardrail approach, you can safely draw 25% more (initial draw of 5% rather than 4% of your nest egg) and cut your risk of running out of money by a factor of 3!
The gist of the method is to annually adjust your prior-year draw by inflation (like with the 4% rule). However, you then recalculate what percentage the new draw is of your then-current portfolio. If the fraction is over 6%, trim it by a tenth. If it’s under 4%, boost it by a tenth.
4. Reduce Fixed Expenses to Keep Your Retirement Budget Flexible
For any given budget, if nearly all of it is fixed costs (think mortgage/rent, utilities, insurance, etc.) that you can’t easily change, you don’t have much flexibility to reduce spending whenever your portfolio takes a hit due to a market crash.
On the flip side, if your expenses are mostly discretionary, you can trim spending rather easily to avoid selling too many shares in a down market. Then, when the market recovers, you can go back to spending more.
Research shows that going from a nearly all-fixed budget to a nearly all-flexible one lets you increase your safe draw more than 3-fold.
5. Use Part of Your Portfolio to Buy Guaranteed Income (Annuities)
A new report titled Paving the Way to Optimized Retirement Income was released by asset manager BlackRock and the Bipartisan Policy Center (BPC), a Washington-based think tank. The report suggested that people saving for retirement can increase their retirement spending and reduce their risk of running out of money by purchasing fixed income (e.g., annuities) with a portion of their portfolio.
The report presents a case study where a 35-year-old worker making $44k, setting aside 5% for retirement, and who already has a $19k nest egg. If the worker purchases annuities with part of his annual savings, such that by retirement that investment is 30% of his nest egg, the report claims a 5% average increase in safe retirement spending and a 5% average reduced risk of running out of money.
6. Delay Retirement and Claim Social Security at Age 70
As Nationwide reports, 25% of near-retirees are now planning to delay social security, and another 15% don’t expect to ever be able to retire.
The extra time lets you continue to save another few years, gives your existing portfolio more time to compound, and reduces the length of retirement you need to fund.
Meanwhile, Your Social Security benefit will increase by 8% for each year you delay claiming past your full retirement age, up to age 70. If you were born in 1960 or later, that works out to a 24% benefit boost for life. Even better, you still get cost-of-living adjustments each year.
The above-mentioned BlackRock/BPC report also mentions that delaying retirement and claiming Social Security by two years (the report assumed delaying from age 65 to age 67), the increase in safe spending went up another 16%, and the risk of running out dropped by a similar 16%.
7. Consider a Reverse Mortgage
If you own your home, you may be able to convert your equity into a lifetime income stream through a so-called reverse mortgage. This is where a lender pays you an agreed monthly amount for life (or until you sell the home).
The lender gets repaid the pre-agreed amount when you die (or sell the house), but no matter how long that takes and how much they paid you over that time, they don’t get more than the proceeds of selling the house.
This is a complex product, so you’d be well served to consult a professional before pursuing it.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
Do Annuities Pay More Than a Stock and Bond Portfolio in Retirement?
Using the Schwab income annuity calculator, we can estimate what income you could get from a single-premium immediate or deferred annuity. For our comparison, let’s assume the income is for a single man living in Maryland, and that the income will start when he reaches age 67.
For a $100k investment, the estimated annual payouts are as follows (“single life only” and assuming a 3% annual inflation rate for the next 30 years). We assume here only that single $100k investment.

The lower row shows the estimated purchasing power in today’s dollars of the income in the first year when the retiree hits age 67. Inflation will continue to erode the purchasing power of that income each additional year of retirement.
Next, let’s look at the growth of $100k invested in a mix of stocks and bonds that returns 7% a year. Here too, we assume no additional investment.
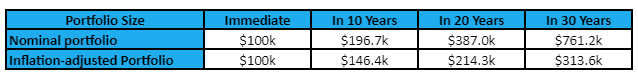
Using the 5% safe draw from the Guardrails Approach, here are the Year-1 draws from these portfolios.
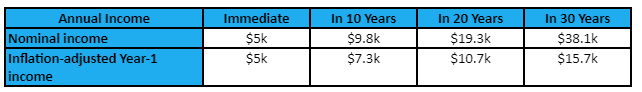
Comparing the two options’ inflation-adjusted incomes, we find:
- For immediate income, the annuity wins $7.7k vs. $5.0k – over 50% higher!
- For a 10-year deferment, the annuity still comes out ahead, $9.8k vs. $7.3k – a healthy 34% edge.
- For a 20-year deferment, the annuity still comes out ahead, $11.7k vs. $10.7k – a slight 9% edge.
- For a 30-year deferment, the annuity loses out, $11.3k vs. $15.7k – a 28% underperformance!
For all but the longest deferment periods, single-premium fixed annuities offer a higher income for any given investment amount, but for immediate annuities, that edge is greatest.
What Do Financial Advisors Say About Annuities for Retirement Income?
This agrees with the advice of Michael Hunsberger, ChFC®, Owner, Next Mission Financial Planning, LLC, who says “Guaranteed income is important in retirement as the Blackrock/BPC study suggests, allowing retirees to feel more comfortable spending because they know they have money coming in every month. I typically advise clients to maintain flexibility by purchasing an annuity when they need it and to not use it as a savings vehicle during their accumulation period.”
However, that just compares income from the two sources at Year 1 of retirement. Using the guardrails approach to safely draw from a portfolio over decades lets your income gradually rise to match inflation, while annuity payments don’t increase. Over a 20+ year retirement, this could dramatically degrade the benefit of annuities.
Chris Chen, CFP®, CDFA®, Insight Financial Strategists agrees, noting:
The insurance industry has been on a roll trying to sell more annuities. However, most annuity contracts out there aren’t inflation-adjusted, such that with a standard contract and the long-term average inflation of 3.5%, benefits drop by half over 20 years (nearly half of those retiring at 65 will live past 85). This means retirees counting on annuities will have a lot less income over time than they expected. Somehow, this issue continues to be unaddressed by insurance companies.
Caleb Vering, Associate Wealth Advisor, Farnam Financial, doesn’t think annuities are a slam-dunk case either, saying, “Annuities, while they may sound good on their face, have many disadvantages investors should consider. High fees, lower returns than stocks, and complex rules. They also often limit liquidity and make it difficult to draw on your savings if, for example, you had a large medical expense to cover in retirement.” Jorey Bernstein, Executive Director, Wealth Manager, and Founder, Bernstein Investment Consultants agrees with all these points, adding, “That’s why it’s crucial to get personalized advice and explore all your options before making big decisions about your retirement savings.”
P. Timothy Uihlein, CFP®, MBA, Partner, Managing Director, and Senior Wealth Manager at Vincere Wealth Management, also isn’t convinced annuities are the answer, suggesting an alternative:
Fixed-income instruments won’t necessarily prevent you from running out of money. While they can help and add diversification, I’d argue a bond or CD ladder is often a better alternative than an annuity, especially from a cost standpoint.
A final drawback is that the annuity leaves nothing behind to heirs (unless you pick some other option such as “single life with 10 year certain,” “single life with 20 year certain,” “single life with cash refund,” etc., any of which reduces your annual income.
However, if you’re single and have no heirs, that may not concern you.
The Bottom Line: Minimize Fixed Expenses and Maximize Fixed Income
If you’re like most people, a comfortable retirement isn’t a given for you.
You’ll need to do much more than most people do to build up a nest egg big enough to support a comfortable retirement with a low risk of running out of money and experiencing poverty in your old age.
This article describes 7 simple (but not easy) paths to escape that fate and reduce your retirement risks, including the possibility of using a portion of your nest egg to buy a low-cost single-premium fixed annuity, guaranteeing a portion of your retirement budget will always be covered.
Typically, for a retiree to be financially safe, it’s best to minimize fixed expenses and maximize fixed income, at least to a point.
Find a Financial Advisor
What to Read Next:
- How to Enjoy Life After Retirement
- How Much Does a Financial Advisor Cost?
- What Does Health is Wealth Mean?
Frequently Asked Questions
What are the biggest risks of running out of money in retirement?
The article’s core risk is a gap between income and spending: Social Security plus a typical nest egg may cover far less than the roughly 80% of pre-retirement income most people need. A largely fixed budget adds risk, because it leaves little room to cut spending when a market crash hits the portfolio.
How can I reduce the risk of running out of money in retirement?
Opher Ganel lists seven options: increase your income, raise your savings rate, replace the static 4% rule with the guardrails approach, reduce fixed expenses, buy fixed income such as annuities with part of your portfolio, delay retirement and Social Security to age 70, and consider converting home equity into income. Most work best in combination.
How does the guardrails approach differ from the 4% rule?
Both adjust the prior year’s withdrawal for inflation, but the guardrails approach then checks what percentage of the current portfolio that draw represents. If it is over 6%, you trim it by a tenth; if it is under 4%, you raise it by a tenth. According to the article, this allows an initial draw of 5% instead of 4% while cutting the risk of running out of money by a factor of three.
How much does delaying Social Security to 70 increase benefits?
Your benefit rises 8% for each year you delay past full retirement age, up to age 70. For people born in 1960 or later, that means a 24% larger benefit for life, and cost-of-living adjustments still apply. Delaying retirement also adds years of saving and compounding and shortens the retirement you need to fund.
Is an annuity better than a stock and bond portfolio for retirement income?
It depends on timing and inflation. In the article’s comparison, single-premium annuities produced more Year-1 income for all but a 30-year deferment, with the biggest edge for immediate annuities. However, portfolio withdrawals under the guardrails approach can rise with inflation while most annuity payments don’t, and advisors interviewed noted high fees, lower returns, limited liquidity and nothing left to heirs under single-life payouts.
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.

About the author
Contributing Writer, Wealthtender
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.