What this article covers

This guide explains how a 401(k) works, from signing up and choosing investments to employer matching, vesting, withdrawals and required minimum distributions, with the 2026 and 2027 contribution limits and a step-by-step walk-through of how contributions grow.

Key Takeaways

1

A 401(k) lets you save for retirement straight from each paycheck

Contributions go in pre-tax with a traditional 401(k) or after-tax with a Roth 401(k), and the money is invested in funds you choose. On a $100,000 salary, a 6% contribution is about $230.77 per paycheck over 26 pay periods.

2

The 401(k) limit is $24,500 for 2026 and $25,500 for 2027

Workers 50 and older can add an $8,000 catch-up in 2026 and $8,500 in 2027, and those aged 60 to 63 get a higher catch-up of $11,250 in 2026 and $11,750 in 2027. There are no income limits for 401(k) contributions.

3

An employer match is free money, but vesting rules decide when it is yours

A common match of 50 cents per dollar up to 6% of pay turns a $6,000 contribution into $9,000 a year. If you leave before the vesting period ends, you may forfeit some or all of the employer contributions.

Retirement is on every employee’s mind, whether they are young or old.

In America, most workers have a 401(k), a similar plan, or a pension. However, fewer and fewer people have access to pensions, so it is essential to know how a 401(k) plan works. Your retired life could depend on it.

A 401(k) plan is a retirement savings plan. It permits employees to save money each pay period. The savings are known as contributions. Depending on the 401(k) type, the contributions are either pre-tax or after-tax. But in both cases, the savings accumulate and ideally grow with time until they are withdrawn from the plan. The money in a 401(k) is invested in whichever mutual funds the worker picks.

Consequently, it is vital to understand how a 401(k) plan works. Make the wrong choices, and you may not get to retire as early as you desire.

What Is a 401(k)?

A 401(k) plan is a qualified defined contribution plan many employers offer. It allows workers to save for retirement. The plan is named after a section in the United States Internal Revenue Code.

Employees can automatically deduct a percentage of their income from each paycheck into the investment account. In addition, employers may match a part of their employee’s contributions, usually up to a limit. Depending on your employer, you may have access to a 401(k), a parallel plan, or both.

Significant changes for 401(k) plans came from the SECURE 2.0 Act, passed as part of the federal government’s 2023 spending bill. These changes raised the required minimum distribution (RMD) age, added a higher catch-up contribution for ages 60 to 63, required automatic enrollment in many new plans, and allowed a penalty-free emergency withdrawal of up to $1,000 a year, among others. Workers should talk to their financial advisors or plan administrator about these changes.

How Does a 401(k) Work in Practice?

For example, suppose you earn $100,000 annually and desire to contribute 6% of your pay to a 401(k). The total amount, $6,000, is divided into the number of pay periods per year, typically 26. The employee contributes roughly $230.77 to the investment account in each paycheck.

The employer may match the employee contribution. For example, if they match 50% up to the first 6%, the amount added to the 401(k) plan would be $115.38 each paycheck. Thus, the combined contribution is $9,000 annually, $3,000 more than the employee’s contribution.

4 Types of Employer-Sponsored Retirement Plans

Four types of employer-sponsored retirement plans exist. Most workers have at least heard about the traditional and Roth 401(k) plans. In addition, some workers have access to a 403(b) or a 457(b).

The four types of retirement accounts are conceptually similar because they are all defined contribution plans with comparable contribution levels, investment choices, and withdrawal rules. Some workers may need to pick from two or more types of these plans; thus, it is vital to understand how a 401(k) works.

Traditional 401(k)

Employees contribute pre-tax dollars from their paychecks in a traditional 401(k). The money is invested in funds selected by the employee. Consequently, the taxable income is reduced by the amount contributed. Also, no taxes are paid on the amount contributed until the money is withdrawn, meaning the dollars are tax-deferred.

For instance, if you earned $50,000 and contributed $2,000 into a traditional 401(k), your taxable income is reduced to $48,000. But the $2,000, any investment gains and dividends, are taxed when the money is withdrawn at the prevailing tax rate.

Roth 401(k)

The second type of defined contribution plan is a Roth 401(k) plan. Employees contribute after-tax dollars from their paychecks, so there is no tax deduction. The money is invested in funds selected by the employee.

Since taxes are paid before the contribution is made, they are not paid at withdrawal except on the employer match. Moreover, taxes are not paid on investment gains or dividends, a significant advantage of the Roth 401(k).

403(b)

A 403(b) plan is typically available to workers at a non-profit organization, like public schools, colleges, churches, libraries, hospitals, etc. The plan type is parallel to a 401(k).

Some workers may have access to both a 401(k) and 403(b). However, investment choices may be narrower in a 403(b), and many offer annuities instead of mutual funds, so check with your plan administrator regarding the rules.

457(b)

A 457(b) plan is usually available to civil servants, municipal employees, police officers, firefighters, and executives at hospitals, charities, and unions. This plan type is akin to 401(k) and 403(b), with some differences in maximum contributions. Again, check with your plan administrator regarding the rules.

Stay connected

See more of Wealthtender when you search Google

Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.

401(k) Contribution Limits for 2026 and 2027

No income limits exist for 401(k) plans. But the IRS enforces a maximum and catch-up contribution limit. These usually increase annually to make up for inflation.

Other rules exist, too, for additional non-deductible after-tax contributions and highly compensated employees. So workers should check their plan rules.

In 2026, the annual maximum employee contribution is $24,500, and the catch-up limit for those 50 and older is $8,000 ($11,250 at ages 60 to 63). For 2027, the IRS raised those limits to $25,500, $8,500 and $11,750.

If an employer offers a Traditional and Roth 401(k), employees can split their contributions between the two. However, they cannot exceed the maximum annual limits.

How a 401(k) Employer Match Works

Another aspect is employer matching. This is money that an employer contributes toward their worker’s retirement accounts. Most companies match a percentage of the employee’s contribution up to a maximum.

For instance, they may match 50 cents for every dollar the worker contributes up to a specific percentage of salary, like 5% or 6%.

This is not money you see directly as take-home pay. Hence, financial advisors often recommend contributing at least enough of your salary to receive the complete employer match. In effect, this is free money for a retirement investment account.

Vesting: When the Match Becomes Yours

However, most employers have a vesting requirement for their match. If a worker changes jobs and companies before the vesting period ends, the money or a percentage of it goes back to the employer.

For example, suppose the vesting period is three years, and you leave after two years. A possibility is one-third of the employer match is returned while two-thirds stay in your 401(k) plan.

401(k) Withdrawals and Required Minimum Distributions

A person can generally withdraw money without a penalty starting at age 59½, or at 55 if they leave their employer in or after the year they turn 55. The funds can then be used for income and living expenses.

The IRS does not allow people to keep money in a 401(k) forever. Depending on their birth year, they must start withdrawing required minimum distributions (RMDs) starting at age 73 for most people today, rising to 75 for those born in 1960 or later.

Starting in 2024, the Roth 401(k) does not have an RMD during a worker’s lifetime.

How Does a 401(k) Plan Work? 4 Steps

Step 1: Sign Up

When you start a new job, an employer offers a 401(k) or a similar plan as part of your benefits package. At this point, you should learn how a 401(k) plan works.

First, a worker must enroll in the plan, decide how much to contribute annually, and select investment options. This step is crucial for long-term success, but many people don’t know how to choose low-cost mutual funds to build a portfolio.

Step 2: Contribute

Once you receive your paycheck, a portion of it is deposited in an investment account. The funds are allocated to the mutual funds selected by the employee at the specified percentages.

If the money goes towards a Traditional 401(k), it is pre-tax income. If the money goes towards a Roth 401(k), it is after-tax income.

Step 3: Accumulate and Grow

Money in the 401(k) plan will accumulate and grow with each passing year. Suppose the total contribution is $9,000 annually between the employee and employer match. In five years, the amount saved for retirement is $45,000. But this amount does not account for investment gains and losses.

Over time, investments tend to gain, but annual losses can occur, a risk to future retirees. Moreover, the capital gains and dividends are tax-deferred.

Step 4: Withdraw

After you retire, it is time to start withdrawing money from the 401(k) for monthly expenses. The IRS generally does not allow penalty-free withdrawals until a person reaches age 59½.

If the money is withdrawn from a Traditional 401(k), you must pay taxes at your current tax rate. Depending on your birth year, you must start taking required minimum distributions at age 73 or 75.

The Bottom Line on How a 401(k) Works

While watching their retirement accounts grow, many workers ask themselves, how much should I have in my 401(k)? The answer is, “it depends.”

In the 55 to 64 age bracket, near retirement, the average 401(k) plan balance is $189,800, but the median is much lower at $56,450. This means fewer workers have large balances, pulling the average up. That said, retirees will need a more significant amount combined with Social Security for a secure retirement.

The bottom line is that a young person should start saving for retirement as early as possible. With a longer time horizon, employees can leverage the power of compounding and attain a higher dollar value.

Are You Ready to Hire a Financial Advisor?

You’ll find a growing number of financial advisors featured on Wealthtender. You can search based on the areas of specialization most important to you and where they’re located, or browse our financial advisor directory for more search options to find advisors who may be a good fit for you.

Find Your Next Financial Advisor on Wealthtender

📍 Click on a pin in the map view below for a preview of financial advisors who can help you reach your money goals with a personalized plan. Or choose the grid view to search our directory of financial advisors with additional filtering options.

📍Double-click or pinch pins to view more.
Showing

Frequently Asked Questions

How does a 401(k) work?

You choose a percentage of each paycheck to contribute, your employer deposits it into your 401(k) account, and the money is invested in funds you select. Traditional contributions reduce your taxable income now and are taxed at withdrawal, while Roth contributions are made after tax and qualified withdrawals are tax-free.

What is the 401(k) contribution limit for 2026 and 2027?

For 2026, employees can contribute up to $24,500, plus an $8,000 catch-up at age 50 or older or $11,250 at ages 60 to 63. For 2027, those limits rise to $25,500, $8,500 and $11,750. Traditional and Roth 401(k) contributions share the same limit.

When can I withdraw money from a 401(k) without a penalty?

Generally at age 59½, or at 55 if you leave your employer in or after the year you turn 55. Earlier withdrawals usually face a 10% penalty plus income tax on pre-tax money, with some exceptions.

When do required minimum distributions start for a 401(k)?

For most people today, required minimum distributions from a traditional 401(k) start at age 73, rising to 75 for those born in 1960 or later. Starting in 2024, Roth 401(k)s no longer require distributions during the owner’s lifetime.

Find your fit

Find financial advisors who specialize in helping people like you

Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.

Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
Prakash Kolli, Ph.D., P.E.

About the author

Prakash Kolli, Ph.D., P.E.

Contributing Writer · Founder, Dividend Power

Prakash Kolli is the founder of the Dividend Power site. He is a self-taught investor, analyst, and writer on dividend growth stocks and financial independence. His writings can be found on Seeking Alpha, InvestorPlace, Business Insider, Nasdaq, TalkMarkets, ValueWalk, The Money Show, Forbes, Yahoo Finance, and leading financial sites.
What this article covers

Brian Thorp compares a Roth IRA and a 401(k), including the Roth 401(k), across contributions, taxes, employer matching, early withdrawals, income limits and required minimum distributions, with the 2026 and 2027 contribution limits and a side-by-side table to help you decide where to save first.

Key Takeaways

1

Capture your full 401(k) employer match before funding a Roth IRA

A common match of 50% of the first 6% of pay turns a $6,000 contribution on a $100,000 salary into $9,000, an instant 50% return. After that, a Roth IRA often offers more investment choices and more flexible access to contributions.

2

401(k) limits are far higher than IRA limits in 2026 and 2027

You can defer up to $24,500 into a 401(k) in 2026 and $25,500 in 2027, versus $7,500 for an IRA in both years. Workers 50 and older can add catch-up contributions, and Roth IRA eligibility phases out at higher incomes, while Roth 401(k)s have no income limit.

3

Your tax rate today versus in retirement usually decides Roth vs. pre-tax

Higher earners often benefit from pre-tax contributions, while younger savers in lower brackets may favor Roth. Flexibility, saving habits, and plans to live abroad also matter, since some countries do not recognize a Roth IRA’s tax-free status.

The Roth IRA and 401(k) are two of the most popular retirement accounts. Choosing which strategy is best for your circumstance can be a tough decision. This article will compare the benefits of choosing a Roth IRA vs. 401(k) and help you decide where to save and invest for the long run.

What Are the Differences Between Investing in a Roth IRA vs. 401(k)?

The first significant difference between investing in a Roth IRA versus a 401(k) plan is how you go about making contributions. With a Roth IRA, the onus is on you to open the account (usually at a popular online brokerage company’s website) and then fund it. The contribution often comes from your checking or savings account, and it must be done with cash.

With a 401(k), contributions come directly from your paycheck through your employer’s payroll system. New employees usually elect 401(k) plan contributions to complete benefit enrollments. Investment choices are fewer in a 401(k) plan, but there will generally be a set of both stock and bond funds from which to choose. Many plans now offer a set of target-date mutual funds, too.

The second significant difference between a Roth IRA and 401(k) is the tax treatment. Roth contributions are made after-tax, while regular 401(k) deferrals are done pre-tax. That means you pay income tax today when putting money into a Roth IRA, while you get a current-year tax deduction when making 401(k) contributions.

Capture the Full 401(k) Employer Match

It’s also important to consider how employer matching contributions work within a 401(k) plan. Many firms have a matching policy; for example, 50% of the first 6% of contributions. That means, if you earn $100,000 and contribute $6,000 per year into your 401(k), your employer will pop in another $3,000 at no cost to you. That is an instant 50% return on your money in that scenario! It’s a great deal. Employer contributions are made pre-tax, regardless of whether you elect regular pre-tax contributions or Roth. Of course, there is no employer match with a Roth IRA.

Early Withdrawal Rules: Roth IRA vs. 401(k)

Here is a situation where a Roth IRA beats out the Roth 401(k): early withdrawals. Usually, pulling money out of your retirement comes with a penalty. That is not always the case with a Roth IRA since you can withdraw contributions at any time. The IRS also allows you to take out earnings from a Roth IRA penalty-free in some situations. Some of the more common reasons to take the earnings out of a Roth IRA early include money for a first-time home purchase, qualified education expenses, qualified medical expenses, and for disability or death. You can view the IRS list of all the reasons here.

Beyond Traditional 401(k)s, How Do Roth IRAs Differ From Roth 401(k)s?

Another trend that has emerged in the 401(k) space is the offering of a “Roth” 401(k). A Roth 401(k) works like a Roth IRA in some ways and like a 401(k) in other ways. We know that “Roth” means contributions are made after-tax. A Roth 401(k) is simply another employer-sponsored retirement account, but money in that account has already been taxed and will grow tax-free through retirement.

Roth IRAs Offer More Withdrawal Flexibility Than a Roth 401(k)

A Roth IRA differs from a Roth 401(k) in that contributions made to a Roth IRA can be withdrawn tax-free and penalty-free at any time. Inside a Roth 401(k), a nonqualified withdrawal before age 59½ includes a share of earnings, which can be taxed and hit with a 10% early withdrawal penalty.

2026 and 2027 Contribution Limits for Roth IRAs and 401(k)s

A Roth IRA also has a lower annual contribution limit than a Roth 401(k). According to the IRS, the maximum IRA contribution is $7,500 for both 2026 and 2027 ($8,600 for those age 50 or older). The most you can put into a 401(k) plan is $24,500 in 2026 ($32,500 for those age 50 or older, or $35,750 at ages 60 to 63), and the IRS raised that limit to $25,500 for 2027 ($34,000 at 50 or older, or $37,250 at ages 60 to 63). Those limits apply to combinations of Traditional IRA and Roth IRA contributions and Regular and Roth 401(k) contributions, respectively.

Roth IRA Income Limits for 2026 and 2027

You will not be able to contribute to a Roth IRA if your income exceeds certain thresholds. A Roth 401(k) does not have an income limit. For Roth IRAs, retirement savers should review rules determined by the IRS. For 2026, the ability to contribute phases out between $153,000 and $168,000 of modified adjusted gross income for single filers and between $242,000 and $252,000 for joint filers; for 2027, those ranges rise to $158,000 to $173,000 and $250,000 to $260,000. High-income individuals and couples should forecast their adjusted gross income for the year before making Roth IRA contributions.

FeatureRoth 401(k)Roth IRAPre-tax 401(k)
ContributionsAfter-taxAfter-taxPre-tax
2026 limit (under 50)$24,500$7,500$24,500
2027 limit (under 50)$25,500$7,500$25,500
Income limitsNonePhase-out starts at $153,000 single / $242,000 joint (2026)None
Employer matchIf offeredNoneIf offered
Qualified withdrawalsTax-freeTax-freeTaxed as ordinary income
Lifetime RMDsNone (since 2024)NoneStart at age 73
Table 1.Roth 401(k), Roth IRA, and Pre-tax 401(k) Retirement Accounts (IRS). Source: IRS Roth comparison chart and IR-2026-136.

Required Minimum Distribution Rules

Required Minimum Distributions (RMDs) are something to be mindful of with 401(k) plans. Your RMD is the minimum amount you must withdraw from your retirement account each year. The IRS does not allow retirees to leave money in a tax-sheltered vehicle. They want a cut of your nest egg! Under the SECURE 2.0 Act, retirement savers generally must begin taking Traditional IRA and regular 401(k) withdrawals at age 73, rising to 75 for those born in 1960 or later. (The original SECURE Act had already raised the starting age from 70½ to 72.)

Roth IRA money is not subject to RMDs during the owner’s lifetime, and starting in 2024, SECURE 2.0 also eliminated lifetime RMDs from Roth 401(k) accounts. Rolling a Roth 401(k) into a Roth IRA can still make sense for wider investment choices and simpler account management.

Stay connected

See more of Wealthtender when you search Google

Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.

When Should You Choose One vs. the Other (or a Mix of Both)?

Your situation is paramount when deciding on retirement saving strategies (like most aspects of long-term financial planning). However, it is wise to ensure you get the most out of these tax-advantaged accounts. Snatching the company 401(k) match is usually a good first move. Many millennial and Gen Z savers should investigate their plan vesting policies. If a company requires a worker to stay several years before the match is fully vested, putting your first savings dollar into the plan might not make sense. Nevertheless, contributing to a 401(k) up to the match is often a good first step toward saving for retirement.

Contribute to the 401(k) Plan Match, Then Go for the Roth IRA

After getting the match, focusing on putting the maximum to a Roth IRA can be a savvy move. Roth IRAs are more flexible than 401(k) plans since you can withdraw your contributions at any time tax-free and penalty-free. With more investing options, often at a lower cost, you can keep more of what’s yours in an IRA versus a 401(k).

“Once an individual is saving enough in their 401(k) to take advantage of the full company match, it usually makes sense to then save additional dollars to a Roth IRA (if their income allows this),” says Eric Simonson, financial planner and founder of Abundo Wealth. “The benefits of a Roth IRA over a 401(k) are: 1) You are the owner of the account, rather than a plan participant. 2) You have far greater investment options to add diversification and potentially lower your fees. And 3) Roth IRAs have more favorable withdrawal options, and these dollars are potentially more accessible than a 401(k).”

Use Online Resources to Help You Choose How to Save for Retirement

So, a mix of 401(k) and Roth IRA contributions makes sense for many people. Workers in their high-earning years are likely to be better off making pre-tax contributions (e.g., Traditional IRA contributions and regular 401(k) deferrals). In contrast, younger workers in their low-earning years might be better suited to choosing after-tax Roth contributions. Here is a tip: Be sure to research online calculators to help determine which contribution type and account type are ideal for your situation.

How Should a Super-Saver Make Retirement Contributions?

Super-savers can contribute to both a Roth IRA and 401(k). In 2026, a worker under age 50 could hypothetically put $7,500 into a Roth IRA and $24,500 into a 401(k), and in 2027, $7,500 and $25,500. The IRA limit can be made up of both Roth and Traditional IRA contributions. The same logic applies to 401(k) contributions: a plan participant’s payroll deferrals can be a mix of pre-tax and Roth money.

Know Your Saving Habits and Tax Rate

Always be sure to review your financial situation as the years go by, or hire a financial advisor such as a Certified Financial Planner who can work with you to understand your unique circumstances. The cost of hiring a financial advisor may be less than you think, as an increasing number of advisors offer subscription-based pricing or will charge a flat fee to build your personalized financial plan.

Knowing your marginal income tax rate is essential, as is the level of your emergency savings. Having a solid grasp of your hierarchy of saving priorities helps you optimize building long-term wealth.

Ask yourself: Are you a saver or spender? People who have a challenging time saving should consider making Roth contributions. With Roth IRA and Roth 401(k) contributions, retirement savings are made after-tax, so taxpayers do not get a bigger tax refund. Spendthrift individuals will not be tempted to spend the tax savings immediately. If you are a diligent saver, making pre-tax contributions and simply investing the current-year tax savings in a taxable account could make more sense.

The Better Move Might Come Down to Taxes

Here’s an example: Suppose $5,000 of retirement savings went into a Roth IRA, and the individual has a 22% marginal tax rate. You essentially pay $1,100 of income tax in the current year, but your account grows tax-free forever. With a pre-tax account, that $1,100 will show up in your tax refund the following spring when you file. Natural spenders might be tempted to make a big purchase with the tax savings. Meanwhile, that $5,000 (plus any growth) is subject to income tax upon withdrawal during retirement.

Special Circumstances for Foreign-Born Families

Depending upon your status as a US citizen, it’s essential to consider additional factors that could have a meaningful impact on your potential tax advantages of choosing a Roth IRA vs. 401(k). A financial advisor who specializes in working with immigrants and foreign nationals could prove invaluable to minimizing the risk of losing tax benefits.

“With the foreign-born families that I work with, there is always a possibility that they plan to go back to the country where they were born. In this case, then we consider whether the foreign country will recognize the tax-free nature of the Roth IRA,” says Jane Mepham, financial planner and founder of Elgon Financial Advisors. “Some countries like Germany do not and will tax the Roth IRA account again at withdrawal. In that case, I would shy away from having the client open a Roth IRA and have them stick with the 401(k) account.”

The Bottom Line on Roth IRA vs. 401(k)

Consider your current tax rate versus your tax rate in retirement when deciding on pre-tax or Roth contributions. If you are in a relatively high tax bracket today, pre-tax contributions might be the better play. Also, weigh the flexibility of a Roth IRA versus sometimes-stringent 401(k) plan rules. If you might need to pull money out of your retirement accounts, a Roth IRA is a better option. Of course, knowing your 401(k) plan’s employer matching rules is essential to getting the most bang for your retirement savings buck.

Frequently Asked Questions

Should I contribute to a 401(k) or a Roth IRA first?

A common approach is to contribute enough to your 401(k) to get the full employer match first, then fund a Roth IRA if your income allows, then return to the 401(k) for additional savings. The right order depends on your tax rate, investment options and how much flexibility you need.

How much can I contribute to a Roth IRA and a 401(k) in 2026 and 2027?

For 2026, you can contribute up to $7,500 to IRAs ($8,600 at 50 or older) and $24,500 to a 401(k) ($32,500 at 50 or older). For 2027, the IRA limit stays at $7,500 and the 401(k) limit rises to $25,500 ($34,000 at 50 or older). The limits are separate, so you can contribute to both.

Does a Roth 401(k) have income limits?

No. Roth 401(k) contributions are not limited by income. Direct Roth IRA contributions phase out between $153,000 and $168,000 of modified adjusted gross income for single filers in 2026 ($158,000 to $173,000 in 2027).

Do Roth 401(k)s have required minimum distributions?

Not anymore. Starting in 2024, SECURE 2.0 eliminated lifetime required minimum distributions from Roth 401(k) accounts, matching the Roth IRA rule. Traditional IRAs and pre-tax 401(k)s still require distributions starting at age 73 for most people.

Find your fit

Find financial advisors who specialize in helping people like you

Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

January 14, 2026

For many high earners, especially those with additional income streams, the bigger challenge is finding ways to continue saving beyond these limits in a tax-efficient way.

At the same time, it’s becoming increasingly more common for full-time employees to earn income outside their primary job. If you offer freelancing or consulting services, or maybe you’re turning your favorite hobby into an income source, you may need an LLC. This is especially true for 1099 contractors who earn meaningful self-employment income alongside a W-2 job. Not only can an LLC provide critical legal protections for business owners, but it also allows sole proprietors and their spouses to access additional retirement savings opportunities—as long as certain conditions are met.

One of the most compelling benefits is the ability to make post-tax contributions and convert them to Roth within a properly structured Solo 401(k), potentially creating a powerful source of tax-free retirement income.

Here’s why it may be worth establishing a separate retirement account, called a Solo 401(k), under your LLC.

What Is a Solo 401(k)?

A Solo 401(k) is a retirement plan, similar to a traditional 401(k), that’s designed specifically for self-employed individuals or business owners with no full-time employees (other than a spouse). This includes business owners and 1099 contractors who earn self-employment income, even if they also participate in an employer-sponsored retirement plan through a W-2 job. To be eligible to open and contribute to a Solo 401(k) under your LLC, you must earn income. 

A Solo 401(k) can be an especially advantageous offering for solopreneurs since it enables you to contribute as both the employee and the employer. As the employee, you can make contributions up to the annual limit. As the employer, your business can make additional profit-sharing contributions, subject to IRS limits tied to income and compensation.

Importantly, you can own and contribute to both a traditional 401(k) and a Solo 401(k), but both are subject to the same annual contribution limit—meaning your combined pre-tax contributions to both accounts cannot exceed $24,500 in 2026. However, this limit applies only to employee deferrals, not total contributions.

Solo 401(k) Strategies

While they can certainly work in tandem, each plan may serve a slightly different purpose within your retirement savings strategy. Your traditional plan can help you capture benefits tied to your employment, including employer matching, while your Solo 401(k) allows your business income to fund its own retirement strategy, often with more flexibility and higher overall contribution potential. For many high-income business owners and 1099 earners, that flexibility is what makes advanced Roth strategies possible.

Here are a few ways to leverage a Solo 401(k) alongside your traditional plan.

Hire Your Spouse

If your spouse can contribute to the business in a legitimate, documented role, paying them a reasonable wage is one way to increase access to tax-advantaged retirement savings. As an employee of the LLC, your spouse may be eligible to contribute to the Solo 401(k) up to the annual employee deferral limit. The business can also make employer contributions on their behalf.

By including your spouse as an employee, you may be able to meaningfully increase household retirement savings while keeping your business income within the family.

Optimize Your Employer Matching

Most employers who offer 401(k)s to employees will include contribution matching to incentivize participation. Often, the matching contributions are limited to a certain percentage or dollar amount, say 3% of the employee’s salary.

If you or your spouse receives an employer match through a W-2 job, continue contributing up to the matching limit. This is essentially free money from your employer, which can compound greatly between now and retirement.

Once you reach the employer matching limit, consider then focusing your contributions on your Solo 401(k) instead. You can direct additional employee deferrals into the Solo 401(k) and layer in employer contributions from your business, essentially achieving tax-deferral benefits from both plans.

Customize Your Investment Options

Employer 401(k)s are often limited to a few predetermined funds or strategies, often target-date mutual funds. They’re trying to find the most generally beneficial solution for a wide range of people. With a Solo 401(k), however, you have the flexibility and control to create a tailored investment lineup that fits your investment needs, comfort level with risk, and timeline towards retirement. Depending on the custodian and structure, you may have access to a much broader investment universe, including ETFs, private investments, and alternative strategies.

Create Potential Tax-Free Retirement Income with Roth Conversions

Certain 401(k) plan structures allow participants to make post-tax contributions, which can be converted into Roth accounts through a Roth conversion or mega backdoor Roth conversion. Over time, this can help build a pool of tax-free retirement assets alongside traditional, tax-deferred savings. This is one of the most powerful planning opportunities available to high-income business owners and 1099 contractors.

When designed correctly, a Solo 401(k) may allow you to contribute beyond standard pre-tax limits by making post-tax contributions and converting them to a Roth. The maximum allowable contribution to a 401(k) is $72,000 in 2026. This includes both employee and employer contributions and may also include post-tax contributions depending on plan design. [Editor’s note: For 2027, the IRS raised the employee deferral limit to $25,500 and the total limit to $75,000.]

Roth conversions can be technically complex and often require certain stipulations or criteria to be effective. Check with your advisor and plan provider first before pursuing a conversion.

Making the Most of Your 401(k) in 2026 and Beyond

If you tend to meet the maximum contribution limits on your workplace retirement plan before the year is over, a Solo 401(k) through your LLC could offer additional planning opportunities. This can be especially valuable for 1099 contractors and business owners who want greater control over how and where they save for retirement. If you’re considering opening and contributing to a new plan, speak with a financial advisor first. Our team at Envision can help you understand the contribution rules, investment options, tax considerations, and more. Schedule a call to get started.

Sources:

  1. https://www.irs.gov/newsroom/401k-limit-increases-to-24500-for-2026-ira-limit-increases-to-7500

This article was originally published here and is republished on Wealthtender with permission.

Headshot of Sean Gerlin, CFP®, CPWA®, ChFC®, CLU®
Sean Gerlin, CFP®, CPWA®, ChFC®, CLU® Creating Clarity Out Of Complexity

Sean Gerlin, CFP®, CPWA®, ChFC®, CLU® | Envision Wealth Planners

A Year-End Financial Checkup

As 2025 draws to a close, it’s the perfect time to pause, reflect, and take inventory of your financial progress. Start by reviewing the goals you set at the beginning of the year. Which milestones did you achieve? Take a moment to celebrate those wins – each represents meaningful progress toward your long-term wealth and life goals.

Next, look at the goals that are still in progress. Are you on track to complete them before year-end? Would a course correction – such as rebalancing investments, adjusting tax strategies, or reviewing cash flow – help you finish strong? These conversations are best had in partnership with your financial planner, who can help you prioritize high-impact actions before December 31.

The final quarter of the year is an ideal time to make intentional financial moves that can significantly reduce your tax liability, align your portfolio with your broader wealth goals, and set the stage for a stronger year ahead.

Why 2025 Is a Pivotal Year for Tax Planning

The One Big Beautiful Bill Act (OBBBA) that was passed in July 2025 introduced meaningful changes, and understanding how these impact high-net-worth taxpayers is essential for strategic year-end tax planning.

SALT Deduction Cap Increases in 2025

The State and Local Tax (SALT) deduction cap was increased from $10,000 to $40,000, rising by 1% each year through 2029. However, the expanded deduction phases out once modified adjusted gross income (MAGI) exceeds $500,000, returning the maximum deduction to $10,000.

This change means that high-income households just under that threshold may benefit from a larger deduction – at least temporarily. If you anticipate being close to the phase-out limit, your financial planner can help determine whether strategies such as deferring income or accelerating deductions might help you optimize the SALT benefit before the window closes.

Charitable Deduction Adjustments

Charitable giving remains a core element of year-end tax planning, but the OBBBA imposes new limits beginning in 2026. Under the new rules:

  • Taxpayers who itemize will forgo an amount equal to 0.5% of adjusted gross income (AGI) when calculating charitable deductions.
  • For example, a taxpayer with $400,000 in AGI will lose the deduction on the first $2,000 of donations.
  • Additionally, those in the top tax bracket will only be able to deduct at a 35% rate, down from 37%.

For high-income individuals, this makes 2025 a crucial year to accelerate charitable giving. One effective strategy is to fund a Donor-Advised Fund (DAF) before year-end, which allows you to take a full deduction for 2025 and distribute gifts to charities over time. Another technique is “bunching” charitable contributions – making several years’ worth of gifts in one tax year to maximize your itemized deduction before the new limitations apply.

Year-End Strategies for Tax-Efficient Giving

For those holding long-term appreciated investments, donating these securities can deliver a double benefit:

  1. You receive a charitable deduction based on the investment’s fair market value, and
  2. You avoid paying capital gains tax on the appreciation.

If you’ve owned the asset for more than one year, this strategy can meaningfully enhance the tax impact of your giving while aligning with your philanthropic goals. Remember that your deduction is limited to 30% of AGI for long-term capital gain property, but any excess can be carried forward for up to five years.

Maximize Tax-Deferred Opportunities

If you’re still in your working years, make sure you’re taking full advantage of retirement and health-related savings accounts before year-end.

  • 401(k) Contributions: The 2025 elective deferral limit is $23,500, and if you’re age 50 or older, you can also make an additional “catch-up” contribution of $7,500. And be sure to see if your employer sponsors a “super catch-up” contribution, which allows an additional $11,250 on top of the standard catch-up for those aged 60 to 63. [Editor’s note: The super catch-up replaces the standard catch-up rather than adding to it, so savers aged 60 to 63 can contribute up to $11,250 in catch-up contributions in total. For 2026, the deferral limit is $24,500 with an $8,000 standard catch-up; for 2027, the IRS raised those limits to $25,500, $8,500 and $11,750.]
  • Health Savings Accounts (HSAs): If you’re enrolled in a high-deductible health plan (HDHP), an HSA provides triple tax benefits – contributions are deductible, growth is tax-free, and qualified withdrawals are also tax-free.

Review your open enrollment options, adjust payroll deductions as needed, and consider increasing contributions before December 31 to capture the full tax benefit for the year.

Qualified Charitable Distributions

For those age 70½ or older, Qualified Charitable Distributions (QCDs) from an IRA can satisfy part or all your Required Minimum Distribution (RMD) while excluding that amount from taxable income. It’s a tax-efficient way to give back while managing the impact of RMDs on your overall income.

Roth Conversions

Converting a portion of traditional IRA assets to a Roth IRA may make sense now – especially if you expect to be in a higher tax bracket later.

Tax-Loss Harvesting

If your taxable accounts have underperforming investments, harvesting capital losses can offset gains and reduce your overall tax bill. Just remember the wash-sale rule, which prohibits repurchasing a substantially identical security within 30 days.

Final Thoughts: Make 2025 a Year of Action

Year-end tax planning isn’t just about saving money – it’s about proactively managing wealth in a changing legislative landscape. High-net-worth families who act early and plan strategically can minimize future tax exposure, preserve more wealth for future generations, and continue supporting the causes they care about most.

Before the end of 2025, review your income, deductions, charitable giving, and investment strategies with your financial advisor. This is a rare window where timing, coordination, and execution can lead to lasting benefits.

Coordinating with your fiduciary financial advisor / wealth manager, CPA, and estate attorney ensures your strategy remains aligned with your broader goals. For high-net-worth individuals, integration across tax, investment, and estate planning is key – especially as legislative changes continue to evolve.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

Headshot of John Foligno, CMC®
John Foligno, CMC® Providing tax-efficient financial counsel to professionals and business owners.

John Foligno, CMC® | Grand Life Financial

Your SGLI Benefits and the HEART Act: A Golden Opportunity for Your Future

As a Gold Star Widow, you have already given so much in service to our country. The loss of your spouse represents the ultimate sacrifice, and while nothing can replace what you’ve lost, there are financial tools available to help secure your future and honor their memory through wise financial planning.

If you’ve received Servicemembers’ Group Life Insurance (SGLI) benefits and Death Gratuity payments, you have a unique opportunity that most people or even the typical financial advisors don’t know about. Thanks to some legislation called the HEART Act, you can put these entire benefits into a special type of retirement account called a Roth Individual Retirement Account (IRA). This choice could mean hundreds of thousands of extra dollars for you and your family over time.

Think of this as planting a seed that will grow into a mighty oak tree over the years. The money you plant today can grow tax-free for decades, giving you and your children a much brighter financial future as a gift of love from your late spouse and as a debt of gratitude from our nation.

What is SGLI and Death Gratuity and Why They Matter to You

Servicemembers’ Group Life Insurance, or SGLI for short, is life insurance that the military provides for service members. When a service member dies, their family receives this insurance money. The current SGLI benefit is $500,000 for most military families.

Along with SGLI, you may also be eligible for the Death Gratuity benefit. This is a special tax-free payment of $100,000 that goes to eligible survivors of members of the Armed Forces who die while on active duty or while serving in certain reserve statuses. The Death Gratuity is the same regardless of the cause of death and is exempt from federal income tax. This benefit is typically paid out within 72 hours of receiving DD Form 397 so most people recieve this benefit before SGLI.

Together, these benefits can total $600,000. This money is meant to help you and your family during this difficult time. It can pay for immediate needs like funeral costs, daily expenses, and help replace the income your spouse provided. For many Gold Star families, these benefits represent the largest amount of money they will ever receive at one time.

Both the SGLI benefit and Death Gratuity come to you tax-free. This means you don’t have to pay income taxes on this money when you receive it. This is already a huge advantage, but there’s an even bigger opportunity available to you through the HEART Act.

Understanding the HEART Act: A Gift for Military Families

The Heroes Earnings Assistance and Relief Tax Act, known as the HEART Act, became law in 2008. Congress created this law specifically to help military families who lost loved ones in service to our country. The law recognized that these families needed special help and deserved special treatment when it comes to taxes and retirement savings.

One of the most powerful parts of the HEART Act deals with something called “qualified military death benefits.” Both your SGLI payment and Death Gratuity fall into this category. The HEART Act says that if you receive these benefits, you can put the money into retirement accounts in ways that other people cannot.

Normally, there are strict limits on how much money you can put into retirement accounts each year. For 2024, most people can only put $7,000 per year into an IRA. [Editor’s note: For 2026 and 2027, the IRS limit is $7,500, or $8,600 at age 50 or older.] If you wanted to put $600,000 into an IRA the standard way, it would take you many decades! But the HEART Act changes this rule for military families like yours.

The Roth IRA Opportunity: Your Path to Tax-Free Growth

A Roth Individual Retirement Account, or Roth IRA, is like a special savings account for retirement. What makes it special is that once you put money into it, that money can grow for decades without you paying taxes on it again (subject to certain restrictions). Not when it grows, not when you take it out in retirement, and not when you pass it on to your children.

Here’s how it normally works: You put money into a Roth IRA after you’ve already paid taxes on it. The money then grows tax-free. When you retire and take money out, you don’t pay any taxes on what you withdraw. It’s like planting a seed with after-tax dollars and harvesting a tax-free tree years later.

The HEART Act gives you something amazing: the ability to put your entire SGLI benefit and Death Gratuity into a Roth IRA, even though it’s much more than the normal annual limits. You can contribute up to the full amount of your qualified military death benefits. So if you received $500,000 in SGLI benefits and $100,000 in Death Gratuity, you could potentially put all $600,000 into a Roth IRA.

The long-term benefits of this opportunity are truly life-changing.

The Amazing Long-Term Benefits of This Choice

When you put your SGLI and Death Gratuity benefits into a Roth IRA through the HEART Act, you’re setting yourself up for incredible long-term growth. Let’s look at what this could mean for your future with some real numbers.

Imagine you put the full $600,000 into a Roth IRA and let it grow for 30 years. If your investments earn an average of 7% per year (which is reasonable for a long-term investment mix), your $600,000 could grow to over $4.5 million. And remember, you would never pay taxes on any of this growth or when you withdraw it in retirement.

But the benefits go far beyond just the numbers. Here are the key advantages that make this opportunity so special:

Tax-Free Growth Forever: Once your money is in the Roth IRA, it grows without any tax burden. Every dollar of growth is yours to keep. Compare this to a taxable savings or brokerage account where you pay taxes on interest, or a traditional IRA where you pay taxes when you withdraw money in retirement.

No Required Withdrawals: Unlike traditional retirement accounts that force you to start taking money out at age 73-75 (see SECURE Act 2.0), Roth IRAs have no required minimum distributions during your lifetime. This means your money can keep growing for as long as you want it to, even well into your retirement years.

Tax-Free Legacy for Your Children: When you pass away, your children can inherit your Roth IRA and continue to benefit from tax-free growth. This means the sacrifice your spouse made can continue to bless your family for generations to come. Your children will be required to withdraw the money over 10 years, but all of those withdrawals will be completely tax-free to them.

Flexibility When You Need It: This is one of the most common questions and hesitations from clients … “What about needing some of the funds in the near term, not just for retirement?” While the Roth IRA is designed for retirement, you can withdraw your original contributions (the $600,000 you put in) at any time without taxes or penalties. This gives you a safety net if you face a true emergency or just need withdrawals built into the plan along the way. The growth portion has some restrictions if you withdraw it before age 59½, but your original contribution is always available to you.

Let’s look at another example to show the power of time. If you’re 35 years old when you make this contribution and let it grow until you’re 65 (30 years), your $600,000 could become over $4.5 million. If you’re 25 years old, that same money growing for 40 years could become over $8.9 million. The longer it compounds, the more powerful this becomes.

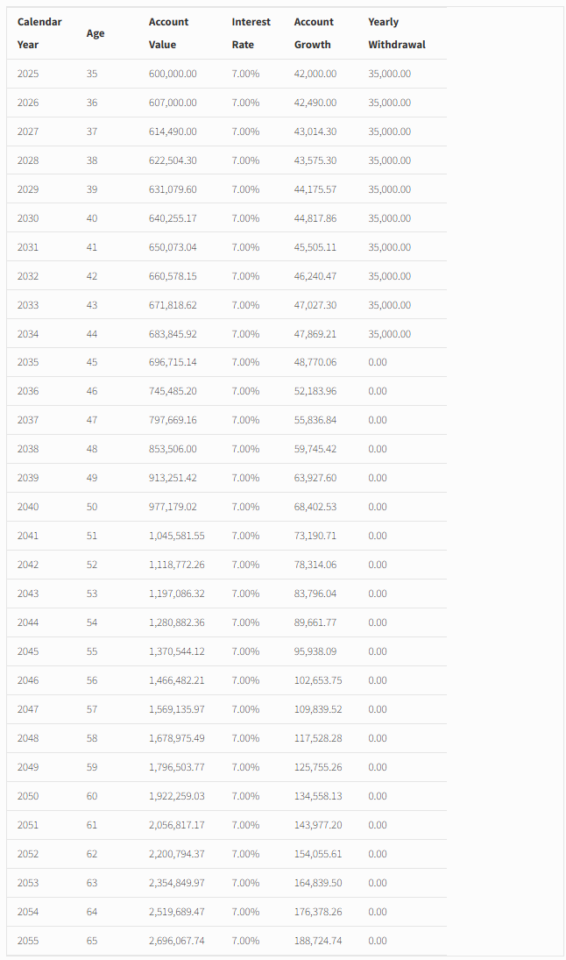
Even if you need to use some of the money along the way, you’re still far ahead. Let’s say you withdraw $350,000 over 10 years for various needs while still having kids in the house and taking the time to figure out what is next. In that case, the original contribution plus account growth is still on track to set you up for future retirement needs very nicely with a projected balance of more than $2.6M at age 65.

A table shows yearly projections from 2025 to 2055 of age, account value, 7% interest rate, account growth, and yearly withdrawal, with withdrawals of $35,000 each year from 2025 to 2037, then $0 withdrawals afterward.
The growth that remains continues to compound tax-free, still giving you a substantial tax-free retirement benefit

How to Actually Do This: Your Step-by-Step Guide

Making this HEART Act Roth IRA contribution might seem overwhelming, but the process is straightforward when you break it down into steps. Here’s exactly what you need to do:

Step 1: Know the Timeline – You Have One Year: The most important thing to know is that you must make this contribution within one year of receiving your SGLI benefits. This deadline is firm, so don’t wait. Mark your calendar with the one-year anniversary of when you received these benefits. Ideally you want to have this completed several months ahead of time in case there are questions or complications.

Step 2: Choose a Financial Institution: You can open a Roth IRA at most banks, credit unions, or investment companies. Look for institutions that offer low fees and good investment options. Some popular choices include Vanguard, Fidelity, Schwab, and you would be well served at either of those. You can also work with a financial advisor like Wise Stewardship Financial Planning who can help you choose the right place and investments.

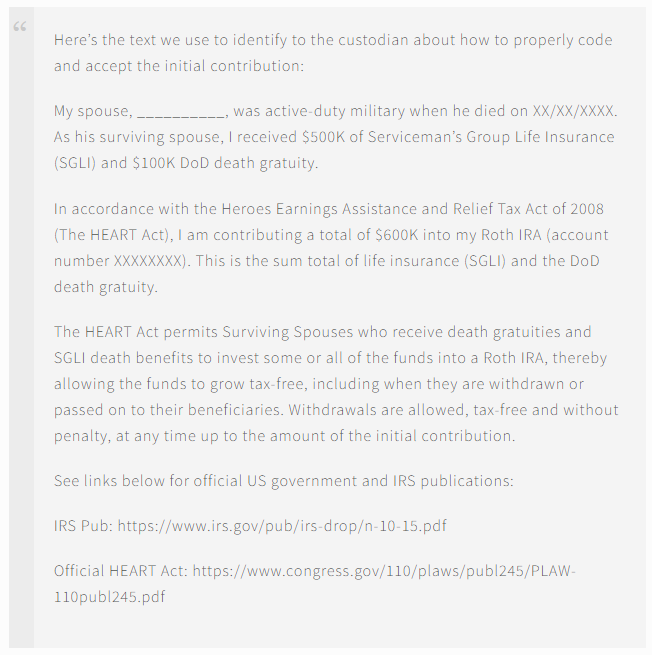
Step 3: Open Your Roth IRA Account: When you open the account, tell them you want to make a HEART Act contribution. Don’t be surprised if the representative on the phone doesn’t know what that is. Instead, typically use written correspondence with references to legislation and IRS publications. You may need to provide documentation showing that you received qualified military death benefits. Typically though, the custodian knows you have to keep the proof in case of IRS questions so they rely on your application.

A light gray text box containing a statement about coding military survivor benefits, mentioning Serviceman’s Group Life Insurance (SGLI), DoD death gratuity, and referencing IRS and congressional publications. Some details are redacted.

Step 4: Make the Contribution: You can contribute up to the full amount of your qualified military death benefits. This includes both SGLI ($500,000) and Death Gratuity ($100,000) for a total of up to $600,000. You don’t have to contribute the full amount (but it is generally best practice to fund it all at once) if you don’t want to or if you need some of the money for other purposes. But in most cases even if you plan to use some of the funds as discussed above, you can withdraw the original contribution amounts as needed with no taxes and penalties.

Step 5: Choose Your Investments: Once the money is in your Roth IRA, you need to invest it. Leaving it in cash or a savings account won’t give you the growth you need. Consider a diversified mix of stock and bond funds based on your age and risk tolerance.

Step 6: Keep Good Records: Save all documentation about your contribution, including records of your SGLI and Death Gratuity payments, and your Roth IRA contribution paperwork. You’ll need this for your tax records, especially for withdrawals of the contribution basis prior to your age 59 1/2.

Other Things to Think About

Making the decision to put your SGLI and Death Gratuity benefits into a Roth IRA is a big choice, and it’s normal to feel overwhelmed. As someone who has walked this path of grief and brain fog myself, I understand the things that can cloud your thinking during grief.

When I became a widower after my wife Sarah passed away, I experienced firsthand what grief brain fog feels like. Simple decisions became difficult. I would forget where I put my keys, struggle to remember conversations, and feel exhausted even after a full night’s sleep. More than nine out of 10 widows experience this brain fog, according to studies by Modern Widows Club, so if you’re feeling this way, you’re not alone.

During my grief journey, I learned that making major financial decisions while dealing with brain fog and the pain of loss requires extra care and support. That’s why it’s so important to think through all aspects of this decision before you act.

How This Fits with Your Other Financial Goals: Before putting all of your benefits into a Roth IRA, consider your complete financial picture. Do you have an emergency fund with 3-6 months of expenses? Are there any immediate debts you need to pay off? What other life insurance or retirement and investement accounts are also available for needs now and in the future?

You don’t have to put the entire $600,000 into the Roth IRA. You might choose to put $400,000 into the Roth IRA and keep $200,000 for immediate needs and emergency funds. Or you might put in the full amount if you have other resources to cover your short-term needs. The key is making a thoughtful decision that fits your unique situation.

Think About Your Timeline: The Roth IRA is most powerful when you can let the money grow for many years. If you’re younger, this opportunity is even more valuable because you have more time for compound growth. If you’re closer to retirement age, you will still benefit greatly, especially considering the tax-free legacy you can leave to your children.

When Professional Help Makes Sense: During my own grief journey, I learned that sometimes we need to lean on others for support. Just as I relied on my family, church, fellow widowed spouses, and an invaluable grief counselor to help me move forward, you might benefit from professional financial guidance during this difficult time.

A financial planner who understands grief and military benefits can help you work through the brain fog and make decisions that align with your values and goals. They can help you see the big picture when everything feels overwhelming and ensure you’re making choices that honor your spouse’s memory while securing your future.

Don’t Rush, But Don’t Wait Too Long: You have one year to make this decision, but that doesn’t mean you should wait until the last minute. Grief has a way of making time feel strange – some days crawl by while months seem to disappear. Set a target date well before your deadline so you have time to think through your options without pressure.

Remember, there is no “moving on” from grief – it will always be a part of you. But there is moving forward and taking the next step. Making wise financial decisions during this time is one way to honor your spouse’s sacrifice while building security for your future.

Key Takeaways and Your Next Steps

Your SGLI and Death Gratuity benefits represent more than just insurance money – they represent your spouse’s final gift to you and your family. Through the HEART Act, you have a unique opportunity to turn this gift into lasting financial security that can benefit you and your children for decades to come.

Here’s what you need to remember:

  • You can contribute up to $600,000 ($500,000 SGLI + $100,000 Death Gratuity) to a Roth IRA under the HEART Act
  • This money will grow tax-free for the rest of your life and can be passed tax-free to your children
  • You have one year from receiving these benefits to make this contribution
  • The earlier you do this, the more powerful the long-term growth becomes

The potential is enormous. This isn’t just about money – it’s about creating the financial freedom to live the life your spouse would have wanted for you and your family.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

Headshot of Daniel Kopp, CFP®, MA
Daniel Kopp, CFP®, MA Financial planning and advice for widows and widowers across the U.S.

Daniel Kopp, CFP®, MA | Wise Stewardship Financial Planning

Are you familiar with the concept of a Backdoor Roth IRA contribution? If not, you may be missing out on a powerful wealth-building strategy that could enhance your retirement savings. In this article, we will dive deep into this specialized strategy and unveil its immense potential benefits.

For many Americans with higher incomes, a regular contribution directly into a Roth IRA may not be possible if their earnings fall above the stated IRS threshold.  A Backdoor Roth IRA contribution is a lesser-known method that can help these high-income earners bypass these regular Roth IRA contribution limits and still be able to fund a Roth each year. By first making nondeductible contributions to a Traditional IRA and then converting them to a Roth IRA, individuals can take advantage of tax-free growth and withdrawals in retirement.

In this comprehensive guide, we will demystify the process of making Backdoor Roth IRA contributions. We’ll explore the eligibility criteria, potential tax implications, and step-by-step instructions to help you maximize this strategy’s benefits. Additionally, we’ll address common misconceptions and potential pitfalls to ensure you make informed decisions.

Read on to learn more about how you can take advantage of this lesser-known financial tool and how it can help grow your tax-advantaged savings bucket for retirement.

Understanding the Benefits of a Backdoor Roth IRA

Retirement planning is a crucial aspect of financial security, and maximizing the benefits of tax-advantaged accounts can be a smart move. While regular Roth IRA contributions have income limits that may restrict high earners, the Backdoor Roth IRA strategy offers an alternative solution.

The primary benefit of a Backdoor Roth IRA contribution is the ability to bypass these income limits, allowing high-income individuals to enjoy the long-term benefits of tax-free growth potential and tax-free withdrawals in retirement.

Additionally, the Backdoor Roth IRA contribution allows for increased flexibility in retirement planning. Unlike traditional retirement accounts that require minimum distributions at a certain age, Roth IRAs have no required minimum distributions (RMDs). This means that you can let your investments grow tax-free for as long as you desire, providing more options for managing your retirement income.

Lastly, a Backdoor Roth IRA can provide estate planning benefits as well. For surviving spouses, they can roll the inherited Roth IRA into a Roth IRA in their own name, allowing them to treat the assets like their own and extending the tax-free benefits. As long as the original account was a Roth IRA and the assets were in the account for 5 years or more, distributions could be tax-free. For non-spouses, the beneficiaries would need to establish an inherited Roth IRA and follow the standard Required Minimum Distribution (RMD) rules, which dictate distributing the entire account within 10 years of the original owner’s death. However, unlike inherited Traditional IRAs, these required distributions would be tax-free.

Traditional IRA vs. Roth IRA: What’s the Difference

Before diving into the specifics of the Backdoor Roth IRA contribution strategy, it is crucial to understand the differences between a Traditional IRA and a Roth IRA. While both types of accounts offer tax advantages, they have distinct characteristics that can impact your retirement savings.

A Traditional IRA allows for tax-deductible contributions, meaning that you can reduce your taxable income for the year. However, these accounts are tax-deferred, meaning future withdrawals from a Traditional IRA in retirement are eventually subject to income tax (and a 10% penalty if distributions are made before age 59.5). Traditional IRAs also come with Required Minimum Distributions (RMD) beginning at age 73 (age 75 for those born in 1960 or later), which are taxable at ordinary income rates.

On the other hand, Roth IRA contributions are made with after-tax dollars and do not provide an immediate tax deduction. However, future growth and withdrawals in retirement are tax-free (as long as the Roth has been open for at least 5 years). RMDs also do not apply to Roth IRAs, providing the potential for future income tax savings as well as the potential for extended tax-free growth.

Step-by-Step Guide to Making Backdoor Roth IRA Contributions

Now that you understand the benefits and differences between a Traditional IRA and a Roth IRA, let’s dive into the process for making Backdoor Roth IRA contributions. While the process may seem complex at first, following this step-by-step guide can help simplify the process.

Check Your Eligibility

As stated previously, high-income earners may be limited in their ability to make regular Roth IRA contributions due to the imposed income limits. For 2024, single filers making $161,000 or more and those that are married filing jointly making $240,000 or more cannot contribute directly to a Roth IRA; therefore, these individuals may be able to do a Backdoor Roth IRA. [Editor’s note: Those were 2024 figures. For 2026, direct Roth IRA contributions phase out completely at $168,000 for single filers and $252,000 for joint filers; for 2027, the IRS raised those thresholds to $173,000 and $260,000.] However, it is also very important to be aware of any existing pre-tax IRA accounts you may have currently, which can impact the ability for you to do the Backdoor Roth IRA tax-free. This is known as the Pro-Rata Rule, which determines what percentage of an IRA distribution (or conversion to a Roth) is taxable when an account owner has both pre-tax and after-tax dollars in their IRAs.

The IRS views IRA balances as one large bucket irrespective of how many accounts an individual has open, so it is very important to be aware of this rule prior to proceeding with a Backdoor Roth IRA. To provide an example, let’s say an individual has $100,000 of pre-tax dollars in an existing Traditional IRA account. The individual then decides to proceed with a Backdoor Roth IRA and makes a maximum, non-deductible contribution of $7,000 into the existing Traditional IRA account (or a new Traditional IRA account) to start the process. Since the $7,000 is non-deductible and considered after-tax dollars, the individual now has 7% of after-tax dollars and 93% pre-tax dollars across all Traditional IRAs combined.  As a result, when the individual tries to only convert the $7,000 into the Roth, this conversion would not be 100% tax-free. Instead, only 7% of it would be tax-free, while the remaining 93% (or $6,510) would be counted as taxable.

Make a Nondeductible Contribution to a Traditional IRA

Assuming you are a high-earner and have no pre-tax IRA balances, you may proceed to the next step of making a non-deductible contribution to a Traditional IRA. As a reminder, there are no income limits for making Traditional IRA contributions. Income limits only apply to your ability to receive a tax deduction for an IRA contribution, which are much lower than Roth IRA income limits and generally not available to high-earners. Once you make the non-deductible contribution, be sure to leave the funds invested in cash or in a low-interest bearing cash equivalent. Any earnings during the period between the non-deductible contribution and subsequent conversion to a Roth would be taxable, so keeping interest/earnings low while the funds are in the Traditional IRA is very important.

Convert the Traditional IRA to a Roth IRA

After making a nondeductible contribution to your Traditional IRA, the next step is to convert the balance to a Roth IRA. This conversion can be done by contacting your financial advisor or IRA custodian and following their specific process. In terms of timing, you may consider converting the funds very quickly within a matter of days, or within a matter of weeks or months. It is important to remember that any earnings during the period between the non-deductible contribution date and the date of the conversion would be taxable. Converting fairly quickly could potentially help eliminate any potential earnings, making the contribution tax-free.

Pay Taxes on the Conversion

Since the conversion involves moving funds from a pre-tax account to a post-tax account, you may be required to pay taxes on the earnings of the converted amount as stated in Step 3. This is why it is important to leave the non-deductible contribution funds uninvested while in the IRA and consider the timing of when you convert to the Roth IRA.

Maximize the Benefits

  1. Once the conversion is complete, your funds are now in a Roth IRA, allowing for tax-free growth and tax-free withdrawals in retirement. It is also ideal to continue making Backdoor Roth IRA contributions on an annual basis, if possible, to further maximize your tax-free savings for retirement.

As always, it is highly recommended to work with your tax professional and a qualified financial planner with expertise in Backdoor Roth IRAs, like our team at Tenet Wealth Partners, when considering this move. This is important not just for the short-term but also how to incorporate this strategy into your long-term financial plan.

Common Mistakes to Avoid When Making Backdoor Roth IRA Contributions

While the Backdoor Roth IRA contribution strategy can be a powerful tool for high-income earners, there are common mistakes that individuals should be aware of and avoid. By understanding a few of these pitfalls, you can navigate the process with confidence and avoid potential complications.

Not Being Mindful of the Pro-Rata Rule

As stated above in the step-by-step guide, the pro-rata rule is critical to be aware of before proceeding with a Backdoor Roth IRA. Not understanding how existing pre-tax IRA balances can impact this process can lead to additional, unwanted income tax.

Not Tracking After-Tax Basis of Your IRA

Related to the above, another common mistake is forgetting to track your basis in the Traditional IRA. Basis refers to the after-tax contributions made to the Traditional IRA. It’s important to keep a record of these contributions to accurately calculate the taxable portion of any future conversion (or distribution) from an IRA.  A tax professional can help keep track via IRS Form 8606, which records non-deductible contributions you made to traditional IRAs.

Ignoring the 5-Year Rule

It is important to remember that Roth IRA contributions, including Backdoor Roth IRA conversions, are subject to the 5-year rule. This rule dictates that you must wait five years after making your first contribution to avoid potential taxes when taking withdrawals from the account. In other words, if you are going to need the funds you want to contribute to a Backdoor Roth IRA within 5 years, you may consider holding off.

Tips for Maximizing the Benefits of a Backdoor Roth IRA

To fully optimize the benefits of a Backdoor Roth IRA contribution, and follow the process the right way, consider the following tips.

Consult with a Qualified Financial Advisor

Getting guidance from a financial advisor with expertise and experience with Backdoor Roth IRAs can help you navigate the complexities and nuances while tailoring it to your specific financial situation.

Consult with Your Tax Professional

Given the numerous tax considerations and other related rules, it is always advisable to work with your CPA to understand the potential impacts from a tax perspective.

Consider the Long-term Benefits

While the upfront tax benefits may not seem as attractive as a Traditional IRA, the tax-free growth potential and tax-free withdrawals in retirement make the Backdoor Roth IRA a powerful tool for long-term wealth accumulation.

Plan Conversions Strategically

Timing your conversions to minimize tax liabilities can be a smart move. Consider factors such as your current tax bracket, potential future income changes, and the impact on your overall tax situation.

Stay Organized

Keeping clear records of your contributions, conversions, and tax implications is essential for accurate reporting and ensuring compliance with IRS regulations.

Frequently Asked Questions About Backdoor Roth IRA Contributions

  1. Are there income limits for a Backdoor Roth IRA contribution?  No. While there are income limits for making regular, direct contributions to a Roth IRA, the Backdoor Roth IRA contribution strategy allows high-income earners to bypass those limits. However, if your income falls below these stated income limits, then you may consider making a regular, direct contribution instead.
  2. Can I make a Backdoor Roth IRA contribution if I already have a Traditional IRA?  Technically, yes. However, it’s very important to consider the tax implications of the pro-rata rule, and it is highly recommended to work with your tax professional and a qualified financial planner if considering this move.
  3. Is there a limit to how much I can contribute through a Backdoor Roth IRA?  For 2024, the maximum contribution limit for individuals under the age of 50 is $7,000, with an additional catch-up contribution of $1,000 for individuals aged 50 and above. Keep in mind that this maximum applies to IRA and Roth contributions combined and is not separate for each account type. [Editor’s note: For 2026 and 2027, the limit is $7,500, with a $1,100 catch-up at age 50 and older.]
  4. Do I have to pay taxes on the converted amount in a Backdoor Roth IRA?  Potentially. As mentioned above, any earnings between the date of the non-deductible contribution and the date of the conversion are subject to income tax. This why it is important to leave the contributed funds in cash while in the Traditional IRA and also consider the timing of how quickly you convert to the Roth IRA. Again, it’s important to consult with a tax professional and experienced financial planner to understand any potential tax implications based on your individual circumstances.

Wrapping Up: Unlocking the Full Potential of Backdoor Roth IRAs

The Backdoor Roth IRA contribution strategy is a powerful wealth-building tool that can enhance your retirement savings, particularly for high earners. By understanding the benefits, nuances, and tax implications of Traditional and Roth IRAs, you may be able to leverage this strategy to magnify the benefits and further build your retirement nest egg. Remember to follow the step-by-step guide, avoid common mistakes, and consult with your tax professional and financial planner to ensure you make informed decisions. With careful planning and execution, you can unlock the full potential of this strategy and pave the way to a more secure financial future.

At Tenet Wealth Partners, our financial advisors have deep expertise in retirement planning and tax-advantaged savings strategies, including Backdoor Roth IRAs. Our team can help alleviate any concerns of potential pitfalls and simplify the process of utilizing the Backdoor strategy on an annual basis. Contact our team today or schedule an appointment to learn more about this strategy and how you can potentially incorporate it into your overall financial plan and retirement savings strategy.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

Headshot of Kevan Melchiorre, CFP®
Kevan Melchiorre, CFP® Fiduciary Financial Advisor Based in Champaign, IL

Kevan Melchiorre, CFP® | Tenet Wealth Partners

What this article covers

Find financial advisors in Lexington, Kentucky ready to help with your financial planning needs so you can enjoy life more with less money stress.

Financial Advisor Directory for Lexington, Kentucky

📍 Map: Financial Advisors with their Primary Office Location in Lexington

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Lexington.

📍Double-click or pinch pins to view more.

Showing

Key Takeaways

1

You can compare Lexington financial advisors by credentials, specialty and verified client reviews before you contact anyone.

The map shows advisors whose primary office is in Lexington. Profiles include Certified Advisor Reviews™, designations such as the CFP® and the services each advisor offers.

2

Lexington’s university, nearby Toyota plant and Kentucky’s retirement income rules shape the planning help many residents need.

University of Kentucky faculty, clinicians and staff often coordinate several workplace plans, while Toyota’s Georgetown plant and employers such as Lockheed Martin and Amazon bring manufacturing and corporate pay. Retirees can exclude up to $31,110 of pension and retirement plan income from Kentucky tax, with income above that taxed at a flat 3.5% for 2026.

3

Interview more than one advisor and confirm how each one is paid.

Ask about services, fees and whether the advisor acts as a fiduciary, then check their background for free on the SEC’s Investment Adviser Public Disclosure website before you hire.

Financial Planning Considerations for Lexington Residents

Every city has its own financial landscape. Here are a few local factors worth discussing with a Lexington financial advisor.

University of Kentucky and UK HealthCare

The University of Kentucky, including UK HealthCare, is by far Lexington’s largest employer, with 24,849 employees in Fayette County in the city’s 2022 count. Faculty, clinicians and staff often have more than one workplace retirement plan to coordinate, and the IRS allows up to $24,500 in 403(b) deferrals for 2026, plus an $8,000 catch-up at 50 or older. For 2027, the IRS raised those amounts to $25,500 and $8,500. Physicians, nurses and residents should also weigh student loan repayment strategies and own-occupation disability insurance early in their careers.

Toyota Georgetown and Bluegrass manufacturing

Just north of Lexington, Toyota Motor Manufacturing Kentucky in Georgetown is Toyota’s largest vehicle manufacturing plant in the world, with 10,000 full-time employees building the Camry Hybrid and RAV4 Hybrid plus engines. Lexington itself is home to employers such as Lockheed Martin and Amazon. Manufacturing and engineering workers benefit from budgeting around overtime, capturing the full employer match and planning ahead for early retirement offers. See our Q&As for Lockheed Martin employees and Amazon employees.

Kentucky’s pension income exclusion

Kentucky lets retirees exclude up to $31,110 of pension and retirement plan distributions from state income tax, a limit in place since 2018. Retirement income above that is taxed at Kentucky’s flat 3.5% rate for 2026. Retirees with sizable IRA, 401(k) or pension income may want to plan withdrawals and Roth conversions with the exclusion in mind. The Kentucky Department of Revenue notes that some retirees may be able to exclude more, so check how your own pension is treated.

The Benefits of Hiring a Financial Advisor in Lexington

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Lexington, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Who are the largest employers in the Lexington area?

Lexington’s biggest employers are led by the University of Kentucky, along with Amazon, public schools and health systems, based on employee counts for Fayette County. Highlighted companies link to advisor Q&As about their employees.

  1. University of Kentucky 24,849 employees
  2. AmazonRead advisor Q&A →5,727 employees
  3. Fayette County Public Schools 5,057 employees
  4. Baptist Health Lexington 3,108 employees
  5. Lexington-Fayette Urban County Government 2,784 employees
  6. CHI Saint Joseph Health 2,754 employees
  7. Conduent 2,500 employees
  8. Lexington VA Medical Center 2,000 employees
  9. Lockheed MartinRead advisor Q&A →1,500 employees
  10. Lexmark International (now part of Xerox) 1,433 employees

Work for one of these companies or another large employer? Explore our employer Q&As for advice on making the most of your benefits.

Source: Lexington-Fayette Urban County Government, Annual Comprehensive Financial Report, Principal Employers (2022 data from Commerce Lexington). Counts cover Fayette County and date from 2022. Toyota’s Georgetown plant is in neighboring Scott County and isn’t included.

Do you work for one of the largest employers in Lexington? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Types of Financial Advisors You’ll Find on Wealthtender

Thousands of people visit Wealthtender each month to find and compare financial advisors based on their location, education, experience, areas of specialization and online reviews. Wealthtender’s Certified Advisor Reviews™ help consumers make informed hiring decisions with important details about the relationship between reviewers and advisors always displayed to ensure you gain the transparency you deserve when your life savings could be at stake.

On Wealthtender, you can explore a diverse range of financial advisors and wealth management firms that include:

  • Fiduciary advisors committed to acting in clients’ best interests
  • CFP® professionals with advanced financial planning credentials
  • Fee-only advisors compensated solely by clients
  • Advisors for growing families, people nearing retirement, and business owners
  • Specialists across multiple categories (e.g., life stage, occupation, ethnicity, lifestyle, religion)
  • Highly-rated advisors with positive client reviews
  • Firms of varying sizes with advisors who can meet with you in person or online
  • Fee-based advisors who offer access to insurance and alternative investments

How to use this directory: Compare financial advisors in the Lexington area based on what matters most to you. Use the directory to:

  • View advisor profiles to evaluate credentials, services, and areas of specialization
  • Read Certified Advisor Reviews™ to learn what clients value most
  • Identify advisors recognized with Wealthtender Voice of the Client Awards™
  • Contact advisors and schedule free introductory video calls

Wealthtender Voice of the Client Awards™: Top Rated Lexington Financial Advisors

Wealthtender Voice of the Client Awards™ recognize financial advisors and firms that consistently earn exceptional client feedback. Below are Lexington-area advisors and firms that have met the criteria for Highly Rated recognition.

Firm/Advisor Firm City State Voice of the Client Award Website

To qualify for a Highly Rated award, advisors and firms must achieve an average client review rating of 4.75 or higher (on a scale of 1 to 5) based on a minimum number of eligible client reviews published on Wealthtender within a defined timeframe for each particular award (Timeframe for 2025 Award: 1/1/24 – 12/31/25; Timeframe for Subsequent Year Awards: July 1 of the preceding year through December 31 of the Award Year (e.g., Timeframe for 2026 Award 7/1/25 – 12/31/26). Eligible reviews are limited to clients (as of the review submission date) that advisors/firms must self-attest have no material conflicts of interest and received no compensation in exchange for their reviews. ↗️ View full award methodology & FAQs

Although financial advisors and wealth management firms compensate Wealthtender for marketing services (including eligibility to be considered for awards), Wealthtender’s award criteria is objective and not influenced by compensation. Wealthtender Voice of the Client Awards are not a guarantee of future performance or success and client reviews may not be representative of the experience of all past or future clients.

Quick Tips For Hiring a Lexington Financial Advisor

Before hiring a financial advisor in Lexington, here are a few quick tips to help you find the best advisor for you.

1

Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor who specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2

Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3

Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4

Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.

Frequently Asked Questions

What makes a financial advisor “trusted”?
A trusted financial advisor typically earns positive client feedback over time, operates transparently, and clearly explains how they’re compensated. On Wealthtender, trust is reflected through Certified Advisor Reviews™ that combine insights into the client experience and character of advisors with important disclosures about each reviewer to ensure you gain the transparency you deserve when your life savings could be at stake.

Financial advisors and wealth management firms that consistently receive superior client reviews can also qualify for Wealthtender’s Voice of the Client Awards™ designed to recognize America’s most trusted advisors. Learn More About Wealthtender Voice of the Client Awards™
What are Certified Advisor Reviews™?
Certified Advisor Reviews™ from Wealthtender help consumers make smarter hiring decisions when choosing a financial advisor.

Clients and other individuals can submit reviews for financial advisors and wealth management firms that have turned on the reviews feature. Before each review is publicly displayed, financial advisors agree to disclose important information about their relationship with the reviewer to ensure consumers gain the transparency they deserve when their life savings could be at stake. These disclosures also help financial advisors satisfy compliance with industry regulations.

After financial advisors provide the required disclosures, Wealthtender publishes the review with the Certified Advisor Review™ mark. Learn More About Certified Advisor Reviews™
Can I find fiduciary financial advisors on Wealthtender?
Yes, you’ll find hundreds of fiduciary financial advisors on Wealthtender. Fiduciary financial advisors must act in their clients’ best interest. Before hiring an advisor, always ask if they will act in your best interest as a fiduciary.

For example, financial advisors who have earned their Certified Financial Planner (CFP) designation are fiduciaries. To hold themselves out as a CFP, these credential holders must acknowledge they will adhere to the CFP Board’s Code of Ethics and Standards of Conduct and act as a fiduciary when providing financial advice to their clients. Learn More About Fiduciary Financial Advisors
Can I find fee-only financial advisors on Wealthtender?
Yes, you’ll find hundreds of fee-only financial advisors on Wealthtender. Fee-only financial advisors are paid directly by their clients. Since they aren’t compensated based on the products and services they recommend (e.g., commissions), their compensation model helps reduce potential conflicts of interest.

When viewing financial advisor profiles on Wealthtender, look for the Compensation Methods section that shows ways each financial advisor can be paid for their services, including if they offer fee-only financial planning services. Learn More About Fee-Only Financial Advisors
What distinguishes Wealthtender Voice of the Client Awards™ from other advisor recognition programs?
Wealthtender’s Voice of the Client Awards™ recognize financial advisors and wealth management firms that consistently receive superior client reviews. Unlike award programs with ranking factors that favor financial institutions with the most assets and the fastest revenue growth, the Wealthtender Voice of the Client Awards provide both local financial advisors who choose to remain small and large wealth management firms with the opportunity to be recognized on a metric that matters more to consumers – actual client feedback reflecting the quality of their experience. Learn More About Voice of the Client Awards™
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit. But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a Lexington financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Learn how to get featured

Please note: Wealthtender may be compensated by financial advisors featured on our site and within this guide. Learn more about how we operate with integrity to earn your trust.

Watch

How Much Does a Financial Advisor Cost?

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

What this article covers

Find financial advisors in Vancouver, Washington ready to help with your financial planning needs so you can enjoy life more with less money stress.

Financial Advisor Directory for Vancouver, Washington

📍 Map: Financial Advisors with their Primary Office Location in Vancouver

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Vancouver.

📍Double-click or pinch pins to view more.

Showing

📍 Additional Advisors Who Serve Clients in Vancouver

In addition to the advisors featured above, these advisors can also meet with you in person in Vancouver.

Key Takeaways

1

You can compare Vancouver financial advisors by credentials, specialty and verified client reviews before you contact anyone.

The map shows advisors whose primary office is in Vancouver, and the section below it lists advisors who also serve Vancouver clients in person or virtually. Profiles include Certified Advisor Reviews™, designations such as the CFP® and the services each advisor offers.

2

Living in Washington while working or shopping in Oregon shapes the planning help many Vancouver residents need.

Vancouver residents who work in Oregon owe Oregon income tax on wages for work done there, and purchases carried home from Oregon can still owe Washington use tax. Locally, health systems such as PeaceHealth and tech employers such as HP and TSMC Washington bring retirement plan and stock compensation decisions.

3

Interview more than one advisor and confirm how each one is paid.

Ask about services, fees and whether the advisor acts as a fiduciary, then check their background for free on the SEC’s Investment Adviser Public Disclosure website before you hire.

Financial Planning Considerations for Vancouver Residents

Every city has its own financial landscape. Here are a few local factors worth discussing with a Vancouver financial advisor.

Working in Oregon, living in Washington

Washington has no income tax, but Oregon taxes nonresidents on Oregon-source income, filed on Form OR-40-N. Oregon taxes only wages for work performed in Oregon, so days you work from home in Washington generally aren’t taxed by Oregon; keep records if your employer reports all your pay as Oregon wages. Many Vancouver residents work for Portland-area employers such as Intel and Nike. Shopping across the river has a catch too: Washington’s Department of Revenue says goods bought tax-free in Oregon for use in Washington owe Washington use tax.

Health care and tech employers

PeaceHealth, with an estimated 4,908 employees, and Vancouver Clinic, with 2,582, are Clark County’s largest private employers on Greater Portland Inc’s 2026 list. Health care employees often juggle a 403(b), possibly a 457(b), and decisions about disability coverage; for 2026 the 401(k), 403(b) and most 457 plan deferral limit is $24,500, and the IRS raised it to $25,500 for 2027. Tech employers including HP, TSMC Washington and nLIGHT may add RSUs or an ESPP, which raises questions about taxes and how much to hold in one stock. See our HP Q&A.

The Benefits of Hiring a Financial Advisor in Vancouver

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Vancouver, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Who are the largest employers in the Vancouver area?

These are the largest Clark County employers in Greater Portland Inc’s regional major employers list, which covers private employers, health systems and colleges. Highlighted companies link to advisor Q&As about their employees.

  1. PeaceHealth 4,908 employees
  2. Vancouver Clinic 2,582 employees
  3. Fisher Investments (Camas) 1,950 employees
  4. Clark College 1,478 employees
  5. ilani (Ridgefield) 1,357 employees
  6. HPRead advisor Q&A →1,000 employees
  7. TSMC Washington (Camas) 1,000 employees
  8. SEH America 950 employees
  9. Banfield Pet Hospital 800 employees
  10. nLIGHT (Camas) 650 employees
  11. ZoomInfo 557 employees
  12. Columbia Machine 533 employees

Work for one of these companies or another large employer? Explore our employer Q&As for advice on making the most of your benefits.

Source: Greater Portland Inc, Major Employers (March 2026). Counts are Greater Portland Inc estimates compiled from varied sources and dates and may include employees outside the region. The list excludes school districts, governments and most retailers, so large public employers such as Vancouver Public Schools are not shown.

Do you work for one of the largest employers in Vancouver? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Types of Financial Advisors You’ll Find on Wealthtender

Thousands of people visit Wealthtender each month to find and compare financial advisors based on their location, education, experience, areas of specialization and online reviews. Wealthtender’s Certified Advisor Reviews™ help consumers make informed hiring decisions with important details about the relationship between reviewers and advisors always displayed to ensure you gain the transparency you deserve when your life savings could be at stake.

On Wealthtender, you can explore a diverse range of financial advisors and wealth management firms that include:

  • Fiduciary advisors committed to acting in clients’ best interests
  • CFP® professionals with advanced financial planning credentials
  • Fee-only advisors compensated solely by clients
  • Advisors for growing families, people nearing retirement, and business owners
  • Specialists across multiple categories (e.g., life stage, occupation, ethnicity, lifestyle, religion)
  • Highly-rated advisors with positive client reviews
  • Firms of varying sizes with advisors who can meet with you in person or online
  • Fee-based advisors who offer access to insurance and alternative investments

How to use this directory: Compare financial advisors in the Vancouver area based on what matters most to you. Use the directory to:

  • View advisor profiles to evaluate credentials, services, and areas of specialization
  • Read Certified Advisor Reviews™ to learn what clients value most
  • Identify advisors recognized with Wealthtender Voice of the Client Awards™
  • Contact advisors and schedule free introductory video calls

Wealthtender Voice of the Client Awards™: Top Rated Vancouver Financial Advisors

Wealthtender Voice of the Client Awards™ recognize financial advisors and firms that consistently earn exceptional client feedback. Below are Vancouver-area advisors and firms that have met the criteria for Highly Rated recognition.

Firm/Advisor Firm City State Voice of the Client Award Website

To qualify for a Highly Rated award, advisors and firms must achieve an average client review rating of 4.75 or higher (on a scale of 1 to 5) based on a minimum number of eligible client reviews published on Wealthtender within a defined timeframe for each particular award (Timeframe for 2025 Award: 1/1/24 – 12/31/25; Timeframe for Subsequent Year Awards: July 1 of the preceding year through December 31 of the Award Year (e.g., Timeframe for 2026 Award 7/1/25 – 12/31/26). Eligible reviews are limited to clients (as of the review submission date) that advisors/firms must self-attest have no material conflicts of interest and received no compensation in exchange for their reviews. ↗️ View full award methodology & FAQs

Although financial advisors and wealth management firms compensate Wealthtender for marketing services (including eligibility to be considered for awards), Wealthtender’s award criteria is objective and not influenced by compensation. Wealthtender Voice of the Client Awards are not a guarantee of future performance or success and client reviews may not be representative of the experience of all past or future clients.

Quick Tips For Hiring a Vancouver Financial Advisor

Before hiring a financial advisor in Vancouver, here are a few quick tips to help you find the best advisor for you.

1

Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor who specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2

Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3

Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4

Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.

Frequently Asked Questions

What makes a financial advisor “trusted”?
A trusted financial advisor typically earns positive client feedback over time, operates transparently, and clearly explains how they’re compensated. On Wealthtender, trust is reflected through Certified Advisor Reviews™ that combine insights into the client experience and character of advisors with important disclosures about each reviewer to ensure you gain the transparency you deserve when your life savings could be at stake.

Financial advisors and wealth management firms that consistently receive superior client reviews can also qualify for Wealthtender’s Voice of the Client Awards™ designed to recognize America’s most trusted advisors. Learn More About Wealthtender Voice of the Client Awards™
What are Certified Advisor Reviews™?
Certified Advisor Reviews™ from Wealthtender help consumers make smarter hiring decisions when choosing a financial advisor.

Clients and other individuals can submit reviews for financial advisors and wealth management firms that have turned on the reviews feature. Before each review is publicly displayed, financial advisors agree to disclose important information about their relationship with the reviewer to ensure consumers gain the transparency they deserve when their life savings could be at stake. These disclosures also help financial advisors satisfy compliance with industry regulations.

After financial advisors provide the required disclosures, Wealthtender publishes the review with the Certified Advisor Review™ mark. Learn More About Certified Advisor Reviews™
Can I find fiduciary financial advisors on Wealthtender?
Yes, you’ll find hundreds of fiduciary financial advisors on Wealthtender. Fiduciary financial advisors must act in their clients’ best interest. Before hiring an advisor, always ask if they will act in your best interest as a fiduciary.

For example, financial advisors who have earned their Certified Financial Planner (CFP) designation are fiduciaries. To hold themselves out as a CFP, these credential holders must acknowledge they will adhere to the CFP Board’s Code of Ethics and Standards of Conduct and act as a fiduciary when providing financial advice to their clients. Learn More About Fiduciary Financial Advisors
Can I find fee-only financial advisors on Wealthtender?
Yes, you’ll find hundreds of fee-only financial advisors on Wealthtender. Fee-only financial advisors are paid directly by their clients. Since they aren’t compensated based on the products and services they recommend (e.g., commissions), their compensation model helps reduce potential conflicts of interest.

When viewing financial advisor profiles on Wealthtender, look for the Compensation Methods section that shows ways each financial advisor can be paid for their services, including if they offer fee-only financial planning services. Learn More About Fee-Only Financial Advisors
What distinguishes Wealthtender Voice of the Client Awards™ from other advisor recognition programs?
Wealthtender’s Voice of the Client Awards™ recognize financial advisors and wealth management firms that consistently receive superior client reviews. Unlike award programs with ranking factors that favor financial institutions with the most assets and the fastest revenue growth, the Wealthtender Voice of the Client Awards provide both local financial advisors who choose to remain small and large wealth management firms with the opportunity to be recognized on a metric that matters more to consumers – actual client feedback reflecting the quality of their experience. Learn More About Voice of the Client Awards™
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit. But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a Vancouver financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Learn how to get featured

Please note: Wealthtender may be compensated by financial advisors featured on our site and within this guide. Learn more about how we operate with integrity to earn your trust.

Watch

How Much Does a Financial Advisor Cost?

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.

What this article covers

Find financial advisors in Creve Coeur, Missouri ready to help with your financial planning needs so you can enjoy life more with less money stress.

Financial Advisor Directory for Creve Coeur, Missouri

📍 Map: Financial Advisors with their Primary Office Location in Creve Coeur

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Creve Coeur.

📍Double-click or pinch pins to view more.

Showing

Key Takeaways

1

You can compare Creve Coeur financial advisors by credentials, specialty and verified client reviews before you contact anyone.

The map shows advisors whose primary office is in Creve Coeur. Profiles include Certified Advisor Reviews™, designations such as the CFP® and the services each advisor offers.

2

Creve Coeur’s Bayer campus, ag-science research and hospitals shape the planning help many residents need.

Employees of Bayer and the area’s plant-science organizations often need help with corporate benefits and job changes, and Missouri now lets individuals subtract 100% of capital gains from state income. Mercy Hospital St. Louis and Barnes-Jewish West County bring health care professionals with their own retirement and insurance questions.

3

Interview more than one advisor and confirm how each one is paid.

Ask about services, fees and whether the advisor acts as a fiduciary, then check their background for free on the SEC’s Investment Adviser Public Disclosure website before you hire.

Financial Planning Considerations for Creve Coeur Residents

Every city has its own financial landscape. Here are a few local factors worth discussing with a Creve Coeur financial advisor.

Bayer and the ag-science corridor

Creve Coeur was Monsanto’s home until Bayer acquired it in 2018, and Bayer’s crop science operations remain in the area along with the Donald Danforth Plant Science Center and the 39 North AgTech Innovation District. In 2024, Bayer announced more than $100 million in investments at its Creve Coeur and Chesterfield campuses while exploring the sale of part of the Creve Coeur campus. Employees going through reorganizations often need help with severance, 401(k) rollovers and health coverage.

Missouri’s capital gains subtraction

A 2025 Missouri law lets individuals subtract 100% of the capital gains reported on their federal return from Missouri income, according to the Missouri Department of Revenue. Capital losses don’t qualify, and trusts and estates can’t claim it. For residents with company stock, a concentrated portfolio or appreciated real estate, this changes the after-tax math on selling, though federal capital gains tax still applies.

Hospital and medical careers

Mercy Hospital St. Louis and Barnes-Jewish West County Hospital are both in Creve Coeur, and Mercy employs 15,342 people in the St. Louis County area. Doctors, nurses and other clinicians often balance student loans, disability insurance and more than one retirement plan. For 2026, 403(b) plans allow up to $24,500 in employee contributions, plus higher catch-up amounts at 50 and older and a larger catch-up for ages 60 to 63. For 2027, the IRS raised the limit to $25,500.

The Benefits of Hiring a Financial Advisor in Creve Coeur

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Creve Coeur, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Who are the largest employers in the Creve Coeur area?

These are the ten largest employers in the St. Louis County area, as reported in the St. Louis County Library District’s 2024 financial report. Highlighted companies link to advisor Q&As about their employees.

  1. Washington University in St. Louis 21,278 employees
  2. Boeing Defense, Space & SecurityRead advisor Q&A →16,681 employees
  3. SSM Health 15,631 employees
  4. Mercy 15,342 employees
  5. Schnuck Markets 8,496 employees
  6. Archdiocese of St. Louis 7,000 employees
  7. Charter Communications 6,230 employees
  8. Special School District of St. Louis County 5,903 employees
  9. Edward Jones 5,446 employees
  10. Enterprise Mobility 5,000 employees

Work for one of these companies or another large employer? Explore our employer Q&As for advice on making the most of your benefits.

Source: St. Louis County Library District, 2024 Annual Comprehensive Financial Report (Principal Employers, citing the St. Louis Business Journal) (2025). Counts are for the St. Louis County area, not Creve Coeur alone, and come from the St. Louis Business Journal as cited in the library district’s report. BJC HealthCare does not appear in this table.

Do you work for one of the largest employers in Creve Coeur? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Types of Financial Advisors You’ll Find on Wealthtender

Thousands of people visit Wealthtender each month to find and compare financial advisors based on their location, education, experience, areas of specialization and online reviews. Wealthtender’s Certified Advisor Reviews™ help consumers make informed hiring decisions with important details about the relationship between reviewers and advisors always displayed to ensure you gain the transparency you deserve when your life savings could be at stake.

On Wealthtender, you can explore a diverse range of financial advisors and wealth management firms that include:

  • Fiduciary advisors committed to acting in clients’ best interests
  • CFP® professionals with advanced financial planning credentials
  • Fee-only advisors compensated solely by clients
  • Advisors for growing families, people nearing retirement, and business owners
  • Specialists across multiple categories (e.g., life stage, occupation, ethnicity, lifestyle, religion)
  • Highly-rated advisors with positive client reviews
  • Firms of varying sizes with advisors who can meet with you in person or online
  • Fee-based advisors who offer access to insurance and alternative investments

How to use this directory: Compare financial advisors in the Creve Coeur area based on what matters most to you. Use the directory to:

  • View advisor profiles to evaluate credentials, services, and areas of specialization
  • Read Certified Advisor Reviews™ to learn what clients value most
  • Identify advisors recognized with Wealthtender Voice of the Client Awards™
  • Contact advisors and schedule free introductory video calls

Wealthtender Voice of the Client Awards™: Top Rated Creve Coeur Financial Advisors

Wealthtender Voice of the Client Awards™ recognize financial advisors and firms that consistently earn exceptional client feedback. Below are Creve Coeur-area advisors and firms that have met the criteria for Highly Rated recognition.

Firm/Advisor Firm City State Voice of the Client Award Website

To qualify for a Highly Rated award, advisors and firms must achieve an average client review rating of 4.75 or higher (on a scale of 1 to 5) based on a minimum number of eligible client reviews published on Wealthtender within a defined timeframe for each particular award (Timeframe for 2025 Award: 1/1/24 – 12/31/25; Timeframe for Subsequent Year Awards: July 1 of the preceding year through December 31 of the Award Year (e.g., Timeframe for 2026 Award 7/1/25 – 12/31/26). Eligible reviews are limited to clients (as of the review submission date) that advisors/firms must self-attest have no material conflicts of interest and received no compensation in exchange for their reviews. ↗️ View full award methodology & FAQs

Although financial advisors and wealth management firms compensate Wealthtender for marketing services (including eligibility to be considered for awards), Wealthtender’s award criteria is objective and not influenced by compensation. Wealthtender Voice of the Client Awards are not a guarantee of future performance or success and client reviews may not be representative of the experience of all past or future clients.

Quick Tips For Hiring a Creve Coeur Financial Advisor

Before hiring a financial advisor in Creve Coeur, here are a few quick tips to help you find the best advisor for you.

1

Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor who specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2

Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3

Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4

Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.

Frequently Asked Questions

What makes a financial advisor “trusted”?
A trusted financial advisor typically earns positive client feedback over time, operates transparently, and clearly explains how they’re compensated. On Wealthtender, trust is reflected through Certified Advisor Reviews™ that combine insights into the client experience and character of advisors with important disclosures about each reviewer to ensure you gain the transparency you deserve when your life savings could be at stake.

Financial advisors and wealth management firms that consistently receive superior client reviews can also qualify for Wealthtender’s Voice of the Client Awards™ designed to recognize America’s most trusted advisors. Learn More About Wealthtender Voice of the Client Awards™
What are Certified Advisor Reviews™?
Certified Advisor Reviews™ from Wealthtender help consumers make smarter hiring decisions when choosing a financial advisor.

Clients and other individuals can submit reviews for financial advisors and wealth management firms that have turned on the reviews feature. Before each review is publicly displayed, financial advisors agree to disclose important information about their relationship with the reviewer to ensure consumers gain the transparency they deserve when their life savings could be at stake. These disclosures also help financial advisors satisfy compliance with industry regulations.

After financial advisors provide the required disclosures, Wealthtender publishes the review with the Certified Advisor Review™ mark. Learn More About Certified Advisor Reviews™
Can I find fiduciary financial advisors on Wealthtender?
Yes, you’ll find hundreds of fiduciary financial advisors on Wealthtender. Fiduciary financial advisors must act in their clients’ best interest. Before hiring an advisor, always ask if they will act in your best interest as a fiduciary.

For example, financial advisors who have earned their Certified Financial Planner (CFP) designation are fiduciaries. To hold themselves out as a CFP, these credential holders must acknowledge they will adhere to the CFP Board’s Code of Ethics and Standards of Conduct and act as a fiduciary when providing financial advice to their clients. Learn More About Fiduciary Financial Advisors
Can I find fee-only financial advisors on Wealthtender?
Yes, you’ll find hundreds of fee-only financial advisors on Wealthtender. Fee-only financial advisors are paid directly by their clients. Since they aren’t compensated based on the products and services they recommend (e.g., commissions), their compensation model helps reduce potential conflicts of interest.

When viewing financial advisor profiles on Wealthtender, look for the Compensation Methods section that shows ways each financial advisor can be paid for their services, including if they offer fee-only financial planning services. Learn More About Fee-Only Financial Advisors
What distinguishes Wealthtender Voice of the Client Awards™ from other advisor recognition programs?
Wealthtender’s Voice of the Client Awards™ recognize financial advisors and wealth management firms that consistently receive superior client reviews. Unlike award programs with ranking factors that favor financial institutions with the most assets and the fastest revenue growth, the Wealthtender Voice of the Client Awards provide both local financial advisors who choose to remain small and large wealth management firms with the opportunity to be recognized on a metric that matters more to consumers – actual client feedback reflecting the quality of their experience. Learn More About Voice of the Client Awards™
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit. But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a Creve Coeur financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Learn how to get featured

Please note: Wealthtender may be compensated by financial advisors featured on our site and within this guide. Learn more about how we operate with integrity to earn your trust.

Watch

How Much Does a Financial Advisor Cost?

Brian Thorp

About the author

Brian Thorp

Founder & CEO and Editor-in-Chief, Wealthtender

Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.

Brian and his wife live in Austin, Texas.