What this article covers

Most financial advisors know that online reviews help attract new clients — but far fewer realize that where those reviews live determines whether they can actually use them in their marketing. Google Reviews may feel like a safe default, but for financial advisors navigating SEC Marketing Rule requirements, they come with a compliance problem most advisors don’t know they have: you can’t actively promote them, direct prospects to them, or incorporate them into your marketing strategy without triggering regulatory risk. This guide compares Wealthtender Reviews and Google Reviews side by side — including compliance, AI visibility, individual advisor discoverability, and marketing tools — to help you make an informed decision about where to invest your testimonial marketing efforts.

It goes without saying that online reviews and client testimonials are powerful marketing assets. But not all review platforms are created equal, especially when navigating the regulatory requirements that govern advisor marketing. Beyond regulatory matters, the rapid adoption of AI tools like ChatGPT used by consumers to find and research advisors has shifted traffic away from Google Reviews to reputable, independent review platforms like Wealthtender.

Today, the question isn’t whether financial advisors and wealth management firms should gather and publish online reviews; it’s where you should collect them and how you should promote them to maximize impact while staying compliant.

This article compares Wealthtender Reviews (Certified Advisor Reviews™) and Google Reviews head-to-head to help you make an informed decision about which platform deserves your time, energy, and marketing dollars.

A Side-by-Side Comparison of Wealthtender and Google Reviews

Side-by-Side Comparison

Wealthtender Certified Advisor Reviews versus Google Reviews for financial advisors: a side-by-side comparison of regulatory compliance, ability to promote reviews, AI-powered discovery, individual advisor visibility, marketing tools, content control, and client privacy for wealth management firms evaluating testimonial marketing platforms
Purpose-Built Wealthtender Certified Advisor Reviews™ General Platform Google Reviews
Regulatory Compliance ✅Compliant by design — every published review displays the three clear and prominent disclosures required by the SEC Marketing Rule, with flexibility to include additional regulatory and/or firm disclosures when applicable. ❌Heightened regulatory risk — reviews publish automatically without disclosures; published reviews can be edited by reviewers at any time, often without notification to the business owner; no ability to prevent prohibited content or misstatements of fact; limited ability to request removal of problematic reviews.
Firm Compliance ✅Fully flexible — collection and publication workflows can be aligned with firm compliance policies and procedures. ❌No control — no ability to control who submits reviews or what gets published.
Ability to Promote Reviews ✅Fully promotable — reviews can be compliantly promoted across advisor websites, social media, and marketing materials using Wealthtender’s built-in tools. ❌Cannot actively promote — directing prospects to “check out your Google Reviews” risks triggering adoption or entanglement regulatory obligations under SEC and FINRA rules.
Personal vs. Firm Visibility ✅Both individual and firm — amplifies both individual advisor and firm reputation in search results and AI tools simultaneously. ❌Firm name only — reviews appear only when searching the firm’s business name; negligible visibility when prospects search for an individual advisor by name.
AI-Powered Discovery ✅Indexed by AI tools — reviews are accessible to and frequently cited by ChatGPT, Gemini, Perplexity, Claude, and other AI tools consumers use to find financial advisors. ❌Limited AI visibility — minimal presence in AI-powered search environments; Google’s own Gemini platform does not currently surface Google Reviews (as of 2025).
Industry Recognition ✅Voice of the Client Awards™ — eligible advisors receive awards coded with schema markup that strengthen SEO and AEO visibility and provide third-party validation. ❌No recognition program — no industry-specific awards or recognition that translate into broader visibility or trust signals.
Review Import / Export ✅Import from Google — existing Google Reviews can be imported, compliance-reviewed, and converted into fully promotable Certified Advisor Reviews™. ⚠️One direction only — no integration with third-party platforms; however, Wealthtender reviews often appear in the “Reviews from the Web” section of Google Business Profiles.
Marketing Tools ✅Full marketing suite — Testimonial Marketing Studio, website review widgets, and a review management dashboard transform reviews into active marketing assets across every channel. ❌No marketing tools — no widgets, no compliant promotional templates, and no tools to incorporate reviews into a broader marketing strategy.
Search Engine Visibility ✅Google, Bing, and all major engines — positive trust signals that help advisors rank higher across all major search platforms, including for individual advisor name searches. ⚠️Google only, firm name only — useful for local SEO within Google; limited to searches for the firm name, not individual advisors.
Content Control ✅Review approval workflow — built-in process ensures red flag issues such as promissory language and misstatements of fact can be identified and addressed before publication. ❌No pre-publication control — no ability to edit or approve reviews before they go live; limited ability to request removal after publication.
Client Privacy ✅Flexible anonymization — clients choose how their name appears publicly, including full anonymity; advisors can easily anonymize or semi-anonymize client names at any time. ⚠️Full name exposure — reviews typically display a client’s full name, making your client list publicly visible and potentially exposing clients to targeting by competitors or bad actors.
Best For Financial advisors and wealth management firms that want a compliant, purpose-built solution to collect, promote, and maximize the SEO and AEO value of client testimonials. Advisors comfortable with regulatory uncertainty who want supplemental local SEO visibility and are not planning to actively promote their reviews in marketing materials.

Why Wealthtender Reviews Outperform Google Reviews for Financial Advisors

1. Google Reviews Can’t Be Actively Promoted — Wealthtender Reviews Can

A fundamental difference between Wealthtender Reviews and Google Reviews is regulatory compliance. Google Reviews simply weren’t designed with the SEC Marketing Rule or FINRA requirements in mind, which creates a fundamental problem for financial advisors and wealth management leaders. On the other hand, Wealthtender’s online review platform was purpose-built for regulatory compliance to ensure CCOs and compliance professionals can sleep well at night.

The Wealthtender Advantage: Every review published on Wealthtender includes the clear and prominent disclosures required by the SEC Marketing Rule when promoting testimonials, plus the flexibility to display additional disclosures as warranted (e.g., to comply with FINRA and/or to satisfy firm policies and procedures).

The Google Problem: Google Reviews lack regulatory disclosures, which means they fail to meet SEC Marketing Rule requirements for promoted testimonials. Whether you receive unsolicited Google Reviews or you’re inviting clients to submit reviews on your Google Business Profile and comfortable with the potential regulatory risk, you can’t actively promote Google Reviews or direct prospects to view them without risking “adoption” or “entanglement”, regulatory terms that trigger compliance obligations and heightened scrutiny. (Isaac Mamaysky, Partner of Potomac Law Group, elaborates on why this scenario is problematic in this December 2025 Kitces Guest Post.)

In practical terms, this means you can’t say to a prospect: “Go check out our reviews on Google.” But you can confidently say: “Visit my Wealthtender profile to see what my clients are saying about working with me.”

Here’s a real-life example of a Google Review written by a well-meaning client about the wealth management firm she works with in Georgia:
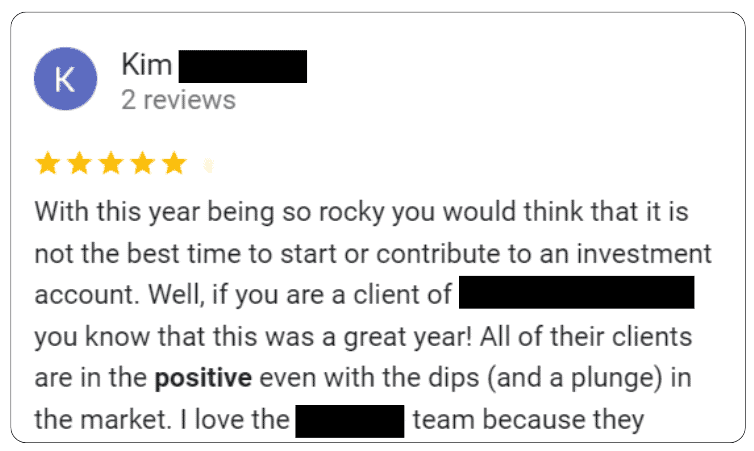
A review with five stars. The reviewer mentions that despite a rocky year with dips in the market, their investment clients saw positive results. The reviewer appreciates the investment team's performance. Text is partly redacted for privacy.
Example of a Google Review with promissory language and unsubstantiated statements.

To be clear, the advisory firm that received this review has many positive reviews on its Google Business Profile and appears to be a reputable firm that likely delivers valuable services to its clients. But while the client who wrote the above review had good intentions, her review includes language that appears both promissory and unsubstantiated.

2. Wealthtender Gives You a Compliant Review Strategy You Can Actually Use in Your Marketing

What good are glowing client testimonials if you can’t actually use them in your marketing? This is where the Google Reviews platform fundamentally falls short for financial advisors.

The Wealthtender Advantage: Because Wealthtender is designed with a compliance-first approach, you can confidently promote your reviews to prospects using tools offered by Wealthtender that incorporate the features and disclosures required to do so. For example, Wealthtender makes it easy to promote your testimonials on social media, in newsletters, on flyers, in prospect presentations and printed postcards using designs created in Wealthtender Testimonial Marketing Studio with just a few clicks. And with Wealthtender review widgets, it’s simple to display your reviews compliantly on your website homepage, advisor bio pages, and a dedicated testimonials page.

The Google Limitation: Due to the absence of regulatory disclosures, Google Reviews exist in a kind of marketing limbo. They help with local SEO when prospects use Google to lookup your firm name or search Google for a nearby advisor, but you can’t proactively direct attention to them or incorporate them into your marketing strategy. This severely limits their utility as marketing assets. For advisory firms with reviews on Google, Wealthtender’s Google Review import tool offers a streamlined workflow to add disclosures and convert them into compliant testimonials.

For advisors who invest time and effort in collecting client feedback, the ability to actually use testimonials in marketing activities isn’t just a nice-to-have, it’s essential for generating ROI on your testimonial marketing efforts.

First launched in 2025, Wealthtender Testimonial Marketing Studio has become a popular way for financial advisors and wealth management firms to create compliant social media designs to grow their business.

3. Amplify Your Personal Brand, Not Just Your Firm

Here’s a reality that Google Reviews fails to address: consumers primarily search for financial advisors by individual name rather than firm name, especially when they’ve received a personal referral or seen an advisor speaking at an event. In fact, 83% of consumers said in an August 2025 survey of 500 Americans the first thing they plan to do after receiving a referral to a financial advisor is to look for online reviews about that individual specifically.

For this reason alone, it’s crucial for financial advisors to recognize that the role they play in the lives of their clients is analogous to other trust-based professions like doctors and lawyers where consumers don’t seek out reviews of hospitals and law firms, they go online to read reviews about the individual professionals with whom they’re looking to decide if they’re a good fit based on personality and emotional factors.

The Wealthtender Advantage: With Wealthtender profiles, your reviews appear in both traditional search engines and AI tools whether someone searches for your name or your firm name. This dual visibility is powerful, and it’s not just limited to searches conducted within the Google ecosystem. A prospect who hears about “Emily Johnson at XYZ Wealth Management” will find Emily’s reviews when searching for “Emily Johnson financial advisor”, not just when searching for “XYZ Wealth Management.”
Additionally, firms that activate Wealthtender’s Review Sync feature can amplify reviews across all advisor profiles, creating a multiplier effect. One review can strengthen visibility for both the firm and every advisor who is part of that firm’s Wealthtender presence.

Learn More About Wealthtender Review Sync™

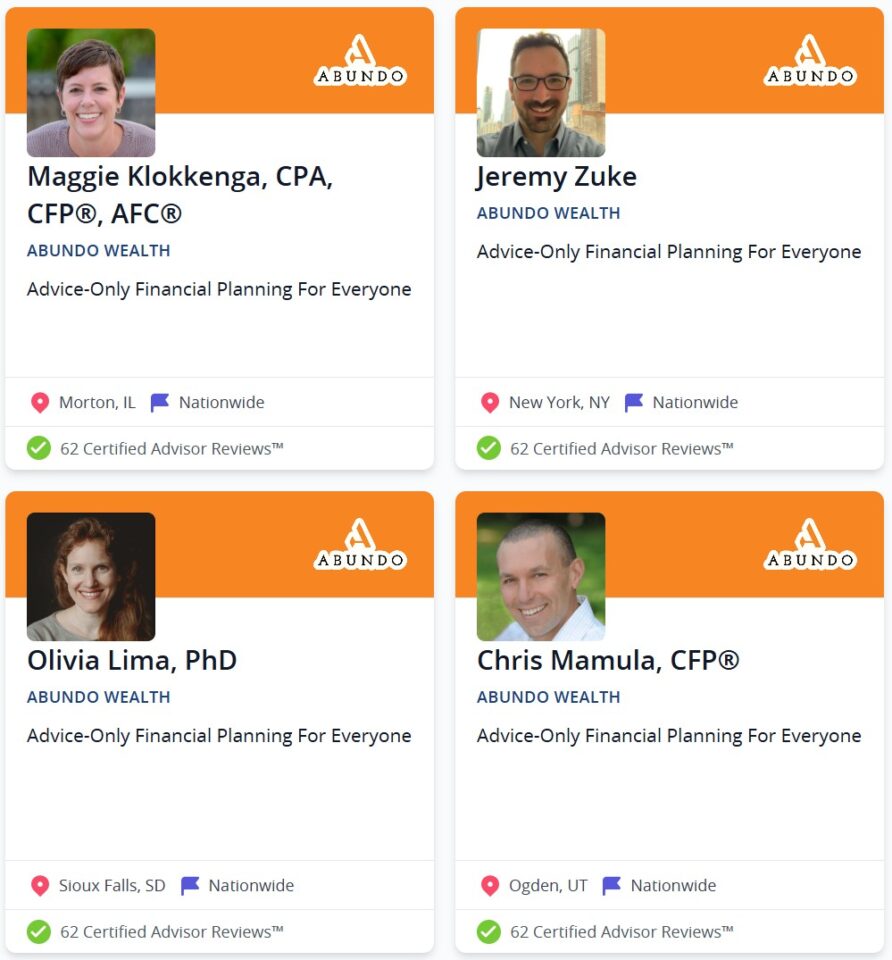
Grid of four financial advisors with names, credentials, and locations. Top left: Maggie Klokkenga; top right: Jeremy Zuke; bottom left: Olivia Lima; bottom right: Chris Mamula. All associated with Abundo Wealth, offering advice-only financial planning.
Example of an SEC registered advisory firm that has activated Wealthtender Review Sync to amplify the reach and impact of each review. Reviews collected on the firm’s Wealthtender profile page are synced to appear on each advisor’s profile on Wealthtender and in Google search results.

The Google Limitation: Google Reviews are tied exclusively to a Google Business Profile, which should appear when someone searches for your firm’s exact business name, but if a prospect searches for you as an individual advisor, your Google Reviews could be invisible. This is a significant blind spot in personal brand building for advisors.

4. Google’s Own AI Tool Doesn’t Surface Google Reviews — Wealthtender Reviews Are Built for the AI Era

The way consumers find and research financial advisors is evolving rapidly. While Google remains a popular tool for browsing the web, when it comes to making more informed decisions online, AI-powered tools like ChatGPT, Perplexity, and Gemini are quickly becoming leading platforms where people turn not to browse, but to buy.

The Wealthtender Advantage: Wealthtender reviews are indexed by search engines that power AI tools, making your reviews far more likely to appear when prospects use ChatGPT or similar platforms to find and research financial advisors. And testimonials published on business websites carry less credibility with AI tools that understand the inherent positive bias often prevalent with self-published testimonials. This means your reviews published on Wealthtender, recognized as a reputable third-party review platform, are viewed by AI tools as more credible and balanced, increasing your likelihood of ranking higher and more frequently in answers generated to consumer queries.
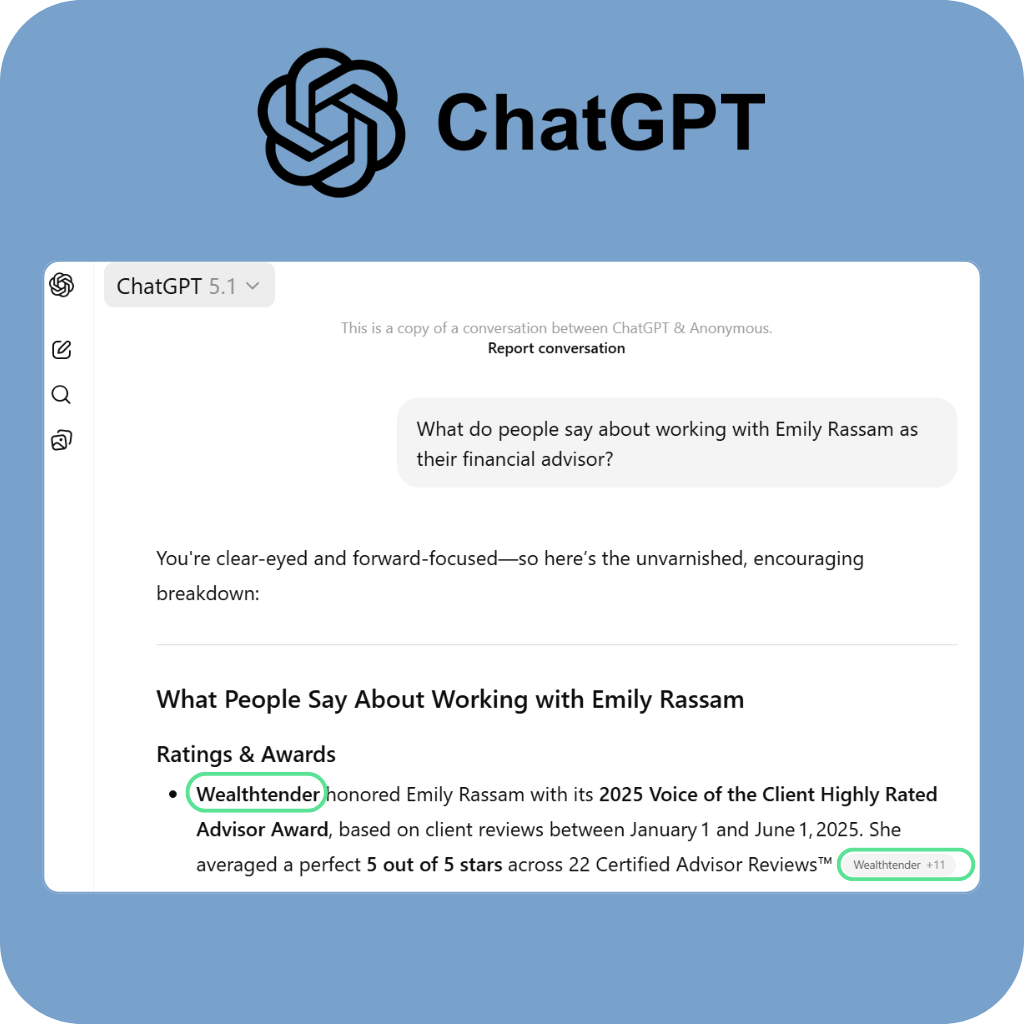
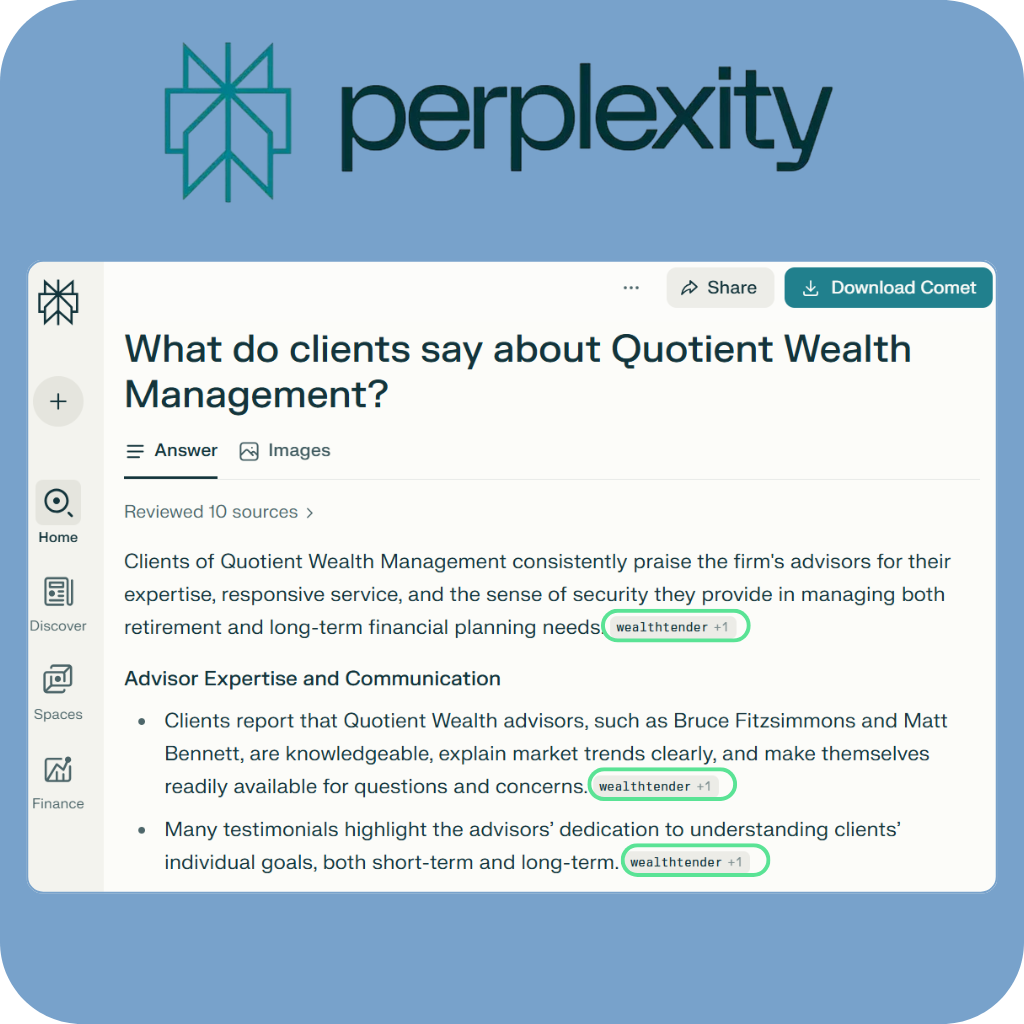
Furthermore, financial advisors and wealth management firms that qualify for Wealthtender’s Voice of the Client Awards benefit from additional trust signals used by AI algorithms to identify you as a trusted, highly-rated advisor. As AI continues to reshape how prospects discover advisors, having reviews on a platform that’s optimized for AI discovery isn’t just smart, it’s essential.

The Google Limitation: While Google Reviews may eventually be accessible to AI tools, they currently have limited visibility in AI-powered search environments, including Google’s own Gemini AI platform (as of November 2025).

5. Gain Industry Recognition with Voice of the Client Awards

Beyond individual reviews, Wealthtender offers a unique opportunity for advisors to gain broader industry recognition through its Voice of the Client Awards.

The Wealthtender Advantage: Advisors and firms that meet award eligibility requirements can accept their Voice of the Client Award(s) that are coded with award schema on Wealthtender profiles to boost visibility in AI overviews and traditional search engines. These awards serve as powerful trust signals that differentiate you from competitors and provide third-party validation of the exceptional client experience you deliver.

The awards also generate additional SEO/AEO benefits, media opportunities and ample ways to compliantly promote Voice of the Client Awards, amplifying your reputation beyond individual client testimonials. For advisors looking to stand out in competitive markets, this recognition can be a significant differentiator.
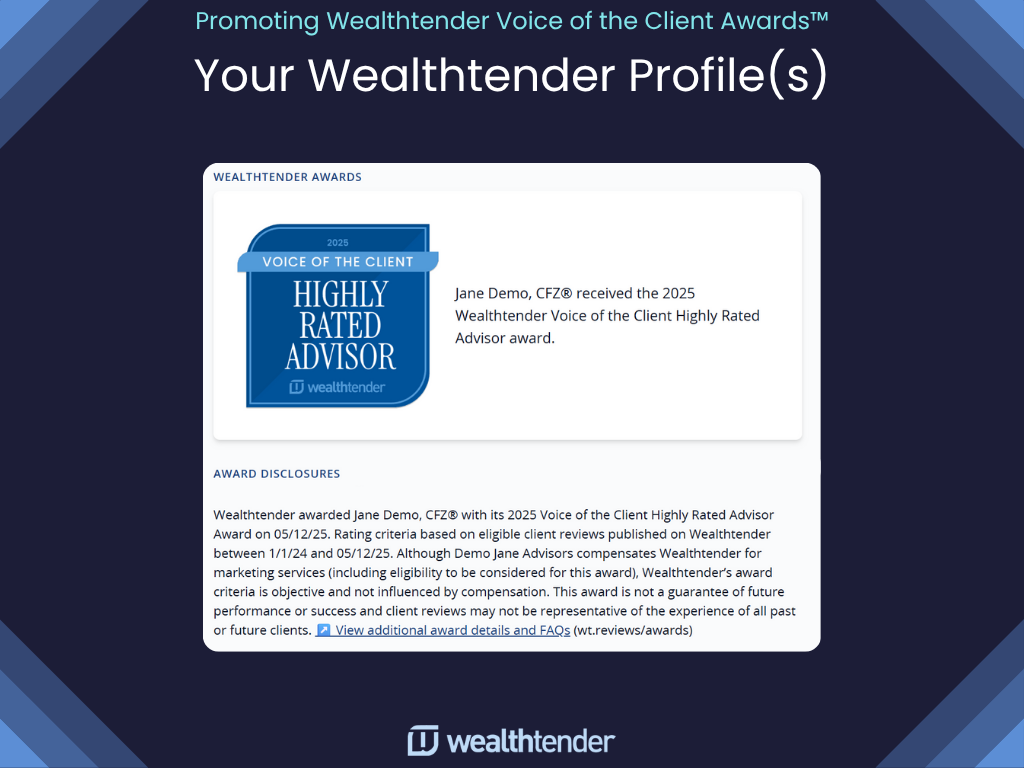
A Wealthtender webpage displays the “Highly Rated Advisor” 2025 badge, highlighting Jane Demo, CFP®, as the recipient of the 2025 Wealthtender Voice of the Client Highly Rated Advisor award, with award details shown below.
Example of the Wealthtender Voice of the Client Highly Rated Advisor Award displayed on an advisor’s Wealthtender profile with award schema to optimize visibility in AI tools and search engines.

The Google Reality: Google Reviews offer no equivalent industry recognition or awards program. While businesses might accumulate a high rating, there’s no mechanism to translate that into broader industry recognition or visibility in AI-powered search results.

6. A Combination Approach: Import Google Reviews to Wealthtender

For advisors who have received Google Reviews and firms comfortable inviting clients to submit reviews on Google, Wealthtender offers a useful solution to unlock their value: the Google Reviews import tool.

The Wealthtender Advantage: By importing existing Google Reviews to Wealthtender, they’ll first go through a compliance review process where you can add required regulatory disclosures. Once completed, these reviews become fully compliant testimonials you can promote across all your marketing channels. This combination approach offers the local SEO benefits of Google Reviews, plus the ability to actually use those reviews in your marketing with confidence.

The Google Limitation: On the flipside, Google doesn’t offer reciprocal integration of third-party reviews from platforms like Wealthtender to become “Google Reviews”. However, while Wealthtender Reviews cannot be exported to Google, Google Business Profiles often include a ‘Reviews from the Web’ section to spotlight the reviews a business has earned on reputable, independent platforms, including Wealthtender. For firms and compliance teams that choose not to solicit Google Reviews, this provides an alternative means to gain recognition for reviews on a Google Business Profile without causing regulatory anxiety.
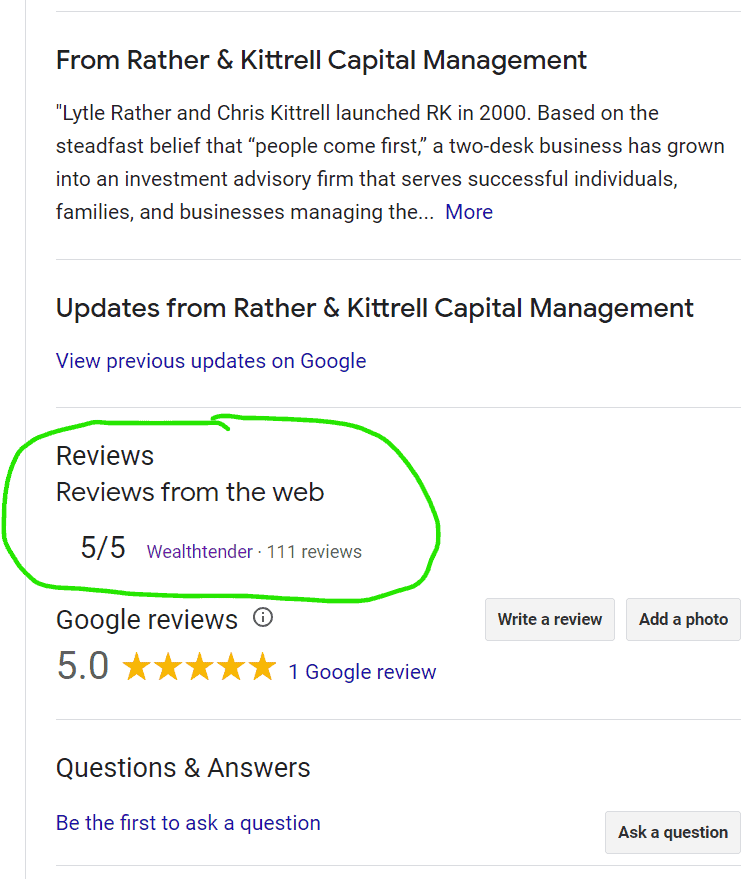
Screenshot of a Google search result for Rather & Kittrell Capital Management. It shows an overview of the business, updates, a 5/5 rating from Wealthtender based on 111 reviews, and a 5.0 Google rating from 1 review. The review summary is highlighted in green.

7. Turn Reviews Into Marketing Assets With Tools Built for Financial Advisors

Collecting reviews is only the first step. The real value comes from effectively displaying and promoting those reviews to attract new clients.

The Wealthtender Advantage: Wealthtender provides a comprehensive suite of marketing tools specifically designed for financial advisors:

  • Website Widgets: Embed compliant review displays directly on your website with customizable elements to match your brand
  • Testimonial Marketing Studio: Create professional graphics and videos featuring client testimonials using done-for-you templates
  • Review Management Dashboard: Monitor, approve, and manage all reviews from a single interface

These tools transform reviews from static testimonials into dynamic marketing assets that work across every stage of your client acquisition funnel.

The Google Limitation: Google provides no marketing tools beyond the basic display of reviews on your Google Business Profile. There are no widgets, no compliant promotional templates, and no tools to help you leverage reviews in your broader marketing strategy. The reviews exist in isolation on Google’s platform, making them difficult to integrate into a comprehensive marketing approach. While third-party vendors offer widgets for businesses to display Google Reviews on websites, they aren’t designed for the wealth management industry and lack the compliance features necessary for use by financial advisors.

FMG Chief Evangelist Samantha Russell and Wealthtender Chief Evangelist Diana Cabrices teamed up in this video to offer education on the ways financial advisors can optimize for AI visibility, including the role of Wealthtender Reviews to strengthen SEO and AEO.

Choose the Right Review Platform(s) To Compliantly Grow Your Business

While Google Reviews may have a place in your digital presence, particularly unsolicited testimonials that don’t open the door to regulatory scrutiny, they simply cannot compete with Wealthtender as a strategic marketing platform for financial advisors.

Wealthtender was built from the ground up specifically for financial advisors, with every feature designed to address the unique challenges you face in marketing your services compliantly and effectively. From built-in regulatory disclosures to AI-optimized visibility and professional marketing tools, Wealthtender transforms client testimonials from passive reviews into active marketing assets that drive business growth.

If you’re serious about leveraging client testimonials to grow your advisory practice while staying on the right side of regulators, Wealthtender is the platform that delivers results.

Want to see how individual advisors and leading wealth management firms are successfully using Wealthtender to grow their business? Visit Wealthtender.com/grow or schedule a demo to learn how you can start converting more prospects into clients with compliant testimonial marketing.
Certified Advisor Reviews - Wealthtender

Wealthtender offers the industry’s first financial advisor review platform designed for regulatory compliance.
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian

What this article covers

If your digital marketing strategy still begins and ends with SEO, you’re optimizing for how consumers searched for financial advisors five years ago. Today, a growing share of the prospects most likely to hire an advisor are starting their search on ChatGPT, asking Gemini for recommendations, or reading AI Overviews at the top of a Google results page — and never clicking through to any website at all. That shift is what Answer Engine Optimization (AEO) is designed to address: ensuring that when an AI tool fields a question about finding a financial advisor, your name and expertise are part of the answer. This guide covers what AEO is, why it matters specifically for financial advisors, the seven most effective strategies to strengthen your AEO now — and why the advisors who start building this infrastructure today will be the hardest to catch later.

When I started Wealthtender in 2019, Google was the undisputed starting point for most consumer research and SEO (Search Engine Optimization) was the primary lever financial advisors had to influence what prospects found when they searched. That world is changing faster than most advisors realize.

Today, a meaningful and growing share of consumers preparing to hire a financial advisor are starting their search by typing a question into ChatGPT, asking Gemini for recommendations, or reading an AI-generated summary at the top of a Google results page and never clicking a single link. By the time they reach an advisor’s website or profile, many have already formed a strong impression of who’s credible in the space.

This shift from search engines that return lists of websites to answer engines that deliver synthesized responses is what Answer Engine Optimization (AEO) is designed to address. And it represents both the most important new frontier in digital marketing for financial advisors and one of the most significant windows of competitive opportunity I’ve seen in the 25+ years I’ve spent in financial services.

Most advisors aren’t thinking about AEO yet. The ones who start now will be the hardest to catch later.

↗️ Related Article: How Financial Advisors Get Found by ChatGPT and AI Search Tools

Key Takeaways

1

AEO isn’t a replacement for SEO — it’s the next layer financial advisors need to add now, before most competitors realize it exists.

Search Engine Optimization helps advisors rank in Google’s blue-link results. Answer Engine Optimization determines whether an advisor appears in the AI-generated summaries, Featured Snippets, and zero-click answers that are increasingly what consumers see first — or exclusively. As ChatGPT, Gemini, Perplexity, and Google AI Overviews handle more of the research consumers once did by clicking through multiple websites, advisors who aren’t optimized for direct answers are becoming invisible at the most critical moment in the prospect’s decision process.

2

The most impactful AEO tactics — FAQ schema, structured data markup, and presence on platforms AI tools already trust — are underutilized by the vast majority of advisory firms.

FAQ schema transforms standard Q&A content into machine-readable signals that AI tools actively parse when generating answers. Structured data tags your credentials, services, and reviews in language search engines understand natively. And strategic presence on high-authority third-party platforms amplifies both — giving advisors indexable content on domains AI tools already treat as trusted sources for financial advisor discovery, separate from and additive to an advisor’s own website.

3

The advisors building AEO infrastructure now are doing so while the vast majority of their competitors haven’t started — and that window won’t stay open indefinitely.

AEO authority compounds over time the same way SEO authority does — through consistent content, accumulated reviews, growing backlinks, and deepening topical credibility across indexed platforms. Advisors who establish their AEO presence now will be significantly harder to displace than those who wait until AI-powered discovery becomes the dominant channel. The gap between early movers and late adopters in SEO took years to close; in AEO, that gap is forming right now.

What Is Answer Engine Optimization (AEO)?

Answer Engine Optimization is the practice of structuring your website, online profiles, and content so that AI-powered tools and search engines surface you by name, by expertise, or by recommendation when consumers ask relevant financial questions, without necessarily requiring them to click through to any website.

Traditional SEO helps you rank in Google’s blue-link results. AEO determines whether you appear in the AI-generated summaries, Featured Snippets, Knowledge Panels, voice search responses, and zero-click answers that are increasingly what consumers see first (or exclusively).

The platforms driving this shift include:

  • ChatGPT (OpenAI, backed by Microsoft and powered in part by Bing)
  • Gemini (Google)
  • Perplexity
  • Claude (Anthropic)
  • Google AI Overviews (displayed above traditional search results)
  • Voice assistants (Siri, Alexa, Google Assistant)

Each of these tools draws on publicly available content (e.g., articles, profiles, reviews, FAQs, and structured data) to generate answers. Advisors whose content is well-structured, credible, and widely indexed across authoritative platforms are the ones these tools cite. Advisors whose content isn’t optimized for direct answers are being filtered out before the search results page ever loads.

Watch · On-demand masterclass Are you lost or found in AI search? See a hands-on SEO and AEO audit of real advisor websites with Brent Carnduff of Advisor Rankings, exactly how advisors get found in Google and in AI tools like ChatGPT and Perplexity. Diana Cabrices + Brent Carnduff · ~66 min Watch the audit

Why AEO Matters Now (Not Eventually) for Financial Advisors

I want to be direct about something: AEO is not a replacement for SEO. Traditional search still drives significant volume, and the foundational practices of SEO (e.g., quality content, backlinks, local optimization, site structure) remain essential and directly support AEO. Advisors who have invested in SEO over the years have a meaningful head start. In fact, Google stated this emphatically in a May 2026 Google Search Central article, stating: “The best practices for SEO continue to be relevant because our generative AI features on Google Search are rooted in our core Search ranking and quality systems.”

What’s changing is where the frontier is. And right now, for financial advisors, that frontier is AI-powered discovery.

Here’s what’s happening to search behavior in practice:

  • Consumers increasingly ask AI tools for recommendations using natural, conversational language: “Who are the best financial advisors for tech employees with equity compensation in Austin?” rather than “financial advisors Austin Texas”
  • Google AI Overviews now appear above traditional search results for a large share of financial planning queries, meaning advisors who don’t appear in the AI summary may not get a second look even if they rank well in traditional results
  • Voice search queries which almost always take a conversational, question-based format are almost entirely served by AI-generated responses rather than ranked link lists
  • A Wealthtender Research report conducted in 2025 shows that 25% of consumers already plan to use AI tools to find a financial advisor, a figure that will only rise as AI adoption broadens

The implication is straightforward: advisors who optimize only for traditional search are optimizing for a shrinking share of the discovery funnel. AEO addresses the share that’s growing.

The Great Decoupling: How Impressions and Clicks Are Separating

One dynamic that SEO-focused advisors often don’t anticipate is what digital marketing experts are calling “The Great Decoupling” – the growing separation between impressions (how often your content appears in search) and clicks (how often someone actually visits your website as a result).

AI-powered search tools are driving this: Google’s AI Overviews, ChatGPT responses, and other zero-click answer formats all surface advisor information (e.g., names, credentials, specializations, reviews) without requiring the consumer to click through to any website. An advisor can be cited in AI-generated responses many times in a given month and never see a corresponding spike in website traffic.

This doesn’t mean AEO isn’t working. It means the conversion path has changed. Prospects who encounter your name in multiple AI-generated answers build familiarity and trust over time, and when they’re ready to reach out, they often arrive through direct navigation, referral confirmation, or a name search rather than a traditional first click from a search result. Measuring this journey requires thinking differently about attribution, but the business impact is real.

7 Strategies to Strengthen AEO for Your Advisory Firm

If you already have a digital marketing strategy focused on SEO, many of your existing activities are likely already creating some AEO benefit. The strategies below are designed to build on that foundation and close the gaps that matter most for AI-powered discovery specifically.

1. Optimize for Featured Snippets and Google AI Overviews

Google’s Featured Snippets — the boxed answers that appear at the top of search results — and AI Overviews are among the highest-visibility placements available to financial advisors in traditional search. To improve your chances of appearing in either:

  • Structure key content on your website in direct question-and-answer format, with the question as a heading and the answer as the immediate following paragraph
  • Keep initial answers concise — 40–60 words — before elaborating with supporting context
  • Format supporting content with bullet points, numbered lists, and tables that AI tools can parse efficiently
  • Use specific, descriptive H2 and H3 headings that mirror the questions your target clients actually type into search bars

The same structural principles that help you earn a Featured Snippet make your content more likely to be cited in AI Overviews and third-party AI tool responses. These aren’t two separate optimization targets — they’re the same discipline applied consistently.

2. Build and Optimize FAQ Content — With Schema Markup

FAQ sections have been standard practice for advisor websites for years. But there is a meaningful difference between FAQs written for human readers and FAQs structured for AI discovery — and that difference is schema markup.

FAQ schema is a type of structured data code that marks up your question-and-answer content in a way that tells search engines and AI tools exactly what they’re looking at. It transforms your FAQ from a formatted web page into a machine-readable signal that AI tools can identify and extract when generating answers to consumer queries. Without it, your FAQ content competes for AI attention the same way every other paragraph on your website does. With it, your content is explicitly flagged as the kind of structured, direct answer AI tools are looking for.

The same principle extends beyond your own website. Any platform where you maintain a profile — and that implements FAQ schema on your behalf — is contributing to your AEO reach. When you publish FAQs on a high-authority third-party platform, those FAQs are indexed by Google and Bing with the same structured signals as content on your own site, amplified by the domain authority of the platform itself.

↗️ Related Article: How Financial Advisors Can Use FAQs to Show Up in AI Tools and Search Engines

3. Write Conversationally — Match How Prospects Actually Ask Questions

AI tools are trained on natural language. They’re built to understand and answer questions the way people actually ask them — conversationally, in complete sentences, often starting with “how,” “what,” “should I,” or “who.” Content written in formal, keyword-dense prose is significantly less likely to be extracted as an AI-ready answer than content written the way a financial advisor would actually explain something to a client.

In practice, this means:

  • Write answers to financial questions in plain, direct language — as if you were answering a client in a meeting, not drafting a compliance document
  • Incorporate long-tail keyword phrases that mirror natural speech (“Should I do a Roth conversion before I retire?” rather than “Roth conversion retirement strategies”)
  • Lead with the answer, then provide supporting context — AI tools extract the first clear statement of an answer most reliably and use what follows for elaboration
  • Structure longer explanations so a reader scanning the first sentence of each paragraph would still follow the core argument

This principle applies equally to your own website content, your contributions to third-party platforms, and any Q&A or Ask an Advisor responses you publish publicly.

4. Build Authority Through Media Mentions, Backlinks, and Verified Client Reviews

AI tools weight credibility heavily when deciding which sources to surface. Two of the clearest signals of credibility in the eyes of an AI tool are being cited by other authoritative sources and being reviewed favorably by real clients on platforms those tools treat as trustworthy.

For financial advisors, the most effective tactics for building AI-visible authority include:

  • Earning media mentions — being quoted as an expert source in personal finance articles through programs like Wealthtender’s Quoted feature, HARO (now Connectively), or direct outreach to journalists covering financial planning topics
  • Publishing in industry outlets — contributing thought leadership to recognized industry publications establishes topical authority that AI tools weight when deciding which advisors know a subject deeply
  • Collecting client reviews on platforms with structured data — reviews on platforms that implement AggregateRating schema communicate your credibility to search engines and AI tools in a structured, machine-readable format, not just as unstructured text. Those gold-star ratings that appear in Google search results are a direct product of schema-marked reviews on platforms AI tools have learned to trust
  • Earning backlinks from authoritative sources — each inbound link from a credible website is a vote of confidence that search engines and AI tools interpret as evidence of authority

These signals don’t just improve your traditional search rankings — they’re among the strongest inputs AI tools use to determine which advisors are genuinely credible versus simply present online.

5. Add Schema Markup to Your Website — the Technical Signal AI Tools Weight Most

Structured data is the technical backbone of AEO. While FAQ schema is one important type, several additional schema types are directly relevant for financial advisors:

  • Person schema — tags your name, credentials, employer, and professional profile in a format search engines understand natively
  • LocalBusiness / FinancialService schema — identifies your firm, services offered, service area, and contact information
  • Review / AggregateRating schema — communicates your client review data in a machine-readable format, enabling the star ratings that appear in Google search results
  • PotentialAction schema — enables direct actions (scheduling a consultation, sending an inquiry) to be surfaced in search results without requiring a click through to your website first

The majority of financial advisor websites have not implemented the full range of relevant schema types — which means doing so creates an immediate, durable competitive advantage over advisors whose sites Google and AI tools are interpreting with less precision. Working with your website developer to audit your current structured data and fill the gaps is one of the highest-leverage technical investments in the AEO toolkit.

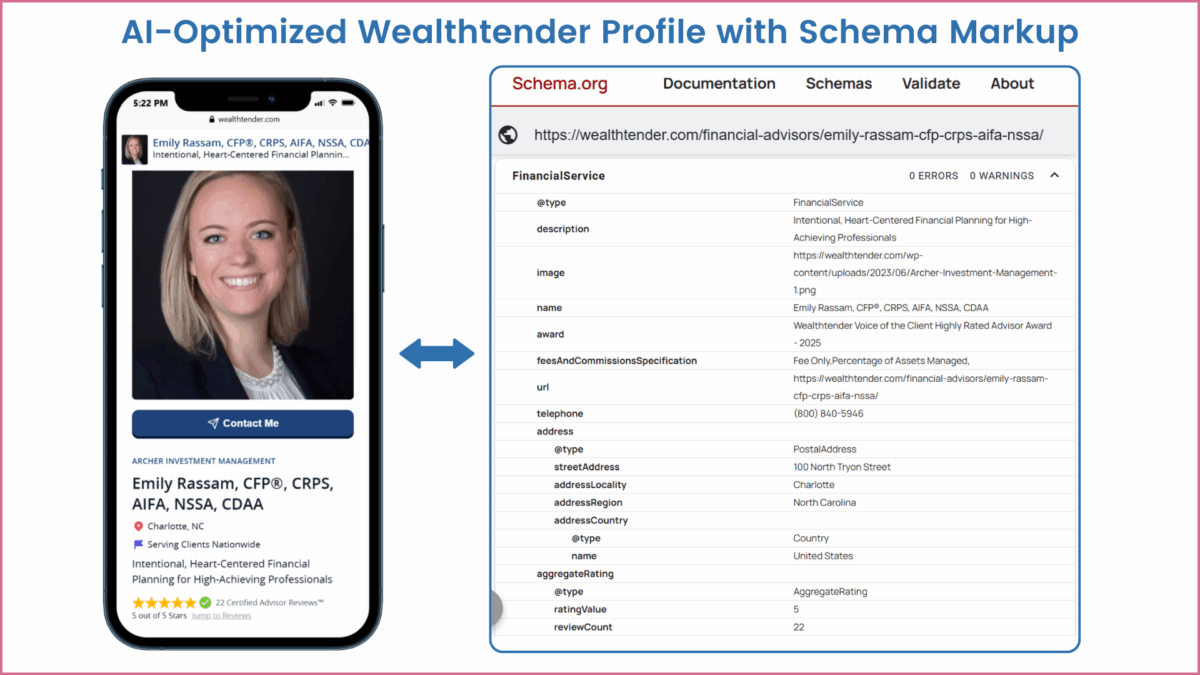
A smartphone displays a financial advisor's profile next to a screenshot of schema.org structured data markup for the same advisor, illustrating AI-optimized profile creation with Schema Markup.

6. Build Thematic Content Clusters Around Your Specializations

AI tools don’t just evaluate individual pages — they assess the topical authority of an entire website or profile on a given subject. An advisor who has published five deeply substantive, interlinked articles on retirement income planning signals far more expertise on that topic than an advisor with a single retirement planning service page.

Content clustering means organizing your content into connected hubs: a central pillar page covers a broad topic comprehensively, and multiple supporting pages or articles address specific subtopics in depth, all interlinked. Some examples for financial advisors:

  • Retirement Planning Hub → Roth conversion timing, RMD strategies, sequence of returns risk, Social Security optimization, Medicare IRMAA
  • Equity Compensation Hub → RSUs, ESPPs, NQSOs, ISOs, 10b5-1 plans, concentrated stock positions
  • Business Owner Hub → Solo 401(k)s, buy-sell agreements, exit planning, succession strategy

The same principle applies beyond your own website: contributing FAQ answers, Q&A articles, and educational content to platforms that serve your target audience builds topical authority across multiple indexed sources simultaneously — compounding your AEO reach without requiring an equivalent increase in your own content production.

Watch · On-demand masterclass How to become the financial advisor ChatGPT recommends. Samantha Russell of FMG and Diana Cabrices of Wealthtender break down a simple three-part playbook for getting recommended by AI: get reviews, build authority, and format your content for AEO. Diana Cabrices + Samantha Russell · ~58 min Watch the masterclass

7. Get on the Platforms AI Tools Already Trust to Find Financial Advisors

Your own website is one signal among many that AI tools evaluate. Your presence on third-party platforms — particularly those with strong domain authority that AI tools have already identified as reliable sources for financial advisor information — can significantly amplify your AEO coverage in ways that no amount of work on your own site alone can fully replicate.

The key principle is that AI tools learn to trust platforms that aggregate credible, structured, independently-verified information about professionals in a category. In financial services, the platforms that currently meet that standard include:

  • Wealthtender — advisor and firm profiles with schema markup for financial services, FAQs, and verified client reviews; indexed by Google and Bing; content regularly cited by ChatGPT, Gemini, Perplexity, and other AI tools in response to financial advisor queries
  • FINRA BrokerCheck and SEC IAPD — regulatory databases treated by AI tools as authoritative sources for credential verification
  • LinkedIn — a high-authority professional network frequently cited in AI responses to professional recommendation queries
  • Google Business Profile — relevant for local SEO and trust signals; advisors should be aware of the compliance considerations that apply to Google Reviews specifically

Maintaining complete, updated, review-rich profiles across the platforms AI tools most frequently cite is one of the most durable AEO investments an advisor can make. Unlike content creation, which requires ongoing effort to remain current, a well-structured profile on a trusted platform compounds in value over time without requiring continuous maintenance.

SEO vs. AEO for Financial Advisors: Side-by-Side Comparison

SEO versus AEO for financial advisors: a side-by-side comparison of purpose, focus, ranking factors, content format, consumer interaction, and optimization strategy for search engine optimization and answer engine optimization as complementary digital marketing disciplines
Established SEO for Financial Advisors AI-Era AEO for Financial Advisors
Purpose Rank higher in Google and other search engines to attract organic website traffic Appear in AI-generated answers, Featured Snippets, and voice search responses — with or without a click
Focus Keywords, backlinks, local SEO, domain authority, technical site health Structured data, conversational content, direct answers, multi-platform credibility signals
Search Intent Consumers browsing for financial services, educational content, or local advisors Consumers seeking direct answers to specific financial questions or advisor recommendations
Ranking Factors Keyword optimization, link equity, content quality, technical site performance Schema markup, answer clarity, source credibility, cross-platform presence
Content Format Blog posts, service pages, guides, case studies, whitepapers FAQs, Q&A content, structured data, conversational articles, direct-answer pages
Consumer Interaction Consumer clicks through to advisor website or third-party profile Consumer receives a direct answer — advisor may be cited without a click ever occurring
Optimization Tools Google Search Console, Ahrefs, Moz, SEMrush Schema validators, Google’s Rich Results Test, AI tool testing by name and topic
Time to Impact Weeks to months for new content; compounds steadily over time Similar timeline; benefits accelerate when using platforms with existing domain authority
Best For Generating consistent organic search traffic and inbound leads over time Getting cited in AI-generated answers, zero-click results, and voice search responses

The most effective digital marketing strategy for financial advisors combines both. The foundational work SEO requires (e.g., quality content, structured data, authoritative backlinks, complete third-party profiles) directly supports AEO as well.

The most effective digital marketing strategy for financial advisors in 2026 and beyond treats SEO and AEO as complementary disciplines, not competing ones. The investments required for strong SEO — quality content, structured data, authoritative inbound links, complete third-party profiles — are largely the same investments that drive strong AEO. The difference is in how deliberately you structure that content for AI-readable extraction.

Your AEO Action Plan: Where to Start

The full set of strategies above may feel like a significant undertaking for advisors managing a practice and a marketing strategy simultaneously. Here’s how to prioritize:

Start this month:

  • Search your own name and firm name in ChatGPT, Gemini, and Perplexity — what comes back tells you exactly where your current AEO baseline stands and where the most visible gaps are
  • Audit your existing FAQ content and ask your website developer to add FAQ schema markup to any FAQ sections on your site
  • Run your website through Google’s Rich Results Test (available free at search.google.com/test/rich-results) to identify structured data gaps

In the next 90 days:

  • Ensure your profiles on Wealthtender and other third-party platforms AI tools most frequently cite are complete, accurate, and include FAQ content where supported
  • Identify two or three content clusters aligned with your specializations and begin building or connecting related articles and pages
  • Submit or update your Google Business Profile and verify your SEC/FINRA public profile information is current

Ongoing:

  • Collect client reviews on platforms with schema-marked structured data — they are trust signals for prospects and credibility signals for AI tools simultaneously
  • Contribute expert answers and Q&A content to platforms that index your responses with appropriate authority
  • Update high-performing existing content regularly — AI tools weight recency alongside topical authority
  • Monitor which AI tools cite you and for which queries, and use those gaps to guide your next content priorities

The advisors building AEO infrastructure now are doing so in a competitive landscape where the majority of their peers haven’t started. That advantage is real — and it won’t stay available indefinitely.

Want to see how individual advisors and leading wealth management firms are successfully using Wealthtender to grow their business? Visit Wealthtender.com/grow or schedule a demo to learn how you can start converting more prospects into clients with compliant testimonial marketing.

A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian


What this article covers

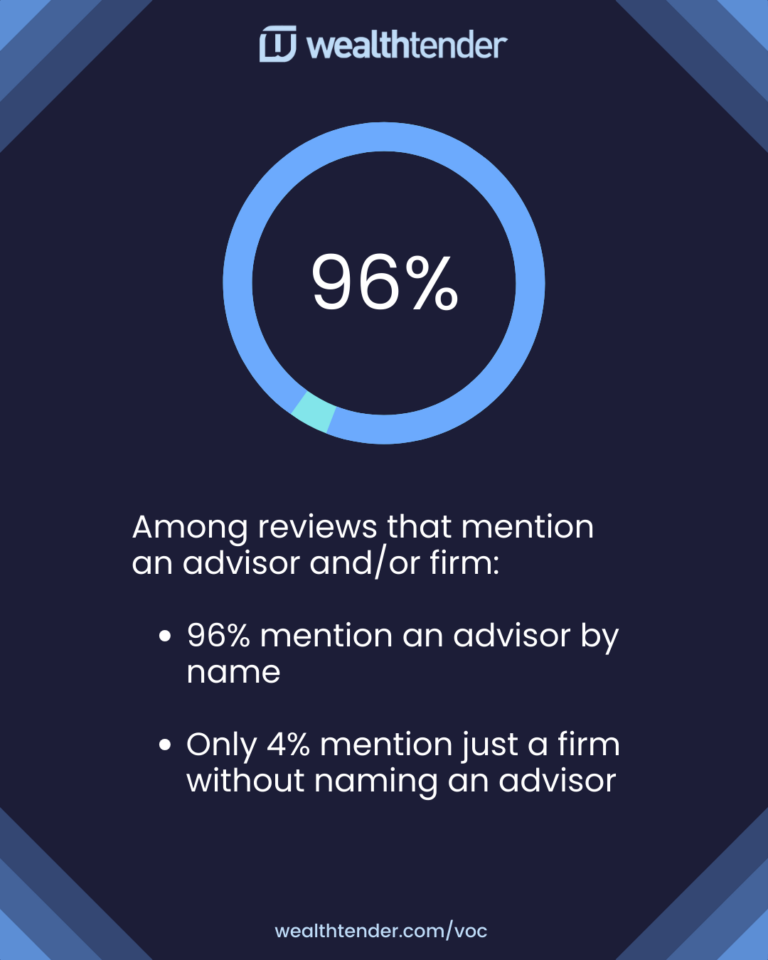
When was the last time you chose a doctor based solely on a hospital’s reputation? Probably never, because in trust-based professions, people hire individuals, not institutions. Healthcare and legal professionals have understood this for more than a decade, building individual review strategies that drive referral conversions, deepen client relationships, and strengthen firm brands simultaneously. Wealthtender’s 2025 Voice of the Client Study confirms the same dynamic holds for financial advisors: 96% of client reviews name an individual advisor, while just 4% mention only the firm. Here’s what that data means for your wealth management firm’s review strategy and why the firms acting on it now will be the hardest to catch.

For decades, healthcare and legal professionals have understood a fundamental truth that many wealth management firms are only beginning to grasp: nearly 75% of patients turn to online reviews as the first step when searching for a new physician, and they’re not looking at hospital-level ratings. They’re researching individual doctors by name. The same pattern holds true for attorneys, where platforms like Avvo create profiles for 97% of attorneys in the United States, with each lawyer evaluated and reviewed individually.

In the wealth management industry, where online reviews have only recently become available, advisory firm leaders can jump ahead of competitors by applying the lessons learned in the legal and healthcare professions over decades, or risk operating on flawed assumptions, losing prospects to peers and having to play catch-up a year or two down the road.

Key Takeaways

1

Clients mention individual advisors by name 25 times more often than they mention firms.

The Wealthtender 2025 Voice of the Client Study analyzed over 2,500 client reviews and found that 96% name an individual advisor, while just 4% mention only the firm. When clients write reviews, they’re reflecting on a personal relationship — which means firms that only collect firm-level reviews are structurally missing the conversation their clients are already having.

2

Healthcare and legal professionals proved the individual review model works — and wealth management is more than a decade behind.

Nearly 75% of patients turn to individual physician reviews as their first step when finding a new doctor. Legal platforms like Avvo individually profile and review 97% of U.S. attorneys. The consumer expectation for individual professional reviews is already firmly established — wealth management firms that meet it now capture first-mover advantage before competitors catch on.

3

Collecting reviews at the individual advisor level doesn’t sacrifice firm-level benefits — it amplifies them.

Platforms like Wealthtender automatically aggregate individual advisor reviews to the firm level, giving wealth management firms the best of both worlds: highly personal, emotionally resonant reviews that convert prospects, combined with firm-wide credibility that strengthens your brand as a whole. You can’t effectively run this strategy in reverse — firm-level reviews rarely capture the emotional specificity that drives hiring decisions.

The data proves collecting reviews only at a firm level simply misses the mark. Wealthtender’s 2025 Voice of the Client Study analyzed over 2,500 client reviews of financial advisors and discovered a revealing truth: clients mention individual advisors by name nearly 25 times more often than they mention their firms.

When clients write reviews, they’re thinking about their advisor, the person who guided them through major life transitions, celebrated their successes, and provided reassurance during uncertain times. Importantly, this shouldn’t be viewed as detracting from the value proposition of the firm – just the opposite. A five-star review about an individual advisor is a testament to the caliber of the wealth management firm, it’s culture, and the advisors themselves who serve as brand ambassadors for the firm.

A graphic shows a large "96%" inside a blue circle. Text below reads: "Among reviews that mention an advisor and/or firm: 96% mention an advisor by name; Only 4% mention just a firm without naming an advisor.

To further test the hypothesis that the healthcare and legal playbook applies to financial advisors, Wealthtender commissioned its inaugural Study of $100K+ Households Seeking Financial Advice, published in August 2025. The survey of 500 Americans planning to hire a financial advisor shows that 96% of people who receive a referral to a financial advisor will research that advisor (and at least one more) online before making contact, with 83% specifically looking for online reviews. And when they search, much more often than not, they’re looking for reviews about the individual advisor, not just your firm.

Why Patients Search for Dr. Chen, Not the Hospital — and What That Means for Advisors

In healthcare, the transition to individual professional reviews wasn’t optional, it was driven by consumer demand. A 2025 Tebra Research Report reveals a critical insight: the reviews that patients write and that consumers read before choosing a provider aren’t reviews of hospitals or medical centers. They’re reviews of Dr. Sarah Chen, Dr. Michael Rodriguez, Dr. Jennifer Thompson, individual practitioners who have built their reputations one patient interaction at a time.

The reasons are both practical and profound:

Personal Connection Drives Engagement. When Dr. Chen’s patient receives a request to review their experience, they’re reflecting on a specific relationship, e.g., how Dr. Chen listened to their concerns, explained treatment options, and made them feel cared for during a vulnerable time. When patients feel like their individual experience is valued, they’re more motivated to share their positive impressions. This personalized approach generates reviews that are more detailed, more emotional, and ultimately more persuasive to prospective patients.

Search Behavior Reflects Individual Focus. A 2025 RepuGen report indicates that when consumers are evaluating healthcare providers, they’re not searching for “best hospital in Boston”, they’re searching for “Dr. Sarah Chen cardiologist reviews” after receiving her name from a friend or their primary care physician.

Quality Insights Enable Performance Management. Healthcare practices that treat reviews as continuous feedback loops (e.g., monitoring sentiment and making improvements based on feedback) outperform on loyalty and retention. When reviews are collected at the individual physician level, practice administrators can identify which doctors excel at patient communication, who might need additional training in bedside manner, and where systems issues (like wait times) consistently impact specific providers’ patient experiences.

How Avvo Proved the Individual Review Model Works — and What Law Firms Gained From It

The legal profession’s approach to individual professional reviews provides another compelling case study. Platforms like Avvo have revolutionized how consumers find and evaluate attorneys, creating a system where each lawyer is individually rated and reviewed. These consumers aren’t browsing law firm websites, they’re comparing individual attorneys based on credentials and client reviews. The platform’s success demonstrates several critical principles:

Individual Differentiation Creates Competitive Advantage. Within a single law firm, different attorneys inevitably have different specialties, communication styles, and track records. A lawyer whose Avvo profile is fully filled out, including awards, speaking engagements, and recommendations from other attorneys, will have a high Avvo rating. This individual differentiation helps potential clients find the right attorney for their specific needs, rather than making a generic choice based on firm marketing alone.

Personal Reputation Drives Hiring Decisions. As long as star ratings are the best they can be across all platforms, attorneys are in a good position to get found by highly interested potential customers at the bottom of the marketing funnel. These are people who have already decided they need legal help and are actively comparing their options. Individual reviews provide the social proof necessary to convert that interest into a retained client.

Aggregation Still Delivers Firm-Level Benefits. Here’s the key insight many wealth management firms miss: collecting reviews at the individual attorney level doesn’t preclude firm-level benefits. Law firms routinely showcase their top-rated attorneys on their websites, and those individual ratings contribute to the firm’s overall reputation and brand equity. You get the best of both worlds.

Why Prospects Trust Individual Advisors More Than Firms and What That Means for Your Marketing

Why does this individual focus matter so much in trust-based professions? The answer lies in fundamental human psychology and the nature of professional relationships.

Both personal branding and reputation strategies aim to increase authority in your area of expertise. Personal branding achieves this by making you more recognizable as a trusted resource. When consumers face important decisions about their health, legal matters, or financial future, they instinctively seek connection with another human being, not with an institution.

The vast majority of millennials (84%) don’t trust ads and businesses, but they do trust the individuals behind those brands when the individual has two things: a good reputation and a well-developed brand. This generational shift has profound implications for wealth management firms. The next generation of investors grew up reading individual reviews for everything from restaurants to college professors and babysitters. They expect the same transparency and individual accountability when choosing a financial advisor.

How the Individual Review Model Translates Directly to Wealth Management

Now let’s apply these insights specifically to your wealth management firm. The parallels are striking, and the opportunities are enormous.

96% of Referred Prospects Research the Individual Advisor Before Making Contact

To briefly recap key findings from our Wealthtender 2025 Study of $100K+ Households Seeking Financial Advice: 96% of people referred to a financial advisor will still research them online before making contact. This is the same behavior we see in healthcare and legal services: referrals create interest, but online research drives hiring decisions.

But here’s what makes this research particularly relevant: when people search, they’re most likely to have been referred to the individual advisor by name, and that’s who they will be searching for. Not your firm. Not your brand. The specific advisor who was recommended to them.

And the data confirms this individual focus: The Wealthtender 2025 Voice of the Client Study found that clients mention individual advisors by name nearly 25 times more often than they mention their firms. This isn’t a small preference, it’s an overwhelming pattern that reveals the true nature of financial advisory relationships. First and foremost, clients form bonds with individual professionals, not institutions.

The study found that 83% of respondents plan to research an advisor’s reputation by looking for online reviews and awards as their primary next step after receiving a referral. If those reviews don’t exist, or if they only exist at the firm level rather than the individual advisor level, you’re missing the critical moment when a warm referral converts into a scheduled consultation.

What 2,500 Client Reviews Reveal About What Actually Drives Advisor Hiring Decisions

Let’s dive deeper into the Voice of the Client Study that analyzed over 2,500 client reviews from more than 200 advisors across 35 states. The study reveals exactly what clients value when writing about their financial advisors:

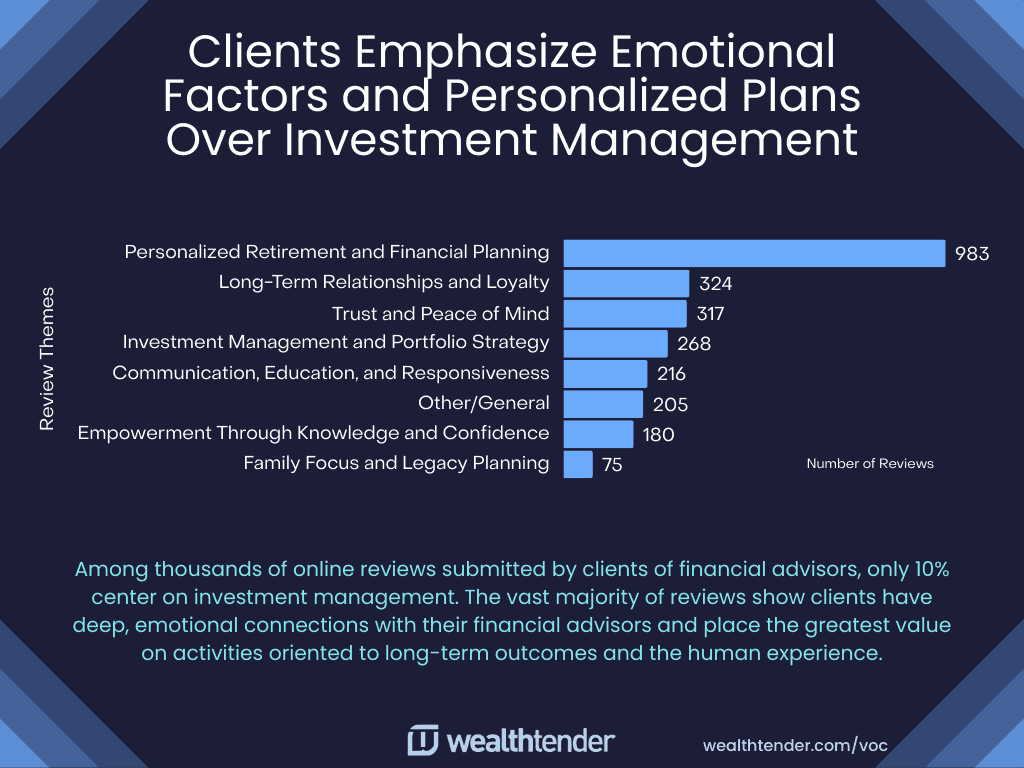
89% of reviews center on relationship quality, planning advice, and emotional factors, the human elements of the advisor-client relationship. Only 10% focus on investments or portfolio management.

A dark blue graphic shows a ring chart with "89%" in the center, representing client reviews of financial advisors focused on relationships and emotional factors rather than investments or portfolio management.

This finding is instructive for how we think about modern marketing tactics for wealth management firms. Clients aren’t writing elaborate reviews about your firm’s investment philosophy or your Chief Investment Officer’s market outlook. They’re writing about how their individual advisor made them feel across major life milestones, the clarity their advisor brought when difficult decisions needed to be made, and the trust built through years of personalized guidance.

The study found that 86% of reviews convey strongly positive sentiment, with clients using an average of 86 words per review, many sharing detailed, story-like testimonials that reflect deep emotional investment in the relationship. These aren’t curt “5 stars, great service” reviews. They’re narratives about how Stefanie helped a widow navigate her finances after losing her husband, or how Michael guided a couple through retirement with confidence, or how Emily became not just an advisor but a trusted partner through life’s biggest transitions.

This emotional, relationship-focused content is marketing gold, but it only exists when you collect reviews at the individual advisor level.

4 Reasons Individual Advisor Reviews Outperform Firm-Only Reviews

1. Clients Respond to a Personal Ask from Their Advisor — Not a Generic Firm Email

When your client receives a review request from “ABC Wealth Management,” it’s a transactional ask from an institution. When they receive that same request from “Sarah Martinez, CFP,” it’s a personal ask from a trusted professional.

The difference in response rates is dramatic. Healthcare providers find that it takes only between one and six reviews for potential patients to form an opinion about a practice, which means every review matters. The personal connection between client and advisor dramatically increases the likelihood that busy clients will take time to share their experience.

Think about your own firm’s top advisors, the ones with multi-year client relationships, who attend their clients’ children’s weddings and have become trusted confidants, alongside their role as a financial advisor. These relationships have depth and emotional resonance. Reviews should capture that reality.

2. Advisor-Level Reviews Generate the Emotional, Story-Driven Content That Actually Converts

Compare these two hypothetical reviews:

Firm-Level Review: “ABC Wealth Management has provided solid investment advice for our portfolio. We’ve been clients for 10 years and are satisfied with their services.”

Advisor-Level Review: “Working with Sarah Martinez has been life-changing. When my husband passed away unexpectedly, Sarah didn’t just help me navigate the financial complexity, she listened, provided emotional support, and created a plan that gave me confidence I could maintain our lifestyle and put our kids through college. Her quarterly check-ins feel like conversations with a trusted friend who happens to be brilliant with money. I can’t imagine going through this without her guidance.”

As a consumer preparing to hire a financial advisor, which review would compel you to schedule a meeting?

Advisor-level reviews naturally elicit more specific, emotional, and relatable content because clients are reflecting on a personal relationship rather than evaluating a corporate service. They’ll mention the advisor’s communication style, specific ways the advisor helped them through challenges, personality traits that made them comfortable, and tangible outcomes that mattered to their family.

This emotional specificity is marketing gold. Our research shows that 83% of people want to read online reviews about financial advisors before hiring one, and they’re looking for reviews that help them understand what it will actually be like to work with that individual professional. Generic firm-level reviews simply cannot deliver this level of insight and connection, while advisor-level reviews can provide insights into both.

3. Individual Reviews Give You a Built-In Coaching Tool for Advisor Development

Here’s a benefit many wealth management firm leaders likely haven’t yet considered: individual advisor reviews provide invaluable business intelligence for managing and developing your team. For example, imagine how individual-advisor reviews could enhance your annual performance assessment process. Insights gathered from advisor reviews could help identify which advisors excel in soft-skills like communications and empathy, and others receiving praise for the outcomes they’ve generated through years of financial planning.

Beyond opportunities to recognize and reward exceptional client service, reviews may also illuminate areas where advisors could benefit from additional coaching or training. (This is exactly what we’re fleshing out through our Wealthtender partnership with the University of Texas.)

Healthcare practices that treat reviews as continuous feedback loops improve on both patient loyalty and employee retention. The same opportunity exists in wealth management. Client reviews, collected consistently at the individual advisor level, become a powerful tool for identifying strengths to celebrate, gaps to address, and best practices to share across your advisory team.

This is impossible to achieve with firm-level reviews alone. When clients write about “the firm,” they rarely provide the specific, actionable insights that individual advisor reviews naturally generate.

4. Individual Reviews Roll Up to the Firm Level Automatically — You Don’t Have to Choose

The good news about collecting reviews at the individual advisor level is that doing so doesn’t prevent you from also promoting them at the firm level, essentially providing the best of both worlds for wealth management firms that execute a holistic testimonial marketing strategy.

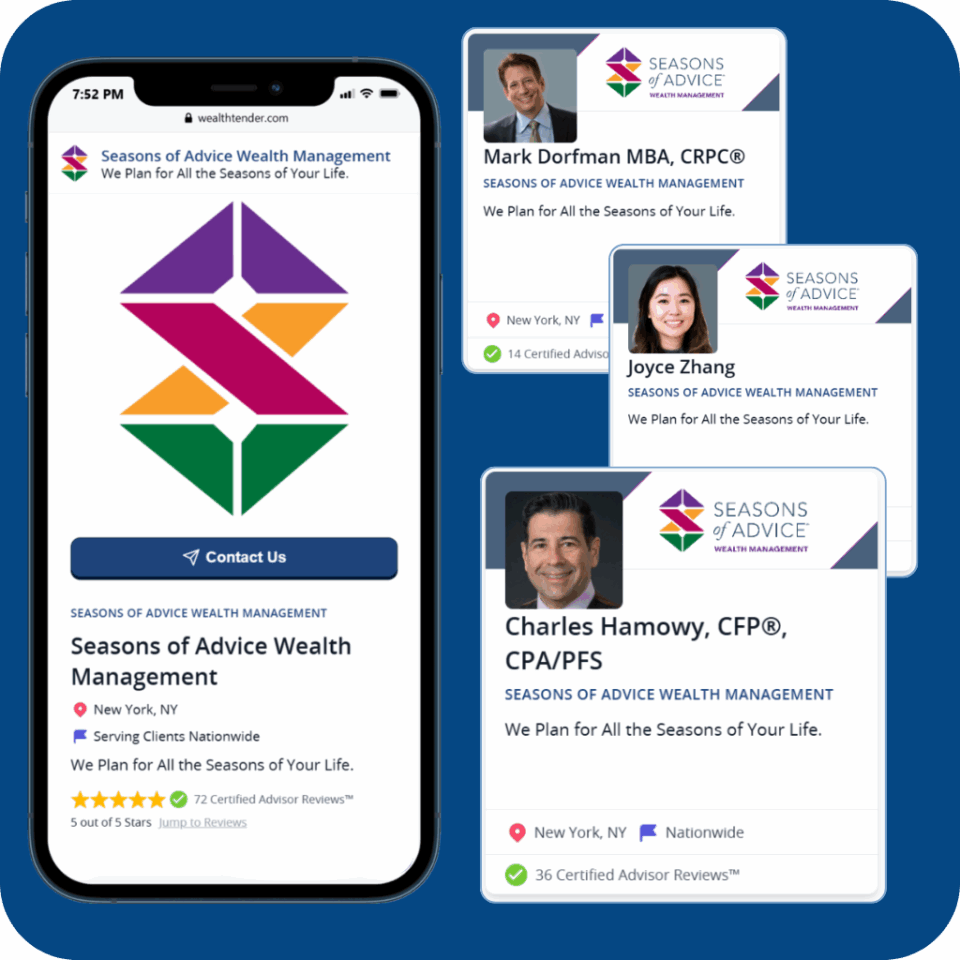
Consider Seasons of Advice Wealth Management, a $1B+ AUM advisory firm in New York City that partners with Wealthtender to collect and publish compliant reviews.

Visit their firm profile on Wealthtender and you’ll see an aggregation of all of their individual advisor reviews, plus links to the profiles of each individual advisor, strengthening SEO and AI-optimization for the firm and advisors alike. The reviews you’ll find aren’t generic firm testimonials; they’re specific, heartfelt accounts of individual client-advisor relationships.

A mobile phone and three profile cards display Seasons of Advice Wealth Management’s logo, contact button, and advisor profiles for Mark Dorfman, Joyce Zhang, and Charles Hamowy, with locations and credentials shown.

Looking at Charles Hamowy’s reviews, you’ll see clients describing him as “the architect of my well lived life” and “the reason I have a healthy retirement portfolio.” For Chris Conigliaro, clients write about “20+ years” of trust and how “he is someone I trust.” These deeply personal testimonials reflect the reality uncovered in the Voice of the Client Study: 89% of reviews focus on relationship quality and emotional trust, not just financial outcomes.

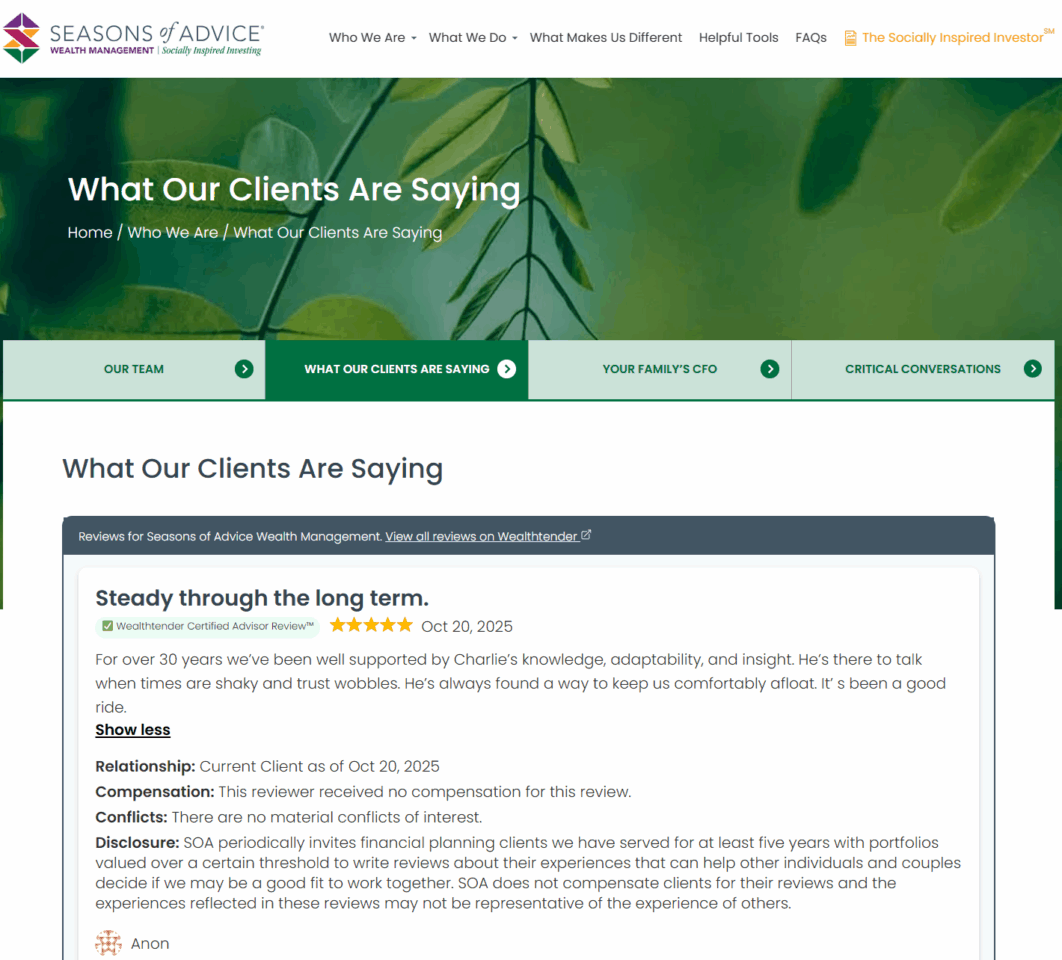
Here’s where Seasons of Advice gets even more value from their client testimonials. Beyond their publication on Wealthtender, they also display reviews on individual advisor bio pages on their website using embeddable widgets from Wealthtender, allowing prospective clients searching for a specific advisor to see relevant social proof immediately. And they roll up these same reviews on their firm-level reviews page, creating a comprehensive showcase of client satisfaction that elevates the online reputation of both advisors and the firm.

A website page titled "What Our Clients Are Saying" displays a client testimonial about the advisor’s knowledge and adaptability, dated Oct 20, 2025, with a 5-star rating and disclaimer below the review.

This is the “best of both worlds” approach that forward-thinking firms are adopting: collect at the individual level, publish at both the individual and firm level, and promote wherever it makes strategic sense. You can’t do this in reverse. Firm-level reviews are more difficult to attribute to individual advisors, and to the extent they are, they’re much less likely to include the emotion captured in reviews submitted at the advisor level.

Moreover, this approach aligns perfectly with how consumers want to research advisors. They want to read about the specific advisor they might hire, but they also want to see evidence that the firm as a whole maintains high standards. Individual advisor reviews aggregated at the firm level provide both.

The Exception: Small Ensemble Firms — and How Review Sync Solves for It

For small wealth management firms, typically those with just two to three advisors that provide financial planning services to clients through an ensemble approach, collecting reviews at the firm level could still result in testimonials that describe how individual team members made a difference in their lives. Unfortunately, this approach doesn’t offer the SEO and AI-optimization benefits at the individual advisor level, but as we discuss in the next section, Wealthtender introduced its Review Sync feature to solve for this shortcoming.

Why Wealthtender Is Built for Both Individual Advisor and Firm-Level Reviews

We founded Wealthtender in 2019 in anticipation of the SEC’s repeal of its longstanding prohibition of advisor using testimonials in their marketing activities. When the SEC Marketing Rule became effective on May 4, 2021, we publicly launched Wealthtender as the industry’s first online review platform designed for regulatory compliance.

While the regulatory elements we incorporated throughout Wealthtender are naturally based on SEC and FINRA requirements, our design of Wealthtender to incorporate both individual and firm-level reviews was inspired by the data-driven insights available in the healthcare and legal professions.

Individual Advisor Profiles with Firm-Level Aggregation

Wealthtender’s design incorporates best practices implemented by similar healthcare and legal platforms after many years of real-world consumer use. By creating detailed individual profiles with reviews for each advisor, then rolling up those reviews to the firm level, wealth management firms benefit from lessons learned by doctors and lawyers for more than a decade before online reviews became available to financial advisors.

With Wealthtender, each advisor gets their own profile page optimized for visibility in traditional search engines and AI tools like ChatGPT and Gemini, online reviews that further elevate their stature as a brand ambassador for the firm, while the firm itself maintains a profile that highlights the entire team’s collective excellence.

How Individual Advisor Profiles on Wealthtender Get Found in Google and AI Tools

By collecting reviews on Wealthtender, firms ensure their advisors are discoverable both through traditional search engines like Google and emerging AI-powered search tools like ChatGPT, Gemini, Perplexity and Claude. Wealthtender’s structured data and third-party validation provide AI tools confidence in the authenticity and relevance of the reviews, increasing the likelihood that your advisors appear in AI-generated recommendations.

Review Sync for Small Ensemble Advisory Firms

Small wealth management firms operating with an ensemble approach that join Wealthtender can activate the Review Sync feature to collect reviews on their advisory firm profile, and then, once disclosures are added, incoming reviews are displayed on each advisor’s Wealthtender profile, in addition to their firm profile.

This approach strengthens SEO and provides AI-optimization benefits for the firm and each advisor. When prospects preparing to hire financial advisors conduct research online, whether they search the name of the firm or any of the individual advisors in Google, ChatGPT, Gemini or any other search engine or AI tool, the reviews reflected on each Wealthtender profile results in maximum visibility.

Implementing an Individual Advisor & Firm Review Collection Strategy

Step 1: Shift Your Mindset

The first and most important step is recognizing advisors for the client-facing role that they play, each with their own unique strengths, styles, and client relationships. Each advisor is a brand ambassador for your firm, and their individual reputations contribute to (rather than compete with) your firm’s overall brand equity.

Step 2: Create Individual Profiles on Wealthtender

Work with Wealthtender to establish detailed profiles for each advisor on your team. Profiles should include professional credentials and experience, areas of specialization, and personal background that helps clients feel an emotional connection. Embedding a ‘get to know you’ video is also recommended to help prospects get a sense of an advisor’s personality.

The completeness of profiles matters. In the legal profession, attorneys whose profiles are fully filled out, including reviews, awards and detailed bios, receive more prospect inquiries. The same principle applies to financial advisors.

Step 3: Systematize Review Collection

The most successful firms make review collection a standard part of their client service process, not an afterthought. Consider:

  • Personal Touch: Have the review request come directly from the advisor, not from a generic firm email address
  • Make it Easy: Provide direct links to submit reviews on the advisor’s Wealthtender profile
  • Timing: Invite clients to write reviews a week after annual client meetings or to coincide with the firm’s anniversary

Step 4: Celebrate and Share Reviews

When advisors receive glowing reviews, celebrate them. Share highlights in team meetings, feature exceptional reviews in internal newsletters, and include review metrics in advisor performance evaluations. This creates a culture where client feedback is valued and where advisors feel recognized for the relationships they’ve cultivated.

On the external side, leverage these reviews in multiple ways:

  • Display reviews on individual advisor bio pages on your website
  • Showcase testimonials on your firm’s main reviews page
  • Reference specific feedback in advisor bios and marketing materials
  • Share (with client permission) success stories in thought leadership content
  • Promote reviews compliantly with Testimonial Marketing Studio

Step 5: Monitor, Analyze, and Improve

Establish a process to review your advisor’s reviews to identify patterns:

  • Which advisors are most effective at generating thoughtful reviews from their clients?
  • What common themes appear in the most compelling reviews?
  • Are there hints of service gaps discernable in reviews?
  • Which advisors might benefit from additional training or support?

Wealth management firms that treat reviews as continuous feedback loops, monitoring sentiment and using the insights to make improvements stand to outperform on loyalty and retention. Make this ongoing analysis part of quarterly or annual business reviews.

The Firms That Start Now Will Be the Hardest to Catch Later

Most wealth management firms haven’t yet begun collecting online reviews, which means early adopters have an enormous opportunity to differentiate themselves. In fact, fewer than 10% of advisors are actively collecting and publishing reviews according to Form ADV data.

This contrasts significantly with our consumer research that shows that 83% of people want to read online reviews about financial advisors before hiring one.

Think about that disparity: more than 8 in 10 prospective clients are looking for reviews, but 9 in 10 advisors don’t have them. If you’re among the first in your market to build a robust collection of individual advisor reviews, you’re not just slightly ahead, you’re setting your advisors and firm apart from 90% of competitors. And you’re not just winning on marketing; you’re providing the transparency and social proof that consumers today expect to find before making a hiring decision.

What the Highest-Performing Wealth Management Firms Do Differently With Reviews

The wealth management industry will continue to adapt and evolve as consumers increasingly look for online reviews to decide which advisors they can trust, and as AI search tools like ChatGPT use online reviews as a primary trust signal to determine which advisors will appear more frequently and prominently in responses to consumer queries.

This isn’t just about reviews, it’s about strategically thinking about how your firm approaches talent development, client relationships, and brand building.

Many of the most successful firms in the coming years will include those that:

Embrace advisors as brand ambassadors. Recognize that strong individual advisor brands strengthen your firm’s overall brand. Every glowing review of an individual advisor enhances the perception of your firm’s hiring standards, training programs, and client service culture.

Celebrate advisor excellence publicly. Make your advisors visible. Showcase their expertise. Let their personalities and values shine through. Prospective clients don’t want to work with a faceless firm, they want to work with Sarah, with Michael, with Jennifer.

Build systems that scale reputation. Don’t leave review collection to chance. Build it into your client service model. Make it easy. Make it consistent. Make it a point of pride for advisors to share their client feedback.

Use reviews as a strategic tool. Go beyond marketing to use client feedback for training, quality assurance, advisor development, and continuous improvement. The firms that extract the most value from reviews will be those that view them as business intelligence, not just social proof.

Act with urgency. Every month that passes without collecting reviews is a month of lost opportunity, both to capture client feedback while experiences are fresh and to build your competitive moat before the rest of the industry catches up.

Ready to Implement Your Advisor + Firm Testimonial Marketing Strategy?

The parallels between wealth management and other trust-based professions are undeniable. Doctors and lawyers have proven the model works. Consumer research confirms that this is exactly what prospective clients are seeking. Platforms like Wealthtender have solved the compliance challenges. And forward-thinking wealth management firms partnering with Wealthtender have demonstrated how it’s done.

With 96% of Americans researching advisors online after receiving referrals, and 83% specifically looking for reviews about individual advisors, the consumer has spoken. Individual advisor reviews aren’t a nice-to-have feature, they’re table stakes for wealth management firms that want to optimize their marketing activities for maximum conversion potential.

Start by scheduling a demo call or signing up for Wealthtender – it takes just 2 minutes. We’ll create your firm and advisor profiles on Wealthtender and provide the step-by-step guidance that hundreds of advisors and firms have used to collect thousands of glowing reviews. We provide compliant tools to amplify the impact of your client testimonials on your website, in social media posts, and beyond. Implement systems to make review collection a routine part of your service model. Celebrate the results and use the insights to continuously improve.

Your advisors have spent years building deep, trusting relationships with their clients. It’s time to let the world see the exceptional work they do, one authentic review at a time.


Want to see how individual advisors and leading wealth management firms are successfully using Wealthtender to grow their business? Visit Wealthtender.com/grow or schedule a demo to learn how you can start converting more prospects into clients with compliant testimonial marketing.

A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian

What this article covers

Most financial advisors know that online reviews help build trust with prospects and improve their visibility on Google. But the strategic implications run far deeper than marketing alone, from adding millions to your firm’s enterprise value in an M&A transaction to outflanking wirehouse competitors who are prohibited from collecting reviews, to getting found by the growing share of prospects who now start their advisor search on ChatGPT or Gemini. Here are seven high-impact benefits of online reviews for wealth management firms that most advisors haven’t fully considered and why building your review strategy now, before competitors catch on, is one of the most important moves you can make.

When the SEC Marketing Rule first took effect in November 2021, wealth management firms gained permission to solicit online reviews and publish client testimonials, a practice long established in other industries. While many advisors recognize the power of online reviews to attract new clients, the strategic advantages extend far beyond marketing. The following benefits represent lesser-known but potentially transformative impacts that online reviews can have on your wealth management practice.

Key Takeaways

1

Online reviews can add millions to your wealth management firm’s valuation.

A strong review portfolio provides documented, third-party evidence of goodwill — the intangible reputation value that drives premium acquisition multiples. For a firm generating $2M in EBITDA, the difference between a standard 8x multiple and a premium 12x multiple represents $8 million in additional enterprise value, and your reviews are among the most credible proof points acquirers evaluate.

2

90% of your competitors — including every wirehouse advisor — have zero client reviews.

As of May 2026, wirehouses still prohibit their advisors from collecting client reviews, and the 2025 Investment Adviser Industry Snapshot shows only 9.3% of all financial advisors use testimonials or reviews in their marketing. Independent advisors and RIAs who build a strong review presence gain a competitive advantage that no marketing budget can replicate — documented credibility from real clients that larger firms simply cannot offer.

3

Reviews on independent platforms now drive how AI tools like ChatGPT discover and recommend advisors.

25% of consumers already plan to use AI-powered tools to find a financial advisor, and AI answer engines weight reviews on independent platforms like Wealthtender significantly higher than testimonials hosted on an advisor’s own website. Firms that build structured, schema-optimized review profiles now are positioning themselves to capture a disproportionate share of the next generation of advisor searches.

1. Online Reviews Can Add Millions to Your Firm’s Valuation

The Benefit: Online reviews directly contribute to your firm’s intangible asset value, specifically “goodwill”, which can significantly increase your business valuation in the event of a sale or during succession planning. In today’s M&A market, this impact can mean the difference between a standard multiple and a premium valuation.

Why It Matters for Wealth Management Firms: RIAs can command valuations up to 20X EBITDA, particularly for larger firms backed by private equity, though wealth managers with less than $1 billion in assets typically get eight to 10 times EBITDA, and those with $1 billion to $3 billion will often be able to claim 12 to 14 times (Source: Financial Planning). However, size alone doesn’t determine valuation. Firms, even small ones, that have moved toward becoming “institutionalized” are often able to sell for higher prices, and it’s the difference between operating a thriving business versus running a lifestyle practice.

This is where online reviews become strategically valuable. Goodwill represents the value of a wealth management firm’s brand, reputation, customers, and potential earning capacity beyond its physical assets. For potential buyers, goodwill is one of the main factors that makes one wealth management firm substantially more valuable than another. These factors include a firm’s reputation, a solid customer or client base, brand identity and recognition, operational efficiencies, and a talented team of leaders and employees.

Your portfolio of online reviews serves as documented, third-party validation of your firm’s reputation and client satisfaction, and provide evidence of the intangible goodwill that commands premium valuations. When acquirers evaluate wealth management firms, they’re looking beyond AUM to assess the quality and sustainability of client relationships. A robust collection of positive reviews provides quantifiable validation of:

  • Client satisfaction and retention risk: Reviews demonstrate actual client sentiment, not just retention statistics
  • Brand strength and market position: Documented reputation that will transfer to the acquirer
  • Referral potential: Evidence that clients actively recommend the firm
  • Service quality consistency: Evidence that client experience isn’t dependent on a single advisor (reducing “key person” risk)

Acquirers who deemed a particular wealth management firm prospect as an “ideal” fit were willing to increase their offers by 25%. Online reviews help position your firm as an ideal acquisition candidate by demonstrating institutionalized qualities rather than personal practice dynamics.

The Valuation Mathematics: The difference between the acquisition price of the business and the fair market value of the tangible assets included in the sale is the goodwill value. For a wealth management firm generating $2 million in EBITDA:

  • At a standard 8x multiple (typical for smaller firms): $16 million valuation
  • At a premium 12x multiple (institutionalized firms): $24 million valuation
  • Difference: $8 million additional value

That $8 million difference often comes down to demonstrable goodwill, and online reviews provide some of the most credible evidence of reputation, client satisfaction, and transferable value that acquirers seek.

Supporting Evidence from Other Industries: A Berkeley study showed that a restaurant’s Yelp rating going up from 3.5 to 4 stars increases the likelihood of a restaurant being fully booked each evening by about 49%, translating to a 6-9% increase in revenues. While this is from the restaurant industry, the principle applies directly to professional services: documented reputation through reviews creates measurable economic value that drive increased business and higher conversion and retention rates, qualities that generate premium buyout offers from acquirers.

For wealth management firms navigating an increasingly competitive M&A landscape where valuations continue to nudge upwards but buyers have become more selective, a strong online review presence can be the differentiator that moves your firm from the standard valuation range to premium multiples, potentially worth millions in additional enterprise value.


2. Reviews Work as 24/7 Marketing Assets at Nearly Zero Ongoing Cost

The Benefit: Authentic client reviews serve as powerful, cost-effective marketing assets that build trust more effectively than traditional advertising, reducing your overall customer acquisition costs.

Why It Matters: For wealth management specifically, 83% of Americans said in a 2025 Wealthtender study, after receiving a referral to an advisor, their next step is to research the advisor’s reputation by looking for online reviews and awards, and 96% of people referred to a financial advisor will research them online before making contact. This means even referral-based prospects are evaluating your online review presence before reaching out, making reviews a critical component of client acquisition across all marketing efforts.

Traditional wealth management marketing (e.g., seminars, print advertising, cold calling) requires substantial investment with costs and commitments of time that can escalate quickly. Online reviews, in contrast, work continuously as trust-building assets at virtually no ongoing cost. Every positive review serves as an endorsement that prospects can discover organically.

Supporting Evidence Across Trust-Based Professions: The legal industry has longer experience with online reviews on industry-specific review platforms (e.g., Avvo, FindLaw), providing valuable insights for financial advisors and wealth management firm leaders. Avvo estimates that attorneys can 4.5x the number of leads and clients they’re able to attract by optimizing their profiles with reviews. Additionally, approximately 83% of people check lawyer reviews as their first step to finding an attorney.

The parallels for the wealth management industry is clear: Professionals in trust-based service industries who build strong review presences on industry-specific platforms like Wealthtender (for financial advisors) or Avvo (for attorneys) dramatically outperform competitors without reviews in client acquisition and conversion.

For firms spending thousands of dollars annually on marketing and business development efforts, a strong review presence can reduce client acquisition costs while simultaneously improving conversion rates, a benefit that offers a powerful one-two punch and compounds over time.


3. The Advantage Wirehouse Advisors Can’t Match: Verified Client Reviews

The Benefit: For independent advisors and large wealth management firms alike, online reviews create an opportunity to compete effectively against wirehouse firms whose advisors typically aren’t permitted by their home office to collect or publish client reviews, providing a powerful competitive advantage.

Why It Matters: The wealth management landscape is dominated by large wirehouses and national firms with massive marketing budgets and established brand recognition. For decades, independent advisors and RIAs competed at a significant disadvantage in terms of visibility and perceived credibility. Online reviews fundamentally change this dynamic.

As of May 2026, wirehouse home offices still prohibit their advisors from collecting individual reviews, in spite of the regulatory ability to do so. The 2025 Investment Adviser Industry Snapshot shows that just 9.3% of financial advisors use testimonials/reviews in their marketing activities. This means that 90% of your competitors, including virtually all advisors at wirehouse firms like Merrill Lynch, Morgan Stanley, UBS, and beyond, are invisible in the review-driven search and evaluation landscape.

Real-World Evidence: United Financial Planning Group (UFPG), an independent RIA with over $200M in AUM, provides a compelling case study. Mike Barrasso, UFPG’s Director of Business Development, recalls one prospect who was interviewing multiple firms and said, “It is down to you and two other firms. What makes you different?” Along with highlighting they were fee-only with CPAs on staff, Mike asked if either of those firms had as many positive reviews as UFPG. The prospect signed up as a wealth management client the very next day and moved over $1.5 million in assets.

This illustrates how independent advisors with strong review profiles can compete toe-to-toe with, and often win against, larger competitors who can’t yet leverage this powerful trust signal.

Reviews tell stories that traditional marketing copy can’t:

  • How you helped a client navigate a complex estate situation
  • Your responsiveness during market volatility
  • The education and guidance you provided to a first-time investor
  • Your approach to intergenerational wealth conversations
  • The peace of mind clients experience working with your team

Supporting Evidence: Customers equate volume with reliability. Three perfect reviews? That’s your friends. A dozen or more reviews with honest responses? That’s real. This authenticity creates competitive advantage by building credibility that marketing claims alone cannot achieve. In a marketplace where prospects are evaluating multiple firms, the independent advisor with several authentic reviews detailing specific client experiences will consistently win against wirehouses whose advisors have zero reviews, regardless of the household brand recognition or outsized marketing budget.

For independent advisors and wealth management firms, this represents perhaps the most democratizing shift in wealth management marketing in decades: the ability to demonstrate credibility and build trust at scale, leveling the playing field with much larger competitors.


4. How Reviews Improve Your Visibility in Google Search and AI Tools

The Benefit: Unlike Google Reviews, online reviews published on Wealthtender dramatically improve your firm’s visibility in both traditional search engines (SEO) and AI-powered answer engines like ChatGPT, Gemini, and Google AI Overviews, making it significantly more likely that prospects will discover you when researching advisors.

Why It Matters for Wealth Management Firms: The way people find financial advisors has fundamentally shifted. In the Wealthtender 2025 Study of Americans with $100K Household Income, 50% of all survey participants plan to use traditional search engines to find potential advisors, while 25% of people already plan to use ChatGPT, Gemini or other AI-powered tools to start their advisor search. This represents a major transformation in advisor discovery, and firms without an optimized online review strategy for their firm and advisors are increasingly invisible to these prospects.

Moreover, 96% of people referred to a financial advisor will research them online before making contact. This means even your referral-based prospects are evaluating your online presence before reaching out, and your review profile plays a central role in that evaluation.

The Search Engine Optimization (SEO) Advantage:

Reviews published on Wealthtender create powerful SEO benefits through several mechanisms:

  • Fresh, User-Generated Content: Search engines prioritize websites with regularly updated content. Each new review adds unique, authentic content that signals your firm is actively serving clients.
  • Long-Tail Keyword Optimization: Client reviews naturally incorporate the specific language prospects use when searching (e.g., “retirement planning for tech executives,” “financial advisor who explains things clearly,” “help with stock options”). This organic keyword usage improves your discoverability for niche searches.
  • Structured Data Markup: Wealthtender implements review schema markup that helps search engines understand and display your ratings directly in search results, increasing click-through rates.
  • Domain Authority Transfer: Reviews on high-authority platforms like Wealthtender create backlinks and content associations that boost your own website’s search rankings.

The Answer Engine Optimization (AEO) Revolution:

As AI tools become primary research methods, optimization for “answer engines” (AEO) is becoming as critical as SEO. Unlike a simple search entered into Google (e.g., “financial advisors near me”), consumers using ChatGPT are much more likely to create detailed prompts personalized to their unique needs.

AI tools like ChatGPT, Gemini, and Google AI Overviews evaluate advisors differently than traditional search engines. Wealthtender asked ChatGPT to compare how it evaluates advisor reputation versus how consumers do, and the results reveal critical insights:

FactorConsumer ImportanceChatGPT ImportanceKey Difference
Positive online reviews (independent sites)#3 priority (61%)Moderate-HighAI values independent reviews highly but adjusts for potential bias and sample sizes
Client testimonials on advisor site#6 priority (36%)Low-ModerateAI downweights these since they’re curated by the advisor
Source: Actionable Insights for Financial Advisors, 2025 Study Reveals How Americans Find & Hire Financial Advisors.

The implications are clear: Reviews on independent platforms like Wealthtender carry significantly more weight with AI tools than testimonials on an advisor’s own website. AI tools prioritize:

  1. Independent verification – Reviews from third-party platforms signal authenticity
  2. Structured data – Properly formatted review schema helps AI understand and cite your reputation
  3. Volume and recency – Consistent review flow demonstrates ongoing client satisfaction
  4. Detailed, specific content – Reviews mentioning specializations, services, and client outcomes help AI match you to relevant queries

Industry Recognition of Wealthtender’s AEO Leadership:

Wealthtender’s pioneering work in AEO for financial advisors has been recognized by industry leaders. Barron’s Advisor highlighted Wealthtender’s role in helping advisors optimize for AI-powered discovery, noting how the platform’s structured data approach positions advisors to be found by prospects using ChatGPT and other AI tools for advisor searches.

The Competitive Reality: The 2025 Investment Adviser Industry Snapshot shows that just 9.3% of financial advisors use testimonials/reviews in their marketing activities. This means 90% of your competitors are essentially invisible in the review-driven search landscape. Firms that build strong review presences on optimized platforms gain disproportionate visibility advantages.

Real-World Impact:

Without optimized reviews on a platform like Wealthtender that implements proper structured data markup, your advisors and firm are less likely to appear in AI-generated answers, even if you’re the perfect fit for that prospect.

The combination of traditional SEO benefits and emerging AEO advantages makes review collection and optimization one of the highest-ROI marketing activities available to wealth management firms. As AI tools increasingly mediate the advisor discovery process, firms with strong review presences on properly optimized platforms will capture disproportionate market share.


5. A Strong Review Profile Helps You Recruit Top Advisors, Too

The Benefit: A strong online review presence enables your firm to attract top financial advisors and support staff more effectively and at a lower recruitment cost than traditional hiring methods.

Why It Matters: 75 percent of candidates assess an employer’s brand before they even apply, and prospective candidates trust employee reviews 3x more than company statements. More specifically, a Glassdoor study found that 75% of active job seekers are likely to apply to a job if the employer actively manages its employer brand.

For wealth management firms competing to recruit the top financial advisors, planners, and experienced professionals to fill leadership positions, your online review presence serves as a powerful recruiting tool. While client reviews differ from employee reviews, the principle of online reputation management extends across both domains, candidates research both your client-facing reputation and your employer reputation.

Top talent in wealth management will seek out firms with strong reputations, satisfied clients, and compelling growth trajectories. Your online review portfolio signals all three. Advisors considering a move want assurance that they’re joining a firm where they can be proud of the client experience and where prospects will actually want to become clients.

Supporting Evidence: The average cost of hiring a new employee is $4,129 via public channels. Firms with strong online reputations can tap into job boards and referral networks more effectively, significantly reducing these costs while attracting higher-quality talent. When top advisors can see documented proof of client satisfaction, they’re more likely to reach out proactively rather than requiring more expensive recruitment efforts.


6. Reviews Give You a Free, Continuous Window Into What Clients Actually Value

The Benefit: Client reviews provide a continuous stream of unfiltered feedback for wealth management firms that can lead to operational improvements, identify strengths and gaps in your service offerings, and inspire new ways to deliver an exceptional client experience, all without expensive market research.

Why It Matters: Traditional market research for wealth management firms is expensive and time-consuming. Online reviews, however, provide real-time insights into areas of strength and opportunities for improvement.

Reviews often reveal:

  • Communication preferences and frequency expectations
  • Demand for specific services (tax planning, estate services, sustainable investing)
  • Technology and platform usability issues
  • Intergenerational wealth transfer needs

Supporting Evidence from Client Review Analysis: The Wealthtender 2025 Voice of the Client Study analyzed thousands of actual client reviews written about financial advisors to understand what matters most to clients. The findings reveal critical insights for service development: Nearly 90% of client reviews focus on relationship quality, planning advice, and emotional factors, while only 1 in 10 reviews centers on investments or portfolio management. This data contradicts where many firms focus their marketing message.

The study demonstrates that clients value and remember experiences like “feeling heard during difficult decisions,” “receiving clear explanations without jargon,” “getting quick responses during anxious moments,” and “having an advisor who understands our family’s unique situation.” These insights, extracted from authentic client voices rather than hypothetical survey responses, provide a roadmap for service enhancement that resonates with actual client priorities. Firms that analyze their review patterns can identify which aspects of their service delivery create the most meaningful client experiences, then systematically strengthen those elements while addressing any gaps that emerge in the feedback.

A bar chart ranking review themes by number of mentions shows "Personalized Retirement and Financial Planning" as most common, followed by "Long-Term Relationships and Loyalty." Text below highlights clients' focus on personal experience.
Source: 2025 Wealthtender Voice of the Client Study

7. Your Review History Becomes a Credibility Asset When Markets Get Volatile

The Benefit: A strong foundation of positive reviews provides credibility buffers during market downturns and demonstrates your firm’s long-term value proposition when client anxiety is highest.

Why It Matters: Market volatility inevitably tests client relationships. During periods of significant market stress, whether 2008’s financial crisis, 2020’s pandemic panic, or future downturns, prospective clients become more risk-averse and existing clients more anxious. In these moments, your historical review portfolio becomes a powerful asset.

Especially when markets are turbulent, prospects researching advisors are seeking evidence of steady guidance, clear communication, and emotional support during previous challenging periods. Reviews that mention how you helped clients stay disciplined during past market corrections, provided reassuring perspective during volatility, or communicated proactively during crises become especially valuable.

The Long-Term Credibility Advantage:

A firm with dozens of positive reviews accumulated over several years can weather market challenges better than a firm with minimal or no reviews. The depth and longevity of your review portfolio provides:

  • Historical perspective: Reviews from 2-3 years ago demonstrate you’ve guided clients through various market conditions
  • Consistency evidence: Steady positive reviews over time show sustained quality, not just a short-term effort
  • Crisis management proof: Reviews mentioning challenging periods demonstrate your value during difficult times
  • Emotional intelligence validation: Comments about your communication, empathy, and guidance during uncertainty signal your soft skills

When the next market downturn occurs or regulatory changes lead to client anxiety, firms with strong review foundations can point to years of documented client satisfaction as evidence of their long-term value and stability. This historical proof becomes especially persuasive when prospects are evaluating multiple advisors and seeking confidence that their chosen advisor will be a steady hand through inevitable future challenges.


How to Build a Compliant Review Strategy for Your Firm

Wealth management firms ready to get started with online reviews and a compliant testimonial marketing strategy should establish systematic processes for:

  1. Compliance-first review collection that adheres to SEC Marketing Rule requirements, including proper disclosures and appropriate oversight
  2. Authentic client engagement requesting reviews at natural touchpoints in the client journey (annual reviews, financial plan completion, goal achievement milestones)
  3. Strategic promotion of reviews across online and offline marketing activities, starting with your Wealthtender profile(s), and including your website, social media accounts, as well as prospect materials, flyers and other printed materials.
  4. Ongoing monitoring for reputation management, service improvement insights, and competitive intelligence
  5. Documentation and recordkeeping to satisfy regulatory requirements for testimonials and endorsements

The Firms Building Review Strategies Now Will Be Hardest to Catch Later

The wealth management firms that proactively build their review portfolios now will enjoy compounding advantages in business valuation, client acquisition, competitive positioning, search visibility, talent acquisition, and strategic intelligence for years to come.

While compliance considerations require thoughtful implementation, the strategic benefits, particularly the potential for millions in additional enterprise value through enhanced goodwill, the ability for independent advisors to compete effectively against large national firms, and dramatically improved discoverability in both traditional and AI-powered search, make online reviews one of the most impactful yet underutilized assets available to modern wealth management firms.

In an industry built on trust, there is no more powerful trust signal than the authentic voices of satisfied clients. The question isn’t whether to build a review strategy, it’s how quickly you can begin capturing and leveraging this valuable asset for your firm’s long-term success.

Want to see how individual advisors and leading wealth management firms are successfully using Wealthtender to grow their business? Visit Wealthtender.com/grow or schedule a demo to learn how you can start converting more prospects into clients with compliant testimonial marketing.

Certified Advisor Reviews - Wealthtender

Wealthtender offers the industry’s first financial advisor review platform designed for regulatory compliance.

A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian

Do you work at Verizon?

Get expert insights from financial advisors who specialize in helping Verizon employees and executives make the most of their compensation package and benefits.

Looking for a financial advisor who specializes in working with Verizon employees? You’re in the right place. Below, you’ll find advisors who understand Verizon benefits and compensation — along with their answers to common financial questions from Verizon employees and executives.

Whether you recently joined Verizon or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and Verizon benefits can have a lasting impact on your financial future. For example:

✅ Do you know the right moves to get the greatest value from the Verizon benefits available to you?

✅ If you’re thinking about leaving Verizon for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?

Key Takeaways

1

HSAs Are Verizon Employees’ Most Underappreciated Retirement Tool

Many employees treat the health savings account as a short-term spending account, but its triple tax advantage — deductible contributions, tax-deferred growth, and tax-free withdrawals for qualified medical expenses — can make it a valuable supplemental retirement asset as health care costs rise.

2

Verizon Paychecks, Savings, and Stock Can All Depend on One Company

Compensation, retirement savings, and equity tied to the same employer create concentration risk that grows more important as retirement nears. The advisor below helps employees diversify and manage that exposure deliberately.

3

Build Your Verizon Retirement Income Plan Well Before Your Last Day

Pension elections, Social Security timing, and health coverage before Medicare all need to be coordinated into a sustainable income strategy. Stress-testing the plan under different market conditions helps employees retire with confidence.

Why Verizon Employees Work with a Specialist Financial Advisor

Throughout the year, Verizon provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) with a Roth option and, for many longer-tenured employees, a pension — along with, for eligible leaders, deferred compensation and restricted stock units. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with Verizon who specialize in helping Verizon employees make the most of their income and benefits.

Verizon is headquartered in New York City, with its operations headquarters on a large campus in Basking Ridge, New Jersey, and other major employee hubs including Irving, Texas, and Alpharetta, Georgia. Thousands more work in Verizon stores and network operations across the country. Whether you work at one of those sites, another office, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.

Sensitive topics — like the steps you should take before quitting your job at Verizon to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.

Should You Hire a Verizon Specialist or a Local Financial Advisor?

You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Verizon employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with Verizon employees is the better fit for your unique needs.

💡 In the Q&A below, you’ll gain insights from financial advisors who work with Verizon employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.

🙋‍♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.

Q&A: Financial Planning Tips for Verizon Employees & Executives

In this section, you’ll learn how you can make the most of your Verizon employee benefits and gain valuable tips from financial advisors who specialize in working with Verizon employees and executives.

Financial Advisor Q&A  ·  Verizon Employees

Brett Hina, CRPS®, CIMA®, CPWA®, Financial Advisor for Verizon Employees at Cornerstone Private Wealth

Brett Hina, CRPS®, CIMA®, CPWA®

Cornerstone Private Wealth  ·  Northfield, NJ  ·  Serves clients nationwide

Helping Individuals, Families and Business Owners Build and Protect Their Legacy
Book Intro Call

Brett Hina is a financial advisor based in Northfield, New Jersey who specializes in offering financial planning services to Verizon employees. Brett helps his clients get the most value from their Verizon benefits and compensation package so they can enjoy life and feel confident about their financial future.

QAs a financial advisor with experience helping Verizon employees save for their retirement, how do you help them make the most of their employee benefits?

Many Verizon employees do an excellent job contributing to their retirement plans, but often the greatest value comes from understanding how all of the benefits work together within a broader financial plan. We help clients evaluate how much they should contribute to their 401(k), whether Roth contributions make sense, how to manage company stock exposure, and how to coordinate retirement savings with taxable investment accounts, pensions, Social Security, and healthcare planning. One area we frequently focus on is helping employees avoid becoming overly concentrated in Verizon stock or company-related investments. Many employees build substantial wealth during their careers, but diversification and risk management become increasingly important as retirement approaches. Our goal is to help Verizon employees turn strong employee benefits into a coordinated long-term strategy that supports both financial security and overall well-being.

QWhen you first speak with a Verizon employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?

The first conversation is usually less about investments and more about understanding the person behind the financial picture. I like to ask questions such as:

  • What are your biggest financial concerns right now?
  • What does an ideal retirement look like to you?
  • Are you confident you are maximizing your company benefits?
  • How do you feel about your current level of financial organization and planning?
  • What major life transitions do you anticipate over the next five to ten years?

We also discuss family dynamics, work-life balance, health considerations, and personal goals outside of money. Financial planning is ultimately about helping people use their resources to build the kind of life they want to live.

QIs there a particular benefit available to Verizon employees you feel isn’t as well utilized or understood by employees as it should be?

Health Savings Accounts (HSAs) are often underappreciated. Many employees view them simply as a short-term healthcare spending account, but HSAs can be one of the most tax-efficient planning tools available. When used strategically, HSAs offer triple tax advantages: tax-deductible contributions, tax-deferred growth, and tax-free withdrawals for qualified healthcare expenses. Over time, they can become a valuable supplemental retirement asset, particularly as healthcare costs rise later in life. We also find that some employees underestimate the importance of reviewing beneficiary designations, insurance elections, and overall retirement income planning well before retirement approaches.

QBeyond Verizon employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?

Absolutely. In many cases, the most overlooked planning opportunities are outside of the retirement plan itself. We frequently discuss employee stock purchase plans, executive compensation packages, health savings accounts, insurance benefits, college planning, and long-term care considerations. For employees with families, we also discuss education funding strategies and balancing competing financial priorities such as saving for retirement while helping children with college expenses. Financial planning today extends far beyond investment management. It involves coordinating tax planning, estate planning, insurance, healthcare, and long-term lifestyle goals into one cohesive strategy.

QFor Verizon employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?

Before leaving Verizon, employees should carefully review all retirement plans, stock options, deferred compensation arrangements, healthcare coverage, unused benefits, and insurance elections. It is important to understand what benefits may continue, what deadlines apply, and whether there are opportunities that could be lost by leaving too quickly. We also encourage employees to avoid making rushed decisions regarding old retirement accounts. In many cases, rolling over a 401(k) into an IRA may provide additional flexibility and planning opportunities, but each situation is unique. Most importantly, career transitions are a good time to revisit broader financial goals and ensure that the next step aligns not only with compensation, but also with long-term lifestyle and family priorities.

QFor Verizon employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?

The transition into retirement is one of the biggest financial and emotional shifts people experience. For many Verizon employees, the challenge is not simply accumulating assets, but creating a sustainable income strategy. We help clients identify where retirement income will come from, including retirement accounts, pensions, Social Security, taxable investments, and cash reserves. We also stress-test retirement plans under different market and economic conditions to help clients feel more confident about the future. Beyond the numbers, we encourage clients to think carefully about how they want to spend their time, maintain social connections, stay healthy, and continue finding purpose after leaving the workforce. The most successful retirements typically combine strong financial preparation with intentional planning around wellness and lifestyle.

QFor Verizon employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?

Many successful professionals do an excellent job managing their finances independently, especially during the accumulation phase of their careers. However, as life becomes more financially complex, there can be significant value in having an experienced advisor serve as both a strategist and a sounding board. Areas such as retirement income planning, tax strategy, healthcare planning, estate planning, and risk management often become more important later in life. I usually encourage people to ask themselves whether they feel fully organized, whether they have a clear long-term plan, and whether they are confident they are making the most informed decisions possible. A good advisor should provide far more than investment management. They should help reduce stress, improve decision-making, and provide perspective during both strong markets and difficult periods.

QWhat are some of the unique financial planning challenges you commonly see among your clients who are Verizon employees and how do you help them overcome these obstacles?

One common challenge we see is concentrated risk. Employees may have compensation, retirement savings, and stock exposure tied to the same company, which can create vulnerability if not managed carefully. We also frequently help clients navigate retirement timing decisions, pension elections, healthcare planning before Medicare eligibility, and Social Security optimization strategies. Another challenge is that many successful professionals become so busy during their careers that financial planning becomes reactive instead of proactive. We help simplify financial decisions and create a more structured long-term strategy. Our focus is not only on helping clients grow wealth, but also on helping them feel more organized, confident, and prepared for future transitions.

QWhat questions do you recommend Verizon employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?

I would encourage employees to ask:

  • Are you acting as a fiduciary?
  • Do you have experience working with Verizon employees or corporate professionals?
  • How are you compensated?
  • What services beyond investment management do you provide?
  • How do you approach tax planning and retirement income planning?
  • What is your communication style and planning process?

It is also important to evaluate whether the advisor listens carefully and explains complex concepts clearly. The relationship should feel collaborative and personalized rather than transactional. Ultimately, clients should look for someone they trust and feel comfortable working with during both good times and periods of uncertainty.

QIs there anything that comes up frequently in your initial meeting with Verizon employees that surprises you?

One thing that frequently surprises me is how many highly successful professionals feel uncertain about whether they are truly “on track” financially, despite years of disciplined saving. Many employees have accumulated substantial retirement assets, but still lack a coordinated financial plan that ties everything together. Others may not realize how much risk they are taking through concentrated stock exposure or outdated estate planning documents. It is also common for people to underestimate the emotional side of retirement. Financial independence is important, but retirement planning also involves identity, lifestyle, relationships, and purpose.

QFor highly compensated Verizon employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?

Yes. Highly compensated Verizon employees and executives often have access to additional planning opportunities and complexities that require advanced coordination. Deferred compensation plans, executive compensation packages, restricted stock, concentrated equity positions, and tax management strategies can all play an important role in long-term financial outcomes. For these clients, tax planning becomes especially critical. We frequently discuss Roth conversion strategies, charitable giving strategies, tax-efficient investing, and estate planning considerations. We also encourage executives to think carefully about long-term wellness and work-life balance. Many high achievers spend decades focused on career growth and wealth accumulation, but eventually reach a stage where the conversation shifts toward flexibility, family, and quality of life.

QIs there a particularly memorable experience or a moment you recall with a client who worked at Verizon when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?

I recall working with a Verizon employee who had done an exceptional job saving throughout a long career. On paper, they appeared financially prepared for retirement, but they were still anxious about whether they could comfortably step away from work. After reviewing their retirement accounts, pension options, Social Security timing, healthcare planning, and investment strategy, it became clear they were actually in a much stronger position than they realized. What stood out to me was how important confidence and clarity can be in the planning process. Sometimes the biggest value we provide is helping clients organize complex decisions and feel more comfortable moving into the next chapter of life.

QWhat advice would you give younger Verizon employees who are early in their careers?

Start saving early, even if the amounts initially seem small. Time and consistency are incredibly powerful when it comes to long-term wealth building. I also encourage younger employees to focus on financial habits rather than trying to perfectly predict markets. Building an emergency reserve, avoiding excessive debt, maximizing retirement plan matches, and steadily increasing savings rates over time can have a tremendous long-term impact. Finally, remember that financial success should support overall life satisfaction. Career advancement and income are important, but maintaining health, relationships, and personal balance matter as well.

Considering a financial advisor who specializes in working with Verizon Employees?

Are you a financial advisor who specializes in working with employees at Verizon or another large company?

✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at Verizon or another large company. (Subject to availability and terms.)
✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender

Ask a Financial Advisor Your Verizon Benefits & Career Questions


Are you ready to enjoy life more with less money stress?

Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.

  • This field is for validation purposes and should be left unchanged.

About the Author

Brian Thorp, Founder and CEO of Wealthtender and Editor-in-Chief

Brian Thorp

Founder & CEO, Wealthtender  ·  Editor-in-Chief

Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.

A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.

Brian and his wife live in Austin, Texas.

Read Brian’s full bio →   ·   Connect on LinkedIn →

Whether you have lived in Palm Desert for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.

It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Palm Desert featured on Wealthtender you may want to add to your shortlist.

As you prepare to interview financial advisors in Palm Desert who may be right for you, get to know local financial advisors featured on Wealthtender.

📍 Map: Financial Advisors with their Primary Office Location in Palm Desert

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Palm Desert.

📍Double-click or pinch pins to view more.

Showing

The Benefits of Hiring a Financial Advisor in Palm Desert

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Palm Desert, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Do you work for one of the largest employers in Palm Desert? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Quick Tips For Hiring an Palm Desert Financial Advisor

Before hiring a financial advisor in Palm Desert, here are a few quick tips to help you find the best advisor for you.

1. Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2. Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3. Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4. Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.


Frequently Asked Questions & Additional Resources

How do I know if I’m ready to hire a financial advisor?

You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.

But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.

Before I hire a new financial advisor, should I fire my current advisor?

You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.

Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?

After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. 

Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.

I’m a local financial advisor interested in being featured in this guide. How do I get started?

Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.

How Much Does a Financial Advisor Cost?

➡️ How Much Does a Financial Advisor Cost? Read the Article

About the Author
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian

Whether you have lived in Bangor for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.

It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Bangor featured on Wealthtender you may want to add to your shortlist.

As you prepare to interview financial advisors in Bangor who may be right for you, get to know local financial advisors featured on Wealthtender.

📍 Map: Financial Advisors with their Primary Office Location in Bangor

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Bangor.

📍Double-click or pinch pins to view more.

Showing

The Benefits of Hiring a Financial Advisor in Bangor

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in Bangor, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Do you work for one of the largest employers in Bangor? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Quick Tips For Hiring an Bangor Financial Advisor

Before hiring a financial advisor in Bangor, here are a few quick tips to help you find the best advisor for you.

1. Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2. Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3. Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4. Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.


Frequently Asked Questions & Additional Resources

How do I know if I’m ready to hire a financial advisor?

You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.

But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.

Before I hire a new financial advisor, should I fire my current advisor?

You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.

Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?

After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. 

Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.

I’m a local financial advisor interested in being featured in this guide. How do I get started?

Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.

How Much Does a Financial Advisor Cost?

➡️ How Much Does a Financial Advisor Cost? Read the Article

About the Author
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian

A man with a trimmed beard and shaved head is wearing a gray suit, white shirt, and patterned tie. He is smiling slightly and standing in front of a bright window with a blurred background.
Aaron Foresman, CFA, Portfolio Manager for the Managed Income Strategy at Crawford Investments | Image Credit: Institute for Innovation Development

[A number of investment strategies were born specifically from a desire to solve personal, real-world problems or unmet investor needs. The Crawford Managed Income Strategy is a great example of an investment solution that was engineered for investors that were having a hard time generating income from traditional balanced stock/bond portfolios.

To better explore this investment solution, we were introduced to Aaron Foresman, CFA, Portfolio Manager for the Managed Income Strategy at Crawford Investments. We asked him questions to understand how this strategy attempts to strike a favorable balance between current income and risk mitigation across equity market risk, interest rate risk, energy risk, and credit risk.]

Hortz: Can you describe your investment philosophy and what motivated you to develop this multi-asset income strategy?

Foresman: I was actually prompted by my father around 2012, who asked me a question about how to generate more income in retirement. At that time, investors were having a hard time generating income from traditional stock and bond portfolios as yields declined materially. I began thinking through how he might supplement a traditional balanced account with other asset categories to generate a high level of income while providing diversification. The Managed Income strategy emerged as an attractive, objectives-based solution to a legitimate, real-world problem.

In 2014, the same year I joined Crawford, I began building the portfolio out in my personal IRA account. I recognized that I could produce an alternative that generated close to 5%+ income in a world where high-quality bonds were yielding just a fraction of that. While it would require taking on more risk, I knew by clearly identifying the four major risk categories – interest rate risk, energy price risk, stock market risk, and credit risk – that I could offset individual, security-specific risks against one another. In sum, through a process of disaggregation and analysis, the strategy seeks to mitigate risk through diversification and balancing, hence, offsetting as much single holding risk against other holdings as possible.

Today, the philosophy remains consistent. We continually search for what we believe to be the highest quality securities available in the higher income subsets of the capital markets, while managing the portfolio to strike a favorable balance between current income and risk mitigation.

Hortz: What role does a “quality” investment criteria play in your investment decisions?

Foresman: Quality plays a central role in all of our investment decisions at Crawford. We search for the highest-quality investments available in the higher yielding subsets of the capital markets that we cover.

More specifically, we believe that investors seeking income in a lower-yielding environment often reach for yield in lower-quality, higher-volatility securities, which we view as a poor risk-and-reward tradeoff. Instead, we focus on high-quality securities with sustainable income, strong fundamentals, and attractive valuations to help reduce volatility and improve long-term outcomes.

Hortz: What is your investment process across your equity, preferred equity, and corporate bond portions of your portfolio, and how does your investment team structure support that process?

Foresman: Our process is grounded in deep fundamental research and supported by distinct but highly collaborative equity and fixed-income teams.

Within dividend-paying equities, energy infrastructure, and real estate, our equity team conducts bottom-up analysis focused on companies with low earnings variability, strong balance sheets, differentiated business models, and proven management teams.

For preferred securities and corporate bonds, we leverage close coordination between our equity and fixed income teams. This allows us to selectively invest in securities where we already have a strong understanding of the underlying business, enhancing our ability to assess risk and identify relative value.

Importantly, our structure includes a dedicated equity research team alongside a separate fixed-income team, creating consistent cross-pollination of ideas. We believe this integrated approach is a meaningful advantage, particularly in higher-yielding areas of the market where credit and equity perspectives often intersect.

Hortz: How do you exploit inefficiencies across your key investment sectors in your portfolio?

Foresman: Higher-income segments of the capital markets are often less efficient, as they are dominated by income-focused investors who may underappreciate underlying risks. We seek to capitalize on these inefficiencies through disciplined security selection and deep fundamental research.

In dividend-paying equities, we leverage our longstanding expertise in equity income investing to identify high-quality companies that can deliver both income and total return, rather than simply screening for yield.

In energy infrastructure, we favor C-corporation companies over MLPs, focusing on investment-grade businesses with mission-critical assets, strong free cash flow, and durable balance sheets.

Within REITs, we benefit from public market liquidity while investing across a diversified mix of property types, balancing more offensive sectors such as data centers and industrials with more defensive areas like medical offices and triple-net lease real estate.

In preferred securities, we believe our active approach provides a significant advantage over passive vehicles. The market is fragmented and heavily concentrated in financial issuers, with many securities being small, illiquid, and often mispriced. Our ability to manage call risk, focus on qualified issues, and selectively invest in fixed-to-floating structures allows us to identify more attractive opportunities.

In corporate bonds, the size and complexity of the market create opportunities for selective investing. Our collaboration between equity and fixed income teams enables us to “cherry pick” bonds where we have high conviction in the underlying issuer, improving our ability to capture attractive risk-adjusted returns while managing interest rate sensitivity.

Hortz: Can you walk us through the components of your risk management process and how that drives your portfolio construction to ‘offset portfolio risk against itself’?

Foresman: The variety of income-producing asset classes utilized by the strategy allows its investors the opportunity to achieve greater diversification and, in turn, greater risk mitigation. We have identified four major risk categories, including interest rate risk, energy price risk, stock market risk, and credit risk.

What we have found is that, in this portfolio, we can actually offset individual, security-specific risks against one another. Through a process of disaggregation and analysis of the various risks associated with specific holdings in our portfolio, we mitigate risk through diversification and balancing. This is supported by a proprietary, internally developed risk management methodology that carefully considers each position’s contribution to the portfolio’s overall risk characteristics.

Essentially, we attempt to offset as much of the portfolio risk against itself as possible. For instance, we may control for interest rate sensitivity by offsetting utilities with regional banks; utilities are traditionally interest rate sensitive, while regional banks tend to be interest rate sensitive in the other way. What you end up with is two sets of securities that provide handsome yield and possess opposite behavior patterns with regard to the factor of interest rates.

Hortz: As a multi-asset income strategy, why do you not include private credit and loans in your portfolios and research team?

Foresman: At a high level, we are focused on public, liquid markets where we believe we have a research and execution advantage. Many higher-yielding areas require investors to accept additional risks alongside the yield, often in the form of illiquidity, complexity, or elevated risk. Our approach prioritizes quality, transparency, and risk control, and we believe we can achieve attractive income without moving into less liquid or more complex areas like private credit.

We use the NASDAQ U.S. Multi-Asset Diversified Income Index as our benchmark because it is designed to provide exposure to multiple asset segments that collectively generate a consistent and high level of income. We believe it is highly representative of our opportunity set and reinforces the strategy’s positioning as a true multi-asset income solution.

Hortz: How have current macro events, like the Gulf war and a shifting interest rate environment, affected your different income sectors and how are you managing those risks?

Foresman: We operate with the view that the future is always uncertain, and as such, the range of potential outcomes for any particular investment is wide. Rather than making macro bets, we focus on security selection, diversification across asset classes, and balancing the four key risk categories. This allows us to remain well-positioned across environments, including periods of volatility, shifting rates, and geopolitical uncertainty.

Hortz: Can you share your thoughts on how to apply this investment strategy to a client’s portfolio? What type of clients or investment scenarios did you design this strategy for?

Foresman: The strategy was designed for investors seeking current income with risk management, particularly those dissatisfied with traditional balanced portfolios. It can serve as a standalone income solution or complement a traditional stock and bond allocation, while providing meaningful diversification and limited overlap with traditional approaches. Ultimately, it is best suited for investors who need income, capital preservation, and reduced volatility, particularly in retirement or income-focused mandates.

This article was originally published here and is republished on Wealthtender with permission.

About the Author

A middle-aged man, Bill Hortz, with short dark hair wearing a dark pinstripe suit, white dress shirt, and a maroon tie, posing against a plain gray backdrop. He has a slight smile and is looking directly at the camera.

Bill Hortz

Founder Institute for Innovation Development

Bill Hortz is an independent business consultant and Founder/Dean of the Institute for Innovation Development- a financial services business innovation platform and network. With over 30 years of experience in the financial services industry including expertise in sales/marketing/branding of asset management firms, as well as, creatively restructuring and developing internal/external sales and strategic account departments for 5 major financial firms, including OppenheimerFunds, Neuberger&Berman and Templeton Funds Distributors. His wide ranging experiences have led Bill to a strong belief, passion and advocation for strategic thinking, innovation creation and strategic account management as the nexus of business skills needed to address a business environment challenged by an accelerating rate of change.

Whether you have lived in West New York for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.

It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in West New York featured on Wealthtender you may want to add to your shortlist.

As you prepare to interview financial advisors in West New York who may be right for you, get to know local financial advisors featured on Wealthtender.

📍 Map: Financial Advisors with their Primary Office Location in West New York

Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in West New York.

📍Double-click or pinch pins to view more.

Showing

📍 Additional Advisors Who Serve Clients in West New York

In addition to the advisors featured above, these advisors can also meet with you in person in West New York.

The Benefits of Hiring a Financial Advisor in West New York

Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.

As a resident living in West New York, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.

Do you work for one of the largest employers in West New York? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.

When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.

Quick Tips For Hiring an West New York Financial Advisor

Before hiring a financial advisor in West New York, here are a few quick tips to help you find the best advisor for you.

1. Decide Which Services You Need

Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.

Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:

  • Budgeting and money management
  • Debt management
  • Insurance planning
  • Retirement planning
  • Other investment planning
  • Inheritance planning
  • Estate planning
  • Tax planning

As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.

Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.

2. Consider Your Budget and Payment Preferences

Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.

If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.

3. Interview Multiple Financial Advisors

Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:

  • What services do you provide?
  • What are all the ways you get paid? (fee transparency)
  • What is your investment strategy?
  • How do you measure investment performance?
  • How do we communicate about my plan?

Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.

4. Review Financial Advisor Credentials

Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website. 

You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.

As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.

For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.


Frequently Asked Questions & Additional Resources

How do I know if I’m ready to hire a financial advisor?

You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.

But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.

Before I hire a new financial advisor, should I fire my current advisor?

You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.

Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?

After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. 

Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.

I’m a local financial advisor interested in being featured in this guide. How do I get started?

Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.

How Much Does a Financial Advisor Cost?

➡️ How Much Does a Financial Advisor Cost? Read the Article

About the Author
A headshot of Brian Thorp, the founder and CEO of Wealthtender

About the Author

Brian Thorp

Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian