Discover financial advisors trusted by residents of Northfield, New Jersey in the only local directory featuring 5-Star Certified Advisor Review™ recipients and Wealthtender Voice of the Client Award™ winners—recognition earned for exceptional client feedback. Compare fiduciary, fee-only advisors, CFP® professionals, and specialists to find the right fit for your unique financial needs.
Whether you have lived in Northfield for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.
It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Northfield featured on Wealthtender you may want to add to your shortlist.
Featured Northfield Financial Advisors
As you prepare to interview financial advisors in Northfield who may be right for you, get to know local financial advisors featured on Wealthtender.
📍 Map: Financial Advisors with their Primary Office Location in Northfield
Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Northfield.
The Benefits of Hiring a Financial Advisor in Northfield
Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.
As a resident living in Northfield, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.
Do you work for one of the largest employers in Northfield? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.
When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.
Quick Tips For Hiring an Northfield Financial Advisor
Before hiring a financial advisor in Northfield, here are a few quick tips to help you find the best advisor for you.
1. Decide Which Services You Need
Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.
Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:
Budgeting and money management
Debt management
Insurance planning
Retirement planning
Other investment planning
Inheritance planning
Estate planning
Tax planning
As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.
Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.
2. Consider Your Budget and Payment Preferences
Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.
If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.
3. Interview Multiple Financial Advisors
Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:
What services do you provide?
What are all the ways you get paid? (fee transparency)
What is your investment strategy?
How do you measure investment performance?
How do we communicate about my plan?
Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.
4. Review Financial Advisor Credentials
Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website.
You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.
As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.
For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.
Frequently Asked Questions & Additional Resources
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.
But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings.
Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a local financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.
Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian
Are you a New Mexico PERA member?
Get expert insights from financial advisors who specialize in helping New Mexico PERA members make the most of their compensation package and benefits.
Looking for a financial advisor who specializes in working with New Mexico PERA members? You’re in the right place. Below, you’ll find advisors who understand New Mexico PERA benefits and compensation — along with their answers to common financial questions from New Mexico PERA members.
Whether you’re early in your public service career or approaching retirement, making smart decisions about your income and New Mexico PERA benefits can have a lasting impact on your financial future. For example:
✅ Do you know the right moves to get the greatest value from the New Mexico PERA benefits available to you?
✅ If you’re thinking about leaving public service for another job or planning to retire in a few years, are you taking the right steps today to receive all the retirement benefits you’ve earned?
Key Takeaways
1
SmartSave, New Mexico’s 457(b), Is Underused by Many PERA Members
Members can mix pre-tax and Roth contributions, use a special pre-retirement catch-up of up to double the regular limit, and take distributions after separation without the 10% early withdrawal penalty.
2
Think Twice Before Taking a PERA Refund When You Leave
Leaving contributions on deposit preserves service credit if you return to PERA-covered work, while a refund forfeits the future pension and can be costly to buy back.
3
Survivor Elections and Service Credit Purchases Are Decisions You Make Once
These choices, along with the order in which you draw down accounts, have lasting consequences and deserve careful planning within about ten years of retirement.
Why New Mexico PERA Members Work with a Specialist Financial Advisor
New Mexico’s Public Employees Retirement Association provides members with a defined benefit pension, and members can also save in SmartSave, the state’s 457(b) deferred compensation plan, with pre-tax and Roth options — along with retiree health care through the New Mexico Retiree Health Care Authority (NMRHCA). While PERA offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with PERA who specialize in helping members make the most of their retirement benefits.
New Mexico PERA is headquartered in Santa Fe and serves employees and retirees of the state, counties, cities, and other public employers across New Mexico, including police officers, firefighters, and correctional officers. Wherever you work in the state, you may have questions about your retirement benefits better suited for a financial professional who can offer unbiased advice and guidance.
Sensitive topics — like the steps you should take before leaving a PERA-covered job, choosing among pension payout and survivor options, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.
Should You Hire a New Mexico PERA Specialist or a Local Financial Advisor?
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving New Mexico PERA members. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with New Mexico PERA members is the better fit for your unique needs.
💡 In the Q&A below, you’ll gain insights from financial advisors who work with New Mexico PERA members to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.
🙋♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.
Q&A: Financial Planning Tips for New Mexico PERA Members
In this section, you’ll learn how you can make the most of your New Mexico PERA benefits and gain valuable tips from financial advisors who specialize in working with New Mexico PERA members.
Financial Advisor Q&A · New Mexico PERA Members
Peter Bo Rappmund, EA, CFP®
Counterpoint · Santa Fe, NM · Serves clients nationwide
Clarity and alignment | Fiduciary financial advisor
Peter Bo Rappmund is a financial advisor based in Santa Fe, New Mexico who specializes in offering financial planning services to New Mexico PERA members. Peter helps his clients get the most value from their PERA benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping New Mexico PERA members save for their retirement, how do you help them make the most of their benefits?
When I meet with a New Mexico PERA member, my goal is to help them see their benefits as part of a larger system instead of a mishmash of disconnected pieces. The cornerstone is the PERA defined benefit pension, a 401(a), which is a huge asset most private-sector employees don’t have access to.
I like to get clear on the specifics. We consider the coverage plan, tier, projected pension benefit, and then compare that to the income a client will need in retirement. The gap is usually where SmartSave, New Mexico’s 457(b) deferred compensation plan, comes in. Many members underutilize it, either assuming the pension alone will be sufficient or finding the plan intimidating to navigate. I help think through how much to contribute, the right mix of pre-tax and after-tax (Roth), and how those choices can coordinate with their broader tax picture.
From there we round out the plan. This entails potential service credit purchases that can boost a pension benefit when timed correctly, NMRHCA retiree health care, survivor election decisions (beneficiaries), and how Social Security fits in or, for some PERA roles, how the absence of it shapes the income strategy. We’re not necessarily maximizing a number on a benefits estimate but rather trying to build a safe and sound plan that lets you retire on your terms, with confidence and on the sustainability of your income.
QWhen you first speak with a PERA member, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
Any PERA member’s situation will be unique enough that a generic intake doesn’t serve them well, so my initial conversation is about gathering the inputs that drive everything else. The first questions are almost always: when were you first hired into PERA-covered employment, and which coverage plan are you in? Or even simpler, do you know how to login to RIO (the online PERA system)? From there we can quickly determine your tier, your contribution rate, your benefit multiplier, and your earliest retirement eligibility. Without those, the advice I’d give would be unreliable.
I also want to know what retirement looks like to them, what they are imagining, and roughly when they want to actually retire, best-case scenario. I look into whether they’ve ever taken a refund, or served in the military (each of which may open the door to a service credit purchase); and how they’re using SmartSave, including the mix of pre-tax and Roth. I also ask about their household and gather information on their spouse or partner, dependents, and the rest of the financial picture. Survivor election decisions can be among the most consequential choices a PERA member makes.
Finally, I want to understand what exists outside of PERA, be it IRAs, prior employer plans, a spouse’s retirement, NMRHCA eligibility, and life and disability coverage. PERA is the anchor, but it’s rarely the whole picture, and the early conversations become less about gathering data than about understanding the person behind it.
QIs there a particular benefit available to PERA members you feel isn’t as well utilized or understood by members as it should be?
I’d point right back to SmartSave (deferred comp), which I touched on earlier. It’s New Mexico’s 457(b) deferred compensation plan, and while most PERA members know it exists, few use it to its full potential. One thing members often don’t realize is the flexibility built into the contribution side. You can save pre-tax (lowering current taxable income), or after-tax (Roth), or mix the two together. For participants whose tax bracket in retirement is likely to look different than it does today, which is most people, that flexibility can make a huge difference.
A second underused feature is the special pre-retirement catch-up. In addition to the standard catch-up available starting at age 50, governmental 457(b) plans like SmartSave allow eligible members to contribute up to double the regular annual limit during the three years before normal retirement age, provided they didn’t fully use their contribution room in earlier years. For someone in the home stretch of their career who’s behind on retirement savings, or who’s recently come into extra cash flow, this is something easy to take advantage of.
Next is access. SmartSave permits plan loans and, in qualifying circumstances, unforeseeable emergency withdrawals, which gives members reassurance that the money they defer isn’t completely locked away. Another one of the underappreciated advantages of a 457(b) is that once a participant separates from service, distributions are not subject to the 10% early withdrawal penalty that applies to most 401(k)’s and 403(b)’s, regardless of age. That distinction matters a great deal for members planning to retire before 59½.
QBeyond PERA member benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?
I almost always have a conversation around health care through New Mexico Retiree Health Care Authority. We’ll talk about eligibility rules, premium subsidies, and how that coverage bridges to Medicare. For many, NMRHCA is one of the most valuable pieces of their public-employee compensation package outside of the pension itself.
Beyond that, I usually have questions on insurance, any additional health savings, and whether long-term care coverage is on their radar. Nothing flashy, but they’re the kind of decisions that quietly shape financial security in retirement.
QFor PERA members thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
Leaving a PERA-covered job is a major financial decision that deserves more thought than it usually gets. For some, it is similar to leaving a tenured position. Before resigning, it is usually a good idea to maximize what you can put into the system on the way out. For example, deferring as much cash flow allows into the 457(b), especially if you’re in the catch-up window, and confirm what you’ll receive for your final paycheck, sick leave payout, and any annual leave cash-out.
If you aren’t vested, the biggest decision is what to do with your PERA contributions, and in most cases my recommendation is to leave them on deposit with the state. Many New Mexicans who leave one PERA-covered position end up returning to another public sector role in New Mexico, and leaving your contributions with PERA preserves your service credit so you can pick up right where you left off. Taking a refund forfeits the future pension benefit you’ve earned, it basically cashes in on time worked, and if you do return to a PERA-covered job later, the cost to buy that service back can be substantial. A refund can still make sense in some situations, particularly if you’re confident you won’t return to public sector work and have an urgent need for cash, but I want any member to fully understand what they’d be giving up before going that route.
Deferred comp balances can stay in the plan, roll to an IRA, or move to a new employer plan, each with different trade-offs and rules to follow. Update your beneficiary designations after the transition and make sure your new employer’s benefits are configured before separation to avoid a coverage gap.
QFor PERA members approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
A lot of my clients are surprised when I show them how much money they are spending to work. Also, planning on how money may shift to unforeseen health care costs, or vacation spending in retirement. I’ve even worked with a couple who went on a semi-permanent cruise once they left their state job.
The first step though is requesting a formal benefit estimate from PERA. From there, build a realistic retirement budget and compare it to your projected pension, SmartSave balance, Social Security (if applicable), and any outside savings. The work then shifts to sequencing and timing of withdrawals across those accounts to keep your tax bill manageable in retirement. Before you separate, look at moves like service credit purchases or maximizing SmartSave contributions through things such as vacation/sick-leave payouts.
QFor PERA members who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
Honestly, doing it yourself for a long time is something to be proud of- many people don’t. A good question to ask is whether the next phase of your life involves decisions that are bigger and more complicated than what you’ve handled before. For New Mexico PERA members, that moment usually arrives somewhere within ten years of retirement, when the choices on the table start to look very different. Survivor benefit decisions, service credit purchase windows, and the order in which you draw down your accounts in retirement are all decisions you generally make once, and the cost of getting them wrong is high.
I’d also think about the tax planning side. If you’re juggling a PERA pension, SmartSave (with both pre-tax and Roth balances), Social Security, IRAs, and possibly a spouse’s accounts, the question stops being “am I saving enough?” and becomes “in what order, and at what rate, do I draw these down to keep my lifetime tax bill as low as possible?” That’s a different kind of math, and a planner who knows your situation can be invaluable.
You also need to know how you actually want to spend your time and energy. Some people enjoy reading retirement research, playing with investing and running their own models, and that’s terrific. But many of my clients tell me the real value of working with an advisor isn’t just the technical work. It’s the freedom to stop carrying the weight of every financial decision themselves, and the confidence that comes from having a second set of trained eyes on a plan they’ve worked their whole career to fund.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are PERA members and how do you help them overcome these obstacles?
The challenges I see most often come back to complexity and irreversibility. PERA’s tier rules vary enough that two members in seemingly similar jobs can have meaningfully different benefit structures. Add deferred comp, Social Security, and any outside accounts to the picture, and the planning lift is suddenly very real. My job is to slow those decisions down, lay out the trade-offs in plain language, and make sure each move fits a coherent long-term plan rather than getting decided in isolation.
QWhat questions do you recommend PERA members ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
Know whether the advisor operates as a fiduciary at all times. A fiduciary is legally and ethically bound to put your interests ahead of their own in every recommendation. Beyond that, look at credentials and specialty. Ask whether the advisor has hands-on experience with PERA members specifically, since the system has its own vocabulary and quirks. Finally, confirm how they’re paid. Fee-only advisors charge solely for advice and don’t earn product commissions.
QIs there anything that comes up frequently in your initial meeting with PERA members that surprises you?
I feel lucky I get to work with such thoughtful and values-driven government employees out here in New Mexico. People who choose public service generally aren’t doing it solely for the money, and that same long-view, mission-oriented mindset shows up in how they approach their lives. They tend to be disciplined savers, and genuinely focused on making good decisions for their families and communities. It makes the work feel less like advising and more like collaborating with people who already know what matters most.
QFor highly compensated PERA members and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?
This is another case where we’ll make sure the employee is making full use of SmartSave. The governmental 457(b) is a powerful tool for high earners because it doesn’t have the highly compensated employee testing that limits private-sector 401(k) deferrals, so executives can typically max it out without restriction. The 3-year pre-retirement catch-up is especially valuable here, since it can effectively double the contribution limit during the final years of a career, a window when income tends to peak and the tax benefit of deferral is at its highest. From there, we get into tax-bracket management around the gap between salary income, pension start, and Social Security claiming, which is often where the biggest planning wins live for this group. As a CFP® and an Enrolled Agent (EA), that kind of multi-year tax work is where I tend to spend the most time with clients in this position.
QIs there a particularly memorable experience or a moment you recall with a client who worked at PERA when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?
Prior to starting my own firm, I spent years working exclusively with PERA members and traveling all over the state to meet with New Mexico’s public sector employees. I have too many stories at this point to pick just one, but something that always resonated with me was getting to help people cross the finish line into retirement and then catching up with them on the other side. Public sector employees tend to retire younger than their private-sector counterparts, and more often than not I’d see them taking on a whole new career or life post-government. And I’d see how what we had worked on together was going to help not only them, but their future generations as well.
There’s also a part of myself outside finance that shapes how I approach everything in general. As a working artist, I’ve spent years learning to notice what others miss and to make something coherent out of pieces that don’t always seem to belong together. Planning, at its best, asks for this same instinct.
Considering a financial advisor who specializes in working with New Mexico PERA Members?
Are you a financial advisor who specializes in working with New Mexico PERA members or other public employees?
✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with New Mexico PERA members or other public employees. (Subject to availability and terms.) ✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender
Ask a Financial Advisor Your New Mexico PERA Benefits & Career Questions
Get answers from the Wealthtender network of financial professionals and educators.
Are you ready to enjoy life more with less money stress?
Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.
Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.
A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.
Get expert insights from financial advisors who specialize in helping EOG Resources employees and executives make the most of their compensation package and benefits.
Looking for a financial advisor who specializes in working with EOG Resources employees? You’re in the right place. Below, you’ll find advisors who understand EOG Resources benefits and compensation — along with their answers to common financial questions from EOG Resources employees and executives.
Whether you recently joined EOG Resources or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and EOG Resources benefits can have a lasting impact on your financial future. For example:
✅ Do you know the right moves to get the greatest value from the EOG Resources benefits available to you?
✅ If you’re thinking about leaving EOG Resources for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?
Key Takeaways
1
EOG Performance Units Can Create a Sudden Tax Spike
Performance-based equity payouts depend on company results and can be much higher or lower than expected. Planning ahead for vesting events, and deciding how much to sell and how to allocate the proceeds, keeps a strong year from becoming a tax bomb.
2
Once the EOG 401(k) Is Maxed, the Real Planning Begins
High earners can extend tax-advantaged saving with after-tax 401(k) contributions and Roth conversions (when available), backdoor Roth IRAs, and tax-efficient brokerage accounts. The focus shifts from saving more to saving across the right account types.
3
Net Unrealized Appreciation on EOG Stock Is a One-Time Opportunity When You Leave
If EOG stock is held in the 401(k), the NUA strategy can let appreciation be taxed at long-term capital gains rates. The decision is tied to triggering events such as separation from service, so plan it before you leave.
Why EOG Resources Employees Work with a Specialist Financial Advisor
Throughout the year, EOG Resources provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) with a company match — along with performance-based bonuses and equity compensation such as restricted stock units and performance units. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with EOG Resources who specialize in helping EOG Resources employees make the most of their income and benefits.
EOG Resources is headquartered in downtown Houston, Texas, and operates in major U.S. oil and gas basins, including the Permian Basin in West Texas and New Mexico and the Eagle Ford in South Texas, with division offices in cities such as Midland and San Antonio, Texas, and Denver, Colorado. Whether you work at one of those sites, another office, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.
Sensitive topics — like the steps you should take before quitting your job at EOG Resources to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.
Should You Hire an EOG Resources Specialist or a Local Financial Advisor?
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving EOG Resources employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with EOG Resources employees is the better fit for your unique needs.
💡 In the Q&A below, you’ll gain insights from financial advisors who work with EOG Resources employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.
🙋♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.
Q&A: Financial Planning Tips for EOG Resources Employees & Executives
In this section, you’ll learn how you can make the most of your EOG Resources employee benefits and gain valuable tips from financial advisors who specialize in working with EOG Resources employees and executives.
Dr. Preston Cherry is a financial advisor based in Houston, Texas who specializes in offering financial planning services to EOG Resources employees. Preston helps his clients get the most value from their EOG Resources benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping EOG Resources employees save for their retirement, how do you help them make the most of their employee benefits?
EOG Resources professionals are often in a strong financial position—high salary income, performance-based bonuses, and long-term incentives tied to company results. That creates a powerful wealth-building opportunity, but also introduces a different kind of planning challenge: how to allocate, structure, and tax-optimize that income efficiently. Making the most of EOG benefits is not about maximizing one account. It’s about coordinating cash flow, equity compensation, taxes, and long-term investment strategy so peak earning years translate into lasting flexibility.
When working with EOG professionals, I focus on integrating:
401(k) strategy beyond standard deferrals, including after-tax contributions and Roth conversion opportunities (when available)
Employer match optimization and investment exposure within the plan
Equity compensation (RSUs and performance-based PSUs) and how vesting impacts taxes and concentration
Bonus income planning and marginal tax bracket management
Brokerage account strategy to build flexible, tax-efficient capital
Backdoor Roth IRA contributions alongside workplace plans
Retirement income modeling while income is at its peak
For many high-income EOG professionals, once traditional 401(k) contributions are maxed, the real planning begins, deciding how to allocate income across tax-deferred, tax-free, and taxable accounts. The goal is not just accumulation. It’s building a structure where your income, investments, and future withdrawals work together to support both retirement durability and lifestyle flexibility.
QWhen you first speak with a EOG Resources employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
With EOG professionals, the starting point is analyzing the benefits summary and, more importantly, understanding how income actually behaves. Compensation often includes variability through bonuses and performance-based equity, which directly affects tax planning and investment strategy.
I focus on questions like:
What percentage of your compensation is variable vs fixed?
How consistent have your bonuses been across cycles?
What is your current savings rate during strong income years?
How much of your net worth is tied to EOG or the energy sector?
Are you building assets outside of retirement accounts?
What does financial independence or optional work look like for you?
EOG professionals typically earn well. The key question is whether that income is being deployed intentionally.
QIs there a particular benefit available to EOG Resources employees you feel isn’t as well utilized or understood by employees as it should be?
One of the most misunderstood areas for EOG professionals is how equity compensation actually behaves, especially performance-based awards. At EOG, equity is often delivered through performance-based incentives (PSUs), which can lead to significant income variability. Unlike RSUs, which vest on a schedule, PSU payouts depend on company performance and can be materially higher or lower than expected.
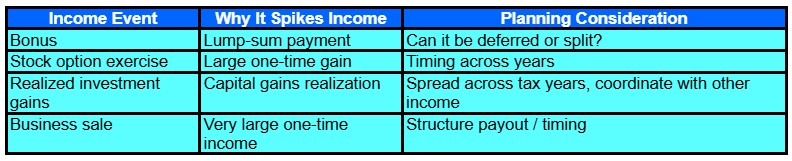
In strong years, this can result in a sudden increase in taxable income. This is where many high earners experience what they describe as a “tax spike” or “tax bomb.” A large PSU payout may arrive in a single year, pushing income into higher marginal brackets and increasing overall tax liability if not planned for in advance.
EOG professionals navigating equity compensation alongside broader energy sector planning considerations can find additional resources on our Oil & Gas Financial Planning page.
The opportunity is not just in receiving the compensation, but in how it’s managed once it’s received.
That includes:
Planning ahead for the tax impact of vesting events
Determining how much to sell immediately vs retain
Allocating proceeds intentionally across: lifestyle and short-term needs, ongoing financial goals, and long-term investment strategy
When equity vests, the key question is: What role does this money play in your life going forward?
I often guide clients to think in three buckets:
Lifestyle + taxes
Ongoing goals
Long-term capital
Another overlooked opportunity is what happens after traditional retirement contributions are maxed out. Many EOG professionals stop at the 401(k) when additional strategies may be available:
After-tax 401(k) contributions with Roth conversion (when supported)
Backdoor Roth IRA contributions
Brokerage accounts structured for tax efficiency and flexibility
At higher income levels, the focus shifts from saving more to saving across the right account types.
QBeyond EOG Resources employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?
For EOG professionals, one of the most valuable “benefits” is income itself and how it’s used.
Beyond traditional retirement plans, I focus on:
Brokerage accounts for flexibility and early access
Tax-efficient investing across account types
Health Savings Accounts as long-term investment vehicles
Insurance and protection planning aligned with income
Liquidity planning for career transitions or market cycles
Retirement accounts are important, but they come with restrictions. Brokerage accounts, when used intentionally, partner with retirement accounts to provide flexibility, especially for professionals who may want optionality before traditional retirement age.
QFor EOG Resources employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
Leaving EOG is more than a career decision—it’s a financial event.
Before making a transition, EOG professionals should evaluate:
Bonus timing and eligibility
Vesting schedules for RSUs and PSUs
Unvested equity that may be forfeited
Changes in income structure
Retirement plan contributions and match
Healthcare differences
One of the most important—and often overlooked—areas involves employer stock inside a retirement plan. If EOG stock is held within a 401(k), there may be a one-time opportunity to use a strategy called Net Unrealized Appreciation (NUA). When structured properly, NUA allows the appreciation on employer stock to be taxed at long-term capital gains rates instead of ordinary income rates. However, this is a one-time decision tied to specific triggering events like separation from service. If missed or executed incorrectly, the opportunity is typically lost.
Timing matters. A difference of a few months can impact:
Equity vesting outcomes
Tax exposure
Retirement strategy
Transitions should be structured in advance, not figured out afterward.
QFor EOG Resources employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
For EOG professionals, retirement planning often happens later than it should. Not due to lack of resources, but because income has been strong. Planning should include:
Converting assets into a structured income strategy
Managing tax exposure across account types
Reducing concentration in company or sector exposure
Coordinating Social Security and withdrawals
Maintaining lifestyle flexibility
The shift is from “Can I retire?” to “How do I want to live, and how do I fund that efficiently?”
QFor EOG Resources employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
The need usually appears when decisions become more complex and more impactful. For EOG professionals, that includes:
Managing multiple income streams
Coordinating tax strategy
Allocating high earnings efficiently
Reducing concentration risk
Structuring retirement income
The value is not just investment management. It’s confident strategy, coordinated decisions, collaborative guidance, time optimization, and disciplined implementation.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are EOG Resources employees and how do you help them overcome these obstacles?
EOG professionals often face:
Income variability tied to performance
High earnings that can mask inefficiencies
Concentration in the energy sector
Underutilization of advanced tax strategies
Delayed planning due to strong income
The real risk is unstructured income. Earning well without a clear plan for how it’s allocated, invested, and used over time.
QWhat questions do you recommend EOG Resources employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
EOG professionals should ask:
Are you a fiduciary?
How are you compensated?
Do you charge a flat fee or a percentage of assets?
How do you integrate tax strategy with investing?
How do you handle equity compensation?
Fee structure matters. It determines whether advice is aligned, transparent, and built on trust.
QIs there anything that comes up frequently in your initial meeting with EOG Resources employees that surprises you?
What surprises me most is how often high earners feel uncertain despite doing many things right. Another common theme is excess cash accumulation during strong income years, which delays investment decisions. Once structure is introduced, clarity follows quickly.
QFor highly compensated EOG Resources employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?
Highly compensated EOG professionals often have:
Performance-based compensation
Equity awards
High tax exposure
Access to advanced savings strategies
Planning should focus on:
Tax management across years
Roth and after-tax strategies
Brokerage account construction
Equity and sector diversification
The opportunity is meaningful, but it only works when it’s structured with intention and follow-through.
QIs there a particularly memorable experience or a moment you recall with a client who worked at EOG Resources when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?
The most memorable moments working with EOG professionals aren’t just about hitting a number. They’re about defining what “enough” means. Many have high incomes and equity compensation but lack clarity about how it’s all being allocated and coordinated. Once income, investments, and tax strategy are aligned around how they want to live, everything changes. Clarity replaces uncertainty. Confidence replaces hesitation.
Considering a financial advisor who specializes in working with EOG Resources Employees?
Are you a financial advisor who specializes in working with employees at EOG Resources or another large company?
✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at EOG Resources or another large company. (Subject to availability and terms.) ✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender
Ask a Financial Advisor Your EOG Resources Benefits & Career Questions
Get answers from the Wealthtender network of financial professionals and educators.
Are you ready to enjoy life more with less money stress?
Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.
Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.
A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.
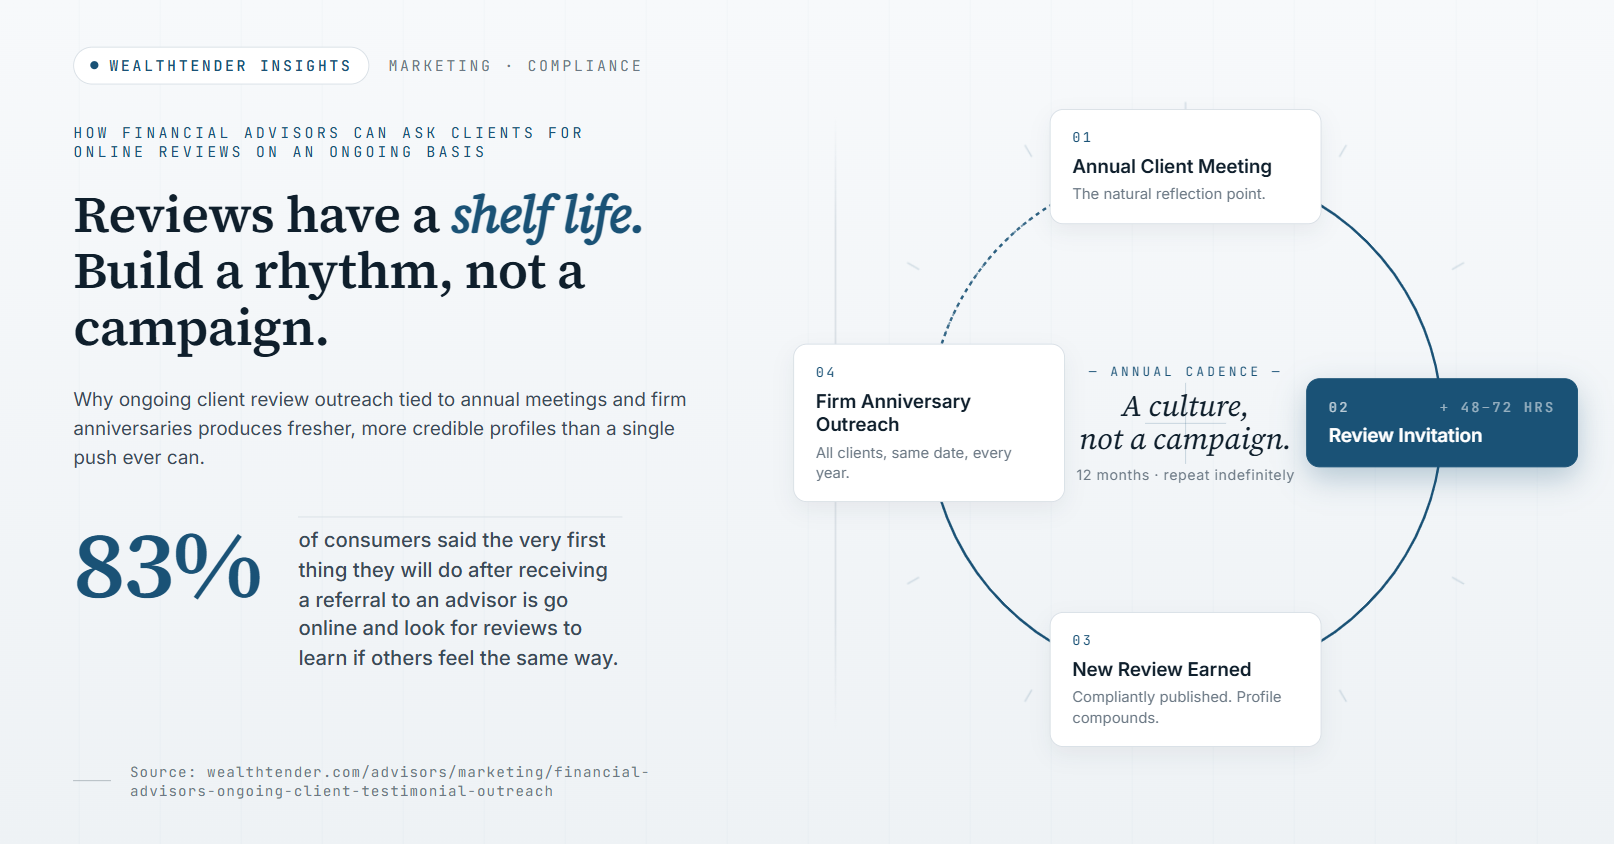
Your first round of client reviews was a meaningful accomplishment — and it put you ahead of the 90% of advisors who still haven’t asked. But if you’ve been coasting on that initial effort, your review profile may be quietly falling behind, even as your client relationships continue to grow stronger. Reviews age. Prospects notice. Search engines and AI tools weight recency. This guide explains why ongoing review outreach matters more than most advisors realize, why wealth management requires a different cadence than the transactional professions that have been doing this longer, and how to build a sustainable, compliant process — including two ready-to-use email templates and a CRM and AI meeting tool workflow — that keeps fresh reviews flowing in year after year.
Congratulations. You did something the majority of financial advisors still haven’t done: you invited your clients to write reviews. You drafted the email, cleared it with compliance, hit send, and watched your glowing testimonials begin to roll in. That was a meaningful step, and it put you ahead of 90% of advisors still sitting on the sidelines.
But your first round of reviews was just the opening chapter. If you’ve been coasting on that initial effort without a plan for what comes next, your review strategy may be quietly falling behind, even as your client relationships continue to grow stronger every year.
In this article, we’ll explain why ongoing review outreach matters, why wealth management presents a unique set of challenges compared to other professions that have been doing this longer, and how you can build a sustainable, compliant, and client-friendly process for keeping your review profile fresh year after year.
Key Takeaways
1
Asking for reviews once is not enough — ongoing outreach is essential.
A single round of review invitations is a great start, but reviews age over time. Advisors who treat review outreach as a one-time campaign risk their review profile getting stale, reducing SEO/AEO benefits and costing them credibility with prospects who look to recent reviews for social proof.
2
Wealth management requires a different review cadence than transactional professions.
Unlike doctors or lawyers who can tie review requests to discrete appointments or case closings, financial advisors serve clients in an ongoing relationship with no natural finish line. This makes it critical to identify recurring, relationship-driven moments — like annual client meetings or firm anniversaries — to re-invite clients to share their experience compliantly and gracefully.
3
Building review outreach into your CRM and annual meeting process turns it from a chore into a habit.
Advisors who systematize their review outreach — using CRM automation, AI meeting tools, and annual client touchpoints — generate a steady, compliant stream of new reviews without it feeling awkward or burdensome for clients. The key is consistency: a modest but regular flow of fresh reviews is far more valuable than an occasional spike.
Why Financial Advisors Need to Ask Clients for Reviews More Than Once
When you sent your first-round review invitations, you were thinking about a moment. What most advisors don’t anticipate is that reviews, like any content, have a shelf life.
Across any type of business, consumers don’t just count reviews they look to see when they were written. Research in the legal profession has found that recency of reviews is one of the most important factors in how much weight prospective clients assign to them. The same behavioral tendency, albeit to a lesser degree given the long-term nature of advisor/client relationships, could be expected when evaluating financial advisors as well.
Think about it from a prospect’s perspective. You’re considering working with an advisor and you pull up their Wealthtender profile. You see eight glowing reviews, all from three years ago. Compare that to an advisor with five reviews, three of which are from the past six months. Who feels more active, more trusted, more current? Almost always, the latter.
Beyond consumer perception, there is a practical SEO and answer engine optimization (AEO) argument as well. Search engines and AI tools that power recommendation engines give greater weight to businesses with consistent, recent review activity. A profile that continues to earn reviews over time is a profile that continues to earn the greatest visibility.
The conclusion is simple: your first round of reviews built a foundation. But building the structure on top of that foundation requires an ongoing commitment.
Why the Doctor and Lawyer Playbook Doesn’t Fully Apply to Financial Advisors
To understand why ongoing review outreach feels harder for wealth managers than for other professions, it helps to look at how doctors and lawyers handle it because they’ve had much more time to develop their playbooks. While both professions, like financial advisors, survive and thrive based on consumer trust, there are differences worth noting.
A physician’s practice is inherently transactional in cadence. Every appointment is a discrete event and a natural moment of reflection that lends itself to an immediate ask. A patient finishes their visit, feels grateful for the care they received, and receives a follow-up text or email asking them to share their experience. The review request matches the moment.
Law firms face similar dynamics. As one legal marketing guide describes it, review requests work best “within one to two weeks after case closure, when details are fresh and positive emotions are still present.” The end of a legal matter creates a moment of resolution and relief, a natural trigger for asking a client to reflect on their overall experience.
Wealth management is different in a fundamental way: there is no finish line. Your client relationship doesn’t end with a discharged diagnosis or a closed case. It is, by design, an ongoing relationship intended to span years, decades, and in many cases, generations. That’s the beauty of what you do, and it’s also what makes the review ask more complex.
When you invite a longtime client to write a review, they’re not reflecting on a single interaction. They’re reflecting on the entirety of a relationship that may include bull and bear markets, major life transitions, estate planning conversations, and the quiet reassurance of knowing someone is looking out for their financial future. That’s a richer, deeper experience to articulate, and that’s actually a good thing for the quality of reviews you’ll receive. But it means the “timing” question is less obvious than it is for a doctor or a lawyer.
There is an additional wrinkle specific to wealth management: the question of what to do about clients who have already written a review. This creates a real tension. You want to keep your review profile fresh. But you don’t want to create awkward pressure for a client who already came through for you once. And from a compliance standpoint, you remain obligated to avoid cherry-picking which means your approach to ongoing outreach needs to remain systematic and consistent, not targeted at select clients.
How Financial Advisors Should Structure Ongoing Review Outreach
Given these dynamics, how should advisors think about reigniting and sustaining their review efforts over time? The answer lies in shifting from a campaign mindset to a culture mindset.
A campaign is something you launch, run, and conclude. A culture is something you embed in your workflows, your team habits, and your client communications. The advisors who will build the most powerful review profiles over the next five years won’t be the ones who do one big annual push. They’ll be the ones who have woven review outreach into the rhythmic fabric of how they serve clients every year.
Here are two primary frameworks to consider:
Strategy 1: Send an Annual Review Invitation to All Clients
One of the most elegant solutions to the “how often do we ask?” question is the annual firm-wide invitation, a message sent to your entire client list on approximately the same date each year (for example, the anniversary of your firm).
This approach has several advantages:
It treats all clients equally, which is essential for demonstrating to regulators that you are not cherry-picking reviewers.
It establishes a predictable, firm-wide rhythm rather than an ad hoc, person-by-person approach.
It frames the ask as an expression of gratitude rather than a request for a favor.
The annual touchpoint also gives you a graceful way to re-invite clients who have already written a review. The message can be framed to acknowledge that some recipients may have already shared their feedback – thanking them for having done so – while gently opening the door for them to update or add to their review if their experience has continued to evolve.
Think about how this might feel to a client: you’re not asking them to repeat themselves or do something they’ve already done. You’re inviting them, if they’re willing, to share how the relationship has grown. That’s a meaningful distinction.
Strategy 2: Ask for a Review Within 48 Hours of Every Annual Client Meeting
The annual client review meeting, already a cornerstone of most advisory practices, is an ideal natural trigger for a review invitation. It’s the one moment each year when a client is most engaged with the breadth of their relationship with you, thinking holistically about their financial picture, their goals, and the progress they’ve made.
That reflective energy is precisely the mindset that produces rich, authentic reviews.
Rather than asking for a review during the meeting itself (which can feel awkward and transactional), the most effective approach is to send a brief, personal follow-up email within a few days of the meeting concluding. The timing is important: the conversation is still fresh, the client is likely in a positive frame of mind, and the ask arrives as a natural extension of the touchpoint rather than an unrelated cold request.
This approach also integrates cleanly into CRM-based workflows, which we’ll discuss in more detail below, making it something your team can execute consistently rather than something that depends on an individual advisor remembering to follow up.
Compliant Email Templates for Asking Financial Advisor Clients to Write Reviews
The art of re-inviting clients to write reviews, especially clients who have already done so, is to make the ask feel warm, purposeful, and genuinely optional. Your work ethic and culture of compliance requires that you not pressure clients or selectively target favorable ones. Good judgment requires that you not make anyone feel obligated or uncomfortable.
The language below is designed to honor both of these principles.
Template 1: Annual Client Review Invitation Email (For All Clients, Including Those Who’ve Already Written a Review)
Template 1: Annual Firm-Wide Review Invitation
For All Clients
Subject:A thank-you from [Firm Name] — and a small favor if you’re willing
Hi [First Name],
Each year around this time, I take a moment to reflect on what I’m most grateful for in this work, and without question, the trust our clients place in us is at the top of that list.
Thank you for being a valued client of [Firm Name]. It’s a privilege to play a role in your financial journey, and I don’t take that lightly.
As part of our ongoing commitment to transparency, we periodically invite our clients to share their experience online. These reviews help people who are searching for a financial advisor get a genuine sense of what it’s like to work with us, and they help us continue earning the trust of new clients the same way we earned yours.
If you’ve written a review for us in the past, we’re genuinely grateful, and there’s no need to take any additional action unless you’d like to update or add to what you shared. If you haven’t yet written a review, we’d be truly honored if you’d consider it when you have a few minutes.
Here’s a link to our profile: [Your Wealthtender Profile “Review Me” Link]
It only takes a couple of minutes, and it means a great deal to us and to those who are trying to make an informed decision about their financial future.
As always, please don’t hesitate to reach out with anything on your mind. We’re here for you.
With gratitude,
[Your Name]
Subject:Great catching up — one small ask when you have a moment
Hi [First Name],
Thank you for the time we spent together this week. I always look forward to our annual conversations. Getting a clear picture of where things stand and thinking through what’s ahead with you is one of the most meaningful parts of this work.
I have a small favor to ask, and please know it’s entirely optional. I’d be grateful if you’d consider sharing your experience in a review on our Wealthtender profile. Reviews like yours help people who are looking for a financial advisor understand what working with us is really like, and they make a real difference.
Here’s a link to our profile: [Your Wealthtender Profile “Review Me” Link]
If you’ve already written a review for us in the past, thank you. There’s no need to do so again unless you’d like to. And if this isn’t the right time, I completely understand. I’m just glad we had the chance to connect.
Looking forward to continuing to support you and your family. Please don’t hesitate to reach out if anything comes up before we speak again.
[Your Name]
How to Automate Ongoing Client Review Outreach Using Your CRM and AI Meeting Tools
Knowing what to say is only part of the equation. The advisors who succeed at ongoing review outreach are the ones who have removed the burden of remembering to do it. That means building the process into your systems, not your willpower.
Here’s how to make it systematic:
Use Your CRM to Automate Annual Outreach
Most modern CRM platforms used by advisors (including Salesforce, Redtail, and Wealthbox, among others) allow you to set recurring tasks or automated email triggers based on specific dates or relationship milestones. Configure your CRM to flag all active clients for a review outreach campaign once per year, tied to either the anniversary of your first review push or a fixed date meaningful to your firm.
Tag clients who have already submitted a review so you can customize the messaging accordingly, sending one version to first-time recipients and a subtly different, appreciative version to those who have already written one. This segmentation keeps the communication thoughtful without crossing into the territory of cherry-picking, since both messages go out to entire cohorts rather than selectively chosen individuals.
How AI Meeting Tools Like Jump.ai and Zocks Can Automate Your Review Follow-Ups
AI-powered meeting and note-taking tools like Jump.ai, Zocks, and others are transforming how advisors capture and act on client meeting insights. These tools don’t just summarize conversations, they can trigger post-meeting workflows based on what was discussed.
If your firm uses one of these tools, work with your team to configure a workflow that adds a review follow-up task to the advisor’s queue whenever an annual review meeting is logged. The task can include a pre-drafted email template (like Template 2 above) that the advisor can review, lightly personalize if desired, and send with minimal friction.
This approach accomplishes something important: it turns review outreach from something advisors have to remember to do into something the system prompts them to do. That’s the difference between a process and a culture.
Assign Ownership: Who on Your Team Is Responsible for Review Outreach?
Just as healthcare practices train their front-desk staff to request reviews as a natural part of the checkout process, advisory firms benefit from making review outreach a team responsibility rather than a solo advisor task. Designate someone, whether an operations coordinator, a client service associate, or a marketing lead, as the person accountable for ensuring the annual outreach goes out on schedule and that post-meeting follow-ups are sent within a defined window (ideally within 48 to 72 hours of the meeting).
Track it as you would any other business metric. How many review invitations went out this year? What’s the response rate? How many new reviews were added to the profile? Giving the process the same visibility you give other growth metrics ensures it doesn’t slip through the cracks during busy stretches.
Lessons From Doctors and Lawyers on Building a Consistent Review Culture
Doctors and lawyers have had years of practice building review cultures and there are lessons worth borrowing.
The most important one is this: consistency matters more than volume. Legal marketing research consistently finds that a modest but steady flow of reviews is more valuable to online visibility and consumer trust than a large spike followed by a long silence. The same logic applies for financial advisors. Ten thoughtful reviews added across the course of a year do more for your profile than thirty collected in January and nothing thereafter.
The second lesson is about framing the ask around the relationship, not the transaction. Law firms that have cracked the code on ongoing review outreach have learned to invite clients to share how it felt to work with them, the communication, the responsiveness, the sense of being cared for, rather than asking them to narrate specific outcomes or case details. That reframe makes the ask feel less vulnerable and more genuine.
For financial advisors, this is especially resonant. You’re not asking a client to describe their portfolio returns. You’re inviting them to share what it feels like to know that someone is helping them navigate the complexity of their financial life with care and expertise. That’s a story most clients are happy to tell, if you give them an easy, comfortable way to do it.
How Wealthtender Helps Financial Advisors Collect Reviews Compliantly and Consistently
Building an ongoing review culture is only valuable if it’s built on a compliant foundation. That’s where Wealthtender’s platform is purpose-built to support you.
Unlike general consumer review platforms which lack the infrastructure to address the SEC Marketing Rule’s prohibitions and disclosure requirements, Wealthtender’s Certified Advisor Reviews™ are designed from the ground up with regulatory compliance in mind. That means:
Required disclosures are built into the review display, ensuring that reviews you promote meet the SEC’s disclosure requirements for testimonials and endorsements.
A compliant review collection process helps you demonstrate to regulators that you are inviting reviews broadly and consistently, not cherry-picking favorable clients.
A profile that compounds over time, so every new review you collect builds on the ones before it, deepening your profile’s credibility and visibility with consumers, search engines and AI answer engines.
The first round of reviews was your beginning. With the right process in place, the next round, and every one after it, can become one of the most valuable habits you build as a marketer and as a trusted advisor to the clients who count on you.
This article is for informational purposes only. Nothing herein constitutes legal, compliance, or investment advice. Financial advisors should consult with their compliance team and legal counsel before implementing any review outreach strategy.
Want to see how individual advisors and leading wealth management firms are successfully using Wealthtender to grow their business? Visit Wealthtender.com/grow or schedule a demo to learn how you can start converting more prospects into clients with the industry’s first digital marketing platform for AI-optimization and compliant online reviews.
About the Author
Brian Thorp
Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian
Book a Demo
Select a day in the calendar below to schedule a meeting with Brian Thorp, Wealthtender founder and CEO.
Discover financial advisors trusted by residents of Bellingham, Washington in the only local directory featuring 5-Star Certified Advisor Review™ recipients and Wealthtender Voice of the Client Award™ winners—recognition earned for exceptional client feedback. Compare fiduciary, fee-only advisors, CFP® professionals, and specialists to find the right fit for your unique financial needs.
Whether you have lived in Bellingham for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.
It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Bellingham featured on Wealthtender you may want to add to your shortlist.
Featured Bellingham Financial Advisors
As you prepare to interview financial advisors in Bellingham who may be right for you, get to know local financial advisors featured on Wealthtender.
📍 Map: Financial Advisors with their Primary Office Location in Bellingham
Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Bellingham.
The Benefits of Hiring a Financial Advisor in Bellingham
Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.
As a resident living in Bellingham, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.
Do you work for one of the largest employers in Bellingham? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.
When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.
Quick Tips For Hiring an Bellingham Financial Advisor
Before hiring a financial advisor in Bellingham, here are a few quick tips to help you find the best advisor for you.
1. Decide Which Services You Need
Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.
Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:
Budgeting and money management
Debt management
Insurance planning
Retirement planning
Other investment planning
Inheritance planning
Estate planning
Tax planning
As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.
Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.
2. Consider Your Budget and Payment Preferences
Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.
If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.
3. Interview Multiple Financial Advisors
Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:
What services do you provide?
What are all the ways you get paid? (fee transparency)
What is your investment strategy?
How do you measure investment performance?
How do we communicate about my plan?
Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.
4. Review Financial Advisor Credentials
Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website.
You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.
As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.
For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.
Frequently Asked Questions & Additional Resources
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.
But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings.
Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a local financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.
Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian
You work hard to earn money, save diligently, and invest for the future. But do you actually know what your financial picture looks like right now, across every account you own?
Knowing your net worth in real time isn’t just satisfying; research consistently shows that people who actively track their wealth make better financial decisions, stay on budget more reliably, and build toward financial goals faster. Whether you’re just starting out or managing a complex portfolio across multiple brokerages, the right wealth tracker can be the single tool that brings everything into focus.
Pearson’s Law states: “When performance is measured, performance improves. When performance is measured and reported back, the rate of improvement accelerates.”
So, if you’re working toward a financial goal, tracking your progress will help you achieve it quicker! The hard part is finding an efficient way to do it.
That’s where wealth tracker apps and websites come in to help you know your net worth and achieve your goals. These useful tools aggregate info from your various accounts and allow you to monitor (and manage) everything from your income and expenses to your investments – all from a single dashboard. Making informed financial decisions and hitting those big money goals becomes much easier as a result.
Want to find one that’s right for you? Keep reading to discover 7 of the best wealth trackers available today.
Key Takeaways
1
Tracking your net worth accelerates wealth-building — not just awareness.
Research supports what Pearson’s Law describes: when you measure financial performance and regularly review it, improvement accelerates. Wealth tracker apps automate the aggregation of your accounts into a single dashboard, making consistent monitoring effortless rather than a manual chore.
2
The best wealth tracker depends on what financial visibility you actually need.
Beginners benefit most from budgeting-first tools like YNAB, while those who want a comprehensive view of spending and net worth together will find all-in-one platforms like Monarch Money or Empower ideal. Advanced investors with complex, diverse portfolios may prefer the deeper tracking capabilities of Kubera. Knowing what you need most — budgeting, net worth tracking, investment analytics, or all three — is the right starting point for choosing a tool.
3
Free tools can get you started, but paid options deliver meaningfully more insight.
Several apps on this list offer free tiers — including Empower and PocketSmith — but their most powerful features (investment analytics, multi-account sync, long-range financial projections) typically require a paid plan. Given that most premium wealth trackers cost less than $150/year, the ROI on better financial decisions usually far outweighs the subscription cost.
What Is a Wealth Tracker App and Why Does It Matter?
A wealth tracker app is a digital tool that connects to your financial accounts (e.g., bank accounts, investment portfolios, retirement funds, loans, and more) and aggregates everything into a single, unified dashboard. Instead of logging into five different apps or building a spreadsheet from scratch, you get a real-time snapshot of where you stand financially, including your total assets, liabilities, and net worth.
Net worth is one of the most important numbers in your financial life, yet most people have only a vague sense of what it actually is. Your net worth, the difference between everything you own and everything you owe, is the clearest measure of whether your financial life is moving in the right direction. Wealth tracker apps make that number visible, trackable, and actionable rather than something you calculate once a year (if at all).
Beyond the snapshot, the best wealth tracker apps and websites reveal patterns you’d otherwise miss: spending categories quietly eating into your savings, investment accounts drifting out of alignment with your goals, or retirement projections that suggest you need to course-correct sooner than you thought. Used consistently, these tools don’t just tell you where you are, they help you get to where you want to be.
Want to track your wealth and invest at the same time? Try Betterment, the “all-on-one financial dashboard.” The app’s a roboadvisor – a digital financial advisor that manages your investing accounts (Betterment restricts you to investing in exchange-traded funds, or ETFs) depending on your goals and risk tolerance. However, you can also sync your bank accounts to enjoy a birds-eye view of your finances, set goals, and track your saving/investing progress.
There are two service tiers: Digital and Premium. Choose the former if you’re on a budget and investing less than $100k. There’s no minimum to get started, and the annual advisory fee is 0.25%.
2. Empower
Empower (previously called Personal Capital) is another popular and widely-used wealth tracker that comes highly recommended online. Empower is powerful, versatile, and has many impressive free-to-use tools – as well as a paid wealth management service for those who need/want it.
After signing up, you can link your financial accounts (e.g., bank, credit cards, savings, loans, investing, retirement, etc.) to get a real-time look at your net worth. You can then monitor cash flow, set budgets, and leverage many other special tools, including a Savings Planner, Retirement Planner, and Fee Analyzer. The fact you get so much for free is a huge selling point.
EmpowerWhatever your financial happiness looks like, let’s help get you there.
Self-billed as “the world’s most modern wealth tracker,” Kubera is an advanced portfolio-tracking app that offers a near-limitless number of bank connections and detailed insights on your investments.
It’d be ideal for someone with a large and diverse portfolio – even if it includes international holdings. Kubera tracks all of your assets in one place and shows their current and estimated resale value, making monitoring your net worth over time straightforward.
Take note, though: unlike other wealth trackers with a diverse range of tools, Kubera has a heavy investment focus. Likewise, there’s no free plan. Once the 14-day $1 trial is over, you’ll pay $150 per year.
4. Monarch Money
If Mint’s shutdown left a gap in your financial toolkit, or if you’ve never found a personal finance app that truly brings everything together, Monarch Money may be exactly what you’re looking for. Launched in 2021 and now widely regarded as the leading all-in-one personal finance platform in the post-Mint era, Monarch combines account aggregation, net worth tracking, budgeting, and investment monitoring in a single, polished dashboard.
What sets Monarch apart is its balance of depth and usability. Connect your bank accounts, credit cards, investment portfolios, loans, and retirement accounts, and you get a real-time picture of your complete financial life, not just one slice of it. The budgeting tools are intuitive without being rigid, the net worth tracker updates automatically as balances change, and a collaborative feature makes it particularly well-suited for couples managing finances together.
Monarch is available on both iOS and Android and is priced at $99.99 per year (or $14.99 per month billed monthly). There’s no permanent free tier, but a 30-day free trial gives you time to evaluate it before committing. For anyone who wants a comprehensive, beautifully designed tool that moves beyond basic budgeting into genuine wealth visibility, Monarch Money belongs near the top of your list.
5. PocketSmith
PocketSmith is an easy-to-use personal finance software that helps users with money management, cash flow forecasting, and personal budgeting.
There’s a lot to like, but one highlight is the info it provides on your future financial situation based on your current spending habits and earnings. This glimpse of what’s to come should compel positive financial action in the present.
The fact that PocketSmith offers a free plan is a bonus, although its features are quite limited. If you wish to connect your accounts to a single dashboard (for the most accurate wealth tracking) and enjoy financial projections well into the future, you’ll need to pay for a premium plan.
Image Credit: Depositphotos.
6. Tiller
Calling all spreadsheet fans and aficionados! Tiller could be the best wealth tracker for your needs. Like Microsoft Excel on steroids, this tool syncs to your financial accounts and imports real-time data to robust, highly customizable spreadsheet templates. That means no more manual data entry – unless you choose to edit certain fields or set custom rules!
Among other elements, the basic template offers a net worth tracker and a breakdown of your annual budget. However, many others are available, such as a template for retirement planning and another for debt reduction. Try Tiller for free on a 30-day trial, after which you’ll pay $79 annually.
7. YNAB
Short for “You Need a Budget,” YNAB is a fantastic tool that helps users budget, pay down debt, and manage money more effectively. It’s a great wealth tracker for beginners, with a program that revolves around four basic rules:
Give every dollar a job – be intentional with money, allocating everything you earn to specific expenses based on your financial priorities.
Embrace your true expenses – handle larger but less frequent expenses more easily by breaking them into smaller bills that you save for each month.
Roll with the punches – forget rigid budgets and simply move money from less important budgeting categories when you overspend elsewhere.
Age your money – spend less than you earn, watch your money accumulate, and start buying things today with money you earned in the past.
After a ~30-day free trial, you’ll need to pay for a subscription. This costs $14.99 per month or $98.99 per year.
Choose From This List of the Best Wealth Trackers to Know Your Net Worth
As Pearson’s Law points out so eloquently, tracking your progress is crucial to moving in the right direction and achieving goals sooner rather than later. That’s why it pays serious dividends – sometimes quite literally – to use a wealth tracker in your bid to budget, save, and invest as effectively as possible!
If you’ve been hunting for the best tracking tool, we hope this list has helped. Whether you’re an advanced investor with a vast and diverse portfolio or someone brand new to the pursuit, there should be a service here to suit your needs.
Author Bio
Danny Newman is a nationally syndicated freelance writer with a focus on travel. MSN feed and Associated Press bylines. Danny is a digital nomad from the UK who’s been traveling full-time since 2018. Learn More About Danny.
Find Financial Advisors on Wealthtender
📍 Click on a pin in the map view below for a preview of financial advisors who can help you reach your money goals and enjoy a comfortable retirement with a personalized plan. Or choose the grid view to search our directory of financial advisors with additional filtering options.
Do you have questions about your financial future? Find a financial advisor who can help you enjoy life with less money stress by visiting Wealthtender’s free advisor directory.
Whether you’re looking for a specialist advisor who can meet with you online, or you prefer to find a nearby financial planner, you deserve to work with a professional who understands your unique circumstances.
Have a question to ask a financial advisor?Submit your question and it may be answered by a Wealthtender community financial advisor in an upcoming article.
–
Do you already work with a financial advisor? You could earn a $50 Amazon Gift Card in less than 5 minutes. Learn more and view terms.
This article originally appeared on Wealthtender. To make Wealthtender free for our readers, we earn money from advertisers, including financial professionals and firms that pay to be featured. This creates a natural conflict of interest when we favor their promotion over others. Wealthtender is not a client of these financial services providers.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
April 20, 2026
If you’ve been watching AI dominate headlines and wondering whether you’re positioned to actually benefit from it, you’re not alone. Most high-income investors have exposure to AI through a handful of large-cap tech stocks. That’s a start, but it’s a narrow slice of one of the most significant economic expansions of our lifetime. The global AI market is on track to grow from roughly $376 billion this year to more than $2.4 trillion by 2034. The opportunity isn’t just in the companies everyone already owns.
Most investors are still playing the same crowded trade. NVIDIA, the dominant force in AI computing, has become the default bet, with Wall Street analysts continuing to raise the ceiling. Consensus estimates project Nvidia’s revenue to jump roughly 48% in fiscal 2027, and some analysts believe the stock could approach double its current price if earnings growth accelerates as expected. The enthusiasm is understandable. North America alone captured nearly one-third of the global AI market in 2025, and this giant sits squarely at its center.
But here’s the question serious investors should be asking: if enthusiasts already own Nvidia, where’s the edge?
For example, cloud deployment now accounts for more than 71% of the AI market share, growing at a projected rate of 30.7% annually. And the infrastructure powering that cloud buildout is where the real leverage may lie. The AI opportunity goes beyond computing itself. It’s the physical and digital backbone that makes an entire ecosystem operate at scale: data centers, power supply, networking, and cooling. These are the unsexy picks that investors aren’t always talking about at dinner parties, which might be exactly why they’re worth a closer look.
AI Runs on Power, and That’s a Problem
Once you start looking beyond the headlines, one constraint becomes hard to ignore: AI doesn’t just run on innovation; it runs on electricity.
Every query, model, and automation tool relies on data centers working around the clock. And those facilities are power-hungry in ways most people haven’t thought about. A typical AI-focused data center consumes as much electricity as 100,000 households annually, and the largest ones currently under construction are expected to use 20 times that amount. U.S. data centers consumed 183 terawatt-hours of electricity in 2024, more than 4% of the country’s total, and that figure is projected to more than double by 2030.
According to Bloomberg, a confluence of factors is placing significant strain on power grids worldwide, creating a tangible drag on economic growth. And according to Pew Research, everyday Americans are shouldering the cost in their power bills. In the PJM electricity market, which stretches from Illinois to North Carolina, data centers contributed to an estimated $9.3 billion increase in capacity market pricing.
I’ve been paying attention to this for a while.
There’s genuine debate about how to solve the energy problem, and some of it gets political fast. But set the politics aside, and the underlying dynamic is straightforward: demand for a critical resource is outpacing the infrastructure supporting it. That gap is where investment opportunities tend to emerge.
What “Investing in the Grid” Actually Means
When I talk about investing in the grid, I’m not talking about chasing a theme or picking the next AI stock. I’m talking about owning the assets that make AI possible. That includes data centers, power generation, transmission infrastructure, and fiber networks.
These are physical, capital-intensive assets built to support sustained, long-term demand. And the scale of that demand is hard to overstate.
McKinsey estimates that by 2030, data centers will require $6.7 trillion in cumulative capital investment worldwide to keep pace with AI-driven compute needs, spread across real estate developers, energy providers, semiconductor firms, and cloud operators. Utilities and energy providers alone face an estimated $1.3 trillion in AI-related capital requirements.
If you’ve invested in commercial real estate, this asset class should feel familiar. Data centers are increasingly treated as a specialized form of real estate — physical buildings with long-term leases, mission-critical tenants, and predictable cash flows. A 2025 survey by CBRE found that 95% of major investors worldwide plan to increase their allocations to data centers, with 41% planning to commit $500 million or more in equity, up from 30% the year prior. Vacancy rates in the sector finished 2025 at a historic low of 1% for the second consecutive year, with 92% of capacity currently under construction already pre-committed by tenants.
The appeal is structural. These are long-duration, hard assets — the kind where demand isn’t speculative but is driven by an accelerating, durable tailwind. AI doesn’t run on software alone. It runs on land, steel, power lines, and cooling systems. That’s the investment conversation worth having.
I encourage clients to take a disciplined approach and acknowledge what we don’t know. Researchers at the World Resources Institute point out that modeled projections for data center energy use by 2030 range from 200 to over 1,050 terawatt-hours per year, which is a pretty staggering spread. Some experts have also warned that utilities are being flooded with speculative grid connection requests, which may be distorting load forecasts.
The investment case for infrastructure isn’t built on assuming the most aggressive projections are right, but on recognizing that even the conservative ones point to a significant and sustained build-out, and that the physical assets required to support it will need to exist regardless.
Why the Real Action Is in Private Markets
These opportunities aren’t readily accessible to everyone. Most of the meaningful investment in AI infrastructure isn’t happening in the public markets, and there’s a structural reason for that.
Large-scale data centers, energy systems, and digital networks require significant capital, long development timelines, and patient ownership. These are conditions private markets are built for, and institutional conviction is growing.
The World Economic Forum puts the scale of opportunity in sharp focus. Meeting the world’s infrastructure demand will require $106 trillion in investment by 2040, spanning energy, digital, and transportation systems. Private investment plays a critical role, as public funding alone falls well short.
For high-income investors, access to these markets has improved meaningfully in recent years. But access isn’t the strategy. As I’ve written before, private credit and infrastructure funds can generate steady cash flow even when public markets struggle, and that’s exactly the kind of characteristic that belongs in a long-term, disciplined wealth plan. The trade-offs around liquidity, structure, and complexity are real, and they deserve a direct conversation. That’s always where we start.
What to Watch Out For
This is where I usually slow things down.
Private infrastructure and similar investments can be a good fit, but they come with real trade-offs.
Liquidity is one of the biggest. You’re not buying something you can sell tomorrow; you’re committing capital for years, and that needs to align with your broader plan. As I’ve noted in past articles on private investments, these structures often involve lock-up periods and limited access to funds, which can be challenging when flexibility is needed.
Manager selection is just as important. Two funds may both be labeled “infrastructure,” but have very different strategies, risk profiles, and outcomes depending on how they’re built and managed. Not all opportunities are created equal.
I’ve seen investors get pulled in by a compelling theme without fully understanding how the investment works — how returns are generated, what assumptions are being made, and how long capital is tied up. That’s why the focus should always be on fundamentals. If we can’t clearly answer those questions, we don’t move forward.
A Different Way to Think About AI Investing
This isn’t about chasing AI hype or trying to pick the next winner. It’s about understanding where durable, long-term value is being built and whether those opportunities belong in your portfolio. If you’re curious how this type of investment could fit into your broader plan, that’s a conversation worth having.
You’ve both managed money successfully before. You’re professionals, homeowners, and financially stable. So why does talking about money together feel so much harder than it should?
In blended families, money isn’t just financial—it’s relational. Each of you brings financial beliefs shaped by different experiences: how you were raised, what your first marriage taught you, what felt safe or risky during the years you were on your own. These beliefs run deep, and they don’t always surface until you’re making decisions together.
The challenge isn’t that one person’s approach is right, and the other’s is wrong. It’s those assumptions about fairness, responsibility, and what money should do that often go unspoken until a decision forces them into the open. When that happens, what looks like a disagreement about numbers is actually a clash of unexamined values.
Traditional financial planning assumes alignment and moves quickly to strategy. But in blended families, that sequence gets it backward. The hard part isn’t the math—it’s the conversations that clarify what you’re building together. When those conversations happen first, the financial decisions become clearer because you’ve defined the direction.
Understanding What Drives Your Financial Choices
In any relationship, you don’t want to lose sight of who you are as an individual. While marriage calls two people to come together as a strong partnership, it also requires honoring each person’s unique experiences, perspectives, and priorities.
Examining your money values helps you do exactly that. It clarifies what drives you financially and reveals the motivations behind both your best decisions and your most challenging ones. Someone who experienced financial instability in their first marriage might prioritize emergency savings above everything else. Another person who managed fine as a single parent might feel more comfortable taking calculated risks or spending on experiences today.
Neither perspective is right or wrong. They’re protective responses to different stories.
But in blended families, those protective instincts can collide in unexpected ways. What feels like financial caution to one spouse can feel like resistance to the other. What looks like generosity might feel like favoritism. Understanding your own values gives you the language to explain what’s driving a decision and helps your spouse see it as protection, not rejection.
When you can name what money means to you, conversations shift from defending positions to understanding each other.
Bringing Your Money Values Into the Open
Once you understand what drives your own financial choices, the next step is harder: sharing those beliefs with your spouse, and creating space to hear theirs.
In blended families, this isn’t a conversation about budgets or account structures. It’s about surfacing the assumptions you’ve both been carrying: what feels fair, what feels threatening, what you’re protecting, and what you’re afraid of repeating from your first marriage.
You’re navigating questions with no easy answers: How do we balance supporting your kids and mine fairly? What happens to assets you brought into the marriage? Should inheritance stay separate or become shared? What feels like protection to you but feels like distrust to me?
There’s emotional math at play—invisible calculations about loyalty, fairness, and what each of you promised yourself you’d never do again. These don’t show up on a spreadsheet, but they shape every financial decision you make together.
Traditional financial planning skips this step. It assumes alignment and moves straight to strategy. But in blended families, when assumptions go unspoken, they don’t disappear. They build consequences that surface years later as conflict or unintended outcomes.
Start by naming what money means to you and what shaped that belief—not what you think you should say, but what’s actually true. Maybe you’re still carrying fear from your first marriage. Maybe you feel protective of your kids in ways that are hard to explain. Your spouse’s perspective will be different, and that’s not a problem to solve immediately. The work here is to understand, not to convince.
Money conversations can get emotional. It’s tempting to label one partner as “bad with money” or overly cautious. But those labels shut down understanding. Don’t assume you know what drives your spouse’s choices without asking. And don’t treat your own perspective as fact while dismissing theirs as opinion.
Where you find common ground, acknowledge it. Where you see differences, don’t ignore them. The danger isn’t disagreeing—it’s leaving assumptions unspoken.
This conversation is how you move from two separate money stories to one shared direction. When you surface what you’re each building toward, the financial decisions become clearer because you’ve defined where you’re going first.
Start Creating Intentional Alignment
You don’t have to agree on every financial detail throughout your marriage. Rather than aim for perfection, build a shared understanding of how your values will be expressed in real life.
For example, you might need to clarify expectations around spending, saving, supporting children, and charitable giving. As a blended family, you may need to think deeper about inheritance planning, financial responsibilities for children from previous relationships, or how household expenses will be shared.
Understand that you won’t be perfectly aligned at every step, and that’s okay. The point is to be more intentional with your decisions and come from a place of understanding. When you know how you both feel about money and what shaped those perspectives, you create a shared sense of direction. That direction becomes your North Star. It won’t eliminate every disagreement, but it gives you a framework for making decisions together.
Knowing what you’re building together helps you measure individual choices against a bigger picture. That’s what alignment actually looks like: not identical opinions on every detail, but clarity about where you’re going and why.
Ready to Go Deeper?
Navigating money conversations in a blended family is complex, but it’s also an opportunity to build deeper understanding and alignment within your marriage.
California’s top state income tax rate of 13.3% doesn’t discriminate — it applies to wages, bonuses, investment gains, and business sale proceeds alike. But while every high earner in California faces the same tax code, not all of them pay the same amount. The ones who keep more aren’t doing anything illegal, and they don’t have access to secret strategies unavailable to others. What they do have is a deliberate, multi-year approach built around three core levers: controlling when income is recognized, structuring investments for state-level tax efficiency, and making coordinated financial decisions with long-term tax consequences in mind. Here’s how it works and why waiting until tax season to think about any of this is one of the most expensive habits a high earner in California can have.
California taxes are high. In fact, according to the Tax Foundation, Fiscal Year 2022 data show they’re second only to New York. Overall, California tax collections per capita were about $10,319, compared to a US average of $7,109.
But if you’re a high earner there, doubtless you already know this.
You may be less aware that even within the same tax system, people earning similar amounts can pay different amounts of taxes. Some even make more than others while paying less in state taxes, sometimes significantly so.
This isn’t about tax evasion, which is illegal, nor do these people try to avoid California taxes altogether, which is next to impossible for California residents. Instead, they focus on optimizing when and where income shows up, and on how different financial decisions interact and affect outcomes.
Implementing these strategies won’t let you eliminate your taxes, but it can make a big difference in how much you get to keep over a lifetime.
Key Takeaways
1
California taxes long-term capital gains the same as ordinary income — making federal tax strategies unreliable at the state level.
Unlike the federal tax code, California offers no preferential rate for long-term capital gains, which means strategies specifically designed to minimize federal taxes can fall flat — or even backfire — for California residents. High earners need a California-specific tax framework, not a one-size-fits-all approach borrowed from federal planning.
2
Stacking income events in a single tax year is one of the most expensive mistakes high earners in California make.
Bonuses, stock option exercises, RSU sales, and business sale proceeds hitting in the same calendar year can push high earners into California’s steepest marginal tax brackets — a self-inflicted tax problem that proactive income timing can often prevent. Spreading these events across multiple years, when feasible, can meaningfully reduce the effective rate paid on that income.
3
The highest-impact California tax strategies — including direct indexing, municipal bonds, and multi-year deferral planning — require ongoing coordination, not a once-a-year tax filing mindset.
Tools like direct indexing (which harvests losses even in up markets), California municipal bonds (exempt from both federal and state taxes), and long-term deferral vehicles such as cash balance plans and deferred compensation can dramatically reduce lifetime tax drag — but only when implemented consistently and coordinated across your financial advisor and CPA well before year-end.
Why California Tax Strategies Are Different and Why That Matters for High Earners
Not only are California taxes higher than almost any other state’s, but they’re also broader than most. For example, there are no preferential tax rates for long-term capital gains (LTCG).
When
marginal rates are high,
income is broadly taxed, and
there’s limited preferential treatment,
many common tax-reduction strategies stop working. In fact, some can even backfire. This is why the gap between managing and optimizing taxes vs. just paying them tends to be wider in California than in most other states.
The Most Common California Tax Mistakes High Earners Make
So, if it isn’t about tax evasion, generic tax tips, or access to some secret tools, how do certain high earners optimize their taxes better than others?
First, most high earners don’t ignore taxes, but they do tend to focus mostly on maximizing their earnings. They evaluate compensation, bonuses, and business-sale windfalls based on how large they are.
They think of taxes, but often as a secondary consideration.
In California, as in other high-tax states, income timing can be crucial. Having multiple one-time income spikes in a single year can push you into higher tax brackets.
That makes your taxes more expensive.
Second, many assume that the same strategies they use to optimize federal taxes work equally well for state taxes.
In California, some, but not all, do.
Here’s one example that doesn’t.
If you’re a high earner, concentrating long-term capital gains in a taxable portfolio lets you pay significantly lower federal income tax on them than placing them in a tax-deferred account, such as a traditional IRA.
California, however, taxes long-term capital gains the same as wage income, so strategies built around long-term holding periods for federal purposes don’t carry the same state-level benefit.
Third, people only think about taxes when it’s time to file, when it’s already too late to do much optimizing. Or, at best, they think about them one year at a time.
That’s understandable, since that’s how we report our income and pay our taxes.
But this is far less powerful than multi-year tax planning. If you have an especially high income in a single year, you’ll get pushed into the higher tax brackets of California’s progressive tax system, which would extract much higher taxes than if you could spread the excess income over two or more years.
While these patterns are understandable, not evidence of carelessness, they won’t let you achieve the optimal results you want.
You need a different approach for that.
3 Proven Strategies High Earners Use to Reduce California State Taxes
In California, there are 3 main ways you can optimize your lifetime taxes.
Time Your Income to Avoid California’s Highest Tax Brackets
Build State Tax Efficiency Into Your Investment Portfolio
Plan Taxes Across Years, Not Just Tax Seasons
Here’s how they work.
1. Time Your Income to Avoid California’s Highest Tax Brackets
Here, your power move is combining two ideas, income timing and the resulting tax rates.
In a high-tax state like California, this is connected even more tightly than in other states.
Beyond “base” income, high earners often have other large compensation sources (Table 1).
Bonuses.
Exercised stock options.
Significant realized investment gains, e.g., when selling Restricted Stock Units (RSUs) at highly appreciated prices.
Selling (part or all of) a business.
Table 1. Events that can spike your income and what you can consider doing about them.
When several of these get stacked in a single tax year, you may get pushed into higher marginal tax brackets, forcing you to pay a larger fraction of your income in taxes.
Dr. Steven Crane, Founder of Financial Legacy Builders, agrees, “The biggest mistake I see is people focusing only on how much they make, not when and where it’s taxed. California is aggressive, and if you stack income in one year, bonuses, stock sales, and business income, you can get hit far harder than expected. A lot of high earners don’t realize they’re creating their own tax problem just through timing.
“The people who plan ahead keep more. The ones who react usually pay more. California taxes success aggressively, but it doesn’t mean you’re stuck. The key is realizing that taxes aren’t just something that happens to you; they’re something you can plan around. Most of the damage I see isn’t from bad investments, it’s from unplanned tax events that could have been managed with a little foresight.”
That’s why smart high earners try, when they can, to spread these events across multiple years. This doesn’t let them avoid the tax, but it does let them pay at least somewhat lower taxes on the same income.
A similar notion shows up in picking what retirement accounts to contribute to.
Roth accounts, both IRA and 401(k), are attractive because they let you pay taxes now on your contributions, but avoid paying any taxes on withdrawals, even when the majority of the withdrawn money is investment gains.
That makes sense in some situations.
But when your current marginal tax rates are very high, that’s an expensive choice. One that doesn’t usually optimize your long-term results.
As Joe Stabile, Founder at Coast Financial, explains, “A common mistake I see many high earners in California make is blindly choosing to fund Roth retirement accounts. While Roth accounts have their benefits, it’s important to realize that your top marginal tax rate in California, between federal and state, can be 50.3%, which means any income you can defer at this level to future years, where your effective rate is lower, is extremely powerful. Deferral strategies can include 401(k) plans, HSAs, deferred compensation plans, cash balance plans for business owners, and more.”
The key here is that by contributing to a tax-deferred account, rather than a tax-now account like a Roth, you can pay taxes later, when your marginal tax bracket may be lower.
This will often reduce your lifetime taxes, even with the same lifetime income.
If, like me, you’ve put most of your long-term savings into such tax-deferred accounts, you may be unhappy that all withdrawals, including money that originated from long-term capital gains, get taxed at regular income tax rates, rather than at preferential LTCG rates.
In states like California, where LTCG is taxed the same as regular income, the negative impact of this is smaller than in states that treat LTCG preferentially, as do federal taxes.
Tushar Kumar, Founder, Twin Peaks Wealth Advisors, has a different perspective, “The number one mistake I see high taxpayers in California making is not maxing out all of the tax-advantaged buckets at their disposal. Most of my clients max out their 401(k) contributions, but many overlook the Mega Back Door Roth 401(k) option. Most of my clients make some contributions to 529 accounts, but many don’t max them out or don’t take advantage of the super-funding rules. Most people don’t understand how much money they are leaving on the table by not maxing out these accounts.”
How California treats the 529 college savings plan is different from many other states. There is no state tax deduction for contributions made to these plans, but qualified withdrawals are tax-free.
Ajay Vadukul, CFP®, EA, Vice President of Endeavor Advisors, also sees Roth accounts as a useful tool, “Roth conversions are a conversation we start early, too, since California offers no special treatment for retirement distributions. Converting in lower-income years before Required Minimum Distributions (RMDs) kick in reduces your long-term burden at both levels.”
2. Build State Tax Efficiency Into Your Investment Portfolio
Next up is how you structure your investments.
Not all income sources get taxed the same, which you can use to your benefit.
For example, as Ray Prospero, Partner Advisor, AdvicePeriod, details, “My practice is geared toward the high-net-worth space, and two of the tax-mitigation strategies I like to explore for my high-income California clients are municipal bond ladders and direct indexing.
“Municipal bond ladders can generate consistent, tax-advantaged income while managing interest rate risk by holding individual bonds with staggered maturities. On the equity side, direct indexing gives us more control. By owning the individual stocks within an index, we’re able to harvest losses throughout the year, even in up markets, while staying broadly aligned with overall market performance. Those losses can then be used to offset capital gains and potentially reduce a portion of taxable income.
“When combined, it can be an effective way to potentially enhance tax efficiency while maintaining a disciplined, long-term investment strategy.”
Kumar agrees, “I see many California residents sitting on cash in high-yield savings accounts or money market funds when they could be considering California muni bonds for tax-free yield. Of course, there is a risk trade-off there.”
As this demonstrates, you can and should build tax efficiency, especially at the state level, into your portfolio structure.
Income from municipal bonds is exempt from federal and, for bonds issued by California public agencies, state taxes.
Direct indexing lets you harvest losses even when the index is up. That’s because there are almost always some companies in the index with depressed prices, even in a bull market. This means you can sell those shares to capture a loss, without selling the entire index, which may be at a higher price point than when you bought in.
Then, when enough time has gone by so it isn’t a wash sale, you can buy back those shares to reestablish the full index.
Doing this consistently, not as a once-and-done exercise, provides long-term tax benefits. That’s why you should make a point of it, even if you’re busy.
3. Plan Taxes Across Years, Not Just Tax Seasons
Yes, income is reported, and taxes are paid on an annual basis.
But that doesn’t mean that’s the optimal way to plan. The most effective tax strategies play out over years or even decades and help guide and coordinate decisions across multiple aspects of your financial life.
As James Selu, CFP®, CEPA®, CBDA®, President & Founder of Palm Coast Wealth Management, says, “One of the biggest mistakes high earners make is waiting until tax season to think about taxes. By the time you’re preparing a return in March or April, the tax year is already over, and many of the best planning opportunities are gone. At that point, you’re often limited to reporting what happened rather than improving it.”
This is where long-term planning becomes critical.
Advanced tax planning for higher-net-worth households looks five, ten, twenty, or even more years into the future, rather than focusing on the next Tax Day.
These strategies include various trusts, permanent insurance, annuities, charitable giving vehicles, and more, with each family’s situation calling for a different set of tools, implemented in a tailored way.
Selu again, “Depending on the client’s situation, strategies may include maximizing retirement plan contributions, Roth conversions in lower-income years, tax-loss harvesting, charitable giving, municipal bond strategies, deferred compensation planning, or repositioning assets into more tax-efficient investments. The right strategy depends on how someone earns income: W-2 wages, business income, stock compensation, real estate, or investments.”
Vadukul expands, “The biggest mistake high-earning Californians make is treating state taxes as a fixed cost instead of a planning opportunity. With California’s 13.3% top rate, there’s real leverage available. You just have to use it.
“For clients who are charitably inclined and over 70½, qualified charitable distributions from your IRA are one of the cleanest tools available, reducing your Adjusted Gross Income (AGI) at both the federal and state level in one move. If you’re sitting on appreciated stock, gifting shares to children in a lower bracket rather than selling yourself can dramatically cut the capital gains bill.
“On the deferral side, maxing your 401(k) is table stakes, but self-employed clients and business owners should be looking at solo 401(k) plans or cash balance plans, which can shelter hundreds of thousands annually. An S-corp election is also worth revisiting for the right business owner. And for clients facing a large capital gains event, Qualified Opportunity Zone investments can defer and potentially reduce that exposure in ways most people haven’t considered.”
None of this implies that you, or even a financial advisor, can predict the future with any guaranteed accuracy.
However, planning over the long term gives you a better chance of success than focusing on the current tax year, or worse, on the previous one.
Taken together, these three levers don’t eliminate state taxes, but they do let you optimize how you position yourself, which determines how efficiently you can maximize your lifetime take-home money.
The Bottom Line: California Taxes Are High, But Your Lifetime Tax Bill Isn’t Fixed
Whatever you think or feel about California’s high state income taxes, if you live there and earn a high income, they’re a major, unavoidable factor in your financial picture.
Some people suggest moving out of California because of this.
Moving to a lower-tax state can indeed reduce your tax burden, but you should only consider it if it makes sense for your overall life. And even then, California’s residency rules mean the timing and structure of that move matter. If it looks temporary or primarily tax-driven, you may not achieve the outcome you expect.
Vadukul agrees, “Something I only half-joke about with clients: one of the most effective California tax strategies is leaving California. Texas, Nevada, Florida, Arizona. The savings can be $50,000 a year or more for a high earner. But there are things money can’t buy. Family, community, California’s business ecosystem. I’ve had clients look at that number and say, ‘still worth it to stay,’ and that’s a completely legitimate answer. The goal is to make sure the decision is informed, not to let the tax tail wag the life dog.”
For most people, you can get the results you want from planning, without needing to relocate. From not treating taxes as something you deal with once a year for a few weeks, but rather planning and managing them continuously, even if you’re busy with your career and family.
As Selu puts it, “Successful professionals are so busy building careers or businesses that tax planning gets pushed aside. Unfortunately, California’s high state tax rates can make procrastination expensive. Without proactive planning, people often miss opportunities to manage income timing, harvest losses, maximize retirement contributions, or structure investments more efficiently.
“Tax planning should be ongoing, not seasonal. The earlier you plan, the more options you tend to have. The most valuable habit a high earner can have in this regard is scheduling a coordinated year-end tax planning meeting with both their financial advisor and CPA before December 31. That gives you time to evaluate what happened during the year and make adjustments while there’s still time to act.
“California taxes may be high, but with proactive planning, coordination, and discipline, you can often reduce unnecessary tax drag and keep more of what you earn.”
Crane sums it up, “The most effective strategies usually come down to control. Control when income hits, diversify how it’s taxed, and be intentional about where you live and work. That might mean spreading income across years, using tax-deferred and tax-free buckets, or even thinking seriously about residency if it aligns with your life.”
It’s simple, but not necessarily easy to implement:
Taxes aren’t just something you file. They’re something you manage.
Ongoingly.
And in a high-tax state like California, small, consistent improvements in how you manage them can add up to a noticeable difference in what you keep over a lifetime.
Are You Ready to Hire a Financial Advisor?
You’ll find a growing number of financial advisors featured on Wealthtender. You can search based on the areas of specialization most important to you and where they’re located, or browse our financial advisor directory for more search options to find advisors who may be a good fit for you.
Find Your Next Financial Advisor on Wealthtender
📍 Click on a pin in the map view below for a preview of financial advisors who can help you reach your money goals with a personalized plan. Or choose the grid view to search our directory of financial advisors with additional filtering options.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
About the Author
Opher Ganel, Ph.D.
My career has had many unpredictable twists and turns. A MSc in theoretical physics, PhD in experimental high-energy physics, postdoc in particle detector R&D, research position in experimental cosmic-ray physics (including a couple of visits to Antarctica), a brief stint at a small engineering services company supporting NASA, followed by starting my own small consulting practice supporting NASA projects and programs. Along the way, I started other micro businesses and helped my wife start and grow her own Marriage and Family Therapy practice. Now, I use all these experiences to also offer financial strategy services to help independent professionals achieve their personal and business finance goals. Connect with me on my own site: OpherGanel.com and/or follow my Medium publication: medium.com/financial-strategy/.