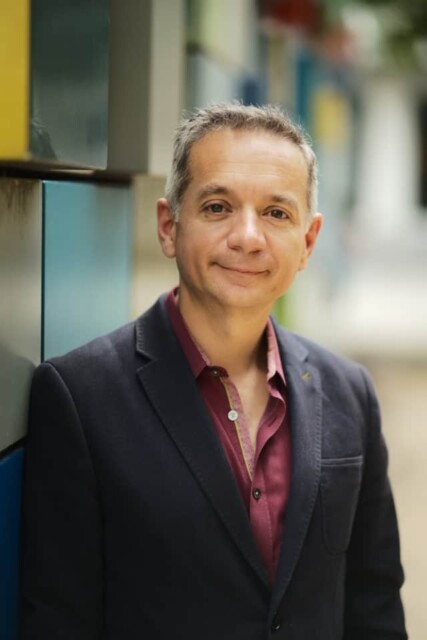
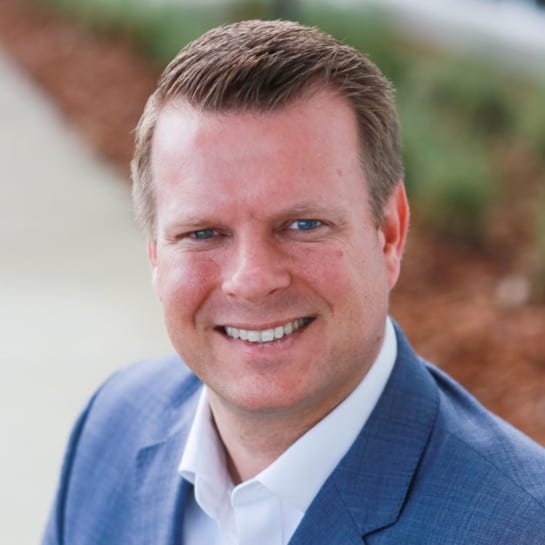
Dan Sondhelm of Sondhelm Partners | Image Credit: Institute for Innovation Development
[The birth of a new ETF is an incredibly exciting time for asset managers but also a treacherous endeavor if strategic planning around the launch is not fully thought-out, developed, and implemented. For many managers, enthusiasm can lead to an optimistic “if we build it, they will come” mindset; a focus on the actual launch as the endpoint (not just the beginning); and the expectation of a natural siphoning-off of the surging growth in ETF assets.
The reality is that despite the surging growth of global ETF assets reaching a record $23.09 trillion through June 2026 and attracting $1.33 trillion of net inflows (the highest first-half total on record), the top three sponsors (iShares/BlackRock, Vanguard, State Street) controlled about 59% of global ETF assets, despite more than 1,000 ETF providers globally.
It is also important that managers track how fast the market now closes funds that fail to gather assets. Nearly 1,000 active ETFs were launched in 2025, while 146 active ETFs (a record high) and 86 passive ETFs were liquidated. ETF issuers are shutting products at the fastest pace in years, and the average lifespan of an ETF liquidated in 2026 has fallen to one year and nine months, down from three and a half years in 2025 and nearly five years in 2024, according to Bloomberg Intelligence, as reported by Wealth Management. Issuers increasingly set an explicit clock, closing a fund that is not gaining traction within 12 to 18 months and recycling the resources.
Cerulli also found that since 2021, more than 85% of ETF closures have involved funds with less than $50 million in assets, and that this proportion reached 92% in 2025. They similarly noted that issuers are becoming quicker to shut down products that fail to gather assets and warned that the rapid proliferation of new strategies increases the risk of a future “closure wave.”
To better understand the current ETF marketplace dynamic and strategic decisions needed behind successfully launching and growing a new ETF, we reached out to Dan Sondhelm of Sondhelm Partners. Dan brings 30 years of experience in marketing and sales for asset managers, including ETF sponsors, and built Sondhelm Partners over the past 10 years; helping boutique managers and RIAs get noticed, earn distribution, and gather assets. His firm was shortlisted for PR Campaign of the Year in the 2026 “With Intelligence Mutual Fund and ETF Awards” and as Best PR and Communications Firm in the 2024 “ETF Express US Awards”. We asked Dan to share his perspectives and experiences in helping firms launch their ETFs and knowing what strategic decisions they have to make.]
Hortz: What do ETF sponsors most underestimate?
Sondhelm: They underestimate how hard it is to get noticed. A good strategy isn’t enough. Most first-time sponsors assume that a better product will find its own audience, and that assumption costs them more than anything else they get wrong.
Firms spend months designing ETFs and almost no time on how anyone finds them. Shelf space is limited. Gatekeepers control access, and getting approved does not mean money follows. What determines whether an ETF works is decided long before performance means anything, and most of it is marketing, distribution, and patience.
The other problems compound from there. Sponsors underestimate how long distribution takes, so their asset targets are wrong from day one. They do not account for how crowded the category is, so a strategy that feels distinctive to them looks interchangeable to an investor. They budget for the launch and not for the years after it, which is when assets are actually gathered. And many of them are entering a market they have never sold into, with a sales approach built for a different buyer.
Hortz: With the top three sponsors controlling nearly 60% of ETF assets, how does a boutique firm compete against that?
Sondhelm: You don’t. Not on their terms. If you are trying to win the same broad-market allocation that goes to a three-basis-point S&P fund, you have already lost, because that decision was made years ago and it was not about you.
What a boutique has is the ability to be the best answer to a narrow question. The large sponsors are built for scale, which means a strategy that could gather $200 million is not worth their attention. For you, that’s a business. The question is what you can own that BlackRock has no reason to want.
Advisors also are not looking for another large-cap fund. They are looking for the piece of the portfolio they cannot fill with something obvious, and that is where a specialist manager gets considered. But they have to know you exist first, which is the part most boutiques underestimate. The big firms have distribution, brand, and a wholesaler in every territory. You have your expertise and whatever visibility you are willing to build. That’s a fair trade only if you build it.
Hortz: Why do so many ETFs fail to stand out?
Sondhelm: Most of them are not as different as their managers think. You built the strategy, so the distinction is obvious from where you sit. The advisor or the gatekeeper, on the other hand, is looking at your fund next to hundreds of alternatives, and from that seat it often disappears. Before you launch, you should be able to answer three questions in one sentence each:
Why does this ETF exist?
What investor problem does it solve?
Why doesn’t another ETF already solve that problem?
I sat with a manager once who spent the first twenty minutes of our meeting explaining why his fund was different. He was right. His process weighted holdings by something no one else in his category was using, and by the end I understood why it mattered. Then I asked him to say it in a sentence, and he couldn’t. He kept starting over and reaching for another chart. That fund had a real edge and no way to hand it to anyone. An advisor gives you thirty seconds. A gatekeeper skimming a one-pager gives you less. Whatever does not survive that trip is, in practical terms, not a differentiator.
The second reason is that performance does not speak for itself. Managers wait for the numbers to make the case, and the numbers cannot do it alone. Nobody buys or recommends a fund they have never heard of, and the advisors who have heard of it still need to understand where it fits in a client portfolio before they will use it. That takes education, visibility, and time, and none of it happens on its own.
Hortz: How early should marketing begin, and how much should it shape the product itself?
Sondhelm: Marketing should begin before the fund exists, not after it launches. The mistake I see most is a firm building the ETF first and then asking who it’s for. By then the decisions that determine whether it sells are already locked in.
What makes ETFs different is that many firms launching one are adding a new line of business. They already run wealth management or asset management and have never brought an ETF to market. The strategy, the process, and the people are often the same. The market is not. Advisors and retail investors buy ETFs in a completely different way than high-net-worth clients buy holistic wealth management, or institutions buy money management. Same firm, same expertise, but a new buyer with a different process.
That is where marketing has to shape the product, not just promote it. Before you file, you need to know the niche you are serving, who actually puts it in a portfolio, and how you grow it beyond the founder, friends, family, and existing clients who seed most launches. That last question is the one firms skip, and it’s the one that determines whether the fund gets past its first $20 or $30 million. The answers often change the fund itself, how you position the strategy, who you build it for, even the name and ticker.
And you have to be honest about the team. A firm that has sold wealth management or institutional strategies for years may have no one who has sold an ETF. The sales and marketing muscle for this market is different, and most firms launching their first ETF do not have it yet.
Hortz: What are the issues that ETF sponsors need to be aware of in dealing with industry investment gatekeepers?
Sondhelm: Gatekeepers matter more than investors. ETF marketing is mostly a gatekeeper problem, and the gatekeepers are RIAs, wirehouses, broker-dealers, TAMPs, model portfolio platforms, and due diligence committees. The end investor is rarely your first customer. The gatekeeper is.
Approval also takes far longer than sponsors expect. They plan in weeks. It often runs months, sometimes past a year. Asset targets built on the shorter timeline are wrong before anyone starts.
Part of it is timing. Part of it is whether they will add the fund at all. Gatekeepers do not have unlimited shelf space, so they weigh why they would take on your ETF and whether it earns a spot. A minimum asset level is common, and $100 million is a familiar bar. But clearing it guarantees nothing. Plenty of $100 million ETFs never get on, because every platform sets its own criteria. On some platforms, a new fund only gets added if a similar one comes off to make room. The analysts do their homework, but their process runs on limited shelf space, not on your launch timeline.
One ETF we worked with had about $90 million and was talking to a large wirehouse whose minimum was $100 million. The founder added enough to clear it and was on the platform within three months. Not every founder can do that. Sometimes the difference between shortlisted and approved is a business decision, not a marketing one.
So, build the relationship before you need the approval. Gatekeepers are evaluating the firm and the people behind the fund, not just the track record.
Hortz: Can you walk us through your approach to marketing an ETF?
Sondhelm: Start by owning a topic. Pick the area where you have something to say that other managers do not and become the person advisors associate with it. Then teach rather than sell. Explain the problem the strategy solves, what you see in the market, why you built the fund the way you did. Articles, videos, guides, interviews, webinars, all of it works. The format matters less than whether an advisor comes away understanding something new.
That content starts on your website. Your site is the one channel you control, and everything else should point back to it. From there it moves out to where advisors already spend their time, whether that’s LinkedIn, industry publications, podcasts, or their inbox.
Search is what makes any of it findable. Most advisors research a problem long before they know your fund exists, and more of them now ask an AI assistant instead of typing into Google. If your content answers the question they are asking, you appear in both places, and every article and mention builds the reputation that search engines and AI tools read when they decide who to cite.
PR does something your own content cannot do for you. A quote in a trade publication or an interview with a reporter is a third-party vouching for you, and advisors weigh that differently than anything on your website. It builds visibility and credibility at the same time.
All of this serves one purpose. The advisor, the investor, and the gatekeeper each take months to decide, and they rarely tell you where you stand. What you are doing in between is staying in front of them, so that when they are ready to act, or when the due diligence committee finally gets to your fund, you are familiar rather than unknown. If you have salespeople, this is what supports them. Marketing keeps touching the prospect when your sales team isn’t in the conversation, and each new piece gives them a reason to reach out that is not just checking in.
Then measure. A tech stack like HubSpot lets you see engagement, click-through, lead quality, how people move through your site, and what each campaign returns. That data tells your salespeople when to call. An advisor who just read two pieces on your strategy and opened your last email is a different prospect than one who has not touched anything of yours in six months.
Hortz: What do you believe most separates the ETF sponsor winners from the losers?
Sondhelm: Commitment to engaging the audience. You can usually tell which group a sponsor belongs to within the first year, and it has almost nothing to do with performance.
They can say why the fund exists in one sentence. Instead of chasing every channel at once, they pick one and go deep. Gatekeeper relationships get built before the approval is needed. And, the marketing keeps running for years, because that is how long it takes.
The ones that struggle expect the numbers to do the selling. They copy a strategy that already exists, wait until after launch to think about marketing, and expect assets on a timeline nobody in distribution would recognize. When the flows don’t come in the first year, they decide the market rejected the fund. Usually, the market never knew it was there.
Hortz: Any final advice for a firm getting ready to launch its first ETF?
Sondhelm: Portfolio construction matters far less than most sponsors think. What matters is whether anyone knows the fund exists. Whether they understand the problem it solves. Whether they can buy it at all. Most sponsors budget for the first year and assume the rest will take care of itself.
In a market this crowded, your marketing, your brand, and your message are what get you seen at all. Plan the launch like a three-year business build, not a product release.
Bill Hortz is an independent business consultant and Founder/Dean of the Institute for Innovation Development- a financial services business innovation platform and network. With over 30 years of experience in the financial services industry including expertise in sales/marketing/branding of asset management firms, as well as, creatively restructuring and developing internal/external sales and strategic account departments for 5 major financial firms, including OppenheimerFunds, Neuberger&Berman and Templeton Funds Distributors. His wide ranging experiences have led Bill to a strong belief, passion and advocation for strategic thinking, innovation creation and strategic account management as the nexus of business skills needed to address a business environment challenged by an accelerating rate of change.
Divorce in your 40s and early 50s occupies a specific financial territory that does not get discussed enough. You are not in your 30s, when the asset base is smaller and the runway to rebuild is long. And you are not in your late 50s or 60s, where the gray divorce conversation addresses concentrated retirement wealth and compressed timelines.
Mid-life divorce tends to involve something more complicated: real assets and real consequences, but also real time to recover, provided the financial decisions made during and immediately after the divorce are sound. Children may still be in the household. One spouse may have stepped back from a career. Retirement accounts have had 15 to 20 years to grow but are still in the accumulation phase. The family home may carry both equity and emotional weight.
The financial decisions made in the first 90 days after a divorce is final have consequences that extend for decades. This checklist is designed to help you navigate them clearly.
If you are divorcing after 55, our companion piece Gray Divorce: 5 Financial and Tax Considerations for Couples Over 50 addresses the specific dynamics of that situation. If you are planning a second marriage after this one, the financial planning considerations around prenuptial agreements are covered in Prenuptial and Postnuptial Agreements: What a Financial Planner Brings to the Conversation.
Why Mid-Life Divorce Is Financially Different
Most financial guidance around divorce falls into two camps: the general checklist aimed at anyone, which glosses over the specific stakes, or the gray divorce conversation aimed at couples over 55 with 30 years of joint wealth to untangle. Divorcing in your 40s or early 50s involves a distinct set of pressures.
You likely have dependent children, which means child support, education funding, and the question of who keeps the family home and at what long-term cost. You have had enough working years to build meaningful retirement savings, but those accounts are not yet fully formed. A division that looks equitable on paper today may look very different by the time you actually retire.
You also face a Social Security calculation that changes when a marriage ends. The 10-year marriage rule for divorced spousal Social Security benefits is a meaningful planning variable, and whether you are approaching that threshold or already past it affects your long-term income picture in ways worth understanding before any settlement is finalized.
The bottom line: mid-life divorce requires financial analysis specific to your situation, not a generic checklist. An advisor with the Certified Divorce Financial Analyst designation is trained specifically for this work. For more on what to look for in a financial advisor during a divorce, see How to Find a Fiduciary Financial Advisor: What the Title Really Means and What to Ask.
The First 30 Days: Stabilize Your Financial Footing
Get a Complete Inventory of All Marital Assets and Liabilities
This includes every account you know about and every account you should know about. Retirement accounts at current and former employers, brokerage accounts, bank accounts, real property, business interests, deferred compensation, stock options, pension entitlements, outstanding loans, and credit card balances. Compile statements covering the last three years at minimum.
In Minnesota, both spouses are entitled to full financial disclosure. If you were not the spouse who managed finances during the marriage, this inventory may reveal accounts or obligations you were not aware of.
Open Individual Accounts in Your Name Only
If your banking and credit have been primarily joint, establish individual accounts immediately. You need a checking account, a savings account with an emergency fund target, and at least one credit card in your name only. Building your own credit history and financial identity is not aggressive. It is necessary.
Do not drain joint accounts unilaterally. Courts take a dim view of one spouse liquidating marital assets before or during proceedings. Transfer only what is reasonable for your living expenses.
Review Your Credit Report
Pull reports from all three major bureaus and review every account listed. Joint accounts, authorized user relationships, and any debt your spouse holds in their name only can affect you depending on how the settlement is structured. Know what is there before your attorney starts negotiating.
Locate and Secure Key Documents
Tax returns for the past three years, recent pay stubs for both spouses, mortgage statements, retirement account statements, insurance policies, and any business ownership documents. Store copies somewhere only you can access.
The Settlement Phase: What You Take Matters More Than What It’s Worth Today
The most common financial mistake in divorce settlements is evaluating assets at their current value without accounting for the tax and liquidity implications of actually using them. A CDFA is trained specifically to catch these gaps.
Not All Retirement Accounts Are Equal
A traditional 401(k) with a $200,000 balance is not worth $200,000 to you. It is worth $200,000 minus the ordinary income tax you will pay when you withdraw it, which depending on your bracket could mean $140,000 to $160,000 in actual purchasing power. A Roth IRA with a $200,000 balance is worth $200,000 after tax, since qualified withdrawals are tax-free.
Agreeing to receive a greater share of pre-tax retirement accounts in exchange for giving up other assets can look like a good deal and turn out to be an expensive one. Make sure any settlement comparison is done on an after-tax, apples-to-apples basis. For more on how Roth and pre-tax accounts behave differently over time, see Is a Roth Conversion Right for You?
The House Is Usually More Complicated Than It Looks
Keeping the family home is often driven by the children’s stability, which is a real and legitimate consideration. But the financial reality deserves a clear-eyed look. Can you carry the mortgage, property taxes, insurance, and maintenance on a single income? If doing so requires giving up retirement account contributions or building no cash reserve, the math may not work long-term. The house is an illiquid asset. Retirement savings are portable and compounding. Trading one for the other at 44 has consequences you will feel at 64.
If you do keep the home, understand the capital gains implications when you eventually sell. As a single filer, you can exclude up to $250,000 of gain. As a married couple, the exclusion is $500,000. A home with significant appreciation may carry a meaningful tax liability on a future sale that was invisible during the marriage.
Understand the QDRO Process Before You Sign Anything
Employer-sponsored retirement plans require a Qualified Domestic Relations Order to divide the account without triggering taxes or penalties. A QDRO is a separate court order that must be drafted, reviewed by the plan administrator, and executed correctly. It is not automatic, and it is not the same as what is written in the divorce decree.
A common error is finalizing a divorce with language that specifies a retirement account division but failing to execute the QDRO afterward. Years later, when the account owner dies or the plan changes, the non-participant spouse may have no recourse. Do not let the QDRO be an afterthought.
The 10-Year Social Security Rule
If your marriage lasted at least 10 years, you may be eligible to claim Social Security benefits based on your ex-spouse’s earnings record. This benefit is up to 50% of their full retirement age benefit and does not reduce what they receive. If you are approaching the 10-year mark, the timing of finalizing a divorce is worth discussing with a financial advisor. A few months can make a meaningful difference in your long-term income options. For more on how Social Security strategy works for divorced individuals, see The Social Security Bridge Strategy: How to Maximize Lifetime Income by Delaying Benefits.
Education Funding Needs to Be Addressed Explicitly
If you have children who will attend college, who pays and in what proportion should be addressed in the settlement, not left to figure out later. In Minnesota, courts can address post-secondary educational support, but what is in the agreement matters. Do not assume it will work itself out.
The 90-Day Reset: Rebuilding Your Financial Plan
Update Every Beneficiary Designation Immediately
Retirement accounts, life insurance policies, and annuities pass to named beneficiaries regardless of what your will says. Divorce does not automatically change these designations in all cases. An ex-spouse left on a 401(k) beneficiary form may receive that account when you die.
Update beneficiary designations on every account as soon as the divorce is final. Then check again in 30 days to make sure the updates processed correctly. For the full set of documents that need updating after a major life transition, see The Legacy Planning Checklist: 7 Documents You Can’t Ignore.
Rebuild Your Emergency Reserve
The settlement process, legal fees, and the transition to a single-income household often deplete cash reserves. Before directing money anywhere else, build a buffer of three to six months of living expenses in an accessible account. If your income is variable or you are self-employed, aim for the higher end of that range.
Recalibrate Your Retirement Savings Rate
Your retirement picture just changed. The assets you will retire on are different than what you modeled as a couple. Your expected Social Security benefit may change depending on your earnings history and whether you qualify for divorced spousal benefits. Your projected expenses in retirement are different.
Run a new retirement projection based on your actual situation as a single filer. For 2026, the 401(k) elective deferral limit is $24,500. If you are 50 or older, an additional catch-up contribution of $7,500 is available. Clients who are not maximizing available contribution room are leaving meaningful tax advantages on the table.
Revisit Your Insurance Coverage
Health insurance is the most immediate issue if you were covered under a spouse’s employer plan. COBRA continuation coverage is available for up to 36 months but is expensive. ACA marketplace plans may offer better options depending on your income.
Disability insurance, which protects your earning capacity, is the most underowned form of coverage and often the most important for a single-income household. Life insurance needs also change after divorce. If you have children who depend on your income, adequate coverage is not optional.
Revise Your Estate Plan
Your will, powers of attorney, healthcare directive, and trust documents likely need to be rewritten. Treat your estate plan as a complete rebuild after divorce, not a quick update. For a full list of the documents that need review, see The Legacy Planning Checklist: 7 Documents You Can’t Ignore.
A Note on Finding the Right Advisor
The clients who come through mid-life divorce in strong financial shape are the ones who built a team: a divorce attorney who handled the legal process, a financial advisor with CDFA training who modeled the long-term implications of settlement options, and a CPA who understood how filing status, asset transfers, and support payments would affect their taxes.
For guidance on what to look for in a financial advisor, including how to verify fiduciary status and why the CDFA designation specifically matters in a divorce context, see How to Find a Fiduciary Financial Advisor: What the Title Really Means and What to Ask.
Planning for What Comes Next
Once the immediate financial stabilization is complete, a broader planning conversation becomes possible. Many clients navigating mid-life divorce eventually think about remarriage. If that is on the horizon, the financial planning around a prenuptial agreement is worth understanding early, not as a signal of pessimism but as a form of clarity. We cover the full financial dimension of that process in Prenuptial and Postnuptial Agreements: What a Financial Planner Brings to the Conversation.
Frequently Asked Questions
Q1: Do I need a financial advisor or just an attorney for my divorce?
You need both, and they serve different functions. An attorney handles the legal process. A financial advisor, particularly one with the CDFA designation, analyzes the long-term financial implications of settlement options, helps you understand the after-tax value of what you are receiving, identifies issues your attorney may not catch, and helps you rebuild a plan once the process is complete.
Q2: What is a CDFA and how is it different from a regular financial advisor?
A Certified Divorce Financial Analyst is a financial professional with specialized training in the financial dimensions of divorce: after-tax evaluation of asset divisions, QDROs, Social Security implications, the tax treatment of support payments, and how to rebuild a financial plan post-divorce. Mitchell J. Thompson holds the CDFA designation and works with divorcing clients throughout the planning and rebuilding process.
Q3: Should I keep the house or take the retirement accounts?
This is one of the most consequential decisions in a mid-life divorce settlement, and the right answer depends on your specific situation. The house is illiquid, carries ongoing costs, and may trigger capital gains tax on a future sale. Retirement accounts are invested, portable, and compounding. Many people who take the house at the expense of retirement savings find themselves asset-rich and cash-constrained in their 50s and 60s. Modeling both scenarios with full cash flow and tax projections over a 20-year horizon, rather than comparing today’s values on paper, is how you make this decision well.
Q4: How does divorce affect my ability to claim Social Security?
If your marriage lasted at least 10 years and you have not remarried, you may be eligible to claim Social Security based on your ex-spouse’s earnings record, up to 50% of their full retirement age benefit. Your claiming does not affect what they receive. Timing your claim relative to your own full retirement age affects the amount. See The Social Security Bridge Strategy for more on how this interacts with your broader retirement income plan.
Q5: I was out of the workforce for several years during the marriage. How do I restart financially?
Start with a complete picture of what you have, then build in order: emergency fund, then maximize any employer retirement plan match, then address insurance gaps. If returning to full-time work is part of the picture, factor in the income ramp-up timeline in your projections. Many people in this situation also need to rebuild their credit history, which takes 12 to 24 months of consistent on-time payments on accounts in their name.
How to Find a Fiduciary Financial Advisor: What the Title Really Means and What to Ask
Conclusion
Mid-life divorce is financially disruptive in ways that take time to fully understand. The decisions made during the process and in the months that follow determine whether you rebuild on a solid foundation or spend the next decade undoing avoidable mistakes.
The good news is that divorcing in your 40s or early 50s still gives you meaningful time. Time to rebuild retirement savings. Time to let investments compound. Time to restructure a financial plan around your actual life, not the one you shared.
Do you work at California Public Employees (CalPERS)?
Get expert insights from financial advisors who specialize in helping California Public Employees (CalPERS) members make the most of their compensation package and benefits.
Looking for a financial advisor who specializes in working with California Public Employees (CalPERS) members? You’re in the right place. Below, you’ll find advisors who understand California Public Employees (CalPERS) benefits and compensation — along with their answers to common financial questions from California Public Employees (CalPERS) members.
Whether you recently joined California Public Employees (CalPERS) or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and California Public Employees (CalPERS) benefits can have a lasting impact on your financial future. For example:
✅ Do you know the right moves to get the greatest value from the California Public Employees (CalPERS) benefits available to you?
✅ If you’re thinking about leaving California Public Employees (CalPERS) for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?
Key Takeaways
1
CalPERS Pension Elections and Retirement Date Are Largely Irreversible, So Sequence Matters
Decisions like pension option elections, the retirement date that locks in your age factor, and whether to purchase service credit are difficult or impossible to undo after the fact. A financial advisor helps CalPERS members map these choices in sequence and model specific scenarios before committing, because getting the order wrong can have lasting consequences.
2
The Low-Income Window Before Social Security and RMDs Is a Critical Tax-Planning Opportunity for CalPERS Retirees
The years after a CalPERS member’s paycheck stops but before Social Security and required minimum distributions raise taxable income often represent their lowest-income stretch. This finite window creates room for strategies like Roth conversions, harvesting capital gains at lower brackets, and deliberate account drawdown sequencing—especially valuable for those who retire early.
3
The PEPRA Compensation Cap Makes Savings Plus Accounts More Important for Higher-Earning CalPERS Members
For members hired in 2013 or later, only pay up to an annual limit counts toward the pension calculation, meaning higher earners replace a smaller share of their income through CalPERS alone. The 457(b) and 401(k) available through Savings Plus become essential tools to fill that gap, yet these accounts often sit underused when members assume the pension is sufficient.
Why California Public Employees (CalPERS) Members Work with a Specialist Financial Advisor
Throughout the year, California Public Employees (CalPERS) provides its members with updates about their benefits, ranging from health insurance to a defined-benefit pension, a 457(b) or Thrift Savings Plan, and other benefits available to members. While the organization offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with California Public Employees (CalPERS) who specialize in helping California Public Employees (CalPERS) members make the most of their income and benefits.
Whether you work at one of California Public Employees (CalPERS)’s offices, from a regional hub, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.
Sensitive topics — like the steps you should take before quitting your job at California Public Employees (CalPERS) to work elsewhere, protecting yourself in advance of a layoff or workforce reduction, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.
Should You Hire a California Public Employees (CalPERS) Specialist or a Local Financial Advisor?
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving California Public Employees (CalPERS) members. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with California Public Employees (CalPERS) members is the better fit for your unique needs.
💡 In the Q&A below, you’ll gain insights from financial advisors who work with California Public Employees (CalPERS) members to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.
🙋♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.
Q&A: Financial Planning Tips for California Public Employees (CalPERS) Members
In this section, you’ll learn how you can make the most of your California Public Employees (CalPERS) employee benefits and gain valuable tips from financial advisors who specialize in working with California Public Employees (CalPERS) members.
Financial Advisor Q&A · California Public Employees (CalPERS) Members
Elias Young is a financial advisor based in the Sacramento area who specializes in offering financial planning services to California Public Employees (CalPERS) members. Elias helps clients get the most value from their California Public Employees (CalPERS) benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping California Public Employees (CalPERS) employees save for their retirement, how do you help them make the most of their employee benefits?
I help members of CalPERS by looking at their own individual financial picture, and helping to assess exactly how they should be utilizing things like Savings Plus. For instance, there is a 457(b) and a 401(k), so part of helping is assessing how to best utilize them.
QWhen you first speak with a California Public Employees (CalPERS) employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
I like to take time to talk about what goals they have, and what kind of timeline they are thinking about when it comes to achieving those goals. I also like to find out more about them personally, to try to help take planning beyond the numbers and math to personalize the advice I am giving as much as possible.
QFor California Public Employees (CalPERS) employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
I would encourage them to think about whether the new job is within a system that has reciprocity with CalPERS, which enables benefits to continue growing. If the new company involves leaving public service entirely, I would first suggest looking at the immediate opportunity costs (like if you miss out on vesting by leaving now), and then evaluating what your long-term plan looks like based on the new benefits package vs your existing one.
QFor California Public Employees (CalPERS) employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
First off, understanding that your pension estimate is not final, and to think about anything that may materially affect it (for instance, if you were divorced, is your ex-spouse entitled to any part of your benefit). After that, map out what your actual lifestyle costs are, and figure out how much income your other assets could potentially generate. Then, coming up with a longer-term cash flow projection to make sure things look OK, factoring in things like inflation, market volatility, taxes, etc.
QFor California Public Employees (CalPERS) employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
The question usually isn’t whether you’ve managed your finances capably. It’s whether the decisions ahead are the same kind you’ve been making. You may also be considering an earlier retirement, which requires intentionality. Much of what CalPERS members face approaching retirement is harder to reverse after the fact: pension option elections, the retirement date that locks in your age factor, whether to purchase service credit, how to bridge income if you retire before Social Security or Medicare begin.
Then, the years after your paycheck stops but before Social Security and required minimum distributions raise your taxable income are often your lowest-income stretch, which opens a window of time for specific strategies: Roth conversions, realizing capital gains in a lower bracket, and drawing from accounts in a deliberate order. The window is finite, so much of the value is in recognizing it and acting before it closes. Retiring earlier lengthens that window and gives those strategies more runway, as long as you planned ahead and saved enough to support the additional years.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are California Public Employees (CalPERS) employees and how do you help them overcome these obstacles?
The recurring one is that a large guaranteed pension reshapes the plan, so standard advice written for people living off a portfolio doesn’t fit as well. A CalPERS member’s largest asset may actually be an income stream that can’t be rebalanced or left to heirs, which changes how everything else fits together. Things like how much to hold in stocks, how much cash to keep in reserve, and whether life insurance has a role have a different thought process. A few patterns come up often. Savings Plus accounts may also sit underused because the pension may feel sufficient, which can leave the early retirement and tax-planning years with less flexibility. Much of what I do is sequencing choices before they’re made, running two or three specific scenarios instead of general rules, and keeping each decision in view of the others.
QFor highly compensated California Public Employees (CalPERS) employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?
The PEPRA compensation cap makes it more important to be taking advantage of Savings Plus. For members hired in 2013 or later, only pay up to an annual limit counts toward your pension. The higher your salary, the larger the share of your income that the pension isn’t replacing. That makes the supplemental accounts and your own investing more important. The theme is that a strong pension can mask how much of a high earner’s retirement still depends on decisions they’re making on their own, and the point of planning is to make those decisions on purpose rather than by default.
QBecause CalPERS members can purchase service credit (‘air time’ or prior service) to boost their pension benefit, how do you evaluate whether making that lump-sum or installment payment purchase makes financial sense compared to deploying those same dollars elsewhere?
This is where modeling alternative scenarios becomes important. For decisions like this, I like to run the decisions through financial models, measure what the pros/cons are, and to see if one choice or the other comes out as the better option.
QHow do you advise CalPERS members on coordinating their pension income with Social Security benefits, particularly given that some CalPERS-covered positions may be subject to the Windfall Elimination Provision or Government Pension Offset rules?
This one has become much simpler after the Social Security Fairness Act, which repealed both Windfall Elimination Provision (WEP), and Government Pension Offset (GPO) rules. So now these no longer reduce Social Security benefits, assuming you paid into the system.
This is also a good example of the benefit of having a financial plan, and revisiting/updating it periodically to adjust accordingly as things change.
Considering a financial advisor who specializes in working with California Public Employees (CalPERS) members?
Fiduciary Financial Advisors does not accept any liability for the use of the information discussed. Consult with a qualified financial, legal, or tax professional prior to taking any action. Before investing, consider investment objectives, risks, fees, and expenses. Investments in securities involve the risk of loss, including loss of principal. Past performance is no guarantee of future returns. The views and opinions reflected in the content are subject to change at any time without notice. The content speaks only as of the date indicated. Some information was obtained from external sources. The information is believed to be accurate, but there is no guarantee that it is.
This commentary is for informational purposes only and does not constitute investment, tax, or legal advice. The views expressed reflect current conditions and are subject to change without notice
Fiduciary Financial Advisors is a Registered Investment Adviser. Past performance is not indicative of future results, and there is no guarantee that any forecast or projection discussed will come to pass. Third-party data referenced above has not been independently verified by Fiduciary Financial Advisors.
CFP® and Certified Financial Planner® are certification marks owned by the Certified Financial Planner Board of Standards, Inc., and are awarded to individuals who meet its education, examination, experience, and ethics requirements.
Are you a financial advisor who specializes in working with members at California Public Employees (CalPERS) or another large company?
✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with members at California Public Employees (CalPERS) or another large company. (Subject to availability and terms.) ✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender
Ask a Financial Advisor Your California Public Employees (CalPERS) Benefits & Career Questions
Get answers from the Wealthtender network of financial professionals and educators.
Are you ready to enjoy life more with less money stress?
Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.
Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.
A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.
Got PFIC’s in your overseas portfolio? This one is for you.
In this post, I’ll discuss the passive foreign investment company (PFIC). I’ll address the origin (briefly), the taxation, and how you can tell if there is a PFIC lurking in your overseas accounts or not.
I’ll conclude with how to think about them if they are a part of your overseas portfolio.
One of my questions for those who reach out to discuss working together is, “What assets do you have overseas?”
I pay attention to the answers, and when Investment/Retirement accounts come up, I dig deeper. And they come up a lot.
Typically, the prospect will mention the account type or the account name or try to describe it in a way that makes “US” sense.
Here are some examples of what prospects have provided (in their own words) and what they call them back home.
Foreign Accounts That May Hold PFICs
Demat Accounts, KiwiSaver, Super account, TFSA, MMF account, CDS account, an investing ISA, AFORE account, etc.
Many of these accounts hold assets that are deemed to be PFICs (Passive Foreign Investment Companies).
And this is where we start to get into trouble because of how the IRS taxes them. It’s excessive, punitive, and the paperwork involved is a nightmare (complex and takes too much time).
Let’s dive into the details of PFICs, including a brief history, tax implications, and how to tell if a PFIC is lurking in your overseas accounts.
Why Are Foreign-Born Families Investing Outside the US?
With foreign-born families, I completely get and understand investing outside the US. This applies to those on work visas, green card holders, or citizens.
For some of you, these are your old retirement accounts (after all, you were working and saving in your home country’s workplace/government accounts, before moving to the US).
For others, this is where you were investing before moving to the US.
Some of you are trying to diversify, you also believe the returns are better in your home country, and of course, there is home bias.
Finally, there are those who have inherited the accounts after their elders passed away.
Regardless, PFICs can and tend to be highly problematic under the Internal Revenue Code.
The “Income test” – 75% or more of its gross income is passive, which means the income is coming from investments or sources not related to regular business operations.
The Asset Test
The “asset test” – 50% or more of its assets are in investments that produce income in the form of earned interest, dividends, or capital gains.
Once an investment is classified as a PFIC, it will always be a PFIC.
In this podcast episode, we answer the question “What’s a PFIC”
Examples of PFICs
According to the above definition, many overseas investments fall into the PFIC category. Some examples include non-US domiciled mutual funds or ETFs, private startups/family holding companies, and foreign corporations holding different assets.
In and of itself, a PFIC is a legitimate way to invest. The issue comes from how the IRS taxes them.
There are three ways your PFIC can be taxed. The taxation methods are complex, and they are best handled by a tax pro.
Excess Distribution – The Default
Under section 1291, you pay ordinary taxes on “excess distributions”. IRS defines “excess distributions” as any part of the distribution received from a section 1291 fund in the current tax year that is greater than 125% of the average distributions received.
If you sell a PFIC or receive a large distribution, the IRS considers it an excess distribution, and it also spreads the gain over the number of years you held the fund.
The back years are taxed at the highest rate possible for that year (regardless of your tax bracket), and then, for good measure, it adds an interest charge for the taxes you haven’t paid to date (the prior years). Told you it was bad!
This leads to the excessive taxation I mentioned.
Qualifying Electing Fund (QEF) Election
In this method of taxation, the PFIC is taxed similarly to a US fund. You pay taxes only on the shares of the fund that you own (as ordinary income) and net capital gain taxes every year.
For this to work, the fund has to be willing to provide extensive financial data to the IRS each year. Very few foreign funds are willing to do this.
Mark-To-Mark Election
To qualify for the MTM election, the fund must be traded on the market. Any gains are treated as ordinary income for that year. This is just a little better than the default with excess distributions, even though it treats the PFIC as if it were sold at the end of the year (fair market value).
The election needs to be made before the first year of filing and before you file taxes. If you’ve missed the prior reporting, the older reporting must be done under the default method.
This is why, when you reach out, and you’ve been holding onto your PFICs (even though you probably had no idea), we can’t just go to the MTM method right away.
The reporting, tax regime election, and the actual taxes are reported on Form 8621, which is one of the most complex forms to complete. According to the IRS, it can take up to 48 hours to complete one of these forms.
It’s why CPAs aren’t thrilled when you tell them you need to catch up on your PFIC filing.
Each PFIC fund or asset must be filed on its own Form 8621. For example, if Peter has an overseas account with 10 foreign-registered mutual funds, he’ll need to complete 10 8621 forms.
Exemption to Filing Form 8621
You may not need to file Form 8621 in the following situation, but I have seen cases where people still filed it as a precaution.
If the PFIC is in a retirement account with a pension protective wrapper, it might escape PFIC status and, hence, the need to file Form 8621.
If the PFIC value is below $25,000 (filing single), and below $50,000 (filing married), and there is no excess distribution for the year, you may be able to avoid filing the form.
Next, if you have a G-4 visa and are working in the US, you are still considered a non-resident for tax purposes. So, you are not including overseas assets in your filing, so the PFIC may not be an issue for you.
Back to the Start – PFICs Complexity
The biggest issue is not knowing you have problematic investments overseas. Very few of you know how tricky these investments are, and for most of you, it’s the first time you learn that your investment overseas is an issue and a serious one, too.
The toughest ones that I have come across are where a relative overseas passes away, and suddenly, you inherit a lot of PFICs you were not even aware of.
Unfortunately, every year you ignore the issue, it just compounds. And keep in mind that there is no statute of limitations – so if you’ve failed to file the form, waiting does not improve matters.
In addition to Form 8621, other international forms may need to be completed, such as the FBAR, FATCA, 3520-A, and Form 5471 if a foreign corporation.
Curious If Your Foreign-Domiciled Mutual Fund Or ETF Is A PFIC Or Not?. Try the following test.
What Does Your Tax Person Think?
Reach out to your tax professional, your CPA, your EA, or your cross-border professional, and ask them. If they are in the cross-border space, I’ll expect them to be able to give you an answer.
Alternatively, reach out to a cross-border financial planner, like us.
Talk to the Foreign Company/Custodian Holding Your Accounts.
Many foreign fund companies are familiar with this regime. Ask them directly whether what you have is PFIC or not.
What we’ve discovered is that if it’s a PFIC, the foreign company may not be able to provide 100% assurance. That probably gives you the answer you are looking for.
In a recent case, we reached out to the overseas company, and they responded right away, confirming that the client’s holdings were PFICs.
Examine the ISIN
Finally, look at the ISIN. The ISIN (International Securities Identification Number) is a unique identifier for all international securities. It’s a 12-character alphanumeric code that uniquely identifies a security.
If the first couple of digits are not “US”, then this is most likely a PFIC.
If it turns out you have PFIC, take the following steps.
Confirm it’s truly a PFIC – we’ll need the exact statements to help.
Understand whether you have missed filing the 8621 form and how far back it needs to go to make you compliant.
Act now to file the missing forms. A tax professional can help you avoid costly mistakes and penalties.
As soon as you’re caught up, establish a strategy for managing the funds going forward. For some people, selling them and taking the hit is the call, but for some, holding them and dealing with the filing may be the better option.
For example, if you are here on a temporary visa and plan to return soon, and you’ve held PFICs for a long time in a pension or other account, it may be worth a second and third conversation.
Caution – Gifting PFICs
I’ve seen cases where, as soon as somebody finds out they have PFICs, they want to sell them immediately or give them away.
Many people will have follow-up questions once they realize how the IRS treats PFICs. Below are a few.
1. Which overseas investments can you own without triggering PFIC treatment?
Yes, there are some possibilities. Some of these are individual stocks, government bonds, and a few more.
2. Are there situations where it makes sense to keep the PFIC?
Absolutely, if you are in the US on a temporary visa (such as H-1B, O-1, TN, or E-3) and plan to return to your home country soon, it may make sense to keep it. But you still want to model the situation with a cross-border CPA, to compare the numbers for keeping it, versus selling it outright. Of course, this assumes you’ve dealt with any late or missed filings.
3. At what rate are the PFICs taxed?
For the previous years, PFICs are taxed at the highest rate for that year, regardless of your individual tax rate. So you could be in the 12% tax bracket, but they get taxed at 39%.
4. I just learned about PFICs, and I think I’m delinquent. What do I do?
Take a deep breath, reach out to a cross-border CPA or EA, or reach out to us, and we can help you chart the way forward. You don’t have to deal with this on your own.
Discover financial advisors trusted by residents of Shrewsbury, New Jersey in the only local directory featuring 5-Star Certified Advisor Review™ recipients and Wealthtender Voice of the Client Award™ winners—recognition earned for exceptional client feedback. Compare fiduciary, fee-only advisors, CFP® professionals, and specialists to find the right fit for your unique financial needs.
Whether you have lived in Shrewsbury for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.
It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Shrewsbury featured on Wealthtender you may want to add to your shortlist.
Featured Shrewsbury Financial Advisors
As you prepare to interview financial advisors in Shrewsbury who may be right for you, get to know local financial advisors featured on Wealthtender.
📍 Map: Financial Advisors with their Primary Office Location in Shrewsbury
Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Shrewsbury.
The Benefits of Hiring a Financial Advisor in Shrewsbury
Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.
As a resident living in Shrewsbury, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.
Do you work for one of the largest employers in Shrewsbury? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.
When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.
Quick Tips For Hiring an Shrewsbury Financial Advisor
Before hiring a financial advisor in Shrewsbury, here are a few quick tips to help you find the best advisor for you.
1. Decide Which Services You Need
Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.
Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:
Budgeting and money management
Debt management
Insurance planning
Retirement planning
Other investment planning
Inheritance planning
Estate planning
Tax planning
As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.
Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.
2. Consider Your Budget and Payment Preferences
Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.
If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.
3. Interview Multiple Financial Advisors
Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:
What services do you provide?
What are all the ways you get paid? (fee transparency)
What is your investment strategy?
How do you measure investment performance?
How do we communicate about my plan?
Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.
4. Review Financial Advisor Credentials
Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website.
You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.
As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.
For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.
Frequently Asked Questions & Additional Resources
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.
But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings.
Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a local financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.
Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian
Whether you’re a financial advisor who recently joined Wealthtender and wondering what to expect, a seasoned advisor looking to make the most of your Wealthtender experience, or simply trying to understand how Wealthtender’s digital marketing benefits differ from traditional lead generation, this guide covers all of it. Honestly, with data, and without the sales pitch…well, maybe just a subtle sales pitch.
Key Takeaways
1
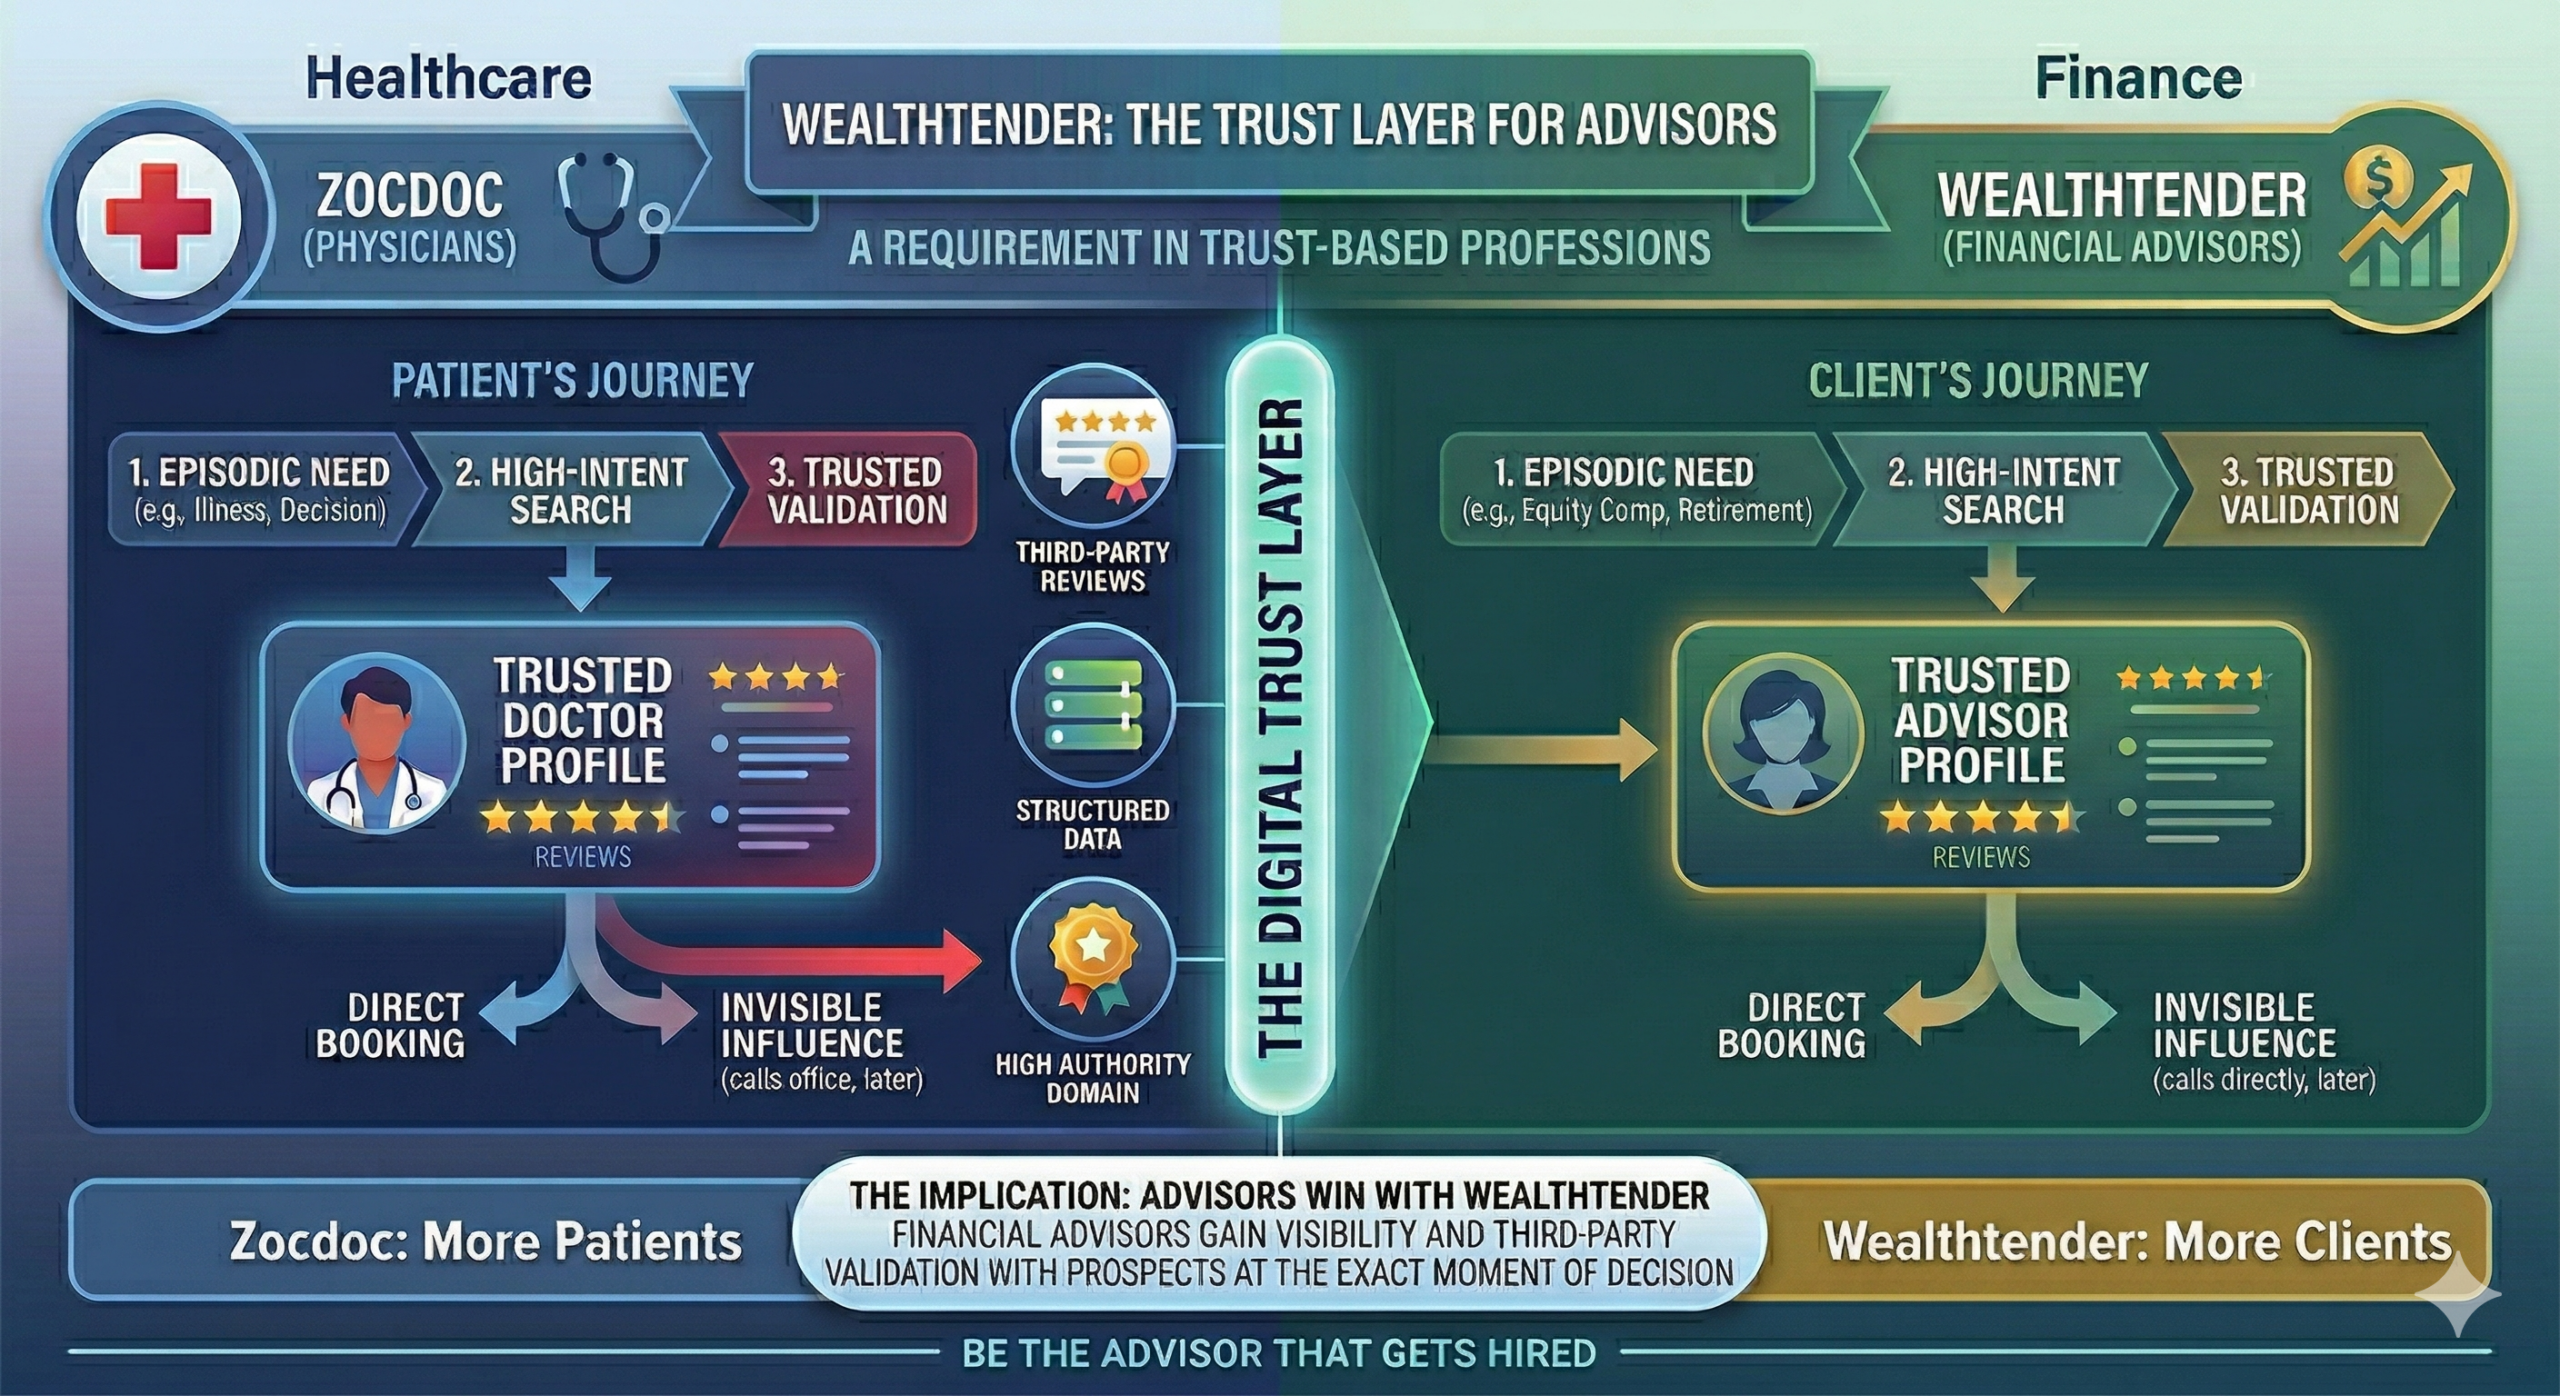
Wealthtender is to financial advisors what Zocdoc is to physicians: a trust-layer platform where high-intent prospects make their final decision.
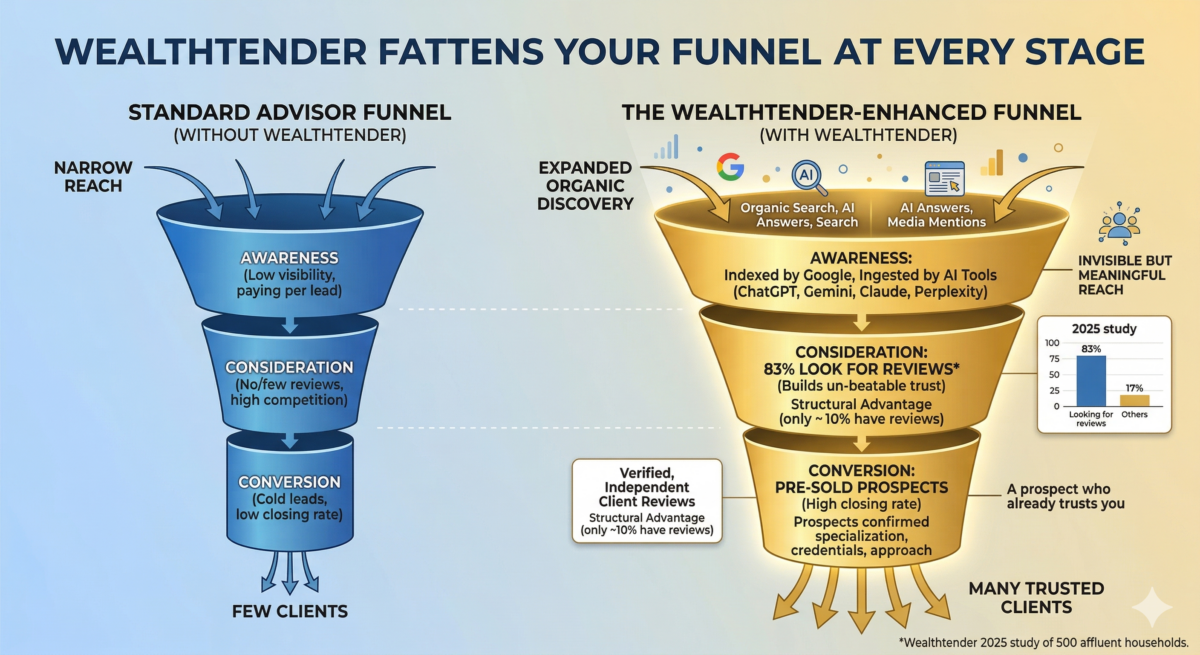
Just as patients don’t choose a doctor based on a hospital’s brand alone, prospective clients don’t hire a financial advisor based on a firm’s marketing alone — they research individuals, read reviews, and validate trust before ever reaching out. Wealthtender positions you inside that decision moment: discoverable in Google and AI tools, credible through independently verified client reviews, and visible to prospects who are already motivated to act. That’s a fundamentally different point in the funnel than where traditional lead generation platforms operate.
2
Wealthtender delivers daily digital marketing ROI that increases visibility in Google and AI search, with a lead gen call option.
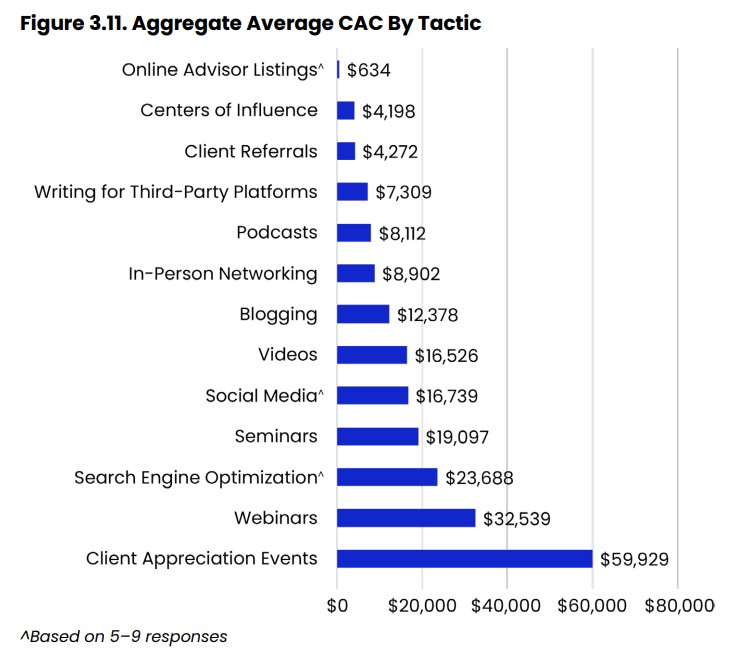
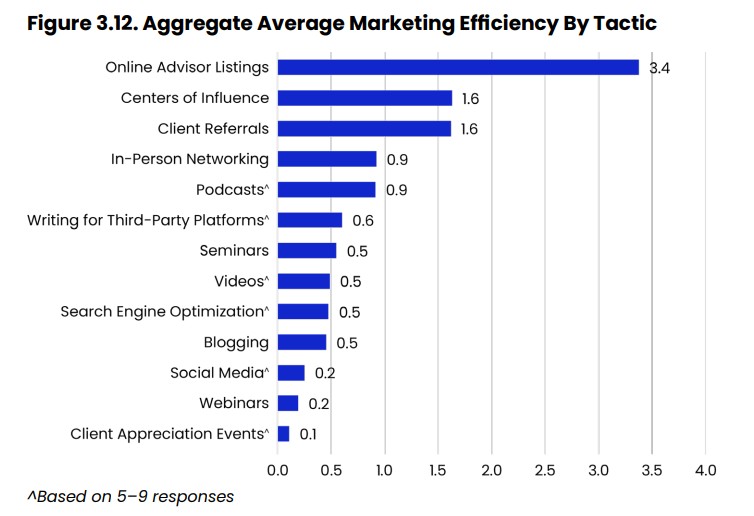
Think of your subscription as offering a call option: the monthly fee is the premium, and the intrinsic value is impactful — your profile indexed in Google and AI tools, your reviews differentiating you from the 90%+ of advisors who have none, your specializations surfacing in relevant searches every day. The option value (above and beyond intrinsic value) materializes when a qualified prospect discovers you on Wealthtender. Independent Kitces research found online advisor directory listings have the lowest client acquisition cost ($634) and highest marketing efficiency of any tactic studied across 14 categories.
3
Wealthtender influences more prospect decisions than advisors can directly measure.
Prospects may find you through AI-generated answers that cite Wealthtender content, see your reviews embedded on your website or compliantly promoted on social media, or discover you in a specialist directory or Q&A feature published on Wealthtender. And since 96% of referred prospects research advisors online before making contact, your Wealthtender profile is actively working on every referral you receive, not just the leads that originate directly through the platform.
What Wealthtender Is (Before We Talk About What It Isn’t)
Let’s start with a comparison that may feel outside our industry, but arguably explains Wealthtender better than anything else:
Wealthtender is to financial advisors what Zocdoc is to physicians.
This comparison matters because both financial advisors and physicians operate in what are known as trust-based professions. Yes, credentials matter. Experience matters. Designations matter. But those are table stakes. When a consumer is deciding which doctor or financial advisor they will hire, the decision is ultimately driven by something else: trust.
Today, trust is built (and validated) online. That’s where platforms like Zocdoc (for physicians) and Wealthtender (for financial advisors) come in.
The Role of the “Trust Layer” & Bottom-of-Funnel Intent
Zocdoc is a popular tool used by people to find, compare and hire doctors. But patients don’t use Zocdoc every day, and doctors don’t sign up for Zocdoc with the expectation of receiving a steady stream of appointments. Usage is episodic. People use Zocdoc when they have a specific need (e.g., when something is wrong, when a decision needs to be made, when they’re ready to act). And when they show up, they’re not casually browsing. It’s bottom-of-funnel intent. They search for providers they can trust, compare profiles and specialties, read reviews carefully, and make a decision. Sometimes they book through Zocdoc. Sometimes they call the office directly. Sometimes they leave and come back later. And sometimes, they never visit Zocdoc at all.
How Zocdoc (and Wealthtender) Influence the Decision – Even If They’re Invisible
This is where many people misunderstand how platforms like Zocdoc – and Wealthtender – actually work. These platforms operate as part of the internet’s trust layer. Consumers today rely on third-party platforms for provider discovery, lean on reviews and profiles to evaluate credibility, and move through a multi-step journey before ever reaching out. And increasingly, that journey includes something new: AI-powered search.
When someone asks “Who is a good doctor in Los Angeles for an executive physical?” or “What do patients say about Dr. Smith?”, or, in the advisor world, “Who is a good financial advisor in Austin for Dell employees?” or “What do clients say about [advisor name]?”, AI tools like ChatGPT, Gemini, Perplexity, and others generate answers by pulling from trusted sources across the web. Platforms like Zocdoc and Wealthtender are among those sources, because each hosts independent third-party reviews, structure data in ways AI systems can interpret, and sit on high-authority domains that both search engines and AI tools trust. That means even if a consumer never visits Zocdoc or Wealthtender directly, their decision may still be shaped by information sourced from these platforms.
The Implication Some Advisors Miss
This leads to an important and often misunderstood aspect of the value these types of platforms can provide: Specifically, Wealthtender and Zocdoc can be highly valuable and influential even if consumer usage is episodic and attribution is imperfect. The value isn’t just in direct bookings. It’s in being visible in the right places, being validated by third-party credibility, and being trusted at the exact moment a decision is made. This is simply the nature of trust-layer marketplaces.
When a prospective client is ready to hire a financial advisor, they don’t start from scratch, and they don’t rely on a single source. They Google your name, ask AI tools like ChatGPT and Gemini for recommendations, look for reviews and third-party validation, and compare multiple advisors before reaching out. Even when receiving a glowing referral to an advisor from a friend or colleague, 83% of Americans who participated in a 2025 Wealthtender research study said the very next thing they will do is look online for reviews to learn if others feel the same way.
Wealthtender is designed to position you inside that decision process. So when the right prospect shows up, you’re discoverable, you’re credible, and you’re trusted. Sometimes that results in a direct introduction through Wealthtender. Other times, it results in a prospect calling you directly, booking time on your calendar, or reaching out after researching you elsewhere. In those cases, the influence is real, but the attribution isn’t always visible. And that’s okay. Because the goal isn’t constant activity. The goal is simple: be the advisor they choose when they’re ready to decide.
What Wealthtender Isn’t
Now, with that framing in mind, let’s level-set clearly: Wealthtender is not a traditional lead generation platform, and we’re not trying to be.
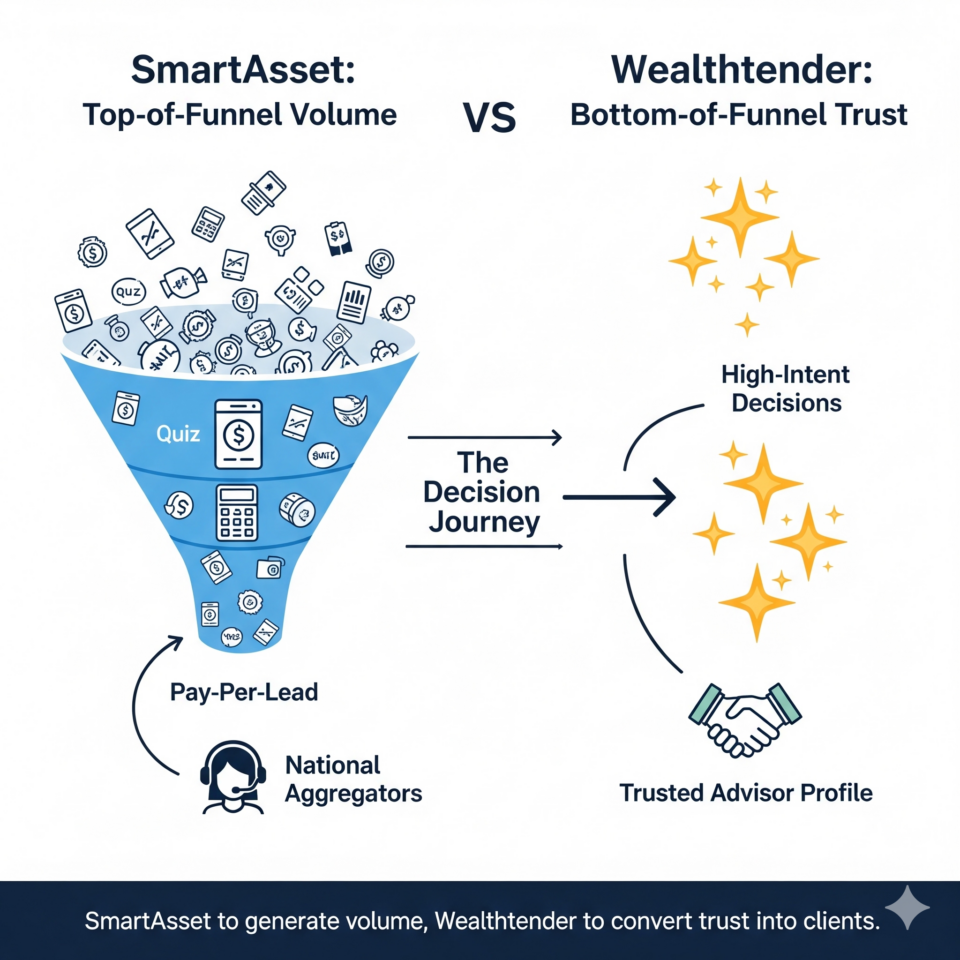
Platforms like SmartAsset are built around a fundamentally different model. They generate a high volume of leads, typically through quizzes, calculators, and forms, and sell that information to advisors on a pay-per-lead basis, with advisors typically investing $2,000–$4,000+ per month to receive a steady stream of inbound contacts. Those leads can absolutely convert, but they come with real tradeoffs.
Prospects originating through SmartAsset are often early in their journey, they may be contacted by multiple advisors simultaneously, and success depends heavily on speed, persistence, and robust follow-up systems. Conversion rates are typically (very) low but scalable with volume. In other words: top-of-funnel intent. That model works well for firms with dedicated sales teams, structured follow-up processes, and the budget to operate at scale. There’s a reason the most successful firms utilizing SmartAsset are national aggregators like Creative Planning and Fisher Investments with call centers exclusively dedicated to working the leads.
Wealthtender operates at a completely different point in the journey. Instead of generating volume at the top of the funnel, Wealthtender positions you where decisions are made: when prospects are actively researching advisors, comparing credibility and fit, and when trust, not outreach, determines who they contact. Which is why lead flow is less frequent, but intent is significantly higher. And why many advisors might choose to use both: SmartAsset to generate volume, Wealthtender to convert trust into clients.
When it comes to traditional lead gen platforms like SmartAsset, here’s an analogy worth your consideration. Casinos have spent decades perfecting the science of the dopamine hit. Slot machines aren’t designed to make you rich, they’re designed to keep you playing. The ding of a near-miss, the flash of three matching symbols, the occasional modest payout just large enough to feel like validation: all of it is engineered to trigger a neurochemical response that makes it genuinely difficult to walk away. And the most sophisticated machines don’t just keep you at the same bet, they gradually encourage you to increase your wager for the prospect of a bigger reward. The cycle becomes self-reinforcing: the next pull might be the one, so you keep pulling.
Traditional lead generation platforms like SmartAsset understand this dynamic, even if they’d never describe it in those terms. The inbox notification of a new lead is a ding. The asset level in the prospect profile is the flashing symbol. The occasional conversion, the client who actually signs, is the payout that keeps you feeding the machine. And when a month goes by with nothing to show for it, the natural human response is not to question whether the machine is working, but to wonder if maybe you just need to increase your spend, improve your follow-up cadence, or try the next tier of the platform.
We’re not saying this analogy is perfectly accurate. Traditional lead gen can and does work for the right practices with the right commitment and resources, as we’ve acknowledged throughout this article. And unlike slot machines, it isn’t purely a game of chance. But the dopamine mechanism is real. It’s human nature to crave the feeling of something happening… a tangible, countable signal that your marketing investment is producing activity. Lead gen platforms like SmartAsset deliver that feeling reliably, which is part of why they’re so compelling even when the ROI math gets difficult to justify.
The honest question to ask yourself is whether that dopamine hit is actually informative signal or just psychological comfort. A lead notification feels like progress. But if that lead turns out to be someone who didn’t even intend to speak with a financial advisor, or who is simultaneously being called by two other advisors, or who stops returning calls after the first voicemail, was that ding actually telling you something useful? Or was it, like so many slot machine payouts, just enough of a reward to keep you in the game a little longer?
Inbound lead generation platforms like Wealthtender are simply not built to offer frequent dopamine hits. There’s no inbox ding when your profile shows up in a Google search. There’s no notification when an AI tool cites your reviews. There’s no alert when a prospect reads your testimonials and decides to reach out through your calendar link without mentioning Wealthtender. These things happen, and they influence real decisions, but they happen quietly. The tradeoff is that Wealthtender also poses no risk to your financial solvency with all plans below $100/month, is very unlikely to ever become your largest marketing expense, and doesn’t require you to talk yourself into another month of spend after a dry run. The downside is truly capped. The upside, when it materializes, tends to show up as exactly the kind of client you actually wanted.
What Wealthtender Delivers
Wealthtender is your long-term digital marketing partner for compliant online reviews and maximum visibility with prospects using AI search tools and Google to research and hire financial advisors, all for less than $100 per month (per advisor).
Each Wealthtender subscription covers a lot of ground. Your profile is built for organic visibility in AI tools like ChatGPT, Gemini, Claude, and Perplexity, in addition to traditional Google search. You get access to the industry’s first SEC/FINRA-compliant platform for collecting and publishing verified client reviews, hosted on a trusted, independent third-party website with industry-leading domain authority. Advisors on the Convert plan and above also receive weekly media quote opportunities in major publications that build authority and fuel AI citations, placement in local guides and specialist directories designed to surface you in the right searches, and the ability to be featured as a specialist in Large Employer Q&A discovery resources to get found and hired by employees and executives. And across all plans, when the right prospect finds you, they can reach out directly: no gatekeeping, no friction, no cost per lead.
Don’t just take our word for it. The 2024 Kitces Research Marketing Survey, arguably the most comprehensive independent study of financial advisor marketing effectiveness periodically conducted, found that online advisor directory listings have the lowest client acquisition cost of any marketing tactic studied, at just $634 per client, and the highest marketing efficiency of any tactic, with a score of 3.4. The Kitces researchers described online directory listings as one of the two “most underappreciated marketing tactics” in the industry.
“Using online directory listings (i.e., various ‘Find An Advisor’ platforms), along with cold calling or door knocking, are likely the 2 most underappreciated marketing tactics. With a solid rate of success and minimal cost to list in an advisor directory, listings have the highest marketing efficiency of any tactic.” — Kitces Report: How Financial Planners Actually Market Their Services (2024)
Think of Wealthtender as a Call Option on High-Quality Leads
Here’s the framework that best captures how Wealthtender works, and why the comparison to high-volume lead gen platforms misses the point entirely.
Joining Wealthtender is similar to purchasing a call option on the opportunity to attract your ideal clients. The monthly subscription (less than $100/month) is the premium you pay. And like any call option, it delivers two distinct types of value.
The first is intrinsic value: benefits you’re receiving every single day, regardless of whether you ever receive a direct inquiry. Your profile is continuously working to strengthen your visibility in Google, ChatGPT, Gemini, Perplexity, and other tools used by consumers to find and research advisors. Your independently-hosted reviews differentiate you from the 90%+ of advisors who have no online reviews at all. Your placement in local, specialist, and designation directories surfaces you in relevant searches. Backlinks from a high-domain-authority platform quietly strengthen your own website’s search ranking. And media quote opportunities build the kind of authority that compounds over time. None of this requires a prospect to contact you through Wealthtender for it to be valuable, though much of it can influence prospects to contact you without either of you ever knowing Wealthtender played a role.
The second is option value: realized when qualified prospects discover your profile and reach out to your directly through Wealthtender. And when that happens, the attributable ROI on your nominal monthly investment can be extraordinary – which is precisely what the Kitces research team calls out.
Just as call options provide asymmetric upside (e.g., limited downside, unlimited potential upside), Wealthtender works the same way. The downside is capped at your modest monthly subscription. The upside, when a single new client can generate thousands or tens of thousands in annual revenue, is uncapped.
This is why we say Wealthtender offers impactful digital marketing benefits as the core value proposition, with a call option on high-quality leads embedded at no additional cost. Not the other way around.
When the Option Is Exercised: Clicks That Become Clients
Prospect inquiries through Wealthtender are episodic: they don’t arrive with the predictable frequency (or cost) of a high-volume cold lead platform. But when they do arrive, they are categorically different from what most lead generation platforms deliver.
These prospects have already researched you. They’ve read your reviews, browsed your profile, confirmed you could be the right fit, and made a deliberate, self-directed decision to reach out to you specifically. They are not annoyed and standoffish, as we hear is often the case among consumers on the receiving end of three call center reps auto-dialing them after they click submit on a SmartAsset quiz. Rather, they are warm, self-qualified, and much further along in their decision-making process.
To illustrate what this looks like in practice, here’s a sample of real messages advisors have received through their Wealthtender profiles:
“We’re interested in learning more about your retirement planning services. Our portfolio is between $5–7M, we are 60 and 61, and live in…”
“My wife and I are looking for an advisor to help with equity and options. We are corporate professionals with options/RSUs in…”
“We are in Austin and retiring in a few weeks… selling our business. I would like to schedule a meeting with you and very likely proceed to…”
“I am currently with Edward Jones and wanted to look into a fiduciary or advisory financial planner…”
“I am an engineer at Google. I would appreciate the opportunity to schedule a brief introductory call…”
“I am a physician with investments in my hospital practice, retirement accounts, real estate, and…”
“We live in California and have a net worth around $5.5M. Please contact me if you are interested in working with us…”
“I came across your profile and would like to explore working with you for divorce-related financial planning…”
“I am looking for a flat fee financial advisor. I found your contact information on Wealthtender.”
We share these not because you should expect them regularly… you shouldn’t. But they do happen, and when they do, Wealthtender can instantly become the lowest cost-per-client acquisition channel of any platform you use. A single new client from one of these inquiries can deliver ROI that dwarfs years of monthly subscription fees. Again, we would point you back to the Kitces research.
Wealthtender Fattens Your Funnel at Every Stage
This is perhaps the most important concept in this entire article: Wealthtender doesn’t just offer the potential to periodically add leads to the top of your funnel. It’s more important role is to make every stage of your funnel fatter (wider) and that compounds dramatically.
At the awareness stage, your Wealthtender profile is indexed by Google and ingested by AI tools like ChatGPT, Gemini, Claude, and Perplexity. More prospects discover you through organic search, AI-generated answers, directory listings, and media mentions without you paying-per-click or per lead. Your reach expands invisibly but meaningfully every day.
At the research and consideration stage, your client reviews create trust that most advisors simply cannot compete with. According to Wealthtender’s 2025 study of 500 affluent households planning to hire an advisor, 83% specifically look for online reviews before deciding whether to reach out. If you have verified, independently-hosted reviews on Wealthtender and your competitors don’t (and fewer than 10% of all advisors have any online reviews at all) you have a structural advantage at the exact moment the decision is being made.
At the conversion stage, consider what a prospect actually knows about you before they reach out through Wealthtender – They’ve read your reviews. They’ve confirmed your specializations match their situation. They’ve evaluated your credentials, your approach, and what real clients say about working with you. They chose you specifically, not because a call center rep from a national aggregator auto-dialed them, but because they did their homework and decided you were the right fit. Compare that to a cold lead who filled out a form and is now fielding calls from three advisors simultaneously. The conversion math isn’t complicated. A prospect who arrives already trusting you closes at a fundamentally different rate than one who has never heard your name.
Wealthtender Benefits You May Not Be Measuring
Here are three Wealthtender benefits with impactful ROI that many advisors dramatically underestimate:
1. You’re Showing Up in Google and AI Search, Whether You Know It or Not
When a consumer searches Google for “financial advisor specializing in equity compensation in Austin” or asks ChatGPT “Who is a good financial advisor for tech employees in Seattle?”, Wealthtender profiles with relevant specializations, client reviews, and well-structured content are increasingly surfacing in those results.
As covered by Barron’s in November 2025, platforms like Wealthtender are “designed to help make advisors discoverable by AI chatbots.” The article featured advisor Arielle Tucker of Connected Financial Planning, who received a new prospect inquiry that began simply: “I was searching for a U.S. expat advisor, and your name came up on ChatGPT.” Tucker’s specialized focus on U.S. expatriates, combined with her Wealthtender profile and client reviews, made her discoverable at the exact moment a highly qualified prospect was looking, without any paid advertising, cold outreach, or subscription to a lead generation platform.
The consumer behavior data behind that story is worth revisiting. According to Wealthtender’s 2025 consumer research study previously referenced, 50% of consumers begin their search for an advisor online through Google, and 25% (likely an even higher percentage today) are using AI tools like ChatGPT and Gemini to research advisors. Perhaps most importantly, 96% of people who receive a referral will still research the advisor online before making contact, and 83% specifically look for online reviews before deciding whether to reach out.
That last statistic carries significant implications. There is no such thing as a purely offline referral anymore. Even when a CPA refers a client to you, that prospect will Google you, ask ChatGPT about you, or look for your reviews before they ever pick up the phone or book a call on your calendar. Your Wealthtender presence is working for you at that exact moment, a moment that matters more than most, whether or not the prospect ever visits wealthtender.com directly.
2. Your Reviews Are Being Ingested by AI Tools
Client reviews published on Wealthtender don’t just live on your profile page. They are indexed by search engines and ingested by AI systems that use them to answer consumer queries. This means a prospect who has never visited Wealthtender.com may still be influenced by your Wealthtender presence, because when they ask ChatGPT or Perplexity what clients say about you, the answer is shaped by the content on your profile. Wealthtender’s structured data architecture, schema markup, and independent review infrastructure are specifically designed to maximize this effect. AI tools weight independent third-party review platforms more heavily than testimonials on advisor websites, which they recognize as self-curated rather than independently verified.
3. You’re Converting More Prospects Across Every Channel
Your Wealthtender profile builds trust that spills over into every other marketing channel you use. When a SmartAsset lead googles you or asks ChatGPT about you after receiving your call/email, your Wealthtender presence can be the difference between a callback and silence. When a seminar attendee goes home and researches you before your follow-up call, your reviews strengthen the likelihood they show up. When a referral researches you before reaching out, your independent third-party profile removes friction and your reviews accelerate their decision. Your profile is always working – 24/7, across all of these scenarios.
The Wealthtender Ripple Effect: How Prospects Find You Without Ever Visiting Wealthtender
One of the most counterintuitive benefits of Wealthtender is that we can influence a prospect’s decision to hire you even if they never visit wealthtender.com. There are three distinct ways this happens.
Through AI-generated answers. When prospects ask ChatGPT, Perplexity, Claude, or Gemini about financial advisors in their area or with a particular specialty, Wealthtender’s structured data and your client reviews surface your name and credentials in those answers more frequently and prominently, even when the prospect doesn’t search Wealthtender specifically. Advisors with complete profiles and verified reviews on the platform have a measurable advantage in AI-generated recommendations, because AI tools treat independently hosted third-party reviews as more authoritative than testimonials published on an advisor’s own website.
Through reviews embedded on your website. Every Wealthtender plan includes the ability to compliantly display your verified client reviews via a widget directly on your website. A prospect visiting your site sees verified third-party social proof without ever clicking to wealthtender.com.
Through specialist resources, like Wealthtender’s Large Employer Q&A content series. Advisors featured in Wealthtender’s Large Employer Q&A content series (available on the Convert plan and higher) can be discovered through highly targeted Google and AI searches by employees and executives of specific companies, with those employees never visiting Wealthtender’s homepage. One advisor in our community described her first experience with the feature this way: “I had a prospect reach out this week from one of the large companies that I did the Q&A on and he mentioned that he found me through a Google search using the keywords of ‘advisor, CFP and [the name of the $50B tech company where he works].’ Wow! These tools at Wealthtender are already working!!” She wasn’t found through Wealthtender’s homepage. She was found through Google, because Wealthtender’s content put her in exactly the right place at exactly the right moment.
The gist is this: Wealthtender’s reach is even greater than Wealthtender’s direct traffic. Our domain authority, structured data, and review infrastructure creates a ‘halo effect’ that extends your visibility across the internet everywhere prospects are looking to find and research advisors.
See It for Yourself: AI Prompts to Try Right Now
One of the most tangible ways to appreciate Wealthtender’s impact is to run a few searches yourself in the AI tools that prospects are already using. These prompts are designed to surface the type of information Wealthtender helps shape, specifically around your reviews and reputation, which are the areas most likely to return results influenced by your Wealthtender presence.
To see how your reviews appear to prospects researching you:
“What do clients of [Your Name] say about their experience working with them?”
“Are there reviews for financial advisor [Your Name]?”
“What is [Your Name]’s reputation as a financial advisor?”
“Can you summarize client feedback for [Your Name], CFP?”
To see how AI recommends you and/or competitors based on areas of specialization:
“Who is a good financial advisor for [your niche] in [your city]?”
“Can you recommend a financial advisor near [your city] who specializes in [your specialty]?”
“I work at [large employer you serve]. What financial advisor would be a good fit for someone in my situation?”
To see how you appear when a prospect researches you by name:
“Tell me about [Your Name], CFP. What are their areas of expertise?”
“I was referred to [Your Name] as a financial advisor. What can you tell me about them?”
“I’m looking for a financial advisor who specializes in [your specialty] near [your city]. Who comes up?”
If you have client reviews published on Wealthtender, you may be pleasantly surprised by what these queries return. If you haven’t yet collected reviews, these prompts will quickly illustrate how much more visible and credible you could be to prospects who are actively looking for someone exactly like you.
What to Do If You’re Not Showing Up — Yet
Don’t be discouraged if your name doesn’t immediately appear in every search. A few things are worth understanding before drawing conclusions, and a few concrete steps are worth taking.
First, understand how AI search actually works. Unlike a traditional Google search which often returns the same ranked list for a given query, AI tools like ChatGPT and Gemini are probabilistic, they don’t return identical answers every time. The same prompt entered twice in the same tool may surface different advisors on different occasions. So before drawing conclusions, run each prompt multiple times across multiple tools (ChatGPT, Gemini, Perplexity, Claude) and note both how often you appear and how consistently certain other advisors appear. You may show up more than you think, or you may identify a clear gap worth closing.
Second, flag the advisors who do appear more often for further analysis. When other advisors consistently appear in searches you want to own, look them up. Visit their website. Look at their Wealthtender profile. Count their reviews. Look for dedicated landing pages built for specific client segments. Check whether they’ve been quoted in media outlets or articles aligned to that topic, or whether they’re featured in YouTube videos or podcasts that could be elevating their AI visibility. Look at whether they’re publishing FAQs with schema markup on their site or profile. This isn’t about copying what they do, it’s about understanding what’s earning them visibility and honestly assessing where your own online presence has gaps you can fill.
Third, make sure the prompts you’re targeting actually match what your ideal clients are searching for. This is where advisors sometimes work hard on the wrong thing. If your ideal client is a Google employee navigating RSU vesting, the question worth asking is: are Google employees actually entering prompts like “financial advisor for Google employees with RSUs” into AI tools or Google itself? (Hint: we know at least some are.) A narrow niche can be extraordinarily powerful for establishing you as the recognized expert and elevating your visibility, but its smaller audience also means inbound interest will naturally be more episodic, even when your online presence is excellent. For niches like this, it’s worth pairing your inbound strategy (Wealthtender, reviews, website, Q&As) with outbound tactics that put you directly in front of your ideal audience: speaking to employee resource groups, writing content distributed in channels your ICP (Ideal Client Profile) frequents, or building relationships with HR teams and CPAs who work with those employees.
Fourth, remember that even referrals are influenced by your online presence. If you serve Amazon employees and a current client refers a colleague to you, that colleague is almost certainly going to Google your name, ask an AI tool about you, and look for reviews before scheduling a call. If your Wealthtender profile has reviews from other Amazon employees describing exactly the kind of help you provided them, a dedicated section on your website for Amazon employees, and FAQs built around their specific financial questions, that referral is very likely to convert. If none of those things exist, the referral may quietly choose someone else, or simply never reach out. This is one of the most underappreciated ways Wealthtender fattens your funnel: it doesn’t just generate new top-of-funnel interest, it helps convert the referrals and warm leads you’re already getting.
What to Expect: A Realistic Timeline for Seeing Results
Like any meaningful investment in organic digital marketing, Wealthtender rewards patience and consistency.
In the first 30–90 days, your profile is published, your specializations and credentials are indexed, and your digital presence begins strengthening. Consumers and AI tools start picking up your Wealthtender profile (typically within a day of signing up). You may not receive a direct inquiry in this early window, but your footprint is already expanding.
Over months 3–12, as you collect client reviews and your profile becomes richer, your visibility in Google and AI search grows. Each additional review is an independent piece of content indexed by search engines, a trust signal for AI tools, and a piece of social proof for any prospect researching you. The compounding effect of reviews accumulating over time is significant.
Over the long term, advisors with a strong presence on Wealthtender, particularly those who actively collect reviews, can expect the most meaningful impact on their business. And we’re grateful for the advisors who have consistently rated Wealthtender near the top of its category in the annual T3 Advisor Software Survey, reflecting strong advisor advocacy year after year. That recognition reflects long-term value, not overnight results.
The most successful Wealthtender advisors tend to share three habits: they keep their profile complete and up to date, they systematically invite clients to write reviews, and they pair their Wealthtender digital marketing benefits with their established sales and marketing tactics to attract and convert the right prospects at the right time.
Tips to Maximize Your Wealthtender Benefits
Knowing what Wealthtender does is one thing. Getting the most out of it is another. These are the habits and features that separate advisors who see compounding returns from those who wonder why the platform isn’t doing more for them.
Complete your profile thoroughly. AI tools strongly favor complete, detailed profiles. Fill in every section: specializations, credentials, geographic information, fee structures, a bio written in the language your ideal client uses, and a video if possible. A half-completed profile is a missed opportunity.
Free Profile Check
Could your Wealthtender profile be working even harder for you?
Paste your profile URL below and get personalized, AI-powered tips in less than 2 minutes. Of course, when it comes to artificial intelligence, it’s no replacement for OG AI: “Actual Intelligence”; We encourage you to speak with your marketing counterpart and your compliance officer before making updates to your profile.
How would you like your feedback?
Reading your profile…
Checking reviews, bio, video, booking links, and more.
This typically takes 60–90 seconds — your personalized report is worth the wait.
Your profile report
📌 Important reminder
This analysis is AI-generated based on a review of your public profile page. While the guidance should prove helpful, please consider it directional and remember there’s a difference between “artificial intelligence” and “actual intelligence” (OG “AI”). For the best guidance and recommendations to improve your profile, please speak with your marketing counterpart or a qualified marketing consultant with experience serving financial advisors. And of course, always speak with your compliance officer for their guidance and approval before making any changes. Questions? yourfriends@wealthtender.com
Collect reviews consistently. This is the single highest-leverage action you can take. Set up a simple, repeatable process: 60–90 days after onboarding a new client, send them an invitation to write a Wealthtender review. Aim for at least 10 reviews in your first year. Even a handful of thoughtful, detailed testimonials can dramatically strengthen your visibility in both Google and AI search tools — and give you a structural competitive advantage over the 90%+ of advisors who have no online reviews at all.
Embed reviews on your website. Every plan includes the ability to display Wealthtender reviews on your website via a compliant widget. Use it. Prospects who land on your site should see social proof immediately, in an SEC-compliant format you can actively promote.
Participate in media opportunities (Convert and Command Plans). Being quoted in popular publications builds credibility, strengthens SEO, and sends trust signals to AI tools. These opportunities come to your inbox weekly — take advantage of them.
Use the FAQ feature strategically (Convert and Command Plans). AI-optimized FAQs with schema markup on your profile are among the most powerful tools for appearing in AI-generated answers. Write FAQs the way your ideal clients actually ask questions — “Does [Your Name] offer retirement planning services for Google employees in the Bay Area?” — rather than generic questions about what financial planning is. Wealthtender automatically applies schema markup so AI tools can extract and cite your answers directly.
Participate in Large Employer Q&As (Convert and Command Plans). If you serve employees of major companies, these features target highly specific, high-intent searches that can produce exceptional results — as the advisor story earlier in this article illustrates. The cost is built into your subscription. The payoff can be substantial.
A Note for Advisors on Legacy Wealthtender Plans
If you joined Wealthtender on one of our older subscription plans (e.g., Growth Essentials, Growth Premier, or Marketing Pro), here’s the most important thing to know: nothing changes unless you want it to. Your pricing and features are currently grandfathered, so you keep what you have at your current price.
In July 2026, we introduced three new plans and features reflecting how much the platform has grown and introducing more ways to show up in AI search and accelerate the trust-building process with prospects: Convert, Compound, and Command. The names describe a progression: convert prospects into clients, compound your reputation over time, then command your market or niche.
Convert ($59/month, or $54/month with annual billing) is the new foundation, and it includes benefits like weekly media quote opportunities and placement in up to four specialist directories, alongside your SEO and AI-optimized profile and Certified Advisor Reviews.
Compound ($79/month, or $73/month with annual billing) adds AI-Optimized FAQs with automatic schema markup, Testimonial Marketing Studio, and your first Large Employer Q&A participation.
Command ($99/month, or $92/month with annual billing) adds a professionally designed, AI-optimized Firm Focus Page built on Wealthtender’s domain authority, upgrades your Large Employer Q&A participation to Tier 1 employers, and includes 10% savings on all add-ons.
If you’d like access to any of these newer benefits, you can migrate at any time. As a thank-you for your early support, legacy subscribers receive a 15% loyalty discount off the new plan rate when choosing to migrate by December 31, 2026. And if your current plan still fits your practice, staying put is a perfectly good decision, too.
You can compare all plan features in detail on our pricing page, or email yourfriends@wealthtender.com and we’ll help you decide whether migrating makes sense for you. No pressure either way. The right plan is the one that matches where you are in your practice growth today.
A Powerful Complement to Other Marketing Strategies
Wealthtender works best as part of a broader marketing strategy, not as a replacement for one.
If you’re using SmartAsset or another lead generation platform, Wealthtender can make that investment significantly more productive. When those leads Google you or ask ChatGPT about you – and research shows 96% of prospects who receive a referral will research you online before reaching out – a credible, review-rich Wealthtender profile accelerates trust and increases conversion. A prospect who arrives already knowing you’re credible closes at a fundamentally different rate than one who finds nothing when they search your name.
If you’re building your practice through referrals, networking, and word of mouth, Wealthtender validates those relationships digitally at the exact moment it matters, when a prospect is doing their research before reaching out.
If you’re investing in content marketing, PR, or social media, Wealthtender’s directory placement and independent review platform reinforce your messaging with third-party credibility that your own content can’t provide alone.
And if AI-driven search is something you’re paying attention to (as it should be, given how rapidly consumer behavior is shifting) Wealthtender is currently the most purpose-built platform in our industry for ensuring you appear favorably in answers generated by ChatGPT, Perplexity, Claude, Gemini, and Google AI Overviews.
In Summary: Is Wealthtender Worth It for You?
If you’re wondering whether Wealthtender is working for you, here’s the honest answer: it’s almost certainly doing more than you can directly measure.
Your profile is being indexed. Your reviews are being read by prospects and AI tools alike. Your specializations are helping you get noticed by consumers looking for someone with your exact expertise. And when the right prospect is ready to reach out, you’re positioned to be found first and trusted immediately.
Direct inquiries that reference Wealthtender by name are a bonus, and a meaningful one when they occur, given the quality of prospects they represent and the extraordinary ROI a single new client can generate. But they represent only a fraction of the value Wealthtender delivers every day.
We’d love to offer the kind of recurring dopamine hits that pay-per-lead platforms deliver, but those hits come at a cost of $200 or more each, adding up to $25,000 to $50,000 a year. So while the full value of your Wealthtender subscription may not always be directly measurable, the money you’re not spending on frequent lead notifications absolutely is. That’s a dopamine hit worth savoring every time you look at your marketing budget.
The advisors who see the greatest returns are those who treat Wealthtender as the long-term investment it is and who give it the time and consistency to compound. If you’d like help assessing how your profile is set up or want to talk through your digital marketing strategy, we’re always happy to talk shop. Reach out to us anytime at yourfriends@wealthtender.com.
Frequently Asked Questions
How long does it take for advisors to see results after joining Wealthtender?
For SEO and AI visibility improvements, the benefits of joining Wealthtender begin accumulating from the moment your profile is published, typically within a day or two of joining. For direct prospect inquiries, there’s no predictable timeline. Some advisors receive their first inquiry within weeks; for others it may take months, and it’s very possible to experience tremendous success attracting leads and converting clients without prospects using the ‘Contact Me’ button on your Wealthtender profile if they instead schedule an intro call from your linked calendar or reach out to you directly. The advisors who see the most meaningful long-term results are those who invest consistently in collecting client reviews and keeping their profile up to date. Think of it as a marathon strategy where the compounding effect grows over time.
How does Wealthtender help me show up in ChatGPT, Gemini, and other AI tools?
Wealthtender profiles are built with structured data, schema markup, and content architecture specifically designed for AI parsing. When someone asks an AI tool about financial advisors in your specialty or location, or asks what clients say about you, Wealthtender’s authoritative domain and independently-hosted reviews signal to AI systems that your information is reliable and worth citing. AI tools consistently weight independent third-party review platforms more heavily than advisor websites because they recognize them as unbiased sources. The more complete your profile and the more reviews you have, the stronger this effect. Read the full guide to AI visibility.
Why do I need Wealthtender reviews if I already have Google reviews?
Google reviews have two significant limitations for financial advisors. First, they lack the SEC-required disclosures for testimonials, which means you can’t actively promote them in your marketing without triggering compliance issues. Second, Google reviews have very limited visibility in AI-powered search environments, including Google’s own Gemini AI (as of Q1 2026). Wealthtender reviews are compliance-first by design, can be actively promoted across all your marketing channels, and are structured to be indexed and cited by the full range of AI tools including ChatGPT, Perplexity, and Claude. You can also import your Google reviews to Wealthtender to convert them into compliant testimonials and amplify their impact. Read the full comparison.
A prospect mentioned they found me on Wealthtender. How should I track this?
Ask every new prospect how they found you and listen carefully when they answer. Some may say Wealthtender directly. Others may say ‘I found you through a Google search or ‘ChatGPT recommended you’ without realizing Wealthtender played a role in surfacing your name. Because Wealthtender intentionally removes friction for consumers (they can contact you directly without gatekeeping), we don’t track attribution the way a pay-per-lead platform would (and that happily charges you hundreds of dollars each time). What we do provide is our ongoing commitment to building upon the investments we’ve made since 2019 into the Wealthtender platform to deliver industry-leading SEO and AEO (Answer Engine Optimization) benefits to ensure your profile strengthens your reputation, improves your ranking in Google, and increases how frequently and prominently you show up in AI search tools like ChatGPT and Gemini.
I’m on a legacy plan (Growth Essentials, Growth Premier, or Marketing Pro). Am I missing out on important benefits?
You’re not missing the fundamentals. Every legacy plan includes the highest-leverage benefits for most advisors: an SEO/AEO-optimized profile, directory placement, the industry’s leading compliant review platform, the ability to embed reviews on your website, and eligibility for Voice of the Client Awards. Those keep working for you exactly as they always have, at your grandfathered rate.
What legacy plans don’t include are the benefits introduced with our newer Convert, Compound, and Command plans. The most significant is the Firm Focus Page included with Command: a professionally designed, AI-optimized page showcasing your firm or niche, built on Wealthtender’s domain authority. The new structure also moved weekly media quote opportunities and specialist directory placements into the base Convert plan, expanded Large Employer Q&A participation with employer tiers, and bundled AI-Optimized FAQs and the Testimonial Marketing Studio into Compound and above.
If any of those would meaningfully advance your marketing strategy, you can migrate at any time, and legacy subscribers receive a 15% loyalty discount off the new plan rate when migrating by December 31, 2026. If not, there’s no need to change anything. Compare all plan features here, or email yourfriends@wealthtender.com and we’ll give you an honest read on whether migrating is worth it for your situation. Compare all plan features here.
I joined Wealthtender several months ago and haven’t received any direct prospect inquiries. Is something wrong?
Not necessarily. While direct prospect inquiries through Wealthtender (e.g., prospects clicking the ‘Contact Me’ button) represent one way a prospect may choose to reach you, they might also schedule a call with you directly through your calendar linked from your Wealthtender profile, or they may visit your website or prefer to call you. Unlike other platforms that ‘gatekeep’ leads, we eliminate friction by letting prospects choose multiple ways to get in touch with you.
And unlike pay-per-lead platforms where advisors can dial lead flow up and down, episodic prospect inquiries are expected and by design, because consumers using Wealthtender always remain in control to reach out when they choose. Also unlike pay-per-lead platforms, prospects who do reach out to you are ‘bottom-of-funnel intent’, meaning they’re much more likely to be ready to hire and a great fit as they’ve spent time researching you and you’ve made their short list for consideration.
Beyond direct inquiries you may receive periodically through Wealthtender, it’s important to remember your profile is showing up in Google searches and AI-generated answers, and prospects who have been influenced by that visibility may have reached out through your website, booked a call directly from your calendar link, or simply not mentioned Wealthtender when they contacted you. The best thing to do is make sure your Wealthtender profile is complete and remains current, start collecting reviews if you haven’t already, and try some of the AI prompts in this article to see your own visibility firsthand.
I collected a few reviews early on but haven’t added more since. Does that matter?
Yes. Review velocity matters to both search engines and AI tools. While it’s still less of an issue for financial advisors since you’re among just 10% of advisors who have online reviews at all, a profile with just a handful of reviews from three years ago sends weaker signals than a profile where reviews accumulate steadily over time. Fresh reviews signal an active practice with ongoing client satisfaction. We recommend making review collection a regular, systematic habit: identify clients at the 60–90 day mark after onboarding and extend a personal invitation. Invite all of your clients to write a review on the anniversary of your firm. A week after your annual client review meeting, invite each client to share their feedback that could help others decide if they’re a good fit to work with you, too. Even adding two or three reviews per year compounds meaningfully over time. https://wealthtender.com/advisors/marketing/financial-advisors-ongoing-client-testimonial-outreach/
Can I use my Wealthtender reviews in my own marketing materials?
Yes, and doing so is one of the most important ways to maximize the ROI of your reviews. Because Wealthtender reviews include the regulatory disclosures required under the SEC Marketing Rule, you can actively promote them using widgets on your website and elsewhere, though it’s important to speak with your compliance counterpart first and also note the additional disclosure requirements for promoting a single testimonial or curated selection of your reviews (Refer to the guide linked below for compliance tips.) Keeping compliance in mind, you can share your reviews on social media, embed them on your website via the Wealthtender widget or your own website provider’s carousel tools, referencing them in email nurturing campaigns, and using them in presentations with prospects attending seminars and webinars. Advisors on the Marketing Pro plan also have full access to Wealthtender Testimonial Marketing Studio, which makes it easy to create compliant social media graphics and marketing assets from your reviews with just a few clicks. Learn how to promote your reviews compliantly.
Is there precedent in other trust-based professions where platforms like Wealthtender have proven to work?
Yes, and it’s one of the most compelling arguments for why this model works in financial services. Think about how patients find and choose physicians today. Platforms like Healthgrades, Zocdoc, and Vitals built independent, third-party review ecosystems for healthcare professionals, and those platforms now fundamentally shape how patients discover, research, and select doctors. When someone receives a referral to a physician, they search for that doctor in Google or an AI search tool and land on one of these platforms to read reviews and narrow their shortlist before booking an appointment. AI tools citing those platforms have amplified that dynamic further. The legal profession has seen the same evolution through platforms like Avvo and FindLaw. Financial services has historically lagged in this area, in part because the SEC’s previous rules on testimonials restricted advisors from collecting and promoting client reviews. The 2021 update to the SEC Marketing Rule changed that, and Wealthtender was built from the ground up to take advantage of this shift. We are, in a meaningful sense, in the early innings of financial services catching up to what healthcare and legal have already proven.
How does the cost of Wealthtender compare to similar platforms in other professions?
Favorably — very favorably. A Healthgrades premium profile for a physician runs several hundred dollars per month. Avvo’s paid attorney plans are similarly priced. Wealthtender offers comparable infrastructure specifically built for financial advisors – including the SEC regulatory compliance architecture that healthcare and legal platforms don’t need to address – starting at $45/month (annual billing). When you factor in the SEO and AI visibility benefits, the media exposure, the directory placement, and the review platform, the value-to-cost ratio is difficult to match in any comparable profession. The more relevant comparison isn’t what Healthgrades charges physicians, it’s what happens to advisors who let competitors build that infrastructure while they wait.
Even More FAQs
Q: I hear what you’re saying, but it feels like you’re promoting Wealthtender as an elixir without showing real proof. What am I missing?
That’s a fair challenge, and we’d rather engage with it honestly than brush past it. Here’s what the evidence actually shows.
What independent research says. The 2024 Kitces Research Marketing Survey, a rigorous, independent study of financial advisor marketing tactics, found that online advisor directory listings have the lowest client acquisition cost ($634) and highest marketing efficiency (3.4) of any tactic studied across 14 categories (See report screenshots excerpted below). The Kitces team specifically called out directory listings as one of the two “most underappreciated marketing tactics” in the industry. Wealthtender is the most comprehensive advisor directory built specifically for the era of AI search and SEC-compliant reviews. That independent finding isn’t about Wealthtender specifically, it’s about the category. We happen to be the most purpose-built platform in that category.
The same study also noted that review sites (which Wealthtender combines with directory listings in a single platform) are seeing adoption grow rapidly since the SEC’s 2022 Marketing Rule update clarified advisors’ ability to use them and projected that their prominence will only increase. Wealthtender was specifically named as the most utilized industry-specific online review platform being monitored and used for marketing by advisors in the study.
What industry reports say. Wealthtender has consistently earned top ratings in the T3 Advisor Software Survey (Digital Marketing Tools – Lead Capture category). These ratings reflect feedback from advisors using the platform. A Barron’s article published in November 2025 covered how Wealthtender is helping financial advisors get found in AI search tools, featuring named advisors who received qualified inbound inquiries directly attributable to their Wealthtender presence. We have case studies like United Financial Planning Group, where reviews on Wealthtender directly influenced a prospect to choose an independent firm over a national wirehouse, a prospect who explicitly cited what they read on the platform as the reason they made contact. And we have lots of documented prospect messages from high-quality leads, physicians, Google engineers, retirees with multi-million-dollar portfolios, who found advisors specifically through their Wealthtender profiles.
The compliance credibility runs deep, too. After reviewing Wealthtender’s platform and review process, the Chief Compliance Officer of a Barron’s Top 100 RIA firm said simply: “I reviewed Wealthtender and their client review process, and I am good with it — I actually really like their process.” For advisors whose compliance teams need to sign off before joining, that kind of peer-level endorsement from a top-ranked firm’s CCO speaks volumes.
What we can’t offer is a SmartAsset-style guarantee of X leads per month. That’s not what Wealthtender is. If you need that kind of guaranteed volume, we’d genuinely tell you to look at a pay-per-lead platform (and then also join Wealthtender to make those leads convert better). But if the question is whether Wealthtender delivers measurable value beyond what most advisors expect when they sign up, the answer is yes, and both the independent research and 800+ advisors and firms who have chosen to partner with us bear that out. Read what financial professionals say about Wealthtender here.
How does the cost of Wealthtender compare to similar platforms for financial advisors?
Within the financial advisor industry, there are two meaningful comparison categories.
Category 1: Review collection tools designed to publish testimonials on your own website. Platforms like FMG Testimonials (FMG’s acquisition of Testimonial IQ, rebranded in early 2026) and Amplify Reviews are capable, well-built tools that do what they set out to do: collect compliant client testimonials and display them on your own website. We have a lot of respect for their founders and teams who share our passion for providing compliance-first solutions to collect and publish testimonials. If you’re using one of these tools, you’re already ahead of roughly 90% of advisors who use no testimonials in their marketing at all.
But there’s an important gap between collecting a testimonial and maximizing its impact, and that gap is exactly where Wealthtender comes in.
When a testimonial lives only on your website, it reaches people who have already found their way to you. Wealthtender functions as the amplification layer: your reviews are published on an independent, high-authority third-party platform that is indexed by Google, cited by AI tools, and visited by 500,000+ consumers annually. That means your testimonials are working to reach people who don’t yet know you exist.
There’s also a credibility dimension. AI tools explicitly weight reviews on independent third-party platforms more heavily than testimonials published on advisor websites, which they recognize as self-curated. Getting your reviews onto Wealthtender in addition to your own site doesn’t replace what FMG Testimonials or Amplify does, it dramatically extends its reach and impact.
Importantly, these review-only tools also carry no find-an-advisor consumer destination, no specialist or local directories, no media quote opportunities, and no Large Employer Q&A features. And notably, Wealthtender’s pricing is lower than some of these review-only tools despite offering substantially more. Advisors who use FMG Testimonials or a platform like Amplify Reviews can choose to pair it with Wealthtender specifically for the third-party amplification and consumer discovery that their existing tool can’t provide. Read more about how FMG Testimonials and Wealthtender work together.
Category 2: Third-party review platforms for financial advisors. Indyfin (now operating under WiserAdvisor following their 2025 acquisition) offers a more direct comparison in that it’s a third-party platform where advisors can collect and publish compliant reviews independent of their own website, similar to what Wealthtender does. That independent positioning is genuinely valuable, and we acknowledge it.
But the platforms are not equivalent, and the shortcomings of Indyfin relative to Wealthtender are significant. The key differences summarized below help explain why multiple advisors and wealth management firms have left Indyfin and migrated their online reviews to Wealthtender.
On pricing: Indyfin charges $99/month for a single advisor. Wealthtender’s Convert plan starts at $59/month, meaning Wealthtender’s entry-level plan costs significantly less than Indyfin. Advisors who choose Indyfin over Wealthtender are paying more for less.
On reach and discoverability: According to data from Ahrefs and Moz, Wealthtender receives approximately 63,700 monthly visitors compared to Indyfin’s 967, roughly 66 times more consumer traffic. Wealthtender’s domain authority is 42 versus Indyfin’s 18, meaning Wealthtender’s profile pages carry significantly more weight with Google and AI tools when surfacing your name in search results. (For the most current figures, see the data disclosures on our Indyfin comparison page.)
On features Indyfin doesn’t offer: The gap extends well beyond traffic. Wealthtender provides media quote opportunities, specialist and niche directories, Large Employer Q&A features, AI-optimized FAQs with schema markup, Voice of the Client Awards, the ability to convert Google Reviews to SEC-compliant testimonials, and Testimonial Marketing Studio for creating social media content from your reviews. None of these exist in Indyfin’s platform.
What does independent industry data say? The T3 Technology Survey, one of the most widely cited independent assessments of advisor technology, has listed Wealthtender in its Digital Marketing Tools – Lead Capture category and consistently rated us among the highest in the category. In the 2025–2026 survey, Wealthtender earned an average user rating of 7.68 (2026) and 7.96 (2025) — among the highest scores in the category — and remains the only independent third-party directory and review platform in the category that combines a compliant review platform, a high-traffic consumer-facing find-an-advisor destination, and a full digital marketing suite in a single subscription. We’re proud of those ratings, which reflect feedback from advisors who use the platform, not from us.
The bottom line: for advisors who simply want a widget to display reviews on their own website, there are capable tools that do exactly that. For advisors who want their reviews, profile, and expertise to be discoverable by consumers and AI tools across the internet, and who want the credibility that comes from an independent third-party platform with real domain authority, Wealthtender stands in a category of its own within the financial services industry.
If my state regulator or home office doesn’t yet allow me to use online reviews, is Wealthtender still worth it?
We want to be completely honest with you here, because this is a question that deserves a straight answer: the inability to collect and publish client reviews does take away from one of the most powerful features Wealthtender offers. Reviews turbocharge the engine for AI visibility, SEO strength, and conversion-rate improvements we discuss throughout this article. We know that, and we don’t want to pretend otherwise.
We also know there are advisors who are waiting specifically for the green light on reviews before they sign up for Wealthtender, and we completely understand that position. If the reviews feature is the primary reason you’re interested in joining, it’s fair to wait until you have the ability to use it fully.
If you’re in this situation, we want you to know that we hear your frustration and we’re actively working on your behalf. Wealthtender has published research and engaged media coverage specifically to shine a light on the regulatory double standard that currently prohibits state-registered advisors in roughly 20 states from collecting and publishing client reviews, even as their SEC-registered counterparts and large national firms are free to do so. We’ve been engaged in ongoing conversations with state regulators, and we’ve found that our advocacy work and media efforts have been helpful in moving the needle. Several states have updated their rules in recent years, and we expect that progress to continue. We’re also in active, constructive conversations with a growing number of broker/dealer home offices, conversations that have increasingly proven fruitful, in part because we’ve built Wealthtender to be the “Boy Scout” of the industry when it comes to regulatory compliance. CCOs at firms including Barron’s Top 100 RIA practices have reviewed our platform and praised our approach. We’ll keep chipping away.
That said, a meaningful number of advisors are currently using Wealthtender even without reviews activated, and getting real value from it. Here’s why:
Your SEO/AEO-optimized profile begins working the moment it’s published, strengthening your visibility in Google searches and AI tools based on your specializations, credentials, location, and the overall authority of Wealthtender’s domain. Your placement in local, specialist, and designation directories puts you in front of consumers who are actively searching for someone like you. Media quote opportunities (Convert plan and higher) give you a consistent avenue to build credibility and gain backlinks from publications your prospects read. Large Employer Q&A features can make you discoverable through highly targeted searches by employees of specific companies in your area. And when your home office or state regulator does eventually grant approval for reviews, as we expect they will, your Wealthtender profile is already established, your profile traffic is already building, and you can activate the reviews feature immediately without starting from scratch.
For advisors in this position, we’d suggest thinking of Wealthtender the way you might think of planting a tree: the best time to have started was a year ago, and the second best time is today. The reviews feature, when available to you, will layer on top of a foundation that’s already working.
What if I want to cancel my Wealthtender subscription? Will I lose my reviews?
You can cancel at any time as there’s no long-term commitment on monthly plans. If you do choose to cancel, your Wealthtender profile is removed from public visibility and you’re no longer able to publicly display reviews or actively collect new reviews through the Wealthtender platform. However, the reviews that were published on Wealthtender are available for you to export and our team is always happy to assist you with the download. And if you decide to reactivate your Wealthtender subscription in the future, we’re happy to reinstate your reviews previously collected on Wealthtender to display on your profile.
Want to see how individual advisors and leading wealth management firms are successfully using Wealthtender to grow their business? Visit Wealthtender.com/grow or schedule a demo to learn how you can start converting more prospects into clients with the industry’s first digital marketing platform for AI-optimization and compliant online reviews.
About the Author
Brian Thorp
Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian
Book a Demo
Select a day in the calendar below to schedule a meeting with Brian Thorp, Wealthtender founder and CEO.
Find financial advisors in Spartanburg, South Carolina ready to help with your financial planning needs so you can enjoy life more with less money stress.
Whether you have lived in Spartanburg for years or recently moved to town, you may need help finding the right financial advisor in the community best suited for your individual needs.
It’s important to first consider your own financial planning priorities before choosing an advisor. Here are a few quick tips to help you get started along with financial advisors in Spartanburg featured on Wealthtender you may want to add to your shortlist.
Featured Spartanburg Financial Advisors
As you prepare to interview financial advisors in Spartanburg who may be right for you, get to know local financial advisors featured on Wealthtender.
📍 Map: Financial Advisors with their Primary Office Location in Spartanburg
Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in Spartanburg.
The Benefits of Hiring a Financial Advisor in Spartanburg
Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.
As a resident living in Spartanburg, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.
Do you work for one of the largest employers in Spartanburg? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.
When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.
Quick Tips For Hiring a Spartanburg Financial Advisor
Before hiring a financial advisor in Spartanburg, here are a few quick tips to help you find the best advisor for you.
1. Decide Which Services You Need
Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.
Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:
Budgeting and money management
Debt management
Insurance planning
Retirement planning
Other investment planning
Inheritance planning
Estate planning
Tax planning
As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor that specializes in those areas.
Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.
2. Consider Your Budget and Payment Preferences
Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.
If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.
3. Interview Multiple Financial Advisors
Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:
What services do you provide?
What are all the ways you get paid? (fee transparency)
What is your investment strategy?
How do you measure investment performance?
How do we communicate about my plan?
Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.
4. Review Financial Advisor Credentials
Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website.
You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.
As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.
For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.
Frequently Asked Questions & Additional Resources
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit.
But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings.
Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a local financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Please click here to learn how you can join local financial advisors featured on Wealthtender.
Brian is CEO and founder of Wealthtender and Editor-in-Chief. He and his wife live in Austin, Texas. With over 25 years in the financial services industry, Brian is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress. Learn More about Brian
I recently attended the Basis Northwest Conference in Seattle, which centered around tax-aware investments and how the landscape is changing. About 30 years ago, ETFs were the hot new thing. But as wealth continues growing and incomes rise, they’re not enough to meet the demands of high-net-worth investors. More often, clients are coming to me focused on achieving greater after-tax return through more sophisticated tax strategies, and a few potential strategies stand out.
What Tax Strategies Are Gaining Traction?
Traditionally, certain tax-aware investing tools were limited to institutional investors and the ultra-wealthy. However, many of those have recently become accessible to individual investors. While the following approaches won’t work for everyone, these strategies are worth considering:
Tax-aware long/short: Tax-aware long/short strategies aim to generate losses used to offset realized gains while maintaining market exposure.
351 exchanges: Investors contribute appreciated securities into a diversified investment vehicle without immediately triggering capital gains taxes. For those with a large position in a single stock, a 351 exchange offers diversification while deferring the tax consequences of a sale.
Tax-aware hedge funds: Certain hedge fund structures try to generate losses or deductions that can offset other sources of taxable income (including W-2 income or Roth conversions).
Oil and gas exploration: Direct investments in oil and gas exploration can provide substantial tax deductions, often allowing investors to deduct a significant portion of their investment in the early years.
Real estate depreciation: Real estate investors benefit from depreciation deductions, which reduce taxable income even as the underlying property potentially increases in value.
Box-spread loans: A relatively new strategy, box-spread loans use your existing investments as collateral to offer reduced interest rates on loans. Box-spread loans tend to benefit those who need liquidity but prefer not to sell appreciated investments outright.
Incorporating Tax-Aware Strategies Into Your Portfolio
Many of the strategies shared above are beyond what’s available through a standard custodial platform or typical advisor relationship. Because they lack accessibility, the number of investors able to implement these more sophisticated tax-aware strategies is limited.
But for those who are able and willing to try, the next hurdle is understanding how these strategies fit together and when they make sense.
Let’s take, for example, an investor with a substantial amount of concentrated single company stock they’ve accumulated over many years. Selling this highly appreciated stock outright to reduce concentration would create a significant tax bill. Instead, they may pursue a tax-aware long/short strategy, which would generate potential losses that help offset future gains. At the same time, they might explore a 351 exchange that would help diversify some of those concentrated holdings without triggering capital gains tax.
Or, consider a business owner preparing to sell their business. Negotiating the highest sale price is important to them, but so is preserving as much after-tax proceeds as they’re able. Again, tax-aware long/short strategies could help offset a portion of that eventual gain and improve the overall after-tax outcome.
Investors with large 401(k) balances or cash balance plans may want to pursue Roth conversions during favorable tax years. Tax-aware hedge fund strategies aim to create deductions or losses that make those conversions more tax-efficient.
An investor with a need for liquidity — for example, if they’re purchasing a new home — may not want to liquidate appreciated investments to access cash. Similarly, an investor committing capital to a private equity opportunity may prefer to leave an existing portfolio intact. In those situations, a box-spread loan can bridge the gap, providing access to capital while allowing the underlying investments to remain invested.
Keep More of What You Earn
What you keep matters as much as what you earn. The investors who understand that plan for taxes year-round, not just in April. It takes strategic planning and careful consideration to find the right mix of tax-aware tools for your specific needs.
IPOs and the excitement surrounding them tend to bring out investors’ emotional biases. Fear of missing out on big potential gains, excitement over the “hot stock” everyone’s talking about, or the optimistic belief that a company’s recent growth means more is coming—these can all influence an investor’s decision-making process.
When a well-known company finally goes public, investors are presented with an opportunity to participate in a story they’ve likely been following for years. Recently, SpaceX and other big names have generated significant attention, with many investors eager to gain exposure before the next potential chapter of growth unfolds.
If you do decide to buy, it’s worth understanding the mechanics behind an IPO and the volatility that tends to come with it. There are ways to both participate in an exciting event like an IPO and consider your long-term financial well-being at the same time. The key is to be strategic, think with a clear head, and keep the potential tax consequences of large gains in mind.
The Nature of IPO Pricing
When a company goes public, it establishes an initial offer price for its shares. That’s all well and good. But once public trading begins, the market ultimately determines what investors are willing to pay. Shares often begin trading at a different price from the original IPO offering price.
A highly anticipated IPO might surge immediately. Other times, shares open flat or even decline. While there’s plenty of excitement surrounding a new public offering, no one knows exactly how the market will respond once trading begins.
Remember, recently IPO’d companies are still relatively early-stage businesses. They’ve demonstrated impressive growth, but they haven’t yet established a consistent path to profitability.
Take Uber as an example. Despite being one of the most recognizable companies to go public in recent years, the stock initially struggled to meet expectations. It took roughly five years after its IPO to achieve profitability. Since going public, it’s actually lagged behind the S&P 500.
Even exciting companies can experience significant volatility and long periods of uncertainty before their business results fully catch up to investor expectations (though there’s no guarantee they ever will).
Preparing for IPO Volatility with Strategic Asset Location
Considering where an investment should live within your portfolio is a commonly overlooked strategy called “asset location.” Different types of accounts carry different tax treatments and consequences. Investors can pair tax-efficient or inefficient assets with the accounts that will best complement their attributes.
For example, a Roth IRA allows qualified growth and withdrawals to occur tax-free. Tax-deferred accounts, such as traditional IRAs, generally allow investments to grow without immediate taxation, with taxes deferred until funds are withdrawn.
Investments with the potential for substantial appreciation are often well-suited for these types of accounts. If an IPO investment performs well, future gains may be shielded from current taxation or deferred for years, depending on the account structure.
When capital gains are realized in a taxable account, they can create an immediate, sizable tax bill. Frequent trades may also be considered taxable events and reduce after-tax return.
Tax-sheltered accounts mitigate tax drag and allow more of the investment’s potential growth to remain invested over time.
That said, an asset location strategy doesn’t make the investment itself safer for your portfolio. Risk and volatility still exist regardless of what account the investment lives in. A company can still disappoint investors, miss expectations, or experience sharp price swings. Rather, considering different account types and their tax characteristics gives you the ability to better control the eventual tax outcome.
When Do Taxable Accounts Make Sense?
Taxable accounts may still be suitable in certain situations, especially if you have access to a tax-reduction wrapper plan such as a long/short strategy.
A long/short strategy can be used to offset gains by intentionally realizing losses elsewhere in the portfolio. Tax-management strategies like this give investors greater flexibility when deciding where to hold a high-growth IPO allocation.
Want to Take Part in the Next IPO?
Investment performance impacts returns, naturally. So does the tax treatment, which can differ depending on where you choose to house investments with significant growth potential.
If you’re tempted to take part in a recent or soon-to-come IPO, consider both the investment opportunity and the tax implications. Strategic decisions, including asset location, can help position your portfolio to keep more of what you earn, especially if the investment succeeds.