Aaron Foresman, CFA, Portfolio Manager for the Managed Income Strategy at Crawford Investments | Image Credit: Institute for Innovation Development
[A number of investment strategies were born specifically from a desire to solve personal, real-world problems or unmet investor needs. The Crawford Managed Income Strategy is a great example of an investment solution that was engineered for investors that were having a hard time generating income from traditional balanced stock/bond portfolios.
To better explore this investment solution, we were introduced to Aaron Foresman, CFA, Portfolio Manager for the Managed Income Strategy at Crawford Investments. We asked him questions to understand how this strategy attempts to strike a favorable balance between current income and risk mitigation across equity market risk, interest rate risk, energy risk, and credit risk.]
Hortz: Can you describe your investment philosophy and what motivated you to develop this multi-asset income strategy?
Foresman: I was actually prompted by my father around 2012, who asked me a question about how to generate more income in retirement. At that time, investors were having a hard time generating income from traditional stock and bond portfolios as yields declined materially. I began thinking through how he might supplement a traditional balanced account with other asset categories to generate a high level of income while providing diversification. The Managed Income strategy emerged as an attractive, objectives-based solution to a legitimate, real-world problem.
In 2014, the same year I joined Crawford, I began building the portfolio out in my personal IRA account. I recognized that I could produce an alternative that generated close to 5%+ income in a world where high-quality bonds were yielding just a fraction of that. While it would require taking on more risk, I knew by clearly identifying the four major risk categories – interest rate risk, energy price risk, stock market risk, and credit risk – that I could offset individual, security-specific risks against one another. In sum, through a process of disaggregation and analysis, the strategy seeks to mitigate risk through diversification and balancing, hence, offsetting as much single holding risk against other holdings as possible.
Today, the philosophy remains consistent. We continually search for what we believe to be the highest quality securities available in the higher income subsets of the capital markets, while managing the portfolio to strike a favorable balance between current income and risk mitigation.
Hortz: What role does a “quality” investment criteria play in your investment decisions?
Foresman: Quality plays a central role in all of our investment decisions at Crawford. We search for the highest-quality investments available in the higher yielding subsets of the capital markets that we cover.
More specifically, we believe that investors seeking income in a lower-yielding environment often reach for yield in lower-quality, higher-volatility securities, which we view as a poor risk-and-reward tradeoff. Instead, we focus on high-quality securities with sustainable income, strong fundamentals, and attractive valuations to help reduce volatility and improve long-term outcomes.
Hortz: What is your investment process across your equity, preferred equity, and corporate bond portions of your portfolio, and how does your investment team structure support that process?
Foresman: Our process is grounded in deep fundamental research and supported by distinct but highly collaborative equity and fixed-income teams.
Within dividend-paying equities, energy infrastructure, and real estate, our equity team conducts bottom-up analysis focused on companies with low earnings variability, strong balance sheets, differentiated business models, and proven management teams.
For preferred securities and corporate bonds, we leverage close coordination between our equity and fixed income teams. This allows us to selectively invest in securities where we already have a strong understanding of the underlying business, enhancing our ability to assess risk and identify relative value.
Importantly, our structure includes a dedicated equity research team alongside a separate fixed-income team, creating consistent cross-pollination of ideas. We believe this integrated approach is a meaningful advantage, particularly in higher-yielding areas of the market where credit and equity perspectives often intersect.
Hortz: How do you exploit inefficiencies across your key investment sectors in your portfolio?
Foresman: Higher-income segments of the capital markets are often less efficient, as they are dominated by income-focused investors who may underappreciate underlying risks. We seek to capitalize on these inefficiencies through disciplined security selection and deep fundamental research.
In dividend-paying equities, we leverage our longstanding expertise in equity income investing to identify high-quality companies that can deliver both income and total return, rather than simply screening for yield.
In energy infrastructure, we favor C-corporation companies over MLPs, focusing on investment-grade businesses with mission-critical assets, strong free cash flow, and durable balance sheets.
Within REITs, we benefit from public market liquidity while investing across a diversified mix of property types, balancing more offensive sectors such as data centers and industrials with more defensive areas like medical offices and triple-net lease real estate.
In preferred securities, we believe our active approach provides a significant advantage over passive vehicles. The market is fragmented and heavily concentrated in financial issuers, with many securities being small, illiquid, and often mispriced. Our ability to manage call risk, focus on qualified issues, and selectively invest in fixed-to-floating structures allows us to identify more attractive opportunities.
In corporate bonds, the size and complexity of the market create opportunities for selective investing. Our collaboration between equity and fixed income teams enables us to “cherry pick” bonds where we have high conviction in the underlying issuer, improving our ability to capture attractive risk-adjusted returns while managing interest rate sensitivity.
Hortz: Can you walk us through the components of your risk management process and how that drives your portfolio construction to ‘offset portfolio risk against itself’?
Foresman: The variety of income-producing asset classes utilized by the strategy allows its investors the opportunity to achieve greater diversification and, in turn, greater risk mitigation. We have identified four major risk categories, including interest rate risk, energy price risk, stock market risk, and credit risk.
What we have found is that, in this portfolio, we can actually offset individual, security-specific risks against one another. Through a process of disaggregation and analysis of the various risks associated with specific holdings in our portfolio, we mitigate risk through diversification and balancing. This is supported by a proprietary, internally developed risk management methodology that carefully considers each position’s contribution to the portfolio’s overall risk characteristics.
Essentially, we attempt to offset as much of the portfolio risk against itself as possible. For instance, we may control for interest rate sensitivity by offsetting utilities with regional banks; utilities are traditionally interest rate sensitive, while regional banks tend to be interest rate sensitive in the other way. What you end up with is two sets of securities that provide handsome yield and possess opposite behavior patterns with regard to the factor of interest rates.
Hortz: As a multi-asset income strategy, why do you not include private credit and loans in your portfolios and research team?
Foresman: At a high level, we are focused on public, liquid markets where we believe we have a research and execution advantage. Many higher-yielding areas require investors to accept additional risks alongside the yield, often in the form of illiquidity, complexity, or elevated risk. Our approach prioritizes quality, transparency, and risk control, and we believe we can achieve attractive income without moving into less liquid or more complex areas like private credit.
We use the NASDAQ U.S. Multi-Asset Diversified Income Index as our benchmark because it is designed to provide exposure to multiple asset segments that collectively generate a consistent and high level of income. We believe it is highly representative of our opportunity set and reinforces the strategy’s positioning as a true multi-asset income solution.
Hortz: How have current macro events, like the Gulf war and a shifting interest rate environment, affected your different income sectors and how are you managing those risks?
Foresman: We operate with the view that the future is always uncertain, and as such, the range of potential outcomes for any particular investment is wide. Rather than making macro bets, we focus on security selection, diversification across asset classes, and balancing the four key risk categories. This allows us to remain well-positioned across environments, including periods of volatility, shifting rates, and geopolitical uncertainty.
Hortz: Can you share your thoughts on how to apply this investment strategy to a client’s portfolio? What type of clients or investment scenarios did you design this strategy for?
Foresman: The strategy was designed for investors seeking current income with risk management, particularly those dissatisfied with traditional balanced portfolios. It can serve as a standalone income solution or complement a traditional stock and bond allocation, while providing meaningful diversification and limited overlap with traditional approaches. Ultimately, it is best suited for investors who need income, capital preservation, and reduced volatility, particularly in retirement or income-focused mandates.
Bill Hortz is an independent business consultant and Founder/Dean of the Institute for Innovation Development- a financial services business innovation platform and network. With over 30 years of experience in the financial services industry including expertise in sales/marketing/branding of asset management firms, as well as, creatively restructuring and developing internal/external sales and strategic account departments for 5 major financial firms, including OppenheimerFunds, Neuberger&Berman and Templeton Funds Distributors. His wide ranging experiences have led Bill to a strong belief, passion and advocation for strategic thinking, innovation creation and strategic account management as the nexus of business skills needed to address a business environment challenged by an accelerating rate of change.
What this article covers
Discover financial advisors trusted by residents of West New York, New Jersey in the only local directory featuring 5-Star Certified Advisor Review™ recipients and Wealthtender Voice of the Client Award™ winners, recognition earned for exceptional client feedback. Compare fiduciary, fee-only advisors, CFP® professionals, and specialists to find the right fit for your unique financial needs.
Financial Advisor Directory for West New York, New Jersey
📍 Map: Financial Advisors with their Primary Office Location in West New York
Double-click (or pinch the map on mobile devices) to zoom in and expand the details for financial advisors whose primary office location is in West New York.
You can compare West New York financial advisors by credentials, specialty and verified client reviews before you contact anyone.
The map shows advisors whose primary office is in West New York, and the section below it lists advisors who also serve West New York clients in person or virtually. Profiles include Certified Advisor Reviews™, designations such as the CFP® and the services each advisor offers.
2
West New York’s location on the Hudson across from Manhattan shapes the planning help many residents need.
Many West New York residents work in New York City or in Hudson County’s finance, health care and logistics sectors, which brings two-state tax filing and a mix of employer benefits into the picture. Property tax bills run below the county and state averages, and retirees weigh New Jersey’s pension exclusion, state relief programs and inheritance tax rules.
3
Interview more than one advisor and confirm how each one is paid.
Ask about services, fees and whether the advisor acts as a fiduciary, then check their background for free on the SEC’s Investment Adviser Public Disclosure website before you hire.
Financial Planning Considerations for West New York Residents
Every city has its own financial landscape. Here are a few local factors worth discussing with a West New York financial advisor.
Working in New York City
West New York sits on the Palisades directly across the Hudson River from Manhattan, and many residents commute there. New York taxes wages earned there, and New Jersey residents can claim a credit on Schedule NJ-COJ for the lesser of the New Jersey tax on that income or the tax actually paid to New York. Filing in two states adds complexity, so it pays to review withholding in both states each year, especially after a raise, bonus or move.
Hudson County’s mix of jobs and benefits
Finance and insurance (38,795 jobs), health care (33,130) and transportation and warehousing (22,994) were among Hudson County’s largest private-sector industries in 2024, according to the New Jersey Department of Labor. That mix means West New York households may be juggling very different benefits, from bank restricted stock and bonuses to hospital 403(b) plans and pensions. Reviewing each earner’s retirement plan, match and insurance together helps avoid gaps and overlap.
Property taxes below the county average
West New York’s average residential property tax bill was $8,144 in 2024, below the Hudson County average of $10,065 and the statewide average of $9,898, according to the New Jersey Division of Taxation. Homeowners 65 and older may also qualify for state relief through Stay NJ, ANCHOR and the Senior Freeze. Income limits and benefit amounts change with the state budget, so check the current rules each year.
How New Jersey taxes retirement income
New Jersey’s top income tax rate is 10.75% for 2026, but Social Security benefits are not taxed. Residents 62 and older with total income of $100,000 or less can exclude up to $100,000 of pension, annuity and IRA income on a joint return ($75,000 single), with a partial exclusion up to $150,000. New Jersey’s estate tax ended for deaths on or after January 1, 2018, but its inheritance tax may still apply depending on how heirs are related to the decedent.
The Benefits of Hiring a Financial Advisor in West New York
Hiring a financial advisor can be a great move to help you build a long-term investing strategy. Advisors can help you build an investment portfolio to meet your financial goals and help you plan appropriately for retirement.
As a resident living in West New York, hiring a financial advisor who lives nearby and understands the local economy, cost of living, and regional employers can be quite valuable, especially if your individual circumstances are deeply tied to such factors.
Who are the largest employers in the West New York area?
These are major private-sector employers across Hudson County, which includes Jersey City, Hoboken, West New York and nearby towns, as listed by Choose New Jersey.
UBS
JPMorgan Chase
Quest Diagnostics
Goldman Sachs
Goya Foods
Verisk (Insurance Services Office)
John Wiley & Sons
Unilever
Hoboken University Medical Center
Bank of America
Work for one of these companies or another large employer? Explore our employer Q&As for advice on making the most of your benefits.
Source: Choose New Jersey, Hudson County Population & Workforce (2025, citing ZoomInfo, Dun & Bradstreet and Choose New Jersey research). The source lists major private-sector employers without employee counts or a size ranking, and excludes government employers. Hoboken University Medical Center has been operated by Hudson Regional Health since April 2025.
Do you work for one of the largest employers in West New York? If so, there’s a good chance the local financial advisor you hire will also have other clients who work there. This knowledge could prove valuable if they are already familiar with your employee benefits, such as a 401(k) plan, Health Savings Accounts, and other components of your total compensation package.
When you reach out to financial advisors you’re considering hiring, let them know where you work and ask if they are familiar with your employer’s unique benefits and compensation structure.
Types of Financial Advisors You’ll Find on Wealthtender
Thousands of people visit Wealthtender each month to find and compare financial advisors based on their location, education, experience, areas of specialization and online reviews. Wealthtender’s Certified Advisor Reviews™ help consumers make informed hiring decisions with important details about the relationship between reviewers and advisors always displayed to ensure you gain the transparency you deserve when your life savings could be at stake.
On Wealthtender, you can explore a diverse range of financial advisors and wealth management firms that include:
Fiduciary advisors committed to acting in clients’ best interests
CFP® professionals with advanced financial planning credentials
Fee-only advisors compensated solely by clients
Advisors for growing families, people nearing retirement, and business owners
Specialists across multiple categories (e.g., life stage, occupation, ethnicity, lifestyle, religion)
Highly-rated advisors with positive client reviews
Firms of varying sizes with advisors who can meet with you in person or online
Fee-based advisors who offer access to insurance and alternative investments
How to use this directory: Compare financial advisors in the West New York area based on what matters most to you. Use the directory to:
View advisor profiles to evaluate credentials, services, and areas of specialization
Read Certified Advisor Reviews™ to learn what clients value most
Identify advisors recognized with Wealthtender Voice of the Client Awards™
Contact advisors and schedule free introductory video calls
Wealthtender Voice of the Client Awards™: Top Rated West New York Financial Advisors
Wealthtender Voice of the Client Awards™ recognize financial advisors and firms that consistently earn exceptional client feedback. Below are West New York-area advisors and firms that have met the criteria for Highly Rated recognition.
To qualify for a Highly Rated award, advisors and firms must achieve an average client review rating of 4.75 or higher (on a scale of 1 to 5) based on a minimum number of eligible client reviews published on Wealthtender within a defined timeframe for each particular award (Timeframe for 2025 Award: 1/1/24 – 12/31/25; Timeframe for Subsequent Year Awards: July 1 of the preceding year through December 31 of the Award Year (e.g., Timeframe for 2026 Award 7/1/25 – 12/31/26). Eligible reviews are limited to clients (as of the review submission date) that advisors/firms must self-attest have no material conflicts of interest and received no compensation in exchange for their reviews. ↗️ View full award methodology & FAQs
Although financial advisors and wealth management firms compensate Wealthtender for marketing services (including eligibility to be considered for awards), Wealthtender’s award criteria is objective and not influenced by compensation. Wealthtender Voice of the Client Awards are not a guarantee of future performance or success and client reviews may not be representative of the experience of all past or future clients.
Quick Tips For Hiring a West New York Financial Advisor
Before hiring a financial advisor in West New York, here are a few quick tips to help you find the best advisor for you.
1
Decide Which Services You Need
Before hiring an advisor, determine what services you need from them. Whether it’s full-service investment management or a plan focused on a specific area of your finances, put together a list of what you’d like help with before contacting an advisor.
Though most people use a financial planner simply to invest for retirement, this is only a small part of what many advisors offer. Here’s a quick rundown of potential services a financial advisor may offer you:
Budgeting and money management
Debt management
Insurance planning
Retirement planning
Other investment planning
Inheritance planning
Estate planning
Tax planning
As you can see, financial advisors can help you with your entire financial picture, not just investing. As you start to plan for life’s bigger milestones, you should consider finding a financial advisor who specializes in those areas.
Finding the right advisor can help you minimize risk, maximize gains and take advantage of tax breaks while investing for your future. They can also help you protect your assets with the right kinds of insurance and help you pass on your financial legacy with a proper estate plan.
2
Consider Your Budget and Payment Preferences
Once you have a list of services you would like, review the fee structures financial advisors offer. Finding a balance between the services you need and the cost of those services will help narrow down the field of advisors you may want to work with.
If you are looking for a full-service advisor to manage all of your investments, consider searching among fee-based financial advisors. If you want to manage your money yourself, consider the flat fee and monthly subscription advisors for ongoing support.
3
Interview Multiple Financial Advisors
Once you have chosen the services and fee structure you prefer, it’s time to contact a few advisors and interview them. Here are questions to ask financial advisors:
What services do you provide?
What are all the ways you get paid? (fee transparency)
What is your investment strategy?
How do you measure investment performance?
How do we communicate about my plan?
Interview multiple advisors to get a feel for who you want to work with. A combination of fees, services, and customer service will help you determine the best fit for your financial advice.
4
Review Financial Advisor Credentials
Once you find an advisor (or two) you feel comfortable with, it’s always a good practice to check their credentials and the firm’s details. You can do this at the Investment Adviser Public Disclosure (IAPD) website.
You can check both the individual and the firm to view their background and experience details, as well as any disciplinary action taken against them or their firm.
As licensed financial professionals, there is oversight into how financial advisors conduct business, so running a quick (free) check on them is recommended.
For additional information about advisor credentials, read our article to learn the most popular designations held by financial advisors, as well as specialized credentials which may be important to consider if you have unique financial planning needs.
Frequently Asked Questions
What makes a financial advisor “trusted”?
A trusted financial advisor typically earns positive client feedback over time, operates transparently, and clearly explains how they’re compensated. On Wealthtender, trust is reflected through Certified Advisor Reviews™ that combine insights into the client experience and character of advisors with important disclosures about each reviewer to ensure you gain the transparency you deserve when your life savings could be at stake.
Financial advisors and wealth management firms that consistently receive superior client reviews can also qualify for Wealthtender’s Voice of the Client Awards™ designed to recognize America’s most trusted advisors. Learn More About Wealthtender Voice of the Client Awards™
What are Certified Advisor Reviews™?
Certified Advisor Reviews™ from Wealthtender help consumers make smarter hiring decisions when choosing a financial advisor.
Clients and other individuals can submit reviews for financial advisors and wealth management firms that have turned on the reviews feature. Before each review is publicly displayed, financial advisors agree to disclose important information about their relationship with the reviewer to ensure consumers gain the transparency they deserve when their life savings could be at stake. These disclosures also help financial advisors satisfy compliance with industry regulations.
After financial advisors provide the required disclosures, Wealthtender publishes the review with the Certified Advisor Review™ mark. Learn More About Certified Advisor Reviews™
Can I find fiduciary financial advisors on Wealthtender?
Yes, you’ll find hundreds of fiduciary financial advisors on Wealthtender. Fiduciary financial advisors must act in their clients’ best interest. Before hiring an advisor, always ask if they will act in your best interest as a fiduciary.
For example, financial advisors who have earned their Certified Financial Planner (CFP) designation are fiduciaries. To hold themselves out as a CFP, these credential holders must acknowledge they will adhere to the CFP Board’s Code of Ethics and Standards of Conduct and act as a fiduciary when providing financial advice to their clients. Learn More About Fiduciary Financial Advisors
Can I find fee-only financial advisors on Wealthtender?
Yes, you’ll find hundreds of fee-only financial advisors on Wealthtender. Fee-only financial advisors are paid directly by their clients. Since they aren’t compensated based on the products and services they recommend (e.g., commissions), their compensation model helps reduce potential conflicts of interest.
When viewing financial advisor profiles on Wealthtender, look for the Compensation Methods section that shows ways each financial advisor can be paid for their services, including if they offer fee-only financial planning services. Learn More About Fee-Only Financial Advisors
What distinguishes Wealthtender Voice of the Client Awards™ from other advisor recognition programs?
Wealthtender’s Voice of the Client Awards™ recognize financial advisors and wealth management firms that consistently receive superior client reviews. Unlike award programs with ranking factors that favor financial institutions with the most assets and the fastest revenue growth, the Wealthtender Voice of the Client Awards provide both local financial advisors who choose to remain small and large wealth management firms with the opportunity to be recognized on a metric that matters more to consumers – actual client feedback reflecting the quality of their experience. Learn More About Voice of the Client Awards™
How do I know if I’m ready to hire a financial advisor?
You should strongly consider hiring a financial advisor if you have a significant amount of money available for saving or investing. This could occur after years of making annual contributions to a retirement plan like a 401(k) through your employer or suddenly if you receive a large inheritance or sell your house for a large profit. But even if you don’t have a lot of money saved, many financial advisors and planners provide reasonable pricing options and valuable services you should consider, especially if you’re facing a significant life event. For example, if you’re starting a new job, getting married, starting a family, getting divorced, lost your job, starting or selling a business, or approaching retirement age, working with a trusted financial advisor or planner may prove worthwhile.
Before I hire a new financial advisor, should I fire my current advisor?
You don’t need to fire your current advisor before beginning your search for a new financial advisor. In fact, your new advisor can help coordinate the transition of your assets from your previous financial advisor.
Where can I read reviews about financial advisors written by their clients to help me decide if I should hire them?
After 60 years of regulatory prohibition of financial advisor reviews in the US, a rule issued by the Securities and Exchange Commission (SEC) became effective on May 4, 2021 that means both financial advisors and directory websites that help consumers search for a financial advisor can collect and display financial advisor reviews, an important factor worth considering when choosing who you’ll hire to manage your investments and life savings. Wealthtender is the first independent advisor review platform designed to be fully compliant with the new SEC rule, and we look forward to helping you evaluate financial advisors based on reviews written by their clients.
I’m a West New York financial advisor interested in being featured in this guide. How do I get started?
Thanks for your interest. We look forward to learning more about your practice and helping you attract your ideal clients where you may be a good fit based on their individual needs and circumstances. Learn how to get featured
Brian Thorp is the founder and CEO of Wealthtender and its Editor-in-Chief. With more than 25 years in the financial services industry, he is applying his experience and passion at Wealthtender to help more people enjoy life with less money stress.
Get expert insights from financial advisors who specialize in helping Boston Scientific employees and executives make the most of their compensation package and benefits.
Looking for a financial advisor who specializes in working with Boston Scientific employees? You’re in the right place. Below, you’ll find advisors who understand Boston Scientific benefits and compensation — along with their answers to common financial questions from Boston Scientific employees and executives.
Whether you recently joined Boston Scientific or you’ve advanced into a management or executive leadership role over a multi-year career, making smart decisions about your income and Boston Scientific benefits can have a lasting impact on your financial future. For example:
✅ Do you know the right moves to get the greatest value from the Boston Scientific benefits available to you?
✅ If you’re thinking about leaving Boston Scientific for another job or planning to retire in a few years, are you taking the right steps today to receive all the compensation and benefits you’ve earned?
Key Takeaways
1
Contribute 6% to Capture Boston Scientific’s Full, Immediately Vested 401(k) Match
Many employees stay at the default auto-enrollment rate and never raise it, leaving match dollars behind every paycheck. Boston Scientific’s match vests immediately, so every matched dollar is yours from the day it is deposited.
2
Boston Scientific’s ESPP, HSA, and Individual Disability Plan Are Easy to Overlook
The ESPP’s discount with a six-month look-back, the company HSA contribution, and portable individual disability coverage at a group discount for higher earners can all add real value. The disability plan is especially worth securing during open enrollment, since the coverage stays with you if you leave.
3
Add Up Every Share of BSX Stock Before Planning Retirement or a Departure
ESPP shares, RSUs, and the 401(k) Company Stock Fund can together leave long-tenured employees with far more concentration than they realize. Timing a departure around vest and purchase dates, and considering net unrealized appreciation for 401(k) stock, can preserve significant value.
Why Boston Scientific Employees Work with a Specialist Financial Advisor
Throughout the year, Boston Scientific provides its employees and executives with updates about their benefits, ranging from health insurance and health savings accounts to retirement plans like a 401(k) with an immediately vested company match and, for eligible senior employees, deferred compensation plans — along with an employee stock purchase plan and equity awards such as restricted stock units, performance share units, and stock options. While the company offers many useful resources and access to knowledgeable staff who can assist with questions, you’ll also find financial professionals not affiliated with Boston Scientific who specialize in helping Boston Scientific employees make the most of their income and benefits.
Boston Scientific is headquartered in Marlborough, Massachusetts, and its other major U.S. sites include Arden Hills, Maple Grove, and Plymouth, Minnesota; Quincy, Massachusetts; and Valencia, California. Whether you work at one of those sites, another office, or remotely from home, you may have questions about your compensation package and benefits better suited for a financial professional who can offer unbiased advice and guidance.
Sensitive topics — like the steps you should take before quitting your job at Boston Scientific to work elsewhere, protecting yourself in advance of a corporate layoff, or deciding when you should plan to retire — are all conversations that may be more comfortable with a trusted financial advisor.
Should You Hire a Boston Scientific Specialist or a Local Financial Advisor?
You’ll likely find dozens of nearby financial advisors well-suited to help you reach your money goals with a personalized plan. But it can be harder to find a financial advisor who specializes in serving Boston Scientific employees. Fortunately, many financial advisors offer virtual services, so you can meet online no matter where you (or they) live — which means you can hire a specialist financial advisor who lives hundreds of miles away if their knowledge and experience working with Boston Scientific employees is the better fit for your unique needs.
💡 In the Q&A below, you’ll gain insights from financial advisors who work with Boston Scientific employees to help them make smart decisions, get the most value from their compensation and benefits, reduce their money stress, and prepare for a comfortable retirement.
🙋♀️ Have a question not yet answered? Use the form below to submit your question. You can also contact financial advisors directly to set up an introductory call or contact them with your questions.
Q&A: Financial Planning Tips for Boston Scientific Employees & Executives
In this section, you’ll learn how you can make the most of your Boston Scientific employee benefits and gain valuable tips from financial advisors who specialize in working with Boston Scientific employees and executives.
Financial Advisor Q&A · Boston Scientific Employees
Matthew Nelson is a financial advisor based in Minneapolis, Minnesota who specializes in offering financial planning services to Boston Scientific employees. Matthew helps his clients get the most value from their Boston Scientific benefits and compensation package so they can enjoy life and feel confident about their financial future.
QAs a financial advisor with experience helping Boston Scientific employees save for their retirement, how do you help them make the most of their employee benefits?
Boston Scientific’s 401(k) match structure is one of the first things I walk new clients through, because it’s both more generous and more nuanced than most employees realize. BSC matches 200% on the first 2% you contribute and 50% on the next 4%. That means to reach the full company contribution of 6% of your pay you need to contribute 6% of your pay. That’s meaningful free money, so be careful not to unknowingly leaving match dollars behind every paycheck by contributing 3% or 4%.
What makes this match especially compelling is that it’s immediately and permanently vested from the day it hits your account. There is no cliff or graded schedule unlike many large employers who use multi-year vesting as a retention tool. Whether you’ve been at Boston Scientific for 18 months or 18 years, every dollar of employer match already belongs to you. That’s a genuine differentiator worth understanding from day one.
Once the 401(k) is optimized, I turn to the ESPP. Boston Scientific’s plan allows employees to contribute 1%–10% of eligible compensation and purchase company stock at 85% of the lower of the stock price at the beginning or end of the six-month offering period. That lookback feature is significant—it means you’re guaranteed a 15% discount at minimum, and in a rising market the effective discount can be considerably larger. I treat proceeds from the ESPP as a systematic funding source: sell the shares at purchase, capture the gain, and redirect the proceeds toward the 401(k), a taxable brokerage account, or other financial goals.
After the 401(k) and ESPP are working efficiently, we build out the broader picture. That means establishing an emergency reserve—I typically recommend two years of accessible savings or investments for clients with significant equity compensation, since a market downturn and a job disruption can happen simultaneously. Beyond that, excess cash flow goes toward maxing out retirement contributions, which also reduces taxable income.
For employees whose income puts them near or above the Roth IRA threshold, pre-tax 401(k) contributions can reduce adjusted gross income enough to open up Roth eligibility. For higher earners above the limit, a backdoor Roth strategy often makes sense. The goal in all of this is to build a tax-diversified retirement picture, not just a large pre-tax balance that creates complications later.
QWhen you first speak with a Boston Scientific employee, what questions do you like to ask to better understand their unique circumstances and determine how you can best help them achieve their goals?
Every first conversation is really about building a complete picture before I say anything prescriptive. Boston Scientific employees often come to me with a specific trigger like a large RSU vest, how to optimize their 401k plan, or a job offer from another company. Often the immediate question is rarely the most important one, so I want to understand the full context before we zoom in on any one decision.
Some of my favorite questions to open with:
What specifically prompted you to reach out now. Was there a triggering event, or has this been on your mind for a while?
What does financial independence look like for you, and when do you want to get there?
Do you see yourself staying at Boston Scientific for the long term, or is a move to another company or a start-up on your radar?
How are you currently handling your equity compensation like RSUs, PSUs, ESPP shares? Do you have a sell strategy, or are shares accumulating without a plan?
Is tax planning something you actively think about, or has it mostly been reactive and you deal with surprises at tax time?
Are there goals outside of retirement that matter to you for family, giving, a business, a second career?
Does anything keep you up at night financially?
That last question often produces the most useful answer. Anxiety about a concentrated BSX stock position, uncertainty about what happens to unvested equity if there’s a layoff, and concern about whether they’re saving enough are the real starting points for a meaningful planning conversation. Everyone’s situation is different, and these questions help me understand not just the goals but the motivations behind them.
QIs there a particular benefit available to Boston Scientific employees you feel isn’t as well utilized or understood by employees as it should be?
The ESPP is the most obvious one. Boston Scientific’s plan offers a 15% discount with a six-month lookback which is a structure that generates an immediate, relatively low-risk return simply by participating. Yet I regularly meet employees who aren’t enrolled, or who are contributing well below the 10% maximum. The most common reason I hear is that it feels complicated, or they’re nervous about accumulating more company stock. Both are solvable by selling the shares immediately on the purchase date and diversify the proceeds rather than holding them.
The HSA is another one that’s consistently underutilized as a long-term tool. Boston Scientific contributes $500 per year for individual coverage and $1,000 for family coverage into employees’ HSAs. That’s before you add your own pre-tax contributions. The triple tax advantage is well known in financial planning circles but rarely internalized by employees. Contributions are pre-tax, growth is tax-free, and withdrawals for qualified medical expenses are tax-free. What most people miss is the long-term power of letting the HSA compound while paying current medical costs out of pocket. The accumulated balance can then be used in retirement for Medicare premiums, long-term care, and other expenses tax-free. After age 65, any withdrawal for non-medical purposes is simply taxed as ordinary income, making it functionally equivalent to a traditional IRA.
But the benefit I find most genuinely overlooked, especially by employees who have been with BSC for several years, is the Individual Disability Income Insurance Plan. Boston Scientific offers eligible employees earning $100,000 or more the ability to purchase individual disability coverage through Guardian at a 25% discount off standard market rates, using unisex pricing. That unisex rate is particularly valuable for women, who typically pay significantly more for individual disability policies on the open market. What makes this benefit especially worth paying attention to is portability. If you leave Boston Scientific for any reason, the coverage stays with you at the same premium, with no conversion requirements and no new underwriting. That kind of guaranteed-issue access at a group discount is very difficult to replicate once you’re no longer with an employer offering it.
QBeyond Boston Scientific employee benefits for retirement savings, are there other types of benefits offered by the company that you find valuable to discuss with your clients?
Absolutely. The HSA is one I come back to often. Boston Scientific contributes $500 annually for individual coverage and $1,000 for family coverage to employees enrolled in the UMR Consumer HDHP. My advice is always the same, treat the HSA as a long-term investment vehicle, not a medical spending account. Pay smaller out-of-pocket costs directly when you can, leave the HSA invested, and let it compound. In retirement, those funds can cover Medicare premiums, long-term care, and healthcare costs that aren’t covered by Medicare—all tax-free. The account is yours permanently, even if you leave Boston Scientific.
The Short-Term Disability program is a benefit I find genuinely underappreciated, and Boston Scientific’s version stands out in the MedTech space. It’s fully company-funded, and the salary continuation schedule is tied to tenure. Employees with 10 or more years of service receive 100% of base pay for the full 26-week STD period. Even employees in their first two years receive 2 weeks at full pay followed by 24 weeks at 75% of base pay. Most employers offer a flat 60% benefit from day one. BSC’s structure is meaningfully stronger, particularly for tenured employees, and it’s worth factoring into total compensation comparisons when evaluating outside offers.
Long-Term Disability is another important area. Boston Scientific’s LTD pays 60% of monthly earnings up to $15,000 per month after a 180-day elimination period, with the full premium company-funded. For higher earners, there may still be a meaningful gap between the LTD cap and actual income needs. That’s where the supplemental Individual Disability Income Insurance Plan comes in. They offer additional coverage at a 25% group discount, with unisex pricing and full portability if you leave.
Beyond insurance, I spend significant time on equity compensation planning like RSUs, PSUs, and stock options. Many employees don’t have a clear strategy for when to sell vested shares, how to reduce concentrated BSX stock exposure, or how to manage the tax consequences of equity events. Getting this right has one of the highest financial impacts of anything we do together.
QFor Boston Scientific employees thinking about leaving the company to accept a job elsewhere, what actions do you recommend they take before resigning and shortly thereafter?
The first thing I tell anyone considering a departure from Boston Scientific is: don’t give notice until we’ve mapped every dollar that’s about to vest. The difference between leaving on a Friday versus the following Monday can sometimes be tens of thousands of dollars in RSUs or ESPP proceeds. Employees may time a resignation based on a new employer’s start date without realizing they were a few weeks away from a significant grant vesting. That’s an avoidable and painful mistake.
Something that surprises many departing employees is Boston Scientific’s 401(k) employer match is immediately 100% vested from the day it’s contributed to your account. No cliff, no graded schedule on the match itself. Whether you’ve been at BSC for eight months or eight years, every dollar of matching contributions in your Vanguard account is already yours and goes with you. Many employees assume there’s a vesting wait because at a number of BSC’s MedTech competitors there is. That’s one less thing to worry about when timing your exit.
The one 401(k) vesting item worth checking before you leave is whether you’ve received any discretionary profit-sharing contributions, which follow a separate 5-year graded schedule at 20% per year. These are distinct from the regular match and made at Boston Scientific’s discretion. Not all employees receive them, but if you have, your Vanguard account will show your exact vested percentage. Worth a quick check before you set a departure date.
Beyond equity and the 401(k), I encourage employees to think carefully about total compensation when weighing an outside offer, not just base salary. Boston Scientific’s STD program pays 100% of base salary for up to 26 weeks for tenured employees, fully company-funded. Most employers can’t match that. If a new offer looks close on paper, it may look less competitive once you account for the benefits package you’re walking away from.
One more item that rarely gets discussed: if you’ve enrolled in Boston Scientific’s Individual Disability Income Insurance Plan, know that this policy is fully portable. You keep it when you leave—same rate, no conversion, no new underwriting. That matters especially if you’re moving to a smaller company or start-up without group disability coverage.
Finally, plan your healthcare bridge before you hand in your notice. Medical coverage ends at termination, and COBRA premiums can be a significant monthly expense. Know your options such as marketplace plans, a spouse’s plan, or COBRA, and have the transition mapped before your last day.
QFor Boston Scientific employees approaching retirement age, how do you recommend they prepare to make the transition from living off their salary to relying upon other sources of income?
Retirement planning for Boston Scientific employees has a few specific wrinkles that don’t apply to everyone. By the time many BSC employees reach their late 50s, they’ve accumulated a meaningful amount of company stock through RSUs that vested over the years, ESPP shares, and contributions to the 401(k)’s Company Stock Fund. The plan has no cap on how much you can hold in company stock, which means concentration risk can grow for years. The single most important pre-retirement move for many of my BSC clients is developing a systematic, tax-efficient plan to diversify away from BSX before they stop working.
Beyond that, the transition from accumulation to distribution requires a clear income map. I ask clients to identify every reliable income stream they’ll have in retirement such as Social Security, pensions, or rental income. Then calculate the gap that savings and investments need to fill. We model out different Social Security claiming ages, because the difference between claiming at 62 versus 67 versus 70 can be substantial over a 25-year retirement. For most BSC employees with significant assets, delaying Social Security and drawing from taxable accounts first is often the stronger path.
Withdrawal sequencing matters enormously for lifetime tax efficiency. Generally, taxable brokerage accounts first, then tax-deferred accounts like the 401(k), with Roth assets held as long as possible. The years between retirement and the age Required Minimum Distributions kick in are often a window to execute Roth conversions at lower tax rates. Many BSC employees retire with very large pre-tax 401(k) balances from years of contributions and a generous match, and converting some of that to Roth in the early retirement years can significantly reduce lifetime tax burden.
I also encourage clients to set aside four to six years of living expenses in lower-risk assets as they approach retirement. This creates a buffer that allows the equity portion of the portfolio to stay invested through market volatility without forcing sales at the wrong time. It’s a simple framework, but it does a lot to reduce the anxiety that comes with shifting from a paycheck to portfolio withdrawals.
QFor Boston Scientific employees who have managed their finances on their own to this point, what would you suggest they consider to help them decide if they should begin working with a financial advisor at this stage in their lives?
There are a handful of inflection points specific to Boston Scientific where the complexity of the benefits package tends to outpace what a generalist or self-directed approach can comfortably handle. If any of the following apply to you, it’s worth a conversation with a specialist.
Ask yourself:
Do you have a written strategy for your ESPP shares. Do you know the difference between a qualifying and disqualifying disposition, and are you timing your sales intentionally?
Do you know the total value of BSX stock you hold across your ESPP account, RSU grants, and the 401(k) Company Stock Fund combined? Many employees are more concentrated than they realize.
Are you contributing at least 6% to your 401(k) to capture the full, company match?
Is your HSA being invested and grown as a long-term retirement asset, or are you spending it down on current medical costs?
Have you enrolled in the Individual Disability Income Insurance Plan during an open enrollment window while guaranteed-issue access is available, and do you understand the portability provisions?
Do you have a proactive tax estimate built around your RSU vesting schedule, or will you find out what you owe in April?
Do you have an estate plan, a current beneficiary review, and a clear plan for what happens to unvested equity if something unexpected happens to you?
Boston Scientific’s compensation package is genuinely complex. The interplay between the 401(k) match structure, ESPP lookback feature, RSU vesting, deferred compensation plans, and disability benefits creates planning opportunities that are easy to miss and mistakes that are easy to make. The employees I work with who have managed their finances independently are often smart, capable people who simply haven’t had the bandwidth to go deep on all of it. That’s exactly what a specialist is for.
QWhat are some of the unique financial planning challenges you commonly see among your clients who are Boston Scientific employees and how do you help them overcome these obstacles?
The most consistent challenge I see is stock concentration that has crept up over the years without the employee fully recognizing it. Boston Scientific’s 401(k) plan has no limit on how much participants can allocate to the Company Stock Fund, and when you layer ESPP shares and RSU grants on top of that, it’s common for a long-tenured employee to have 50% or more of their investable assets in a single stock. Most clients are surprised when we add it all up. We address this with a systematic, tax-aware diversification plan by spreading sales across multiple tax years, using specific identification on ESPP shares to optimize tax treatment, and coordinating with RSU vesting dates to avoid bunching income unnecessarily.
Equity tax surprises are another very common issue. RSU vesting is a taxable event where shares are treated as ordinary income at the time of vesting, regardless of whether you sell them. If supplemental withholding isn’t calibrated correctly, employees can end up with a large, unexpected tax bill in April. ESPP shares add another layer. The tax treatment differs depending on whether you hold shares long enough to qualify for preferential long-term capital gains rates, or sell sooner and trigger a disqualifying disposition. Without planning, employees often make the wrong decision from a tax standpoint simply because they didn’t know the rules.
Pre-tax 401(k) accumulation is a third challenge, a good problem to have, but a real one. Boston Scientific’s immediate match vesting, combined with strong employer contributions and years of employee deferrals, means many long-tenured employees arrive in retirement with very large pre-tax balances. Those balances come with future Required Minimum Distributions that can push retirees into higher tax brackets than they expected. We address this proactively through Roth conversions during lower-income years and tax bracket management strategies that spread the burden more efficiently over time.
Finally, disability income gaps for higher earners are a challenge I encounter regularly. Boston Scientific’s base LTD covers 60% of monthly earnings up to $15,000—but for a director or senior engineer earning $250,000 or more, that coverage replaces a much smaller fraction of actual income. The supplemental Individual Disability Income Insurance Plan available through BSC is the right tool to close that gap, but it requires action during open enrollment. I try to get this on every client’s radar early, because access to guaranteed-issue coverage at a group discount disappears once you leave the company or miss an enrollment window.
QWhat questions do you recommend Boston Scientific employees ask financial advisors they’re considering hiring to help them decide if they’re a good fit?
Finding the right financial advisor is about more than credentials or a good first impression. I recommend employees ask some pointed questions, such as:
Do you have specific experience with Boston Scientific’s benefit plans such as the 401(k) match structure and immediate vesting, the ESPP lookback feature, RSU and PSU programs, and deferred compensation plans like the CAP and NRPS?
How do you coordinate 401(k) planning with equity compensation and outside investments?
Do you have special training in equity compensation planning, such as the Equity Compensation Associate (ECA) designation?
Can you handle financial planning beyond investments such as taxes, estate planning, charitable giving?
Are you a fiduciary, and does your firm act as an Independent Registered Investment Advisor?
What is your fee structure? Do I pay separately for financial planning and investment management, or is it an all-inclusive package?
QIs there anything that comes up frequently in your initial meeting with Boston Scientific employees that surprises you?
Yes—and it tends to cluster around the same themes. The most common surprise is how many employees are enrolled at the default 2% 401(k) contribution rate and have never increased it. The auto-enrollment feature means many people are contributing far less than they intend to—and far less than the 6% needed to capture Boston Scientific’s full, immediately-vested match. That’s usually the first thing we fix.
The second common surprise is equity tax exposure that hasn’t been planned for. An RSU vest or large ESPP purchase can generate significant ordinary income in a single calendar year, and many employees have no idea how much additional tax they’ll owe until they sit down with their accountant. We model this out in advance and adjust estimated payments or withholding elections so there are no April surprises.
A third one that genuinely catches people off guard is a survivor benefit most employees don’t know exists. If a Boston Scientific employee passes away while covered, eligible family members receive six months of COBRA continuation coverage at no cost to them. That’s a meaningful benefit that most employees—and honestly most financial advisors—aren’t aware of. It doesn’t change daily financial decisions, but it’s exactly the kind of detail that matters enormously to a family during a very difficult time.
And almost universally, when we aggregate total BSX stock exposure across the ESPP account, unvested RSUs, and the 401(k) Company Stock Fund, the concentration number is higher than the client expected. Showing someone exactly how much of their net worth is riding on a single stock is often the moment the planning relationship really clicks into place.
QFor highly compensated Boston Scientific employees and executives, are there any special benefits you believe it’s important to take into consideration when preparing their financial plan?
Higher-income employees and executives at Boston Scientific have unique opportunities that require specialized attention. The Capital Accumulation Plan (CAP) and the Non-Qualified Retirement Plan Supplement (NRPS) are two standout examples. These plans allow eligible employees to defer compensation on a pre-tax basis above IRS 401(k) contribution limits, creating significant savings opportunities. However, planning the withdrawal timing carefully is critical. Distributions are taxed as ordinary income and can compound with other retirement income in ways that push retirees into higher brackets than anticipated. We look at payout election strategies to spread distributions in a tax-efficient way.
Company stock concentration is a magnified concern at the executive level. Vice presidents and directors often accumulate large BSX positions through RSUs, PSUs, and years of ESPP participation on top of whatever is in the 401(k). Diversifying strategically in coordination with the company’s trading window requirements and any Rule 10b5-1 plan considerations is essential to reducing portfolio risk as they approach retirement.
For executives earning above the LTD benefit cap, disability income planning takes on added importance. The base LTD covers 60% of earnings up to $15,000 per month, but for a vice president or director earning $300,000 or more, that leaves a very significant income gap. The supplemental Individual Disability Income Insurance Plan available through Boston Scientific is an important tool here: executives can secure substantial additional coverage at a 25% group discount, with guaranteed-issue access during open enrollment and full portability if they leave.
We also focus heavily on tax planning around equity compensation such as estimating and managing payments upfront, exploring Net Unrealized Appreciation (NUA) strategies for company stock held inside the 401(k), and considering charitable vehicles like Donor-Advised Funds to offset income in high-earning years. The complexity scales with income and net worth, but so do the opportunities.
QIs there a particularly memorable experience or a moment you recall with a client who worked at Boston Scientific when you realized they have unique opportunities and circumstances when it comes to their financial planning needs?
One case that stands out involved a senior engineer who had been with Boston Scientific for over 15 years and was planning to leave for a start-up opportunity. Over that time, they had accumulated a significant amount of company stock across their ESPP account, the 401(k) Company Stock Fund, and unvested RSUs. When they first came to me, the immediate question was simply: “when should I give notice?”
But when we looked at the full picture (vesting schedules, ESPP offering period timelines, RSU grant dates, and the tax implications of all of it) the real opportunity became clear. By pressing pause and timing the departure strategically around an upcoming RSU vest and ESPP purchase date, we were able to capture a meaningful amount of additional compensation that would have been forfeited with a hasty exit.
At the same time, we developed a Net Unrealized Appreciation (NUA) strategy for the company stock inside the 401(k), which allowed the client to pay long-term capital gains rates on the appreciated portion of the stock rather than ordinary income rates. This saved a substantial amount in taxes. We also coordinated the ESPP qualifying disposition holding periods to maximize the tax treatment on those shares.
One final detail that mattered: this client had enrolled in the Individual Disability Income Insurance Plan years earlier and hadn’t thought about it in the context of leaving the company. We made sure they understood the policy was fully portable and they kept it at the same rate with no interruption in coverage. This was especially meaningful given they were moving to a start-up with no group disability coverage at all.
That experience was a clear reminder of how much value a specialist in Boston Scientific’s specific plans can bring. The intersection of equity compensation, tax strategy, benefit timing, and insurance planning is complex. When you understand the intricate details, the opportunities are significant. With the right guidance, Boston Scientific employees can put themselves in a strong position for financial independence, whether they’re staying at the company or ready to make their next move.
Considering a financial advisor who specializes in working with Boston Scientific Employees?
Are you a financial advisor who specializes in working with employees at Boston Scientific or another large company?
✅ Join Wealthtender and get featured as a specialist financial advisor based on your knowledge and experience working with employees at Boston Scientific or another large company. (Subject to availability and terms.) ✅ Sign up today and join financial advisors attracting their ideal clients on Wealthtender
Ask a Financial Advisor Your Boston Scientific Benefits & Career Questions
Get answers from the Wealthtender network of financial professionals and educators.
Are you ready to enjoy life more with less money stress?
Sign up to receive weekly insights from Wealthtender with useful money tips and fresh ideas to help you achieve your financial goals.
Brian Thorp is the founder and CEO of Wealthtender and serves as Editor-in-Chief. With over 25 years in the financial services industry — including nearly 22 years at Invesco, where he led strategic partnerships with wealth management firms representing more than $100 billion in assets — Brian founded Wealthtender to help people find financial advisors they can trust and make more informed money decisions.
A member of the National Society of Compliance Professionals and its SEC Marketing Rule Working Group, Brian was recognized by WealthManagement.com as one of its “Ten to Watch in 2024” for his work reshaping how financial advisors market their services. He holds a B.B.A. in Finance from The University of Texas at Austin.
[Professional investors are awash in Exchange-Traded Funds, with over 5,000 U.S. listed ETFs and more than 14,000 listed globally. This momentum is not a temporary surge, but rather a clear reflection of a structural shift in investment product creation and adoption. ETF launches continue to accelerate, driven by investor demand for transparency, tax efficiency, low fees, and precise exposures. Both established asset management firms and new industry entrants are embracing ETFs across broad beta, thematic, active, and alternative strategies.
Adding to this continuing momentum are regulatory changes that now allow mutual funds to convert into ETFs without creating separate products. This legislation enables large fund families to expand into ETF offerings more efficiently, driving faster adoption, increased competition, and continued innovation, while also improving fee structures and tax efficiency for investors.
To better understand this expansive and ever-growing ETF ecosystem, we spoke with Trammel Robinson, Director, Head of ETF Issuer Relations and Jim Gregory, Senior Director, Head of Business Development at ETF Global – a leading independent provider of enterprise-grade ETF reference data and analytics, and host of the semiannual ETP Forum dedicated exclusively to the global Exchange-Traded Products ecosystem. ETF Global’s next ETP Forum will take place in New York City on June 2, 2026. Attendance is complimentary for ETF Investors such as Wealth Managers, Financial Advisors, Financial Consultants, Investment Consultants, Financial Planners, Family Offices, Endowments, Foundations, Pensions and other professional investor profiles.
At the core of the ETF Global value proposition is timely, comprehensive, precise, and well-structured data designed to power a broad spectrum of ETF investment activities ranging from Portfolio and Risk Management to ETF Research and Selection. The firm delivers T+1 institutional-grade data to hundreds of asset managers, asset owners, financial intermediaries, and investment platforms.
As a specialist data provider, we asked how ETF Global developed its data capabilities into their ETF Global Data Helix which is a centralized data hub to support institutional and financial professionals in navigating the rapidly expanding universe of ETF vehicles. The continued growth of the ETF universe has introduced greater complexity across research, due diligence, risk management, trading, and portfolio construction, heightening the need for advanced analytics, robust data tools, and a deeper understanding of how ETF data can be applied across the investment lifecycle.]
Hortz: How do ETF datasets differentiate among competitors, and why is the level of detail crucial for investment research and institutional users? What specific advantages does a higher level of granularity provide to different clients?
Robinson: ETF Global differentiates through the depth, precision, and structure of its ETF reference data, sourced directly from issuers and normalized into a consistent, research-ready format. While many providers offer surface-level ETF data, ETF Global delivers full look-through transparency into underlying holdings, daily fund flows, ETF classifications, and product structures.
This level of granularity is critical because ETFs are no longer simple beta exposure tools. They represent complex vehicles with embedded exposures, derivatives, and evolving strategies. Institutional, enterprise, and even individual users require precise, timely data to properly evaluate risk, product attributes, liquidity, and correlations.
For quantitative firms, this granularity – along with ETFG’s extensive historical data – enables more accurate modeling, factor analysis, and signal generation. For portfolio managers, it improves security selection, peer comparison, and exposure management. For wealth platforms, it supports better product due diligence and portfolio construction. Ultimately, comprehensive granular data reduces blind spots and enables more informed, confident decision-making.
Hortz: Can you briefly discuss the comprehensive nature of your ETF Data Helix capabilities and the major use cases where ETF data can help firms across their entire operation?
Gregory: The ETF Global Data Helix is a centralized, companywide data hub designed to provide a comprehensive data panel that maps ETF data across the full investment lifecycle. It enables firms to integrate ETF intelligence across their enterprise and multiple functional areas rather than treating it as a siloed dataset.
Key use cases include:
Research and Analysis – Supports deep ETF screening, peer comparison, factor analysis, and macro attribution.
Portfolio Management – Enables precise exposure management, portfolio construction, and rebalancing decisions using underlying holdings and fund flows.
Trading and Capital Markets – Provides insight into liquidity, spreads, primary market activity, and execution efficiency.
Risk Management – Allows firms to monitor concentration risk, stress scenarios, and hidden exposures within ETF structures.
Distribution and Sales – Equips sales teams with differentiated insights to position products and engage clients more effectively.
Responsible Investment – Supports ESG analysis through transparency into underlying holdings and classifications.
Client Reporting and Advisory – Enhances reporting with deeper insights into exposures, performance drivers, and portfolio composition.
By connecting these functions, the ETFG Data Helix allows firms to operationalize ETF data across the full enterprise.
Hortz: Can you walk us through the tools and applications that you are developing to help clients understand all the different ways ETF reference data can be utilized? Why is this important?
Robinson: ETF data is highly valuable, but often underutilized due to its volume and complexity. To address this, ETF Global has developed applications and curated datasets, including the Data Helix, to clearly map how ETF data flows across an organization.
These applications simplify complex datasets into intuitive, functional use cases that resonate with different stakeholders – from researchers to sales teams. The broader campaign focuses on education, helping our institutional clients understand not just what data is available, but how it can be applied in practical workflows.
This is important because many firms already have access to ETF data but are not fully leveraging it. By improving understanding and accessibility, ETF Global helps clients unlock additional value from their data investments to drive better outcomes.
Hortz: Let’s dig into some of these use cases more deeply. How can professional investors utilize ETF data when building and managing their own ETF products, investment strategies, and what reconnaissance capabilities does it provide?
Gregory: For asset managers, ETF data has become essential throughout the product lifecycle. During product development, it supports competitive analysis, market gap identification, and product positioning. Managers can analyze peer products, underlying exposures, daily fund flows, and fee structures to refine their strategy.
Post-launch, ETF data enables ongoing monitoring of performance, flows, liquidity, and holdings as well as compliance with regulations such as SEC Rule 6c-11. The ETF Global Data Helix provides reconnaissance capabilities by offering a full view of the competitive landscape, helping managers identify trends, costs, threats, and opportunities.
For Asset Owners such as family offices, endowments, foundations, and asset managers, ETF data serves as a flexible toolkit for building customized strategies. It allows them to deconstruct ETFs into their underlying exposures, identify inefficiencies, and construct portfolios that align with specific mandates, risk tolerances, and macro views.
Hortz: How do RIA platforms and wealth management firms leverage ETF data from your Helix data platform? What role can ETF data play in fueling recommendation engines and portfolio personalization for wealth management firms?
Gregory: RIA platforms and wealth managers use ETF data to build, refine, and scale ETF model portfolios and strategies for clients. Granular holdings data allows for precise allocation decisions, overlap analysis, and diversification.
ETF data also plays a central role in powering recommendation engines. By integrating flows, performance, exposures, and classifications, firms can generate more tailored investment recommendations based on client objectives, risk profiles, and market conditions.
This enables a more dynamic portfolio approach, moving beyond generic models to more targeted, client-specific solutions, while maintaining scalability across large platforms.
Hortz: How can ETF data be embedded into existing platforms, workflows, and advisory tooling to enhance decision-making processes?
Robinson: ETF data can be embedded directly into front, middle, and back-office systems to enhance decision-making in real time.
For example, within capital markets, it supports analysis of primary market activity and liquidity conditions. In trading, it informs spread management and execution strategies. In portfolio management, it improves exposure tracking and rebalancing decisions. In risk functions, it enables stress testing and monitoring of hidden exposures. Across the enterprise, it strengthens data governance by providing a consistent, high-quality reference dataset.
By integrating ETF data into existing workflows, firms can move from static and product-level analysis to continuous, data-driven decision-making at both the ETF and underlying constituent levels.
Hortz: How is ETF data being integrated into AI-driven next-best-action platforms, tax exposure analysis and optimization, and sales and distribution automation tools?
Robinson: ETF data is increasingly being used as a foundational input for AI-driven platforms. In next-best-action systems, it helps identify investment opportunities based on flows, trends, and portfolio gaps.
In tax optimization, ETF data enables analysis of embedded gains, turnover, and tax efficiency, allowing advisors to make more informed decisions around rebalancing and product selection.
For sales and distribution, ETF data powers automation tools that identify relevant prospects, tailor messaging, and surface insights that improve engagement with clients.
As AI adoption grows, high-quality ETF data becomes even more critical, as the accuracy of outputs depends directly on the quality of inputs. AI is only as good as the data on which it is trained.
Hortz: How are fintech companies and digital platforms incorporating ETF reference data to enhance their service offerings?
Gregory: Fintech platforms are integrating ETF data to deliver more sophisticated analytics, screening tools, and portfolio construction capabilities to end users.
This includes enhanced ETF comparison tools, real-time exposure analysis, and personalized investment recommendations. By embedding ETF data into user interfaces, fintech firms can provide institutional-grade insights in a more accessible format.
This elevates the user experience and allows platforms to differentiate through data-driven capabilities.
Hortz: What are the key data requirements for firms engaged in ETF back-office operations and fund administration?
Gregory: Back office and fund administration functions require highly accurate, standardized, and timely ETF data.
This includes holdings data for reconciliation, corporate actions, fund flows, and classification data for reporting and compliance. Consistency and reliability are critical, as errors can impact NAV calculations, regulatory filings, and client reporting.
ETF Global’s structured datasets help ensure that operational teams have a single source of truth to support these functions efficiently.
Hortz: How do you work with firms to help them determine what the most strategic use cases are for them in using ETF data?
Gregory: ETF Global works closely with clients to understand their business model, workflows, and strategic priorities. Rather than taking a one-size-fits-all approach, the focus is on identifying where ETF data can have the greatest impact across the organization.
This involves mapping data capabilities to specific use cases, aligning with functional teams, and helping clients operationalize the data within their existing systems.
The goal is not just to provide data, but to empower clients to fully leverage it to drive measurable outcomes across research, investment, and business functions.
Bill Hortz is an independent business consultant and Founder/Dean of the Institute for Innovation Development- a financial services business innovation platform and network. With over 30 years of experience in the financial services industry including expertise in sales/marketing/branding of asset management firms, as well as, creatively restructuring and developing internal/external sales and strategic account departments for 5 major financial firms, including OppenheimerFunds, Neuberger&Berman and Templeton Funds Distributors. His wide ranging experiences have led Bill to a strong belief, passion and advocation for strategic thinking, innovation creation and strategic account management as the nexus of business skills needed to address a business environment challenged by an accelerating rate of change.
The patterns in ultra-high-net-worth portfolios are more consistent than most people expect, and recent research puts real data behind what we already see in practice. CEG Insights surveyed 350 ultra-high-net-worth investors, defined as those with a net worth of $25 million or more (not including a primary residence), covering their assets, risk tolerance, investment attitudes, and behaviors.
These investors are disciplined, diversified, and intentional. What’s worth unpacking is how they execute on those principles and what their approach looks like in practice. Much of it maps directly to conversations I have with clients every day.
What the Data Actually Show
According to the CEG Insights survey, investable assets make up nearly three-quarters of ultra-high-net-worth portfolios. That alone tells you something about where these investors believe wealth is built and maintained. The approach is intentional and diversified, not built on concentration or speculation.
Equities play a central role. These investors are comfortable with market movement in exchange for long-term growth potential. But they are not relying solely on stocks. Nearly a quarter of their investable assets are held in alternatives, meaning assets outside of traditional stocks and bonds, such as private equity, hedge funds, and real assets like commodities. That allocation reflects a deliberate effort to broaden sources of return and reduce reliance on public markets.
Fixed income, which includes bonds and similar investments, represents another notable slice, providing stability and income across different market conditions. Liquidity is part of the plan as well. Cash and liquid assets stay in the mix, creating flexibility for both unexpected needs and new opportunities.
Even real estate plays a supporting role. Primary residences account for a small fraction of total assets. For these investors, a home is a lifestyle decision, not a primary engine of wealth creation.
The Diversification Thread
The wealthiest investors didn’t build or preserve wealth by betting on a single outcome. The thread running through their portfolios is diversification, applied with intention. That same approach informs how I advise clients to think about portfolio construction today.
For years, investments like private equity, private credit, and real assets were largely reserved for institutions and the ultra-wealthy, but access has expanded. Recent Department of Labor guidance has opened the door for certain private investments to be included in qualified retirement plans. More high-income investors now have access to tools that were previously out of reach.
The idea here is to build on what already works. Private investments can offer exposure to companies and sectors not available through public exchanges and may help reduce the impact of market volatility over time.
That said, fit matters. Private investments typically involve longer time horizons, reduced liquidity, and more complexity. The goal is thoughtful integration, not novelty. A well-diversified portfolio has more building blocks available today than it did even a few years ago. The opportunity is in using them deliberately.
The Mindset Behind the Portfolio
Beyond the allocations, the mindset is just as consistent. According to the CEG Insights data, more than three-quarters of ultra-high-net-worth investors find greater satisfaction in saving and investing than in spending. Most want to stay actively involved in day-to-day portfolio decisions, and they don’t treat growth and preservation as competing priorities. They pursue both.
That balance shows up in the data. The Capgemini World Wealth Report 2025 found that high-net-worth investors are actively rebalancing their portfolios, combining preservation strategies with growth-oriented positions. Alternative investments, including private equity, continue to hold a meaningful allocation. Preservation and growth are managed together, deliberately.
The clients I work with tend to share these instincts: disciplined, engaged, and intentional about where their money goes and why.
The question worth sitting with is whether your portfolio actually reflects those instincts. Over time, allocations drift, priorities evolve, and structures that once made sense can fall out of alignment with current goals. Checking that alignment, not just the returns, is often where the real progress happens.
Your Plan, Revisited
The ultra-wealthy don’t rely on a secret. They build a plan, stick with it, and revisit it as life and markets evolve. If you’ve built serious wealth, you’re already doing the hard part. The principles here aren’t out of reach. They’re likely already part of how you think and operate.
But does your portfolio represent that thinking today?
If there’s a gap between your goals and how your assets are currently structured, now is a great time to take a closer look.
It’s easy to get excited about everything “out there” and forget all the local resources at your disposal. Retirees often have more programs and services available than they might realize. Not every benefit will apply to your situation, but it’s a good idea to know what’s available.
If nothing else, having a good handle on the resources in your local area might help someone else you know in need. It’s important to stay informed about resources for a successful retirement.
Why Local Benefits Matter More Than You Think
Community programs can dwindle and die because of underutilization. Unfortunately, many programs aren’t used due to a common misconception of services being intended for “someone else.” If you qualify for a beneficial program or service, you need to explore it.
Also, by using a benefit or service, you can help others who might benefit from it. There’s nothing better than first-hand experience to help you guide someone else. Regardless, don’t let these benefits go unused!
Reducing Fixed Expenses in Retirement
When it comes to reaching our financial goals, retirement or otherwise, you really only have three main levers: spend less, make more, or adjust your goals. If you’re able to take advantage of programs and services, you can help reduce your expenses. This can be especially helpful for retirees on a fixed income.
Increasing Your “Spendable” Income Without Taking More Risk
At the end of the day, only the money you get to spend matters. If you’re able to take advantage of local tax breaks or incentives, you can increase your “spendable” money. This keeps more money in your nest egg without adding risk.
Many Benefits Go Unused
By some estimates, seniors miss out on billions of dollars of unused federal aid each year. Not everyone qualifies for these programs, but it’s worth taking a look. There are many programs looking to help.
Property Tax Relief Programs
Once you cross the threshold into retirement, taxes often become one of your major expenses alongside healthcare. Even if you paid your mortgage off, you often can’t escape property taxes. Luckily, there are some programs to help alleviate some of your property tax burden.
We can’t speak for all states, but in Missouri and Kansas, where most of our clients live, programs operate very differently. You’ll need to check with your local county, city, and state government offices to find out if they offer tax relief programs. We’ll touch on Missouri and Kansas briefly so you can see what we mean.
Missouri Property Tax Credit and Freeze Programs
For Missouri property tax freeze programs, each county decides whether to participate and how to administer it. With 114 different counties in Missouri, it’s impossible to keep track of them all. Be sure to check with the local county assessor’s and collector’s offices to learn more.
Kansas Homestead and Refund Programs
On the West side of the Missouri River, Kansas operates its property tax freeze programs much differently. There are three separate programs: the Homestead Refund Program, the Safe Senior (SAFESR) Program, and the Senior or Disabled Veteran (SVR) Program. The eligibility criteria for the property tax freeze programs are somewhat restrictive, so you’ll need to check to see if you’re eligible for them.
Additionally, each county can keep overall tax collections the same each year (revenue-neutral), but many don’t.
Why This Matters for Long-Term Planning
The recent explosion in real estate prices since 2020 has caused many seniors’ property taxes to increase significantly. Over time, these higher evaluations can lead to ever higher property taxes for the same home. All while your income may stay the same or even decrease relative to inflation.
Healthcare and Prescription Cost Assistance
Healthcare is one of the most important issues retirees face, if not the single most important issue. Your access and ability to pay for quality healthcare are huge quality-of-life concerns. Be on the lookout for assistance through federal and local government programs.
It’s a good idea to know about these programs even if you’re not eligible. Even if it’s not helpful to you, it may be useful to friends and family who need some assistance.
These often have eligibility requirements, but they vary by program.
Local Clinics and Community Health Resources
Don’t forget to check for other organizations and nonprofits in your local city and county. There are too many resources to list here, but you never know what’s available until you check.
Utility and Everyday Cost Savings
Some programs are specific to certain age groups, disabilities, or other specific qualifying needs.
Utility Assistance Programs
There are several utility assistance programs available to low-income households or senior citizens. Many local electric cooperatives and/or utility companies will have information on their website. A good place to start looking is the local United Way or the nearest Salvation Army.
Transportation and Senior Discounts
If getting to and from the doctor’s office or grocery store becomes difficult, you may be in luck. There are generally several resources available to you. Search for local transportation resources available to you.
Veteran-Specific Benefits
If you or your spouse served in the military, you might be eligible for many services, programs, and discounts. It’s always a good idea to check the National Resource Directory for benefits you may qualify for.
You should be aware of scams. Veterans are never required to pay to apply for or access VA benefits.
Property Tax and Housing Benefits for Veterans
Many states offer an array of tax benefits for military members and veterans. Many of these are specific to the veteran’s VA disability rating, so filing a claim for a service-connected disability should be the first step.
Why Coordination Matters
For veterans, you may need to create a “roadmap” to benefits because many benefits might qualify you for additional benefits. For instance, having a documented service-connected disability may qualify you for additional benefits. Also, you may be eligible for multiple versions of similar benefits.
If you’re not careful, you might end up with a confusing array of benefits which serve similar needs.
Start with Federal, State, and County Resources
Many local benefits depend on funding or eligibility from federal or state benefits. For instance, some prescription programs only apply if you’re already enrolled in Medicare. In other cases, SNAP eligibility might automatically qualify you for other community resources.
However, most local community organizations will help point you in the right direction.
Work with a Financial Planner or Counselor
Just because you’re in a good financial position doesn’t mean you don’t qualify for local resources. It also doesn’t mean you don’t “deserve” help either. If you qualify for a benefit, we’d encourage you to apply.
Most of the time, a financial planner or counselor in the area will have a newsletter or blog with local resource information. Even if you don’t work with them directly, these folks can be a great resource for up-to-date information and insights.
Review Annually
We recommend checking for new benefits and programs each year. It’s common for programs to be shut down or defunded, consolidated, or modified over the years. It never hurts to spend a few minutes checking for new programs.
Bringing It All Together
At the end of the day, knowing your local resources can help you build a more efficient retirement plan. More than likely, your tax dollars fund many of the programs we talked about either directly or indirectly. You may as well get some use from them if you’re eligible.
Stay informed about your local community resources and get the most out of your retirement!
This article reflects the insights and opinions of its author and is not a recommendation or endorsement of their views or services.
About the Author
Clint Haynes, CFP®Helping you build a retirement with pleasure, purpose, and peace of mind.
Opher Ganel, who chose to retire while still carrying two low-rate mortgages, explains why the conventional rule that you must enter retirement debt-free can delay retirement, drain liquidity and leave you more exposed to a market downturn. Four financial advisors weigh in on when paying off the loan makes sense, when to push back (such as a large IRA withdrawal that triggers IRMAA surcharges or a legacy 3% loan), and a third path most retirees never consider.
Key Takeaways
1
Paying off your mortgage before retiring can increase your risk, not reduce it
Eliminating the payment lowers fixed expenses and the income you need, but it converts liquid, income-producing assets into illiquid home equity. Opher Ganel notes that two-thirds of the median net worth for Americans in their late 60s is already tied up in home equity, leaving little to generate income alongside Social Security.
2
Taxes and liquidity often decide whether paying off a mortgage in retirement makes sense
Advisors interviewed caution that funding a payoff from a traditional IRA or 401(k) can push you into a higher bracket, raise Medicare IRMAA premiums two years later and permanently shrink your tax-deferred base. One advisor favors payoff mainly for mortgages at 6% or higher when no meaningful tax event is triggered and 12 to 24 months of liquid reserves remain.
3
A partial paydown or dedicated mortgage reserve can beat paying off or keeping the loan
One advisor almost always models a third option: recasting the mortgage after a partial paydown, or setting aside short-duration Treasuries or a CD ladder earning close to the mortgage rate. He says this often captures most of the psychological benefit of being debt-free while avoiding a one-time tax hit and preserving liquidity.
Featuring insights from financial advisors in the Wealthtender community
Until last year, my wife and I were paying three mortgages. One on our old house, which we kept as a residential rental. Another for an office suite we both use and partially lease to others. The third for our current home.
When we’d had enough of being residential landlords, we sold the rental property, leaving us with two active mortgages. Then I reached a personal and professional decision point: should I mostly retire, or keep running my consulting business full-time?
I chose retirement.
If you were advising me then, you might have asked, “But what about the mortgages? Are you planning to pay them off?” That would have been a fair question. For many people, being debt-free feels like a requirement for retiring responsibly.
In our case, the math didn’t force the issue. We could pay off the mortgage without draining our savings, but both loans carry low fixed rates, so the payments are manageable.
Still, we’ve long planned to downsize. As empty nesters who live close to our kids, we love our home, but it’s more house than we need. But now, things aren’t so simple.
Even if we move to a home costing half as much as our current home and put 20% down, the new mortgage payment would be higher than our current one because today’s rates are so much higher. Downsizing would still reduce our cash-flow needs by lowering utilities, property taxes, maintenance costs, and insurance premiums, so it’ll likely be the right decision in the short to medium term.
But then, we’d face a familiar dilemma: should we buy the next place in cash, or take out a new mortgage and invest the difference? This isn’t a simple “pay it off or don’t” decision.
Even financial advisors don’t all agree. Some say retirees should do everything they can to enter retirement debt-free and stay that way. Others argue that tying up so much net worth in home equity reduces your retirement income and flexibility.
The real issue isn’t whether a mortgage is good or bad, even in retirement. It’s whether you’re evaluating the right factors so you can make the decision that’s right for you.
Why the “Pay Off Your Mortgage Before Retiring” Rule Can Backfire
For many people, the idea of keeping a mortgage into retirement feels not just suboptimal, but outright wrong, maybe even irresponsible.
Blame decades of conventional advice that said the only way to retire responsibly is to pay off your mortgage and any other debt you may have.
That doesn’t mean this view has no merit. If you do this:
Your retirement expenses are lower, making your lifestyle easier to sustain.
No lender can come in and take away your home for missing a few payments.
As a result, there’s the very real emotional comfort of owning your home outright.
That’s why it feels so obvious that if you can pay off your mortgage before you retire, you should absolutely do that.
However, this approach treats your mortgage as a standalone problem you need to solve, rather than as one piece of your larger financial puzzle.
And that’s the pitfall.
Because once you choose to accept that you must pay off your mortgage before retiring, it can dramatically delay your retirement age, just because you haven’t yet “checked that box.”
This, even if your overall financial picture can support it,
The result is that you aren’t optimizing for the life you want to live in retirement. Instead, you’re optimizing for following conventional wisdom that may not be wise for you.
Why Financial Advisors Disagree on Paying Off Your Mortgage in Retirement
Some advisors argue passionately that paying off your mortgage as early as possible, especially if you’re about to retire, or already in retirement, is one of the best moves you can make.
Others make just as strong a case for keeping that mortgage in place, especially if the interest rate is fixed and low.
Both sides’ reasoning is valid, for certain people, in certain circumstances.
A perfect example of why it’s called personal finance.
Advisors who favor paying off your mortgage focus on the resulting simplicity and certainty. It eliminates a high fixed cost from your monthly budget, reducing the retirement income you need. This is especially important during a market crash, when your portfolio is down, and you want to avoid, or at least minimize, selling shares.
Seen from that perspective, retiring your mortgage reduces risk and increases stability.
The advisors who argue the opposite focus on flexibility and opportunity.
If you pay off your mortgage, you’re tying up a large chunk of your investable capital in an illiquid asset that provides no income – home equity. This is often described as a “phantom return” equal to the interest rate of the loan you’re paying off.
The decision isn’t as straightforward as having cash hanging around in your checking account. For example, you may have held your 30-year mortgage for, say, 20 years. At that point, most of your payment goes toward paying off the principal, essentially moving money from your checking account into your home equity. Very little goes to interest. Suppose you have to take an IRA distribution to pay off the mortgage. Does that distribution interfere with your other goals, such as Roth conversions? Does the distribution make you jump a tax bracket, resulting in a higher tax bill? There is no way to know until you run the scenario.
Paying off your mortgage for most is a financial goal that has been worked for multiple decades. Up until 2020, many soon-to-be retirees likely had a mortgage rate of 5%+, but now we see that same demographic of soon-to-be or recent retirees locked in at historically low rates sub 4%, these historically low rates have made the decision a bit murkier.
For many, the decision to pay off or not to pay off the mortgage is part math and part emotion. If they have excess savings in non-qualified accounts, it likely makes sense to pay off the mortgage with those funds simply for the sleep-well factor.
If overfunded with qualified retirement savings, it becomes more complicated. Paying off the mortgage with those funds will have implications not only for your current tax year but also for 2 years later, with the potential for higher Medicare Income-Related Monthly Adjustment Amount (IRMAA) premiums, given the 2-year look-back. As stated above, this is a personal decision that can only be made after a careful discussion with the client and their advisor on what is best for their personal financial goals.
Peter Bo Rappmund, Principal at Counterpoint, agrees:
I lean toward paying off the loan when the math is close and the mortgage creates real friction in a client’s retirement plan. The clearest ‘yes’ cases I see are when a client has a higher-rate mortgage (6% or higher) that they took out in the last few years, the payoff doesn’t require liquidating assets that would trigger a meaningful tax event, and after the payoff, they still have 12–24 months of liquid reserves plus comfortable headroom in their portfolio to cover essential expenses. I’m also more inclined to recommend a payoff when a client takes the standard deduction anyway, that, post-Tax Cuts and Jobs Act (TCJA), is most retirees, because they’re getting no tax benefit from the interest, so the mortgage rate is effectively the after-tax rate.
Behavior matters too. For clients who genuinely sleep better without the debt and who aren’t going to redeploy their freed-up cash flow into something riskier, the psychological return is real and worth pricing in.
Especially today, when so many mortgages are fixed at historically low rates, like our 30-year fixed 3% loan. That’s a very low return compared to what that capital could likely earn if invested for retirement income.
According to DQYDJ.com, the median net worth for Americans in their late 60s is $394k. That’s not very high relative to what’s needed for a comfortable retirement. Worse, however, is that two-thirds of that net worth is tied up in home equity, leaving just $132k to generate income to supplement Social Security retirement benefits.
Anything that ties up a large fraction of your net worth in home equity makes it that much harder to have a reasonable retirement income.
Seen from this perspective, a mortgage isn’t just a liability. It’s a tool for maintaining liquidity, increasing retirement income, and increasing your margin of safety.
That’s why the argument isn’t really about whether keeping a mortgage is good or bad.
It’s about what risk you’re trying to reduce or remove, and which risk you’re more comfortable living with.
Do you prefer predictability and stability, risking a lower standard of living, or would you rather optimize for higher income along with potentially better long-term outcomes?
Neither is universally better.
Each solves for different objectives, which is what makes this a matter for careful, personalized assessment.
How Paying Off Your Mortgage Affects Your Withdrawal Rate, Liquidity and Retirement Income
From the above, it should be clear that framing this as a “mortgage = good/bad” decision is what leads to confusion and disagreement.
Because paying off your mortgage isn’t a simple decision with pros and cons that are independent of the rest of your financial picture.
It’s just one part of your overall finances, along with your income, investments, and spending, and how large or small, and how flexible or fixed, they are.
It’s more useful to shift the question from “Should I pay off my mortgage before or early in retirement?” to “How does paying my mortgage off before retirement (or in early retirement) affect my overall financial safety?”
Once you change your perspective like that, whether to keep the mortgage or pay it off stops being a standalone decision and becomes an integral part of your overall financial plan.
Paying off your mortgage:
Reduces your fixed expenses.
Lowers the retirement income you need to generate.
Per research by David M. Blanchett, PhD, CFA, CFP®, reducing the fixed fraction of your retirement budget lets you increase your safe withdrawal rate (SWR) by ~7% (Blanchett, Head of Retirement Research at Morningstar Investment Management, found that reducing your fixed expense fraction from 75% to 25%, with certain reasonable assumptions, increases SWR from 4.1% to 4.4%).
However, paying off the mortgage also:
Reduces your investable assets.
Reduces your retirement income.
Reduces liquidity and flexibility to respond to unexpected expenses and/or unexpected opportunities, should your circumstances change.
Obviously, keeping your mortgage does the opposite.
Keeps fixed expenses higher.
Requires higher retirement income.
Reduces SWR.
Keeps investable assets higher.
Increases retirement income.
And maximizes liquidity and flexibility.
That’s the trade-off most people miss.
They focus solely on the mortgage decision and miss its implications for flexibility, adaptability, and safety in retirement. And, in retirement, adaptability and safety are every bit as important as optimization, if not more so.
Table 1 shows the factors affecting your decision and how each influences it. In each line, the check mark indicates the preferred outcome.
Table 1These key trade-offs affect your decision about whether to pay off your mortgage or keep it in retirement.
Why Fixed Expenses Like a Mortgage Matter More in Retirement
While you’re working, fixed expenses can be a very good thing.
A fixed-rate mortgage means your principal and interest payment never increases during the life of the loan. No landlord raising rents, and no variable-rate loan letting the lender increase your interest rate when the market turns against you.
Predictable and stable.
As long as your income stays stable, you have little to worry about. And if something unexpected happens, you can, e.g., work longer hours, start a side gig, and/or cut expenses elsewhere.
In retirement, your earnings stop.
Instead, you depend on Social Security, pensions, if any, annuities, if any, and withdrawals from your portfolio.
The first three are predictable, but small to non-existent for most people.
The main source for a comfortable retirement is the last, portfolio-based, assuming you saved enough. Unfortunately, the markets are anything but predictable.
On average, stocks return about 10% a year. But they could gain 50% one year and drop 40% the next.
That’s why flexibility and margin of safety matter even more in retirement.
Fixed expenses like a mortgage, that can’t easily be reduced, make you less flexible.
If markets decline or expenses spike, especially early in your retirement, you have lower discretionary spending, reducing the area where it’s usually the easiest to trim costs when needed.
If you need to cover higher expenses and/or have to sell more shares at depressed prices during a bear market to make ends meet, your risk of running out of money increases.
On the flip side, if more of your spending is discretionary, you have more levers to pull to respond to a market crash and/or an expense spike. You can temporarily reduce travel, delay replacing the car, scale back gift-giving, etc., all without disrupting your core lifestyle for long.
On the other hand, even with somewhat higher fixed expenses, a significantly larger portfolio increases your baseline retirement income, which gives you a greater margin of safety, either by allowing you to increase your discretionary spending even more (so a larger fraction of your budget is discretionary) or by drawing a smaller percentage of your portfolio value each year.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
Why Downsizing Doesn’t Eliminate the Mortgage Trade-off in Retirement
Downsizing seems like an attractive option for many retirees facing cash-flow limitations.
You sell an expensive home that’s larger than you need, and buy a smaller, less expensive one. This lets you eliminate your mortgage or at least replace it with a smaller loan.
Ideally, that smaller loan means lower monthly payments.
Except when it doesn’t, like in our case.
As mentioned above, our current mortgage rate is so much lower than the current market rates that we could move to a home that costs half as much as our current one, take a new mortgage with 20% down, which would significantly reduce our mortgage balance, and end up with a higher monthly payment than what we’re paying now.
At the same time, downsizing will reduce other costs:
A smaller home is easier to manage and cheaper to maintain.
It also tends to reduce utility expenses.
A less expensive home usually means lower property taxes.
It’s also typically less expensive to insure.
All of these reduce monthly cash flow needs, which is an important goal in retirement.
So, we’re still likely going to downsize, at which point we’ll come up against a similar trade-off. What do we do with the equity we unlock from our current home when we sell it?
Do we use most of it to buy a less expensive home outright, with no mortgage, or do we use a small portion of that equity to put down just 20% for a new loan?
This decision goes back to the trade-offs we described above, for eliminating your mortgage before retirement or keeping it in place.
The former would dramatically reduce our cash flow needs and fixed expenses. Still, it would also cost us the opportunity to increase our investable assets and the greater margin of safety that higher retirement income provides.
The latter would reduce our cash flow needs and fixed expenses, but nowhere near as much, because we’d still have the large mortgage payment. However, it would significantly increase our portfolio size, and, along with that, our retirement income and the resulting margin of safety.
Downsizing changes the specifics, but it doesn’t eliminate the trade-offs and the decision.
How to Decide Whether to Pay Off Your Mortgage in Retirement: 5 Questions to Ask
As we said before, there isn’t a single, universally correct answer that tells you to eliminate your mortgage before retirement (and stay debt-free thereafter), or not.
But that doesn’t mean you have to guess.
You just need better questions and a better decision framework.
Rather than considering the mortgage payoff question in a vacuum, you need to evaluate the multiple impacts on your overall financial situation.
With the mortgage vs. without it, how much of your budget is fixed and non-negotiable, and how much is discretionary? The higher your fixed expenses, the more income you need in retirement, regardless of your portfolio’s performance in any given year. This puts more pressure on your investments and makes it harder to adapt when needed.
Next, how much of your fixed expenses are covered by predictable sources like Social Security retirement benefits (which also get adjusted up for inflation), pensions, and annuities? The higher the portion of fixed expenses that you can cover from predictable income, the less you need to take from your portfolio, which is especially important when, not if, the market crashes. This gives you more flexibility in managing your investments.
Now, look at liquidity. How much of your net worth is tied up in your home equity, which is illiquid and doesn’t generate income that lets you cover unexpected (or even planned-for) expenses? Paying off the mortgage (and not taking out a new one) increases the part of your net worth that’s tied up and non-productive like that. Keeping your mortgage (or taking out a new one when downsizing) does the opposite.
Beyond the numbers, it’s time to look at the emotional aspect. When the market crashes, how comfortable will you be with having to continue making fixed mortgage payments? Or would eliminating that mortgage make it easier to stick with your financial plan? Your answers to this point are at least as important as the results of the above three calculations.
Finally, consider your margin of safety. Is your portfolio large enough to comfortably support your lifestyle, even when things don’t go exactly as planned? Or are you so close to the edge that you need to do something to increase your margin, e.g., by increasing your productive investments?
Putting all these factors together is how you can make a holistic decision that accounts for the multiple ways that eliminating or keeping the mortgage will affect your retirement in the long term.
After all, that’s the critical goal here.
Not to become debt-free at all costs, and not to maximize returns at all costs.
But to build a plan that offers you a combination of stability, flexibility, margin of safety, and long-term sustainability that you’re most comfortable with and lets you stick with the plan.
When to Pay Off Your Mortgage Before Retiring, and When Not To
Rappmund offers a comprehensive, balanced look at when to pay off vs. when not to. “I lean toward paying off the loan when the math is close, andthe mortgage creates real friction in a client’s retirement plan. The clearest ‘yes’ cases I see are when a client has a higher-rate mortgage (6% or higher) that they took out in the last few years, the payoff doesn’t require liquidating assets that would trigger a meaningful tax event, and after the payoff, they still have 12–24 months of liquid reserves plus comfortable headroom in their portfolio to cover essential expenses. I’m also more inclined to recommend a payoff when a client takes the standard deduction anyway, that, post-Tax Cuts and Jobs Act (TCJA), is most retirees, because they’re getting no tax benefit from the interest, so the mortgage rate is effectively the after-tax rate.
Behavior matters too. For clients who genuinely sleep better without the debt and who aren’t going to redeploy their freed-up cash flow into something riskier, the psychological return is real and worth pricing in.
I push back hard when paying off the mortgage would require a large taxable distribution from a traditional IRA or 401(k), or a concentrated capital gains realization. Especially if it pushes the client into a higher marginal bracket, triggers IRMAA surcharges, or causes more of their Social Security benefit to become taxable.
I also advise against it when the mortgage is a legacy (3% or lower) loan; that’s an inflation hedge and a negative-real-rate liability you generally don’t want to retire early. And I won’t sign off on a payoff that leaves a client house-rich/cash-poor, because home equity is the least useful asset in a downturn. You can’t eat it, and a Home Equity Line of Credit (HELOC) can be frozen by the bank at exactly the time you need it most.
Common Mistakes When Deciding Whether to Pay Off a Mortgage
But even when the math seems clear, mistakes are common. Rappmund shares several common mistakes people make:
The single most common mistake I see is comparing the mortgage rate to a hoped-for portfolio return without adjusting for risk, taxes, or sequencing. A client says, ‘My mortgage is 4%, and my portfolio earns 8%, so it’s obvious.’ That comparison is wrong on two fronts: paying off the mortgage is a guaranteed, after-tax return equal to the mortgage rate, while the 8% is a pre-tax, risk-bearing expected return that includes years like 2008. The right comparison is the mortgage rate vs. the after-tax yield on a similar-duration, low-risk bond. On that basis, the decision is much closer than people think.
The second mistake is solving for net worth instead of cash flow. Retirement is often fundamentally a cash-flow problem, not a balance-sheet problem. Two clients with identical net worth can have radically different retirement experiences depending on how much of their monthly expenses are fixed and inflexible.
And the third, which I see all the time, is making this decision in isolation, separate from the tax plan. Pulling $300k out of an IRA in a single year to clear a mortgage can cost a client tens of thousands in avoidable taxes and Medicare premium increases, and it permanently shrinks the tax-deferred base that was going to compound for the next 20 years.
The Third Option: Partial Paydown or a Dedicated Mortgage Reserve
So how should you actually evaluate the trade-offs? Rappmund describes how he helps clients with this:
I help clients weigh the tradeoff between reducing fixed expenses and preserving liquidity and investment income in retirement by separating the question from the math and asking what role this decision plays in the plan. We map out essential expenses (housing, food, healthcare, insurance) vs. discretionary, and we look at what’s already covered by guaranteed income (Social Security, pensions, and annuities).
If the mortgage payment is the difference between essentials being covered by guaranteed income and not, that’s a strong argument for retiring the debt; you’re effectively buying yourself a higher floor and reducing sequence-of-returns risk in the early retirement years, which is when portfolio damage is most permanent.
From there, we run the actual numbers in the financial plan, modeling paying it off, keeping it, and a third path. And I almost always show a third option, because most clients don’t realize it exists. That path is something like recasting the mortgage after a partial paydown or carving out a dedicated mortgage reserve in short-duration Treasuries or a laddered CD portfolio that earns close to the mortgage rate and gives the client the option to extinguish the loan later if rates or circumstances change.
That tends to be the right answer surprisingly often, as it captures most of the psychological benefit and avoids a one-time tax event. The frame I leave clients with is that liquidity is itself a form of insurance, and in retirement, it’s one of the cheaper kinds you can own.
Paying off the mortgage converts a flexible asset (cash and securities) into an illiquid one (home equity), and that conversion is irreversible without taking on new debt at whatever rates happen to exist when you need it. So, the question isn’t really ‘should I pay it off?’ Rather, it’s ‘what’s the right amount of fixed-expense reduction I can buy without giving up more flexibility than I can afford to lose?’
It removes a fixed obligation, simplifies your finances, and reduces the retirement income you need. But it does so while reducing your retirement income, increasing the risk that you’ll need to sell assets when they’re depressed, and leaving you with less liquidity and flexibility.
Over a decades-long retirement, in many situations, those risks may be the ones you’re less comfortable carrying.
That’s why there isn’t a universally correct answer to the question of eliminating your mortgage before retiring. It’s because the “enter retirement debt-free” rule, like any other financial rule, is designed to offer a simple shortcut for making decisions.
But your situation isn’t simple.
It’s multi-faceted and different than anyone else’s.
A complexity that simple “rules” can’t capture.
The Bottom Line: Should You Pay Off Your Mortgage Before Retiring?
As frustrating as it may be, I can’t give you an answer on whether you should wait until you’ve paid off your mortgage before entering retirement, or even whether taking out a new mortgage in retirement when downsizing makes sense.
That’s because my answer is just that – mine.
You need your answer.
And that answer depends on many factors:
How large is your nest egg?
How high a retirement income do you need to be comfortable?
How will paying off your mortgage affect those two answers?
What risks are you comfortable carrying, and which ones do you need to avoid?
Which decision gives you the best chance of sustaining your desired lifestyle in retirement over the long haul?
Can you, emotionally, stick with a plan that keeps a mortgage into retirement?
For many people, these factors result in a preference for paying off their mortgage.
For many others, they’ll point to keeping the mortgage in place for as long as possible.
Both approaches are right, given the right circumstances. And both are wrong given the wrong situation.
Your bottom line must be based on a clear understanding that the mortgage payoff decision must be made as part of a comprehensive assessment of your personal situation, goals, and risk preferences.
Because to have a good retirement, your decisions can’t be based on box-checking.
They need to be made as part of a comprehensive plan that you can live with and stick to, through good markets and bad, because you will live through both.
I’d only strongly recommend paying off a mortgage if the payment is creating stress or the person needs simplicity to sleep at night. Beyond that, the math doesn’t always support it. I actually push back on people who rush to pay it off just because it ‘feels safe.’ In a lot of cases, they’re trading liquidity and flexibility for a psychological win.
The biggest mistake is treating the mortgage like the enemy instead of looking at the full picture. I’ve seen retirees drain a large chunk of their savings to wipe out a low-interest mortgage, only to put themselves in a tighter position long term. They feel better emotionally, but financially, they’ve boxed themselves in. I frame it as control vs. comfort. Paying off the mortgage gives you comfort, no payments, and a clean slate. Keeping the mortgage often gives you more control, more liquidity, and more flexibility if something changes. Most people default to comfort without realizing what they’re giving up. Debt isn’t the problem in retirement. Poor planning is. A mortgage can be managed. Running out of options can’t.
A practical way to start is this: picture both scenarios.
One where your mortgage is gone, but your portfolio is smaller, and one where your mortgage remains, but your portfolio is larger and more flexible.
Which scenario gives you more confidence that you can handle whatever comes next?
Frequently Asked Questions
Should I pay off my mortgage before I retire?
There is no universal answer. Paying it off reduces fixed expenses and the retirement income you need, while keeping it preserves investable assets, liquidity and flexibility. The article argues the decision should be made as part of your full retirement plan, weighing fixed versus discretionary spending, guaranteed income, liquidity, emotional comfort and your margin of safety.
When does it make sense to pay off a mortgage in retirement?
One advisor interviewed leans toward paying off the loan when the rate is 6% or higher, the payoff doesn’t require selling assets that trigger a meaningful tax event, and 12 to 24 months of liquid reserves remain afterward. Advisors also note that if being debt-free genuinely helps you sleep at night, that psychological return is real.
Is it a mistake to use IRA money to pay off a mortgage?
It can be costly. Advisors interviewed warn that a large traditional IRA or 401(k) distribution can push you into a higher tax bracket, trigger Medicare IRMAA surcharges based on a two-year look-back, make more of your Social Security taxable and interfere with goals such as Roth conversions. One advisor says pulling $300k from an IRA in a single year can cost tens of thousands in avoidable taxes and premiums.
Should I keep a low-interest mortgage in retirement?
Many advisors say yes, especially for fixed loans at 3% or lower. One advisor interviewed calls such a legacy loan an inflation hedge you generally don’t want to retire early, and another cautions against draining savings to wipe out a low-interest mortgage, only to end up in a tighter position long term.
Does downsizing solve the mortgage question in retirement?
Not entirely. Downsizing can lower utilities, property taxes, maintenance and insurance, but with today’s higher rates a new, smaller mortgage can carry a higher payment than an old low-rate loan. You still face the same choice of buying outright or financing and investing the difference.
Find your fit
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.
Opher Ganel, who paid for his children’s degrees with $0 in college savings, argues that benchmarks like T. Rowe Price’s age-based targets are a sanity check, not a scorecard. Five financial advisors explain why deciding how much you are willing and able to pay, choosing an affordable school and protecting retirement first matter far more than your 529 balance.
Key Takeaways
1
College savings benchmarks measure a hypothetical family, not yours
T. Rowe Price’s targets (for example, about $91k saved by age 15 for a private school) assume you saved consistently from birth, aim to cover about 50% of costs and knew in advance which type of school your child would attend. Most families don’t fit that profile, so being behind on paper reflects mismatched assumptions, not a verdict on whether your child can afford college.
2
Deciding how much you will pay for college matters more than how much you’ve saved
Defining your commitment (full cost at any school, in-state cost only, a fixed dollar amount or a percentage) drives school choice, loans, scholarship goals and how much catching up you need to do. Advisors warn that “If you get in, we’ll figure it out” is the most dangerous promise in college planning, especially with new federal student loan borrowing limits.
3
Prioritize retirement savings over college savings when you can’t fully fund both
Your child can use loans, scholarships, part-time work and school choice to pay for college, while your options for funding retirement shrink the longer you wait. One advisor frames the choice as extra working years: funding $240,000 of undergrad costs on $120,000 of after-tax income could mean working two more years.
Featuring insights from financial advisors in the Wealthtender community
According to T. Rowe Price (TRP), for example, the full cost of attendance for a four-year degree is $103k at a public university for in-state students and $183k for out-of-state students. At a private non-profit school, that cost grows to $244k.
TRP expects parents to save up enough to pay about half of that, considering likely grants, scholarships, loans, and income from current employment during school years.
If you’re anything like my family was while our kids were growing up, it can seem like an impossible task, especially given all the competing priorities, like putting food on the table, keeping a roof over your head, and hopefully saving at least some money for retirement.
When our kids were growing up, we never managed to save a single dollar toward their college costs, let alone meet TRP’s benchmarks, shown in Table 1.
Table 1Guidelines for the amounts to be saved by children’s age and school type, per TRP (based on covering ~50% of total costs).
In practical terms, that means being expected to have tens of thousands saved well before high school. Those are big numbers, especially if you’re starting late.
Say you have a 15-year-old who has her heart set on attending a private university. Do you already have $91k in her college fund?
If you’re not on track with these guidelines, the gap can feel increasingly uncomfortable. You may be asking yourself, “Are we behind?”
And if the answer is yes, you may be thinking, “Are we failing our daughter?”
That’s a feeling I know well from firsthand experience.
Since we didn’t have a college fund, we had to figure out ways to cover those costs as we went, using current income, with trade-offs and uncertainty as our constant companions.
When our son was accepted to our state university’s flagship campus, the University of Maryland, College Park (UMCP), and to a prestigious private school he preferred, we sat him down to discuss what each choice would mean.
We could cover the full costs of a degree at UMCP without taking out loans, but the private school would have left him with many tens of thousands of dollars in student-loan debt by graduation, even considering their offer to reduce his tuition by 50%.
Conversations like this, and the decisions they led to, shaped how we paid for our kids’ degrees, how they approached school and work, and, ultimately, their careers.
All this forced us to face something that benchmarks and guidelines don’t usually address. Those numbers were never intended to be treated as a scorecard.
They’re a useful planning tool, based on specific assumptions, defined savings goals, and the ability to contribute consistently from birth to college graduation. If you’re anything like we were, your life simply doesn’t look like that.
Some families start late.
Some can’t save consistently, or at all.
Even if you saved from your kid’s birth, they may start out willing to attend their state school, only to decide later that they really want to attend a highly selective, super expensive private school. And when that happens, say when they’re 15, even in the unlikely case that you were “on track” up to that point, you’re suddenly less than halfway to where you’re “supposed” to be.
And yet, many of those families still find a way to make it work.
Not by hitting all the benchmarks on time, but by making informed decisions about what they’ll pay for, what they won’t, and how they expect their children to support the process.
Unless you’re uber-wealthy, you can’t avoid all trade-offs. But you can and should make smart choices about the trade-offs you face.
What that looks like is what we’ll cover below.
What Do College Savings Benchmarks Actually Measure, and What Do They Miss?
The biggest pitfall of benchmarks like TRP’s is if you believe they’re something they’re not, which may then lead you to despair or make unsustainable decisions.
First, what they aren’t.
They’re not requirements, predictions, or guarantees.
They’re just intended to give you a sanity check. And even that’s limited, because they’re trying to give you a plausible path to successfully funding your kid’s college career, without knowing anything about your situation.
How old is your child?
What’s the full cost of attendance at the college your child will attend, and how will that cost change by the time your child graduates?
How many college years will your child need to graduate (4 is the minimum, not a maximum or even the median*)?
How many other children do you have, for whom you need to save in parallel?
How much, if anything, do you already have saved up for their college expenses?
How much can you afford to put into their college fund, and how consistently?
How will you invest that college fund, and what returns will you achieve?
* According to the National Center for Education Statistics (NCES), “In 2020, the overall 6-year graduation rate for first-time, full-time undergraduate students who began seeking a bachelor’s degree at 4-year degree-granting institutions in fall 2014 was 64 percent.” This means that more than one in three students took longer than 6 years to graduate! The median time to graduate was 52 months, and only 44.1% graduated in 4 years.
So, not knowing any of those things, they make assumptions:
You have one child (or the following is true for each of your children).
You started saving from your child’s birth and contribute a consistent amount each month.
You aim to cover 50% of the full cost from your college fund.
Your college fund is invested and will compound at a “reasonable” long-term rate.
You know the cost level of your child’s college (between the three levels they show).
With all these hypotheticals in place, they generate a plausible trajectory that helps you see if you’re ahead, on track, or behind.
But there’s a problem.
You live in the real world, not in their hypothetical “typical” scenario.
You may have started saving later than ideal.
You face competing priorities and may have had months (or years) when you couldn’t contribute as much, or at all, to the college fund.
College costs are unlikely to stay the same over the 20+ years from when your kid is born until they graduate from college.
You may think you’ll send your kid to your state’s school, but they may choose to go to a far more expensive private school.
Benchmarks are hard to trust because the true out-of-pocket cost varies so much from family to family. There are too many variables on the front end to know whether you’re ahead or behind.
Using the benchmarks as gospel is like playing on a tilted playing field with moving goalposts.
Stressful and not very helpful.
T. Rowe Price’s “Ramp-Up” Benchmarks for Families Who Start Small
TRP recognizes this and provides a secondary set of benchmarks for parents who can’t save as much as their main model assumes, starting from their child’s birth. This secondary model assumes lower contributions early on, with contributions increasing gradually, as seen in Table 2.
Table 2Guidelines for the amounts to be saved by children’s age and school type, per TRP’s “Ramp up” model (based on covering ~50% of total costs).
This seems much more practical because many families face higher expenses in the early years, especially for childcare, and their earnings are usually lower than in later years. As these factors reverse, it becomes easier to allocate money for college savings.
This shows that TRP realized their benchmarks need flexibility, though even this “ramp-up strategy” doesn’t necessarily account for your specific situation and how it will evolve over 20+ years.
As you can tell, these benchmarks should be viewed as one reference point, not a judgment or verdict on how successful you are.
They help answer the question: If everything went according to the specific assumptions of these benchmarks, where should I be at this point?
They don’t answer any of these questions:
Am I doing this right?
Have I already failed?
Will my child end up unable to go to college because I haven’t saved enough?
They also don’t tell you what to do next, given your specific situation, which is really the only thing that would make a difference.
Things like:
Discuss school choice with your kid and make clear what you can and likely cannot afford.
Adjust your aim to a smaller portion of the full cost of a degree, with grants, scholarships, and loans covering the remainder.
Have your kid work part-time through college to help pay tuition.
Two families can have identical college-fund balances for kids at the same age but have completely different likelihoods of success, depending on how they address potential shortfalls.
That’s why financial advisors tend to treat such benchmarks as a starting point rather than a plan. They use them to surface potential gaps, then shift to defining realistic goals, prioritizing competing needs and goals, and proposing ways of making the plan work by increasing income, decreasing spending, or a combination of the two.
As Joe Stabile, founder of Coast Financial, explains:
Most families I speak with would like to fund their kid’s college 100% if they could, but also understand it may not be realistic. I’ve found that the best way to give them confidence in their decision is to show them different scenarios on what it would take to fund different levels of college tuition. For example, showing them the monthly savings required to fund 100%, 75%, 50%, and 25% of projected college tuition at different tuition rates. Once they see these numbers and we have a conversation about their family values, they feel much more confident in their approach.
This kind of scenario planning helps make trade-offs concrete and easier to evaluate.
In other words, benchmarks can tell you how close you are to a plausible trajectory, but don’t tell you what to do about it.
That’s our next focus.
Stay connected
See more of Wealthtender when you search Google
Add us as a preferred source, and our guides to personal finance and choosing a financial advisor can appear more often in your Google results, with a “Preferred” label in AI Overviews.
How Much Should Parents Pay for College? The Decision That Matters Most
Since benchmarks don’t tell you what to do next, what does?
The answer is both simpler and more uncomfortable than you might expect.
You need to decide how much you’re actually willing and able to pay toward your child’s college.
I find that most families are behind in saving for college and don’t understand what they’re likely to be expected to pay at different schools. While saving for college is important, choosing the best school you can actually afford has far more impact.
What type of school can your child realistically attend, cost-wise?
Will they need to take out student loans, and if so, how large?
Will they need to bring in scholarships and grants?
Will they need to work during college to help cover costs?
How much “catching up” do you have to do?
Without such clarity, you risk defaulting to “We should cover the full cost of attendance at whatever school she chooses.”
Steve Witter, CFP®, CSLP®, Founder of Student Loan Steve, warns:
The biggest mistake I see with parents is telling their kid that ‘if you get into your dream college, we will figure it out.’ With the new student loan borrowing limits and the loss of parents’ ability to repay Parent Plus loans based on income, it’s more important than ever to have a college budget and stick to it.
The most dangerous words in college planning are ‘If you get in, we’ll figure it out.’ Families need a plan and a budget for college. You don’t shop for Ferraris if all you can afford is a Honda. College shouldn’t be any different.
Suffer long-term financial stress that lasts long after your kid graduates.
This is why a good financial advisor won’t ask, “How far behind are you?”
Instead, your advisor is more likely to ask, “What role do you want to play in paying for your child’s college?”
Your answer could be, “All costs related to getting the degree at whatever college he chooses.” And if you can afford that, without shortchanging your other priorities, your advisor will work that into your plan.
However, you could instead say, “Full cost of attendance for 4 years at the in-state tuition level,” or a fixed dollar amount, or a set percentage of total cost.
There’s no universally right answer here.
There’s just an answer that’s right for you, your situation, and your priorities.
Williams explains:
School choice still matters, but it’s not as clean as ‘public = affordable, private = expensive.’ There are exceptions on both sides. What matters more is getting clear early on whose shoulders the funding will fall. Are the parents and student willing to take on loans? Is the student prepared to do the work required to get merit-based aid, such as scholarships or grants? How much? These answers matter a lot.
He then addresses what often happens when there are several children, “I commonly see spouses who aren’t aligned on what college funding should look like, especially with multiple kids, when ‘being fair’ becomes the goal. Fairness is our instinct as parents, but life doesn’t sit still. One spouse loses a job, or bonuses dry up, or, on the flip side, income increases. The financial picture that existed when your oldest started school often looks different by the time your youngest gets there.”
Should You Prioritize College Savings or Retirement Savings?
Except for the wealthiest among us, we all face financial trade-offs.
The biggest such trade-off regarding funding college is how it interacts, not to say interferes, with saving and investing for retirement.
Hunsberger shares how he illustrates this to clients:
I like to frame the savings choice between college and retirement in terms of how much longer the parents will need to work if they decide that funding college is the priority. If their after-tax income is $120,000 and they have 2 kids that they expect will cost $240,000 to get through undergrad, I make sure they’re willing to work for an additional 2 years.
Every family is different, but my general coaching is to put your own oxygen mask on before helping others with theirs. Some parents commit to covering every dollar of their kid’s education without realizing that choice might require them to work three more years before they can retire comfortably. I want them to see that tradeoff clearly before they share any funding expectations with their students.
I’m sure you’ve heard the common saying, “You can borrow for college, but not for retirement.”
And while it’s not completely accurate, since you cantake out a reverse mortgage to help fund retirement, it is directionally true, since those options tend to be expensive, reduce flexibility, and leave you with a smaller cushion later in retirement.
Student loans, on the other hand, are a $1.8 trillion (and growing) industry that includes both federal and private options.
This doesn’t mean that student loans are appropriate in all cases, nor that students don’t often over-extend themselves and then struggle with years or decades of debt repayment.
But it is a broader and more readily available resource.
Peter Bo Rappmund, Principal at Counterpoint, explains:
Regarding how to balance college savings with retirement savings, especially when you can’t fully fund both, the priority is clear: retirement comes first. You put on your oxygen mask, then help your kids. Your child has decades of options to pay for college, including loans, scholarships, part-time work, and school choice. You have far fewer options to fund retirement, and they all diminish the longer you wait. I remind clients that a loving and thoughtful thing you can do for your kids is not to become their financial burden in 20 years. So, we protect retirement at the level we need to commit to, then direct what’s left toward college, and we have an honest conversation with the child about what that means for school choice.
Can You Pay for College With $0 Saved? One Family’s Real-World Example
In our situation with my two older kids, this wasn’t a theoretical trade-off.
We barely managed to put something away for retirement. We certainly couldn’t save anything for their college expenses, so we had to figure out what we could and would do.
Their mother and I, seeing our trajectory early on, told them both, from when they were tweens, that we would cover their full cost of attendance for 4 years at UMCP in-state levels.
If they wanted to attend a more expensive school and/or if they took longer than 4 years, it would be up to them to cover the difference. This could be from grants and scholarships, or student loans.
That was the context of our later conversation with our son, which led him to decline his acceptance to the private school he initially preferred and to attend UMCP.
While this wasn’t an easy conversation to have, it was clear.
And it was that clarity that led him to make that choice, because he understood that (a) managers at the private school had a higher regard for UMCP graduates in his field than their own, all other things being equal; (b) it would be far better for him financially to avoid the crushing student debt he’d incur; and (c) his career outcome was unlikely to be affected by school choice in the long term, based on research that shows long-term earnings are often similar regardless of school selectivity.
As a result, he graduated in 4 years with a degree in his chosen field from a highly regarded school and went on to a successful career, all from a starting point of $0 in college savings when he started school.
Rappmund says such conversations are critical:
The biggest mistake I see parents make when trying to fund their child’s college education is when they avoid the conversation. Parents will save diligently for 18 years and then never sit their kid down to say, ‘Here’s what we can pay for, here’s what we can’t, and here’s what we expect you to bring or compromise on.’ That straightforwardness and clarity are worth more than another $20,000 in the 529 plan. The mistake isn’t so much that too little was saved. It’s hoping the numbers will perfectly work themselves out by the finish line.
This illustrates the limitations of college savings benchmarks.
They focus only on the savings balance and the child’s age. Understandably, they can’t account for the things you can do to address any “paper shortfalls.” Things like setting expectations and deciding what trade-offs you’re willing to make.
Two families can have identical college-fund balances, be equally behind (or on track) on paper, and end up with vastly different ultimate outcomes. Had we encouraged our son to go to the private school, his results would likely have been far worse.
In other words, while how much you’ve saved matters, the decisions you make about funding, school choice, and trade-offs matter far more.
That’s what ultimately determines whether a family ends up with a workable outcome or one that creates long-term financial stress.
As Rappmund puts it:
Benchmarks can be a good sanity check, but shouldn’t be a scorecard. The savings balance tells me where a family stands on a hypothetical track. It tells me almost nothing about whether they’ll reach a good outcome, though. The decisions matter far more. I’ve seen families who were ‘behind’ on paper end up just fine because they had those conversations early. And I’ve seen families who were ‘on track’ get into real trouble because they never did.
The most important takeaway here isn’t that you shouldn’t try to set aside money for your kids’ college education.
It’s that your goal can’t be to avoid every trade-off; it should be to make the trade-off choices that are right for you and your family.
Articulate and share with your kids what you’re willing and able to pay towards their college expenses. Once you do that, even if you’re far behind on paper, your path forward becomes much clearer.
What to Do If You’re Behind on College Savings, Based on Your Child’s Age
If you made it this far and still feel behind, you’re not alone.
But remember, what matters most isn’t where you are relative to benchmarks based on “typical” assumptions.
It’s what you’ll do next.
TRP acknowledges this and offers more nuanced guidance based on your child’s age.
If your kid is young, they suggest trying to redirect money spent on childcare to college savings. The point isn’t to fix everything immediately by magically making up any savings shortfall, but to concentrate on changing the trajectory.
If your kid is about halfway to college age, they suggest asking family and friends to make college-funding contributions as holiday and birthday gifts, and using income increases, and budget cutting to increase college savings. Here, the point is to make serious changes that make it at least plausible that you’ll hit your goal.
When there’s little or no time left, their guidance is to try to get scholarships, student loans, and paid internships or part-time work while in school. At this point, you’re in the situation we were in. It’s too late to save for college, but you still have options for getting to a good outcome, especially if your kid is willing to attend your state school.
In our case, we did what we needed to do:
Set clear boundaries.
Made trade-offs explicit for our kids.
Set expectations that they’d work while in school and contribute some of their earnings toward their college expenses.
Using a 529 Plan for a State Tax Deduction Even When Paying Tuition Now
We also took (legal) advantage of our state’s 529 plan rules.
In Maryland, contributions to a 529 plan may qualify for a state income tax deduction, even if the funds are used shortly after you contribute. Thus, when we needed to make a tuition payment, we first put the money into a 529 plan, then withdrew it the next day and sent it to the school.
We couldn’t benefit from the tax-free growth of investing over time in such plans, but we did get the state income tax deduction for the 529 contributions, which helped make those college expenses somewhat more affordable.
Author’s note
The details of 529 plan rules vary by state, so you may or may not be able to do something similar. But the broader point stands. Even late in the process, there are probably ways you can improve your situation.
The Bottom Line on College Savings Benchmarks
Benchmarks are useful tools. But they’re not a guilty verdict when you’re behind on paper.
Instead of stressing over how far behind you may be, focus on what you can still control.
Evaluate and adjust your strategy and the trade-offs you’re willing to accept.
Decide what you’re willing and able to pay.
Make adjustments where you can.
What you’ve saved so far gives you options you wouldn’t have otherwise. But it doesn’t determine your outcome.
The most important factors in determining your results are the trade-offs you choose and the actions you take from this point forward.
Frequently Asked Questions
How much should I have saved for my child’s college by now?
T. Rowe Price’s benchmarks assume parents save about half of the full cost of attendance, which it puts at $103k for a four-year in-state public degree, $183k out of state and $244k at a private nonprofit school. That works out to roughly $91k saved by age 15 for a private school. The article stresses these figures rest on assumptions (saving from birth, consistent contributions, a known school type) and should be treated as a sanity check, not a requirement.
What should I do if I’m behind on college savings?
Focus on what you can still control: decide what you’re willing and able to pay, share that clearly with your child and make adjustments where you can. With a young child, redirecting childcare money as it frees up can change the trajectory; midway, gifts from family and income increases help; near college age, scholarships, loans, part-time work and an in-state school become the main levers.
Should I save for college or retirement first?
The advisors interviewed say retirement comes first when you can’t fully fund both. Students have loans, scholarships, work and school choice to pay for college, but parents have far fewer ways to fund retirement. One advisor reminds clients that not becoming a financial burden to your kids later is itself a loving thing to do.
How do I decide how much to pay for my child’s college?
Start with the role you want to play: covering every cost at any school, the full cost at in-state levels, a fixed dollar amount or a set percentage. One advisor interviewed shows families the monthly savings needed to fund 100%, 75%, 50% and 25% of projected tuition, then discusses family values. Advisors also urge parents to agree with each other and tell their child early, rather than promising to “figure it out” after acceptance letters arrive.
Can you get a 529 state tax deduction if you pay tuition right away?
In some states, yes. The author’s family, in Maryland, deposited tuition money into a 529 plan, withdrew it the next day to pay the school and still received the state income tax deduction, though without any tax-free growth. 529 rules vary by state, so check yours before trying something similar.
Find your fit
Find financial advisors who specialize in helping people like you
Search Wealthtender by specialty, location and fee type, compare advisors’ approaches, and read what their clients say before you reach out.
Disclaimer: This article is intended for informational purposes only, and should not be considered financial advice. You should consult a financial professional before making any major financial decisions.
My career has taken some unexpected turns, from earning a PhD in experimental high-energy physics, to conducting cosmic-ray research in Antarctica, to supporting NASA projects and programs, to running my own consulting business. I also run several other small businesses and help my wife run her Marriage and Family Therapy practice.
Those experiences taught me to question assumptions, think critically, and recognize that real-world decisions of any significance rarely have simple answers that apply to everyone. Today, I bring that perspective to writing about personal finance. Drawing on my analytical background, business experience, and research, I explore financial decisions, challenge conventional wisdom, and help readers understand the tradeoffs that can affect their financial well-being. To complement my own research and experience, I also weave insights from financial professionals into my articles, drawing on their expertise and real-world experience helping clients navigate financial decisions and challenges.
At medium.com/@opher-ganel, you can read more of my articles and subscribe to receive email notifications when new ones come out.
It seems like a tempting offer; lower fees are certainly a benefit, as costs impact total return for investors. However, an early investor discount isn’t the only factor to consider (nor is it the most important) when deciding if a private equity opportunity is right for your portfolio.
Before locking up a portion of your money into a new opportunity, you should know how the investment works, where it fits into your broader plan, and whether the manager is reputable. Two concepts can help you cut through the noise: the J-Curve, which explains why early returns often look discouraging, and fee discounts, which fund managers use to offset that early sting. Understanding how they connect, and what neither one tells you, can help you make a more informed decision.
What Is the J-Curve?
Many private equity funds begin with an investment period where capital is called from the investor (commonly referred to as drawdown funds). During this period, the fund is looking for feasible investments and collecting capital from investors on an as-needed basis. Once they’ve identified and acquired businesses, the capital is deployed, acquisitions completed, and the businesses are infused with funds to help increase profitability.
When the initial acquisition takes place, no value has yet been gained on the investment, meaning returns are nonexistent—possibly even negative.
The acquired companies begin to improve operations and gain value. During this time, investors may be paying management fees or other operating expenses. With no meaningful exits yet (or no companies sold), gains likely haven’t been realized either. The combination shows a slow start for the fund on paper. If you were to plot the path on a chart, it would resemble the letter “J” (hence the name).
As portfolio companies grow, improve, and eventually get sold or recapitalized, returns may start trending upward at a steeper rate.
While an initial downturn in value might surprise new investors, the J-curve is a relatively normal part of how private equity performance typically moves.
So, Why Do Fund Managers Offer Fee Discounts?
Remember, it’s likely that once investors have joined the fund, they’ll see the value of their investment initially drop before (ideally) rising over time. Fund managers recognize that this initial downward dip can feel painful for investors. Many offer reduced management fees as a way to soften the blow and reward early participation.
Lower fees may modestly improve net returns over time and can help reduce some of the drag that often appears during a fund’s earlier stages.
However, a fee discount does not improve the quality of the underlying investments or determine whether a management team is reputable. It also won’t accelerate when portfolio companies are ready to be sold, nor will it reduce risk.
While it may be an effective way to reward those willing to commit capital early in the fundraising process, it should not be a primary reason to invest.
Deciding if Participation Makes Sense
When I evaluate a private equity opportunity with a client, there are a few specific questions I like to start with.
Who is the fund manager?
It’s important to review a fund manager’s track record, paying close attention to how they performed through different market environments. Remember, you’re trusting these managers with your capital. The quality of the team managing the fund is paramount to the success of the investment.
What is the strategy, and does it make sense for you?
Some funds focus on buying mature businesses. Others target growth companies, distressed opportunities, or niche sectors. The strategy should align with your goals, risk tolerance, and broader portfolio design.
Are you comfortable with the time horizon?
Private equity is typically a long-term commitment, often with a 5- to 10-year lifecycle. Your capital will likely be tied up for an extended period, with limited opportunities for liquidity along the way. Investors need to be comfortable planning around that reality.
How does it fit within everything else you own?
While everyone’s asset mix is unique, a private equity allocation will likely need to complement a larger investment strategy, not dominate it.
That is why I often tell clients, you are not investing because of a fee break. You are investing in a manager, a process, and a long-term strategy.
Selecting the Right Opportunity for Your Portfolio
If you’re already thinking about private equity, it’s certainly worth considering the benefit of lower fees for getting in early. Costs matter, and all else equal, paying less in management fees is better than paying more.

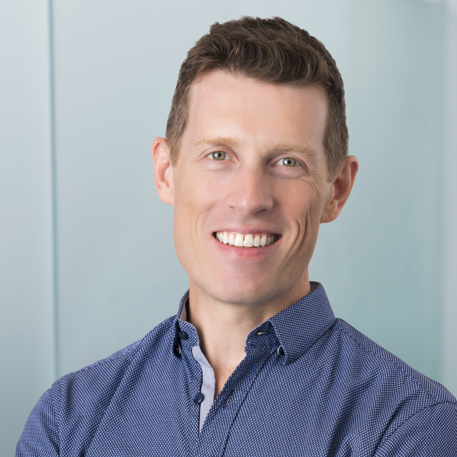

 Chris Chen
 Jeffrey J. Smith
 Peter Bo Rappmund
 Dr. Steven Crane
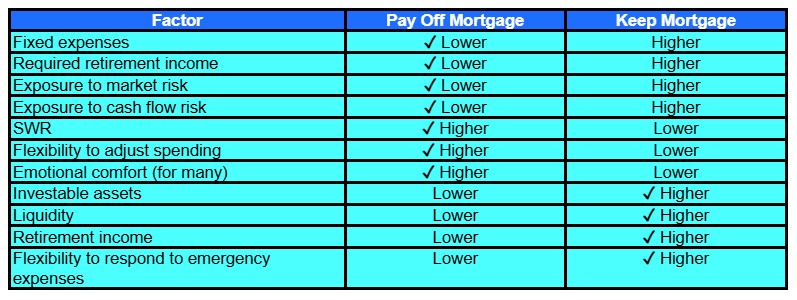

 Cole Williams
 Joe Stabile
 Mike Hunsberger
 Steve Witter